
 Rich Communication Services (RCS) Messaging Market | 2026-2036
Rich Communication Services (RCS) Messaging Market Size, Share, and Industry Trends Forecast 2026-2036
Rich Communication Services (RCS) Messaging Market Analytics
A capital-intensity divergence between cloud-native platforms and legacy telecom infrastructure is collapsing as API-first providers narrow the deployment gap. Google leverages its Android ecosystem to preload RCS capabilities across device manufacturers, sustaining carrier-agnostic reach. Vodafone Group anchors European network interoperability through GSMA-aligned hub services. Twilio competes on developer tooling, extending programmable messaging APIs that bypass traditional carrier gatekeeping.
Rich Communication Services (RCS) messaging upgrades cellular text protocols with read receipts, high-resolution media sharing, and interactive action buttons operating over IP-based data channels rather than circuit-switched SMS infrastructure. Its primary commercial purpose centers on transforming one-way promotional blasts into conversational commerce threads between brands and consumers. Customer Engagement applications lead current deployment volumes as banks and retailers deploy verified sender identities with embedded payment prompts. Cloud-Based Solutions within the technology dimension represent the fastest-expanding architecture as hyperscale infrastructure reduces per-message latency below legacy SMS routing. API Integration solutions command concentrated margin pools where platform providers bundle analytics and chatbot orchestration into tiered SaaS contracts.
The Federal Communications Commission shapes US market access through messaging authentication mandates that favor RCS-verified sender frameworks over unauthenticated SMS flooding. The European Union's Digital Services Act and GDPR impose data governance requirements on conversational data flows, pressuring platform providers to localize message processing. The GSMA Universal Profile standard operates as a de facto technical regulator, determining which feature sets achieve cross-carrier compatibility. Stakeholders must monitor whether Apple extends iMessage interoperability toward RCS Universal Profile compliance or maintains proprietary protocol fragmentation that constrains addressable market expansion.
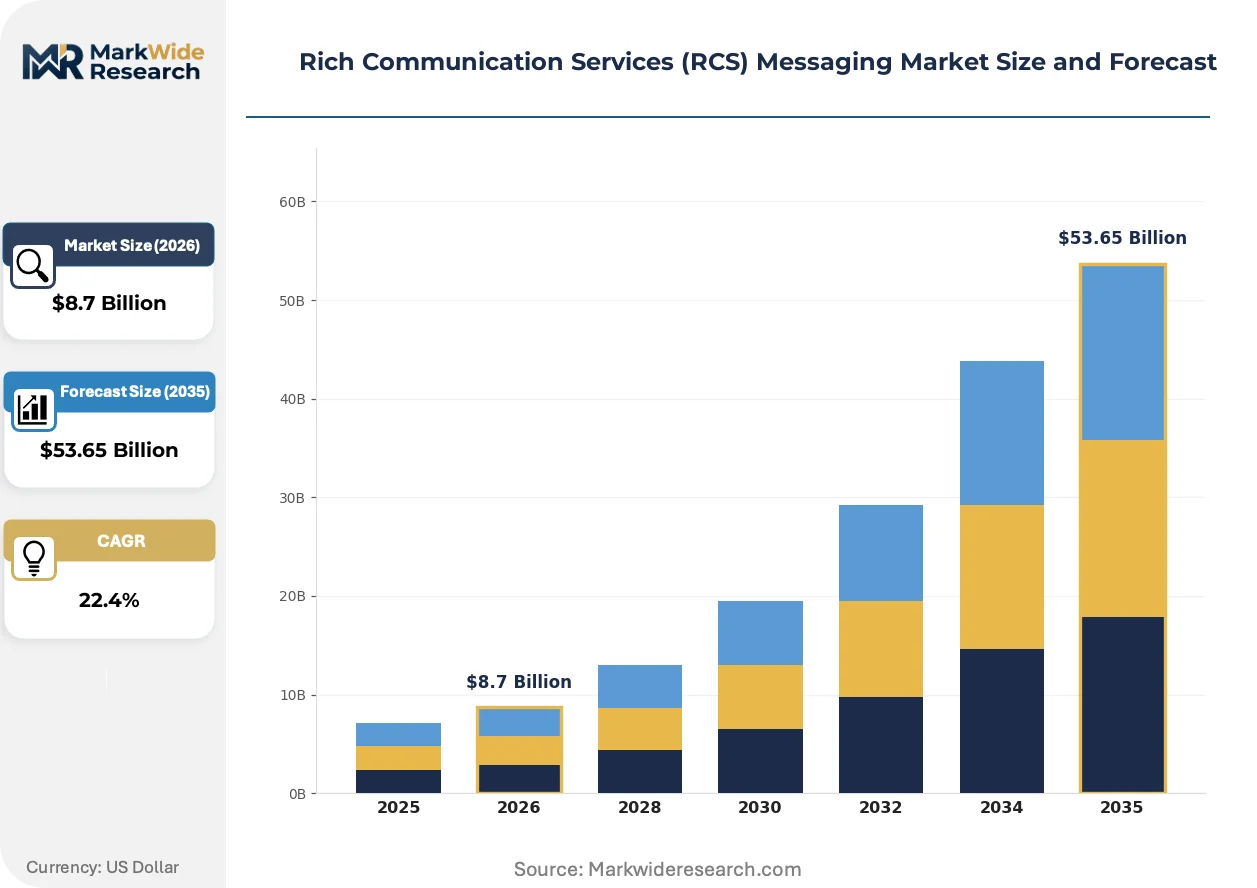
Market Dynamics
Carrier-agnostic IP messaging is collapsing the legacy SMS revenue model as Google preloads RCS Universal Profile across Android OEMs, forcing infrastructure providers to abandon circuit-switched routing investments.
Growth Catalysts
- Verified Sender Frameworks:Banks and retailers in the United States deploy RCS-verified identities to replace phishing-vulnerable SMS alerts, accelerating enterprise migration.
- GSMA Universal Profile:Cross-carrier interoperability standards in Germany and South Korea eliminate fragmentation penalties, reducing deployment friction for multi-market brands.
- Conversational Commerce APIs:Cloud-native platforms embed payment prompts and chatbot orchestration, transforming promotional blasts into interactive transaction threads.
Market Restraints
- Apple Protocol Fragmentation:iMessage maintains proprietary encryption standards that block RCS Universal Profile compliance, constraining addressable market expansion in premium smartphone segments.
- Legacy Infrastructure Sunk Costs:Tier-one carriers in Western Europe face stranded asset risk from SMS firewalls and SS7 signaling investments that resist rapid IP migration.
- GDPR Data Localization:The European Union's conversational data governance mandates require message processing within jurisdictional boundaries, elevating operational complexity for hyperscale platform providers.
Strategic Opportunities
- India Regulatory Tailwind:TRAI's anti-spam mandates and digital payment infrastructure expansion create fertile ground for RCS-based financial inclusion services in underbanked segments.
- Healthcare Appointment Orchestration:Hospital systems deploy interactive scheduling bots with embedded pre-visit forms, reducing no-show rates through richer patient engagement channels.
- 5G Network Slicing Convergence:Ultra-reliable low-latency communication slices enable mission-critical RCS applications for industrial IoT alerting and emergency response coordination.
Industry Challenges
- Interoperability Testing Complexity:Multi-carrier certification timelines for Universal Profile compliance extend 8-14 months, delaying feature rollouts and fragmenting user experiences.
- Legacy Billing System Integration:CSPs struggle to reconcile IP-based RCS usage metering with existing SMS tariff structures, creating revenue recognition disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rich Communication Services (RCS) Messaging Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Customer Engagement, Brand Communication, Two-Way Messaging, Analytics Integration End User: Telecom Operators, Marketing Agencies, Enterprises, Retail Brands Solution: RCS Tools, API Integration, Analytics Platforms, Chatbot Solutions Technology: Cloud-Based Solutions, Cross-Platform Integration, Data Security, Real-Time Messaging |
| Companies Covered | Vodafone Group, Verizon Communications, Infobip, CM.com, Twilio, Google, AT&T, Huawei Technologies, Sinch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rich Communication Services (RCS) Messaging Market Evolving Landscape
Artificial intelligence orchestration layers are compressing deployment timelines for conversational commerce, enabling brands to launch verified messaging campaigns without carrier-specific engineering.
Rich card templates with embedded carousels and quick-reply buttons are miniaturizing the functional gap between native apps and messaging interfaces. Retailers in South Korea deploy these compact interactive units for product browsing, reducing friction in purchase journeys. The technology is miniaturizing consumer expectations for brand engagement, forcing legacy SMS providers to accelerate feature parity investments.
The European Union's Digital Services Act imposes transparency obligations on algorithmic content ranking within messaging platforms, requiring RCS providers to audit recommendation systems. This regulatory pressure elevates compliance costs for conversational AI deployments. Financial services verticals in Germany are responding by segregating promotional and transactional message streams to limit audit scope.
Brand procurement teams now demand outcome-based messaging contracts tied to verified engagement metrics rather than volume-based SMS pricing. This shift disrupts traditional carrier wholesale arrangements, favoring API-first platforms with granular analytics. The United States exhibits the most pronounced migration, with enterprise buyers consolidating vendor relationships around programmable messaging stacks.
Rich Communication Services (RCS) Messaging Market Segmentation
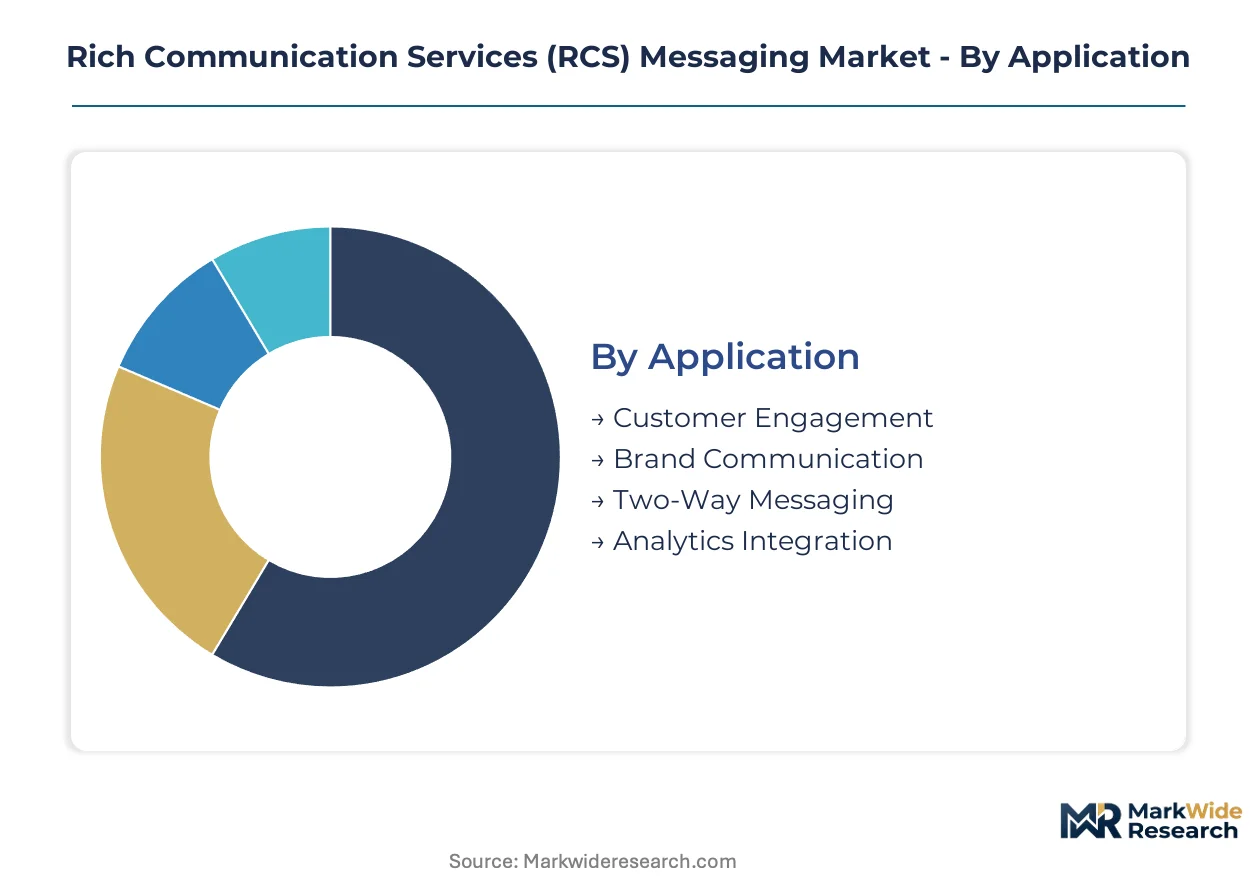
RCS messaging segments reflect distinct commercialization pathways—carrier infrastructure investments diverge sharply from API-first cloud deployments. Channel configuration determines margin capture, with enterprise-facing solutions commanding premium pricing over wholesale carrier interconnects.
Application:
Enterprise procurement teams route messaging budgets through distinct operational channels—marketing departments favor campaign-centric tools while IT organizations prioritize integration infrastructure.
- Customer Engagement:Interactive threads with verified sender badges and embedded action buttons transform promotional broadcasts into conversational commerce. Banks in the United States deploy these capabilities for fraud alerts and payment confirmations, displacing phishing-vulnerable SMS.
- Brand Communication:Rich card templates with carousels and quick-reply interfaces miniaturize app functionality within native messaging. Retailers in South Korea leverage these compact units for product browsing, compressing purchase journeys.
- Two-Way Messaging:Bidirectional conversational flows enable appointment scheduling and customer service automation.
- Analytics Integration:Message-level engagement tracking with read receipts and interaction timestamps feeds attribution models.
Customer Engagement dominates installed base. Brand Communication is where expansion concentrates.
End User:
Procurement authority varies sharply across buyer types—carrier procurement teams negotiate wholesale interconnect rates while enterprise IT departments evaluate API reliability and developer experience.
- Telecom Operators:Network infrastructure owners provision RCS hubs and manage Universal Profile certification timelines. Vodafone Group anchors European interoperability through GSMA-aligned services, monetizing cross-carrier message transit.
- Marketing Agencies:Campaign orchestration specialists demand granular analytics and A/B testing capabilities for rich messaging creative.
- Enterprises:Corporate IT organizations prioritize SLA-backed uptime and GDPR-compliant data residency for transactional messaging.
- Retail Brands:Direct-to-consumer merchants seek outcome-based pricing tied to verified engagement metrics rather than volume-based SMS tariffs.
Telecom Operators capture wholesale infrastructure revenue. Retail Brands are driving the shift toward performance-based contracting models.
Solution:
Margin pools concentrate where platform providers bundle adjacent capabilities—standalone RCS connectivity commoditizes while orchestration layers sustain pricing power.
- RCS Tools:Core messaging infrastructure including hub provisioning, carrier interoperability testing, and Universal Profile compliance certification.
- API Integration:Programmable messaging endpoints that bypass traditional carrier gatekeeping. Twilio competes on developer tooling, embedding analytics and chatbot orchestration into tiered SaaS contracts with the steepest expansion trajectory.
- Analytics Platforms:Message-level attribution dashboards tracking delivery confirmation, read rates, and interactive element engagement.
- Chatbot Solutions:Conversational AI layers for automated customer service and transactional workflows.
API Integration commands concentrated margin pools. Chatbot Solutions are climbing fastest as AI orchestration compresses deployment timelines.
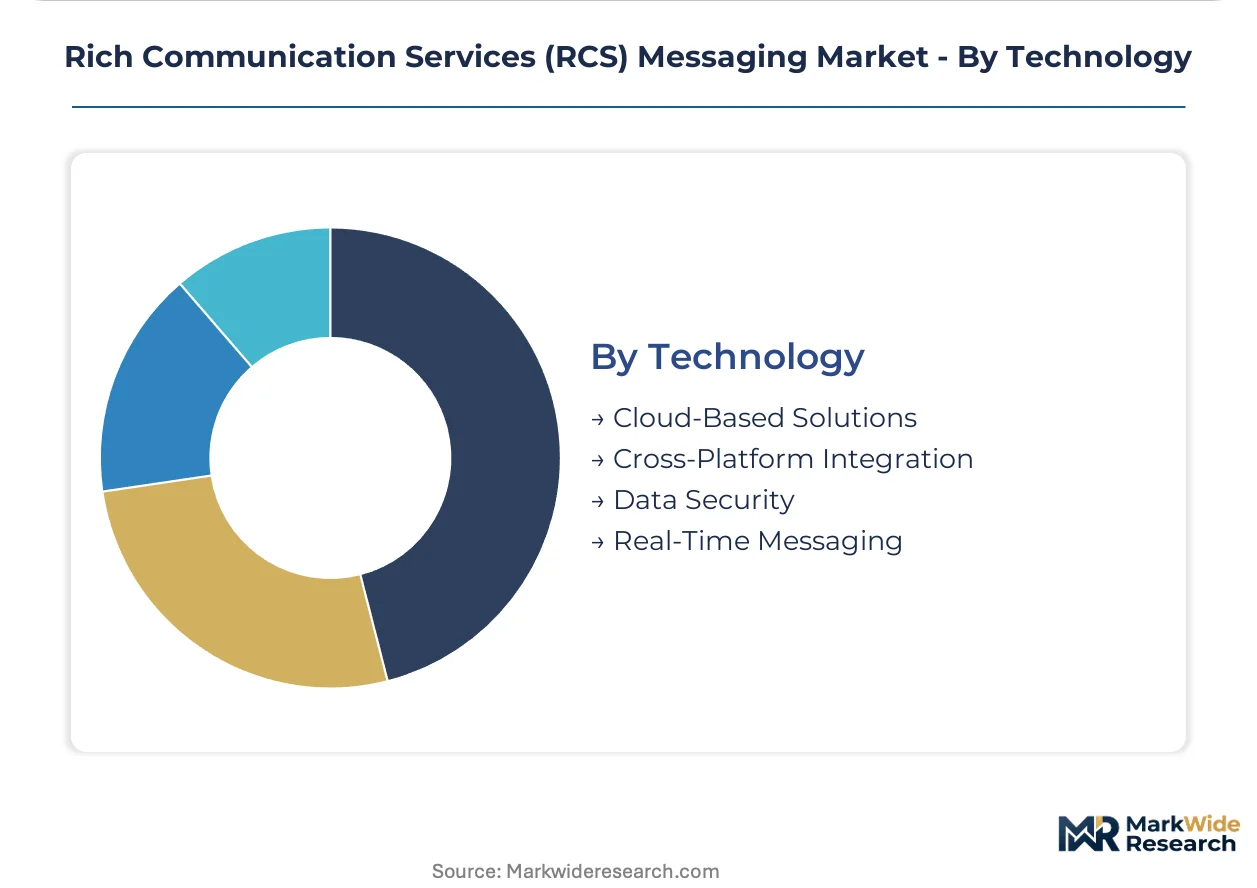
Technology:
Architecture choices determine latency profiles and operational cost structures—cloud-native deployments reduce per-message routing delays below legacy circuit-switched infrastructure.
- Cloud-Based Solutions:Hyperscale infrastructure with elastic capacity scaling and geographic redundancy. These architectures minimize per-message latency through distributed edge processing.
- Cross-Platform Integration:Interoperability layers bridging RCS Universal Profile with proprietary messaging protocols like iMessage.
- Data Security:Encryption standards and access controls for conversational data flows, with GDPR localization mandates elevating compliance complexity in Germany.
- Real-Time Messaging:Ultra-low-latency delivery protocols enabling synchronous conversational experiences.
Cloud-Based Solutions anchor new deployment volumes. Data Security investments are expanding most quickly under regulatory pressure from EU data governance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in Germany by a substantial margin, reflecting divergent carrier consolidation patterns and enterprise procurement sophistication. This asymmetry shapes investment flows across the RCS messaging landscape.
United States
Enterprise procurement teams at major banks and retailers drive demand for verified sender frameworks and interactive payment prompts. The FCC mandates messaging authentication standards that favor RCS-verified identities over unauthenticated SMS flooding. Financial services clusters in New York and San Francisco anchor deployment volumes for fraud alert and payment confirmation use cases.
Germany
Automotive OEMs and industrial manufacturers demand GDPR-compliant conversational data flows with strict localization requirements. The Digital Services Act imposes transparency obligations on algorithmic content ranking within messaging platforms. Berlin and Munich host concentrated platform engineering operations addressing EU data governance mandates.
South Korea
Consumer electronics brands and mobile-first retailers deploy rich card templates with embedded carousels for product browsing. The Korea Communications Commission enforces interoperability standards aligned with GSMA Universal Profile. Seoul anchors the densest carrier network coverage for interactive messaging commerce.
India
Digital payment infrastructure expansion and underbanked population segments create demand for RCS-based financial inclusion services. TRAI's anti-spam mandates accelerate enterprise migration from bulk SMS to verified messaging channels. Mumbai and Bangalore concentrate fintech platform development for conversational banking deployments.
United Kingdom
Marketing agencies and retail brands seek outcome-based messaging contracts tied to verified engagement metrics rather than volume-based tariffs. The Information Commissioner's Office enforces GDPR-aligned data protection standards for conversational AI deployments. London anchors the largest concentration of API-first platform procurement in Europe.
Rich Communication Services (RCS) Messaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the RCS messaging market. The vendor base separates into three distinct tiers: hyperscale cloud platforms with developer-centric tooling, legacy telecom operators with carrier infrastructure ownership, and specialized messaging aggregators with regional interoperability expertise. Strategic moves concentrate on API ecosystem expansion and GSMA Universal Profile certification acceleration. Partnership formations between cloud-native providers and carrier hubs dominate competitive dynamics.
Within the cloud platform tier, Twilio and Google exemplify the API-first archetype that bypasses traditional carrier gatekeeping through programmable messaging endpoints. Vodafone Group occupies a position representing the carrier-hub model, anchoring European network interoperability through GSMA-aligned services. These three entities collectively illustrate the structural divergence between infrastructure ownership and software-layer monetization in conversational commerce.
| Leading Market Players |
|---|
| Vodafone Group |
| Verizon Communications |
| Infobip |
| CM.com |
| Twilio |
| AT&T |
| Huawei Technologies |
| Sinch |
| Others |
Value Network & Pricing Analysis
GSMA Universal Profile certification operates as a dual gatekeeper, simultaneously qualifying platform providers for carrier interoperability and stratifying pricing power between certified and uncertified service tiers. This regulatory mechanism concentrates margin capture among API-first platforms that bundle compliance into premium SaaS contracts while squeezing standalone connectivity providers.
Pricing Analysis
Configured-to-order API integration commands substantial premiums over standard RCS connectivity, with enterprise buyers paying tiered SaaS rates for embedded analytics and chatbot orchestration. Price differentiation rests on GSMA certification status and geographic data residency compliance, with GDPR-aligned localization in Germany adding operational surcharges. Cost compression in wholesale carrier interconnects is intensifying because cloud-native platforms bypass traditional gatekeeping. Marketing agencies exhibit the highest price sensitivity, while financial services prioritize SLA-backed uptime over unit economics.
Supply Chain Analysis
The United States, Germany, and South Korea anchor RCS infrastructure deployment, with hyperscale cloud regions in Virginia, Frankfurt, and Seoul processing message transit at sub-SMS latency. The supply chain draws from carrier-owned network hubs, third-party API platforms, and device manufacturer preloads. Single-source vulnerability concentrates in Google's Android ecosystem control over Universal Profile distribution. Distribution runs through programmable messaging endpoints that disintermediate legacy carrier wholesale arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in GSMA-certified engineering talent and carrier interoperability testing capacity constrains how quickly vendors can scale verified messaging deployments, amplifying returns for platforms that internalize these capabilities early.
For Market Incumbents: Compound defensive positioning by deepening backward integration into carrier hub infrastructure and accelerating Universal Profile certification pipelines before API-first platforms consolidate enterprise relationships. Vertical integration into data residency-compliant processing centers in Frankfurt and Seoul addresses GDPR and KCC mandates that emerging competitors struggle to satisfy at scale. For New Entrants and Emerging Players: Anchor in India's TRAI-mandated anti-spam transition and underbanked financial inclusion segments where incumbent platform presence remains thin. Healthcare appointment orchestration in the United Kingdom offers a penetrable vertical with outcome-based contracting models that favor agile API providers over legacy carrier relationships. For Investors and Strategic Acquirers: FCC messaging authentication mandates reshape the acquisition landscape by elevating verified sender framework capabilities above raw connectivity scale. Target API-first platforms with embedded analytics and chatbot orchestration layers rather than standalone RCS infrastructure plays. Recalibrate positions upon Apple iMessage interoperability announcements, which would instantly expand addressable market boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| GSMA Universal Profile Certification Acceleration | Vodafone Group and Deutsche Telekom compress multi-carrier testing timelines from fourteen months to under six. |
| API-First Platform Integration | Twilio embeds conversational AI orchestration into tiered SaaS contracts that bypass carrier gatekeeping. |
| Data Residency Infrastructure Expansion | Hyperscale providers localize message processing in Frankfurt and Seoul to satisfy GDPR and KCC mandates. |
| Verified Sender Framework Deployment | JPMorgan Chase and Bank of America displace phishing-vulnerable SMS with RCS-verified fraud alerts. |
| Healthcare Appointment Orchestration Partnership | NHS trusts in London reduce no-show rates through interactive scheduling bots with embedded pre-visit forms. |
Research Methodology
Desk research of carrier financial disclosures, GSMA technical specifications, and FCC regulatory filings preceded structured interviews with platform engineering directors, enterprise IT procurement officers, carrier interoperability leads, and conversational AI product managers. Primary fieldwork across the United States, Germany, and South Korea validated deployment timelines and pricing trajectories. Secondary sources included SEC 10-K filings, TRAI consultation papers, and hyperscaler infrastructure capex disclosures. Bottom-up message volume modeling and top-down enterprise spending estimates were triangulated against carrier-reported RCS traffic data.
Variance in projected growth rates decomposes across deployment model, end-user vertical, integration complexity, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from logistic adoption curves fitted to enterprise messaging budget migration patterns and carrier infrastructure investment schedules. Model inputs incorporated 5G network slicing readiness indices, conversational commerce API penetration rates, and GSMA Universal Profile version adoption timelines across the analysis window.
Material uncertainties — Apple protocol fragmentation persistence, legacy carrier stranded asset write-downs, and EU Digital Services Act enforcement intensity — sit outside the modeled envelope. Forecasts reflect assumptions about cross-carrier interoperability achievement and enterprise procurement consolidation velocity. Recalibration cycles align with material shifts in FCC authentication mandates, TRAI anti-spam rulemaking, and iMessage interoperability policy announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
France Telecom Market
Telecommunications
Kuwait Telecom Market
Telecommunications
Private Branch Exchange Market
Telecommunications
Mobile Value-Added Services (MVAS) Market
Telecommunications
Portable Base Station (PBS) Market
Telecommunications
Cloud RAN Market
Telecommunications
Asia Pacific Mobile Virtual Network Operator (MVNO) Market
Telecommunications
C-RAN Market
Telecommunications
Australia Telecom Tower Market
Telecommunications
United States Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Global Hosted PBX Market
Telecommunications
Oman Telecom Market
Telecommunications
Optical Network Terminal (ONT) Equipment Market
Telecommunications
Peru Telecom Market
Telecommunications
Telecom Expense Management Market
Telecommunications
Myanmar Telecom Market