
 Direct Carrier Billing Market | 2026-2036
Direct Carrier Billing Market Size, Share, and Industry Trends Forecast 2026-2036
Direct Carrier Billing Market Intelligence
The European Union's Digital Decade policy, which promotes secure and sustainable digital infrastructures, is realigning payment preferences toward mobile-first solutions. Bango plc leverages its platform technology to connect global merchants with mobile network operators for payment processing. Boku, Inc. specializes in mobile payment solutions for major digital brands. Fortumo OÜ, a part of Boku, extends carrier billing services across emerging markets in Asia and Latin America.
Direct Carrier Billing is a mobile payment method where the cost of digital goods or services is charged directly to a user's phone bill. This process leverages Mobile Network Operator (MNO) APIs for real-time transaction authorization, bypassing the need for credit cards. Micropayment transactions for Content Purchase, especially within the Mobile Gamers segment, constitute a significant volume driver. While One-time Purchases dominate revenue, Subscription models are a fast-growing payment type as media consumption shifts.
Regulatory frameworks like the EU's GDPR and the US FTC's consumer protection rules mandate strict data privacy and transparent billing practices. In India, guidelines from TRAI influence MNO partnerships and transaction limits, shaping market access. Stakeholders must navigate this complex, country-specific regulatory landscape to unlock new revenue streams from unbanked and underbanked populations.
Market Dynamics
The primary structural force shaping the market is the expansion of 5G infrastructure, which enables low-latency transactions essential for real-time services. This technological advance converges with high mobile internet penetration in regions like India, creating fertile ground for card-free payment solutions.
Growth Catalysts
- 5G Infrastructure Rollout:Global 5G deployment reduces transaction latency, critical for real-time authorization in mobile gaming and improving the user experience.
- Demand from Mobile Gamers:The mobile gaming segment's need for frictionless, one-tap micropayments for in-game purchases creates a significant volume driver.
- Supportive EU Policy:The EU's Digital Decade policy promotes secure digital infrastructures, realigning payment preferences toward mobile-first solutions and benefiting carrier billing.
Market Restraints
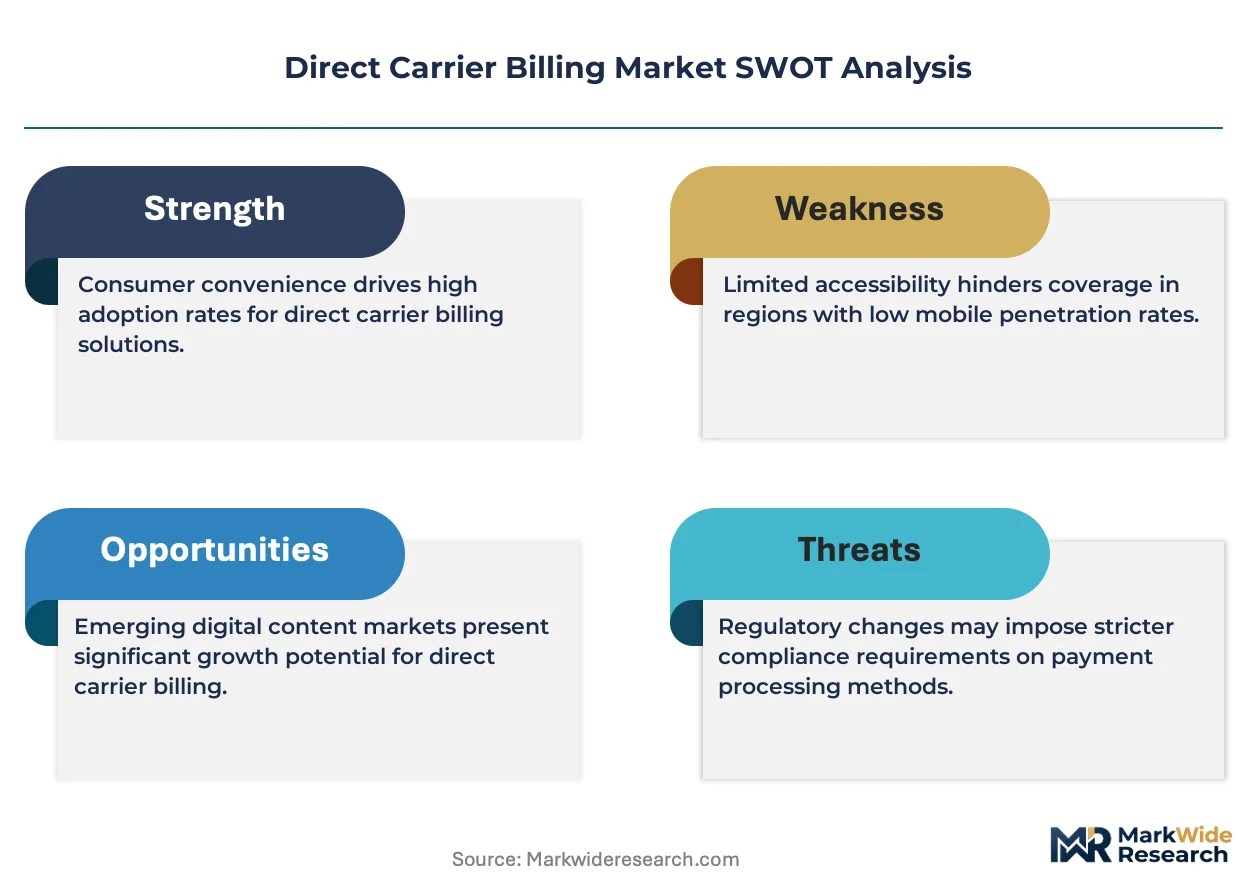
- Fragmented Regulatory Frameworks:Stakeholders face complex, country-specific rules, such as transaction limits set by India's TRAI, which restrict revenue potential and complicate market access.
- API Standardization Gaps:A lack of standardized Mobile Network Operator APIs for transaction authorization creates integration challenges and increases development costs for merchants.
- Mobile Wallet Competition:The rise of alternative mobile payment solutions, particularly mobile wallets in Asian markets, presents a significant substitution threat.
Strategic Opportunities
- Expansion in Latin America:Markets with high mobile penetration but low banking access, like Brazil and Mexico, offer significant white space for reaching unbanked consumers.
- Subscription Model Growth:The shift toward subscriptions for video and music streaming represents a fast-growing revenue stream beyond one-time content purchases.
- IoT Device Integration:Integrating carrier billing into IoT devices for automated micropayments, such as for smart parking, opens new non-content revenue channels.
Industry Challenges
- Data Privacy Compliance:Adhering to stringent data privacy and transparent billing mandates from frameworks like the EU's GDPR and US FTC rules requires continuous investment and legal expertise.
- Legacy System Integration:Integrating modern merchant platforms with the legacy billing infrastructure of some Mobile Network Operators presents a significant technical and operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct Carrier Billing Market |
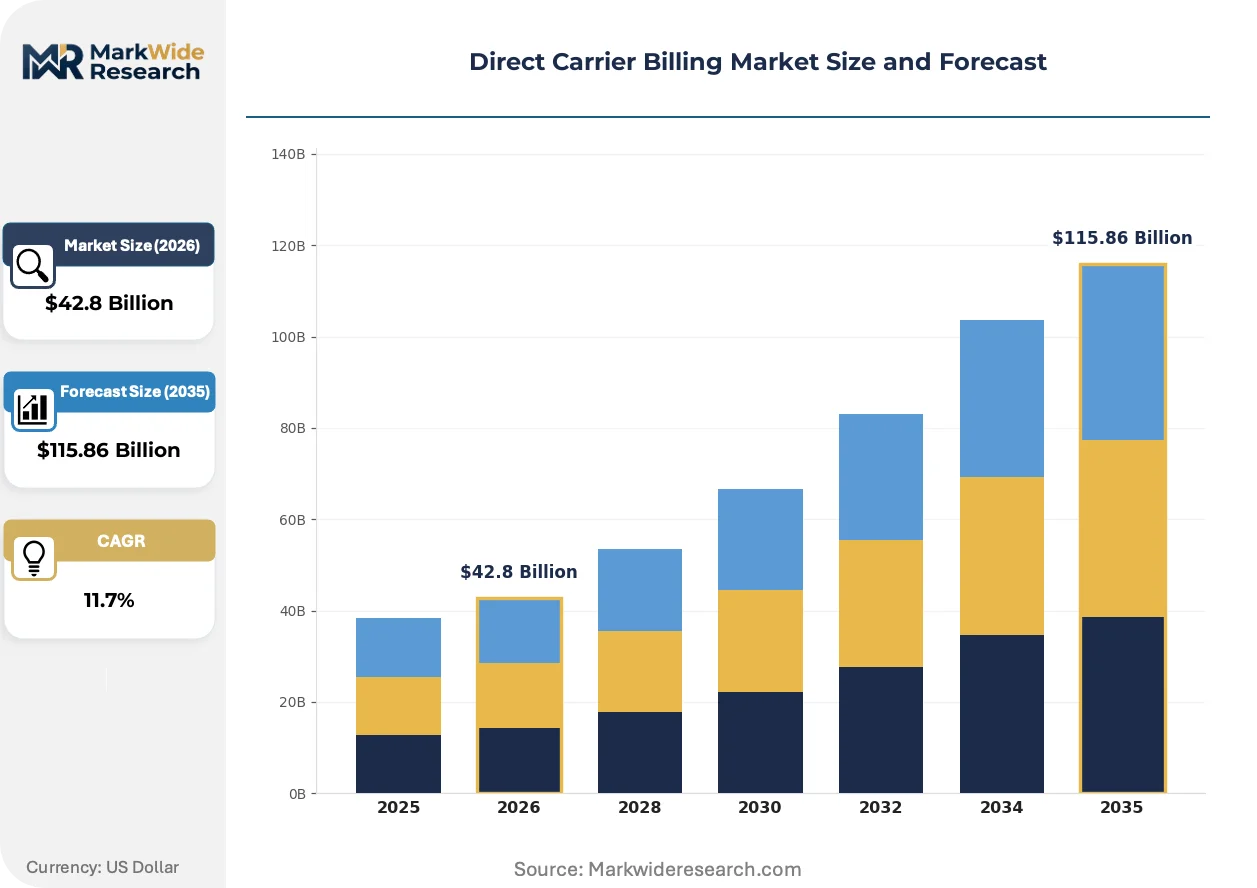
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $115.86 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: One-time Purchase, Subscription, Micropayment, Donation, Pay-per-use End User: Mobile Gamers, Digital Media Consumers, E-Learning Platforms, Utility Customers, Online Shoppers Service Type: Content Purchase, Ticketing Services, Financial Services, Telecom Subscriptions, Digital Wallet Reloads Distribution Channel: App Stores, Carrier Portals, Merchant Websites, Third-party Resellers, Social Media Platforms |
| Companies Covered | Comviva Technologies Limited, Digital Virgo Group, Bango plc, Fortumo OÜ, Fonix PLC, Boku, Inc., DIMOCO Payments GmbH, Orange S.A., Centili Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct Carrier Billing Market Strategic Shifts & Innovations
A shift toward greater payment rail sophistication actively reshapes the market from a simple content sales mechanism into an integrated financial service. This transition is marked by advanced security protocols and a push toward broader financial inclusion beyond entertainment.
Mobile Network Operator (MNO) APIs form the technological backbone, enabling real-time transaction authorization. Global merchants and major digital brands are rapidly adopting these APIs to reach customers without credit cards. This direct integration with carrier infrastructure is decentralizing payment processing, reducing reliance on traditional banking networks for micropayments and digital subscriptions.
The European Union's General Data Protection Regulation (GDPR) sets a global benchmark for data privacy and consumer rights in payment processing. This regulation forces MNOs and merchants to implement transparent billing practices and secure user data, with significant penalties for non-compliance. The content purchase segment, which handles high volumes of user data, is most affected, requiring robust consent management systems.
Consumer payment behavior is shifting from dominant one-time purchases toward recurring subscription models for digital services. This trend disrupts the traditional model of single content sales, as users prefer continuous access to media libraries like video and music streaming. This shift is most visible in developed markets across Europe and North America where media consumption patterns have matured.
Direct Carrier Billing Market Segmentation
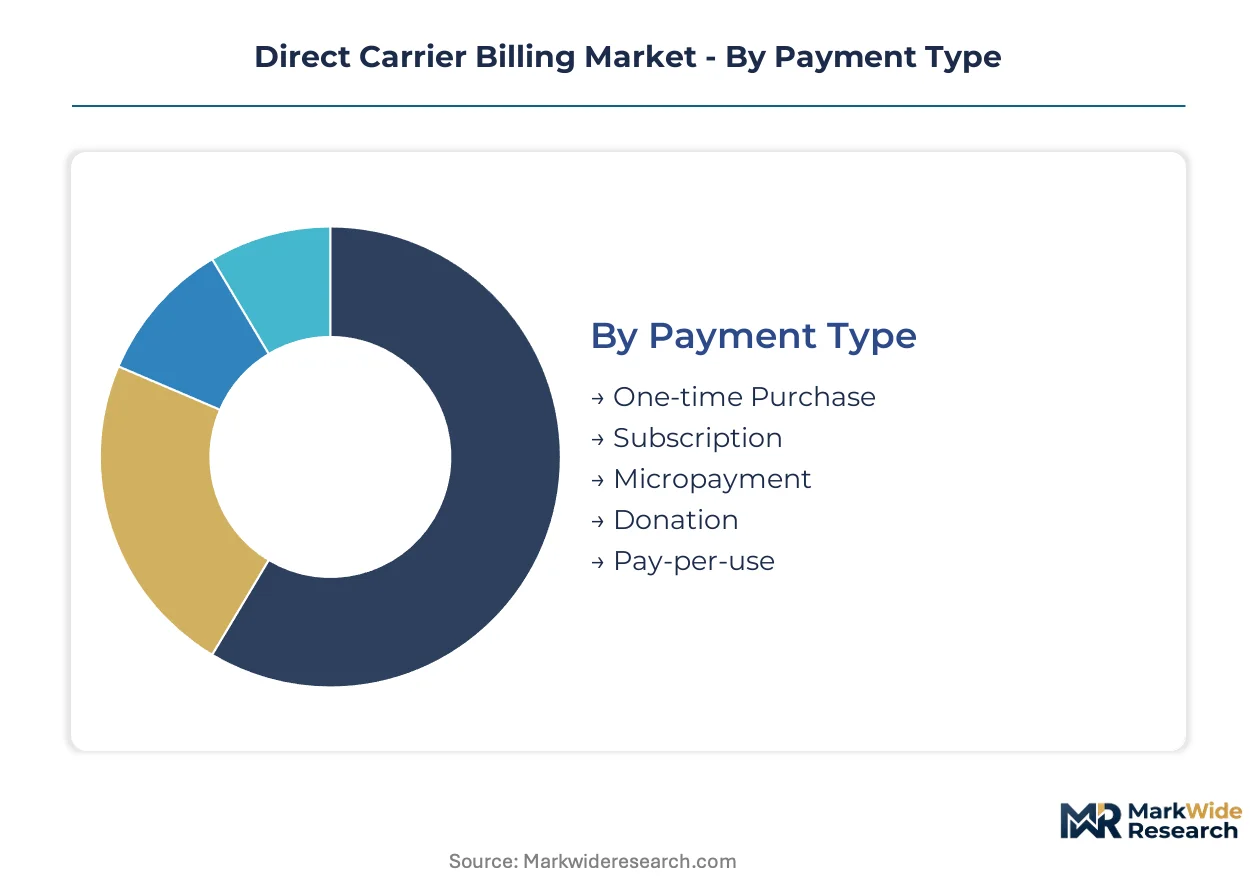
Market segmentation for direct carrier billing illuminates the varied revenue streams and consumer behaviors shaping this expanding digital payment ecosystem. Understanding these distinctions allows stakeholders to tailor offerings and market strategies effectively, addressing specific user needs and payment preferences across diverse demographics.
Payment Type:
The market for direct carrier billing exhibits a clear split between high-volume, low-value transactions and recurring revenue models.
- One-time Purchase:This payment model involves a single transaction for digital goods or services, offering immediate access to content or features. Demand from mobile gamers for in-game items and power-ups drives significant transaction volume due to its frictionless nature.
- Subscription:This model entails recurring payments for continuous access to digital content, services, or premium features over a defined period. The shift in consumer behavior toward media consumption favors subscription models, particularly for video and music streaming platforms in developed markets.
- Micropayment:These are small-value transactions, typically for digital content like ringtones, wallpapers, or small in-game consumables.
- Donation:Users make voluntary contributions to charities, non-profit organizations, or content creators through their mobile bill.
- Pay-per-use:Consumers pay for a service or content based on their actual consumption, often seen in utility or specific digital service access.
Today's leader: One-time Purchase. Tomorrow's challenger: Subscription.
End User:
Direct carrier billing adoption varies significantly across different consumer segments, each driven by unique motivations and purchasing habits.
- Mobile Gamers:This segment comprises individuals who utilize carrier billing for in-game purchases, virtual currency, or premium content within mobile games. The need for frictionless, one-tap micropayments makes carrier billing a preferred option for this high-volume user base.
- Digital Media Consumers:Users in this category leverage direct carrier billing for accessing video streaming services, music subscriptions, e-books, and online news platforms. The convenience of adding digital media costs directly to a phone bill simplifies access for many users.
- E-Learning Platforms:Students and professionals use carrier billing to pay for online courses, educational content, and learning subscriptions.
- Utility Customers:Consumers in regions with limited banking access use carrier billing to settle bills for essential services like electricity, water, or public transport.
- Online Shoppers:Individuals making purchases on e-commerce sites for digital goods or smaller physical items may use carrier billing as an alternative payment method.
Mobile Gamers represent the fastest-growing segment, with Digital Media Consumers expanding quickly.
Service Type:
The range of services supported by direct carrier billing is broadening, moving beyond traditional content into more integrated financial and utility applications.
- Content Purchase:This service type involves the acquisition of digital content such as mobile games, applications, music, videos, and e-books directly via a mobile phone bill. High mobile internet penetration in regions like India fuels demand for content purchases from unbanked populations.
- Digital Wallet Reloads:Users top up their mobile digital wallets using direct carrier billing, enabling financial inclusion and seamless transactions in markets with low credit card penetration. This service offers a crucial bridge for consumers relying on mobile payments.
- Ticketing Services:Consumers purchase tickets for public transport, events, concerts, or cinema directly through their mobile network operator.
- Financial Services:This category includes micro-loans, insurance premiums, or basic banking transactions facilitated through carrier billing partnerships.
- Telecom Subscriptions:Users pay for their mobile data plans, voice packages, or value-added services like caller tunes directly via their carrier bill.
Content Purchase maintains market leadership, while Digital Wallet Reloads are gaining share fastest.
Distribution Channel:
Direct carrier billing reaches consumers through various channels, each offering distinct advantages in terms of reach and user experience.
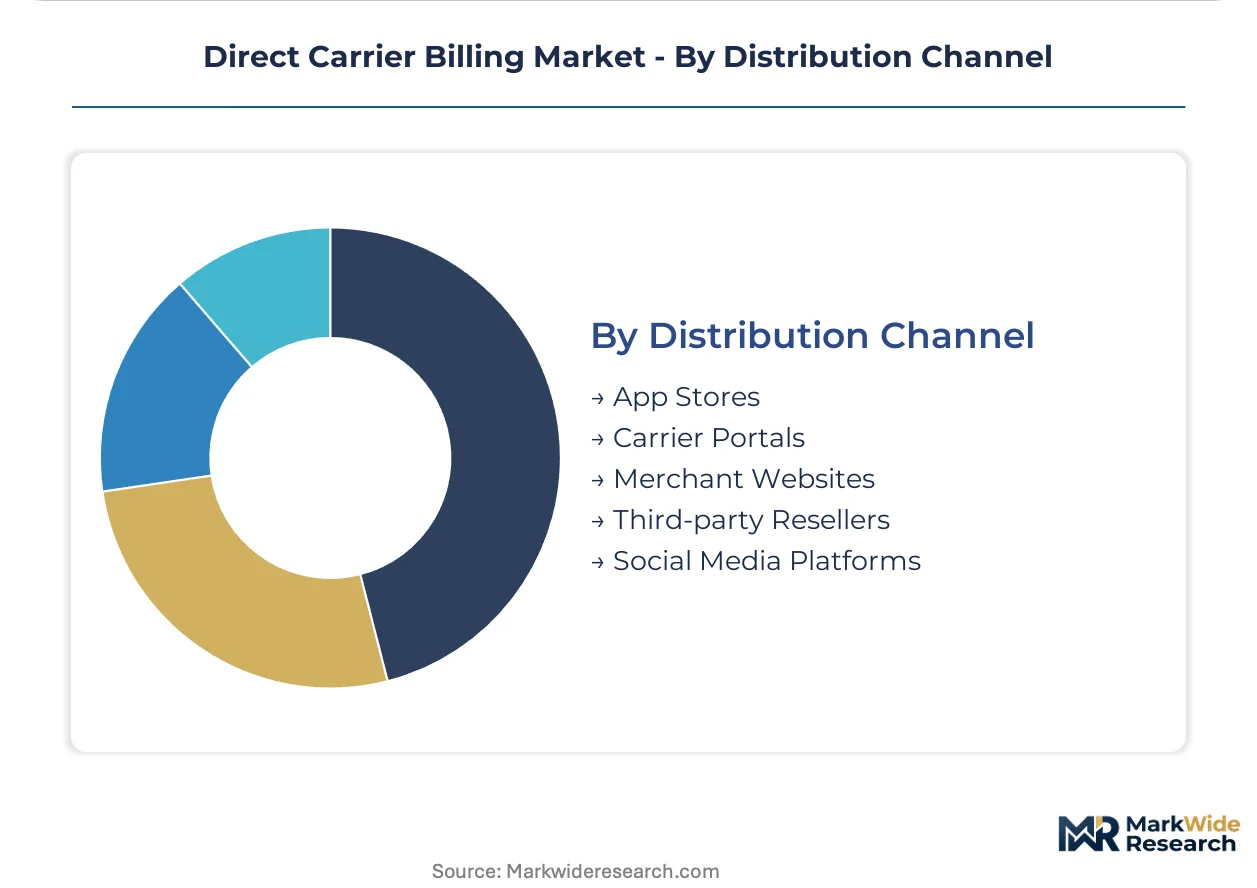
- App Stores:These are digital storefronts where mobile applications and their associated in-app purchases are facilitated directly through the app ecosystem. The ubiquity of app stores on smartphones makes them a primary channel for frictionless mobile content acquisition.
- Merchant Websites:Online merchants integrate direct carrier billing APIs onto their own e-commerce platforms, allowing customers to pay for digital goods or services directly on the merchant's site. This channel expands payment options for consumers without traditional banking methods.
- Carrier Portals:Mobile Network Operators host their own online platforms where subscribers can purchase digital content, services, or manage their telecom subscriptions.
- Third-party Resellers:Aggregators and platforms that combine digital content from multiple providers offer carrier billing as a payment option.
- Social Media Platforms:In-platform purchases for virtual goods, content, or premium features within social networking applications leverage carrier billing for convenience.
App Stores lead in transaction volume, with Merchant Websites showing a steep expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A significant concentration of mobile internet users and a burgeoning unbanked population anchor the Direct Carrier Billing market's growth across diverse global regions. This payment method thrives where traditional banking access is limited or where frictionless digital purchases are paramount. Strategic expansion targets countries with high smartphone penetration and supportive regulatory frameworks for mobile payments.
India
High mobile internet penetration drives demand for content purchases and mobile gaming in India. Guidelines from TRAI influence Mobile Network Operator partnerships and transaction limits, shaping market access. The technology hubs of Bengaluru and Mumbai are seeing rapid adoption of carrier billing for various digital services.
Germany
European consumers increasingly utilize direct carrier billing for digital media subscriptions and app store purchases. The EU's GDPR mandates strict data privacy and transparent billing practices for all payment processors operating in Germany. Berlin's vibrant startup ecosystem fosters new mobile-first payment integrations for local and regional merchants.
Brazil
Brazil's high mobile penetration coupled with low banking access creates a substantial opportunity for direct carrier billing. The Central Bank of Brazil regulates payment service providers, ensuring compliance and consumer protection in mobile transactions. São Paulo, as a major economic center, leads the expansion of digital wallet reloads via carrier billing for its urban population.
Japan
Japanese consumers readily adopt direct carrier billing for in-app purchases and digital content, reflecting a mobile-first culture. METI provides guidelines for electronic commerce, promoting secure and transparent digital payment methods within the country. Tokyo's advanced telecommunications infrastructure supports sophisticated carrier billing integrations for leading digital brands.
United States
The United States market shows strong demand for subscription models and one-time content purchases via mobile billing. The US FTC enforces consumer protection rules, requiring clear disclosures and consent for carrier billing transactions. Silicon Valley's tech ecosystem drives innovation in payment rail sophistication, integrating carrier billing with broader financial services.
Direct Carrier Billing Market Key Industry Players
Capital-heavy Mobile Network Operators compete with asset-light payment platform providers in the Direct Carrier Billing market. The market structure exhibits a tiered consolidation, with established telecom giants alongside specialized payment aggregators. Strategic archetypes include infrastructure providers, platform enablers, and regional integrators. Companies are pursuing strategic partnerships and portfolio diversification to expand their market reach and service offerings.
Specialists in mobile payment platforms, such as Bango plc and Boku, Inc., occupy a significant position within the ecosystem. These entities exemplify the asset-light providers connecting global merchants with mobile network operators for payment processing. Concurrently, Orange S.A., a major telecommunications company, represents the capital-heavy Mobile Network Operator archetype, leveraging its extensive subscriber base to offer direct carrier billing services. These players collectively shape the market's competitive dynamics through their distinct operational models and strategic focuses.
| Leading Market Players |
|---|
| Comviva Technologies Limited |
| Digital Virgo Group |
| Bango plc |
| Fortumo OÜ |
| Fonix PLC |
| Boku, Inc. |
| DIMOCO Payments GmbH |
| Orange S.A. |
| Centili Limited |
| Others |
Cost & Logistics Intelligence
Specialized software engineers in technology hubs like India influence pricing tiers for Direct Carrier Billing services. Labor-cost differentials allow platform providers to offer competitive rates for API integration and transaction processing.
Pricing Analysis
Per-transaction fees for Direct Carrier Billing form the dominant pricing model, often complemented by recurring platform access charges for merchants. Price differentiation arises from transaction volume scale, the complexity of custom API integrations, and the geographic delivery cost for regulatory compliance. Pricing pressure stems from the intense competition posed by alternative mobile wallet solutions in key markets. Mobile Network Operators exhibit lower price sensitivity due to the strategic value of payment channel control, while smaller content providers are highly sensitive to per-transaction costs.
Supply Chain Analysis
Regional data centers and cloud infrastructure form the distribution backbone for Direct Carrier Billing services, enabling low-latency transaction processing globally. Technology development and API integration expertise concentrates in countries like India and the United States. The underlying infrastructure relies on secure API gateways and resilient telecommunications networks. Regulatory fragmentation across diverse markets creates a structural risk, and distribution runs through specialized payment platforms that integrate directly with Mobile Network Operator billing systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Direct Carrier Billing market presents a compelling margin expansion story, driven by the inherent cost efficiency of bypassing traditional payment rails. Shifting consumer preferences towards premium subscription models further enhances revenue potential.
For Market Incumbents: To counter the rising threat of mobile wallet competition, incumbent Direct Carrier Billing providers must deepen strategic partnerships with Mobile Network Operators. Investing in advanced fraud detection and API standardization across diverse MNO systems secures trust and reduces integration costs. Expanding into niche content segments or bundled services with telecom plans offers further differentiation. This approach leverages existing infrastructure while mitigating competitive pressures.
For New Entrants and Emerging Players: Begin with targeting underbanked populations in high mobile penetration regions like Latin America, focusing on essential service micropayments. Developing user-friendly interfaces and transparent billing practices for utility customers or e-learning platforms creates a strong initial foothold. Strategic alliances with local Mobile Network Operators and digital content providers offer rapid market access. This strategy leverages existing demand where traditional banking access remains limited.
For Investors and Strategic Acquirers: Telecom giants are the most active acquirers in this space, seeking to consolidate payment infrastructure and expand digital service offerings. The market offers long-term viability by bridging financial inclusion gaps for unbanked populations globally. Acquisition targets include specialized API aggregators and platform enablers with strong regional MNO relationships. The signal to watch is the acceleration of regulatory harmonization across emerging markets, which will streamline cross-border operations.
| Strategic Initiative | Industry Significance |
|---|---|
| API Standardization Initiatives | Reduces integration costs for merchants and accelerates market expansion. |
| Expansion into Latin America | Captures unbanked consumers in high mobile penetration regions. |
| Subscription Model Development | Aligns with shifting consumer preferences for recurring digital content. |
| Advanced Fraud Detection Integration | Builds consumer trust and reduces revenue leakage for MNOs. |
| Partnerships with E-Learning Platforms | Diversifies revenue streams beyond traditional gaming and media content. |
Research Approach
Multiple input streams — primary interviews, secondary data analysis, and internal databases — were reconciled to construct this market view. Engagements with Mobile Network Operator executives, payment gateway specialists, digital content publishers, and regulatory advisors provided critical primary insights. Secondary validation drew from industry reports, company financial filings, and telecom authority publications. A rigorous bottom-up and top-down triangulation process ensured data coherence.
Historical market data was cross-referenced with expert panel input to develop the forecast framework over the projection horizon. Segmentation dimensions modeled included payment type, end-user, service type, distribution channel, and regional adoption patterns. Compound annual growth rates were derived from historical trends and projected market drivers. Key forecast inputs included mobile internet penetration rates, smartphone adoption, and anticipated regulatory changes.
Caveats apply where unforeseen regulatory changes or rapid technological shifts in payment infrastructure could materially shift the outlook. Forecasts reflect assumptions regarding market dynamics and competitive evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Money Transfer Agencies Market
Payments
China Payment Gateway Market
Payments
Epayment System Market
Payments
Latin America Subscription and Billing Management Market
Payments
Contactless Payment Terminals Market
Payments
Global Virtual Cards Market
Payments
Middle East and Africa Real Time Payments Market
Payments
Germany Payment Gateway Market
Payments
In-Vehicle Payment Services Market
Payments
Contactless Payment Ring Market
Payments
France Mobile Payment Market
Payments
Thailand Mobile Payments Market
Payments
India POS Terminals Market
Payments
POS Terminals Market
Payments
India Gift Card and Incentive Card Market
Payments
UK Prepaid Cards Market