
 New Zealand Payments Market | 2026-2036
New Zealand Payments Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Payments Market Foresight
Physical card plastic is realigning toward tokenized digital credentials across the New Zealand Payments landscape. ASB Bank Limited leverages its digital infrastructure to sustain contactless volume growth in Auckland's retail core. Bank of New Zealand anchors merchant acquiring relationships through integrated POS solutions. Visa Inc competes on network reliability and cross-border settlement speed.
New Zealand Payments encompass electronic fund transfer systems, card networks, mobile wallets, and real-time clearing infrastructure operating through ISO 20022 messaging protocols and dual-message authorization architectures. These systems facilitate commercial exchange, treasury management, and consumer purchasing across physical and digital commerce environments. Credit Card and Mobile Wallet segments command premium interchange revenue pools, while Bank Transfer volumes dominate B2B settlement flows. Peer-to-Peer transaction types exhibit the fastest behavioral shift among retail customers, though Recurring Payments anchor subscription economy retention mechanics for business entities.
The Reserve Bank of New Zealand governs systemic payment stability through the Financial Market Infrastructures Act, while the Commerce Commission monitors retail payment system competition under designated regime powers. The Privacy Act 2020 and forthcoming consumer data right legislation shape data portability requirements for open banking participants. Stakeholders must weigh interoperability investments against regulatory compliance timelines as real-time payment rails mature.
Market Dynamics
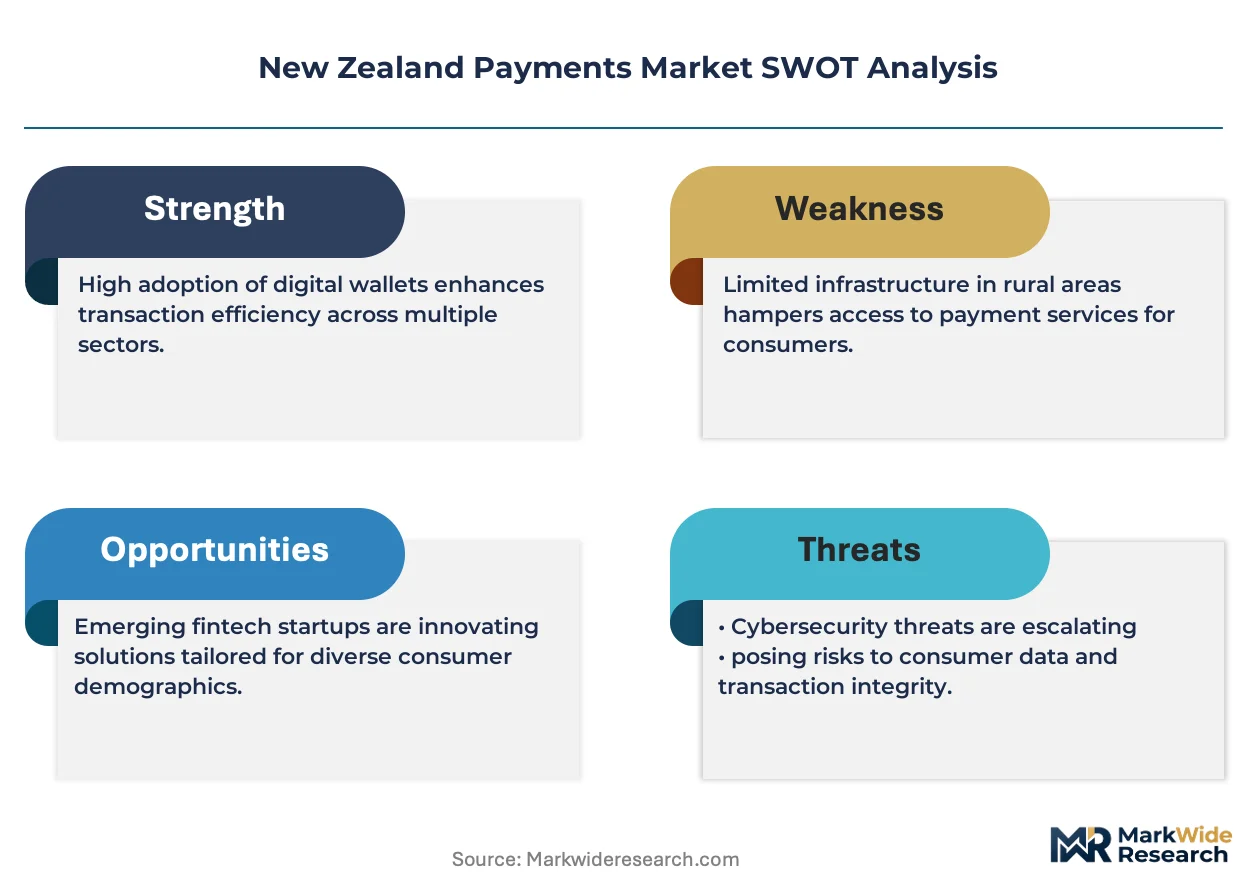
The Reserve Bank of New Zealand's open banking framework is forcing incumbent banks to expose customer data through standardized APIs, collapsing traditional information asymmetries that once protected deposit-based revenue models.
Growth Catalysts
- ISO 20022 migration:The Reserve Bank of New Zealand's real-time payment infrastructure upgrade enables richer data fields for automated reconciliation, accelerating B2B workflow integration among Auckland corporate treasuries.
- Contactless merchant terminals:Hospitality operators across Queenstown and Christchurch tourism corridors are replacing magnetic stripe hardware with NFC-enabled POS systems to capture transit-oriented spending.
- Privacy Act 2020 enforcement:Mandatory breach notification requirements are compelling financial institutions to invest in consent-management platforms that double as competitive differentiators for data-conscious retail customers.
Market Restraints
- Core banking system replacement costs:Legacy mainframe architectures at regional banks require eight-figure capital commitments to achieve real-time clearing compatibility, constraining mid-tier institution participation.
- Interchange fee compression:The Commerce Commission's retail payment systems oversight is capping scheme fees, squeezing acquirer margins and reducing capital available for rural merchant onboarding.
- Cloud concentration risk:Critical payment infrastructure dependencies on hyperscale providers based outside New Zealand create operational resilience concerns under the Financial Market Infrastructures Act.
Strategic Opportunities
- South Island agricultural payments:Federated Farmers members in Canterbury and Otago remain underserved by integrated receivables solutions, presenting white space for livestock and dairy settlement automation.
- Consumer data right legislation:Pending statutory instruments will mandate account-to-account payment initiation, enabling fintech challengers to bypass card networks entirely for e-commerce transactions.
- Biometric-API convergence:Facial recognition authentication layered against open banking rails is creating passwordless checkout experiences for Wellington's high-frequency transit users.
Industry Challenges
- API talent scarcity:The domestic pipeline of developers proficient in both financial services domain logic and modern REST architectures remains insufficient for open banking implementation timelines.
- Legacy ISO 8583 integration:Dual-message authorization systems at major retailers require complex protocol bridging to connect with real-time rail message formats, extending migration projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Payments Market |
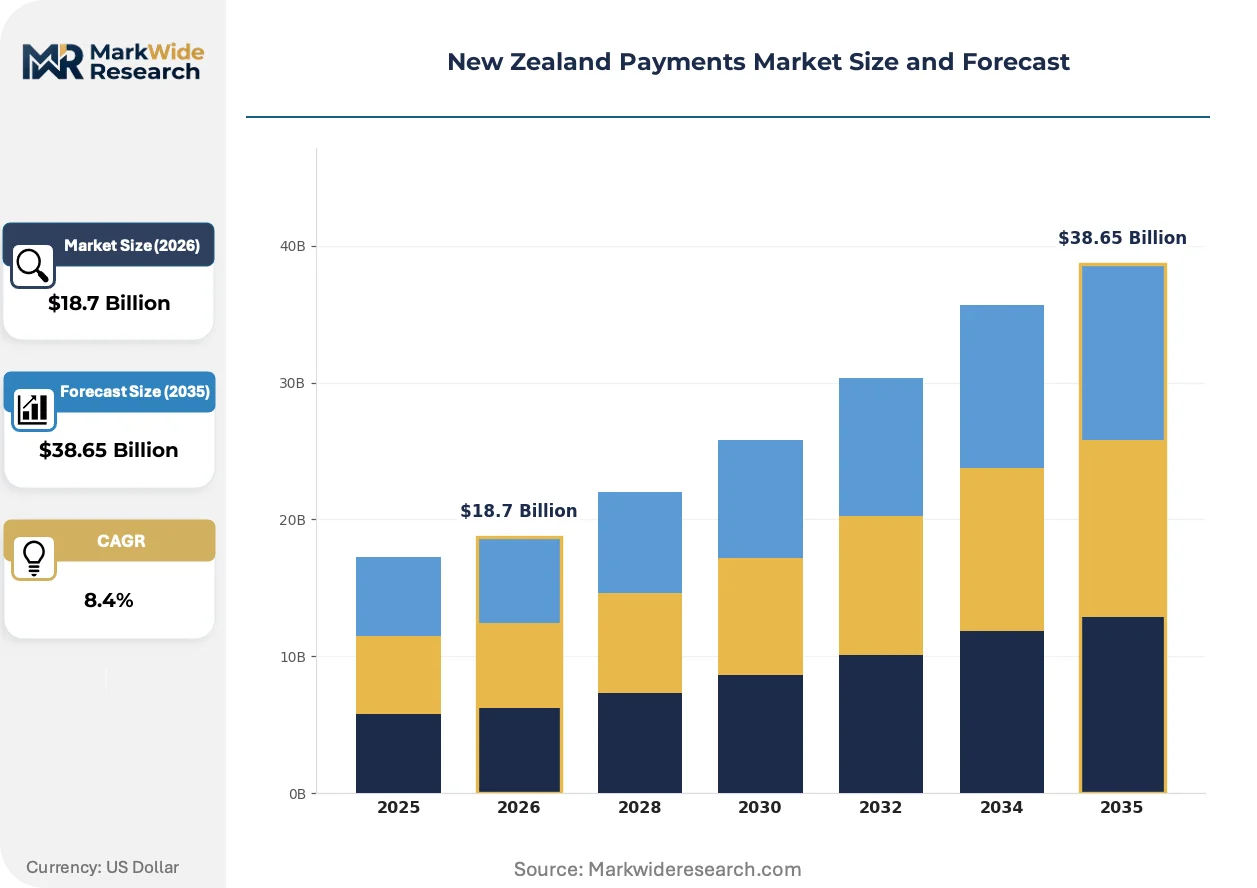
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Mobile Wallet, Bank Transfer Consumer Segment: Retail Customers, Merchants, Business Entities, Government Transaction Type: In-Store, Online, Peer-to-Peer, Recurring Payments Technology: Contactless Payments, QR Code, NFC, E-commerce |
| Companies Covered | ASB Bank Limited, Bank of New Zealand, Visa Inc, POLi NZ, Kiwibank Limited, Mastercard Inc, Westpac New Zealand Limited, Worldline New Zealand Limited, ANZ Bank New Zealand Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Payments Market Shifts & Advancements
Distributed ledger infrastructure is compressing settlement finality windows while regulatory mandates force interoperability investments that erode proprietary network advantages.
Blockchain-based clearing prototypes are decentralizing correspondent banking relationships by enabling direct bilateral settlement between New Zealand financial institutions without intermediary nostro accounts. ASB Bank Limited and Bank of New Zealand are piloting shared ledger arrangements for cross-border remittances. This architecture is decentralizing liquidity management away from traditional correspondent concentration in Australian parent entities.
The Commerce Commission's designated regime powers under the Retail Payment Systems Act are mandating scheme fee transparency and interchange benchmarking against comparable jurisdictions. Acquirers must now publish effective merchant service charges, compressing opacity premiums. Small hospitality merchants in Auckland's Viaduct Harbour are leveraging this data to renegotiate acquiring contracts.
Subscription billing models are displacing transaction-by-transaction purchasing across software and media verticals, forcing payment processors to develop recurring authorization management tools. Recurring Payments now anchor customer lifetime value calculations for SaaS providers. This behavioral shift concentrates most visibly among Wellington's technology sector workforce.
New Zealand Payments Market Segmentation
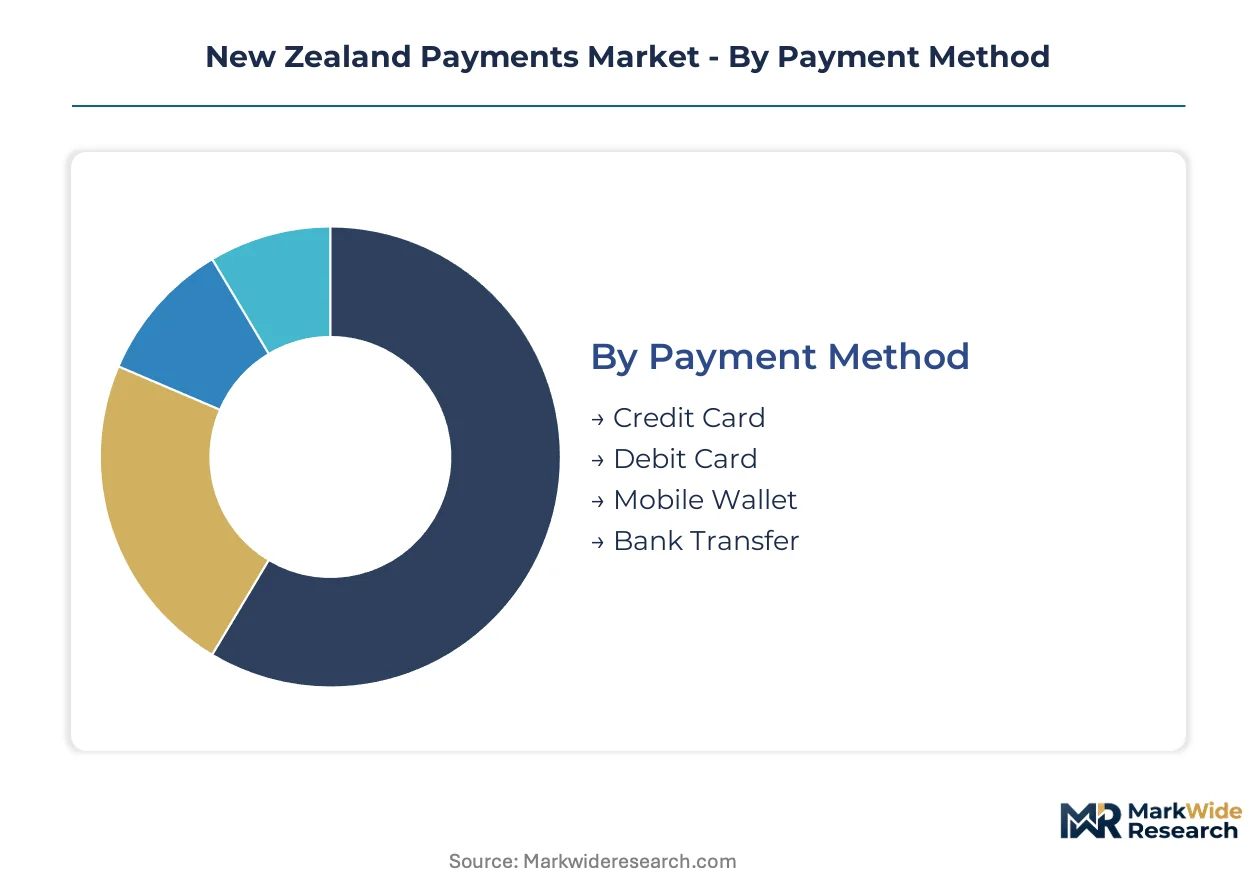
New Zealand's payment infrastructure fragments across distinct usage contexts, each demanding specialized authentication protocols and settlement architectures. Segment boundaries increasingly blur as real-time rails enable hybrid transaction modes that defy traditional categorical definitions.
Payment Method:
Merchant acceptance costs and consumer convenience preferences determine adoption hierarchies across New Zealand's retail and B2B corridors.
- Credit Card:Dual-message authorization systems route through international scheme networks, generating interchange revenue pools that sustain issuer loyalty programs. Auckland's hospitality merchants absorb premium acquiring fees to capture tourist spending at Viaduct Harbour and Queen Street retail clusters.
- Mobile Wallet:Tokenized credential storage on iOS and Android devices enables biometric-authenticated proximity payments. Wellington's transit corridors and Christchurch airport retail zones exhibit the steepest contactless volume acceleration as commuters abandon physical card presentation.
- Debit Card:Single-message EFTPOS infrastructure dominates supermarket and fuel retail across provincial centers, constrained by domestic-only settlement rails that exclude cross-border e-commerce.
- Bank Transfer:Account-to-account initiation through open banking APIs is displacing card rails for high-value B2B settlements among Canterbury agricultural exporters and Otago livestock traders.
Credit Card leads on scale; Mobile Wallet leads on momentum.
Consumer Segment:
Regulatory data portability mandates and treasury automation requirements reshape service delivery priorities across distinct entity types.
- Retail Customers:Individual consumers demand seamless credential provisioning across multiple devices, with consent-management platforms becoming competitive differentiators under Privacy Act 2020 enforcement. Auckland's dense urban corridors concentrate mobile-first adoption.
- Merchants:Hospitality and tourism operators across Queenstown and Rotorua prioritize integrated POS solutions that reconcile inventory, staffing, and settlement data through unified dashboards.
- Business Entities:Corporate treasuries in Wellington's government-adjacent professional services sector require ISO 20022-enriched remittance data for automated reconciliation of multi-party supplier payments.
- Government:Central and local agencies mandate procure-to-pay transparency, driving demand for real-time payment tracking and audit-trail immutability in infrastructure contracting.
Retail Customers anchor volume throughput; Business Entities drive infrastructure investment cycles.
Transaction Type:
Channel-specific authentication protocols and settlement timing requirements fragment technical architectures across physical and digital environments.
- In-Store:NFC-enabled terminal infrastructure at Auckland retail cores processes tap-and-go volumes that dominate physical commerce, though magnetic stripe fallback persists at rural merchants with legacy hardware.
- Online:E-commerce checkout flows demand 3D Secure authentication layering against rising card-not-present fraud attempts, with merchant abandonment rates sensitive to friction in guest checkout pathways.
- Peer-to-Peer:Mobile number-linked account transfers between retail customers exhibit the steepest behavioral shift, displacing cash settlement for informal obligations and shared expenses among younger demographics.
- Recurring Payments:Subscription economy mechanics anchor customer lifetime value for SaaS providers and media platforms, requiring sophisticated authorization management tools to minimize involuntary churn from credential expiration.
In-Store dominates absolute transaction counts; Peer-to-Peer climbs the fastest as cash displacement accelerates.
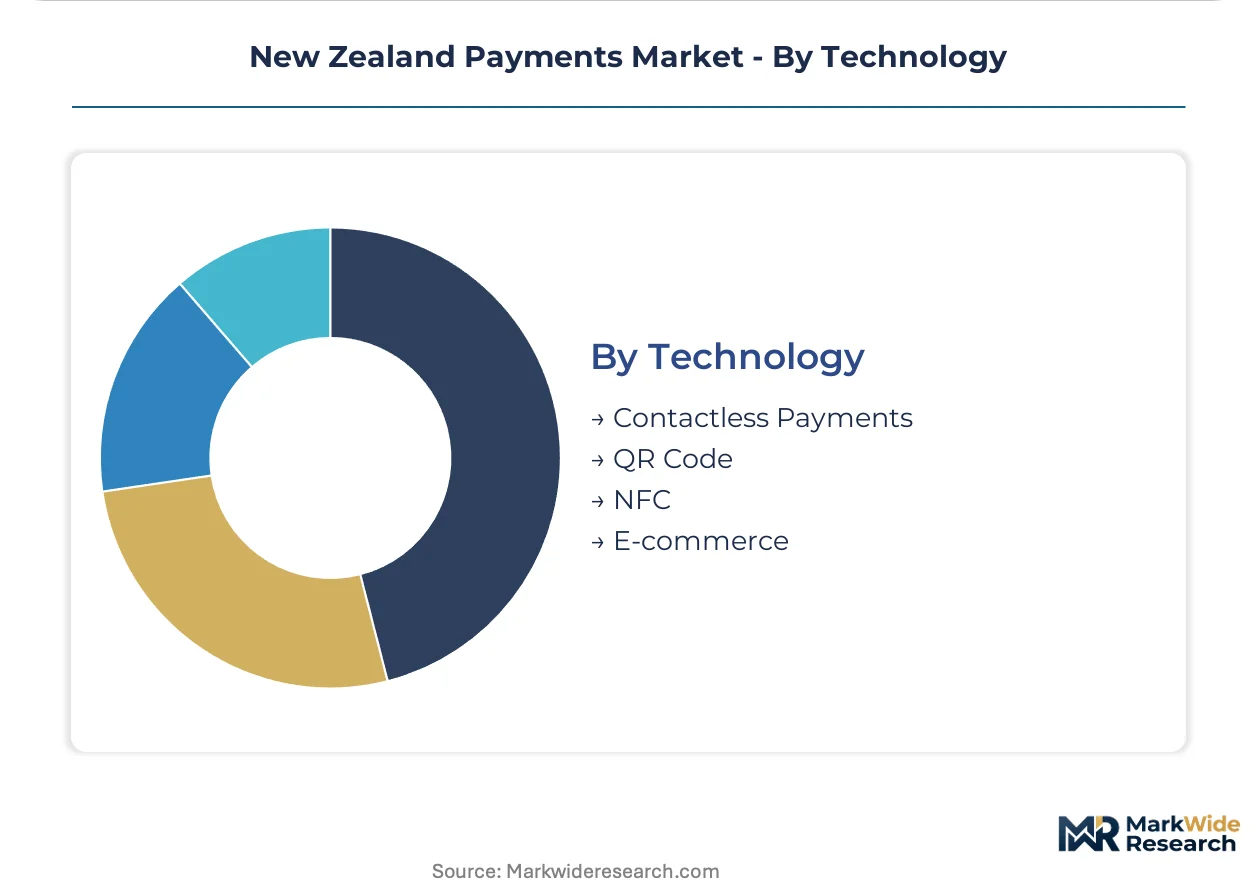
Technology:
Hardware replacement cycles and interoperability standards determine competitive positioning among infrastructure providers.
- Contactless Payments:NFC radio frequency protocols enable sub-500 millisecond transaction completion at transit gates and quick-service retail, with Wellington's Metlink integration demonstrating modal shift potential.
- QR Code:Static and dynamic barcode presentation supports low-cost merchant acceptance without dedicated terminal hardware, penetrating food trucks and market vendors across Christchurch's weekend retail precincts.
- NFC:Near-field communication chipsets in smartphones and wearables enable secure element-based credential storage, with token provisioning complexity representing a barrier for smaller financial institutions.
- E-commerce:Browser-based and in-app checkout flows require sophisticated fraud scoring and seamless wallet integration, with cart abandonment rates directly correlating to payment method diversity at checkout.
Contactless Payments commands installed terminal base; QR Code gains share fastest among micro-merchants avoiding hardware capital expenditure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Auckland's financial district anchors payment infrastructure investment across the North Island, concentrating merchant acquiring relationships and real-time clearing development within New Zealand's commercial core.
Auckland Metro
Hospitality and tourism operators along Viaduct Harbour drive contactless terminal deployment for tourist spending capture. The Reserve Bank of New Zealand's open banking framework mandates API standardization for data portability. Queen Street retail clusters exhibit the steepest mobile wallet adoption velocity among metropolitan centers.
Wellington Region
Government-adjacent professional services generate sophisticated B2B treasury automation demand for ISO 20022-enriched remittance data. The Commerce Commission's retail payment systems oversight enforces scheme fee transparency benchmarks. Metlink transit integration demonstrates biometric-API convergence for passwordless commuter payments.
Canterbury
Agricultural exporters and livestock traders require account-to-account settlement solutions for high-value commodity transactions. The Privacy Act 2020 compels consent-management platform investment for data-conscious rural customers. Christchurch airport retail zones anchor NFC-enabled quick-service commerce infrastructure.
Otago and Southland
Federated Farmers members in dairy and sheep sectors remain underserved by integrated receivables automation. The Financial Market Infrastructures Act governs systemic stability for regional banking participation. Queenstown tourism corridors concentrate merchant demand for unified POS reconciliation dashboards.
New Zealand Payments Market Competitive Landscape
Global majors compete with regional champions across network reliability and merchant relationship depth. The New Zealand Payments structure concentrates around incumbent banking groups with established acquiring portfolios and international scheme network partnerships. Three archetypes dominate: domestic retail banks with integrated digital infrastructure, global card networks competing on cross-border settlement speed, and specialized fintech challengers leveraging open banking rails. Competitive moves center on strategic partnerships for real-time clearing access and portfolio diversification into subscription billing management tools.
Within the domestic banking tier, ASB Bank Limited and Bank of New Zealand exemplify incumbent institutions defending merchant relationships through integrated POS solutions. Visa Inc occupies a position representing global network competition on reliability and settlement infrastructure. These three anchors illustrate the tension between proprietary digital credential ecosystems and standardized open banking interoperability mandates reshaping competitive positioning.
| Leading Market Players |
|---|
| ASB Bank Limited |
| Bank of New Zealand |
| Visa Inc |
| POLi NZ |
| Kiwibank Limited |
| Mastercard Inc |
| Westpac New Zealand Limited |
| Worldline New Zealand Limited |
| ANZ Bank New Zealand Limited |
| Others |
Supply & Pricing Matrix
Merchant demand for real-time settlement and ISO 20022-enriched data is compelling infrastructure providers to upgrade legacy authorization systems, concentrating capital expenditure among tier-one banks and compressing margins for mid-tier acquirers unable to spread fixed costs across volume bases.
Pricing Analysis
Input-cost pass-through from cloud infrastructure and API development talent is intensifying margin pressure on domestic payment processors. Three-tier pricing structure across premium API access, standard gateway services, and economy EFTPOS acquiring dominates merchant billing, with interchange fee compression from Commerce Commission oversight squeezing acquirer spreads most acutely in rural hospitality segments. Price differentiation hinges on settlement speed guarantees and PCI-DSS certification tier. Tourism-dependent merchants in Queenstown exhibit highest price sensitivity; Wellington government contractors show lowest.
Supply Chain Analysis
Domestic-content requirements under the Financial Market Infrastructures Act are reshaping sourcing toward New Zealand-based data centers and local API gateway providers. Critical infrastructure draws from Australia, Singapore, and domestic facilities for primary processing nodes. Raw material dependencies center on semiconductor chipsets for NFC terminals, cryptographic security modules, and fiber optic transmission equipment. Single-source vulnerability concentrates in hyperscale cloud dependencies outside national jurisdiction. Distribution runs through bank-owned acquiring networks, independent sales organizations, and direct fintech API integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
New Zealand Payments operates as a stable compounder anchored by regulatory-mandated infrastructure upgrades that lock in recurring technology refresh cycles across the banking sector.
For Market Incumbents: Cement merchant relationships through exclusive ISO 20022 migration partnerships that embed switching costs before open banking APIs democratize access. Deepen vertical integration into cloud infrastructure to reduce hyperscale dependency exposure. Prioritize Wellington government and Canterbury agricultural verticals where treasury automation demand concentrates. For New Entrants and Emerging Players: Begin with South Island agricultural receivables automation where Federated Farmers members remain underserved by integrated settlement solutions. Target Otago and Southland dairy cooperatives with account-to-account payment initiation bypassing card networks entirely. Lead with mobile-first credential provisioning that collapses onboarding friction for rural merchants lacking dedicated IT staff. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized fintech challengers possessing proven open banking API stacks and existing Commerce Commission compliance frameworks. Long-term viability favors entities with recurring revenue from subscription billing management tools rather than transaction-dependent models. Watch for inflection when consumer data right legislation triggers mass account-to-account payment adoption in e-commerce channels.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20022 Migration Partnership | Locks in merchant switching costs ahead of open banking democratization. |
| Biometric-API Convergence Investment | Enables passwordless authentication for Wellington Metlink transit integration. |
| Agricultural Receivables Automation | Captures Canterbury livestock and dairy settlement flows outside card networks. |
| Consent-Management Platform Development | Turns Privacy Act 2020 compliance into competitive differentiation for retail customers. |
| Cloud Infrastructure Localization | Reduces operational resilience risks under Financial Market Infrastructures Act scrutiny. |
Research Methodology
Multiple input streams — primary interviews with payment infrastructure executives, regulatory affairs specialists at the Reserve Bank of New Zealand, merchant acquiring relationship managers, and fintech platform engineers — were reconciled against secondary validation from Commerce Commission retail payment system reports, Financial Market Infrastructures Act disclosure filings, Privacy Act 2020 enforcement guidance, and ISO 20022 migration documentation. Bottom-up transaction volume modeling and top-down banking sector revenue triangulation anchored market sizing.
Historical transaction growth trajectories were cross-referenced against panel input from corporate treasury managers and hospitality merchant operators to calibrate adoption curves across the projection horizon. Segmentation dimensions modeled include payment method, consumer segment, transaction type, and technology infrastructure tier, with CAGRs derived from regression analysis against real-time rail deployment timelines and open banking API penetration rates. Forecast inputs incorporated interchange fee compression scenarios and cloud infrastructure cost trajectories.
Caveats apply where regulatory implementation delays, core banking system replacement failures, or hyperscale service disruptions could materially shift the outlook. Forecasts reflect assumptions about ISO 20022 migration adherence and consumer data right legislative passage. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Gift Card and Incentive Card Market
Payments
Saudi Arabia Mobile Payments Market
Payments
Mobile Payment Security Software Market
Payments
United Kingdom Payment Gateway Market
Payments
Cross-Border Payment Platform Market
Payments
Smart Payment Market
Payments
Mexico Payments Market
Payments
Mexico POS Terminals Market
Payments
Ghana Mobile Money Market
Payments
Global Accounts Payable (AP) Automation Software Market
Payments
Australia Mobile Payment Market
Payments
Europe Clearing Houses and Settlements Market
Payments
Consumer Mobile Payment Market
Payments
United Arab Emirates Real Time Payments Market
Payments
Mobile Payment Data Protection Market
Payments
Latin America Subscription and Billing Management Market