
 South Korea Payments Market | 2026-2036
South Korea Payments Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Payments Market Analytics
Buyer concentration among Seoul's mid-tier merchant acquirers is restructuring payment infrastructure procurement across the South Korea Payments Market. Kakao Pay Corp. leverages its super-app ecosystem to dominate peer-to-peer transfer volumes. Samsung Electronics Co. Ltd. anchors hardware-dependent point-of-sale acceptance through its device manufacturing scale. NHN PAYCO Corp. competes on specialized gaming and content-commerce integrations.
Payments in South Korea encompass digital fund transfer systems spanning mobile wallets, card networks, and bank rails, operating through encrypted tokenization protocols with sub-second authorization latency to facilitate commercial exchange. Mobile wallet transaction volume leads growth as NFC-enabled smartphones displace physical card presentment. Point-of-sale infrastructure remains mature with stable margin pools concentrated among incumbent acquirers. Peer-to-peer transfer adoption accelerates fastest among younger consumer segments seeking split-payment functionality.
The Financial Services Commission enforces open banking API standards while the Bank of Korea supervises real-time gross settlement stability, together mandating interoperability that lowers barriers for fintech entrants. MFDS guidelines on biometric authentication shape mobile wallet security architecture and user verification workflows. Stakeholders must monitor whether the central bank's digital currency pilot expands from wholesale testing into retail payment rails, as this would recalibrate competitive positioning across the entire ecosystem.
Market Dynamics
The Financial Services Commission's open banking mandates are compressing API standardization timelines across South Korea's payment rails. This regulatory pressure is forcing incumbent acquirers to cede control over proprietary transaction protocols while enabling fintech entrants to embed financial services into non-bank digital platforms.
Growth Catalysts
- Real-time settlement infrastructure:The Bank of Korea's real-time gross settlement system reduces interbank friction. Transaction latency compression attracts merchant acquirers seeking operational efficiency gains.
- Biometric authentication standards:MFDS guidelines on facial and fingerprint verification accelerate mobile wallet security adoption. Hardware manufacturers integrate certified sensors to comply with verification workflows.
- Seoul's retail corridor density:Concentrated merchant clusters in Gangnam and Myeongdong enable rapid contactless terminal deployment. Foot traffic patterns support infrastructure ROI calculations for acquirers.
Market Restraints
- Semiconductor input volatility:NFC chip fabrication concentrates among Taiwan and South Korean foundries. Supply tightness in secure element production elevates point-of-sale hardware costs.
- Legacy core banking dependencies:Major financial institutions operate on decades-old mainframe architectures. API integration with modern payment layers requires expensive middleware development.
- Interchange fee compression:Regulatory pressure on merchant discount rates constrains acquirer margin pools. Revenue per transaction declines as volume shifts to low-yield peer-to-peer channels.
Strategic Opportunities
- Busan-Ulsan manufacturing belt:Industrial payment corridors between port logistics and heavy manufacturing remain underpenetrated by mobile wallets. B2B transaction digitization lags consumer adoption significantly.
- Cross-border remittance corridors:Southeast Asian migrant worker populations in Gyeonggi Province drive demand for low-cost international transfer rails. Licensed operators can capture volume from informal hawala networks.
- Central bank digital currency pilot expansion:The Bank of Korea's wholesale CBDC testing may extend to retail payment rails. Early infrastructure positioning would yield competitive advantage in tokenized settlement architecture.
Industry Challenges
- Embedded finance engineering talent:Demand for API developers and cloud-native payment architects exceeds domestic supply. Fintechs compete with conglomerate technology subsidiaries for specialized labor.
- Multi-party transaction reconciliation:Split-payment functionality across super-apps introduces complex settlement logic. Dispute resolution workflows strain existing back-office operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Payments Market |
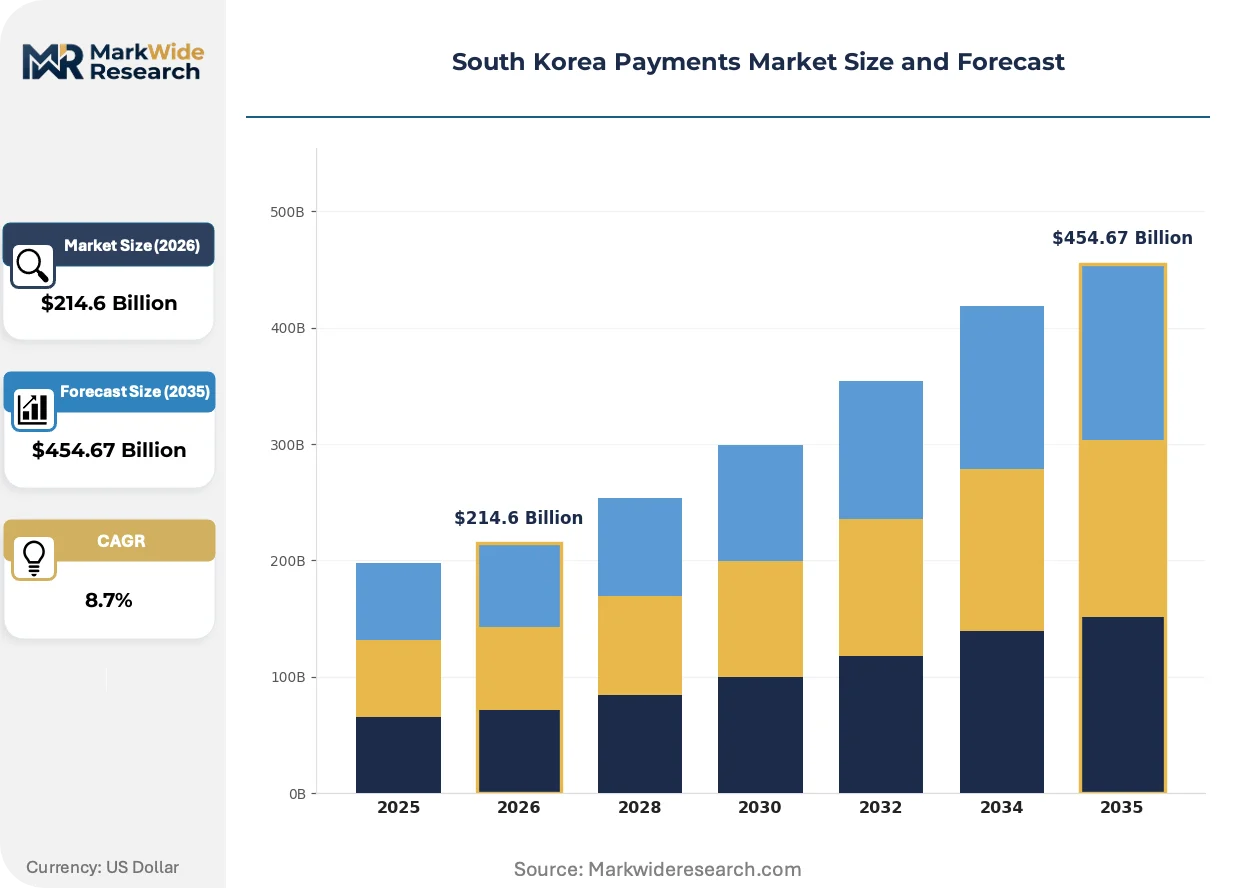
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $454.67 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Mobile Wallet, Credit Card, Debit Card, Bank Transfer Transaction Type: Online Payment, Point of Sale, Recurring Payment, Peer-to-Peer Transfer Consumer Segment: Millennials, Gen Z, Professionals, Seniors Service Type: Payment Processing, Fraud Prevention, Analytics, Customer Support |
| Companies Covered | NHN PAYCO Corp., Visa Inc., Kakao Pay Corp., American Express Company, Mastercard Inc., Naver Corporation, Samsung Electronics Co. Ltd., Rapyd Financial Networks Ltd., Viva Republica Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Payments Market Evolving Landscape
Tokenized credential management is compressing authentication friction across South Korea's payment ecosystem. Three distinct developments are restructuring how value moves through digital rails.
Host card emulation technology is automating the migration from physical to software-based payment credentials. Mid-tier merchant acquirers in Seoul's retail corridors are deploying NFC-enabled Android terminals at accelerated pace. This automation is eliminating dedicated hardware security module requirements and reducing terminal procurement costs for independent merchants.
The Financial Services Commission's open banking API standards are mandating interoperability between traditional deposit institutions and fintech platforms. Incumbent banks must expose account information and payment initiation interfaces to licensed third parties. Retail banking divisions face the greatest disruption as super-apps aggregate financial services previously controlled by branch networks.
Gen Z and millennial cohorts are consolidating transaction activity within messaging-integrated payment interfaces. Peer-to-peer transfer volume concentrates inside platforms offering social context alongside fund movement. This behavioral concentration is most visible in Seoul's university districts and dense apartment complexes where split-payment social norms dominate group consumption patterns.
South Korea Payments Market Segmentation
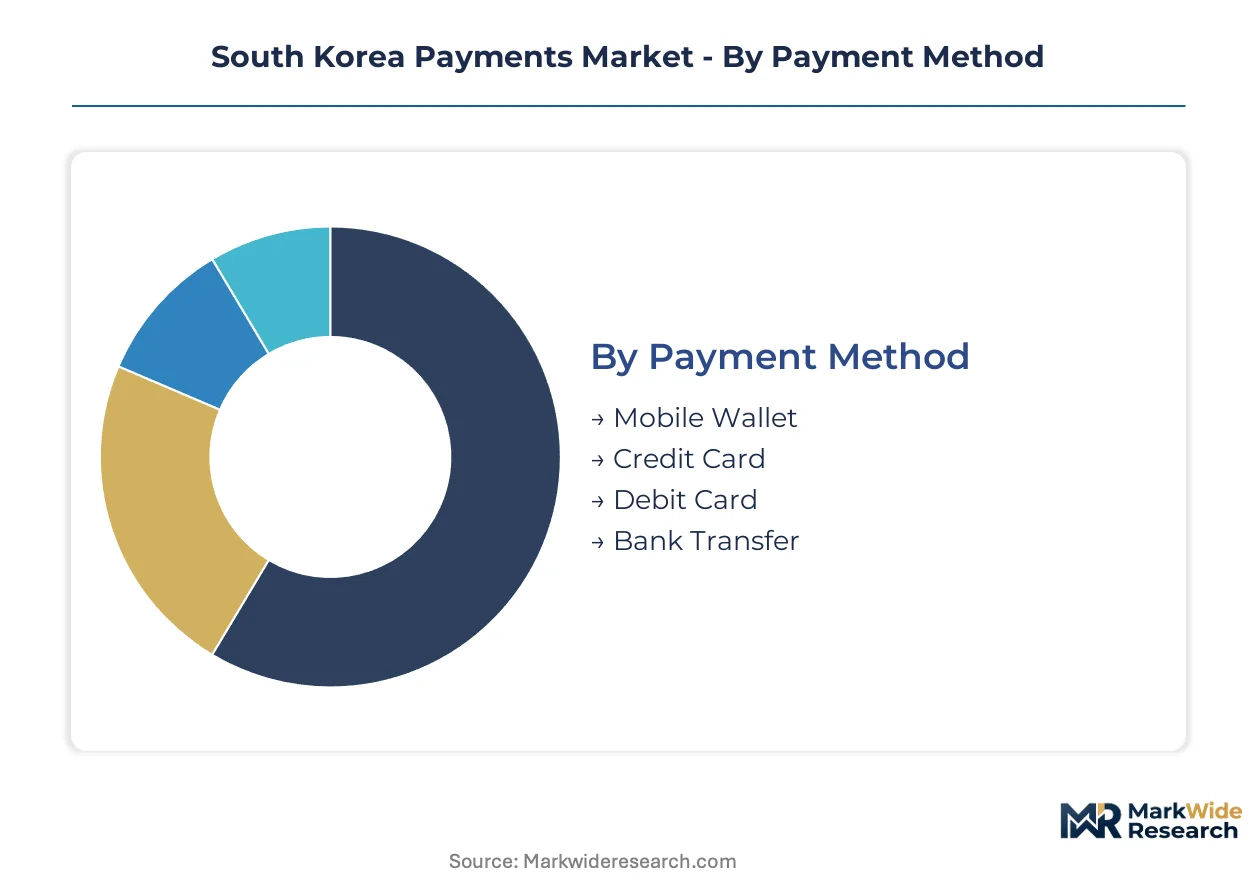
Payment infrastructure in South Korea fragments across four critical dimensions that determine procurement priorities and vendor selection criteria. Methodology preferences, transaction context, demographic concentration, and service sophistication each create distinct competitive battlegrounds for market participants.
Payment Method:
Buyer sophistication separates merchants seeking hardware-light acceptance from those prioritizing established network reliability.
- Mobile Wallet:NFC-enabled smartphone credentials eliminate dedicated terminal hardware. Seoul's dense retail corridors in Gangnam and Myeongdong drive merchant adoption as foot traffic density justifies rapid terminal replacement cycles.
- Credit Card:EMV chip and magnetic stripe networks maintain dominance in high-ticket retail and hospitality. Established interchange frameworks and consumer revolving credit habits preserve volume concentration among department stores and luxury merchants.
- Debit Card:Real-time bank account deduction appeals to budget-conscious segments seeking spending control. NH Bank and KB Kookmin card issuance programs target salary account holders with cashback incentives.
- Bank Transfer:Direct account-to-account settlement dominates B2B corridors and utility bill payments. The Bank of Korea's real-time gross settlement infrastructure enables sub-second confirmation for corporate treasury operations.
Volume sits with credit card networks; growth tilts toward mobile wallet credentials.
Transaction Type:
Settlement timing requirements and reconciliation complexity distinguish merchant procurement priorities across use cases.
- Online Payment:E-commerce checkout flows demand tokenized credential vaulting and 3D Secure authentication. Gyeonggi Province fulfillment center density supports same-day delivery expectations that compress payment authorization windows.
- Point of Sale:Physical terminal acceptance concentrates in Seoul's retail corridors with contactless NFC deployment. Merchant acquirers compete on terminal subsidy programs and same-day settlement guarantees.
- Recurring Payment:Subscription billing automation requires vault-stored credentials and intelligent retry logic. OTT platforms and fitness chains drive demand for failed-transaction recovery workflows.
- Peer-to-Peer Transfer:Messaging-integrated fund movement accelerates fastest among Gen Z cohorts in university districts. Split-payment social norms dominate group consumption in dense apartment complexes.
Revenue pools concentrate in point-of-sale acquiring; expansion is steepest in peer-to-peer channels.
Consumer Segment:
Technology comfort and financial product sophistication determine platform engagement depth and service bundling tolerance.
- Millennials:Primary income earners with established credit histories and multi-product banking relationships. Mortgage and investment product cross-selling opportunities accompany payment service adoption.
- Gen Z:Digital-native cohorts exhibiting super-app consolidation and minimal branch interaction. University district concentration in Sinchon and Hongdae shapes peer-to-peer payment social norms.
- Professionals:High-income earners prioritizing expense management tools and corporate card integration. Business travel and entertainment spending drives premium reward program engagement.
- Seniors:Cash-preferred segment requiring simplified interfaces and voice-assisted authentication. Branch-dependent habits resist mobile-first migration despite government digital inclusion initiatives.
Transaction value concentrates with professionals; user growth is expanding most quickly among Gen Z.
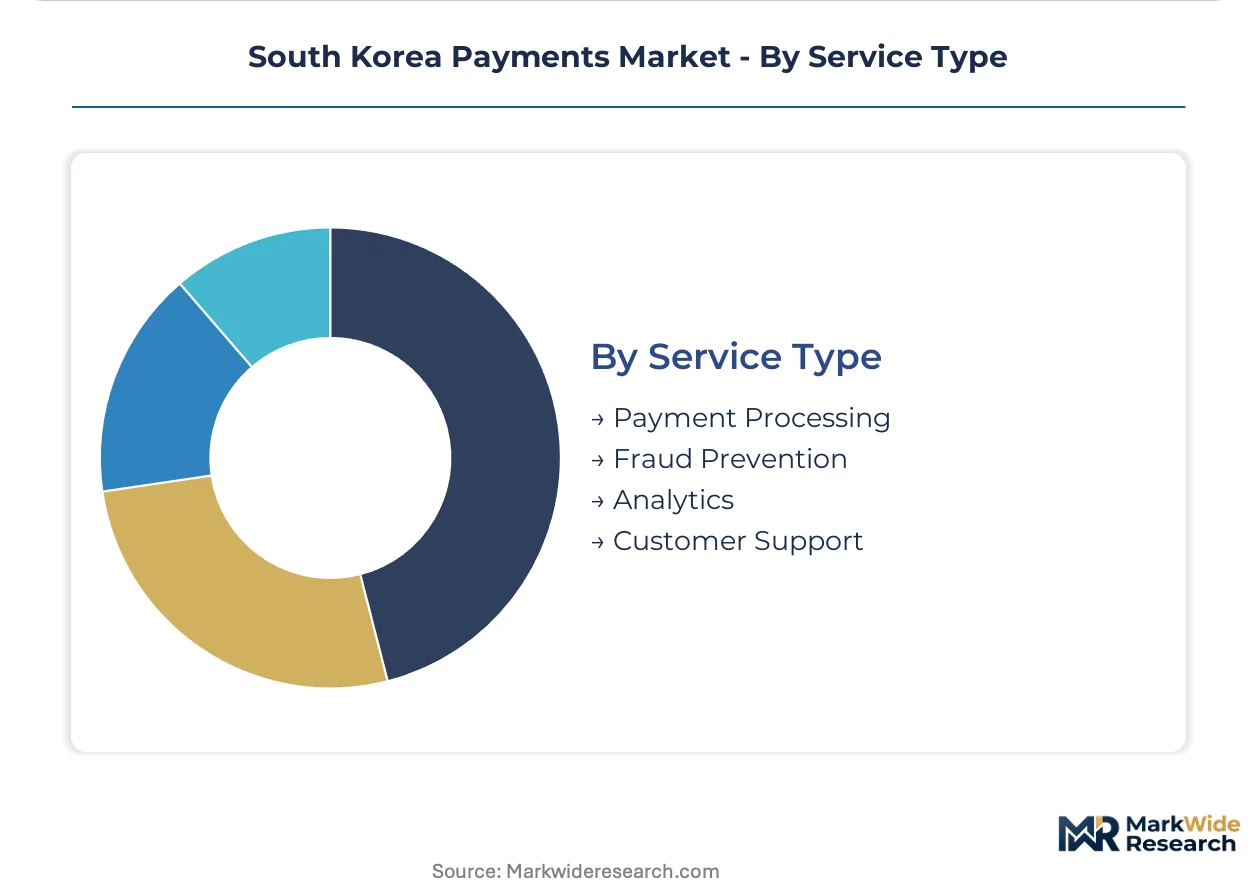
Service Type:
Margin capture potential and technical integration burden separate commodity processing from value-added service layers.
- Payment Processing:Core transaction authorization and settlement rails operate on thin margins with scale-dependent economics. Real-time infrastructure investments by the Bank of Korea compress latency differentiation among processors.
- Fraud Prevention:Machine learning transaction scoring and behavioral biometrics command premium pricing. MFDS authentication guidelines mandate certified security architectures that elevate vendor qualification barriers.
- Analytics:Merchant transaction data monetization and consumer spending pattern insights drive SaaS subscription models. Retailers in Busan-Ulsan manufacturing corridors seek supply chain payment optimization tools.
- Customer Support:Dispute resolution and chargeback management services address regulatory compliance requirements. Multi-party split-payment reconciliation introduces complex settlement logic demanding specialized operational expertise.
Revenue stability sits with payment processing; margin expansion tilts toward fraud prevention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Seoul's dense retail corridors where merchant acquirers deploy contactless terminals at accelerated pace. The Financial Services Commission's open banking mandates are compressing API standardization timelines across all sub-regions. Regional payment infrastructure maturity varies sharply between the capital area and secondary industrial belts.
Seoul Capital Area
Gangnam and Myeongdong retail density drives NFC terminal deployment at scale. The Financial Services Commission enforces open banking interoperability standards that force incumbent banks to expose payment initiation interfaces. University districts in Sinchon and Hongdae concentrate Gen Z peer-to-peer transaction volume within messaging-integrated super-apps.
Busan-Ulsan
Port logistics and heavy manufacturing corridors remain underpenetrated by mobile wallet adoption relative to consumer-facing Seoul. The Bank of Korea supervises real-time gross settlement stability for corporate treasury operations across industrial zones. Manufacturing belt B2B payment digitization lags consumer adoption despite infrastructure availability.
Daegu-Gyeongbuk
Textile and electronics manufacturing clusters generate concentrated B2B transaction flows requiring bank transfer rails. MFDS biometric authentication guidelines shape mobile wallet security architecture for regional financial institutions. Daegu's mid-tier retail corridors are deploying contactless terminals through subsidized acquirer programs.
Daejeon-Sejong
Government administrative concentration creates structured procurement for digital payment infrastructure across public services. The Financial Services Commission's regulatory sandbox permits fintech experimentation with limited geographic scope. Sejong's planned city design incorporates contactless payment acceptance into municipal service architecture from inception.
Gwangju-Honam
Agricultural supply chains and regional banking networks maintain stronger cash dependency than metropolitan sub-regions. Government digital inclusion initiatives target senior segments with simplified authentication interfaces. Honam's retail corridors show accelerating mobile wallet adoption among younger cohorts migrating from card-present habits.
South Korea Payments Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue embedded finance integration and super-app consolidation. The market structure tilts toward ecosystem dominance rather than standalone payment processing scale. Three archetypes define competitive positioning: platform-integrated super-apps anchoring consumer engagement, hardware manufacturers controlling terminal infrastructure, and global network operators managing cross-border rails. Dominant competitive moves include API-based partnership expansion and biometric authentication certification racing.
Within the domestic platform tier, Kakao Pay Corp. and NHN PAYCO Corp. exemplify divergent specialization strategies—one leveraging messaging ecosystem lock-in, the other pursuing gaming and content-commerce verticals. Samsung Electronics Co. Ltd. anchors hardware-dependent point-of-sale acceptance through device manufacturing integration. These three entities represent the core competitive tension between software platform consolidation and hardware infrastructure control.
| Leading Market Players |
|---|
| NHN PAYCO Corp. |
| Visa Inc. |
| Kakao Pay Corp. |
| American Express Company |
| Mastercard Inc. |
| Naver Corporation |
| Samsung Electronics Co. Ltd. |
| Rapyd Financial Networks Ltd. |
| Viva Republica Inc. |
| Others |
Value Network & Pricing Analysis
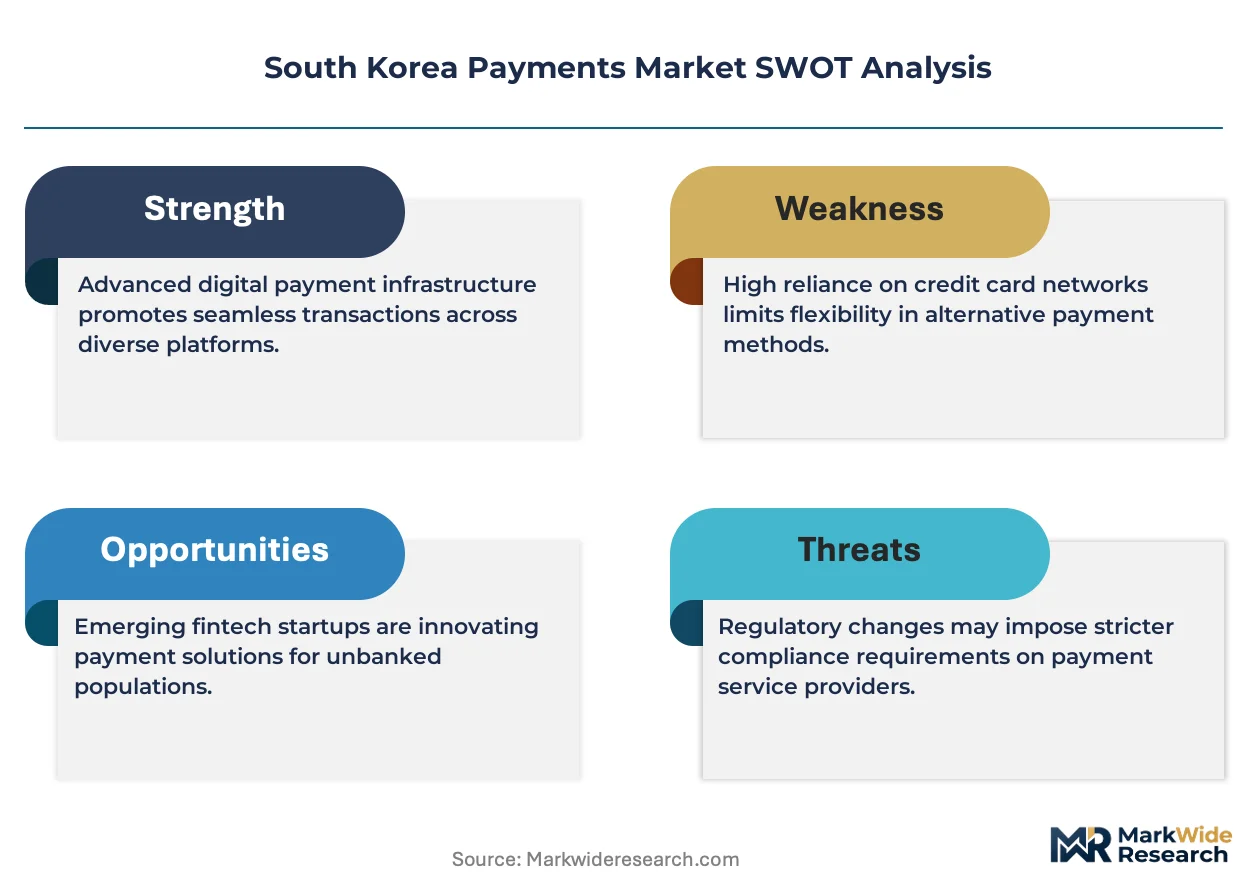
Merchant discount rate compression mandated by the Financial Services Commission is forcing acquirers to absorb margin erosion while demanding volume commitments from terminal manufacturers. Supply-side concentration in NFC chip fabrication tightens procurement leverage, elevating hardware costs for independent merchants seeking contactless acceptance infrastructure.
Pricing Analysis
High-volume peer-to-peer transfers operate on minimal yields while point-of-sale acquiring retains thicker margins through terminal subsidy recovery. Three-tier pricing structure across premium biometric-enabled, standard NFC, and economy magnetic-stripe acceptance separates merchant tiers by authentication sophistication. Cost compression in standard-tier hardware is intensifying because Taiwan foundry capacity constraints elevate secure element pricing. Budget-conscious independent merchants in Gwangju-Honam exhibit greatest price sensitivity; luxury department stores in Gangnam demonstrate lowest.
Supply Chain Analysis
Freight cost volatility from Taiwan and China semiconductor hubs elevates landed costs for NFC terminal components arriving at Busan port. Secure element production concentrates in Taiwan and South Korean foundries; plastic card stock feeds from China and Vietnam. Single-source vulnerability in advanced biometric sensor supply creates procurement risk for MFDS-compliant wallet providers. Distribution runs through Seoul-based merchant acquirer networks with direct terminal deployment to retail corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korea Payments Market occupies a technology-transition phase where host card emulation displaces dedicated hardware security modules. Software-based credential vaulting is replacing legacy chip-and-PIN terminal dependence across Seoul's retail infrastructure.
For Market Incumbents: Cement API interoperability advantages by accelerating open banking certification ahead of regulatory deadlines. Incumbent acquirers must deepen backward integration into cloud-native processing infrastructure to defend against fintech entrants exploiting middleware gaps. The Financial Services Commission's standardization timeline compresses differentiation windows.
For New Entrants and Emerging Players: Begin with underpenetrated B2B corridors in Busan-Ulsan manufacturing belts where mobile wallet adoption lags consumer Seoul. Industrial payment digitization between port logistics and heavy manufacturing presents white-space opportunity. Target mid-tier textile processors in Daegu-Gyeongbuk with supply chain payment optimization tools.
For Investors and Strategic Acquirers: The window for entry favors embedded finance specialists with API development capabilities over standalone processors. Long-term viability hinges on super-app ecosystem integration rather than transaction volume scale. Watch the Bank of Korea's CBDC pilot expansion as inflection signal for tokenized settlement infrastructure positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| API Certification Acceleration | Financial Services Commission mandates compress qualification timelines for open banking participation. |
| Biometric Authentication Investment | MFDS guidelines on facial verification elevate hardware requirements for mobile wallet providers. |
| Manufacturing Belt Expansion | Busan-Ulsan industrial corridors remain underpenetrated by consumer-focused payment platforms. |
| Cross-Border Remittance Licensing | Gyeonggi Province migrant worker populations drive demand for formal international transfer rails. |
| CBDC Infrastructure Positioning | Bank of Korea wholesale pilot extension would recalibrate competitive advantage across settlement layers. |
Research Methodology
Independent corroboration across merchant acquirer executives, fintech platform architects, and Bank of Korea policy specialists underwrites the qualitative findings. Primary interviews with payment network operators, terminal hardware procurement managers, and MFDS compliance officers combined with secondary validation from Financial Services Commission regulatory filings, Bank of Korea settlement system disclosures, and customs import records for NFC components. Bottom-up transaction volume estimates and top-down infrastructure deployment counts triangulate market sizing.
Rate-of-change decomposition across the analysis window separates volume growth from value compression effects. Segmentation dimensions modeled include payment method, transaction type, consumer demographic, and service sophistication tier, with additional industry-specific dimension of regulatory compliance tier. CAGRs derive from infrastructure deployment trajectories and cohort-specific adoption curve analysis. Forecast inputs incorporate real-time gross settlement volume trends and super-app user consolidation patterns.
Underlying measurement precision varies by segment; Seoul Capital Area retail corridor data carries tighter precision than Honam agricultural supply chain estimates. Forecasts reflect assumptions on regulatory timeline adherence and biometric certification adoption rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Ghana Mobile Money Market
Payments
Ireland POS Terminals Market
Payments
Convergent Billing Market
Payments
United States POS Terminals Market
Payments
United States Payments Market
Payments
Europe Gift Card and Incentive Card Market
Payments
United Kingdom Real Time Payments Market
Payments
Payment Instruments Market
Payments
Italy Gift Cards Market
Payments
Asia-Pacific Payment Analytics Software Market
Payments
Buy Now Pay Later Market
Payments
Brazil Real Time Payments Market
Payments
Denmark Payments Market
Payments
Global Gift Card Market
Payments
Europe Payments Market
Payments
Africa Mobile Money Market