
 Ireland POS Terminals Market | 2026-2036
Ireland POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Ireland POS Terminals Market Foresight
Buyer concentration across Ireland's hospitality sector is decoupling as independent restaurants and boutique hotels fragment procurement away from legacy bank-supplied terminal pools. SumUp Inc. leverages its mobile-first hardware to capture street-market and pop-up vendors in Galway and Limerick. NCR Corporation anchors large-format retail deployments through its Dublin service infrastructure. Shopify Inc. competes by bundling POS hardware with its e-commerce platform for omnichannel merchants in Cork and Belfast corridor.
A POS terminal integrates payment processing hardware with software interfaces, typically incorporating EMV chip readers, NFC antennas, thermal receipt printers, and PCI-DSS encrypted communication modules to authenticate and settle card transactions at the point of sale. Mobile terminals lead volume growth among food-truck operators and festival vendors seeking battery-operated, 4G-connected units, while fixed terminals sustain margin pools in supermarket and pharmacy chains requiring dual-screen customer-facing displays. Cloud-based deployment is displacing on-premise installations as Irish SMEs prioritize real-time sales analytics and remote firmware management over capital-intensive server ownership.
The Central Bank of Ireland governs payment system oversight and consumer protection standards, while the National Cyber Security Centre mandates incident reporting protocols for financial infrastructure operators. GDPR compliance through Ireland's Data Protection Commission shapes terminal software architectures, particularly around transaction data retention and cross-border cloud storage. Stakeholders must weigh hardware refresh timing against evolving contactless limits and incoming EU digital identity wallet interoperability requirements.
Market Dynamics
Cloud-connected POS infrastructure is fragmenting Ireland's historically bank-dominated terminal procurement, as independent merchants in Cork and Galway bypass legacy leasing pools for subscription-based hardware models.
Growth Catalysts
- Central Bank contactless thresholds:The Central Bank of Ireland's periodic limit adjustments force hardware refresh cycles among merchants seeking tap-to-pay compliance.
- Food-truck mobility demand:Battery-operated 4G terminals are capturing street-market vendors across Limerick and festival circuits.
- GDPR-compliant cloud architectures:Ireland's Data Protection Commission mandates shape terminal software design, accelerating SME migration from on-premise servers.
Market Restraints
- PCI-DSS certification timelines:Hardware encryption module validation creates 8-14 month product launch delays for new entrants.
- Semiconductor input volatility:NFC antenna chip supply concentrates among Asian foundries, exposing Irish distributors to allocation risk.
- Legacy bank terminal pools:Permanent tsb and AIB merchant services retain pricing power through bundled acquiring contracts.
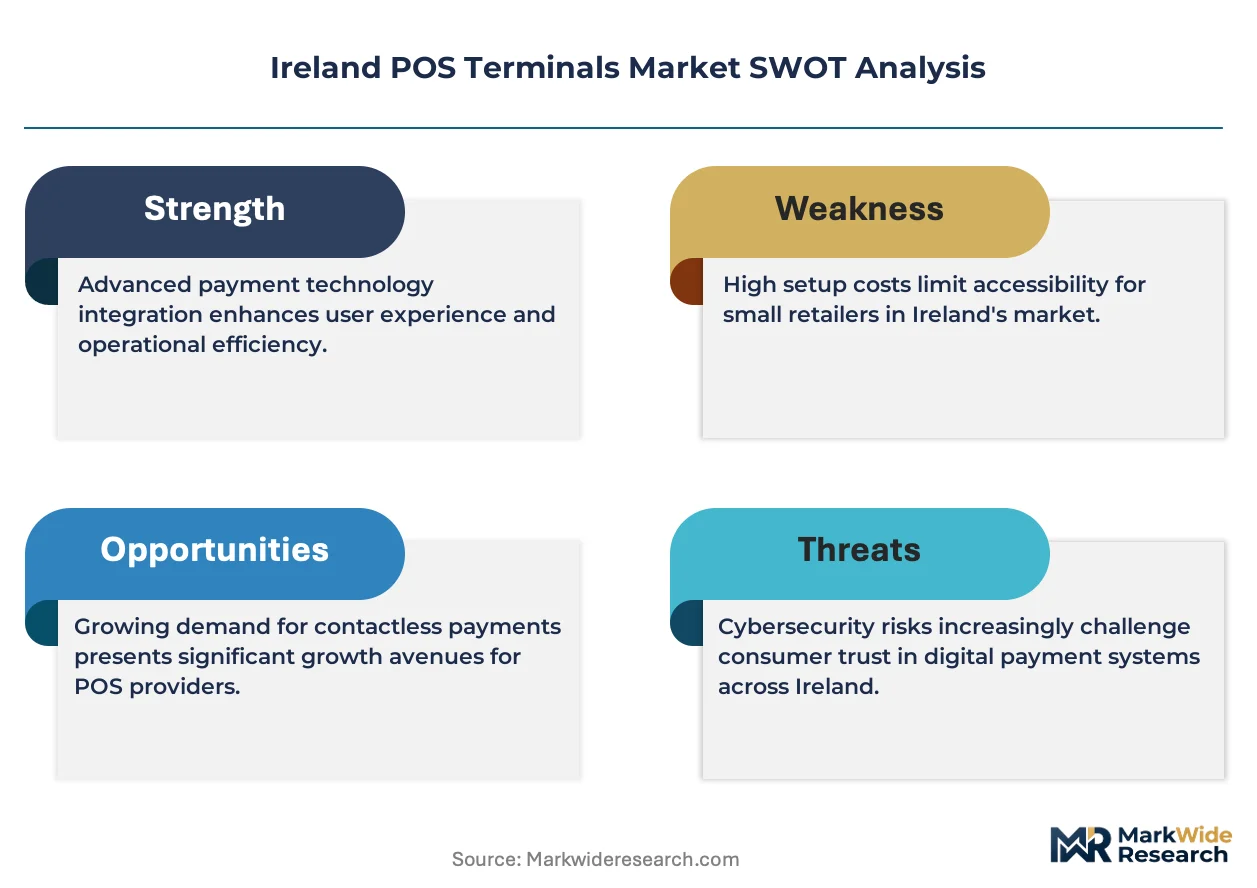
Strategic Opportunities
- EU Digital Identity Wallet convergence:Incoming interoperability standards create first-mover advantage for terminals supporting eID authentication.
- Omnichannel merchant bundling:Cork-based retailers with hybrid online-offline operations seek unified payment-hardware-software stacks.
- Galway's festival economy:Temporary event infrastructure demands short-term terminal rental models underserved by traditional lessors.
Industry Challenges
- EMV kernel integration complexity:Certification with multiple acquirer networks strains engineering resources at mid-tier hardware vendors.
- Cross-border data residency:GDPR Article 44 compliance for cloud-stored transaction logs requires Irish-hosted infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ireland POS Terminals Market |
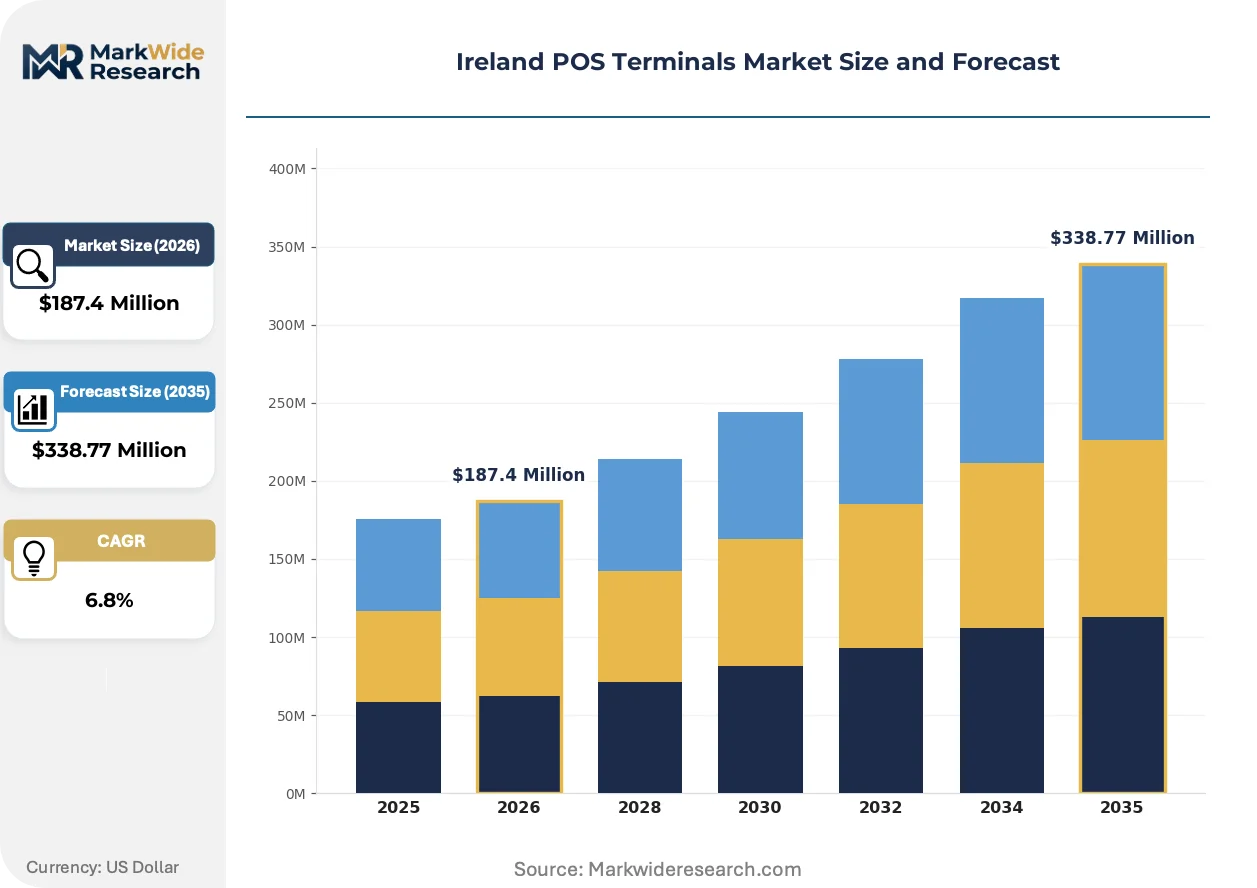
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Mobile Terminals, Fixed Terminals, Contactless Terminals, Self-service Terminals Technology: Chip & PIN, Magnetic Stripe, NFC, QR Code End User: Retailers, Restaurants, Hospitality, Transportation Deployment: Cloud-based, On-premise, Hybrid, Others |
| Companies Covered | SumUp Inc., Postree, Shopify Inc., NEC Corporation, Sharp Electronics, NCR Corporation, Block, Inc. (Square), myPOS World Ltd., VeriFone System Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ireland POS Terminals Market Shifts & Advancements
Payment terminal architecture is pivoting from transaction-only devices to commerce-enablement platforms, embedding software marketplaces and merchant analytics directly at the point of sale.
SoftPOS technology is integrating NFC-enabled smartphones and tablets as certified payment acceptance devices, eliminating dedicated hardware for micro-merchants. Galway pop-up vendors and Dublin market traders are adopting this capability fastest, collapsing entry costs from hundreds to tens of euros per merchant. The technology is integrating payment acceptance into existing merchant workflows rather than requiring standalone terminal procurement.
The Data Protection Commission's enforcement of GDPR Article 25 data protection by design is mandating privacy-preserving terminal architectures with minimized data retention. Hardware vendors must engineer automatic transaction log purging and pseudonymized analytics exports. Irish hospitality chains in the Leinster belt are prioritizing terminals with built-in data residency controls over lower-cost alternatives lacking these features.
Merchant acquiring relationships are unbundling from hardware supply, with independent software vendors and direct terminal manufacturers capturing margin previously held by banks. Boutique hotels in Kerry and independent retailers in Belfast corridor now procure hardware separately from payment processing, comparing acquiring rates across multiple providers. This pattern is most visible among merchants processing under €500,000 annually, where switching costs have fallen dramatically.
Ireland POS Terminals Market Segmentation
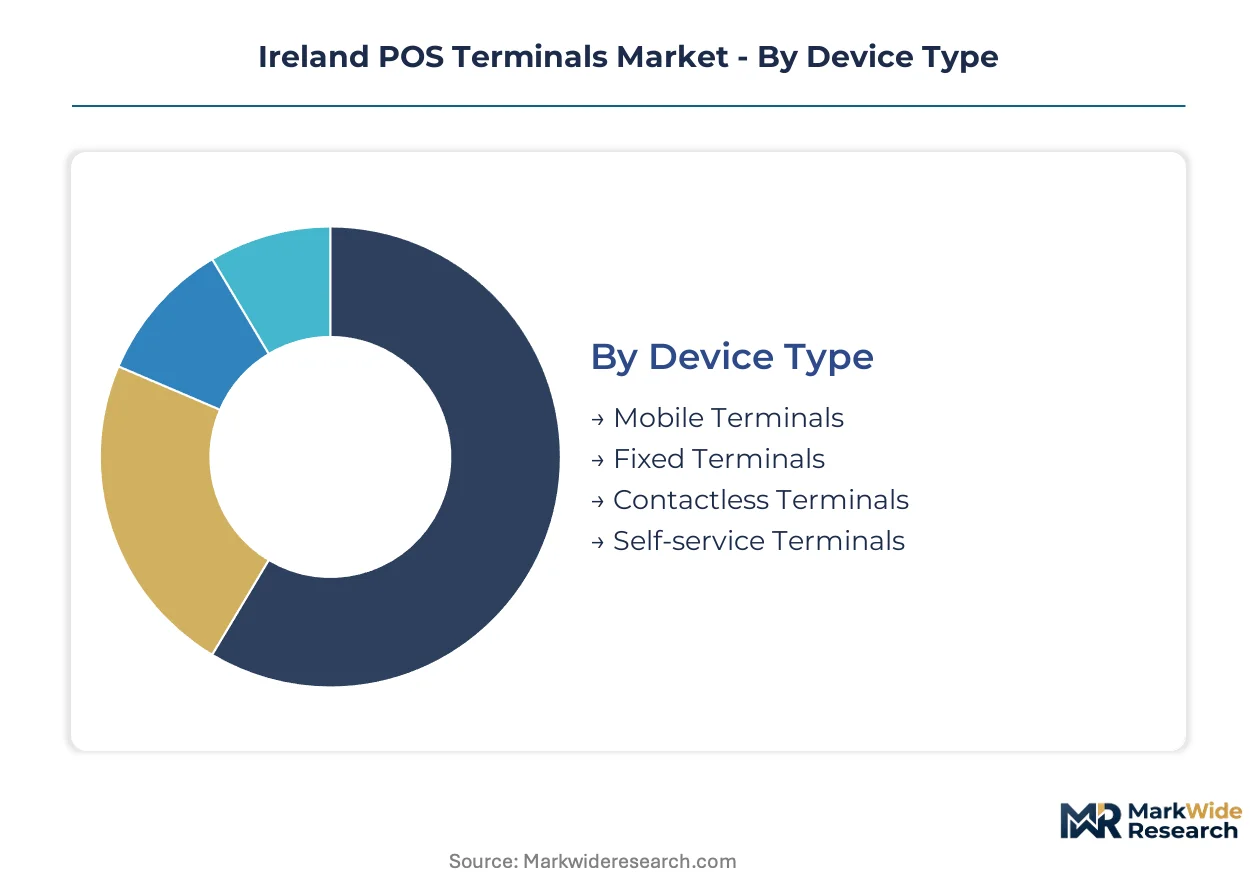
Hardware certification requirements and deployment complexity fragment procurement strategies across Irish merchant tiers. Understanding segment boundaries clarifies where PCI-DSS validation burdens fall heaviest and where cloud migration unlocks cost efficiencies.
Device Type:
PCI-DSS Level 1 certification demands scale with terminal mobility and connectivity architecture, creating divergent compliance timelines across hardware categories.
- Mobile Terminals:Battery-powered units with integrated 4G modems and EMV chip readers. Demand concentrates among Galway food-truck operators and Limerick street-market vendors seeking untethered payment acceptance at festival sites.
- Fixed Terminals:Countertop devices with Ethernet connectivity and dual-screen configurations. Dublin supermarket chains and Cork pharmacy groups deploy these for high-throughput checkout environments requiring customer-facing displays.
- Contactless Terminals:NFC-enabled hardware supporting tap-to-pay protocols. Leinster hospitality venues refresh these units most aggressively to track Central Bank threshold adjustments.
- Self-service Terminals:Kiosk-integrated payment modules with touchscreen interfaces. Belfast corridor retail parks trial these for reduced labor dependency at high-volume locations.
Leading the category by volume: Fixed Terminals. Expanding most quickly: Mobile Terminals.
Technology:
Authentication protocol selection determines hardware cost tiers and merchant vulnerability to fraud liability shifts.
- Chip & PIN:EMV-compliant card insertion with encrypted PIN entry. Kerry boutique hotels and independent retailers maintain these as fallback methods when contactless limits exceed transaction values.
- Magnetic Stripe:Legacy swipe-reading capability retained for international card compatibility. Declining deployment across Irish merchants as liability shifts to non-EMV acquirers.
- NFC:Near-field communication enabling tap-to-pay under Central Bank thresholds. Dublin's retail corridor drives volume as contactless penetration reaches saturation among urban consumers.
- QR Code:Optical scanning for alternative payment app integration. Emerging adoption among Cork omnichannel merchants bridging online wallet users to physical checkout.
Dominant by transaction share: NFC. Steepest decline trajectory: Magnetic Stripe.
End User:
Vertical-specific workflow demands shape terminal feature prioritization and replacement cadence.
- Retailers:High-volume merchants requiring inventory integration and multi-acquirer support. Cork-based hybrid online-offline operators seek unified hardware-software stacks.
- Restaurants:Tableside payment and tip-adjustment functionality. Galway gastropubs and independent cafés favor mobile terminals enabling curbside settlement.
- Hospitality:Property management system integration and pre-authorization capability. Kerry boutique hotels unbundle hardware from bank-supplied acquiring pools.
- Transportation:Ruggedized units with fare-calibration and route-tracking features. Limited penetration outside Dublin commuter rail and airport taxi fleets.
Highest hardware refresh rate: Restaurants. Slowest technology migration: Transportation.
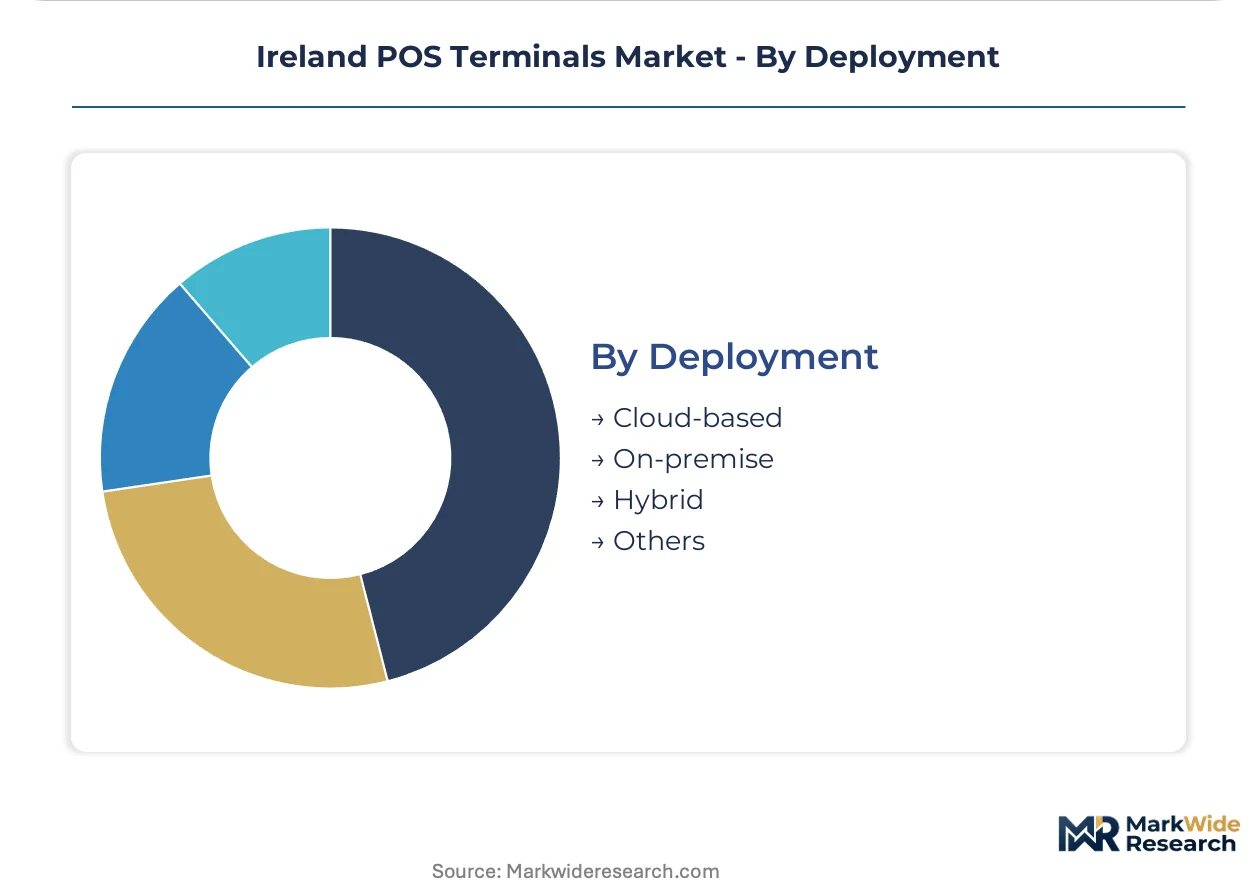
Deployment:
Capital intensity and data sovereignty requirements split merchant preferences between ownership models.
- Cloud-based:Subscription-hosted infrastructure with remote firmware management and real-time analytics. Irish SMEs under €500,000 annual processing migrate fastest to minimize server ownership.
- On-premise:Local server installation with direct network control. Declining preference as GDPR Article 44 compliance burdens shift preference toward Irish-hosted cloud alternatives.
- Hybrid:Mixed architecture with sensitive data retained locally and analytics exported to cloud. Pharmacy chains and mid-market retailers trial this for regulatory risk mitigation.
- Others:Edge-computing and containerized deployments for specialized latency requirements. Minimal adoption outside payment processor test environments.
Gaining share fastest: Cloud-based. Steady residual demand: On-premise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand clusters most visibly in Dublin's retail corridor and the greater Leinster hospitality belt, with independent cafés and gastropubs across Cork and Galway accelerating adoption of cloud-connected terminals.
Dublin and Greater Leinster
The Central Bank of Ireland's contactless payment thresholds drive hardware refresh cycles among high-throughput merchants. GDPR compliance through the Data Protection Commission shapes terminal software architectures for real-time sales analytics. Dublin's retail corridor sustains fixed terminal deployments in supermarket and pharmacy chains requiring dual-screen customer-facing displays.
Cork
Omnichannel merchants with hybrid online-offline operations seek unified payment-hardware-software stacks. The Central Bank of Ireland governs payment system oversight and consumer protection standards for cross-border cloud storage. Independent retailers in the Belfast corridor now procure hardware separately from payment processing, comparing acquiring rates across multiple providers.
Galway
Food-truck operators and festival vendors demand battery-operated, 4G-connected mobile terminals for untethered payment acceptance. The National Cyber Security Centre mandates incident reporting protocols for financial infrastructure operators. Street-market and pop-up vendors adopt SoftPOS technology fastest, collapsing entry costs from hundreds to tens of euros per merchant.
Limerick
Street-market vendors across festival circuits drive volume growth for mobile terminal categories. PCI-DSS certification timelines for hardware encryption module validation create product launch delays that mid-tier vendors navigate. Temporary event infrastructure demands short-term terminal rental models underserved by traditional lessors.
Kerry
Boutique hotels unbundle hardware from bank-supplied acquiring pools as merchant acquiring relationships separate from hardware supply. Ireland's Data Protection Commission enforces GDPR Article 25 data protection by design for privacy-preserving terminal architectures. Hospitality chains prioritize terminals with built-in data residency controls over lower-cost alternatives lacking these features.
Ireland POS Terminals Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue mobile-first and subscription-based hardware models. The vendor base spans consolidated multinational service infrastructures and fragmented independent software vendors. Three archetypes dominate: bank-affiliated legacy lessors, cloud-native hardware disruptors, and omnichannel platform bundlers. Competitive moves center on geographic service infrastructure expansion and strategic unbundling of hardware from acquiring relationships.
Among mobile-first disruptors, SumUp Inc. and myPOS World Ltd. exemplify the archetype of low-entry-cost hardware targeting street-market and pop-up vendor segments. NCR Corporation anchors the large-format retail deployment tier through established service infrastructures. Shopify Inc. occupies a position within the omnichannel bundling archetype, competing by integrating POS hardware with e-commerce platforms for hybrid merchants.
| Leading Market Players |
|---|
| SumUp Inc. |
| Postree |
| Shopify Inc. |
| NEC Corporation |
| Sharp Electronics |
| NCR Corporation |
| Block, Inc. (Square) |
| myPOS World Ltd. |
| VeriFone System Inc. |
| Others |
Supply & Pricing Matrix
NFC antenna chip fabrication costs cascade through three distinct hardware tiers, with Asian foundry allocation constraints compressing margins at the entry-level mobile terminal segment while premium fixed-terminal vendors absorb volatility through longer-term service contracts.
Pricing Analysis
High-volume mobile terminals trade margin for market share while fixed-terminal deployments sustain premium pricing through bundled service agreements. Three-tier pricing structure across enterprise-grade, mid-market, and micro-merchant levels reflects PCI-DSS certification grade and after-sales infrastructure depth. Pricing pressure stems from SoftPOS technology collapsing hardware entry costs below fifty euros per merchant. Micro-merchants in Galway's street markets exhibit highest price sensitivity; Dublin supermarket chains prioritize data residency controls over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for EMV kernel certification push Irish distributors to qualify alternative NFC chip suppliers beyond dominant Taiwan and South Korea foundries. Hardware assembly concentrates in China, Vietnam, and Malaysia, with encryption module production anchored in Germany and the United States. Semiconductor input volatility from single-source NFC antenna suppliers exposes distributors to allocation risk during foundry capacity constraints. Distribution runs through Dublin-based value-added resellers serving Leinster corridor, with direct manufacturer relationships penetrating Cork and Galway merchant tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based terminal architectures are displacing on-premise legacy systems, with subscription SaaS models replacing capital-intensive hardware ownership across Irish SME tiers.
For Market Incumbents: Extend service infrastructure depth in Cork and Galway to defend against mobile-first disruptors capturing micro-merchant segments. Deepen backward integration into encryption module supply to mitigate semiconductor allocation risk. Anchor large-format retail relationships through real-time analytics bundling that cloud-native competitors cannot match. For New Entrants and Emerging Players: Direct-to-merchant digital onboarding platforms bypass traditional distributor markups and accelerate Galway festival-circuit penetration. Target temporary event infrastructure with short-term rental models underserved by legacy bank lessors. Lead with SoftPOS compatibility to collapse customer acquisition costs below incumbent hardware procurement thresholds. For Investors and Strategic Acquirers: Central Bank contactless threshold adjustments are the leading indicator that hardware refresh cyclicality will intensify, favoring vendors with rapid certification pipelines. Long-term viability rests on cloud-native architecture rather than terminal manufacturing scale. Acquisition targets should display Irish-hosted data infrastructure and established Data Protection Commission compliance frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Migration | Enables real-time sales analytics for Cork omnichannel merchants while reducing GDPR Article 44 compliance burdens. |
| SoftPOS Certification Investment | Collapses entry costs for Galway pop-up vendors and fragments bank-dominated terminal procurement relationships. |
| Irish Data Residency Expansion | Satisfies Data Protection Commission requirements for transaction log hosting and pre-empts cross-border storage restrictions. |
| Festival Circuit Rental Models | Captures temporary event demand in Limerick and Galway underserved by traditional hardware lessors. |
| EU Digital Identity Wallet Integration | Positions terminals for incoming eID authentication standards and creates first-mover advantage in hospitality verticals. |
Research Methodology
Multi-period observation of terminal deployment volumes, contactless transaction thresholds, and cloud-migration patterns anchored the trend analysis, supplemented by interviews with payment hardware procurement managers, hospitality IT directors, and independent café operators. Primary fieldwork combined with secondary validation against Central Bank of Ireland regulatory filings, Data Protection Commission enforcement notices, and National Cyber Security Centre incident reports. Bottom-up merchant-tier sizing triangulated with top-down market value estimates derived from distributor shipment data and service contract disclosures.
Segment-weighting approaches distributed value across device type, deployment model, and end-user vertical dimensions throughout the projection horizon. CAGRs were derived from fitted growth curves incorporating hardware refresh cycle timing, regulatory threshold adjustment frequency, and SME cloud-adoption velocity. Forecast inputs included PCI-DSS certification pipeline durations, semiconductor foundry capacity allocation trends, and SoftPOS penetration rates among micro-merchants.
The model holds under stable Central Bank contactless policy and continued GDPR enforcement consistency; deviation in encryption module supply disruption or EU Digital Identity Wallet acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Accounts Payable Software Market
Payments
South Africa Gift Card and Incentive Card Market
Payments
Slovakia POS Terminal Market
Payments
Payment Service Provider Market
Payments
United Kingdom Real Time Payments Market
Payments
Direct Carrier Billing Platform Market
Payments
Asia-Pacific Payments Market
Payments
Global Utility Billing Software Market
Payments
UK Virtual Cards Market
Payments
Japan Credit Cards Market
Payments
Proximity Payment Market
Payments
Retail POS Terminals Market
Payments
MENA Digital Payments Market
Payments
Greece POS Terminals Market
Payments
Uganda Mobile Money Market
Payments
Global Virtual Cards Market