
 South Korea Data Center Rack Market | 2026-2036
South Korea Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Data Center Rack Market Insights
Data center rack distribution in South Korea is fragmenting as domestic system integrators challenge incumbent foreign suppliers for hyperscale contracts. Schneider Electric leverages its global service network to sustain large enterprise relationships across Seoul and Busan. Rittal anchors the industrial edge segment with localized manufacturing support. Vertiv competes aggressively on thermal-integrated rack systems for AI training clusters.
A data center rack is a standardized metal framework that houses servers, networking equipment, and power distribution units, typically built from cold-rolled steel with static load ratings exceeding 1,500 kg and compliant with IEC 60297-3-100 mounting dimensions. Its primary purpose is to organize IT hardware vertically while enabling cable management, airflow control, and physical security in controlled environments. Enclosed racks command premium positioning due to integrated fire suppression and access control requirements from financial services buyers in Seoul. Liquid cooling racks represent the fastest-growing configuration as GPU density requirements exceed 50 kW per cabinet. Standard 42U units remain the volume workhorse across telecommunications central offices nationwide.
MFDS thermal safety guidelines, KTL electrical certification standards, and the Ministry of Science and ICT's data center energy efficiency mandates collectively shape product design and procurement specifications for domestic deployments. The Korea Agency for Technology and Standards enforces structural load testing that foreign suppliers must complete through accredited local laboratories. Buyers should monitor how upcoming carbon intensity regulations for Gyeonggi Province facilities will alter rack-level power and cooling specifications.
Market Dynamics
Liquid cooling technology is compressing traditional air-cooled rack architectures as GPU density requirements exceed thermal limits, forcing suppliers to redesign structural load distribution and cable management systems for liquid-cooled configurations.
Growth Catalysts
- MFDS Thermal Safety Guidelines:MFDS-aligned certification requirements for fire suppression and thermal management are mandating upgraded rack specifications across Seoul financial services deployments.
- Hyperscale Campus Construction:Mega campus builds in Gyeonggi Province by domestic cloud operators are generating concentrated demand for high-load, liquid-ready rack systems.
- AI Training Cluster Expansion:GPU-intensive machine learning workloads are pulling specialized thermal-integrated rack configurations into hyperscale procurement pipelines.
Market Restraints
- Cold-Rolled Steel Price Volatility:Input cost fluctuations for structural steel are compressing margin structures for standardized 42U volume products.
- Foreign Supplier Certification Barriers:KTL electrical certification and Korea Agency for Technology and Standards structural load testing create extended approval timelines for non-domestic manufacturers.
- Technical Limitation on Retrofit Compatibility:Legacy raised-floor data centers face physical constraints integrating liquid cooling manifolds without full infrastructure replacement.
Strategic Opportunities
- Busan Industrial Edge Expansion:Manufacturing automation and port logistics digitization are creating underpenetrated demand for ruggedized, compact rack deployments outside Seoul concentration.
- Carbon Intensity Regulations:Upcoming Gyeonggi Province facility mandates will create procurement preference for rack-level power monitoring and cooling efficiency integration.
- Direct Liquid Cooling Convergence:Immersion cooling technology combined with high-voltage direct current power distribution is opening white space for integrated rack-power-cooling system suppliers.
Industry Challenges
- Thermal-Structural Engineering Talent Scarcity:Domestic system integrators face recruitment constraints for specialists bridging mechanical rack design and liquid cooling fluid dynamics.
- Multi-Certification Timeline Compression:Simultaneous pursuit of MFDS thermal, KTL electrical, and Ministry of Science and ICT energy efficiency approvals extends product launch cycles.
- Legacy Air-Cooled Infrastructure Integration:Hybrid deployments requiring seamless interoperability between traditional and liquid-cooled racks complicate installation and maintenance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Data Center Rack Market |
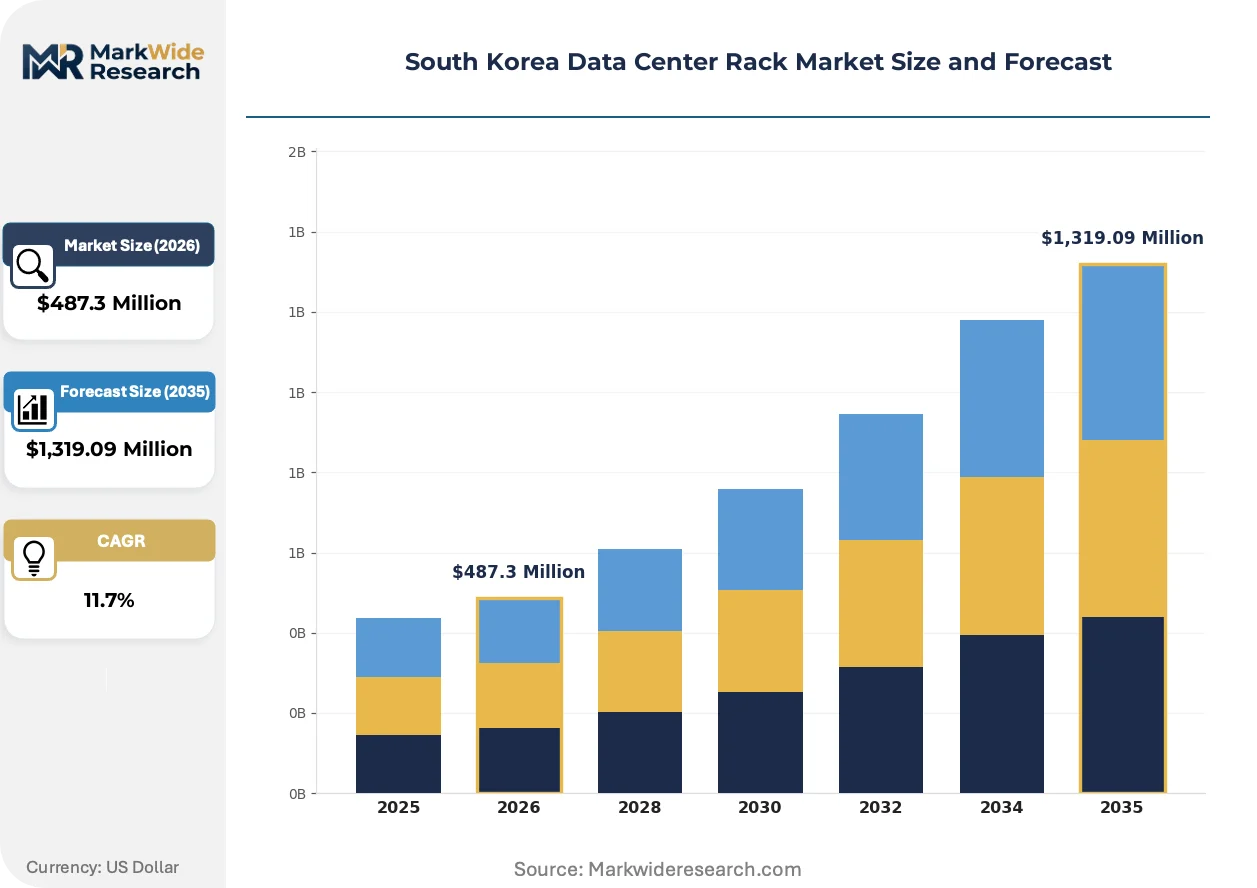
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Rack, Open Frame Rack, Enclosed Rack, Custom Rack End User: Telecommunications, IT & Telecom, Healthcare, Financial Services Cooling Method: Air Cooling, Liquid Cooling, Hybrid Cooling, Free Cooling Size: 42U, 48U, 36U, 24U |
| Companies Covered | Schneider Electric, Rittal, Delta Electronics, Eaton, Huawei, Vertiv, Legrand, STULZ, Honeywell, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Data Center Rack Market Trends and Innovations
Rack architecture is undergoing forced reinvention as thermal density requirements outpace incremental cooling improvements, compressing the viable lifespan of air-cooled designs and elevating liquid-cooled configurations from niche to mainstream procurement.
Direct-to-chip liquid cooling manifolds integrated into rack side panels are rendering obsolete rear-door heat exchanger retrofits for cabinets exceeding 50 kW density. Hyperscale operators in Gyeonggi Province are specifying these configurations in new-build RFPs. The structural consequence is collapsing demand for traditional perforated-door enclosures and raised-floor air distribution systems.
MFDS thermal safety guidelines now mandate integrated fire suppression sensing and automated shutoff capabilities for liquid-cooled rack deployments. This regulatory tightening is disqualifying uncertified foreign suppliers from financial services procurement in Seoul. Domestic system integrators are capturing share by pre-integrating MFDS-compliant suppression systems during manufacturing rather than field retrofit.
Specification authority is migrating from facilities engineering to IT infrastructure teams as rack purchasing decisions increasingly hinge on GPU compatibility and power density roadmaps rather than physical footprint. Channel relationships with value-added distributors possessing thermal engineering capabilities are displacing direct procurement from catalog suppliers. This shift is most visible in Naver and Kakao campus builds where infrastructure teams specify liquid-cooled rack configurations directly.
South Korea Data Center Rack Market Segmentation
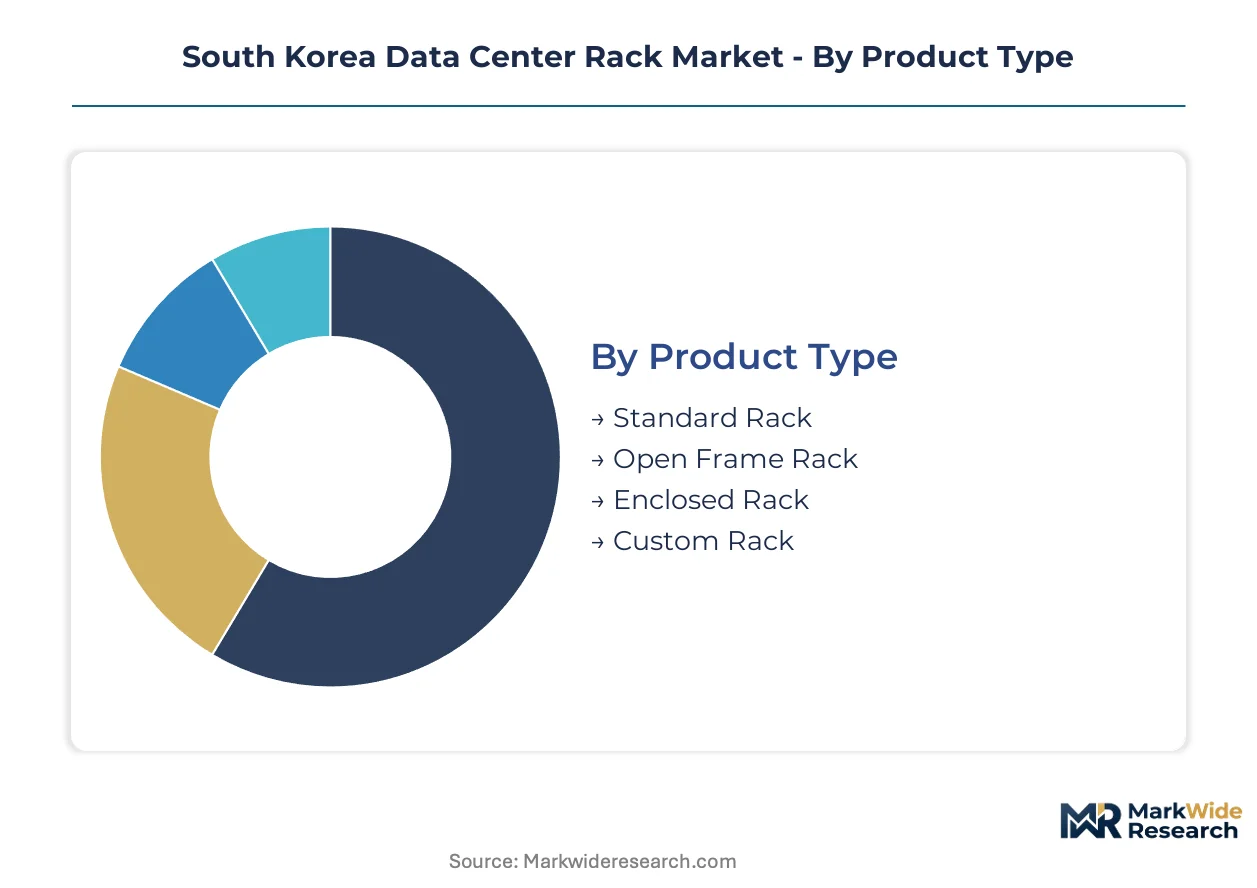
Rack configuration choices in South Korea increasingly hinge on thermal density roadmaps and regulatory compliance tiers rather than physical footprint alone. Segmentation reveals how hyperscale operators in Gyeonggi Province and financial institutions in Seoul are pulling demand toward divergent product specifications.
Product Type:
Mature standardized designs anchor volume procurement, while emerging configurations capture hyperscale premiums.
- Standard Rack:Cold-rolled steel frameworks with IEC 60297-3-100 mounting dimensions and static load ratings above 1,500 kg. Naver and Kakao specify these for general compute rows across their Gyeonggi Province mega campuses where density requirements remain below 30 kW per cabinet.
- Enclosed Rack:Integrated fire suppression sensing and access control systems meeting MFDS thermal safety guidelines. Seoul financial services buyers mandate these for trading floor deployments where physical security and automated shutoff capabilities outweigh cost premiums.
- Open Frame Rack:Structural frames without side panels or doors, favored by telecommunications central offices prioritizing cable accessibility over environmental isolation.
- Custom Rack:Application-specific dimensions and load distributions engineered for GPU-intensive AI training clusters requiring non-standard depth or reinforced mounting rails.
Standard Rack retains volume leadership; Custom Rack holds the steepest expansion curve.
End User:
Customer archetypes span infrastructure-scale deployers and compliance-intensive regulated sectors.
- IT & Telecom:Domestic cloud operators and hyperscale builders driving liquid-ready rack procurement for GPU density exceeding 50 kW per cabinet. Kakao and Naver infrastructure teams specify thermal-integrated configurations directly, bypassing traditional facilities procurement channels.
- Financial Services:Seoul-based banks and securities firms requiring MFDS-aligned fire suppression and KTL electrical certification. Enclosed racks with integrated access control dominate this segment where regulatory compliance overrides unit economics.
- Telecommunications:Legacy central office retrofits and 5G edge deployments favoring standard 42U air-cooled units with minimal customization.
- Healthcare:Medical imaging data storage and hospital IT infrastructure requiring moderate-density configurations with emphasis on reliability certifications.
IT & Telecom commands the largest procurement volumes; Financial Services generates the highest specification premiums.
Cooling Method:
Thermal architecture selection increasingly determines rack structural design rather than retrofit compatibility.
- Liquid Cooling:Direct-to-chip manifolds integrated into rack side panels, specified by hyperscale operators for cabinets exceeding 50 kW GPU density. Gyeonggi Province new-build RFPs are rendering traditional perforated-door enclosures obsolete through this configuration.
- Air Cooling:Conventional raised-floor distribution with perforated doors, remaining viable for legacy infrastructure and density loads below 30 kW. Busan industrial edge deployments continue specifying these for manufacturing automation use cases.
- Hybrid Cooling:Combined air and liquid distribution enabling phased migration paths for data centers transitioning thermal architectures without full infrastructure replacement.
- Free Cooling:Economizer-based systems leveraging seasonal temperature differentials, primarily specified for Busan coastal facilities with favorable ambient conditions.
Air Cooling retains installed base dominance; Liquid Cooling is climbing the fastest.
Size:
Unit height selection reflects density optimization against facility constraints and workload specialization.
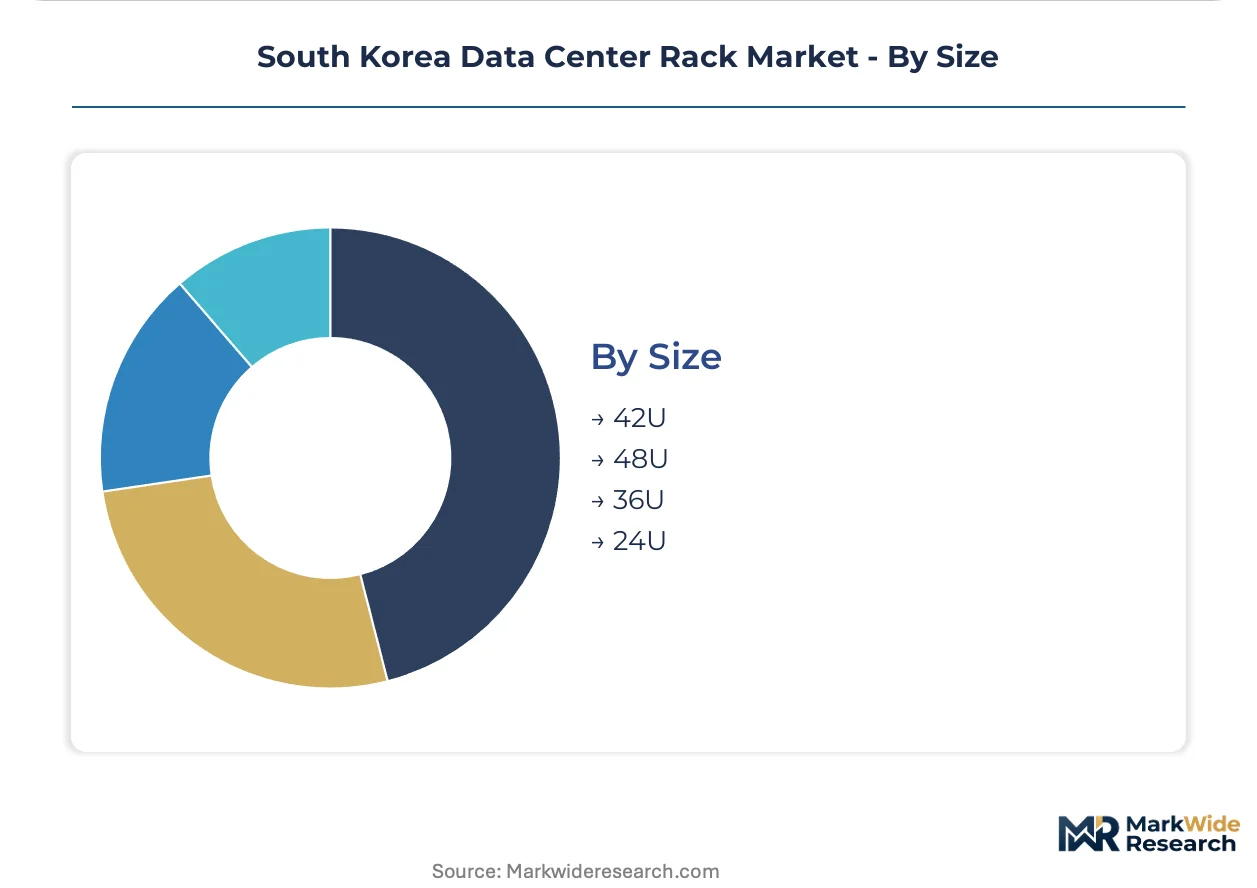
- 42U:The established volume standard across telecommunications central offices and enterprise data centers nationwide. This configuration balances vertical space utilization with structural load distribution for general-purpose compute.
- 48U:Extended-height units gaining traction in hyperscale facilities maximizing floor space efficiency. Gyeonggi Province mega campuses specify these for high-density storage and GPU clusters where ceiling clearance permits.
- 36U:Reduced-height configurations suited to constrained floor-to-ceiling environments and edge deployments with limited physical footprints.
- 24U:Compact units serving industrial edge applications in Busan manufacturing automation and port logistics digitization projects.
42U maintains procurement volume leadership; 48U is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Seoul Capital Area deployments where hyperscale operators absorb premium specifications, while Busan-Ulsan industrial edge buyers negotiate on standardized configurations. This asymmetry shapes supplier strategies across South Korea's data center rack procurement landscape.
Seoul Capital Area
Hyperscale campus construction by Naver and Kakao in Gyeonggi Province drives demand for liquid-ready rack systems exceeding 50 kW per cabinet. MFDS thermal safety guidelines mandate integrated fire suppression for financial services deployments in central Seoul. The Digital New Deal program accelerates cloud infrastructure investment across the metropolitan cluster.
Busan-Ulsan
Manufacturing automation and port logistics digitization create underpenetrated demand for ruggedized 24U and 36U compact rack configurations. KTL electrical certification requirements apply to industrial edge deployments in this southeastern manufacturing corridor. Hyundai Heavy Industries and local port authorities specify corrosion-resistant enclosures for coastal facility installations.
Daegu-Gyeongbuk
Telecommunications central office retrofits sustain volume procurement of standard 42U air-cooled units for legacy infrastructure upgrades. Ministry of Science and ICT energy efficiency mandates shape procurement specifications for regional telecom operators. KT Corporation maintains extensive switching facilities throughout this southeastern region requiring rack replacement cycles.
Daejeon-Sejong
Government data center consolidation projects generate demand for enclosed racks with enhanced access control and MFDS-aligned thermal management. Korea Agency for Technology and Standards enforcement of structural load testing affects supplier qualification timelines for public sector contracts. Sejong City's administrative district hosts multiple central government facilities undergoing infrastructure modernization.
Gwangju-Honam
Healthcare IT infrastructure and medical imaging data storage drive moderate-density rack procurement with emphasis on reliability certifications. Regional hospital networks specify configurations balancing thermal performance against constrained facility footprints. Honam Electric Power Corporation's grid modernization creates adjacent demand for utility-grade enclosure systems.
South Korea Data Center Rack Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying structural frames and thermal subassemblies. Market structure tilts toward consolidation as hyperscale operators reduce vendor counts through direct specification authority. Three archetypes dominate: global electrical infrastructure conglomerates, European enclosure system specialists, and domestic system integrators capturing share through certification agility. Competitive moves center on thermal-integrated product diversification and accelerated KTL/MFDS pre-certification programs.
Among global electrical infrastructure conglomerates, Schneider Electric and Eaton occupy positions exemplifying the integrated power-cooling-rack system archetype. Rittal represents the European enclosure specialist tier with localized manufacturing support capabilities. Vertiv sits within the thermal-integrated platform segment competing on liquid cooling convergence for AI training clusters. Domestic system integrators challenge these foreign anchors by pre-integrating MFDS-compliant suppression systems during manufacturing rather than field retrofit.
| Leading Market Players |
|---|
| Schneider Electric |
| Rittal |
| Delta Electronics |
| Eaton |
| Huawei |
| Vertiv |
| Legrand |
| STULZ |
| Honeywell |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in domestic cold-rolled steel fabrication is compressing margin structures for standardized 42U volume products while hyperscale operators in Gyeonggi Province absorb premium pricing for liquid-ready configurations. This utilization asymmetry between commodity tier and thermal-integrated tier shapes supplier behavior toward certification-heavy customization rather than scale-driven standardization.
Pricing Analysis
The customization-premium spread separates configured-to-order liquid cooling racks from catalog standard units by a substantial multiple. Three-tier pricing structure across premium, standard, and economy levels reflects MFDS certification grade and KTL electrical approval status as primary differentiation drivers. Cost compression in the standard tier is intensifying because cold-rolled steel input volatility erodes fixed-price contract viability. Telecommunications central offices exhibit highest price sensitivity, while Seoul financial services buyers demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Tariff exposure between China and South Korea dominates supply chain risk calculations for structural steel and precision-machined mounting components. Manufacturing concentration centers on China for raw steel feedstock, South Korea for domestic fabrication and KTL certification integration, and Germany for precision thermal management subassemblies. Cold-rolled steel, liquid cooling manifolds, and fire suppression sensors constitute critical input dependencies. Single-source vulnerability persists for direct-to-chip cooling manifold suppliers serving GPU density configurations. Distribution runs through value-added distributors with thermal engineering capabilities rather than direct catalog procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's data center rack market sits in early-cycle expansion as liquid cooling technology penetrates hyperscale procurement pipelines ahead of legacy infrastructure replacement waves. Gyeonggi Province mega campus construction by Naver and Kakao provides the foundational demand tailwind.
For Market Incumbents: Insulate margin position by accelerating pre-integration of MFDS-compliant fire suppression systems during manufacturing rather than field retrofit, neutralizing domestic system integrator certification agility. Deepen backward integration into precision-machined manifold production to reduce single-source dependency for liquid cooling components. Channel control through value-added distributors possessing thermal engineering capabilities remains the critical defensive lever against direct specification authority migrating to IT infrastructure teams.
For New Entrants and Emerging Players: Pursue Busan industrial edge deployments as the most penetrable white space, where manufacturing automation and port logistics digitization create underpenetrated demand for ruggedized 24U and 36U compact configurations outside Seoul concentration. Target corrosion-resistant enclosure specifications for Hyundai Heavy Industries and coastal port authority installations. A certification-first go-to-market angle emphasizing accelerated KTL and Korea Agency for Technology and Standards approval timelines differentiates against incumbent foreign suppliers facing extended qualification cycles.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid-cooled thermal-integrated rack configurations as GPU density requirements exceed 50 kW per cabinet and structural engineering complexity escalates. The five-to-ten year viability window favors platform integrators with converged rack-power-cooling system capabilities over component specialists. Acquisition target archetype: domestic system integrators with established MFDS pre-certification manufacturing workflows and existing hyperscale direct relationships. The signal to watch as inflection indicator is carbon intensity regulation implementation pace for Gyeonggi Province facilities altering rack-level power monitoring procurement specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Pre-Certification Manufacturing Integration | Accelerates hyperscale procurement eligibility by eliminating field retrofit timelines for Seoul financial services buyers. |
| Liquid Cooling Manifold Backward Integration | Captures value from direct-to-chip thermal architecture convergence specified in Gyeonggi Province new-build RFPs. |
| Busan Industrial Edge Distribution Partnership | Establishes early presence in manufacturing automation and port logistics digitization before incumbent channel saturation. |
| Rack-Power-Cooling Platform Convergence | Aligns product architecture with hyperscale operator preference for integrated system procurement over component sourcing. |
| Thermal-Structural Engineering Talent Acquisition | Addresses domestic specialist scarcity bridging mechanical rack design and liquid cooling fluid dynamics capabilities. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with data center infrastructure executives, thermal engineering specialists, hyperscale procurement officers, and KTL certification consultants; and secondary validation through MFDS regulatory filings, Korea Agency for Technology and Standards structural load testing records, hyperscaler capex disclosures, and Ministry of Science and ICT energy efficiency mandate documentation. Bottom-up segmentation modeling triangulated against top-down market sizing from facility construction pipeline tracking.
Forecast inputs considered hyperscale campus construction timelines, GPU density roadmaps across AI training cluster deployments, and regulatory implementation schedules for Gyeonggi Province carbon intensity mandates. Segmentation dimensions modeled include rack configuration type, cooling method architecture, end-user vertical, and regional facility concentration. CAGRs were derived from unit installation projections weighted by thermal density tier and specification premium differentials. Cold-rolled steel price trajectory assumptions and KTL certification timeline compression rates informed sensitivity scenarios.
Sensitivities concentrate around MFDS thermal safety guideline enforcement intensity, cold-rolled steel input cost volatility, and hyperscale operator vendor consolidation pace. Forecasts reflect assumptions about liquid cooling technology adoption curves and legacy air-cooled infrastructure replacement cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Spain Data Center Power Market
Data Center Infrastructure
Norway Data Center Storage Market
Data Center Infrastructure
DCIM Market
Data Center Infrastructure
Belgium Data Center Rack Market
Data Center Infrastructure
South Korea Data Center Physical Security Market
Data Center Infrastructure
Australia Data Center Physical Security Market
Data Center Infrastructure
North America Green Data Center Market
Data Center Infrastructure
South America Data Center Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market
Data Center Infrastructure
Australia Data Center Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
Japan Data Center Physical Security Market
Data Center Infrastructure
Thailand Data Center Physical Security Market
Data Center Infrastructure
Europe Data Center Physical Security Market
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
Middle East and Africa Containerized Data Center Market