
 Positive Temperature Coefficient (PTC) Thermistor Market | 2026-2036
Positive Temperature Coefficient (PTC) Thermistor Market Size, Share, and Industry Trends Forecast 2026-2036
Positive Temperature Coefficient (PTC) Thermistor Market Outlook
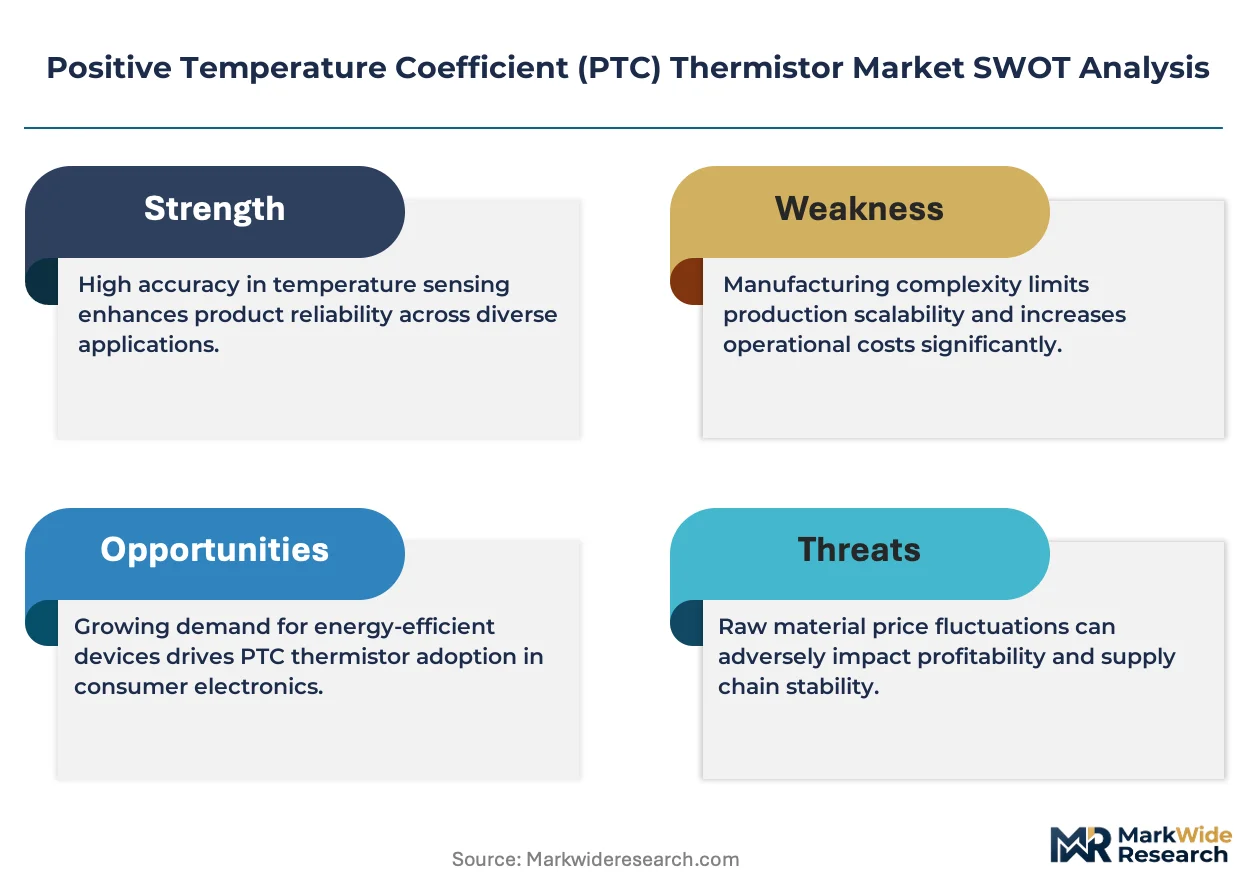
China is fragmenting PTC thermistor production capacity as domestic manufacturers expand ceramic sintering operations to serve electric vehicle and appliance supply chains. TE Connectivity leverages its global distribution network to sustain premium positioning in automotive temperature sensing modules. Bourns, Inc. anchors North American supply security through captive manufacturing of disc and chip thermistor variants for industrial equipment OEMs.
A Positive Temperature Coefficient thermistor is a ceramic or polymer-based resistive element whose electrical resistance rises sharply above a defined threshold temperature, typically manufactured through barium titanate doping and high-temperature sintering to achieve precise switching characteristics. These devices serve primarily as self-resetting overcurrent protectors and temperature limiters across consumer electronics, automotive powertrains, and industrial motor systems. Chip thermistors capture the fastest growth trajectory as miniaturization pressures mount in smartphone battery management and wearable device circuits, while disc thermistors retain mature volume dominance in heating element assemblies where cost sensitivity outweighs form-factor constraints. Polymer thermistors command premium positioning in automotive under-hood applications where vibration tolerance and flexible form factors justify higher unit economics.
The US Consumer Product Safety Commission and Underwriters Laboratories enforce escalating safety mandates for overcurrent protection in lithium-ion battery packs, directly expanding qualified PTC thermistor demand across consumer electronics and e-mobility platforms. IEC 60738 standards for thermistor reliability testing shape export market access for Asian manufacturers supplying European appliance and industrial automation OEMs. REACH compliance on barium titanate raw material sourcing adds material qualification overhead that favors vertically integrated producers with in-house ceramic powder processing. Stakeholders must monitor evolving battery safety regulations across multiple jurisdictions to anticipate specification shifts that will redefine competitive qualification requirements.
Market Dynamics
The PTC thermistor market is undergoing structural compression as electric vehicle battery architectures demand higher switching precision and faster thermal response cycles from ceramic protection components.
Growth Catalysts
- Electric vehicle battery management:Automotive OEMs are embedding PTC thermistors directly into cell-to-pack architectures to enable granular overcurrent isolation. This application segment is expanding faster than any other end-use category.
- IEC 60738 reliability mandates:European appliance and industrial automation OEMs now require certified thermistor performance under extended thermal cycling, forcing qualification upgrades across Asian supplier bases.
- Barium titanate doping advances:Ceramic powder processors have refined dopant concentrations to achieve sharper switching curves, enabling thinner disc geometries without sacrificing current-handling capacity.
Market Restraints
- Raw material concentration:High-purity barium titanate feedstock production concentrates in Chinese chemical processing clusters, exposing non-integrated manufacturers to supply rationing during export quota periods.
- Polymer substitution in automotive:Silicone-based positive temperature coefficient devices are capturing under-hood applications where vibration tolerance and flexible mounting geometries outweigh ceramic thermal performance.
- REACH compliance overhead:European chemical registration requirements for titanate compounds add material qualification costs that disproportionately burden small and mid-scale ceramic component producers.
Strategic Opportunities
- Chip thermistor miniaturization:Wearable device and smartphone battery OEMs are specifying 0402 and 0201 case sizes, creating premium positioning for manufacturers with precision thin-film deposition capabilities.
- US lithium-ion safety mandates:The Consumer Product Safety Commission and Underwriters Laboratories are tightening overcurrent protection requirements for consumer battery packs, expanding qualified supplier lists for PTC protection modules.
- Industrial motor retrofit cycles:Aging HVAC and compressor installations across North American manufacturing facilities are driving replacement demand for disc thermistors in motor starter assemblies.
Industry Challenges
- Ceramic sintering expertise scarcity:Qualified process engineers capable of maintaining tight Curie point tolerances across high-volume tunnel kiln operations are concentrated among a handful of Japanese and Chinese manufacturers.
- Multi-jurisdiction certification timelines:Simultaneous UL, IEC, and GB standard compliance for a single product variant extends qualification cycles by eight to fourteen months, freezing design iterations.
- Legacy equipment integration friction:Industrial automation OEMs face software compatibility gaps when retrofitting digital temperature monitoring systems alongside existing analog PTC protection circuits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Positive Temperature Coefficient (PTC) Thermistor Market |
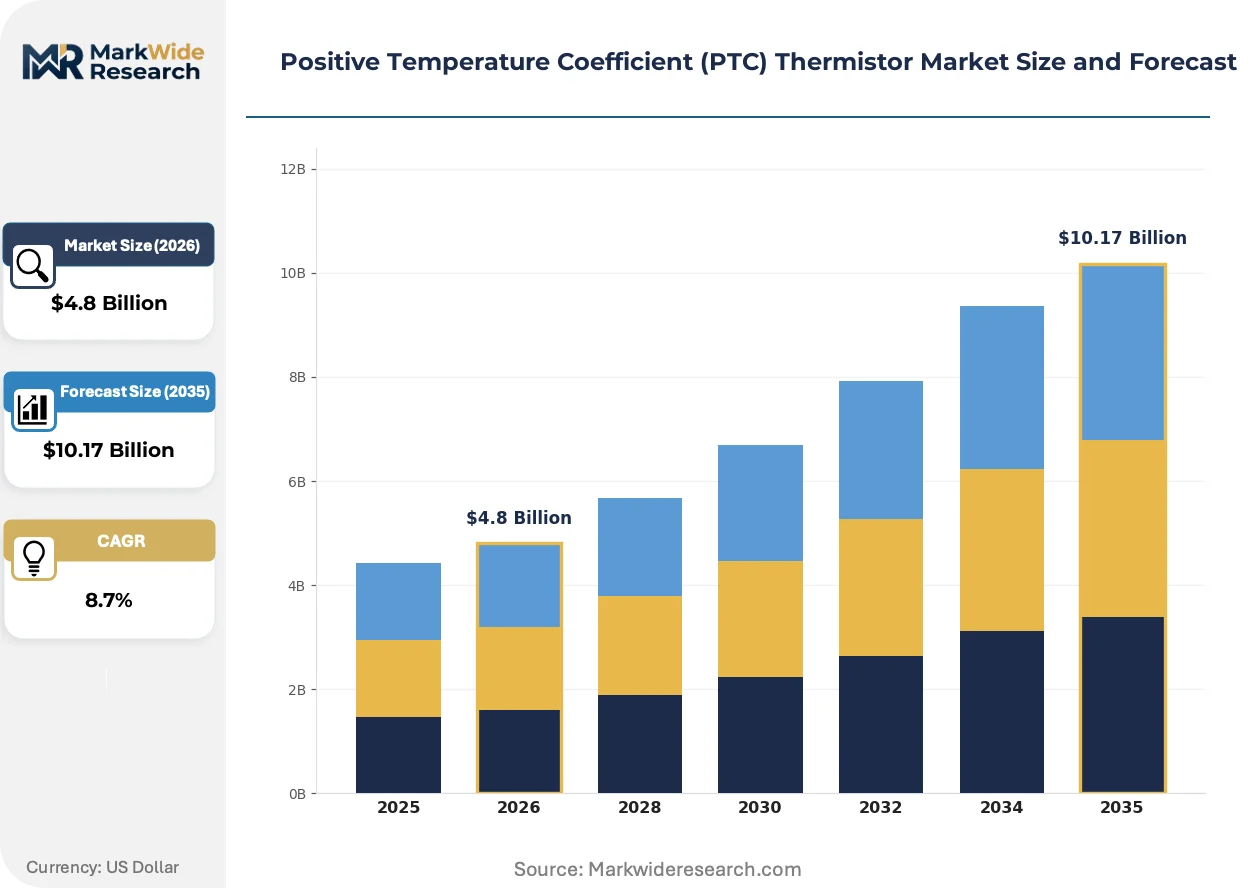
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Thermistors, Chip Thermistors, Glass Thermistors, Polymer Thermistors Application: Heating Elements, Overcurrent Protection, Temperature Sensing, Motor Start End User: Consumer Electronics, Automotive, Industrial Equipment, Home Appliances Installation: Surface Mount, Through Hole, Wire Leads, Integrated |
| Companies Covered | Bourns, Inc., Sea & Land Electric Co., Ltd., TE Connectivity, Hollyland Electronics Co., Ltd., Keter Electronic Co., Ltd., Polytronics Technology Corp., Fuzetec Technology Co., Ltd., TDK (EPCOS), Wayon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Positive Temperature Coefficient (PTC) Thermistor Market Strategic Shifts
Digital temperature sensing architectures are compressing the functional boundary between discrete PTC protection and integrated microcontroller-based thermal management, forcing component suppliers to redefine their value proposition.
Multilayer ceramic chip thermistors with embedded silver-palladium electrode structures are digitizing temperature feedback loops in smartphone battery management systems. Tier-one mobile device OEMs in South Korea and Taiwan are specifying these components for sub-millimeter profile protection circuits. This integration is digitizing the traditional separation between passive protection and active battery monitoring, collapsing board space requirements by sixty percent in next-generation designs.
REACH authorization procedures for barium titanate derivatives are extending material qualification timelines for European industrial equipment exports. The European Chemicals Agency's substance evaluation framework now requires chronic toxicity dossiers for titanate compounds used in heating appliance thermistors. German and Italian appliance manufacturers are responding by dual-sourcing ceramic powder from REACH-registered Chinese suppliers with completed registration dossiers.
Automotive tier-one suppliers are consolidating thermistor procurement through direct platform-level contracts rather than module-level specifications. This bypasses traditional distributor channels for disc and chip variants in electric vehicle battery packs. The shift is most visible in Chinese and German automotive supply chains, where cell manufacturers now specify protection component performance directly to ceramic suppliers.
Positive Temperature Coefficient (PTC) Thermistor Market Segmentation
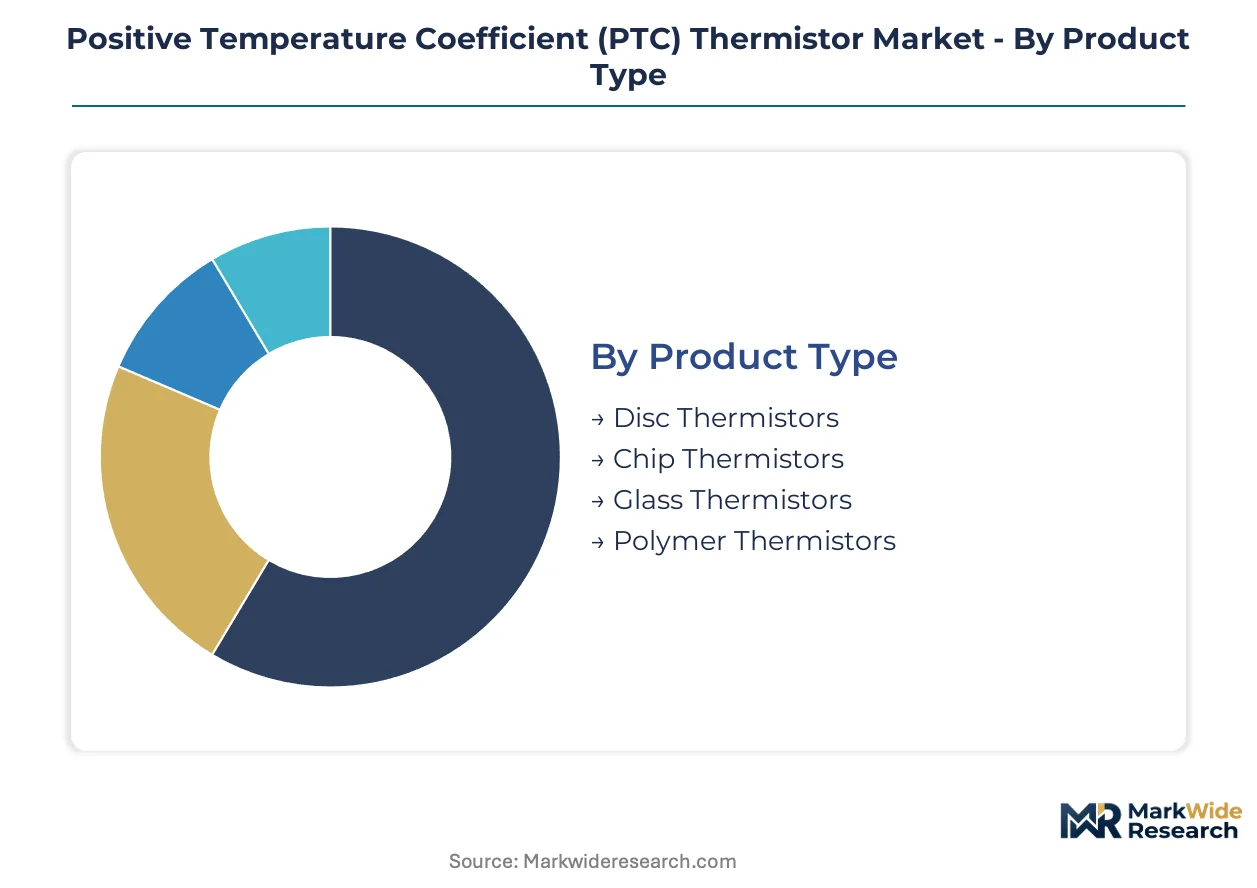
PTC thermistor segmentation reveals how ceramic and polymer chemistries diverge across mounting technologies and thermal management architectures. Each dimension carries distinct qualification burdens and supply chain configurations that reshape procurement patterns for automotive, industrial, and consumer OEMs.
Product Type:
After-sales service intensity varies sharply across ceramic and polymer variants, with disc thermistors demanding minimal field support while polymer formulations require application engineering for automotive integration.
- Disc Thermistors:Barium titanate ceramic discs sintered to precise Curie points dominate heating element assemblies and motor start applications where cost sensitivity outweighs miniaturization needs. Chinese manufacturers in Guangdong and Zhejiang provinces now supply both domestic appliance OEMs and export markets, though IEC 60738 reliability certification remains concentrated among Japanese producers.
- Chip Thermistors:Multilayer ceramic chip constructions with silver-palladium electrode structures enable sub-millimeter profile protection circuits. South Korean smartphone battery OEMs specify 0402 and 0201 case sizes for wearable device integration, where board space compression drives specification premiums.
- Glass Thermistors:Hermetic glass encapsulation suits high-humidity industrial environments and chemical exposure scenarios.
- Polymer Thermistors:Silicone-based positive temperature coefficient materials capture automotive under-hood applications where vibration tolerance and flexible mounting geometries justify higher unit economics.
Disc thermistors hold the largest share; momentum sits with chip thermistors.
Application:
Volume concentration clusters in mature heating and motor applications, while specification intensity concentrates in battery protection where thermal response precision determines platform safety.
- Heating Elements:Self-regulating ceramic discs in HVAC systems, hair dryers, and dehumidifiers exploit the PTC effect to eliminate thermal runaway without external control circuitry. German and Italian appliance manufacturers dual-source ceramic powder from REACH-registered Chinese suppliers to maintain European market access.
- Overcurrent Protection:Battery management systems in electric vehicles embed PTC thermistors for cell-level isolation during fault conditions. This application commands the steepest specification trajectory as automotive OEMs demand faster switching response and tighter Curie point tolerances.
- Temperature Sensing:Analog thermal feedback loops in industrial motor drives and power supply units.
- Motor Start:Compressor starter assemblies in aging North American HVAC installations drive replacement demand for disc thermistors.
Heating elements retain mature volume dominance; overcurrent protection gains share fastest.
End User:
Customer procurement sophistication separates automotive tier-one direct platform contracts from consumer electronics distributor-mediated purchasing.
- Consumer Electronics:Smartphone and wearable OEMs in Taiwan and South Korea specify chip thermistors through consolidated supplier lists. US Consumer Product Safety Commission and Underwriters Laboratories mandates for lithium-ion battery protection expand qualified supplier requirements.
- Automotive:Cell-to-pack architectures in Chinese and German electric vehicle supply chains now bypass traditional distributors for direct ceramic supplier procurement. Vibration-tolerant polymer variants capture under-hood mounting applications.
- Industrial Equipment:Motor starter retrofits and HVAC compressor replacements across North American manufacturing facilities.
- Home Appliances:Cost-optimized disc thermistors in heating appliances where REACH compliance on barium titanate sourcing shapes material qualification.
Consumer electronics maintains the broadest supplier base; automotive commands the steepest specification escalation.
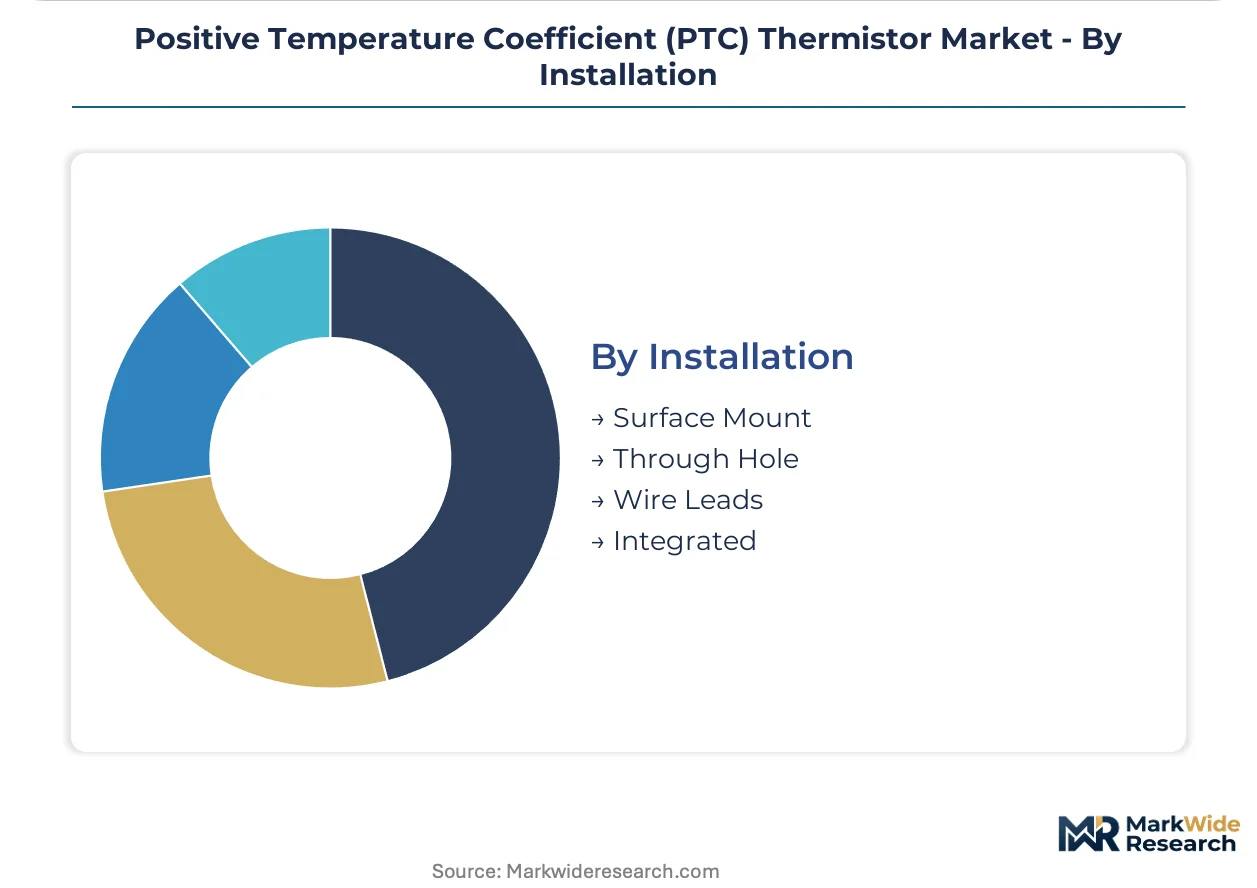
Installation:
Mounting technology selection traces directly to thermal cycling durability requirements and assembly automation compatibility.
- Surface Mount:Chip thermistors in 0402 and 0201 footprints enable high-density smartphone battery management circuits. Precision thin-film deposition capabilities separate qualified suppliers from commodity ceramic producers.
- Through Hole:Disc thermistors in motor starter and heating element assemblies where mechanical robustness outweighs miniaturization pressure. Mature pick-and-place automation supports high-volume appliance manufacturing.
- Wire Leads:Custom lead configurations for industrial motor windings and specialized thermal protection modules.
- Integrated:Embedded protection within battery cell terminals and power module substrates.
Through hole retains installed base dominance; surface mount climbs fastest on miniaturization pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers consume PTC thermistors primarily for domestic appliance and electric vehicle supply chains, while German and US demand tilts toward automotive-grade precision components with stricter switching tolerance requirements.
China
Domestic electric vehicle battery production and home appliance manufacturing absorb the majority of ceramic PTC output. GB standards for thermistor reliability in consumer electronics tighten compliance timelines for export-bound suppliers. Guangdong and Zhejiang provinces host concentrated ceramic sintering operations serving both local OEMs and international markets.
Germany
Automotive cell-to-pack architectures and industrial motor systems drive specification-intensive demand. REACH authorization procedures for barium titanate compounds extend material qualification cycles for heating appliance exports. Bavarian industrial automation clusters source REACH-registered ceramic powders through dual-supplier arrangements with Chinese processors.
United States
Consumer Product Safety Commission mandates for lithium-ion battery protection expand qualified supplier requirements across smartphone and wearable OEMs. Underwriters Laboratories certification timelines stretch eight to fourteen months for multi-standard compliance. Midwest manufacturing facilities drive replacement demand for disc thermistors in aging HVAC compressor installations.
Japan
Precision ceramic sintering expertise concentrates among established producers serving automotive and industrial temperature sensing applications. METI-backed standards for thermistor reliability shape regional procurement specifications. Nagoya-area manufacturers maintain tight Curie point tolerance capabilities for high-volume tunnel kiln operations.
South Korea
Smartphone battery OEMs specify 0402 and 0201 chip thermistor case sizes for wearable device integration. MFDS-aligned safety protocols for lithium-ion protection circuits influence component qualification requirements. Seoul-area electronics clusters consolidate supplier lists for multilayer ceramic chip constructions with embedded electrode structures.
Positive Temperature Coefficient (PTC) Thermistor Market Competitive Environment
Capability concentration sits with Japanese and German specialists commanding premium positioning in automotive-grade precision components; scale advantage sits with Chinese manufacturers expanding ceramic powder processing and sintering capacity for appliance and EV supply chains. The vendor base separates into three archetypes: integrated ceramic powder processors, precision thin-film deposition specialists, and polymer formulation developers. Dominant competitive moves include backward integration into barium titanate feedstock production and direct platform-level contracting with automotive cell manufacturers.
Within the precision-tier segment, Bourns, Inc. and TE Connectivity occupy positions exemplifying North American and European supply security strategies. Among Asia-Pacific ceramic specialists, TDK (EPCOS) and Polytronics Technology Corp. represent the integrated manufacturing archetype with in-house powder processing capabilities. Sea & Land Electric Co., Ltd. sits within the scale-driven tier serving high-volume heating appliance and motor start applications.
| Leading Market Players |
|---|
| Bourns, Inc. |
| Sea & Land Electric Co., Ltd. |
| TE Connectivity |
| Hollyland Electronics Co., Ltd. |
| Keter Electronic Co., Ltd. |
| Polytronics Technology Corp. |
| Fuzetec Technology Co., Ltd. |
| TDK (EPCOS) |
| Wayon Corporation |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor's container rate volatility feeds directly into ceramic PTC component landed costs, amplifying price spreads between integrated Chinese manufacturers and non-integrated Western distributors while forcing procurement managers to weight inventory carrying costs against spot-market exposure.
Pricing Analysis
Geographic price spreads between Guangdong-sourced disc thermistors and Japanese precision chip variants span three performance tiers. Three-tier pricing structure across automotive-grade, industrial-certified, and consumer-economy levels tracks directly to Curie point tolerance bands and UL/IEC certification status. Cost compression in consumer electronics tiers intensifies as smartphone OEMs consolidate supplier lists around 0201 case size specialists. Appliance manufacturers exhibit highest price sensitivity, while automotive cell-to-pack procurement teams prioritize switching precision over unit cost.
Supply Chain Analysis
Extended payment terms from Chinese ceramic powder processors now stretch to ninety days for qualified automotive tier-one customers, shifting working capital burdens downstream. High-purity barium titanate production concentrates in China, Japan, and Germany, with feedstock quality separating automotive-grade from appliance-grade output. The supply chain draws from concentrated chemical processing clusters, exposing non-integrated manufacturers to export quota rationing. Single-source vulnerability concentrates in tunnel kiln sintering expertise held by Nagoya-area specialists. Distribution runs through direct platform contracting in automotive, distributor-mediated channels in consumer electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell-to-pack battery architectures are collapsing the traditional module-tier procurement hierarchy, creating platform-economics inflection where thermistor specification power migrates from tier-one distributors to cell manufacturers and ceramic suppliers.
For Market Incumbents: Build certification moats around simultaneous UL, IEC, and GB compliance capabilities to lock out smaller Asian competitors facing fourteen-month qualification timelines. Deepen backward integration into barium titanate powder processing to offset REACH compliance overhead and raw material concentration risk. Prioritize captive sintering capacity expansion in Zhejiang province to serve domestic Chinese EV demand directly.
For New Entrants and Emerging Players: North American industrial motor retrofit demand represents underpenetrated white space where aging HVAC infrastructure requires disc thermistor replacement without automotive-grade certification barriers. Target surface-mount chip thermistor supply to South Korean wearable device OEMs seeking alternative sources beyond established Japanese producers. Pursue qualification partnerships with REACH-registered Chinese powder suppliers to bypass material registration delays.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive ceramic component divisions lacking scale to justify standalone powder processing investment. Long-term viability centers on switching precision capabilities rather than commodity volume positioning. Monitor IEC 60738 reliability mandate enforcement as inflection signal for qualification-intensive market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barium Titanate Processing | Captive powder production insulates margin pressure from Chinese export quota volatility. |
| Direct Platform Contracting with Cell Manufacturers | Bypassing distributors captures specification influence in Chinese and German EV supply chains. |
| Thin-Film Deposition Capability Investment | 0402 and 0201 chip thermistor production unlocks smartphone battery management premiums. |
| Multi-Jurisdiction Certification Pre-Positioning | Simultaneous UL, IEC, and GB compliance freezes competitor design cycles. |
| Polymer Formulation Development for Automotive | Silicone-based PTC materials capture under-hood applications from ceramic alternatives. |
Study Parameters
Initial hypotheses were tested against primary input from ceramic component procurement managers, automotive battery platform engineers, appliance OEM sourcing directors, and industrial motor maintenance supervisors, then refined through secondary validation against IEC standard documentation, UL certification registries, REACH substance databases, and customs trade flow records, with bottom-up segment builds triangulated against top-down market sizing.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by ceramic versus polymer chemistry, installation technology by surface mount versus through hole, and end-use intensity by automotive precision requirements versus appliance cost optimization. CAGRs were derived from installed base growth in electric vehicle production, replacement cycle analysis in industrial HVAC systems, and miniaturization-driven content expansion in consumer electronics. Forecast inputs included barium titanate powder processing capacity expansion timelines and multi-jurisdiction certification pipeline visibility.
Practitioners should monitor REACH authorization timeline extensions, Chinese barium titanate export policy shifts, and automotive cell-to-pack architecture standardization for early signals of competitive repositioning. Forecasts reflect assumptions regarding continued IEC 60738 enforcement, sustained EV production growth, and stable ceramic sintering expertise concentration. Macroeconomic contraction, regulatory harmonization failure, or solid-state battery displacement would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Smart Water Leak Detector Market
Detection and Regulation Devices
Null Detector Market
Detection and Regulation Devices
Semiconductor Leak Detectors Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
Global Counterfeit Money Detection Market
Detection and Regulation Devices
Constant Current Regulator Market
Detection and Regulation Devices
Duct Smoke Detectors Market
Detection and Regulation Devices
Handheld Optical Gas Imaging Camera Market
Detection and Regulation Devices
Global Ultrasonic Air Bubble Detectors Market
Detection and Regulation Devices
Global Inflation Device Market
Detection and Regulation Devices
Compliance Monitoring Devices Market
Detection and Regulation Devices
Global Tunnel Diode Detectors Market
Detection and Regulation Devices
Signaling Devices Market
Detection and Regulation Devices
Pedestrian Detection System Market
Detection and Regulation Devices
Voltage Detector Market
Detection and Regulation Devices
Underwater Signaling Devices Market