
 North America Omega-3 PUFA Market | 2026-2036
North America Omega-3 PUFA Market Size, Share, and Industry Trends Forecast 2026-2036
North America Omega-3 PUFA Market Analytics
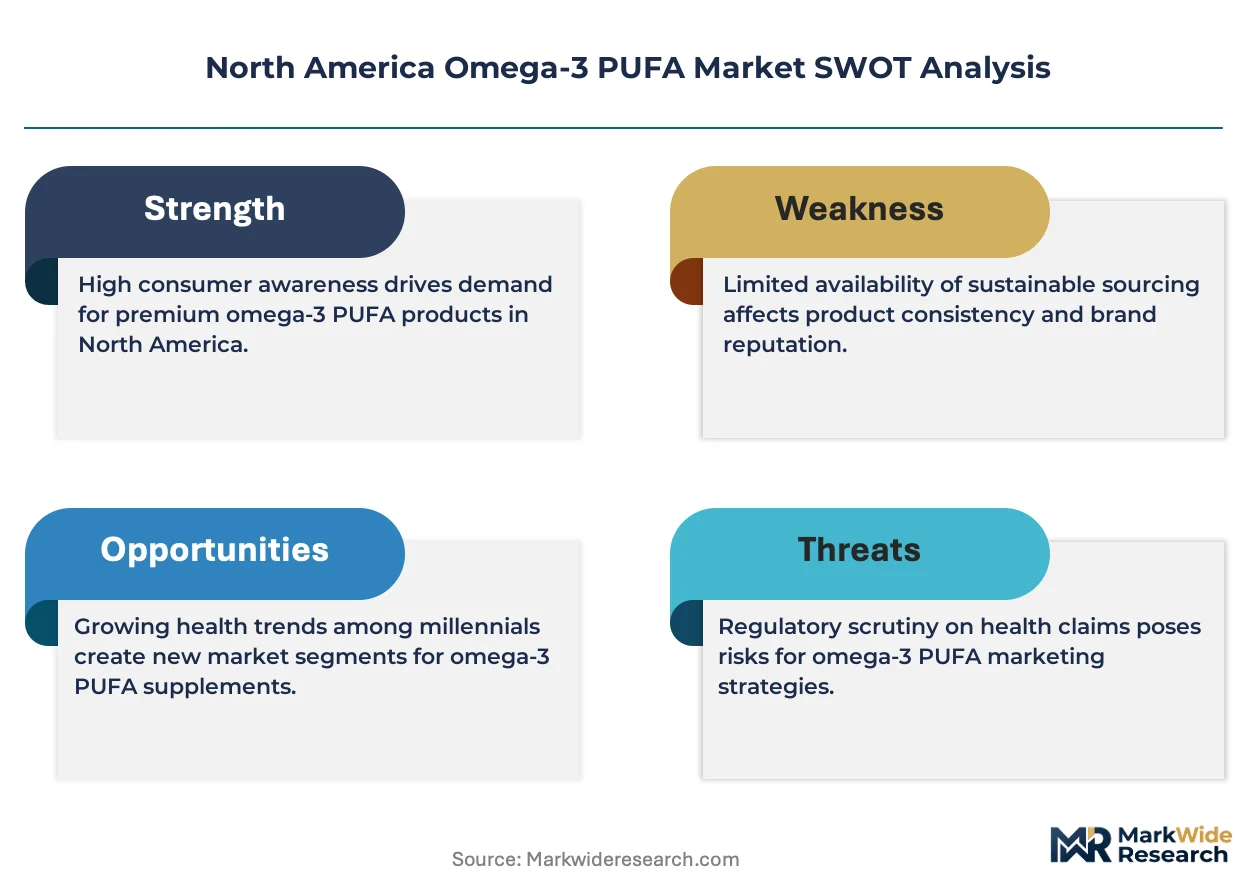
Modular softgel-to-liquid bundling is realigning how supplement brands configure retail and direct-to-consumer portfolios. Cargill, Incorporated leverages its integrated oilseed processing network to secure feedstock traceability from catchment to capsule. BASF SE anchors its position through pharmaceutical-grade EPA/DHA concentrate capacity. Nordic Naturals differentiates via practitioner-channel brand equity and third-party certification depth.
Omega-3 polyunsaturated fatty acids comprise long-chain EPA and DHA molecules typically extracted via molecular distillation or supercritical CO2 processing, with algal fermentation emerging as a land-based alternative to marine harvesting. These lipids function primarily as structural cell membrane components and eicosanoid precursors in cardiovascular, neural, and anti-inflammatory metabolic pathways. Fish oil retains volume leadership across North American channels, though algal oil commands premium positioning within vegan and allergen-free dietary supplement formulations. Softgel delivery dominates adult convenience purchasing, while liquid formats gain traction in pediatric and geriatric compliance segments where swallowing difficulty drives form-factor preference.
FDA New Dietary Ingredient notifications and Health Canada Natural Health Product licensing create dual compliance burdens for cross-border omega-3 suppliers, with EPA/DHA-specific monographs dictating label claims and purity thresholds. The FDA's evolving stance on qualified health claims for cardiovascular risk reduction shapes marketing architecture and R&D investment allocation among manufacturers. Stakeholders must monitor whether algal oil achieves pharmaceutical-grade equivalence certification, as this threshold would unlock prescription channel access and reshape competitive segmentation between marine and fermentation-derived supply chains.
Market Dynamics
FDA and Health Canada are tightening contaminant thresholds for marine-derived omega-3 ingredients, forcing dietary supplement manufacturers to diversify sourcing toward algal fermentation and reconfigure supply chain traceability systems.
Growth Catalysts
- EPA/DHA-Specific Monographs:Health Canada's Natural Health Product licensing creates clear label claim pathways that reduce regulatory uncertainty for compliant suppliers.
- California Functional Food Corridor:Concentrated demand from beverage and fortified food innovators pulls high-volume concentrate contracts toward West Coast processing infrastructure.
- Molecular Distillation Advancement:Supercritical CO2 processing improvements are lowering residual solvent thresholds below pharmaceutical-grade specifications.
Market Restraints
- Wild-Catch Volatility:Peruvian anchovy quota fluctuations and North Atlantic fishing restrictions create raw material input instability for marine oil refiners.
- Dual Compliance Burden:FDA New Dietary Ingredient notifications layered with Health Canada licensing extend product launch timelines by 18-24 months for cross-border suppliers.
- Algal Oil Cost Premium:Land-based fermentation capacity constraints keep DHA from Schizochytrium strains priced 40-60% above equivalent marine concentrates.
Strategic Opportunities
- Pediatric Liquid Formulations:Swallowing difficulty in children under 12 is opening compliance-driven demand for flavored emulsion products outside traditional softgel channels.
- Practitioner Channel Expansion:Clinician-directed dispensing models bypass retail margin compression while capturing insurance-adjacent wellness spending.
- Prescription Channel Access:Pharmaceutical-grade equivalence certification for algal-derived EPA/DHA would unlock formulary placement currently reserved for Lovaza and Vascepa.
Industry Challenges
- Third-Party Certification Backlogs:IFOS and USP verification queue times now exceed 14 months, delaying premium positioning for new market entrants.
- Lipid Oxidation Control:Maintaining peroxide and anisidine values within specification through multi-node distribution requires cold-chain infrastructure investments that strain mid-tier brand margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Omega-3 PUFA Market |
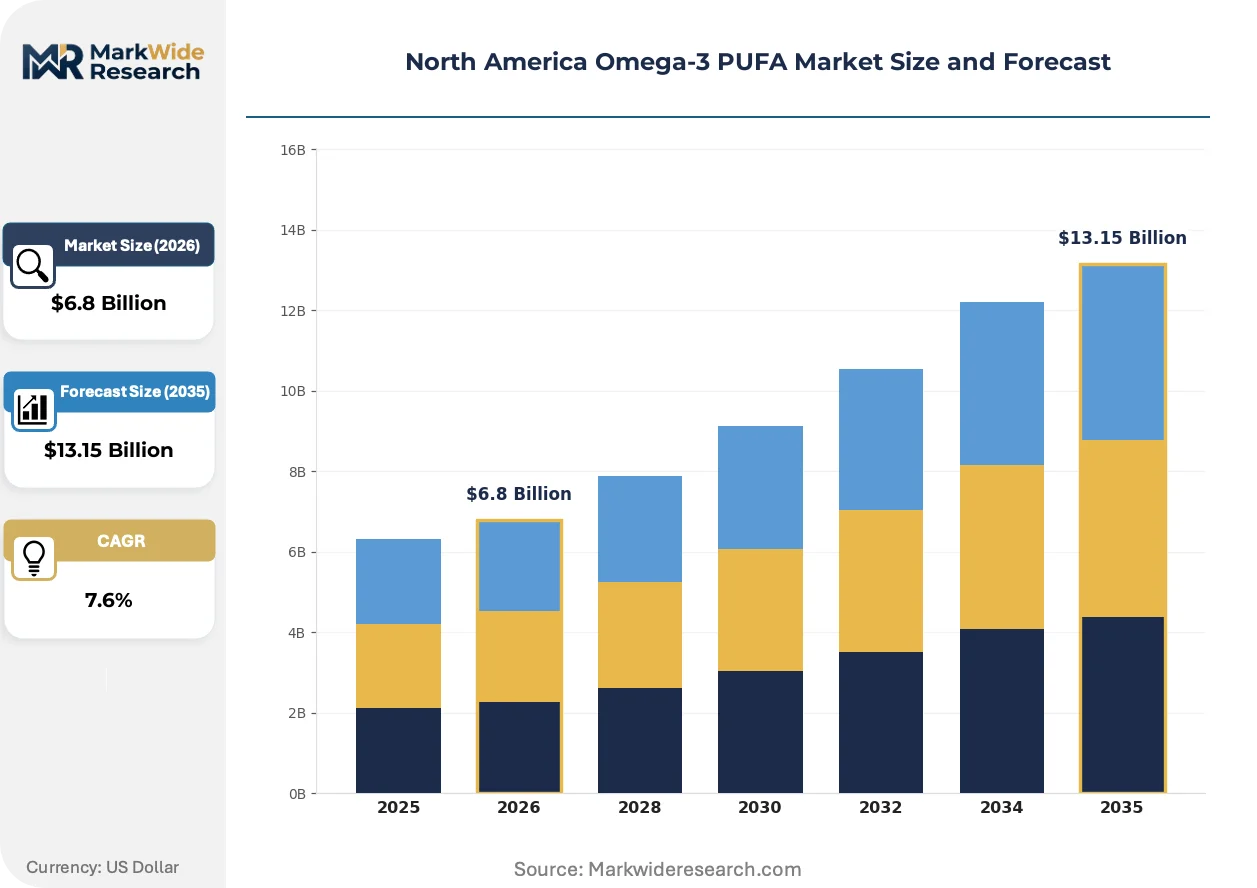
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Oil, Algal Oil, Krill Oil, Fortified Foods Application: Dietary Supplements, Functional Foods, Pharmaceuticals, Animal Nutrition End User: Adults, Children, Pregnant Women, Elderly Form: Softgels, Liquid, Powder, Capsules |
| Companies Covered | Cargill, Incorporated, BASF SE, Corbion NV, Archer Daniels Midland Company, Omega Protein Corporation, Croda International PLC, DSM Nutritional Products, Aker BioMarine, Nordic Naturals, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Omega-3 PUFA Market Evolving Landscape
Algal fermentation technology is compressing the traditional marine harvesting dependency while regulatory divergence between FDA qualified health claim frameworks and Health Canada disease risk reduction approvals is fragmenting marketing architecture.
Supercritical CO2 extraction is absorbing market share from molecular distillation in premium concentrate production. Pediatric and geriatric formulators are adopting this technology fastest, drawn to solvent-free residue profiles that support clean-label positioning. The shift is absorbing capital that previously flowed into ethyl ester infrastructure, reshaping capacity investment patterns across Gulf Coast processing facilities.
Health Canada's evolving Natural Health Product Directorate guidance on cardiovascular risk reduction claims is tightening evidentiary standards for omega-3 monographs. Manufacturers must now submit randomized trial data rather than observational meta-analyses, elevating R&D spend thresholds. Dietary supplement brands targeting dual US-Canada distribution are responding by segregating product formulations to satisfy divergent label claim permissibility.
Direct-to-consumer subscription models are displacing pharmacy and mass retail as the primary acquisition channel for high-dose EPA formulations. Millennial and Gen-Z buyers in coastal metropolitan areas are consolidating purchase decisions around telehealth-integrated wellness platforms. This channel rotation is most visible in California and Pacific Northwest markets where practitioner-adjacent digital health services have achieved highest penetration.
North America Omega-3 PUFA Market Segmentation
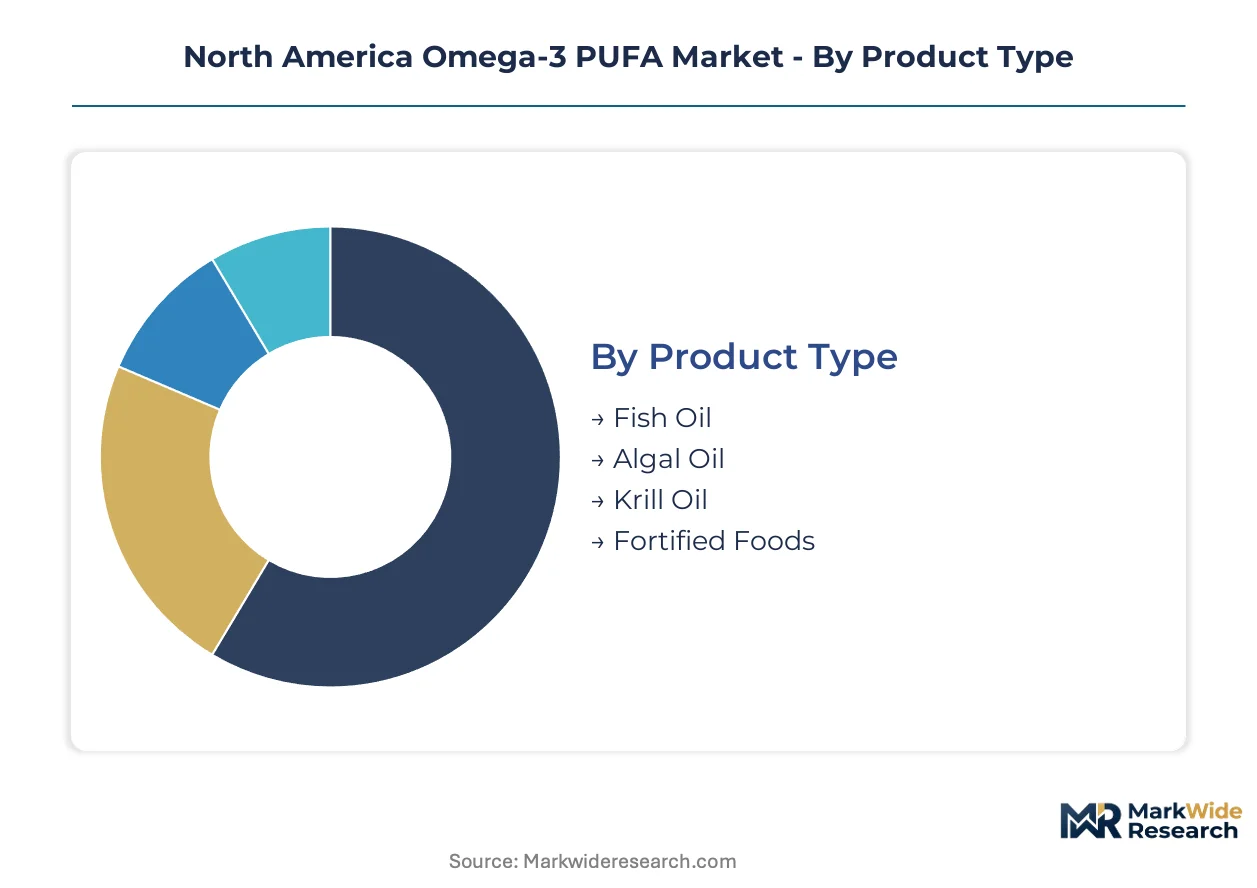
Omega-3 PUFA segmentation reflects divergent capital requirements across extraction technologies and delivery formats. Manufacturers allocate investment toward either high-volume marine processing infrastructure or specialized fermentation systems for algal cultivation.
Product Type:
Capital intensity varies sharply between marine extraction assets and land-based bioreactor facilities.
- Fish Oil:Molecular distillation and ethyl ester conversion require substantial coastal processing infrastructure. Gulf Coast refiners in Texas and Louisiana concentrate volume leadership, though Peruvian anchovy quota volatility forces inventory hedging strategies.
- Algal Oil:Schizochytrium fermentation in closed photobioreactors demands precision environmental control and sterile culture maintenance. California biotechnology clusters absorb the bulk of North American capacity investment despite 40-60% cost premiums over marine equivalents.
- Krill Oil:Antarctic harvesting vessels and onboard processing equipment create extreme capital barriers.
- Fortified Foods:Microencapsulation technology for bakery and beverage applications requires moderate spray-drying infrastructure.
Fish oil retains installed capacity dominance; algal oil is expanding most quickly as FDA and Health Canada tighten marine contaminant thresholds.
Application:
Margin structure and regulatory burden differentiate end-use channels more than volume scale.
- Dietary Supplements:Softgel and liquid formulations dominate adult convenience purchasing with practitioner-channel premiums. California's functional food corridor pulls concentrate contracts toward West Coast processing nodes.
- Pharmaceuticals:Prescription-grade EPA/DHA concentrates require USP verification and FDA NDI notification compliance. Health Canada's Natural Health Product Directorate imposes parallel evidentiary standards that extend launch timelines.
- Functional Foods:Beverage fortification demands emulsion stability and clean-label positioning.
- Animal Nutrition:Aquaculture feed applications in the U.S. Gulf Coast processing belt concentrate demand for bulk concentrate volumes.
Dietary supplements absorb the bulk of value extraction; pharmaceuticals is gaining share fastest as cardiovascular risk reduction claims achieve regulatory clarity.
End User:
Compliance-driven form factor preferences reshape manufacturing flexibility requirements.
- Adults:Convenience-oriented softgel purchasing dominates volume, with subscription models displacing retail acquisition in coastal metropolitan markets.
- Children:Swallowing difficulty under age 12 drives flavored emulsion demand outside traditional capsule channels. Pediatric liquid formulations command manufacturing line reconfiguration for sterile filling operations.
- Pregnant Women:DHA-specific prenatal positioning requires mercury-free certification and third-party testing documentation.
- Elderly:Geriatric compliance segments favor liquid and chewable formats with simplified dosing regimens.
Adults represents the installed base; children is climbing the fastest as formulation innovation unlocks previously inaccessible segments.
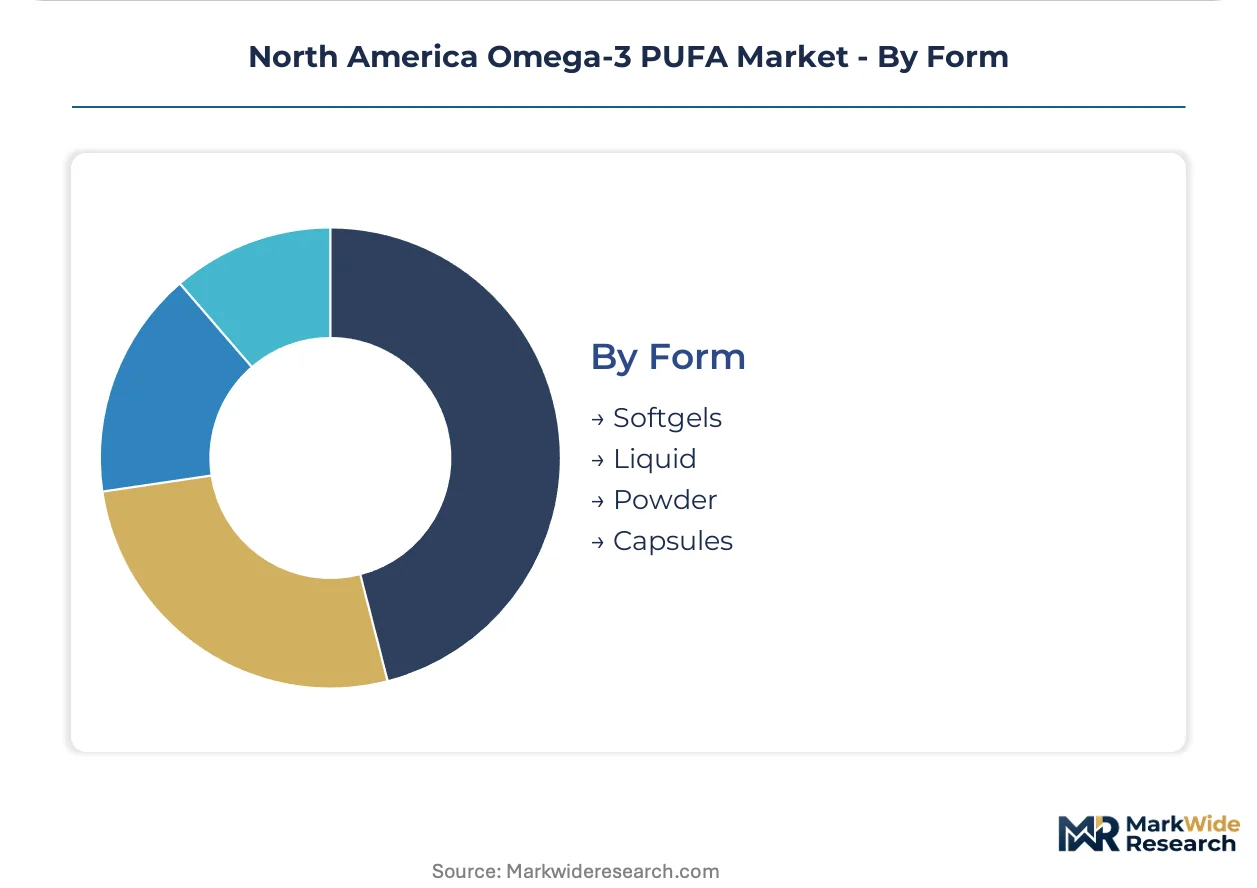
Form:
Packaging technology and oxidation control infrastructure determine competitive positioning.
- Softgels:Gelatin and plant-based capsule shell production requires integrated film-forming and filling lines. Adult convenience purchasing concentrates demand here despite peroxide sensitivity requiring nitrogen flushing and blister packaging.
- Liquid:Emulsion stability and flavor masking systems enable pediatric and geriatric compliance expansion. Cold-chain distribution investments strain mid-tier brand margins.
- Powder:Microencapsulation via spray-drying serves functional food integration with extended shelf-life requirements.
- Capsules:Two-piece hard gelatin alternatives compete on vegetarian positioning and fill-weight precision.
Softgels retains capacity concentration; liquid is gaining share fastest as direct-to-consumer channels prioritize compliance-driven differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Opportunity Zone incentives and Gulf Coast foreign trade subzones concentrate omega-3 processing infrastructure and algal fermentation capacity. FDA and Health Canada regulatory alignment pressures shape cross-border investment patterns. Texas and Louisiana anchor marine oil refining clusters.
United States
Dietary supplement subscription models and direct-to-consumer telehealth platforms drive coastal metropolitan demand. FDA qualified health claim frameworks for cardiovascular risk reduction shape marketing investment allocation. California's functional food corridor pulls concentrate contracts toward West Coast biotechnology clusters in San Diego and the Bay Area.
Canada
Health Canada's Natural Health Product Directorate monographs create clear label claim pathways for compliant EPA/DHA suppliers. Natural Health Product licensing requirements extend product launch timelines for cross-border manufacturers. British Columbia and Ontario concentrate algal oil research partnerships between fermentation startups and university biotechnology programs.
Mexico
Aquaculture feed applications in Baja California and Sinaloa generate bulk concentrate demand for shrimp and finfish farming operations. COFEPRIS regulatory alignment with FDA standards facilitates ingredient importation for domestic supplement manufacturing. Guadalajara's pharmaceutical corridor attracts softgel encapsulation investment serving North American distribution networks.
North America Omega-3 PUFA Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across extraction technology and delivery format segments. The market structure shows moderate consolidation around integrated oilseed processors and pharmaceutical-grade concentrate refiners. Three archetypes dominate: agricultural conglomerates with captive feedstock networks, fermentation technology specialists with algal cultivation platforms, and practitioner-channel brands with certification depth. Capacity expansion in supercritical CO2 infrastructure and backward integration into marine harvesting operations represent the dominant competitive moves reshaping supply chain control.
Among diversified agricultural processors, Cargill, Incorporated and Archer Daniels Midland Company exemplify the integrated feedstock-to-capsule archetype through their oilseed processing networks. BASF SE anchors the pharmaceutical-grade concentrate tier with EPA/DHA refinement capacity. Nordic Naturals occupies a position within the practitioner-channel specialist segment, representing brands that differentiate through third-party certification depth and clinician-directed dispensing relationships.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| BASF SE |
| Corbion NV |
| Archer Daniels Midland Company |
| Omega Protein Corporation |
| Croda International PLC |
| DSM Nutritional Products |
| Aker BioMarine |
| Nordic Naturals |
| Others |
Value Network & Pricing Analysis
Supercritical CO2 extraction adoption simultaneously compresses per-unit processing costs and redistributes capacity ownership toward Gulf Coast refiners with existing pressurized vessel infrastructure. This technology transition rewards operators with captive marine harvesting relationships while squeezing ethyl ester-dependent mid-tier processors unable to amortize retooling investments.
Pricing Analysis
Short lead-time premiums of 15-25% apply to pharmaceutical-grade EPA/DHA concentrates with USP verification, while spot inventory of unverified marine oil trades at discounts. Three-tier pricing structure across pharmaceutical-grade, practitioner-certified, and mass-market standard levels reflects certification depth and purity thresholds. Cost compression in mass-market softgels is intensifying because Peruvian anchovy quota volatility forces inventory carrying cost absorption. Pediatric liquid formulations command lowest price sensitivity due to compliance-driven substitution inelasticity.
Supply Chain Analysis
Dual-sourcing requirements from FDA-registered dietary supplement brands mandate simultaneous qualification of marine and algal fermentation suppliers. Raw material dependencies center on Peruvian anchovy meal, North Atlantic menhaden, and Schizochytrium strain biomass. Supply chain risk hinges on single-source vulnerability in Antarctic krill harvesting vessel capacity. Distribution runs through cold-chain logistics networks serving California functional food corridor and Gulf Coast aquaculture processing belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as Health Canada's elevated evidentiary standards for Natural Health Product licensing force subscale brands toward exit or acquisition.
For Market Incumbents: Anticipate regulatory divergence between FDA qualified health claim frameworks and Health Canada disease risk reduction approvals by segregating formulation architectures. Prioritize backward integration into algal fermentation capacity to secure contaminant-compliant feedstock. Deepen third-party certification depth to defend practitioner-channel premiums against private-label encroachment. For New Entrants and Emerging Players: Capture pediatric liquid formulation white space where swallowing difficulty creates compliance-driven demand outside softgel-saturated adult channels. Target direct-to-consumer subscription acquisition in California and Pacific Northwest coastal metropolitan markets. Pursue telehealth-integrated wellness platform partnerships as primary go-to-market angle bypassing retail margin compression. For Investors and Strategic Acquirers: Re-rating potential sits with fermentation technology specialists given pharmaceutical-grade equivalence certification catalyst unlocking prescription channel access. Long-term viability favors operators with integrated oilseed processing networks spanning feedstock traceability to capsule fill. Monitor algal oil cost parity achievement as inflection indicator reshaping competitive segmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Enables solvent-free extraction meeting pharmaceutical-grade specifications for pediatric formulations. |
| Backward Integration into Algal Fermentation | Secures land-based DHA supply insulated from marine contaminant threshold tightening. |
| Practitioner Channel Partnership | Bypasses retail margin compression while capturing insurance-adjacent wellness spending. |
| Third-Party Certification Investment | Reduces IFOS and USP verification queue exposure delaying premium positioning. |
| Direct-to-Consumer Platform Launch | Consolidates Millennial and Gen-Z acquisition around telehealth-integrated wellness services. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with extraction technology directors, dietary supplement brand managers, and Health Canada regulatory affairs consultants. FDA New Dietary Ingredient notifications, Health Canada Natural Health Product licensing databases, and Peruvian anchovy quota administration records provided demand-side validation. Bottom-up capacity modeling across Gulf Coast and California processing nodes triangulated against top-down consumption estimates.
Granularity extended to extraction technology, delivery format, and end-user compliance segment levels across the analysis window. CAGRs derived from segment-level volume and value buildups incorporating algal fermentation capacity expansion curves and marine oil refining utilization rates. Forecast inputs included Peruvian anchovy biomass assessments, supercritical CO2 equipment installation pipelines, and practitioner-channel dispensing growth trajectories.
The model holds under stable regulatory divergence between FDA and Health Canada frameworks; deviation toward harmonized evidentiary standards would shift competitive positioning toward scale operators. Forecasts reflect assumptions of continued algal oil cost premium persistence and cold-chain infrastructure investment continuity. Deviation in pharmaceutical-grade equivalence certification timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Protein Cookie Market
Functional Food & Ingredients
Functional Non-Meat Ingredients Market
Functional Food & Ingredients
Prebiotic Ingredients Market
Functional Food & Ingredients
Brominated Vegetable Oil Market
Functional Food & Ingredients
Mediterranean Cognitive-First Ingredient Systems Market
Functional Food & Ingredients
Banana Leaf Extract Market
Functional Food & Ingredients
Multifunctional Food Ingredients Market
Functional Food & Ingredients
Italy Protein Market
Functional Food & Ingredients
Low-Carb Low-Fat Meal Market
Functional Food & Ingredients
South America Prebiotic Ingredients Market
Functional Food & Ingredients
Europe Prebiotic Ingredient Market
Functional Food & Ingredients
Essential Fatty Acids Market
Functional Food & Ingredients
Poultry Probiotic Ingredients Market
Functional Food & Ingredients
Europe Omega-3 PUFA Market
Functional Food & Ingredients
Refined Functional Carbohydrates Market
Functional Food & Ingredients
Asia-Pacific Omega3 PUFA Market