
 South America Forage Seed Market | 2026-2036
South America Forage Seed Market Size, Share, and Industry Trends Forecast 2026-2036
South America Forage Seed Market Analytics
The EU-Mercosur sustainability protocols is realigning procurement criteria for imported beef and dairy, pushing South American producers toward certified forage varieties. Bayer AG leverages its breeding infrastructure to supply tropical-adapted grasses across Brazil's central plateau. KWS SAAT SE & Co. KGaA anchors its regional presence through localized trials in Argentina's Pampas. Royal Barenbrug Group specializes in high-digestibility perennial ryegrass for Chilean dairy operations.
Forage seeds are reproductive propagules of grasses, legumes, and cereals selected for germination rate, nutritional value, and persistence under grazing pressure; breeders evaluate crude protein content, neutral detergent fiber, and seedling vigor as core performance parameters. These seeds establish pasture swards that convert solar energy into digestible biomass for ruminant livestock. Legume seeds command premium positioning due to biological nitrogen fixation that reduces synthetic fertilizer dependence in mixed pastures. Grass seeds sustain volume leadership across extensive beef systems where cost per hectare dominates farmer decisions. Application through animal feed channels absorbs the dominant share of seed flows, while cover cropping emerges as a fast-growing outlet as no-till farmers integrate winter forages into soybean rotations.
ANVISA in Brazil oversees phytosanitary standards for seed treatments, while Argentina's national seed institute enforces varietal identity and purity rules under its federal seed law. The Mercosur technical regulation on seed movement harmonizes cross-border trade standards among member states. Stakeholders must track how evolving deforestation-free supply chain mandates reshape the geographic permissibility of pasture expansion and seed sourcing zones.
Market Dynamics
Pasture renovation cycles across Brazil's Cerrado are accelerating as integrated crop-livestock systems displace degraded grazing lands, tightening demand for certified tropical grass varieties with proven persistence under intensive management.
Growth Catalysts
- EU-Mercosur Sustainability Protocols:Import criteria for deforestation-free beef are redirecting Brazilian ranchers toward certified forage seed procurement, creating compliance-driven demand for traceable varieties.
- Biological Nitrogen Fixation:Legume seed adoption is expanding across Argentina's Pampas as farmers reduce synthetic fertilizer dependence in mixed pasture systems, cutting input costs per hectare.
- Colombia's FEDEGAN Pasture Recovery Programs:National livestock federation subsidies are financing seed-based pasture renovation across the Orinoquia region, accelerating variety turnover timelines.
Market Restraints
- Seed Treatment Input Volatility:Fungicide and insecticide coating costs for tropical grass seeds fluctuate with petrochemical feedstock prices, compressing margins for certified seed processors.
- Genetic Concentration Risk:Commercial Brachiaria variety development depends heavily on Embrapa germplasm releases, creating bottleneck vulnerability for Brazil's central plateau suppliers.
- Quarantine Substitution Threat:Mechanical pasture renovation using no-till soybean rotations is displacing seed-based renovation in some Mato Grosso municipalities where seed costs exceed machinery depreciation.
Strategic Opportunities
- Uruguay's Underpenetrated Dairy Belt:Perennial ryegrass and white clover seed penetration remains below Argentine levels, creating white space for high-digestibility variety introductions.
- Winter Cover Cropping Convergence:No-till soybean farmers are integrating black oat and annual ryegrass seed into rotation planning, merging grain and livestock input channels.
- ANVISA Biofertilizer Registration Pathway:Simplified approval for microbial seed inoculants is opening regulatory tailwinds for rhizobia-enhanced legume seed positioning.
Industry Challenges
- Certification Timeline Compression:MAPA's tightening seed purity benchmarks are extending variety registration periods, delaying commercial release windows for new tropical grass cultivars.
- Integrated System Agronomy Gap:Crop-livestock technical assistance capacity lags behind seed demand in Brazil's northeastern expansion zones, constraining adoption velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Forage Seed Market |
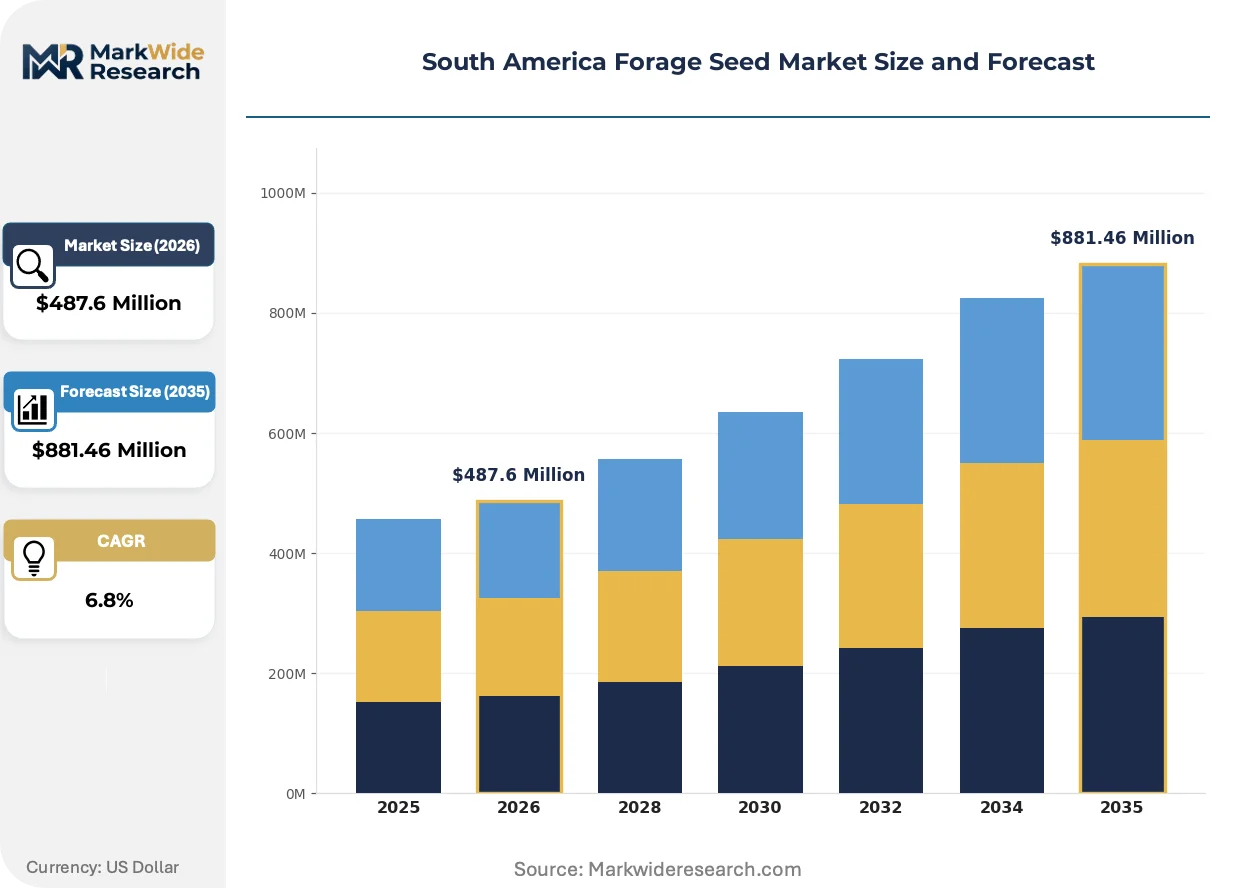
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grass Seeds, Legume Seeds, Cereals, Others End User: Dairy Farms, Beef Cattle Farms, Agroforestry, Crop Rotation Distribution Channel: Retail Stores, Online Platforms, Agricultural Co-operatives, Wholesale Application: Animal Feed, Soil Erosion Control, Soil Fertility Improvement, Cover Cropping |
| Companies Covered | Deutsche Saatveredelung AG, Groupe Limagrain, Advanta Seeds - UPL, Royal Barenbrug Group, KWS SAAT SE & Co. KGaA, Bayer AG, DLF, VIRÖ Semillas, Corteva Agriscience, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Forage Seed Market Evolving Landscape
Digital phenotyping platforms are compressing forage variety development cycles while sustainability-linked procurement criteria rewrite seed certification requirements across South American supply chains.
Gene editing via CRISPR-Cas9 is absorbing into tropical grass breeding programs at Embrapa and private stations, targeting drought tolerance and aluminum toxicity resistance for Cerrado conditions. Seed companies with captive biotechnology infrastructure are securing multi-year supply contracts with integrated crop-livestock operators ahead of conventional breeders. The technology is absorbing regulatory review capacity as Brazil's CTNBio evaluates stacked trait applications for commercial release.
ANVISA's revised phytosanitary residue limits for seed treatments are forcing reformulation of fungicide coatings on tropical grass propagules, particularly affecting thiram-based products. Seed processors are investing in polymer film coating alternatives to maintain export eligibility under tightening Mercosur technical regulations. Argentina's national seed institute is harmonizing testing protocols with Brazilian standards, reducing cross-border certification friction for Brachiaria and Panicum varieties.
Direct-to-farm seed procurement through digital platforms is fragmenting traditional distributor networks across Brazil's Mato Grosso and Goiás states. Large integrated operators are negotiating volume contracts with breeding stations, bypassing regional cooperatives that historically controlled variety access. Chilean dairy cooperatives are replicating this pattern, consolidating ryegrass seed purchases through centralized procurement offices rather than decentralized agent networks.
South America Forage Seed Market Segmentation
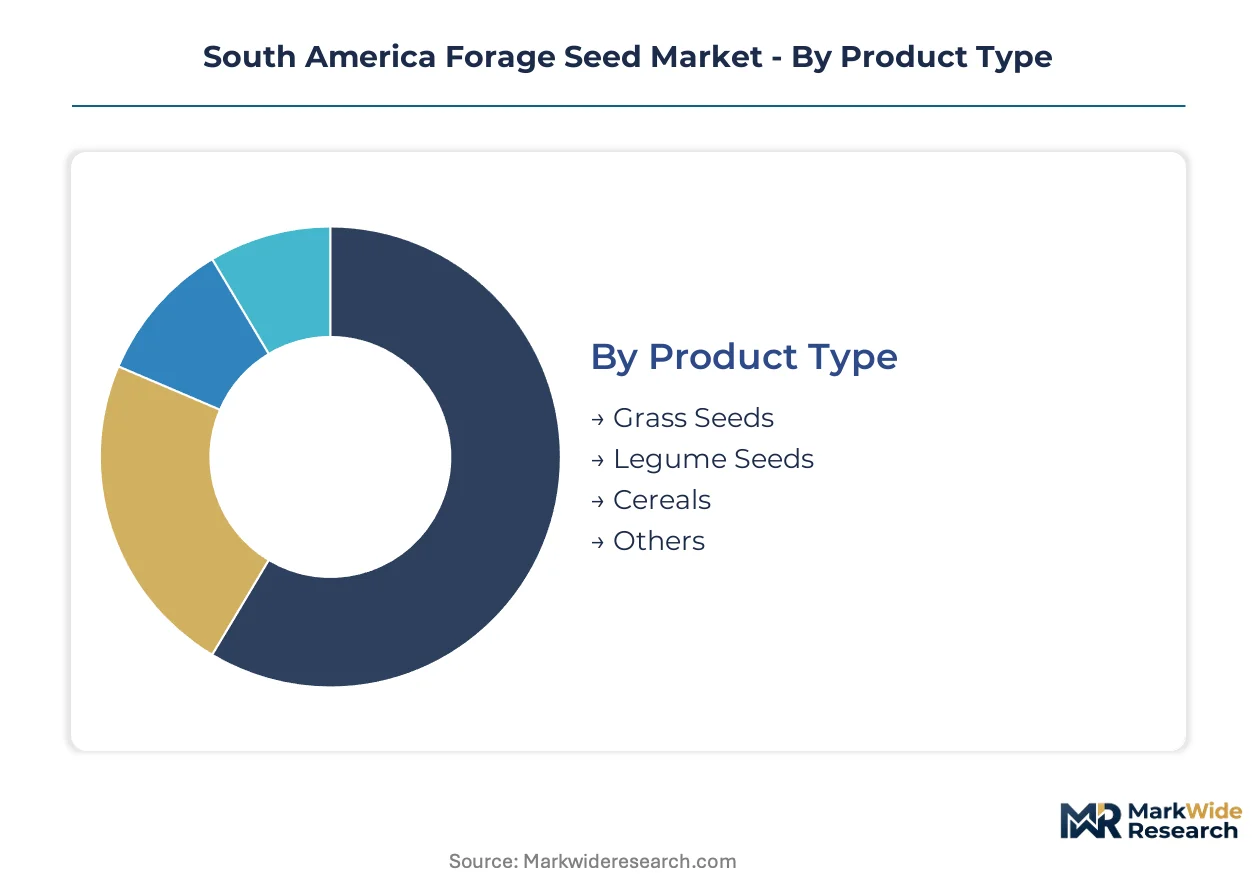
Forage seed procurement patterns across South America diverge sharply between volume-driven extensive beef systems and premium-positioned dairy operations. Breeders calibrate variety portfolios to match these divergent margin structures and technical requirements.
Product Type:
Grass seeds dominate hectare coverage while legume seeds capture disproportionate margin share through nitrogen fixation premiums.
- Grass Seeds:Tropical Brachiaria and Panicum varieties anchor Brazil's Cerrado pasture renovation cycles, with Embrapa germplasm releases supplying the genetic backbone for certified commercial cultivars. Demand concentrates in Mato Grosso and Goiás states where integrated crop-livestock operators prioritize persistence under intensive rotational grazing.
- Legume Seeds:Stylosanthes and Desmodium cultivars deliver biological nitrogen fixation that cuts synthetic fertilizer dependence in mixed pastures. Argentina's Pampas region shows concentrated adoption as farmers rebuild soil fertility in degraded grazing lands.
- Cereals:Black oat and annual ryegrass varieties serve dual-purpose cover cropping and winter forage roles across southern Brazil's no-till soybean belts.
- Others:Forage sorghum and hybrid pearl millet occupy niche positioning for drought-prone northeastern expansion zones.
Mature deployment sits with Grass Seeds. Newer deployment is concentrated in Legume Seeds.
End User:
Beef systems absorb seed volume through extensive renovation programs while dairy operations drive variety premiumization.
- Beef Cattle Farms:Extensive pasture systems across Brazil's central plateau and Colombia's Orinoquia region generate bulk demand for certified tropical grass varieties. FEDEGAN subsidy programs in Colombia are accelerating seed-based renovation timelines.
- Dairy Farms:High-digestibility perennial ryegrass and white clover varieties command premium positioning in Chile's central valley and Uruguay's dairy belt, where milk solids production depends on consistent forage quality.
- Agroforestry:Shade-tolerant forage varieties integrate into silvopastoral systems across Brazil's Atlantic Forest restoration zones.
- Crop Rotation:Winter forage seed integrates into no-till grain rotations, merging livestock and cropping input channels in Mato Grosso municipalities.
Procurement scale clusters with Beef Cattle Farms. Quality premiums concentrate with Dairy Farms.
Distribution Channel:
Channel selection tracks farm scale and technical assistance requirements across divergent customer profiles.
- Agricultural Co-operatives:Regional cooperatives historically controlled variety access through technical assistance bundling, though large integrated operators increasingly bypass these networks.
- Online Platforms:Direct-to-farm digital procurement fragments traditional distributor networks across Brazil's central states, enabling volume contract negotiations with breeding stations.
- Retail Stores:Municipal agro-input retailers serve smallholder segments with limited storage capacity and immediate planting schedules.
- Wholesale:Bulk seed handlers supply processor networks and export-oriented operations requiring phytosanitary certification under Mercosur technical regulations.
Relationship-based channels retain Beef Cattle Farm loyalty. Digital penetration climbs fastest among large integrated operators.
Application:
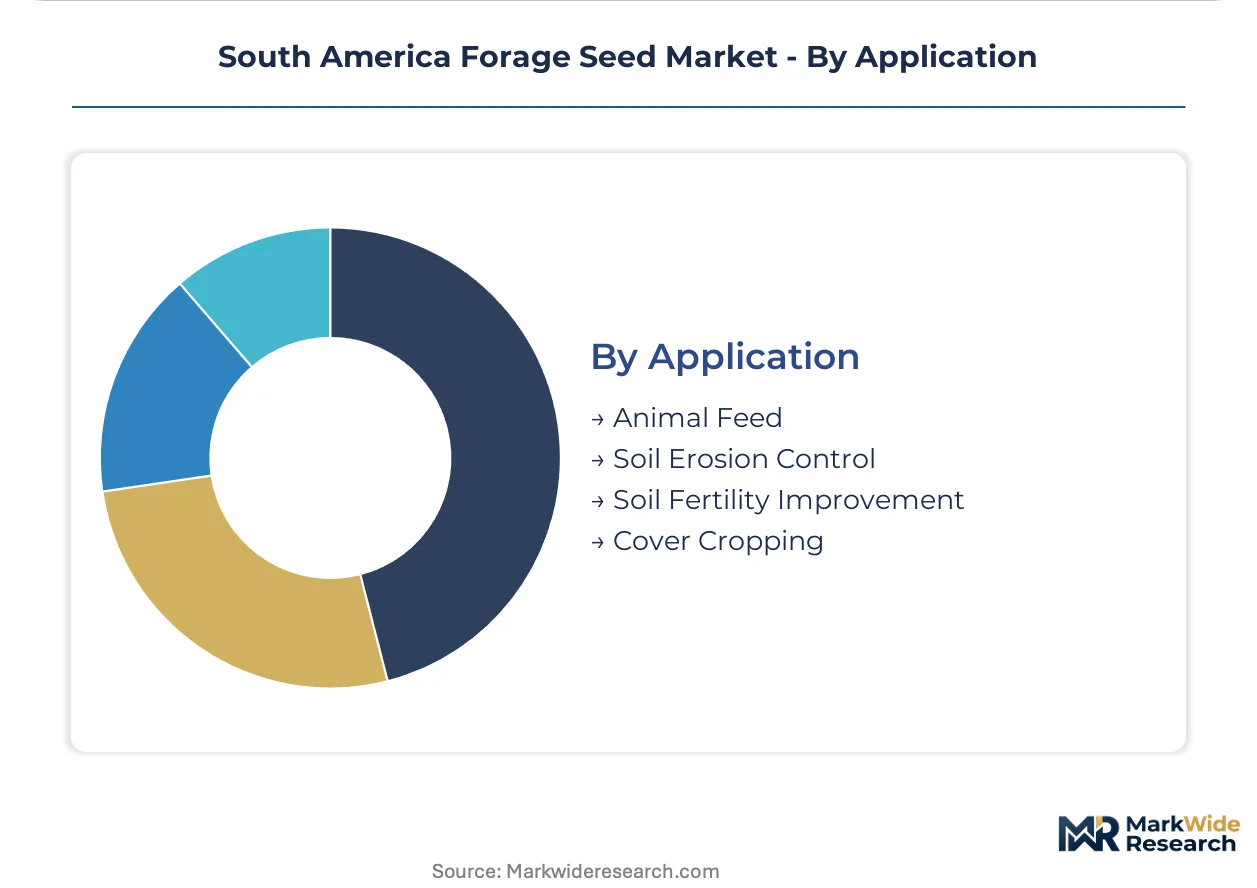
Animal feed absorbs dominant seed flows while environmental applications reshape variety specifications.
- Animal Feed:Pasture establishment for ruminant livestock consumes the majority of commercial seed volume, with crude protein content and neutral detergent fiber driving variety selection criteria.
- Cover Cropping:Winter forage integration into soybean rotations represents the steepest expansion trajectory as no-till farmers seek biomass accumulation and soil moisture retention benefits.
- Soil Erosion Control:Deep-rooted perennial grasses stabilize degraded slopes in Colombia's Andean foothills and Brazil's Atlantic Forest buffer zones.
- Soil Fertility Improvement:Legume-based biological nitrogen fixation rebuilds soil organic matter in Argentina's Pampas and southern Brazil's degraded pasturelands.
Commercial maturity centers on Animal Feed. Regulatory tailwinds favor Cover Cropping expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil produces the bulk of certified forage seed consumed across South America, yet Argentina and Colombia generate substantial internal demand that outpaces domestic breeding capacity. This production-consumption divide shapes cross-border seed flows and regulatory harmonization pressures.
Brazil
MAPA seed certification requirements are tightening quality benchmarks for commercial tropical grass varieties. ANVISA oversees phytosanitary standards for seed treatments, forcing reformulation of fungicide coatings on Brachiaria propagules. Demand concentrates in Mato Grosso's Cerrado belt where integrated crop-livestock systems displace degraded pastures.
Argentina
The national seed institute enforces varietal identity and purity rules under federal seed law, creating compliance friction for imported Brazilian germplasm. Legume seed adoption expands across the Pampas as farmers reduce synthetic fertilizer dependence in mixed pasture systems. Buenos Aires province anchors the country's dairy belt where high-digestibility perennial ryegrass commands premium positioning.
Colombia
FEDEGAN pasture recovery programs finance seed-based renovation across the Orinoquia region, accelerating variety turnover timelines. The national livestock federation subsidies target degraded grazing lands in Meta and Casanare departments. Deep-rooted perennial grasses stabilize slopes in the Andean foothills for soil erosion control applications.
Chile
Dairy operations in the central valley drive demand for certified perennial ryegrass and white clover varieties where milk solids production depends on consistent forage quality. Chilean dairy cooperatives consolidate seed purchases through centralized procurement offices rather than decentralized agent networks. Temuco and Los Lagos regions concentrate the country's pasture renovation activity.
Uruguay
Perennial ryegrass and white clover seed penetration remains below Argentine levels across the country's dairy belt, creating white space for high-digestibility variety introductions. Mercosur technical regulation on seed movement harmonizes cross-border trade standards with Brazilian and Argentine suppliers. Paysandú and Colonia departments generate the strongest demand for certified pasture varieties.
South America Forage Seed Market Competitive Landscape
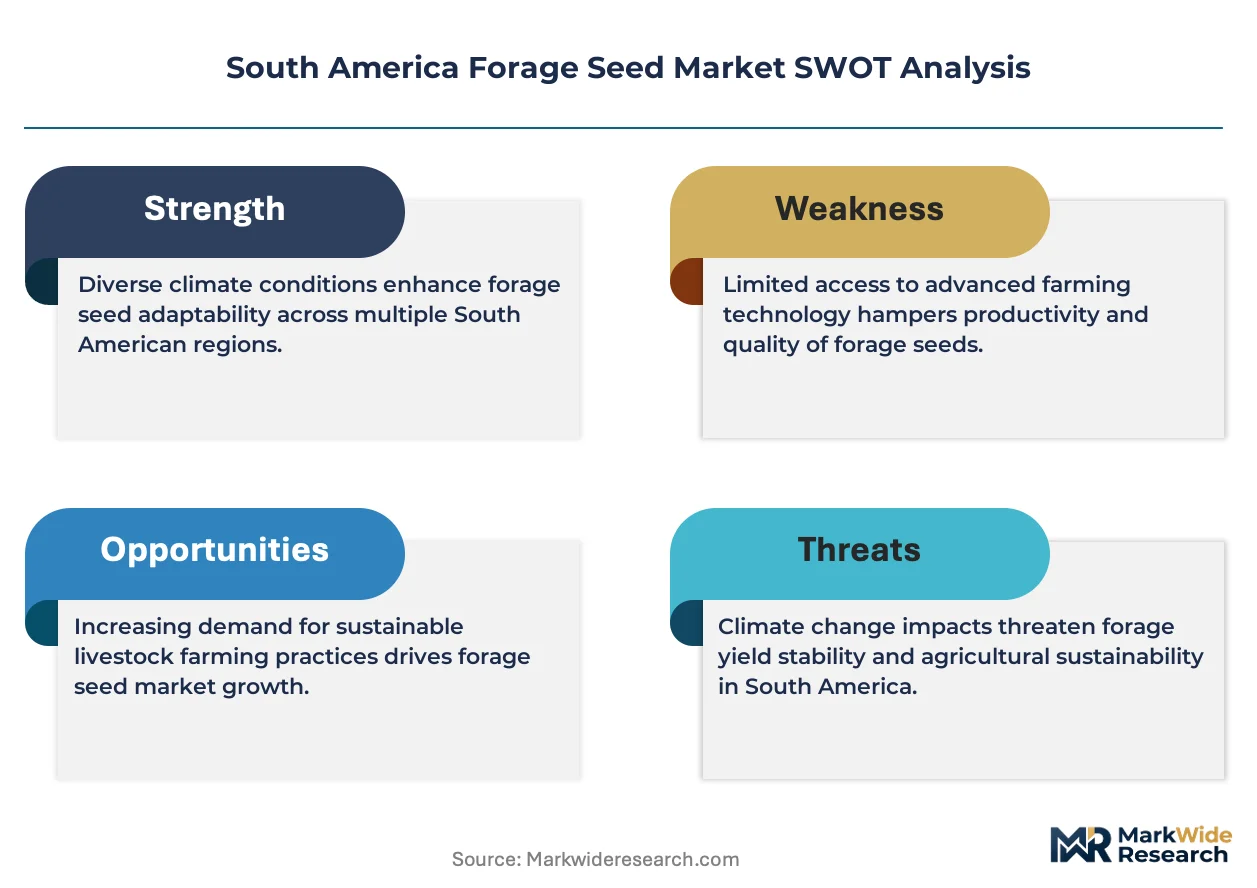
The competitive structure tilts toward multinational agribusiness conglomerates with captive breeding infrastructure. Bayer AG and Corteva Agriscience anchor the premium tier through biotechnology-enabled variety development, while regional specialists occupy mid-market positioning through localized trial networks. Three archetypes dominate: integrated life science conglomerates with seed-to-pesticide bundling, European grass breeding specialists with tropical adaptation programs, and South American originators with Embrapa germplasm access. Competitive moves concentrate on multi-year supply contracting with integrated crop-livestock operators and direct-to-farm digital procurement platform development.
Within the European breeding specialist tier, Royal Barenbrug Group and KWS SAAT SE & Co. KGaA exemplify archetypes built on perennial ryegrass expertise and localized tropical grass trials respectively. Among integrated conglomerates, Bayer AG represents the biotechnology-enabled positioning that secures captive supply relationships ahead of conventional breeders. Deutsche Saatveredelung AG anchors the mid-market through German-origin germplasm distributed across Mercosur trade corridors. These three companies illustrate how geographic origin and corporate structure map to distinct competitive positioning vectors in South American forage seed procurement.
| Leading Market Players |
|---|
| Deutsche Saatveredelung AG |
| Groupe Limagrain |
| Advanta Seeds - UPL |
| Royal Barenbrug Group |
| KWS SAAT SE & Co. KGaA |
| Bayer AG |
| DLF |
| VIRÖ Semillas |
| Corteva Agriscience |
| Others |
Value Network & Pricing Analysis
Fungicide coating costs for tropical grass seeds cascade through three pricing tiers as petrochemical feedstock volatility compresses margins for certified seed processors serving Brazil's Cerrado renovation cycles.
Pricing Analysis
Yield-linked value anchors seed pricing across South American procurement channels. Premium-mid-economy pricing differentiation separates Embrapa-certified tropical grasses from uncertified alternatives and generic commodity seed. Pricing pressure stems from seed treatment input volatility as thiram-based fungicide reformulation costs rise. Large integrated crop-livestock operators show lowest price sensitivity through volume contracting, while smallholder segments in Colombia's Orinoquia region remain most responsive to per-kilogram seed costs.
Supply Chain Analysis
Embrapa germplasm releases rest on Brazilian public breeding infrastructure as the genetic backbone for commercial Brachiaria cultivars. Tropical grass seed multiplication draws from Mato Grosso and Goiás production zones, while perennial ryegrass germplasm sources from European breeding stations in the Netherlands and New Zealand. Single-source vulnerability concentrates in Embrapa's controlled variety releases for Cerrado-adapted genetics. Distribution runs through agricultural cooperatives for relationship-based segments and direct-to-farm digital platforms for large integrated operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene editing via CRISPR-Cas9 is displacing conventional phenotyping as the dominant breeding methodology for drought-tolerant tropical grass development.
For Market Incumbents: Lock in multi-year supply contracts with integrated crop-livestock operators ahead of CTNBio regulatory approvals for stacked-trait varieties. Secure captive biotechnology infrastructure through backward integration into seed coating and microbial inoculant production. The threat of mechanical pasture renovation using no-till soybean rotations demands channel control reinforcement in Mato Grosso municipalities. For New Entrants and Emerging Players: Direct-to-farm digital procurement platforms offer the lowest barrier entry route into Brazil's fragmented distributor networks. Target Uruguay's underpenetrated dairy belt where perennial ryegrass adoption lags Argentine levels by substantial margin. White space exists in ANVISA-simplified biofertilizer registration pathways for rhizobia-enhanced legume seed positioning. For Investors and Strategic Acquirers: CTNBio stacked-trait approval announcements are the leading indicator that biotechnology-enabled seed positioning will consolidate procurement relationships. The five-to-ten year viability window favors acquisition of regional originators with Embrapa germplasm access agreements. Watch FEDEGAN subsidy program expansion as the demand inflection signal for Colombian pasture renovation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Editing Platform Investment | CRISPR-Cas9 infrastructure compresses variety development cycles for Cerrado drought tolerance. |
| Direct-to-Farm Digital Procurement | Bypassing cooperatives captures volume contracts from Mato Grosso integrated operators. |
| Biofertilizer Registration Pathway | ANVISA-simplified microbial inoculant approvals open regulatory tailwinds for legume seed. |
| Multi-Year Supply Contracting | Captive relationships with crop-livestock operators secure offtake ahead of trait commercialization. |
| Regional Trial Network Expansion | Localized Pampas and Cerrado validation builds farmer confidence for new variety adoption. |
Research Methodology
MAPA certification databases, ANVISA phytosanitary filings, and FEDEGAN subsidy program records formed the secondary backbone for seed flow quantification. Primary interviews with tropical grass breeding station directors, MAPA variety registration officials, and procurement managers at Brazilian integrated crop-livestock operations combined with secondary validation. Bottom-up and top-down triangulation cross-checked hectare renovation estimates against seed multiplication capacity disclosures.
Bottom-up modeling anchored forecasts in segment-level seed demand by product type, end user, and application channel across the projection horizon. Segmentation dimensions included grass versus legume versus cereal seed categories, beef cattle versus dairy farm end-use profiles, and animal feed versus cover cropping application splits. CAGRs derived from historical renovation cycle analysis and EU-Mercosur sustainability protocol compliance timelines. Industry-specific inputs incorporated Embrapa germplasm release schedules and CTNBio regulatory review capacity constraints.
The model holds under sustained MAPA certification tightening and FEDEGAN subsidy continuity; deviation in CTNBio approval delays or mechanical renovation substitution rates would shift trajectory. Forecasts reflect assumptions about integrated system adoption velocity and sustainability-linked procurement enforcement. A small set of named triggers warrants ongoing watch: CTNBio stacked-trait decisions, ANVISA biofertilizer registration throughput, and EU-Mercosur protocol implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Indonesia Seeds Market
Seeds
Philippines Rice Seed Market
Seeds
Global Sunflower Seed (Seed for Sowing) Market
Seeds
Fruit Tomatoes Seed Market
Seeds
Carrot Seed Oil Market
Seeds
Europe Seed Market
Seeds
Europe Flaxseeds Market
Seeds
Flaxseed (Linseed) Market
Seeds
Hemp Seeds Market
Seeds
Global Sunflower Market
Seeds
Nepal Seeds Market
Seeds
Psyllium Market
Seeds
Australia Oilseed Market
Seeds
Asia-Pacific Vegetable Seed Market
Seeds
Asia-Pacific Onion Seed Market
Seeds
United States Forage Seed Market