
 Flaxseed (Linseed) Market | 2026-2036
Flaxseed (Linseed) Market Size, Share, and Industry Trends Forecast 2026-2036
Flaxseed (Linseed) Market Insights
Cold-pressing extraction technology is reshaping how flaxseed oil reaches food-grade purity without hexane residues. Archer Daniels Midland Company leverages its North American crushing network to secure origination volumes across the Canadian Prairies. Cargill, Incorporated anchors its position through backward integration into farmer contracting and identity-preserved seed programs. Richardson International Limited dominates western Canadian handling infrastructure, giving it control over export-grade seed flows to Asia and Europe.
Flaxseed, derived from Linum usitatissimum, contains approximately 35-45% oil by weight with alpha-linolenic acid comprising 50-60% of total fatty acid content; primary industrial purposes span human nutrition, functional food fortification, and omega-3 feed formulations for livestock and aquaculture. Ground seeds and oil extracts lead value capture due to direct bioavailability and concentrated nutrient density, while protein powder represents the fastest-growing category as plant-based protein demand expands in sports nutrition and meat alternatives. The organic form commands premium positioning through certified supply chains and clean-label procurement requirements from European and North American buyers.
Health Canada and the FDA govern food-grade flaxseed claims and novel food approvals, while the USDA Organic and EU Organic frameworks dictate certification thresholds for premium market access. REACH and EU Green Deal sustainability criteria are tightening traceability mandates for imported oilseeds, reshaping supplier qualification protocols. Stakeholders must monitor evolving omega-3 health claim restrictions and carbon intensity benchmarks for crop production to preserve market positioning.
Market Dynamics
Cold-pressing technology upgrades are compressing extraction costs while preserving omega-3 integrity, forcing solvent-based processors to accelerate capital replacement cycles or exit food-grade segments entirely.
Growth Catalysts
- EU Green Deal traceability mandates:REACH and sustainability criteria are disqualifying uncertified suppliers, redirecting premium procurement toward identity-preserved Canadian and Baltic origins with verified carbon footprints.
- Aquaculture feed formulation:Salmon and shrimp producers are substituting fish oil with ALA-rich flaxseed meal to reduce marine ingredient dependence and meet retailer sustainability commitments.
- Sports nutrition powder demand:Plant-protein brands are formulating with flax protein isolate for emulsification and fiber fortification in ready-to-mix beverages and meat alternatives.
Market Restraints
- Prairie province concentration risk:Over 80 percent of exportable supply originates from Saskatchewan and Manitoba, exposing buyers to single-region weather shocks and rail logistics bottlenecks.
- Chia and hemp substitution:These oilseeds offer comparable omega-3 profiles with simpler organic certification pathways, capturing share in functional food applications.
- Health claim restriction friction:FDA and EFSA maintain narrow approved language for ALA cardiovascular benefits, limiting marketing differentiation against EPA/DHA sources.
Strategic Opportunities
- Indian functional food penetration:FSSAI novel food approvals for flax-fortified atta and dairy alternatives remain underexploited relative to population scale and rising protein awareness.
- Bioplastics feedstock pivot:Linseed oil's drying properties position it as a renewable input for coatings and composites, diverting lower-grade crush output from feed to industrial chemicals.
- Direct-to-bakery contracting:Artisan and industrial bakeries are bypassing distributors to secure milled flax with specified particle size and microbial certificates.
Industry Challenges
- Organic transition timeline compression:Three-year land conversion requirements and parallel organic supply chain segregation strain working capital for prairie elevator operators.
- Identity-preserved logistics complexity:Maintaining lot traceability from farm through crush to export requires ERP upgrades and third-party audit costs that mid-scale handlers struggle to absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flaxseed (Linseed) Market |
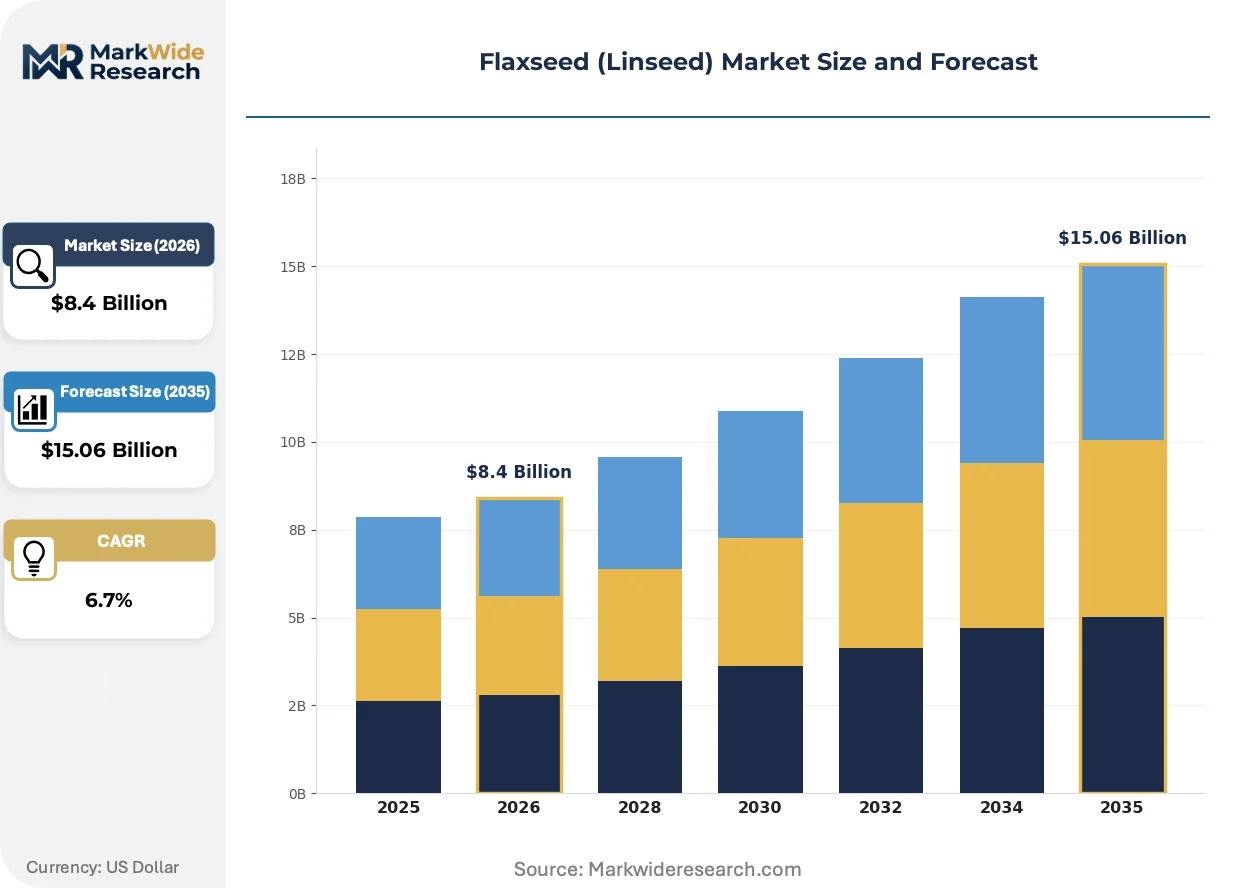
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Seeds, Ground Seeds, Oil Extracts, Protein Powder End Use Industry: Food & Beverage, Dietary Supplements, Cosmetics, Animal Feed Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops Form: Organic, Non-Organic, Cold-Pressed, Roasted |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, AgMotion, Inc., TA Foods Ltd., Richardson International Limited, CanMar Foods Ltd., Bioriginal Food & Science Corp., Johnson Seeds, Healthy Oilseeds, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flaxseed (Linseed) Market Trends and Innovations
Digital seed-to-oil traceability platforms are replacing paper-based organic certification workflows, compressing audit cycles and enabling real-time buyer verification of origin and processing method.
Near-infrared spectroscopy is virtualizing oil content and fatty acid profile assessment at intake elevators, eliminating laboratory delays. Large handlers are deploying portable NIR units across prairie collection points, enabling immediate premium-tier sorting. This technology is virtualizing quality arbitration, removing third-party testing as a rate-limiting step in contract execution.
REACH authorization requirements for hexane solvent residues are tightening maximum permissible limits in EU-imported crude flaxseed oil. Crushers serving European food manufacturers are retrofitting cold-press lines or installing supercritical CO2 extraction to maintain market access. Organic-certified oil now commands widening premia over conventional as solvent-free becomes a de facto import prerequisite.
Clean-label procurement committees at North American CPG firms are mandating single-origin disclosure and carbon intensity scoring for flax ingredients. Buyers are consolidating supplier lists to vertically integrated crushers with farm-level data capture. This concentration is visible in contract farming expansion across Saskatchewan, where handlers are prepaying for dedicated acreage with guaranteed offtake minimums.
Flaxseed (Linseed) Market Segmentation
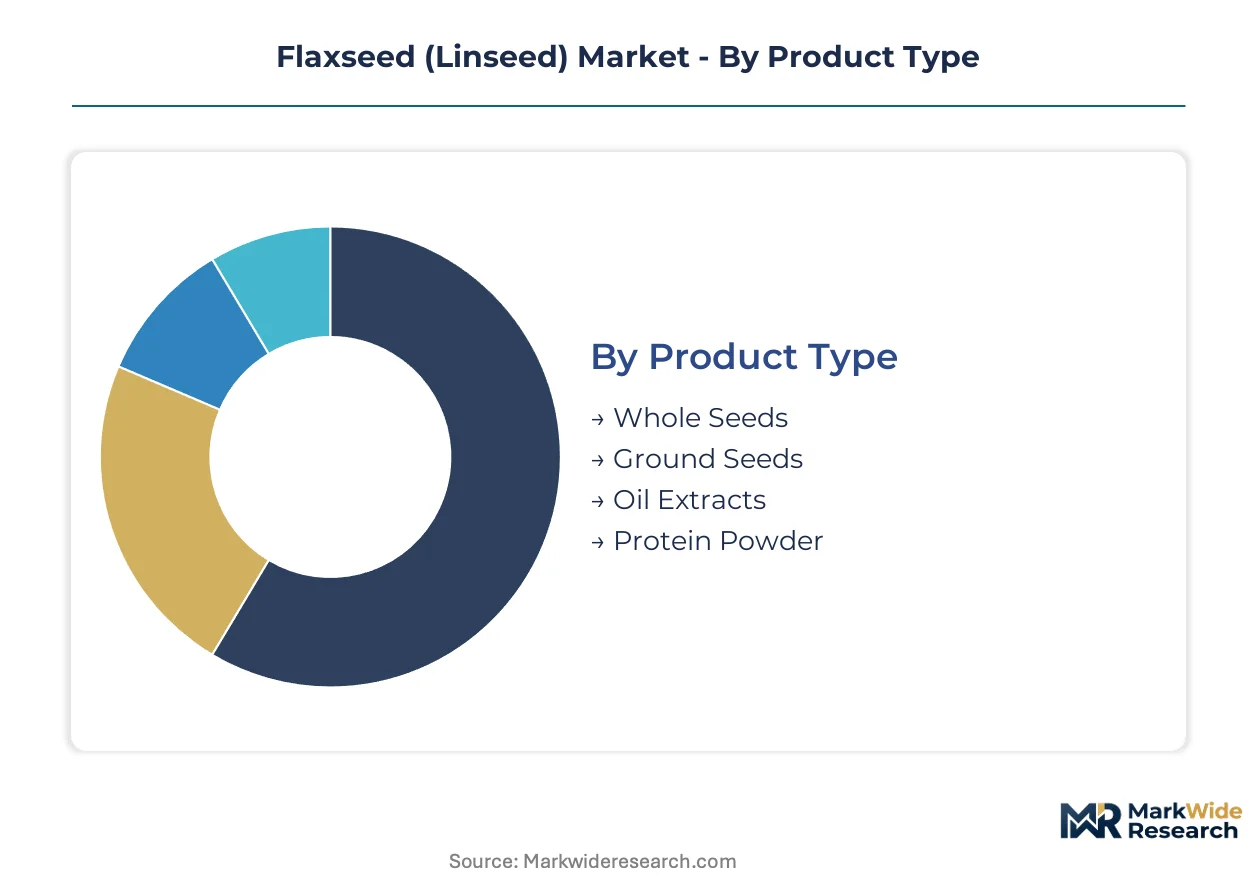
Flaxseed segmentation reveals how value migrates through processing intensity. Raw seed commoditizes while protein isolation and organic certification capture margin. Understanding these tiered value pools directs capital allocation across crushing, extraction, and formulation infrastructure.
Product Type:
The use-case spectrum spans from bulk agricultural commodity to high-purity functional ingredients, with processing depth determining pricing power and customer stickiness.
- Ground Seeds:Milled flaxseed delivers enhanced bioavailability of lignans and dietary fiber through mechanical particle reduction. Food manufacturers in Canada and Germany specify particle size distributions for bakery integration, driving specification-grade contracting. This segment anchors volume demand through direct-to-bakery supply agreements with microbial certificate requirements.
- Oil Extracts:Cold-pressed and refined flaxseed oil concentrates alpha-linolenic acid for omega-3 fortification. REACH-compliant European food manufacturers are consolidating procurement around solvent-free extraction methods, compressing margins for hexane-based processors. Premium positioning depends on fatty acid profile verification through NIR spectroscopy at origin elevators.
- Whole Seeds:Raw seed for home grinding and small-scale food production, traded primarily through bulk agricultural channels with minimal value addition.
- Protein Powder:Flax protein isolate serves plant-based meat alternatives and sports nutrition with emulsification and fiber fortification properties.
The dominant share belongs to Ground Seeds, while Protein Powder is closing the gap fastest.
End Use Industry:
Cost tier stratification separates commodity feed applications from premium human nutrition, with regulatory scrutiny intensity rising toward the consumer-facing end.
- Food & Beverage:Bakery fortification and dairy alternative formulations consume specification-grade milled flax with defined oil content and microbial limits. Clean-label procurement committees at North American CPG firms mandate single-origin disclosure and carbon intensity scoring, consolidating supplier lists toward vertically integrated handlers.
- Animal Feed:Aquaculture feed manufacturers substitute ALA-rich flaxseed meal for fish oil in salmon and shrimp diets to satisfy retailer sustainability commitments. Prairie-origin supply contracts with guaranteed offtake minimums are expanding to secure volume for this segment.
- Dietary Supplements:Encapsulated flax oil and lignan extracts targeting cardiovascular and hormonal health claims, constrained by FDA and EFSA narrow approved language for ALA benefits.
- Cosmetics:Linseed oil's emollient and film-forming properties serve natural skincare formulations, though volume remains limited relative to food applications.
Food & Beverage commands the largest value pool, yet Animal Feed is expanding most quickly as marine ingredient substitution accelerates.
Distribution Channel:
Customer type determines traceability burden and margin structure, with identity-preserved supply chains commanding premium positioning over undifferentiated bulk.
- Supermarkets:Mass retail channels for conventional milled flax and private-label flax oil, competing on shelf price with limited differentiation.
- Health Stores:Specialty retailers curating organic-certified and cold-pressed SKUs with origin storytelling for wellness-focused consumers.
- Online Retail:Direct-to-consumer subscription models for protein powder and specialty oil formats, enabling margin capture without distributor intermediation.
- Specialty Shops:Artisan bakery supply and foodservice distribution with specified particle size and lot traceability for professional kitchens.
Supermarkets retain volume leadership, though Online Retail is climbing fastest as subscription nutrition models penetrate plant-protein categories.
Form:
Certification grade and processing method create pricing stratification that separates premium procurement from commodity substitution.
- Organic:Certified supply chains under USDA Organic and EU Organic frameworks command widening premia as solvent-free becomes a de facto import prerequisite for European buyers. Three-year land conversion requirements and parallel supply chain segregation strain working capital for prairie elevator operators.
- Cold-Pressed:Mechanical extraction without hexane preserves omega-3 integrity and satisfies REACH authorization requirements for EU market access. Crushers are retrofitting cold-press lines or installing supercritical CO2 extraction to maintain positioning.
- Non-Organic:Conventional production for cost-sensitive feed and industrial applications, facing margin compression from organic premia expansion.
- Roasted:Heat-treated seeds for flavor profile modification in snack and bakery applications, niche relative to raw and cold-pressed formats.
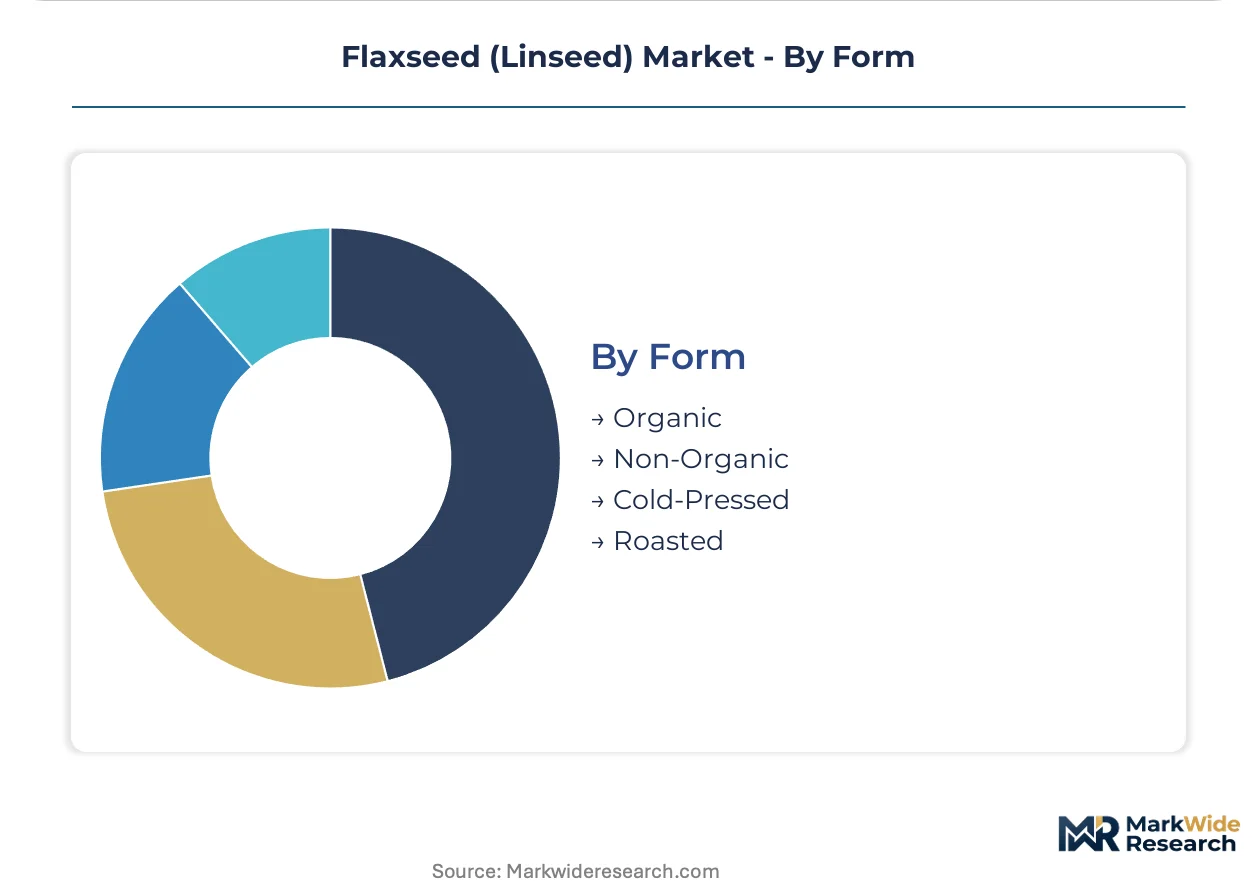
Organic holds the premium position, while Cold-Pressed is gaining share fastest as regulatory thresholds tighten on solvent residues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export origination concentrates in prairie grain belts while import demand clusters in omega-3 deficient regions with stringent residue standards. Trade flows reflect this asymmetry: Canadian handlers ship identity-preserved seed to European food manufacturers and Asian aquafeed compounders. Regulatory divergence between REACH authorization zones and conventional import markets is reshaping supplier qualification protocols.
Canada
Prairie province contract farming dominates exportable supply origination, with Saskatchewan and Manitoba elevators handling over 80 percent of food-grade volume. Health Canada novel food approvals and CFIA export certification requirements govern cross-border seed shipments. Richardson International Limited anchors western Canadian handling infrastructure, controlling export-grade flows through Vancouver and Thunder Bay port terminals.
Germany
REACH authorization mandates for hexane solvent residues are disqualifying conventional crude oil imports, redirecting procurement toward cold-pressed Baltic and Canadian origins. EFSA narrow approved language for ALA cardiovascular claims constrains marketing differentiation against marine omega-3 sources. Hamburg and Bremen crushing facilities are retrofitting supercritical CO2 extraction lines to preserve EU market access.
United States
FDA food-grade flaxseed claims and USDA Organic certification thresholds govern domestic premium positioning, with North Dakota and Minnesota expanding contract acreage for identity-preserved programs. Archer Daniels Midland Company leverages its North American crushing network to secure origination volumes across the northern tier. Chicago and Minneapolis grain merchants are deploying near-infrared spectroscopy at intake points for immediate oil content verification.
India
FSSAI novel food approvals for flax-fortified atta and dairy alternatives remain underexploited relative to population scale and rising protein awareness. BIS quality standards for edible oil imports create friction for uncertified suppliers. Gujarat and Rajasthan processing clusters are expanding cold-press capacity to serve domestic functional food manufacturers and export markets.
China
Dual carbon goals and tightening MEE environmental compliance are pressuring solvent-based crushers to accelerate technology replacement or exit food-grade segments. NMPA novel food registration requirements for imported oilseeds add regulatory lag to market entry. Shandong and Hebei oilseed crushing belts are consolidating around vertically integrated handlers with farm-level traceability systems.
Flaxseed (Linseed) Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated grain handlers with captive origination networks and identity-preserved logistics capabilities. Mid-scale processors face capital replacement pressure as REACH and organic certification requirements tighten. Three strategic archetypes dominate: prairie-based grain merchants with elevator infrastructure, multinational agribusinesses with backward integration into farmer contracting, and specialty oilseed crushers with cold-press technology. Competitive moves concentrate on ERP upgrades for lot traceability and prepayment contracting for dedicated acreage.
Within the multinational agribusiness tier, Archer Daniels Midland Company and Cargill, Incorporated exemplify scale-driven positioning through North American crushing networks and farmer contracting programs. Richardson International Limited anchors the prairie grain merchant archetype with western Canadian handling infrastructure. Among specialty processors, Bioriginal Food & Science Corp. occupies a position representing omega-3 ingredient formulation capabilities.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| AgMotion, Inc. |
| TA Foods Ltd. |
| Richardson International Limited |
| CanMar Foods Ltd. |
| Bioriginal Food & Science Corp. |
| Johnson Seeds |
| Healthy Oilseeds |
| Others |
Pricing and Supply Chain Analysis
Saskatchewan elevator infrastructure anchors North American origination capacity, with Prairie province concentration compressing farmgate basis while amplifying handler negotiating leverage over export buyers. Cold-press retrofit investments and organic certification segregation feed into widening premia for solvent-free supply, restructuring how value distributes across crush tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with specification-grade milled flax commanding premia over commodity seed through fatty acid profile verification and microbial certificate guarantees. Price differentiation rests on certification grade (USDA Organic, EU Organic) and extraction method (cold-pressed versus solvent-based), with REACH-compliant European food manufacturers least price-sensitive due to regulatory disqualification of conventional alternatives. Cost compression in hexane-based processing tiers is intensifying because crushers serving EU markets must absorb capital replacement cycles or surrender food-grade positioning entirely.
Supply Chain Analysis
Tariff exposure between Canada and China dominates strategic planning for prairie handlers, with Beijing's NMPA novel food registration requirements adding regulatory lag that diverts spot volumes toward European and Asian aquafeed compounders. Geographic supply concentrates in Canada, Russia, and Kazakhstan, with raw material dependencies on Prairie-origin seedstock, hexane solvent for conventional crush, and supercritical CO2 equipment for technology upgrades. Single-source vulnerability manifests in rail logistics bottlenecks through Vancouver and Thunder Bay port terminals. Distribution runs through vertically integrated grain merchants with captive elevator networks and identity-preserved lot traceability systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital seed-to-oil traceability platforms represent the fastest-expanding service-attach layer, with subscription-based audit verification and real-time carbon intensity scoring generating recurring revenue streams that outpace hardware margins on crushing equipment.
For Market Incumbents: Build identity-preserved logistics moats through ERP upgrades that compress lot traceability costs below mid-scale handler breakeven thresholds. Prairie-based grain merchants should prepay for dedicated organic acreage with guaranteed offtake minimums to lock origination volume against Baltic competitor expansion. Backward integration into farmer contracting programs defends positioning against multinational agribusinesses with deeper balance sheets for supercritical CO2 extraction retrofits. For New Entrants and Emerging Players: Mid-scale organic-certified crushers in Gujarat and Rajasthan represent the most penetrable entry point, with underexploited FSSAI novel food approvals for flax-fortified atta creating first-mover positioning in Indian functional food manufacturing. Baltic-origin cold-pressed supply gaps in German REACH-compliant procurement channels offer second white-space target. Direct contracting with artisan bakeries bypassing distributor intermediation provides the clearest go-to-market angle for specification-grade milled flax with defined particle size distributions. For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-linked ingredient consolidation play because aquaculture feed substitution trends and EU Green Deal traceability mandates are structurally expanding addressable market for verified low-carbon oilseeds. Acquisition targets should screen for handlers with deployed near-infrared spectroscopy infrastructure and organic certification workflows already digitized. The signal to watch is Prairie province rail logistics investment announcements, as capacity expansion would decompress origination bottlenecks and shift margin capture toward crush technology rather than elevator control.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farmer Contracting | Captures origination volume ahead of REACH-compliant European demand expansion. |
| Cold-Press Technology Retrofit | Preserves EU market access as ECHA tightens hexane residue maximum permissible limits. |
| Digital Traceability Platform Deployment | Compresses organic audit cycles and enables real-time buyer verification of carbon intensity. |
| Identity-Preserved Logistics Investment | Maintains lot segregation from farm through crush to export for premium-tier pricing. |
| Direct-to-Bakery Distribution Channel | Bypasses distributor intermediation to capture margin on specification-grade milled flax. |
Research Methodology
Operator-level perspectives from grain elevator managers, organic certification auditors, aquafeed procurement leads, and cold-press equipment engineers anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation from CFIA export certification records, USDA Organic handler databases, ECHA REACH authorization filings, and customs trade data. Bottom-up volume estimates from prairie province crush capacity and top-down demand segmentation from end-use industry consumption patterns were triangulated to converge on market sizing.
Scenario-bracketing around regulatory implementation timelines and technology adoption curves structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product type (ground seeds, oil extracts, protein powder), form (organic, cold-pressed, conventional), and end-use industry (food and beverage, animal feed, dietary supplements). CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity expansion schedules, with forecast inputs incorporating NIR spectroscopy deployment rates and EU Green Deal carbon intensity benchmarking adoption.
Macroeconomic conditions sit as an overlay; deviation in Prairie province growing season precipitation patterns, ocean freight rate volatility, or euro-dollar exchange rate movements would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology cost decline curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Buckwheat Market
Seeds
Europe Forage Seed Market
Seeds
Crambe Abyssinica Seed Oil Market
Seeds
Avena Sativa Market
Seeds
Punnet Market
Seeds
Chamomile Seeds Market
Seeds
China Vegetable Seed Market
Seeds
Myanmar Seed Market
Seeds
Southeast Asia Seed Market
Seeds
Russia Forage Seed Market
Seeds
Mexico Vegetable Seed Market
Seeds
South Africa Seed Market
Seeds
Rapeseed Market
Seeds
Global Rice Seed Market
Seeds
Glycine Soja (Soybean) Seed Extract Market
Seeds
Mustard Seeds Market