
 Fruit Tomatoes Seed Market | 2026-2036
Fruit Tomatoes Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Tomatoes Seed Market Insights
Market Overview
Spain's Almería greenhouse corridor is narrowing the seasonal supply gap for European retailers seeking consistent fruit tomato volumes. BASF SE leverages its vegetable seed platform to sustain R&D intensity in disease-resistant hybrids. Syngenta Group anchors its position through integrated crop protection bundled with seed genetics. Bayer AG competes via digital farming tools paired with premium varietal portfolios.
Technical Definition and Segment Structure
Fruit tomatoes seed refers to sexually propagated planting material of Solanum lycopersicum varieties bred for fresh consumption, typically selected for brix levels above six degrees, uniform ripening, and extended shelf-life. These seeds undergo precision priming and pelleting to ensure synchronous germination in commercial transplant operations. Cherry and grape types lead volume share due to snacking-format demand from European and North American retail chains. Indeterminate hybrids capture margin pools in greenhouse hydroponics, where labor efficiency and truss uniformity command premium pricing. Heirloom open-pollinated varieties occupy niche channels serving restaurant procurement and farmers' market direct sales.
Regulatory Environment and Outlook
EU Plant Variety Rights under CPVO and seed certification standards enforced by national authorities govern market access and royalty collection across member states. REACH and EU Green Deal sustainability disclosures increasingly shape breeder investment priorities toward reduced-input varieties. Stakeholders must monitor evolving carbon-accounting requirements for protected horticulture and their downstream effects on seed pricing and variety registration timelines.
Market Dynamics
EU Green Deal carbon-accounting mandates are restructuring breeder investment priorities toward reduced-input varieties, forcing seed producers to document embodied emissions across cultivation cycles.
Growth Catalysts
- Controlled-environment agriculture:Spain's Almería province hosts Europe's densest greenhouse cluster, driving varietal specialization for year-round tomato supply to Northern European retailers.
- REACH sustainability disclosures:Chemical registration protocols under ECHA now require seed coating formulations to demonstrate biodegradability, accelerating R&D in bio-based priming agents.
- Snacking-format demand:Cherry and grape tomato categories command premium shelf space in North American and European retail chains, pulling breeder portfolios toward smaller-fruit hybrids.
Market Restraints
- Phosphorus supply volatility:Seed pelleting operations depend on phosphate rock concentrated in Morocco and Western Sahara, exposing cost structures to geopolitical supply disruptions.
- Variety registration timelines:CPVO examination procedures for EU Plant Variety Rights extend 18-36 months, compressing royalty collection windows for hybrid developers.
- Open-pollinated substitution:Heirloom varieties in farmers' market channels compete on flavor differentiation, limiting price elasticity for premium F1 hybrids in direct-to-consumer segments.
Strategic Opportunities
- Carbon-credit monetization:Netherlands greenhouse operators under EU Green Deal protocols can capture verified emission reductions, creating pricing power for low-carbon seed inputs.
- Digital phenotyping convergence:Machine vision and hyperspectral imaging are compressing varietal selection cycles, enabling breeders to stack disease-resistance traits faster than traditional field trials.
- Direct-to-grower channels:E-commerce platforms bypass distributor markups for small-scale protected horticulture operators in Poland and Romania seeking specialized indeterminate hybrids.
Industry Challenges
- Trait-stacking complexity:Combining multiple disease-resistance genes (ToBRFV, TYLCV, TSWV) requires precise marker-assisted selection protocols that strain technical staffing in mid-scale breeding programs.
- Seed health certification delays:National authorities enforcing EU seed certification standards face backlogs in pathogen testing for tomato mosaic virus, extending time-to-market for new introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Tomatoes Seed Market |
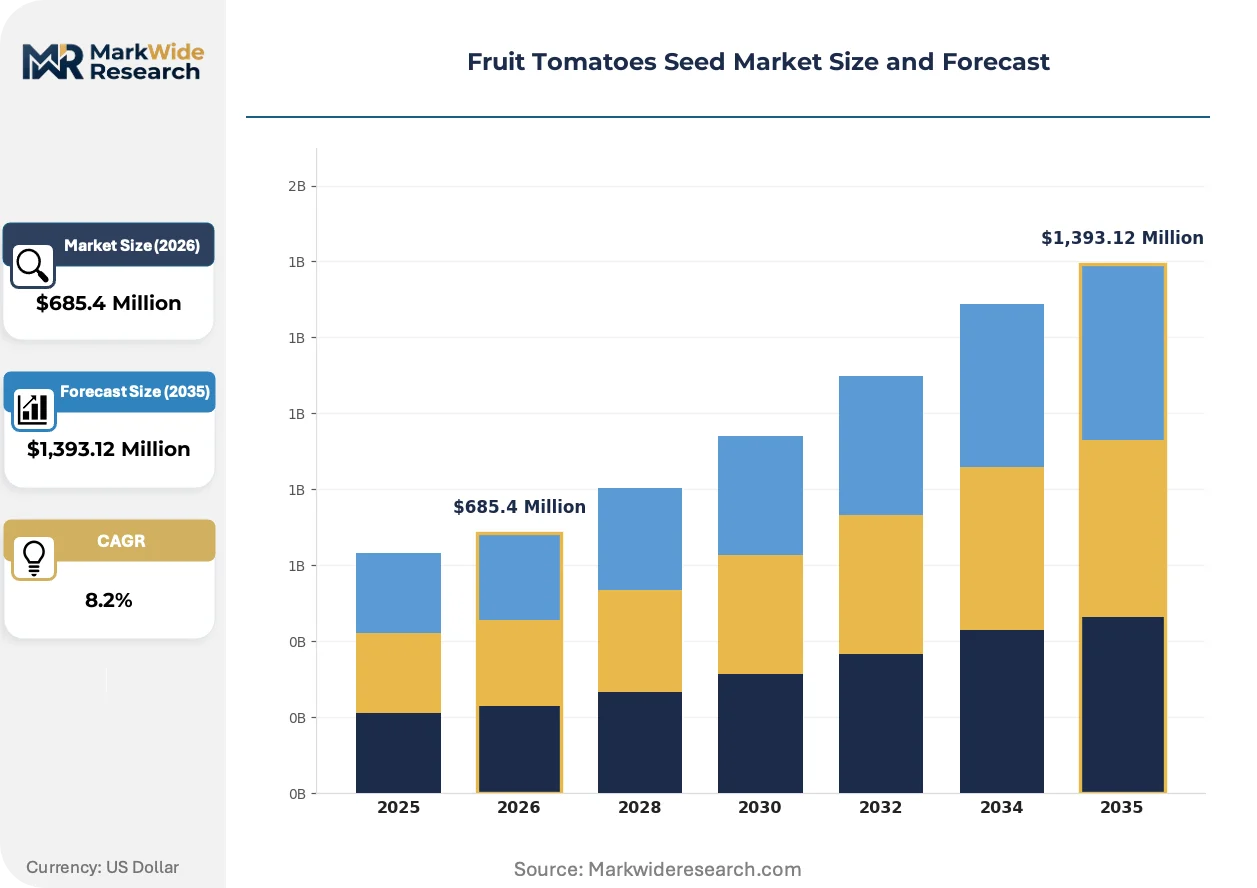
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cherry, Plum, Beefsteak, Grape Hybrid Type: Indeterminate, Determinate, Heirloom, Open-Pollinated End Use: Commercial Farming, Home Gardening, Greenhouses, Hydroponics Packaging Type: Sachets, Bags, Bulk, Blister Packs |
| Companies Covered | BASF SE, Bayer AG, Syngenta Group, Groupe Limagrain, Rijk Zwaan Zaadteelt en Zaadhandel B.V., Enza Zaden, Sakata Seed Corporation, Takii & Co. Ltd., Corteva Agriscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Tomatoes Seed Market Trends and Innovations
Precision breeding tools and sustainability disclosure requirements are compressing varietal development cycles while redirecting portfolio priorities toward input-efficient genetics.
Gene editing via CRISPR-Cas9 is hybridizing conventional hybridization with targeted trait introgression, enabling breeders to fix desirable alleles without transgenic classification. Dutch greenhouse operators are piloting these varieties under controlled conditions to validate field performance. The technology is hybridizing regulatory pathways as breeders navigate divergent GMO definitions across jurisdictions.
EU Green Deal sustainability protocols now mandate scope-three emission disclosures for agricultural inputs, forcing seed producers to document carbon intensity across multiplication and coating operations. Breeder investment is reallocating toward reduced-fertilizer varieties that qualify for green procurement tenders. Protected horticulture in the Netherlands faces the steepest compliance thresholds, accelerating adoption of lifecycle assessment tools.
Retail procurement consolidation is compressing varietal approval timelines as supermarket chains demand exclusive supply agreements with documented shelf-life performance. Category managers at major European retailers now specify brix levels and truss uniformity metrics in seed sourcing contracts. Spain's Almería growers are responding by specializing in single-variety blocks that meet chain-specific quality protocols.
Fruit Tomatoes Seed Market Segmentation
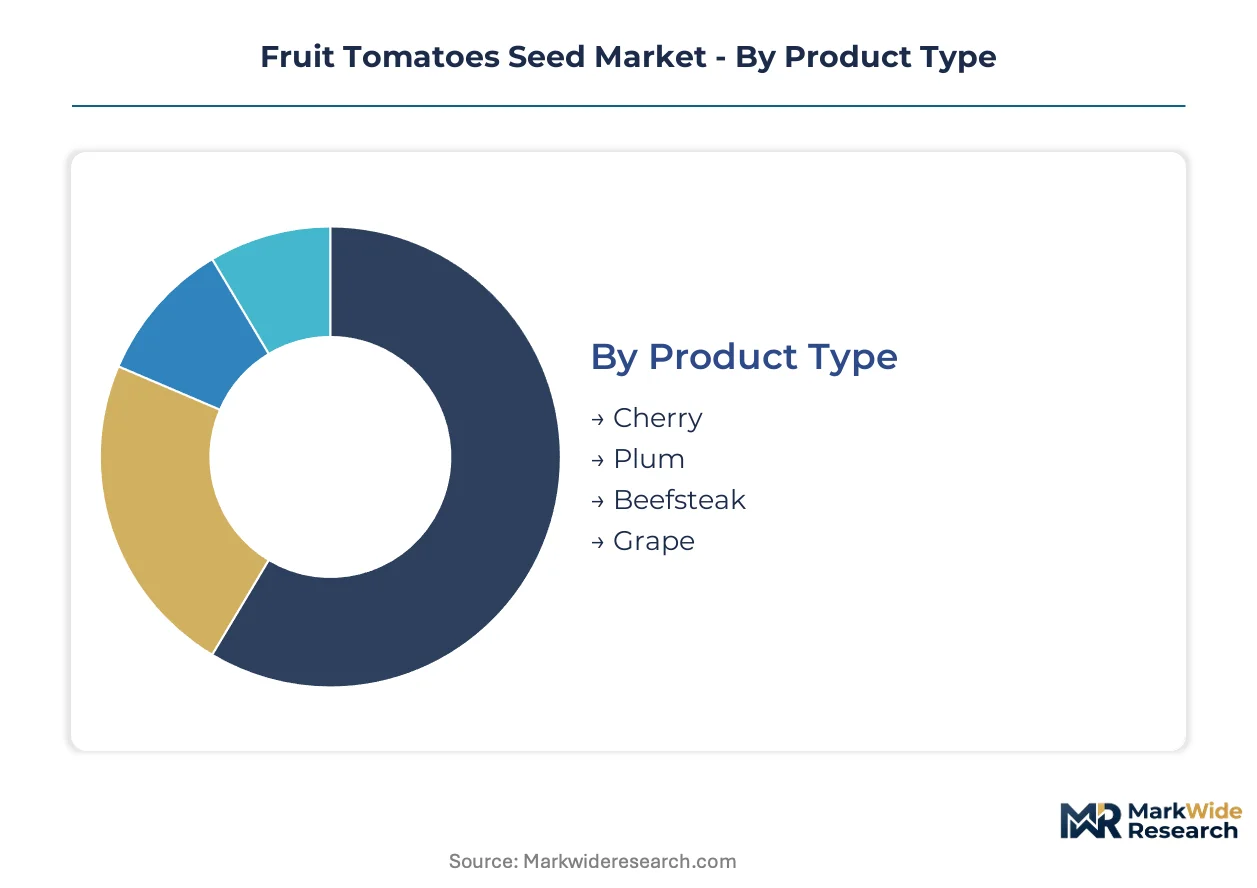
Segmentation in the Fruit Tomatoes Seed Market reveals how varietal specialization aligns with cultivation intensity, distribution scale, and end-user technical requirements. Breeders configure seed formats and genetic architectures to match the divergent needs of industrial greenhouse operators versus home gardeners and direct-market producers.
Product Type:
Cost tier differentiation across fruit morphology shapes breeding investment and royalty structures, with smaller formats commanding premium positioning in retail-facing supply chains.
- Cherry:Small-fruited hybrids bred for elevated brix and truss uniformity dominate snacking-format retail procurement. Netherlands greenhouse operators under EU Green Deal protocols are scaling these varieties for year-round Northern European supply.
- Plum:Elongated fruit types optimized for paste and processing applications concentrate in Spain's Almería province, where controlled-environment agriculture clusters serve industrial tomato product manufacturers seeking consistent solids content.
- Beefsteak:Large-format varieties for fresh-slice applications occupy mid-tier pricing in conventional field production.
- Grape:Miniature elongated types bridge snacking and salad segments with compact truss architecture.
Cherry commands the established base. The steepest expansion runs through Plum.
Hybrid Type:
Application intensity determines genetic system selection, with protected horticulture demanding heterosis exploitation and direct-market channels tolerating open-pollinated stability.
- Indeterminate:Vining growth habit hybrids bred for extended harvest windows and truss uniformity capture margin pools in hydroponic greenhouse operations. Spain's Almería growers deploy these varieties under integrated crop protection protocols for chain-specific retail contracts.
- Determinate:Bush-type architectures with synchronized fruit set serve mechanized field harvesting and concentrated processing windows.
- Heirloom:Open-pollinated varieties preserved for flavor differentiation and regional identity occupy farmers' market channels and restaurant procurement in Italy and France.
- Open-Pollinated:Stable genetic lines without hybrid vigor serve home gardening and seed-saving communities seeking cultivation autonomy.
Indeterminate captures the premium tier. Open-Pollinated is climbing the fastest among cost-conscious direct-market producers.
End Use:
Customer type segmentation separates volume-scale commercial operators from technical specialists and hobbyist cultivators, each demanding distinct seed formats and support services.
- Commercial Farming:Large-scale field operations purchasing treated seed in bulk volumes drive standardization in disease-resistance trait packages. Polish and Romanian growers are expanding protected hectarage under EU Common Agricultural Policy support mechanisms.
- Greenhouses:Controlled-environment agriculture operators in the Netherlands and Spain specify primed and pelleted seed with documented germination uniformity for automated transplant systems.
- Hydroponics:Soilless cultivation specialists require varieties bred for root-zone pathogen resistance and nutrient-use efficiency in recirculating systems.
- Home Gardening:Small-scale cultivators purchasing retail sachets prioritize flavor descriptors and cultivation simplicity over yield metrics.
Commercial Farming commands the established base. Hydroponics shows the steepest expansion trajectory as substrate-based systems proliferate.
Packaging Type:
Volume scale and distribution channel structure dictate seed containment formats, from precision-count retail units to bulk agricultural totes.
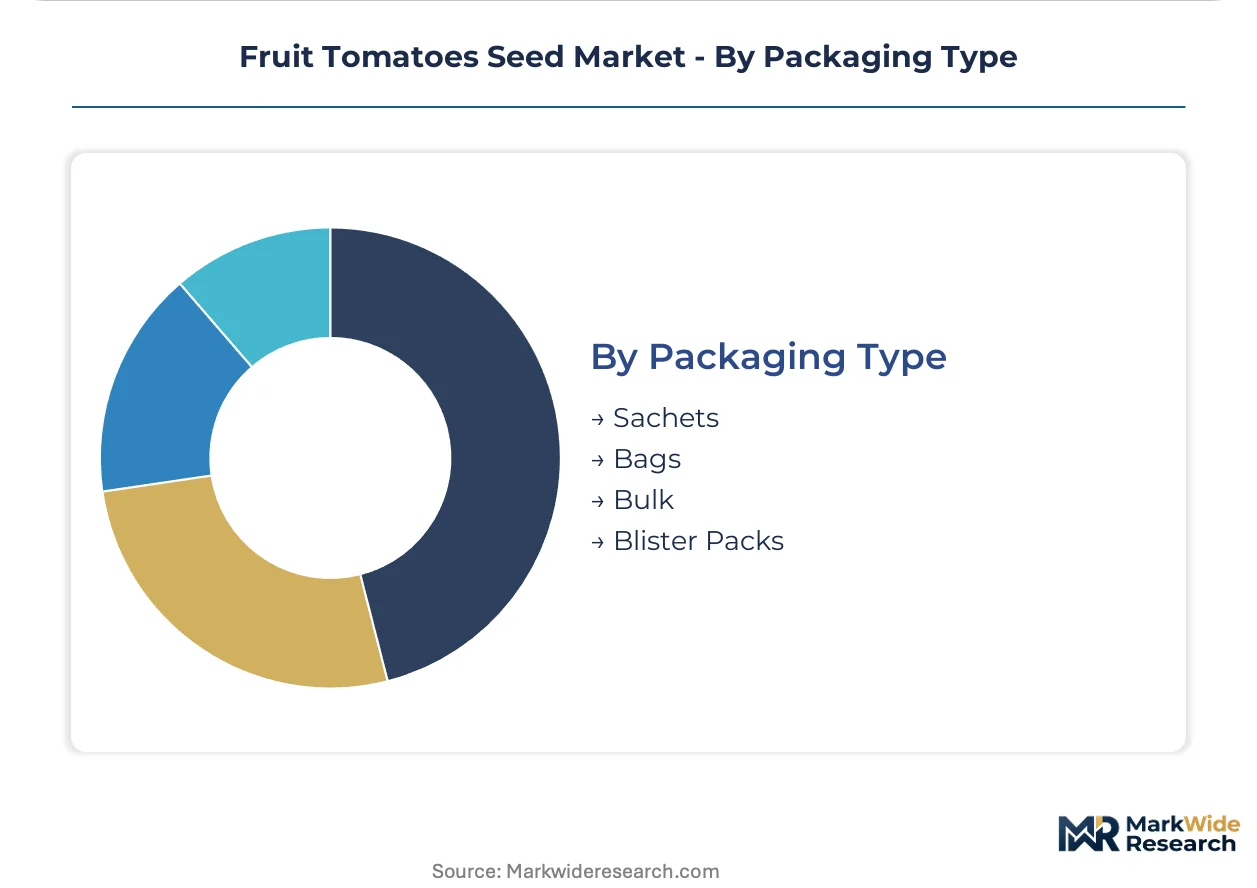
- Sachets:Small-format paper or foil packets containing 10-50 seeds serve home gardening retail and trial plots for commercial variety evaluation.
- Bags:Multi-kilogram woven polypropylene containers deliver treated seed to field-scale farming cooperatives and commercial greenhouse nurseries.
- Bulk:Unpackaged seed in agricultural totes minimizes per-unit packaging cost for large-scale multiplication and direct processor supply.
- Blister Packs:Thermoformed plastic retail displays with printed cultivation instructions target garden center impulse purchasing and gift market segments.
Bags command the established base. Sachets are gaining share fastest through e-commerce direct-to-grower channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain concentrates protected tomato cultivation within Europe's most intensive greenhouse corridor, while Dutch operators scale year-round supply under strict sustainability protocols. National breeding programs and varietal registration systems vary sharply across major producing territories.
Spain
Almería province hosts Europe's densest controlled-environment agriculture cluster, driving specialized cherry and plum tomato seed demand for continuous harvest cycles. EU Plant Variety Rights under CPVO govern varietal registration timelines affecting royalty collection for hybrid developers. Andalusian greenhouse cooperatives now contract directly with Northern European retail chains, specifying brix levels and truss uniformity metrics in procurement agreements.
Netherlands
Westland and Limburg greenhouse operators deploy precision hydroponics requiring indeterminate hybrids bred for nutrient-use efficiency and labor automation compatibility. EU Green Deal carbon-accounting mandates force seed producers to document embodied emissions across multiplication and coating operations. Wageningen University research partnerships accelerate CRISPR-based disease-resistance trait stacking for ToBRFV and TYLCV management.
United States
California's Central Valley and Florida's winter production zones drive field-scale demand for determinate processing tomatoes and fresh-market beefsteak varieties. USDA-APHIS phytosanitary certification requirements govern seed import protocols from European multiplication facilities. Mexico's Sinaloa and Baja California greenhouse sectors increasingly source hybrid genetics through cross-border distributor networks serving North American retail consolidation.
China
Shandong and Hebei provinces anchor domestic protected horticulture expansion, with Shouguang's vegetable seed market serving as a distribution hub for Asian greenhouse operators. National seed law revisions under the Ministry of Agriculture and Rural Affairs strengthen intellectual property enforcement for hybrid tomato genetics. Yangtze River Delta substrate-culture facilities are trialing Dutch-bred indeterminate varieties under localized climate adaptation protocols.
Morocco
Souss-Massa and Doukkala-Abda regions supply counter-seasonal tomatoes to European markets through preferential trade agreements, driving demand for heat-tolerant hybrid seed. National Office of Food Safety (ONSSA) seed certification standards align with EU export requirements for phytosanitary compliance. Agadir-based greenhouse clusters are expanding pelleted seed procurement for automated transplant systems serving French and German retail contracts.
Fruit Tomatoes Seed Market Competitive Landscape
Integrated agrochemical-seed conglomerates and specialized vegetable breeding houses split the market along capability intensity and portfolio breadth. Three strategic archetypes dominate: diversified life-science platforms bundling crop protection with genetics, vegetable-seed specialists concentrating on trait precision and regional adaptation, and regional multiplication operators serving cost-sensitive field production. Competitive moves center on digital farming tool integration and direct-to-grower channel development bypassing traditional distributor networks.
Among diversified life-science platforms, BASF SE, Bayer AG, and Syngenta Group exemplify the integrated-agriculture-input archetype, each occupying positions where seed genetics merge with crop protection and digital advisory services. These conglomerates represent the capital-intensive tier where R&D scale and regulatory navigation capabilities create structural barriers for mid-scale competitors. Specialized vegetable breeding houses including Rijk Zwaan and Enza Zaden sit within the precision-genetics tier, emphasizing trait specificity for protected horticulture and regional climate adaptation rather than broad portfolio coverage.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta Group |
| Groupe Limagrain |
| Rijk Zwaan Zaadteelt en Zaadhandel B.V. |
| Enza Zaden |
| Sakata Seed Corporation |
| Takii & Co. Ltd. |
| Corteva Agriscience |
| Others |
Pricing and Supply Chain Analysis
Phosphate rock concentration in Morocco and Western Sahara feeds directly into margin capture by seed pelleting specialists serving European greenhouse operators. Royalty structures for hybrid tomato genetics concentrate pricing power with breeders holding EU Plant Variety Rights, while downstream growers absorb coating cost volatility through contract pass-through mechanisms.
Pricing Analysis
EU Plant Variety Rights dictates the pricing tier structure across the fruit tomato seed market, separating premium indeterminate hybrids with stacked disease-resistance traits from standard determinate field varieties and economy-grade open-pollinated lines. Price differentiation rests on certification grade under CPVO examination protocols and volume scale of multiplication orders. Cost compression in standard-tier field seed is intensifying because of open-pollinated substitution in direct-market channels. Small-scale protected horticulture operators in Poland and Romania exhibit highest price sensitivity, while Netherlands greenhouse cooperatives under EU Green Deal contracts demonstrate lowest elasticity due to chain-specific quality premiums.
Supply Chain Analysis
Extended payment terms from Dutch greenhouse cooperatives to seed distributors are compressing working capital cycles throughout the multiplication tier. Geographic supply concentrates in the Netherlands for precision priming operations, Spain for Almería corridor distribution, and Morocco for phosphate-based pelleting inputs. Raw material dependencies include phosphate rock for coating formulations, synthetic polymer binders, and bio-based priming agents under REACH biodegradability protocols. Single-source vulnerability runs through Moroccan phosphate supply exposed to geopolitical disruption. Distribution runs through breeder-direct channels for large greenhouse cooperatives and agricultural distributor networks for field-scale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fruit tomato seed market is recovering from input cost cyclicality tied to phosphate fertilizer price normalization. Breeders with captive pelleting capacity and established CPVO portfolios are best positioned to capture margin expansion through the upswing.
For Market Incumbents: Build regulatory moats by accelerating CRISPR-based trait stacking for ToBRFV resistance ahead of EU gene-editing framework finalization. Deepen backward integration into phosphate coating operations to neutralize Moroccan supply volatility. Capture channel control through direct-to-grower e-commerce platforms bypassing distributor markups in Poland and Romania.
For New Entrants and Emerging Players: Mid-scale hydroponic operators in China's Yangtze River Delta represent the most penetrable entry point for Dutch-bred indeterminate varieties under localized climate adaptation protocols. Direct-to-grower digital channels serving Romanian protected horticulture expansion offer lowest customer acquisition friction against established distributor networks. Partner with Wageningen University research consortia for accelerated variety validation under controlled conditions.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vegetable seed specialists holding narrow regional variety portfolios but strong CPVO registration pipelines. Five-to-ten year viability hinges on carbon-credit monetization capabilities for reduced-input varieties under EU Green Deal procurement tenders. Monitor CPVO examination backlog resolution as inflection signal for royalty collection velocity and new introduction time-to-market.
| Strategic Initiative | Industry Significance |
|---|---|
| Trait Stacking Acceleration | CRISPR-based ToBRFV resistance development compresses varietal selection cycles for Dutch greenhouse operators. |
| Backward Integration into Coating | In-house phosphate pelleting capacity neutralizes Moroccan supply concentration and REACH formulation compliance costs. |
| Direct-to-Grower Channel Development | E-commerce platforms bypass distributor markups for Poland and Romania's expanding protected horticulture sector. |
| Carbon-Credit Variety Registration | Reduced-fertilizer hybrids qualify for EU Green Deal green procurement tenders in Netherlands greenhouse clusters. |
| Research Partnership Expansion | Wageningen University collaborations accelerate disease-resistance validation under controlled-environment protocols. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of breeder R&D disclosures, CPVO registration databases, and EU customs trade data for seed multiplication flows. Primary interviews engaged vegetable seed breeding directors, greenhouse cooperative procurement managers, and agricultural distributor network heads across the Netherlands, Spain, and Poland. Secondary validation drew from ECHA chemical registration filings, EU Plant Variety Rights examination records, and national seed certification authority reports. Bottom-up variety-level volume estimates triangulated against top-down greenhouse hectarage expansion data.
Forecast inputs include protected horticulture adoption rates, EU Green Deal carbon-accounting compliance thresholds, and CRISPR regulatory pathway developments across the analysis window. Segmentation dimensions modeled span fruit morphology, hybrid growth habit, cultivation system intensity, and regional climate adaptation requirements. CAGRs derived from compound growth trajectory analysis applied to variety-level royalty streams and multiplication volume projections. Industry-specific inputs incorporate phosphate supply elasticity and CPVO examination timeline volatility.
Macroeconomic conditions sit as an overlay; deviation in fertilizer input costs, EU agricultural subsidy allocations, or greenhouse energy pricing would shift the trajectory. Forecasts reflect documented assumptions regarding breeder R&D intensity and regulatory examination capacity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Mexico Seed Market
Seeds
Thailand Seed Market
Seeds
Global Rice Seed Market
Seeds
Custom Selected Seed Market
Seeds
South America Quinoa Seeds Market
Seeds
Australia Oilseed Market
Seeds
Southeast Asia Seed Market
Seeds
Global Soybean Seed Market
Seeds
E. Angustifolium Market
Seeds
Global Sports Turf Seed Market
Seeds
Crambe Abyssinica Seed Oil Market
Seeds
North America Cannabis Seeds Market
Seeds
Lupin Market
Seeds
Philippines Seed Market
Seeds
North America Maize Seed Treatment Market
Seeds
Europe Chia Seeds Market