
 Smoke Flavorings Market | 2026-2036
Smoke Flavorings Market Size, Share, and Industry Trends Forecast 2026-2036
Smoke Flavorings Market Analytics
Modular flavoring kits is decoupling smoke flavor procurement from captive smoking equipment, letting mid-size meat processors source concentrated liquid formats without capital-intensive smokehouses. Besmoke Ltd leverages its British heritage positioning to supply premium hardwood-derived smoke extracts to European charcuterie specialists. Kerry Group anchors global supply through its integrated taste and nutrition platform, bundling smoke flavorings with texture systems for processed meat clients. Sensient Technologies Corporation differentiates via clean-label smoke color-flavor combinations that help brands navigate sodium reduction and artificial additive restrictions.
Smoke flavorings comprise thermally degraded wood-derived condensates—primarily pyroligneous acids, carbonyls, and phenolic compounds—standardized for food-grade application through controlled pyrolysis of hardwoods such as hickory, mesquite, or oak, then refined via filtration and dilution to achieve consistent flavor intensity and microbial safety. Liquid smoke dominates commercial volumes due to its dosing precision and shelf stability in industrial marinades and brine injections, while smoke powder captures margin pools in dry rub and seasoning blends where water activity constraints matter. Meat processing remains the structural anchor application, though snack food manufacturers are expanding smoke powder use in extruded and kettle-cooked formats as clean-label savory profiles gain shelf space.
EFSA maintains active evaluation protocols for primary condensate smoke flavorings under EU food improvement agent frameworks, while the FDA regulates these ingredients as GRAS substances subject to voluntary notification pathways that shape formulation choices for exporters. BIS standards in India and evolving GB food additive classifications in China are creating divergent compliance templates that multinational suppliers must maintain in parallel. Stakeholders should monitor regulatory divergence between jurisdictions as a decisive factor in regional formulation strategies and capital allocation for new production capacity.
Market Dynamics
Meat processors are abandoning captive smokehouse infrastructure in favor of concentrated liquid formats that standardize flavor intensity while eliminating thermal emissions compliance burdens. This capital-light procurement model is compressing supplier margins and accelerating consolidation among hardwood pyrolysis specialists.
Growth Catalysts
- REACH Chemicals Framework:ECHA's tightening purity benchmarks for pyroligneous acid derivatives are disqualifying artisanal suppliers and concentrating demand among certified industrial producers capable of filtration and dilution standardization.
- Snack Food Extrusion:Kettle-cooked and extruded savory formats are absorbing smoke powder volumes as clean-label savory profiles displace artificial flavor systems in retail shelf resets.
- Frankfurt-Hamburg Corridor:Industrial meat processors and ingredient distributors cluster along German trade routes, creating dense procurement networks that reduce logistics friction for liquid smoke deliveries.
Market Restraints
- Hardwood Feedstock Volatility:Hickory and mesquite supply concentrates in North American timber regions, exposing European pyrolysis operators to currency and freight cost swings.
- EFSA Evaluation Protocols:Primary condensate safety assessments under EU food improvement agent frameworks create approval delays that freeze formulation pipelines for 18-24 month cycles.
- Natural Smoking Substitution:Premium charcuterie specialists in Italy and Spain maintain traditional smoking chambers as heritage positioning, capping penetration in high-margin artisan segments.
Strategic Opportunities
- India BIS Standards Evolution:Emerging food additive classifications create first-mover advantages for suppliers establishing analytical protocols ahead of formalized smoke flavoring categories.
- Clean-Label Color-Flavor Convergence:Sodium reduction mandates are forcing processed meat brands to seek single-ingredient solutions that deliver both visual browning and taste without artificial additive declarations.
- Modular Kit Distribution:Direct-to-processor concentrate dosing systems bypass traditional ingredient distributors, capturing margin pools in mid-size meat processing operations.
Industry Challenges
- Pyrolysis Engineering Talent Scarcity:Controlled thermal degradation of hardwoods requires specialized chemical engineering expertise that concentrates among aging specialists in German and American industrial regions.
- Multi-Jurisdiction Compliance Parallelism:Suppliers must maintain simultaneous GRAS notification pathways with FDA, REACH dossiers with ECHA, and evolving BIS documentation, straining regulatory affairs bandwidth.
- Legacy Smokehouse Integration:Processors retaining hybrid operations face workflow friction between traditional chamber batches and liquid injection lines, complicating production scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoke Flavorings Market |
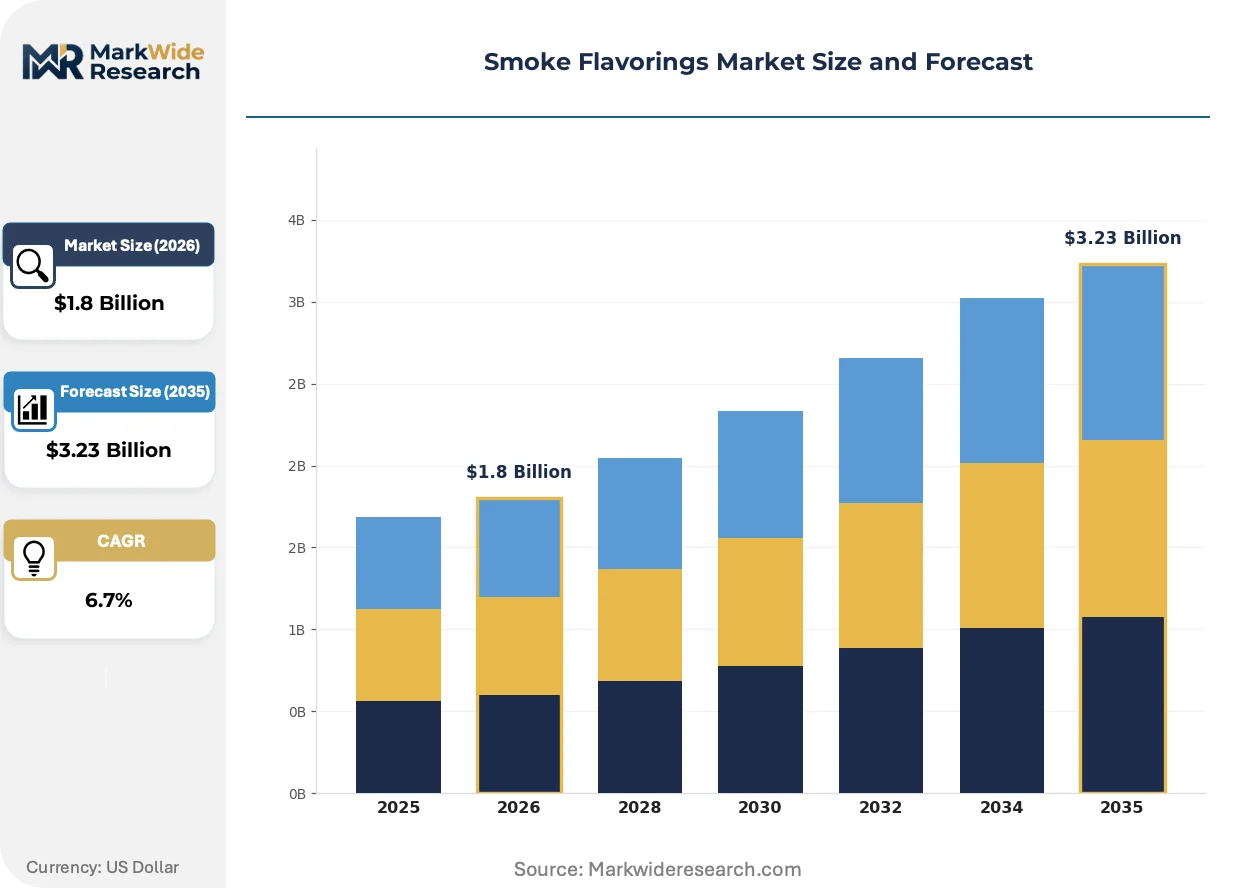
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Smoke, Smoked Salt, Smoke Powder, Smoked Oils Application: Meat Processing, Snack Foods, Sauces, Dairy Products Form: Granules, Liquid, Paste, Concentrates End User: Food Manufacturers, Restaurants, Catering Services, Retail Consumers |
| Companies Covered | Besmoke Ltd, Symrise AG, Kerry Group, Redbrook Ingredients, QST Smoke Flavors, International Flavors & Fragrances Inc., Sensient Technologies Corporation, Frutarom Industries Ltd., Azelis Holding S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoke Flavorings Market Evolving Landscape
Smoke flavoring technology is bifurcating between precision-dosed liquid systems for industrial scale and heritage-positioned hardwood extracts for premium positioning. Regulatory chemistry requirements and clean-label formulation pressures are accelerating this divergence.
Continuous-flow pyrolysis reactors with real-time condensate fractionation are electrifying production economics for liquid smoke manufacturers. Mid-size meat processors in Poland and the Czech Republic are adopting these systems at 18-month replacement cycles. The technology is electrifying capacity utilization rates while compressing batch-to-batch variability that previously required extensive post-processing refinement.
EFSA's ongoing reassessment of primary condensate toxicity under EU food improvement agent frameworks is forcing reformulation investments across European supply chains. Manufacturers are submitting new analytical datasets on carbonyl and phenolic compound profiles to preempt restrictive maximum-level settings. Processed meat categories in Germany and France are most exposed, with several brands accelerating natural smoke powder trials to hedge against potential liquid format constraints.
Buyer consolidation among European meat processing cooperatives is concentrating procurement leverage and demanding outcome-based flavor consistency guarantees rather than ingredient specifications alone. Distributor margins are compressing as direct technical service relationships between pyrolysis specialists and processor quality departments displace traditional broker roles. This pattern is most visible in the Netherlands and Belgium, where cooperative slaughterhouse networks negotiate centralized smoke flavoring contracts covering multiple processing facilities.
Smoke Flavorings Market Segmentation
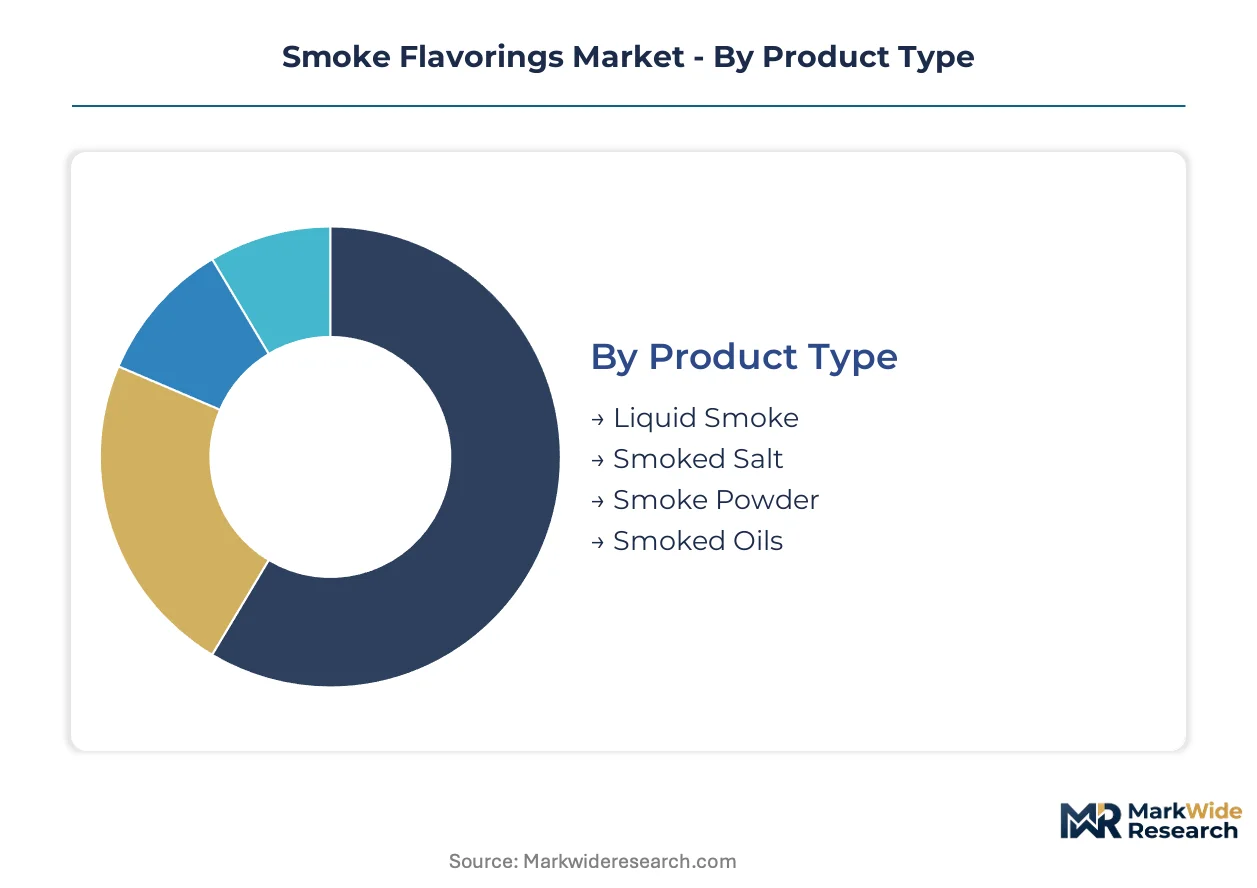
Smoke flavoring procurement patterns diverge sharply between industrial scale operations seeking dosing precision and artisan producers prioritizing heritage positioning. Understanding these segment boundaries clarifies where formulation investments concentrate and which supply formats command pricing power.
Product Type:
Industrial buyers distinguish formats primarily by dosing control and shelf stability requirements rather than flavor intensity alone.
- Liquid Smoke:Water-soluble pyroligneous acid condensates standardized for brine injection and marinade systems. German meat processors along the Frankfurt-Hamburg corridor absorb the largest volumes as they abandon captive smokehouse infrastructure for capital-light alternatives.
- Smoke Powder:Spray-dried or encapsulated smoke condensates optimized for dry rubs and seasoning blends where water activity constraints matter. Snack food extrusion lines in Poland and the Czech Republic are expanding procurement as clean-label savory profiles displace artificial flavor systems.
- Smoked Salt:Crystalline carriers infused with hardwood smoke condensates for surface application and finishing. Premium charcuterie specialists in Italy and Spain favor this format for heritage positioning.
- Smoked Oils:Lipid-based smoke carriers suited for cold-process applications and emulsion stability. Niche demand concentrates among sauce manufacturers seeking fat-compatible flavor delivery.
Liquid smoke leads volumes today; smoke powder is gaining share fastest.
Application:
End-use concentration determines whether buyers prioritize throughput efficiency or label claim simplicity.
- Meat Processing:Structural demand anchor encompassing processed meats, bacon, ham, and sausage production. EFSA evaluation protocols for primary condensates are forcing reformulation investments across German and French processing lines.
- Snack Foods:Kettle-cooked chips, extruded puffs, and savory crackers absorbing smoke powder for clean-label positioning. Retail shelf resets in the Netherlands and Belgium are accelerating format adoption.
- Sauces:Barbecue, marinade, and condiment applications requiring heat-stable smoke flavor systems. Manufacturers navigate dual compliance with FDA GRAS pathways and REACH dossier requirements.
- Dairy Products:Smoked cheese and specialty butter segments where subtle flavor intensity differentiates premium positioning. Artisan producers in Alpine regions maintain traditional cold-smoking chambers.
Meat processing anchors absolute demand; snack foods show the steepest expansion trajectory.
Form:
Physical state dictates equipment compatibility and integration complexity within existing production lines.
- Liquid:Pourable condensates and diluted solutions for injection, tumbling, and spraying systems. Dominates industrial procurement due to metering precision and batch consistency.
- Concentrates:High-potency smoke extracts requiring precise dilution protocols. Mid-size processors in Central Europe are adopting modular dosing kits to bypass distributor markups.
- Granules:Free-flowing particulate formats for dry blending operations. Seasoning compounders favor this form for uniform distribution in spice mixtures.
- Paste:Viscous smoke preparations for surface application and manual processing. Limited to small-batch artisan operations with hybrid traditional-modern workflows.
Liquid forms dominate industrial procurement; concentrates are climbing the fastest as dosing technology spreads.
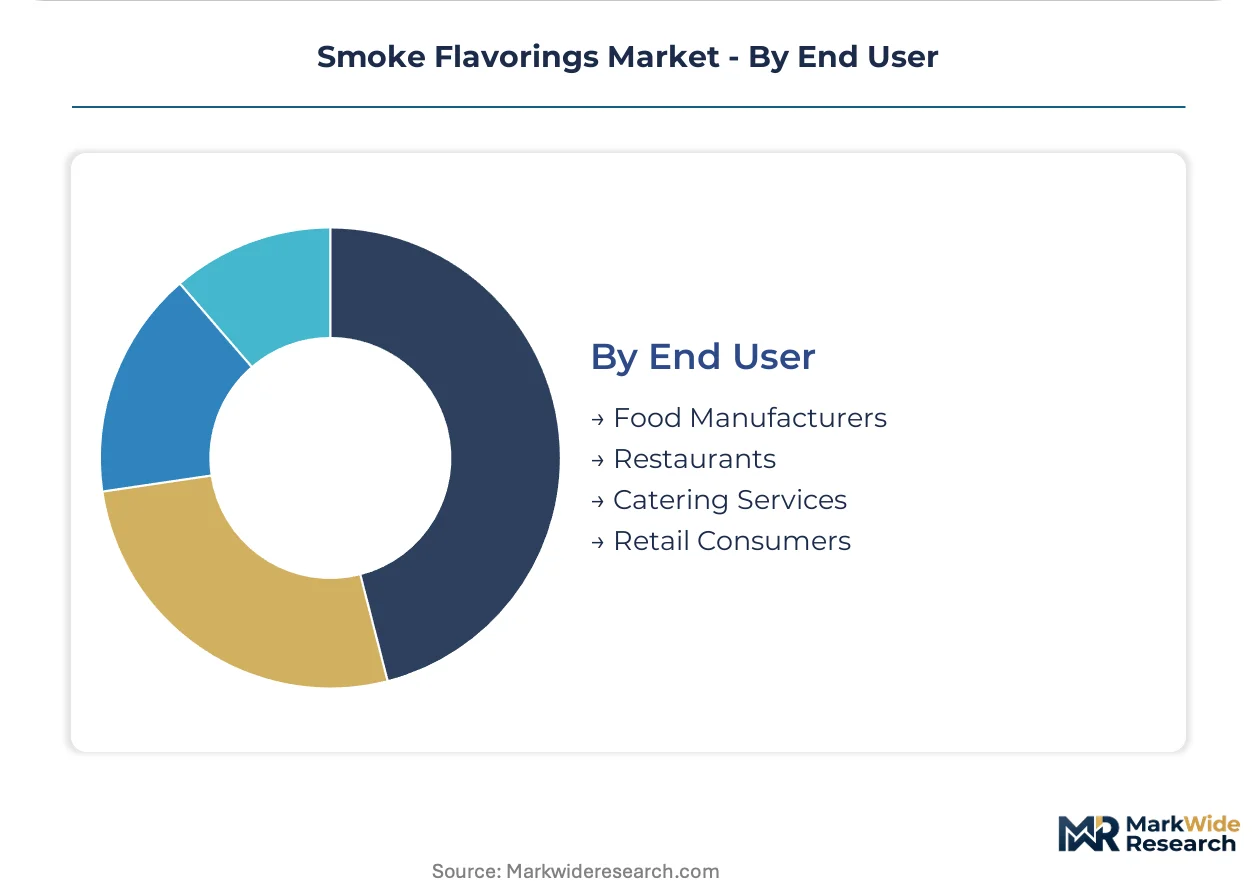
End User:
Customer scale and technical capability determine whether suppliers sell ingredients alone or bundled technical service relationships.
- Food Manufacturers:Industrial processors with quality departments demanding outcome-based flavor consistency guarantees. Cooperative slaughterhouse networks in the Netherlands negotiate centralized contracts covering multiple facilities.
- Restaurants:Commercial kitchens seeking speed-scratch solutions without smokehouse investment. Urban foodservice clusters in Hamburg and Frankfurt drive regional demand concentration.
- Catering Services:High-volume prepared food operations requiring standardized flavor profiles across distributed production sites. Procurement emphasizes shelf-stable formats and simplified storage.
- Retail Consumers:Home cooks purchasing small-format liquid smoke and smoked salts through specialty retailers. Premium hardwood positioning drives margin capture in this channel.
Food manufacturers command the largest procurement volumes; restaurants represent the most rapidly expanding customer segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smoke flavoring production originated in German industrial zones during the post-war standardization of processed meat manufacturing, with pyrolysis engineering expertise concentrating in the Rhine-Ruhr corridor before spreading to North American timber regions and Asian processing hubs.
Germany
Meat processing cooperatives along the Frankfurt-Hamburg corridor drive concentrated procurement of liquid smoke formats as facilities abandon captive smokehouse infrastructure. ECHA's REACH framework enforces stringent purity benchmarks for pyroligneous acid derivatives, disqualifying uncertified suppliers. Industrial clusters in Lower Saxony and Hesse host the densest networks of pyrolysis specialists serving continental European charcuterie demand.
United States
Hickory and mesquite hardwood feedstock availability supports large-scale pyrolysis operations supplying processed meat and snack food manufacturers. FDA GRAS notification pathways shape formulation choices for domestic producers and exporters to regulated markets. Kentucky and Tennessee timber regions anchor hardwood supply chains feeding Midwestern meat processing centers around Chicago and St. Louis.
France
EFSA evaluation protocols for primary condensate safety create regulatory exposure for processed meat brands dependent on liquid smoke systems. Sodium reduction mandates accelerate demand for clean-label color-flavor combinations that reduce artificial additive declarations. Charcuterie specialists in the Auvergne-Rhône-Alpes region maintain hybrid operations blending traditional chamber smoking with concentrated liquid formats.
India
Emerging BIS standards for food additive classifications create compliance preparation windows for suppliers establishing analytical protocols ahead of formalized smoke flavoring categories. Processed meat and savory snack manufacturing expansion in Maharashtra and Gujarat drives format experimentation. Mumbai-Pune industrial corridors attract technical service relationships from multinational ingredient distributors seeking first-mover positioning.
Poland
Mid-size meat processors adopt continuous-flow pyrolysis reactors with 18-month replacement cycles, electrifying capacity utilization while compressing batch variability. EU food improvement agent frameworks govern cross-border trade with German and Dutch cooperative networks. The Łódź and Wrocław manufacturing basins concentrate snack food extrusion lines absorbing smoke powder volumes for clean-label savory profiles.
Smoke Flavorings Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and technical service bundling. The vendor base organizes into three tiers: integrated taste-and-nutrition platforms with multi-ingredient bundling power, specialized hardwood pyrolysis operators with heritage positioning, and regional distributors facing margin compression from direct-to-processor concentrate systems. Consolidation accelerates among pyrolysis specialists as REACH compliance costs rise, while cooperative procurement networks in Northern Europe concentrate buyer leverage against fragmented supplier bases.
Within the heritage-positioned specialist tier, Besmoke Ltd represents British hardwood-derived extract positioning for European charcuterie channels. Kerry Group anchors integrated platform supply through bundled taste and nutrition systems. Sensient Technologies Corporation exemplifies clean-label color-flavor convergence strategies targeting sodium reduction and artificial additive restrictions. These three occupy distinct competitive vectors—regional heritage, global scale integration, and regulatory-driven formulation innovation—rather than direct segment overlap.
| Leading Market Players |
|---|
| Besmoke Ltd |
| Symrise AG |
| Kerry Group |
| Redbrook Ingredients |
| QST Smoke Flavors |
| International Flavors & Fragrances Inc. |
| Sensient Technologies Corporation |
| Frutarom Industries Ltd. |
| Azelis Holding S.A. |
| Others |
Value Network & Pricing Analysis
Family-owned hardwood pyrolysis specialists in Germany's Rhine-Ruhr corridor anchor supply discipline through generational capital structures that resist short-term margin compression, translating feedstock volatility into stable contract pricing for REACH-certified liquid smoke formats while absorbing currency swings via long-term hickory offtake agreements with Kentucky timber operators.
Pricing Analysis
Three-tier pricing structure across premium hardwood extracts, standard pyroligneous acid condensates, and economy blended formats dominates procurement contracts. Price differentiation rests on REACH certification depth and EFSA dossier completeness rather than flavor intensity alone. Pricing pressure stems from cooperative buyer consolidation in the Netherlands and Belgium demanding outcome-based guarantees. Mid-size meat processors in Central Europe exhibit highest price sensitivity as they abandon captive smokehouses, while premium charcuterie specialists in Italy accept heritage-positioned premiums.
Supply Chain Analysis
Hub-and-spoke distribution patterns radiate from Frankfurt and Hamburg trade corridors, with regional distribution centers in Lower Saxony serving continental European processors. Geographic supply concentrates in Germany, the United States, and Poland. Raw material dependencies include hickory and mesquite hardwood feedstocks, filtration membranes for condensate refinement, and food-grade dilution carriers. Single-source vulnerability runs through North American timber regions feeding European pyrolysis operators. Distribution runs through direct technical service relationships displacing traditional ingredient brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smoke flavoring procurement offers geographic-arbitrage potential between REACH-regulated European markets with tightening purity benchmarks and emerging Indian markets where BIS standards remain in formulation, letting suppliers deploy identical pyrolysis capacity against divergent compliance cost structures.
For Market Incumbents: Deepen backward integration into hardwood feedstock sourcing through long-term Kentucky and Tennessee timber agreements to insulate margins from currency volatility. Fortify EFSA dossier investments ahead of primary condensate toxicity reassessments that threaten liquid format viability in German and French processing lines. Capture cooperative procurement leverage in the Netherlands through centralized technical service contracts covering multiple slaughterhouse facilities. For New Entrants and Emerging Players: BIS standards evolution in India opens a window for first-mover analytical protocol establishment ahead of formalized smoke flavoring categories. Target Maharashtra and Gujarat processed meat expansion with modular concentrate dosing kits that bypass distributor markups. Penetrate Poland's snack food extrusion segment through smoke powder formats optimized for clean-label savory profiles displacing artificial systems. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap hardwood pyrolysis specialists lacking REACH certification depth but possessing technical engineering talent in aging German industrial regions. Long-term viability hinges on regulatory compliance parallelism capabilities across FDA GRAS, ECHA REACH, and evolving Asian frameworks. Watch EFSA maximum-level settings on carbonyl compounds as the decisive inflection signal for liquid smoke format economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hardwood Feedstock | Captive hickory and mesquite supply from Kentucky timber regions insulates European pyrolysis operators from currency volatility. |
| REACH Certification Investment | ECHA dossier completeness disqualifies artisanal competitors and concentrates demand among certified industrial producers. |
| Modular Concentrate Dosing Systems | Direct-to-processor distribution bypasses traditional brokers and captures margin pools in mid-size Central European meat operations. |
| Clean-Label Color-Flavor Convergence | Single-ingredient solutions address sodium reduction mandates in French and German processed meat categories. |
| Continuous-Flow Pyrolysis Reactor Deployment | Real-time condensate fractionation electrifies capacity utilization rates for Polish and Czech Republic processors. |
Research Methodology
Direct dialogue with pyrolysis engineering specialists, procurement leads at German meat processing cooperatives, regulatory affairs directors navigating EFSA evaluation protocols, and quality managers at Netherlands cooperative slaughterhouse networks grounded qualitative insights. Secondary validation drew from ECHA REACH dossier filings, FDA GRAS notification databases, BIS draft standard consultations, and customs trade data on hardwood-derived food additive imports. Bottom-up facility capacity assessments and top-down category consumption models triangulated market sizing.
Segment-level value and volume trajectories across the projection horizon reflect disaggregated modeling of liquid smoke, smoke powder, smoked salt, and smoked oil formats by meat processing, snack food, sauce, and dairy applications. CAGRs derive from regression analysis against protein processing output indices, clean-label shelf space expansion rates, and regulatory approval cycle durations. Industry-specific forecast inputs include EFSA primary condensate reassessment timelines and continuous-flow pyrolysis adoption curves in Central Europe.
Revisions become necessary when EFSA maximum-level settings materialize, when BIS finalizes formal smoke flavoring categories ahead of expected windows, or when hardwood feedstock trade flows reorient due to tariff restructuring. Forecasts reflect documented assumptions on regulatory parallelism costs and technology replacement cycles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Caralluma Extract Market
Flavorings and Food Additives
Licorice Extract Market
Flavorings and Food Additives
North America Vanilla and Vanillin Market
Flavorings and Food Additives
Global Paprika Oleoresin Market
Flavorings and Food Additives
Annatto Extract Market
Flavorings and Food Additives
Orange Extract Market
Flavorings and Food Additives
Smoked Condensates Market
Flavorings and Food Additives
Betanin Food Color Market
Flavorings and Food Additives
Maple Extracts Market
Flavorings and Food Additives
All-Natural Flavors System Market
Flavorings and Food Additives
Flavoring Agents Market
Flavorings and Food Additives
Browning Solutions Market
Flavorings and Food Additives
Natural Berry Flavor Market
Flavorings and Food Additives
Vanilla Oleoresin Market
Flavorings and Food Additives
Sea Urchin and Roe Flavor Ingredients Market
Flavorings and Food Additives
Orange Peel Extract Market