
 Pesticide Adjuvant Market | 2026-2036
Pesticide Adjuvant Market Size, Share, and Industry Trends Forecast 2026-2036
Pesticide Adjuvant Market Outlook
Brazil is fragmenting its pesticide adjuvant supply base as domestic formulators expand amid import substitution policies. BASF SE leverages its integrated surfactant-solvent portfolio to anchor pricing power across Latin American distribution channels. Croda International Plc specializes in bio-based adjuvant chemistry, differentiating its offer through sustainability certifications that command premium positioning in European procurement tenders.
Pesticide adjuvants are formulation additives—typically surfactants, oils, or stabilizers blended at 0.1–5% v/v—that modify spray droplet dynamics, enhance active ingredient penetration through cuticular waxes, or reduce hydrolytic degradation in tank mixes. Their primary commercial purpose is restoring or extending herbicide efficacy against resistant weed biotypes where standalone actives fail to achieve lethal uptake. Surfactants occupy the largest volume share due to universal compatibility with glyphosate and dicamba formulations, while oils represent the fastest-expanding margin pool as high-oleic methylated seed oils displace petroleum distillates in drift-reduction programs. Agricultural applications dominate value capture, though horticultural segments sustain higher per-hectare adjuvant intensity through precision greenhouse spraying systems.
The EPA regulates adjuvant compositions through 40 CFR pesticide tolerance exemptions and drift labeling requirements, while REACH in Europe mandates full surfactant toxicity dossiers for market access. Brazil's national environmental regulator enforces ANVISA-aligned residue limits that shape import formulations for soybean and corn export compliance. Stakeholders must monitor evolving buffer zone calculations and bio-based content thresholds that will determine which adjuvant chemistries retain formulary access across major agricultural economies.
Market Dynamics
Herbicide resistance proliferation across major row-crop geographies is forcing adjuvant chemistry to evolve from simple tank-mix additives to precision efficacy-restoration tools, with spray drift mitigation rules simultaneously compressing formulation flexibility.
Growth Catalysts
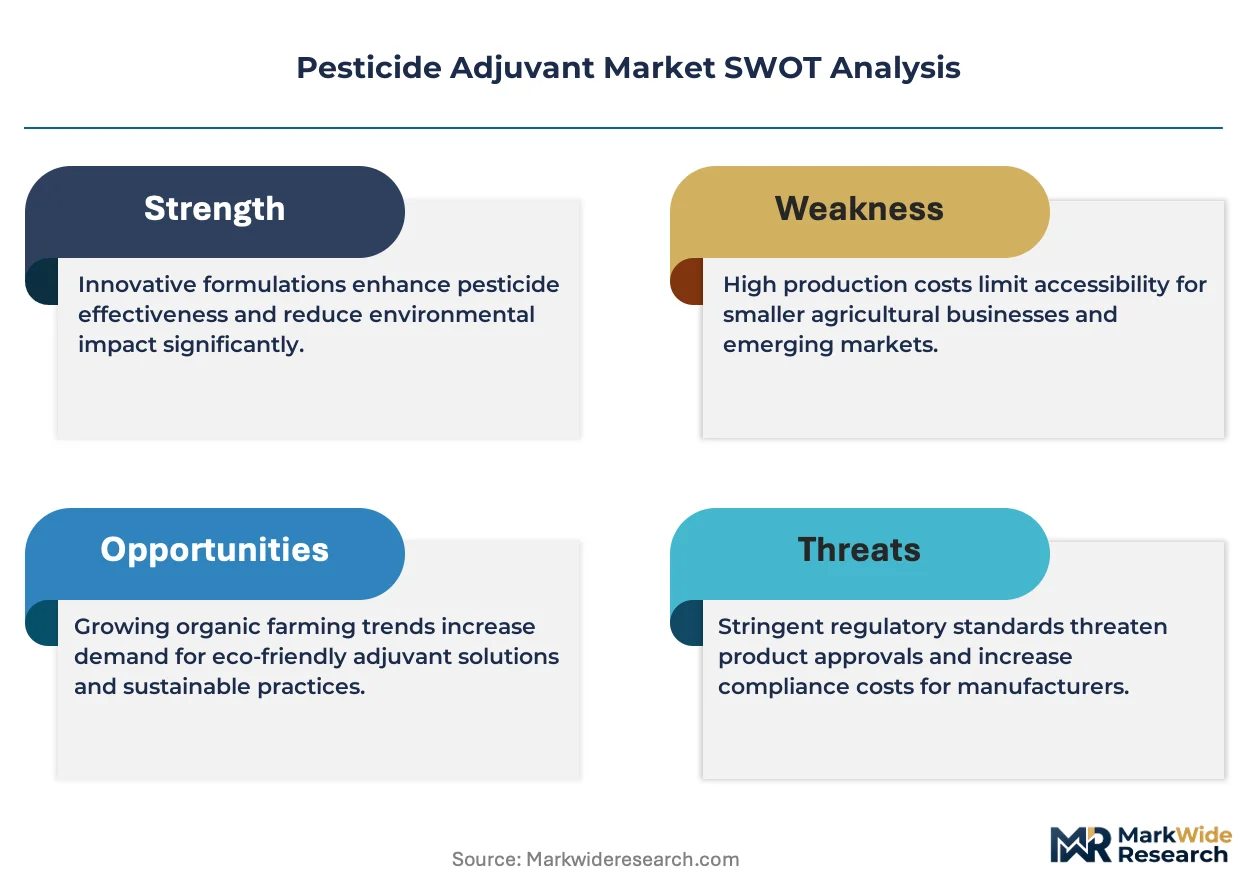
- EPA 2024 Spray Drift Rules:Tighter buffer zone mandates for organosilicone surfactants are accelerating demand for compliant methylated seed oil replacements in aerial application fleets.
- Brazil Import Substitution:Domestic formulator expansion under industrial policy incentives is localizing adjuvant production for Mato Grosso soybean belt procurement.
- Glyphosate Resistance Pressure:Weed biotype proliferation in California specialty crops is expanding surfactant blending rates to restore lethal uptake where standalone herbicides fail.
Market Restraints
- Petroleum Distillate Input Volatility:Crude-linked feedstock costs for mineral oil carriers create margin compression for formulators lacking bio-based substitution pathways.
- REACH Dossier Burden:Full surfactant toxicity documentation requirements in Europe impose fixed compliance costs that disadvantage smaller specialty chemical entrants.
- Technical Compatibility Limits:Cationic surfactant incompatibility with certain dicamba salts restricts formulation flexibility in resistant weed management programs.
Strategic Opportunities
- ANVISA-Aligned Export Formulations:Residue limit harmonization for Brazilian soybean and corn exports creates specification premiums for adjuvants pre-certified to dual US-Brazil standards.
- Greenhouse Precision Systems:Per-hectare adjuvant intensity in horticultural segments exceeds field crops, offering margin expansion through closed-loop recirculating sprayer integration.
- EU Green Deal Bio-Based Thresholds:Mandatory renewable content benchmarks in European procurement tenders reward Croda-type sustainability-certified chemistry with preferential formulary access.
Industry Challenges
- Spray Application Specialist Shortage:Certified aerial applicator capacity constraints in Brazil's expanding soybean belt limit optimal adjuvant deployment timing.
- Tank-Mix Stability Certification Delays:Hydrolytic degradation testing protocols for novel adjuvant-active combinations extend product launch timelines by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pesticide Adjuvant Market |
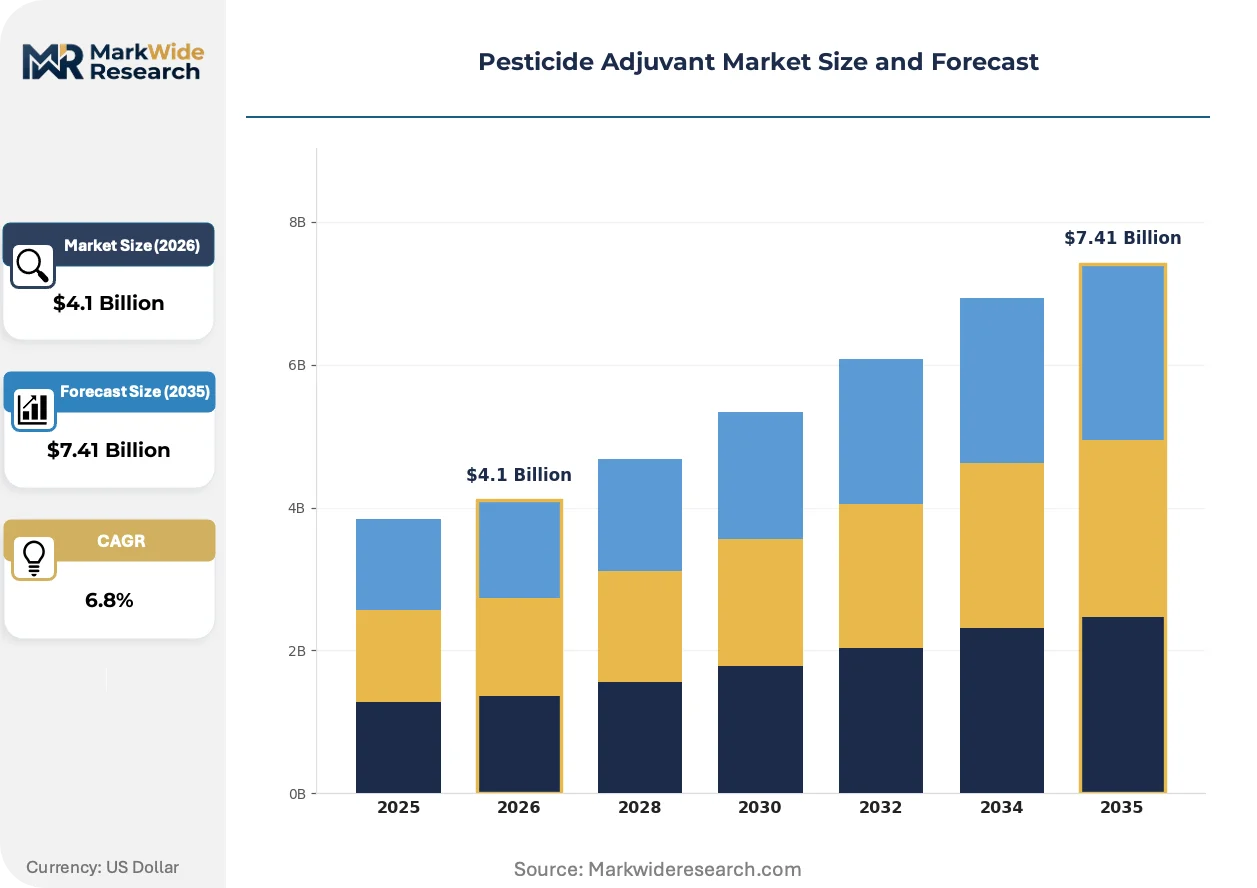
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surfactants, Oils, Acids, Stabilizers Application: Agricultural, Horticultural, Turf, Forestry End User: Farmers, Agricultural Co-ops, Distributors, Retailers Packaging Type: Bulk, Sachets, Containers, Bottles |
| Companies Covered | BASF SE, Corteva Agriscience, Croda International Plc, Evonik Industries AG, Stepan Company, Solvay S.A., Clariant International Ltd., Huntsman Corporation, Nufarm Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pesticide Adjuvant Market Strategic Shifts
Formulation science is converging with precision agriculture hardware to enable real-time adjuvant dosing adjustments, while regulatory pressure on volatile organic compounds and drift potential is compressing permissible chemistry sets.
High-oleic methylated seed oils are penetrating drift-reduction programs through superior droplet retention and reduced volatility compared to petroleum carriers. Aerial applicators in Brazil and US Midwest row-crop zones are adopting these bio-based oils at accelerating rates. The technology is hybridizing conventional surfactant and oil adjuvant categories into single-tank solutions that simplify procurement while meeting tightening EPA buffer requirements.
REACH mandates in Europe now require complete surfactant toxicity dossiers including endocrine disruption screening for market access authorization. Industrial consequence includes elevated fixed compliance costs that consolidate competitive position among integrated multinationals with dedicated regulatory affairs infrastructure. Specialty crop segments in Southern Europe face delayed access to novel adjuvant chemistries as dossier preparation timelines extend.
Buying committees at major Brazilian grain cooperatives are consolidating adjuvant procurement through multi-year framework agreements with domestic formulators. Traditional distributor networks face disintermediation pressure as direct manufacturer relationships offer volume pricing and technical support integration. This pattern is most visible in Mato Grosso and Goias states where soybean production scale justifies dedicated supply contracts.
Pesticide Adjuvant Market Segmentation
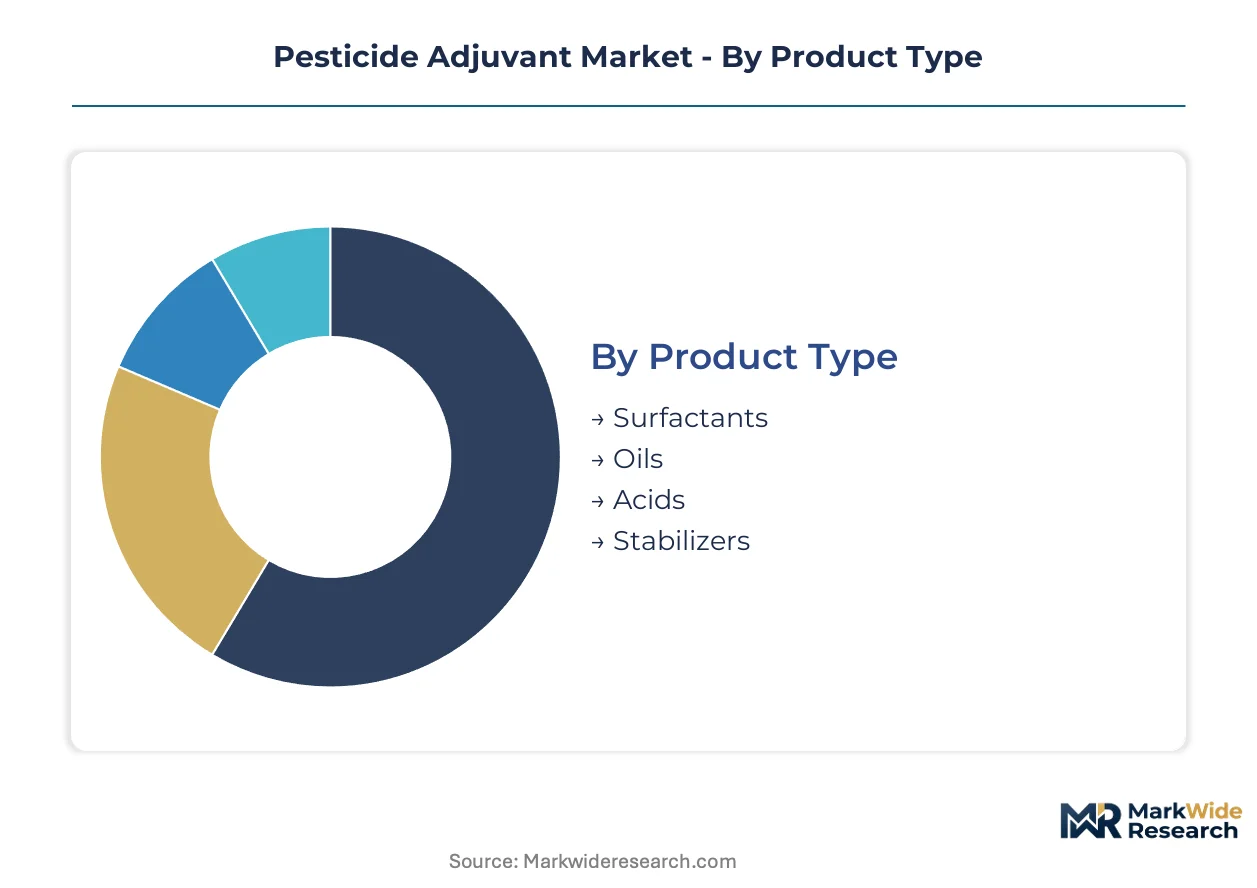
Adjuvant segmentation reveals how formulation chemistry, application method, and procurement channel intersect to determine margin capture. Each dimension shapes competitive positioning differently across row-crop versus specialty agriculture contexts.
Product Type:
The use-case spectrum spans from universal tank-mix compatibility to drift-mitigation specialization, with chemistry selection driven by herbicide mode-of-action and regulatory buffer constraints.
- Surfactants:Non-ionic and organosilicone chemistries modify droplet surface tension to enhance cuticular penetration. Demand concentrates in California specialty crop zones where glyphosate-resistant weeds force elevated blending rates to restore lethal uptake.
- Oils:High-oleic methylated seed oils and petroleum distillates reduce droplet evaporation and improve retention on waxy leaf surfaces. Brazil's Mato Grosso aerial application fleets are displacing mineral carriers with bio-based alternatives under tightening EPA drift rules.
- Acids:pH buffering agents and acidifiers prevent hydrolytic degradation of organophosphate and carbamate actives in alkaline water sources.
- Stabilizers:Compatibility agents and anti-foam compounds extend tank-mix shelf life and prevent nozzle clogging in recirculating spray systems.
The dominant share belongs to Surfactants, while Oils is closing the gap fastest.
Application:
Volume intensity varies dramatically between broad-acre mechanized spraying and precision-controlled environments, creating distinct margin profiles.
- Agricultural:Row-crop and broad-acre cereal production consumes adjuvants at scale through ground and aerial equipment. Brazil's soybean belt and US Midwest corn-soy rotations anchor procurement volumes.
- Horticultural:Greenhouse and protected-culture systems achieve per-hectare adjuvant intensity multiples above field crops through closed-loop recirculating sprayers and precision dosing.
- Turf:Golf course and sports field maintenance drives seasonal demand for aesthetic-quality spray applications with low-phytotoxicity requirements.
- Forestry:Aerial and helicopter-based conifer release treatments require specialized drift-reduction formulations for sensitive watershed proximity.
Agricultural commands the volume base, though Horticulture achieves the steepest margin per treated hectare.
End User:
Procurement authority is shifting from fragmented retail channels toward consolidated direct manufacturer relationships.
- Farmers:Owner-operators below 500 hectares typically purchase through distributor networks with limited technical support.
- Agricultural Co-ops:Brazilian grain cooperatives in Mato Grosso and Goias are consolidating procurement through multi-year framework agreements that disintermediate traditional distributors.
- Distributors:Regional chemical wholesalers face margin compression as manufacturers build direct technical service relationships with large-scale end users.
- Retailers:Farm supply stores and input retailers serve smallholder segments with pre-packaged adjuvant-herbicide bundles.
Agricultural Co-ops are capturing procurement authority fastest, while Distributors defend position through service bundling.
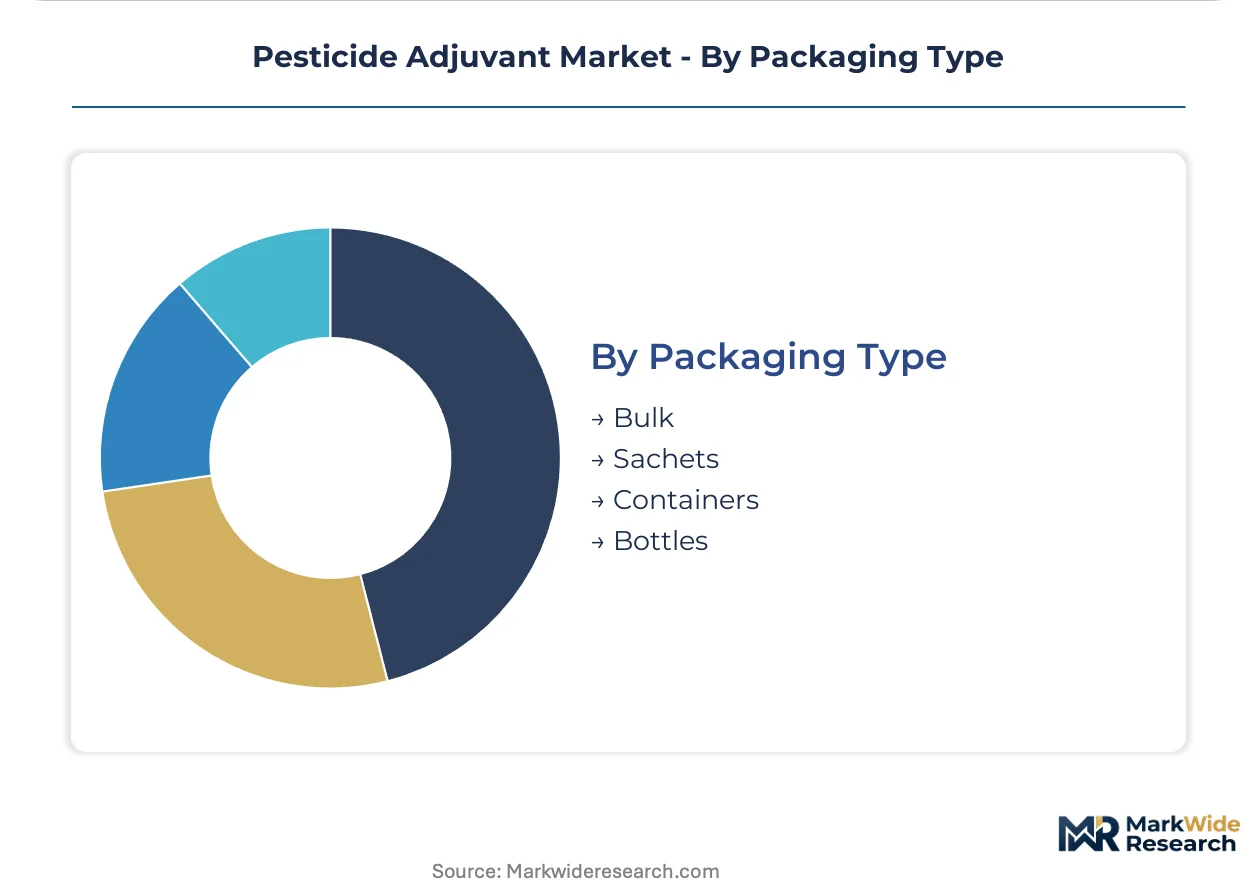
Packaging Type:
Packaging configuration follows application scale and logistics infrastructure density.
- Bulk:Tanker and tote deliveries serve aerial applicator fleets and cooperative blending facilities with dedicated storage infrastructure.
- Sachets:Single-use water-soluble packets eliminate measuring error for smallholder farmers without calibrated mixing equipment.
- Containers:Intermediate bulk sizes dominate commercial farming operations with on-farm chemical handling systems.
- Bottles:Retail-sized packaging serves hobby farmers and specialty turf maintenance contractors.
Bulk captures the volume leadership, while Sachets expand most quickly in emerging market smallholder segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil deploys adjuvants predominantly through aerial application fleets for bulk soybean treatment, while California specialty crop zones demand precision surfactant blending at elevated rates for herbicide-resistant weed management. This consumption-mix differential shapes regional formulation requirements and procurement channel structures.
United States
California's Central Valley specialty crop producers drive surfactant intensity for glyphosate efficacy restoration against resistant weed biotypes. EPA's 2024 updated spray drift mitigation rules tighten buffer zone requirements for organosilicone adjuvants, accelerating methylated seed oil substitution. Midwest corn-soy rotations anchor ground-application volumes through Illinois and Iowa cooperative networks.
Brazil
Mato Grosso soybean belt aerial application volumes concentrate bulk oil adjuvant procurement through domestic formulator expansion under import substitution policies. ANVISA-aligned residue limits shape export formulations for soybean and corn compliance with dual US-Brazil standards. São Paulo-based chemical clusters localize production for cooperative framework agreements displacing traditional distributor channels.
Germany
REACH mandates require complete surfactant toxicity dossiers including endocrine disruption screening for European market access authorization. Industrial consolidation favors integrated multinationals with dedicated regulatory affairs infrastructure over smaller specialty entrants. Rhine-Ruhr chemical manufacturing clusters supply formulation additives across EU procurement tenders with bio-based content thresholds.
China
Domestic glyphosate production integration creates captive adjuvant demand for export-oriented herbicide formulations. National environmental regulator enforcement of GB standards and dual carbon goals pressures petroleum distillate displacement toward bio-based carrier oils. Yangtze River Delta chemical parks concentrate surfactant manufacturing capacity for Asia-Pacific agricultural export markets.
India
Smallholder cotton and rice production segments drive sachet-packaged adjuvant penetration for farmers lacking calibrated mixing equipment. Central Insecticides Board registration requirements extend product launch timelines for novel adjuvant-active combinations. Maharashtra and Gujarat agrochemical formulators expand domestic blending capacity under PLI scheme incentives for import substitution.
Pesticide Adjuvant Market Competitive Environment
Capability concentration sits with integrated multinational chemical groups possessing dedicated regulatory dossier infrastructure; scale advantage sits with regional formulators capturing cooperative procurement consolidation in high-volume agricultural belts. The vendor base separates into three tiers: global surfactant-solvent integrators, bio-based specialty chemistry specialists, and domestic formulators serving localized aerial application fleets. Dominant competitive moves include backward integration into high-oleic methylated seed oil feedstocks and multi-year framework agreement capture with Brazilian grain cooperatives.
Within the integrated chemical tier, BASF SE anchors positioning through combined surfactant-solvent portfolio breadth across Latin American distribution channels. Croda International Plc exemplifies the sustainability-certified specialty archetype, occupying preferential formulary access in European procurement tenders with bio-based chemistry credentials. Evonik Industries AG represents the industrial-scale surfactant manufacturing position, sitting within regulatory compliance leadership for REACH dossier completeness.
| Leading Market Players |
|---|
| BASF SE |
| Corteva Agriscience |
| Croda International Plc |
| Evonik Industries AG |
| Stepan Company |
| Solvay S.A. |
| Clariant International Ltd. |
| Huntsman Corporation |
| Nufarm Limited |
| Others |
Value Chain & Pricing Dynamics
Petroleum distillate input volatility determines both pricing tier spreads and supply chain shape across the pesticide adjuvant market. Crude-linked feedstock costs for mineral oil carriers compress margins for formulators lacking bio-based substitution pathways, while high-oleic methylated seed oil premiums widen price differentiation between petroleum-dependent and sustainability-certified tiers.
Pricing Analysis
Brazilian Mato Grosso procurement runs 15-20% below California specialty crop pricing due to bulk aerial application volumes and cooperative framework agreements. Three-tier pricing structure across premium, standard, and economy levels separates ANVISA-aligned export formulations from domestic-only grades and uncertified commodity surfactants. Cost compression in petroleum-based tiers is intensifying because bio-based substitution accelerates under EPA drift rule tightening. Smallholder farmers in India exhibit highest price sensitivity due to sachet-packaged purchasing patterns, while European greenhouse operators show lowest sensitivity through sustainability-certified premium acceptance.
Supply Chain Analysis
Export-control alignment on surfactant precursor chemicals limits technology flows between Rhine-Ruhr chemical clusters and emerging market formulators. Manufacturing concentrates in Germany, China, and Brazil, with feedstock supply drawing from high-oleic soybean crush in Mato Grosso and petroleum distillate refining in Rotterdam-Antwerp hubs. Single-source vulnerability sits with organosilicone surfactant intermediates concentrated in Yangtze River Delta facilities. Distribution runs through Brazilian grain cooperative direct contracts displacing traditional distributor networks, with bulk tanker deliveries dominating Mato Grosso aerial fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against high-oleic methylated seed oils displacing petroleum distillates in drift-reduction programs. Incumbents must navigate bio-based chemistry certification requirements that reshape competitive positioning.
For Market Incumbents: Entrench regulatory dossier capabilities ahead of REACH endocrine disruption screening expansion. Backward integration into high-oleic methylated seed oil feedstocks secures margin control against petroleum volatility. Capture multi-year framework agreements with Brazilian grain cooperatives before domestic formulators consolidate procurement authority.
For New Entrants and Emerging Players: India's smallholder cotton and rice segments offer lowest competitive density for sachet-packaged adjuvant penetration. Precision greenhouse systems in Southern Europe present premium pricing acceptance without incumbent regulatory infrastructure requirements. Partner with Maharashtra and Gujarat agrochemical formulators expanding under PLI scheme incentives for import substitution.
For Investors and Strategic Acquirers: EPA's 2024 spray drift rule implementation reshapes the acquisition landscape toward bio-based chemistry capabilities. Long-term viability centers on formulators with ANVISA-aligned dual-certification infrastructure serving Brazilian soybean export channels. Watch ANVISA residue limit harmonization announcements as inflection indicators for specification premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Oleic Feedstocks | Captive methylated seed oil supply insulates margins from petroleum volatility in Brazil's Mato Grosso belt. |
| ANVISA-Aligned Dual Certification Investment | Pre-certified adjuvants command specification premiums for US-Brazil soybean export compliance. |
| Greenhouse Precision System Partnership | Closed-loop recirculating sprayer integration captures per-hectare intensity multiples above field crops. |
| Domestic Formulator Capacity Expansion | São Paulo chemical clusters localize production for cooperative framework agreement capture. |
| REACH Dossier Completeness Infrastructure | Endocrine disruption screening capabilities secure European market access against smaller specialty entrants. |
Study Parameters
Desk research of customs trade data, EPA 40 CFR tolerance filings, and ANVISA residue limit publications preceded structured interviews with surfactant plant managers, Brazilian grain cooperative procurement directors, aerial applicator fleet operators, and European regulatory affairs leads. Primary fieldwork combined with secondary validation through SEC chemical company filings, REACH dossier databases, and Brazilian industrial policy announcements. Bottom-up volume modeling across application segments triangulated against top-down value estimates from trade flow analysis.
Fixed assumptions held regulatory enforcement intensity and crude oil price bands within observed ranges across the analysis window. Segmentation modeling spanned product chemistry tiers, application method intensity, and procurement channel concentration. CAGRs derived from volume trajectory analysis calibrated to aerial application fleet expansion in Brazil and surfactant blending rate escalation in California specialty crops. Forecast inputs incorporated glyphosate resistance biotype proliferation patterns and EPA buffer zone calculation methodologies.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by domestic Brazilian formulators would shift outcomes. Material shifts in ANVISA residue limit harmonization timelines or REACH endocrine disruption screening scope expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Global Agricultural Chelates Market
Agricultural Chemicals
Triazole Fungicides Market
Agricultural Chemicals
Europe Swine Feed Premix Market
Agricultural Chemicals
South America Feed Antioxidants Market
Agricultural Chemicals
Asia-Pacific Feed Antibiotics Market
Agricultural Chemicals
North America Feed Acidifiers Market
Agricultural Chemicals
United States Feed Enzymes Market
Agricultural Chemicals
Europe Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
South America Feed Enzymes Market
Agricultural Chemicals
Global Agricultural Disinfectant Market
Agricultural Chemicals
Artificial Humus Market
Agricultural Chemicals
Asia-Pacific Feed Additives Market
Agricultural Chemicals
South America Silage Additives Market
Agricultural Chemicals
Feed Binders Market
Agricultural Chemicals
Fungicides Market
Agricultural Chemicals
Mexico Feed Additives Market