
 Singapore Used Car Market | 2026-2036
Singapore Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Used Car Market Outlook
Japan's export pipeline of low-mileage used vehicles is narrowing as domestic retention rates rise and yen volatility complicates arbitrage. Precise Auto Trading Pte Ltd leverages direct import relationships with Japanese auction houses to secure consistent inventory. Sime Darby Auto Selection Limited anchors its position through certified pre-owned programs backed by manufacturer warranty extensions. United Motoring Pte Ltd competes on volume turnover, operating multiple showroom locations across Singapore's industrial zones.
A used car constitutes a pre-owned passenger or commercial vehicle that has undergone prior registration with a national transport authority, typically assessed through odometer verification, structural inspection, and emissions compliance testing before resale. Its primary commercial purpose centers on providing mobility solutions at depreciated price points relative to new vehicle acquisition costs. Sedan inventory dominates transaction volumes in Singapore's used car marketplace due to compact dimensions suited to urban parking constraints and COE efficiency calculations. Hybrid powertrains represent the fastest-expanding fuel type segment as Land Transport Authority incentive structures and escalating petrol costs redirect consumer preference toward electrified drivetrains. Certified Pre-Owned vehicles command concentrated margin pools through dealer-backed warranty coverage and standardized reconditioning protocols that reduce buyer uncertainty.
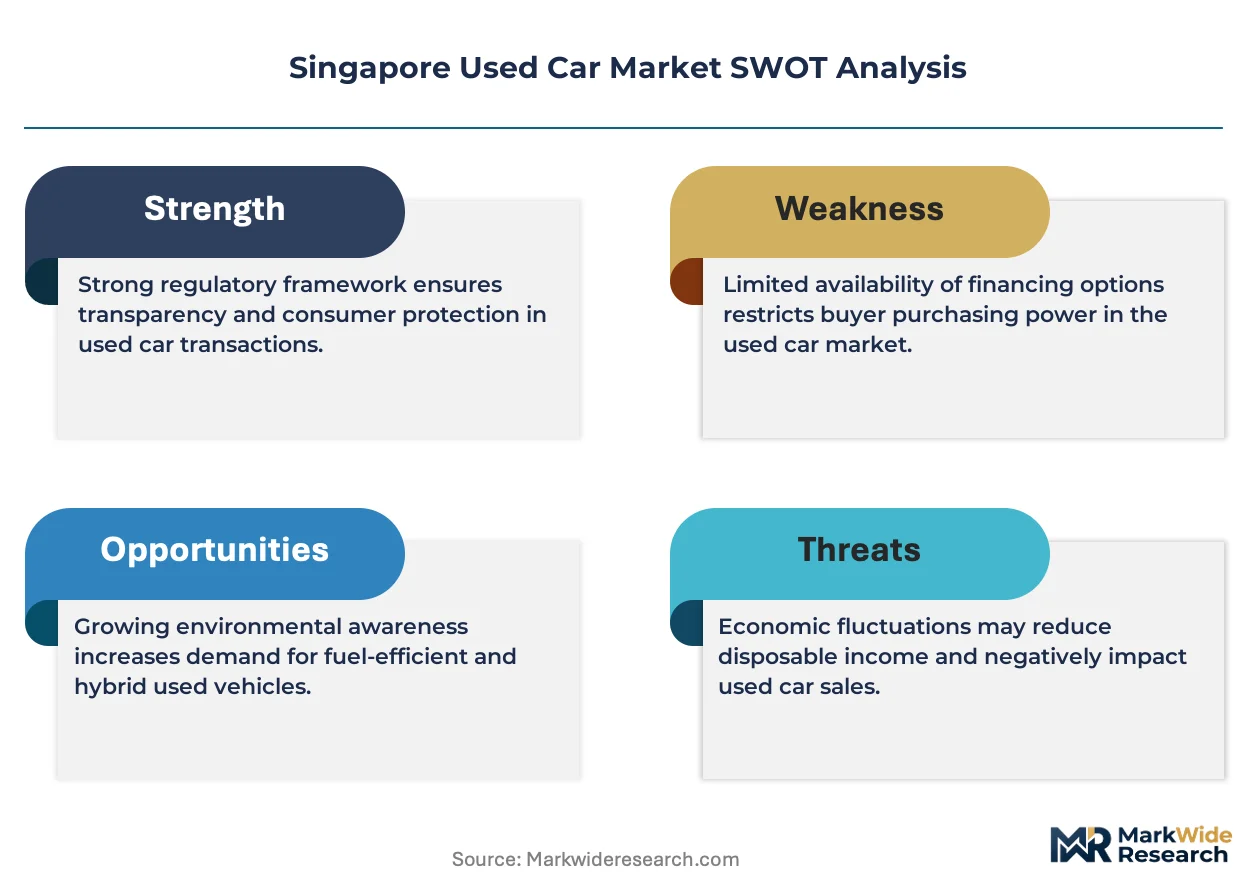
The Land Transport Authority enforces COE quota allocations and vehicle inspection standards that directly constrain used car supply elasticity and mandate periodic roadworthiness certification. Singapore's National Environment Agency administers emissions benchmarks under the Vehicular Emissions Scheme, progressively tightening carbon monoxide and particulate thresholds that filter eligible used car imports. Consumer protection frameworks administered by the Competition and Consumer Commission of Singapore govern disclosure obligations for odometer readings and accident history. Stakeholders must monitor impending COE supply adjustments and evolving electrification mandates to align inventory sourcing with regulatory trajectory.
Market Dynamics
Singapore's Vehicle Quota System and Certificate of Entitlement framework create artificial scarcity that elevates residual values and compresses replacement cycles across the used car ecosystem.
Growth Catalysts
- Ride-hailing fleet expansion:Grab and Gojek operators prioritize cost-efficient vehicle procurement to maximize driver earnings per kilometer. Fleet managers source three- to five-year-old sedans with remaining COE validity.
- Vehicular Emissions Scheme incentives:Singapore's National Environment Agency rebates reward hybrid and electric vehicle adoption. Buyers redirect preference toward electrified drivetrains to capture registration discounts.
- Japanese auction pipeline:Direct import relationships with USS and TAA auction houses secure consistent low-mileage inventory. Arbitrage opportunities persist despite yen volatility and rising domestic retention rates.
Market Restraints
- COE supply rigidity:The Land Transport Authority's bimonthly quota auctions fix vehicle population growth at replacement-rate levels. Used car supply elasticity remains constrained by this administrative ceiling.
- Inspection compliance costs:Periodic roadworthiness certification under LTA standards imposes mandatory maintenance expenditures. Older vehicles face escalating failure rates at inspection stations.
- Import age restrictions:Singapore limits used vehicle imports to three years from first registration. Sourcing windows narrow as Japanese domestic retention extends average vehicle holding periods.
Strategic Opportunities
- Certified Pre-Owned programs:Dealer-backed warranty extensions and standardized reconditioning protocols reduce buyer uncertainty. Margin pools concentrate in vehicles with manufacturer certification.
- Electrification tailwinds:Early battery electric vehicles approach secondary market eligibility as initial COE terms expire. Charging infrastructure density in Singapore supports urban EV practicality.
- Digital auction platforms:Online bidding systems connect dealers directly to Japanese auction houses without intermediary markups. Procurement cost structures compress through platform disintermediation.
Industry Challenges
- Technical assessment standardization:Odometer verification and structural damage detection require specialized diagnostic equipment. Technician training lags behind evolving vehicle electronics complexity.
- Reconditioning capex intensity:Paint correction, interior refurbishment, and mechanical restoration demand facility investment. Workshop throughput limits inventory turnover velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Used Car Market |
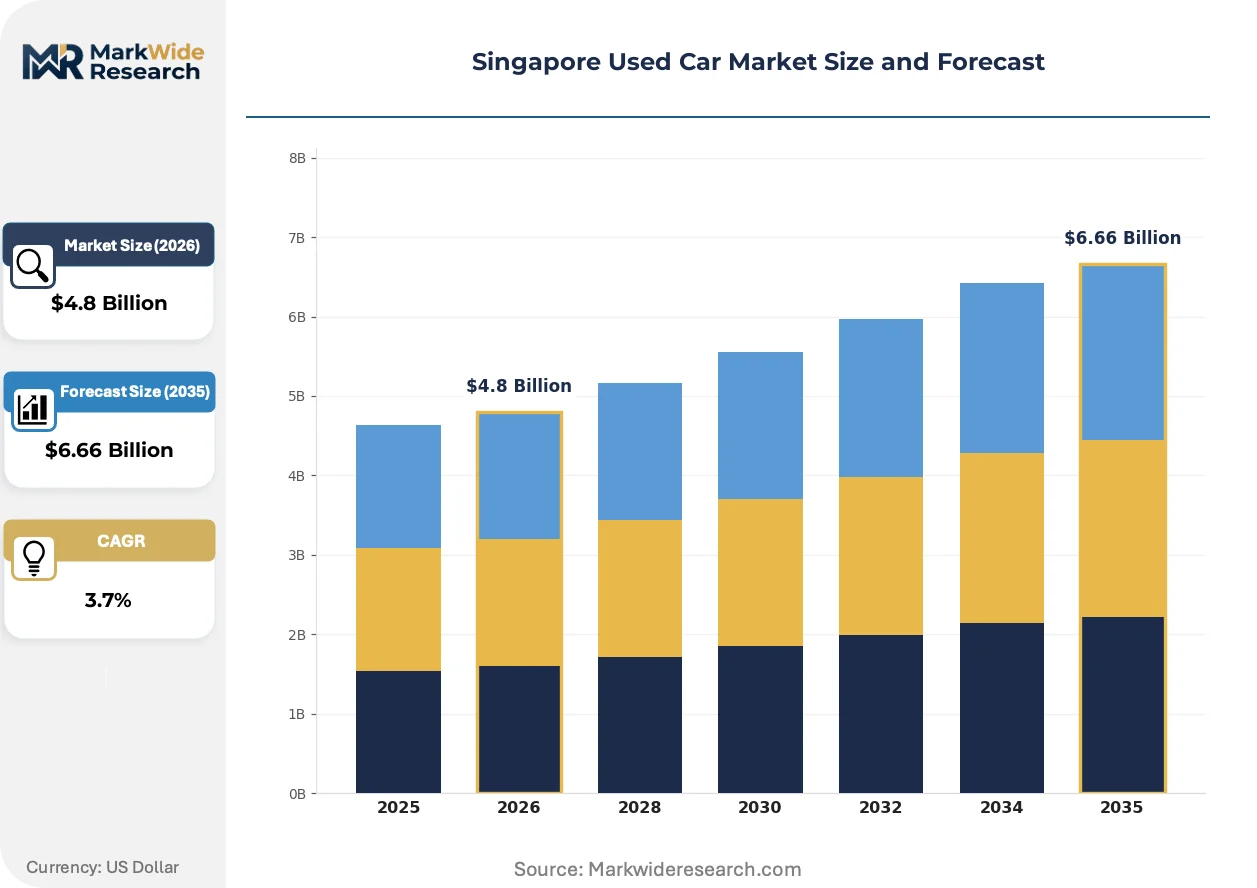
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Fuel Type: Petrol, Diesel, Electric, Hybrid Condition: Certified Pre-Owned, Like New, Used, Damaged Sales Channel: Dealership, Online Platform, Auction, Private Sale |
| Companies Covered | Precise Auto Trading Pte Ltd, United Motoring Pte Ltd, Sime Darby Auto Selection Limited, Car Times Automobile, Supreme Cars Pte Ltd, SG Car Choice Pte Ltd, Sphere Automobile Pte Ltd, Auto Zoom Enterprise Pte Ltd, Vin's Automotive Group Pte Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Used Car Market Strategic Shifts
Digital infrastructure is compressing transaction friction across Singapore's used car value chain. Three developments are reconfiguring how inventory moves from import to final registration.
Blockchain-based vehicle history platforms is digitizing provenance documentation for Japanese imports. Dealers and consumers access immutable service records, accident history, and ownership chains through distributed ledger verification. This transparency compression reduces information asymmetry premiums in pricing negotiations.
Singapore's Land Transport Authority has tightened Vehicular Emissions Scheme thresholds for carbon monoxide and particulate matter. The regulatory compression filters eligible import inventory toward hybrid and electric powertrains. Sedan and compact SUV segments face accelerated obsolescence for internal combustion variants that fail revised benchmarks.
Fleet operators now specify residual value guarantees in procurement contracts with authorized dealers. This risk-transfer mechanism replaces traditional outright purchase models for ride-hailing vehicle supply. Commercial buyers in the Grab and Gojek ecosystems prioritize depreciation protection over upfront acquisition discounts.
Singapore Used Car Market Segmentation
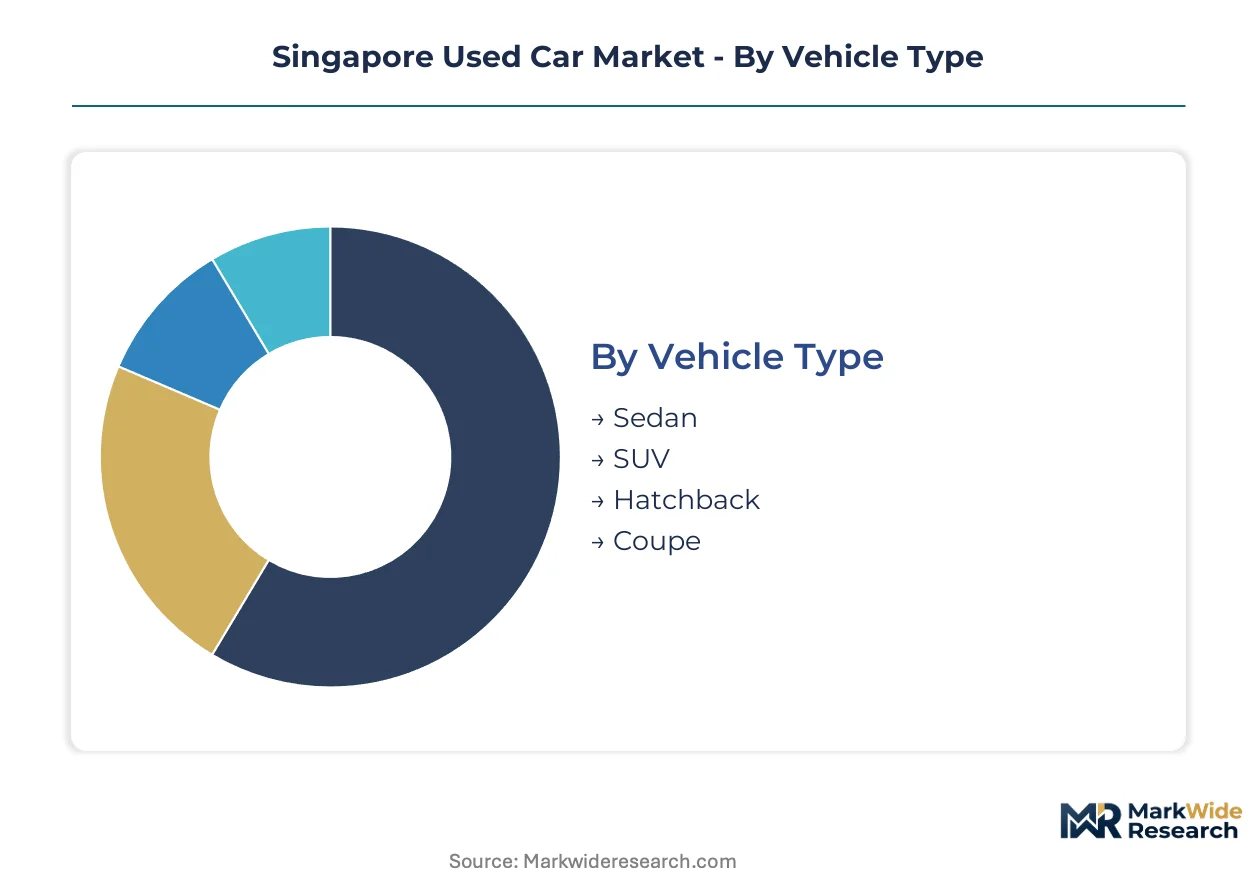
Singapore's Vehicle Quota System fragments demand across distinct mobility profiles. Each segment cluster responds differently to COE tenure calculations and Land Transport Authority emissions thresholds.
Vehicle Type:
Urban parking constraints and ride-hailing fleet specifications shape the use-case spectrum across body styles.
- Sedan:Compact four-door configurations optimize parking efficiency in Singapore's high-density districts. Grab and Gojek fleet managers prioritize three- to five-year-old sedans with remaining COE validity for driver earning optimization.
- SUV:Elevated seating positions and expanded cargo capacity attract family buyers in suburban zones like Tampines and Jurong. COE premium calculations compress demand toward compact crossover dimensions rather than full-size variants.
- Hatchback:Shorter wheelbases suit CBD parking structures and narrow HDB estate lots. Younger owner demographics favor these for first-vehicle entry points.
- Coupe:Two-door configurations with sport-tuned suspensions serve enthusiast niches. Limited practicality restricts volume to collector and weekend-use segments.
Established volume favors Sedan; emerging adoption favors SUV.
Fuel Type:
Cost tier stratification separates powertrain choices across the Vehicular Emissions Scheme rebate structure.
- Hybrid:Dual-mode petrol-electric systems capture maximum NEA registration rebates. Taxi and private-hire operators redirect procurement toward Toyota and Honda hybrid variants for fuel economy compliance.
- Petrol:Conventional internal combustion dominates auction pipeline volume from Japanese import channels. Aging COE tenures on petrol vehicles face accelerating obsolescence under tightening carbon monoxide thresholds.
- Electric:Battery-electric drivetrains approach secondary market eligibility as initial COE terms expire. Charging infrastructure density in Ang Mo Kio and Tampines hubs supports urban practicality.
- Diesel:Compression-ignition engines concentrate in commercial van and light truck segments. Passenger car diesel demand remains minimal due to particulate matter surcharge penalties.
Established volume favors Petrol; emerging adoption favors Hybrid.
Condition:
Margin concentration tracks certification depth and buyer risk tolerance.
- Certified Pre-Owned:Dealer-backed warranty extensions and standardized reconditioning protocols reduce information asymmetry. Sime Darby Auto Selection anchors positioning through manufacturer warranty continuity.
- Like New:Low-mileage vehicles under two years from first registration command minimal depreciation discounts. Japanese auction pipeline supplies these through USS and TAA direct relationships.
- Used:Standard pre-owned inventory without certification dominates volume turnover across industrial zone showrooms. Price-sensitive buyers accept higher mechanical risk for acquisition cost reduction.
- Damaged:Structural or flood-compromised vehicles trade through specialized salvage channels. Repair cost calculus limits viable buyers to workshop operators and export arbitrageurs.
Established volume favors Used; emerging adoption favors Certified Pre-Owned.
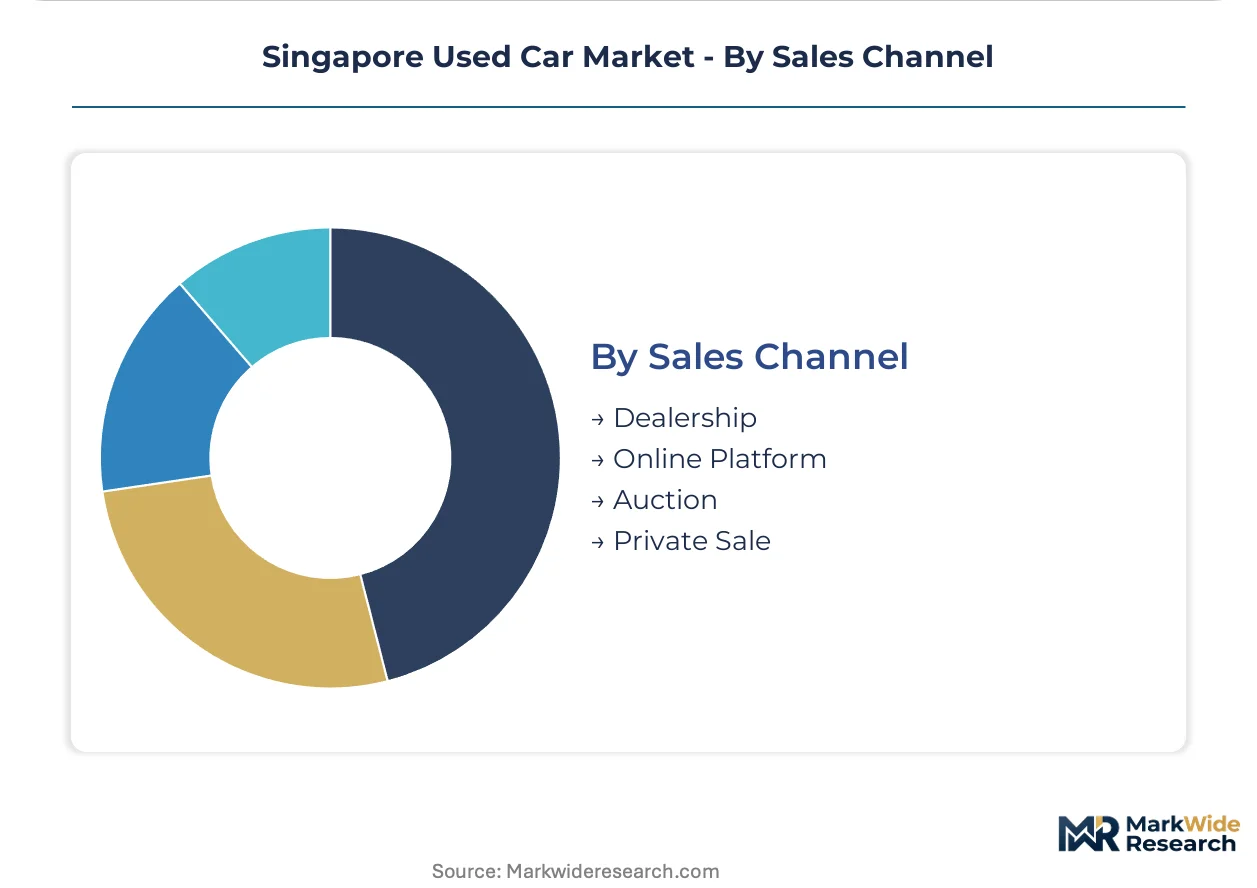
Sales Channel:
Customer type and transaction friction determine channel selection patterns.
- Dealership:Physical showroom operations provide test drive access and financing facilitation. United Motoring Pte Ltd competes through multiple location coverage across Singapore's industrial zones.
- Online Platform:Digital listing aggregators compress search costs for inventory comparison. Platform disintermediation connects buyers directly to Japanese auction houses without intermediary markups.
- Auction:Competitive bidding environments establish price discovery for dealer procurement. Precise Auto Trading leverages direct import relationships with Japanese auction houses.
- Private Sale:Direct owner-to-buyer transactions eliminate dealer margin layers. Odometer verification and accident history disclosure obligations under CCCS frameworks protect consumer interests.
Established volume favors Dealership; emerging adoption favors Online Platform.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Land Transport Authority anchors Singapore's used car ecosystem through COE quota auctions and Vehicular Emissions Scheme enforcement. These mechanisms create artificial scarcity that elevates residual values and compresses replacement cycles. Urban density and parking constraints concentrate transaction activity across Singapore's industrial zones and suburban showroom clusters.
Central Singapore
Ride-hailing fleet operators anchor demand in the Central Business District and surrounding high-density corridors. The Land Transport Authority's COE bidding system forces fleet managers to optimize vehicle holding periods against depreciation curves. Leng Kee and Alexandra Road host concentrated dealership showrooms serving corporate procurement and premium retail segments.
Northeast Singapore
Ang Mo Kio and Serangoon housing estates generate sustained family replacement demand for compact sedans and hatchbacks. The National Environment Agency's emissions rebates redirect buyer preference toward hybrid powertrains in this middle-income corridor. Tampines industrial zones accommodate volume-oriented dealers competing on turnover velocity.
West Singapore
Jurong and Clementi clusters support logistics-linked commercial vehicle trading and light truck segments. The Land Transport Authority's vehicle inspection standards impose compliance costs that filter older diesel inventory from this corridor. Tuas industrial expansion is drawing reconditioning workshop investment to service fleet refurbishment demand.
North Singapore
Woodlands and Yishun estates represent entry-point demand for first-time owners and younger demographics. Japanese import pipeline relationships concentrate procurement activity through direct auction house connections. Industrial zone showrooms in this sub-region compete aggressively on price transparency and financing facilitation.
East Singapore
Bedok and Tampines housing clusters sustain replacement-driven demand for certified pre-owned vehicles with remaining COE validity. The Competition and Consumer Commission of Singapore's disclosure frameworks protect buyers in this high-transaction corridor. Marine Parade and East Coast areas host specialized dealers serving enthusiast and collector segments.
Singapore Used Car Market Competitive Environment
Capability concentration sits with direct-import specialists; scale advantage sits with multi-location dealership networks. Singapore's used car market fragments across three operational tiers: auction-linked importers, certified pre-owned programs, and volume turnover operators. Strategic differentiation follows sourcing depth, warranty backing, and geographic coverage intensity. Competitive moves center on Japanese auction house relationship exclusivity and residual value guarantee structuring for fleet contracts.
Within the direct-import tier, Precise Auto Trading Pte Ltd exemplifies auction-linked procurement specialization through USS and TAA house relationships. Sime Darby Auto Selection Limited occupies the certified pre-owned segment with manufacturer warranty continuity as its positioning anchor. United Motoring Pte Ltd represents scale-driven coverage through multiple showroom locations across Singapore's industrial zones.
| Leading Market Players |
|---|
| Precise Auto Trading Pte Ltd |
| United Motoring Pte Ltd |
| Sime Darby Auto Selection Limited |
| Car Times Automobile |
| Supreme Cars Pte Ltd |
| SG Car Choice Pte Ltd |
| Sphere Automobile Pte Ltd |
| Auto Zoom Enterprise Pte Ltd |
| Vin's Automotive Group Pte Ltd |
| Others |
Value Chain & Pricing Dynamics
Japanese auction house concentration in USS, TAA, and JU channels feeds margin capture toward direct-import specialists with bilateral house relationships rather than intermediary-dependent dealers. COE quota scarcity amplifies this structural advantage by compressing inventory velocity premiums into sourcing efficiency rather than volume throughput.
Pricing Analysis
Price spreads between Leng Kee showroom premiums and Woodlands industrial zone listings compress as digital auction platforms democratize Japanese import access. Pricing stratifies across certified pre-owned tiers with manufacturer warranty backing, standard reconditioned inventory, and direct auction imports without local preparation. Cost compression in the uncertified tier is intensifying because online platform disintermediation erodes traditional dealer markups. Fleet operators at Grab and Gojek show least price sensitivity due to residual value guarantee contracting, while first-time buyers in Yishun and Woodlands drive hardest bargain hunting.
Supply Chain Analysis
Upstream feedstock of low-mileage vehicles draws from Japanese domestic auction pipelines, Singaporean fleet de-fleeting, and parallel import channels from Malaysia. Critical dependencies center on COE tenure validity, odometer authentication technology, and reconditioning workshop capacity. Single-source vulnerability concentrates in USS auction house access for premium hybrid inventory. Distribution runs through industrial zone showroom clusters for physical inspection, supplemented by platform-based remote bidding with local delivery logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's used car market sits in early-cycle expansion as electrified drivetrain adoption accelerates secondary market eligibility for battery electric vehicles and hybrid powertrains capture escalating NEA rebate incentives.
For Market Incumbents: Pre-empt platform disintermediation by securing exclusive Japanese auction house data feeds and embedding residual value guarantee products into fleet procurement contracts. Defend against pure-play digital entrants through certified pre-owned warranty extensions that online-only competitors cannot replicate without facility investment.
For New Entrants and Emerging Players: North Singapore's Woodlands and Yishun corridors show geographic underpenetration by certified pre-owned specialists, with family replacement demand concentrated in hybrid hatchback segments underserved by volume-oriented dealers. Capture this white-space through mobile inspection units and financing facilitation partnerships with local credit unions.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dealership rollups lacking direct Japanese auction relationships and captive reconditioning infrastructure. Five-to-ten year viability hinges on COE supply trajectory and electrification mandate pacing. Monitor LTA bimonthly quota auction clearing prices as the inflection signal for inventory valuation cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Auction House Relationship | Bilateral USS and TAA access secures consistent low-mileage hybrid inventory ahead of competitor bidding. |
| Certified Pre-Owned Program Expansion | Manufacturer warranty extensions reduce buyer uncertainty and capture concentrated margin pools in sedan segments. |
| Residual Value Guarantee Structuring | Fleet contracts with Grab and Gojek operators replace outright purchase models with depreciation risk transfer. |
| Digital Platform Integration | Online bidding systems compress procurement costs by connecting dealers directly to Japanese auction channels. |
| Reconditioning Workshop Investment | Tuas industrial zone facilities support paint correction and mechanical restoration throughput for inventory velocity. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across fleet procurement managers at Grab and Gojek, dealership operations directors at Leng Kee and Alexandra Road clusters, and reconditioning workshop owners in Tuas industrial zones. Secondary validation drew from Land Transport Authority COE auction clearing data, National Environment Agency Vehicular Emissions Scheme rebate schedules, and Competition and Consumer Commission of Singapore disclosure frameworks. Bottom-up inventory flow modeling triangulated against top-down market value reconstruction.
Calibration anchored volume and value outputs to observed transaction patterns across the projection horizon. Segmentation dimensions modeled included vehicle body style, propulsion architecture, certification tier, and sales channel structure. CAGRs derived from regression against COE supply trajectories and electrification adoption curves. Forecast inputs incorporated Japanese domestic retention rate trends and yen exchange rate volatility assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-native entrants with venture-backed customer acquisition spending would shift outcomes beyond modeled bounds. Cross-checking against LTA vehicle registration statistics and NEA emissions compliance databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Indonesia Used Car Financing Market
Used Vehicles
Used E-Scooter Market
Used Vehicles
Spain Used Car Market
Used Vehicles
Nigeria Used Car Market
Used Vehicles
Canada Used Car Market
Used Vehicles
France Used Car Market
Used Vehicles
Used Cars in Russia Market
Used Vehicles
Global Online Second-Hand Car Trading Service Market
Used Vehicles
Norway Used Car Market
Used Vehicles
Kuwait Used Car Market
Used Vehicles
South Korea Used Car Market
Used Vehicles
Russia Used Car Market
Used Vehicles
Japan Used Car Market
Used Vehicles
Switzerland Used Car Market
Used Vehicles
Myanmar Used Car Market
Used Vehicles
United Kingdom Used Car Market