
 Thailand Used Car Market | 2026-2036
Thailand Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Used Car Market Outlook
Modular service bundling—combining inspection, warranty, and financing into single transaction packages—is repositioning buyer expectations across Thailand's secondary vehicle market. Toyota Sure leverages its captive certification network to anchor quality perception in pickup and sedan segments. Carsome competes through integrated online-to-offline logistics that compress delivery timelines. Honda Certified Used Car differentiates via powertrain-specific warranties that reduce residual risk for hybrid buyers.
A used car is a previously registered motor vehicle resold through formal or informal channels, evaluated against odometer readings, structural integrity assessments, and emissions compliance records before re-entry into commercial circulation. Its primary purpose is to extend asset utility while lowering capital outlay for individual and commercial operators relative to new vehicle acquisition. Sedan and pickup categories dominate transaction volumes, reflecting Thailand's fleet-heavy commercial base and family-oriented consumer profile. Certified pre-owned condition tiers command margin premiums as buyers prioritize verified maintenance histories over as-is alternatives. Online platforms represent the fastest-expanding sales channel, displacing traditional dealer foot traffic through price transparency and remote financing pre-approval.
The Department of Land Transport governs ownership transfer protocols and odometer disclosure requirements, while the Excise Department structures tax liabilities that influence resale pricing dynamics. The Thailand Automotive Institute promotes standardized vehicle inspection frameworks that certified pre-owned programs must satisfy. Stakeholders must monitor how evolving emissions testing mandates and digital title transfer systems reshape transaction friction and buyer trust thresholds.
Market Dynamics
Digital title transfer infrastructure and Board of Investment electric vehicle incentives are converging to redirect Thai buyer attention toward certified hybrid and battery-electric inventories in the secondary market.
Growth Catalysts
- BOI EV Assembly Incentives:Tax holidays for electric vehicle manufacturing are accelerating new-model launches, which expand future used-car supply pools and normalize battery-electric resale channels.
- Greater Bangkok Urban Density:Metropolitan congestion and parking scarcity are pushing individual owners toward vehicle turnover, sustaining inventory flow into secondary markets.
- Modular Service Bundling:Integrated inspection-warranty-financing packages are compressing transaction friction and elevating certified pre-owned premiums above as-is alternatives.
Market Restraints
- Battery Degradation Uncertainty:Absence of standardized state-of-health testing protocols for lithium-ion packs creates residual value opacity for electric and hybrid used vehicles.
- Excise Department Tax Liability:Transfer tax structures based on engine displacement disproportionately burden pickup segment resales, distorting price discovery.
- Single-Point Platform Concentration:Online marketplace dominance by two major aggregators creates fee pressure and margin compression for independent dealers.
Strategic Opportunities
- Eastern Economic Corridor Fleet Rotation:Industrial zone expansion near Chonburi and Rayong is generating commercial vehicle replacement cycles that feed secondary market supply.
- Digital Title Transfer Systems:Blockchain-based ownership registries under Department of Land Transport pilot programs promise same-day transaction settlement.
- Powertrain-Specific Warranty Products:Hybrid battery replacement coverage is emerging as a distinct insurance vertical with captive finance tie-in potential.
Industry Challenges
- Odometer Fraud Detection:Mechanical rollback schemes persist despite legal penalties, eroding trust in private-party transactions and elevating certification costs.
- Emissions Testing Mandate Compliance:Evolving exhaust standards require garage infrastructure upgrades that strain small independent inspection operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Used Car Market |
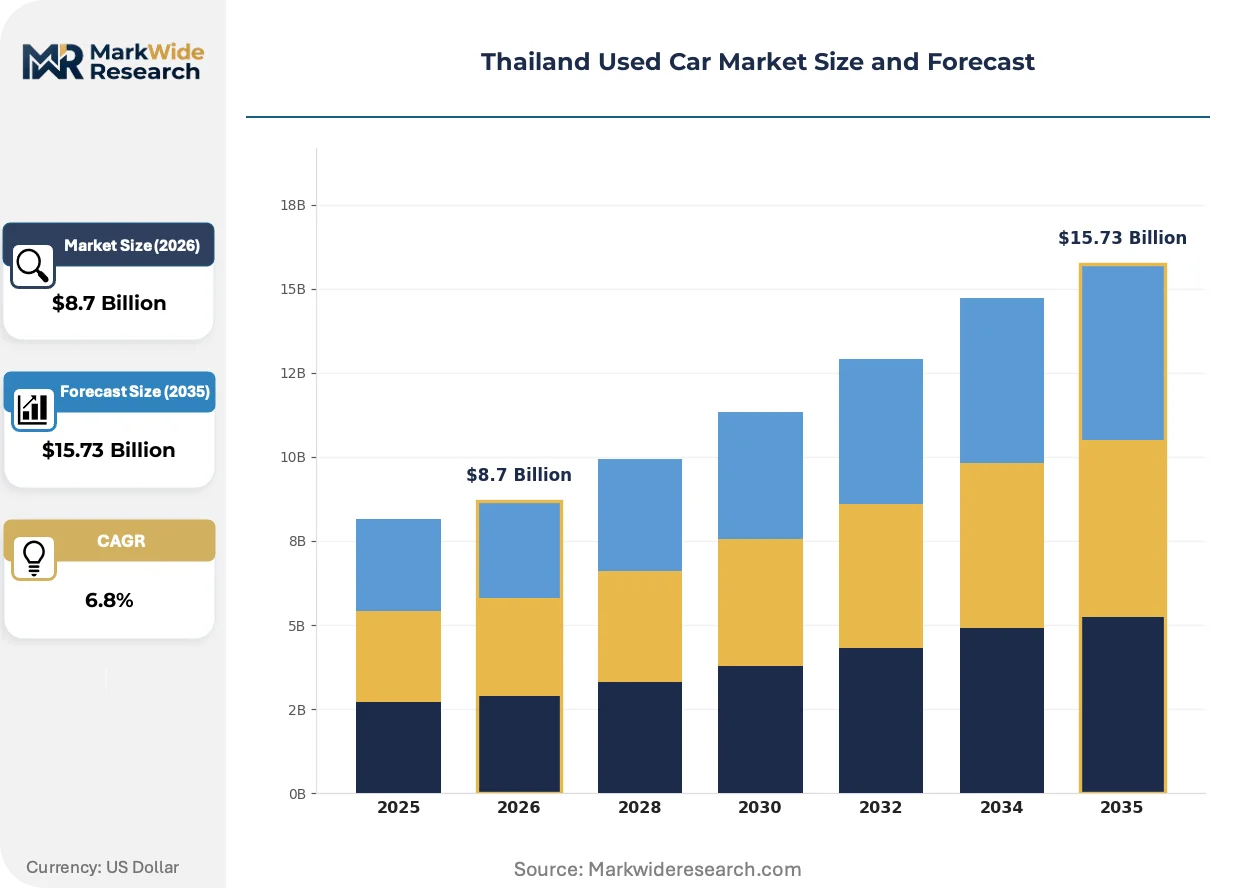
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Pickup Fuel Type: Gasoline, Diesel, Electric, Hybrid Condition: Certified Pre-Owned, Non-Certified, As-Is, Refurbished Sales Channel: Dealerships, Online Platforms, Auctions, Private Sellers |
| Companies Covered | Cars24 Group (Thailand) Co., Ltd, Toyota Sure (Toyota Motor Thailand Co., Ltd.), Carsome (Thailand) Co., Ltd, Carro Thailand, Honda Certified Used Car, iCarAsia (One2Car), SiamMotorworld, Motors.co.th Limited, Pixy Asia Co., Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Used Car Market Strategic Shifts
Technology-enabled trust mechanisms and regulatory digitization are compressing transaction timelines while fragmenting traditional dealer intermediation in Thailand's secondary vehicle ecosystem.
Artificial intelligence-powered visual inspection tools are rewriting damage assessment protocols. Fleet operators and ride-hailing aggregators are adopting automated scratch-and-dent scoring to accelerate procurement decisions. This compression of evaluation cycles is enabling same-day inventory acquisition that previously required multi-day garage assessments.
Thailand Automotive Institute standardized inspection frameworks are mandating uniform condition grading across certified pre-owned programs. The Department of Land Transport is aligning odometer disclosure requirements with these protocols. Franchise dealers in Greater Bangkok are responding by integrating blockchain-verified service histories into their certification packages.
Remote financing pre-approval is displacing showroom credit negotiations as the dominant buyer acquisition path. Digital platforms are capturing loan underwriting before physical vehicle inspection, reversing traditional purchase sequences. This behavioral pivot is most pronounced among first-time used-car buyers in Bangkok's satellite industrial corridors.
Thailand Used Car Market Segmentation
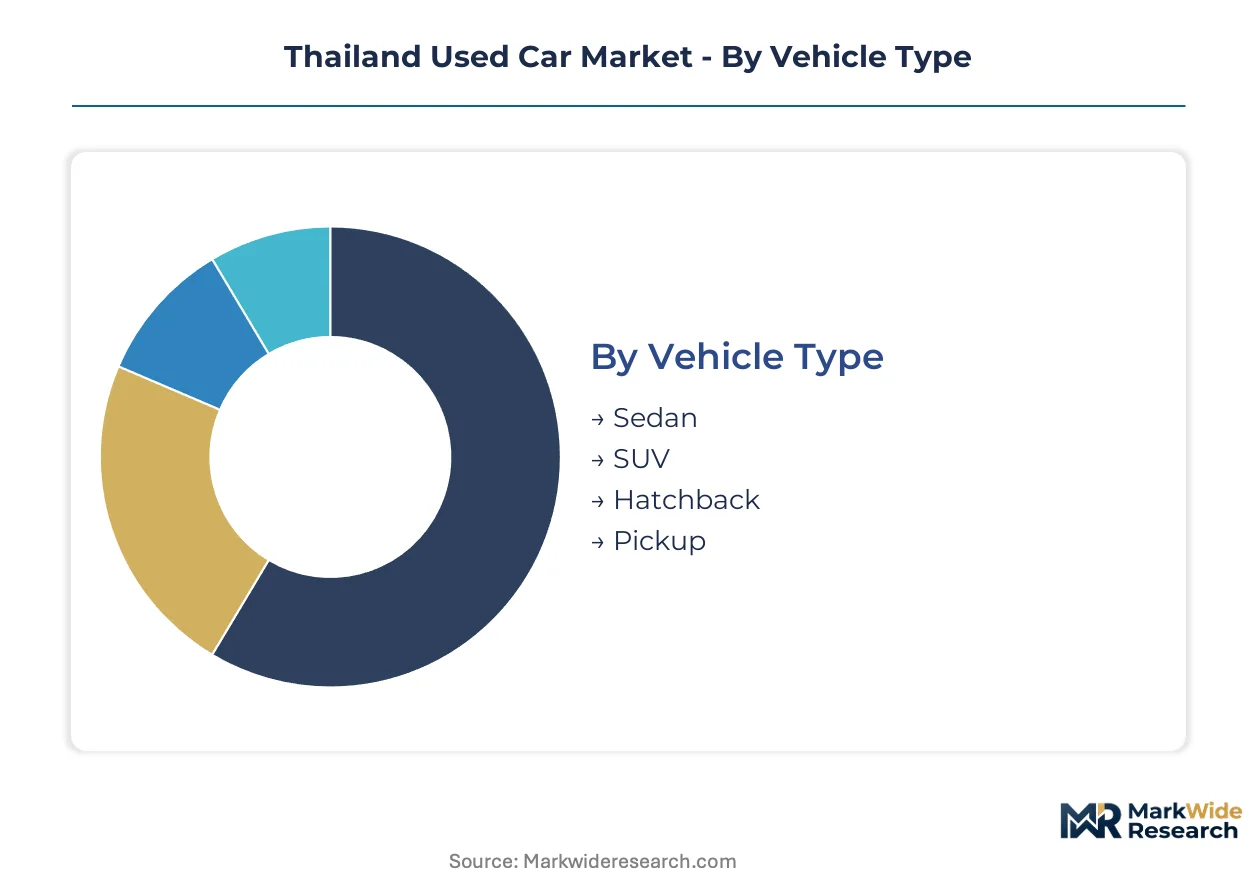
Thailand's used car market fragments across four critical dimensions that shape buyer risk tolerance, financing access, and resale velocity. Fleet operators and individual consumers weight these segments differently, creating distinct margin profiles for dealers and platform operators.
Vehicle Type:
Pickup trucks anchor commercial procurement decisions across Thailand's logistics-dependent economy, while sedans and SUVs compete for family mobility budgets in Greater Bangkok.
- Pickup:Body-on-frame construction with diesel or gasoline powertrains dominates commercial fleet rotations. Demand concentrates in Eastern Economic Corridor industrial zones near Chonburi and Rayong, where factory logistics contracts drive replacement cycles every 4-5 years.
- Sedan:Three-box passenger configuration with unibody construction serves family and ride-hailing applications. Greater Bangkok's urban density and parking scarcity push individual owners toward compact sedan turnover, sustaining steady secondary market inflow.
- SUV:Elevated ride height and expanded cargo capacity attract provincial buyers seeking all-terrain capability. Thai Automotive Institute inspection protocols for structural integrity are tightening certification standards for this segment.
- Hatchback:Compact two-box design with rear cargo access suits first-time buyers and urban commuters. Financing pre-approval rates run highest for this entry-tier category.
Volume sits with pickup and sedan; growth tilts toward SUV as provincial income levels rise.
Fuel Type:
Powertrain choice now intersects directly with Board of Investment incentives and residual value uncertainty, redirecting procurement patterns across commercial and consumer segments.
- Gasoline:Spark-ignition internal combustion engines dominate current inventory depth. Excise Department tax structures based on engine displacement continue to distort price discovery for larger-displacement variants.
- Diesel:Compression-ignition powertrains command pickup segment share due to torque characteristics and fuel efficiency. Eastern Economic Corridor fleet operators specify diesel for heavy-load logistics contracts.
- Hybrid:Parallel and series-parallel electrified powertrains are gaining share fastest as Toyota Sure and Honda Certified programs normalize battery warranty transferability. Greater Bangkok ride-hailing drivers prioritize hybrid for fuel cost arbitrage.
- Electric:Battery-electric propulsion remains supply-constrained in secondary channels. Absence of standardized state-of-health testing protocols for lithium-ion packs creates residual value opacity that restrains transaction velocity.
Gasoline and diesel still transact highest absolute volumes; hybrid is expanding most quickly as certification programs reduce buyer risk perception.
Condition:
Certification tier determines financing eligibility, warranty coverage, and price premium capture, with Thai Automotive Institute frameworks now mandating uniform grading standards.
- Certified Pre-Owned:Dealer-backed inspection programs with verified maintenance histories and extended warranties. Franchise networks in Greater Bangkok integrate blockchain-verified service records to anchor quality perception.
- Non-Certified:Dealer-sold vehicles without formal certification backing, priced at intermediate levels between certified and as-is alternatives. Independent dealers in satellite industrial corridors rely on this tier for margin preservation.
- As-Is:Unwarranted vehicles sold without inspection guarantees, typically through private-party channels. Odometer fraud detection gaps elevate buyer risk and suppress price realization.
- Refurbished:Reconditioned units with component replacements and cosmetic restoration, often sourced from fleet lease returns. Eastern Economic Corridor commercial vehicle rotation feeds this pipeline.
Certified Pre-Owned commands the steepest price premiums; As-Is transactions dominate absolute volume through informal channels.
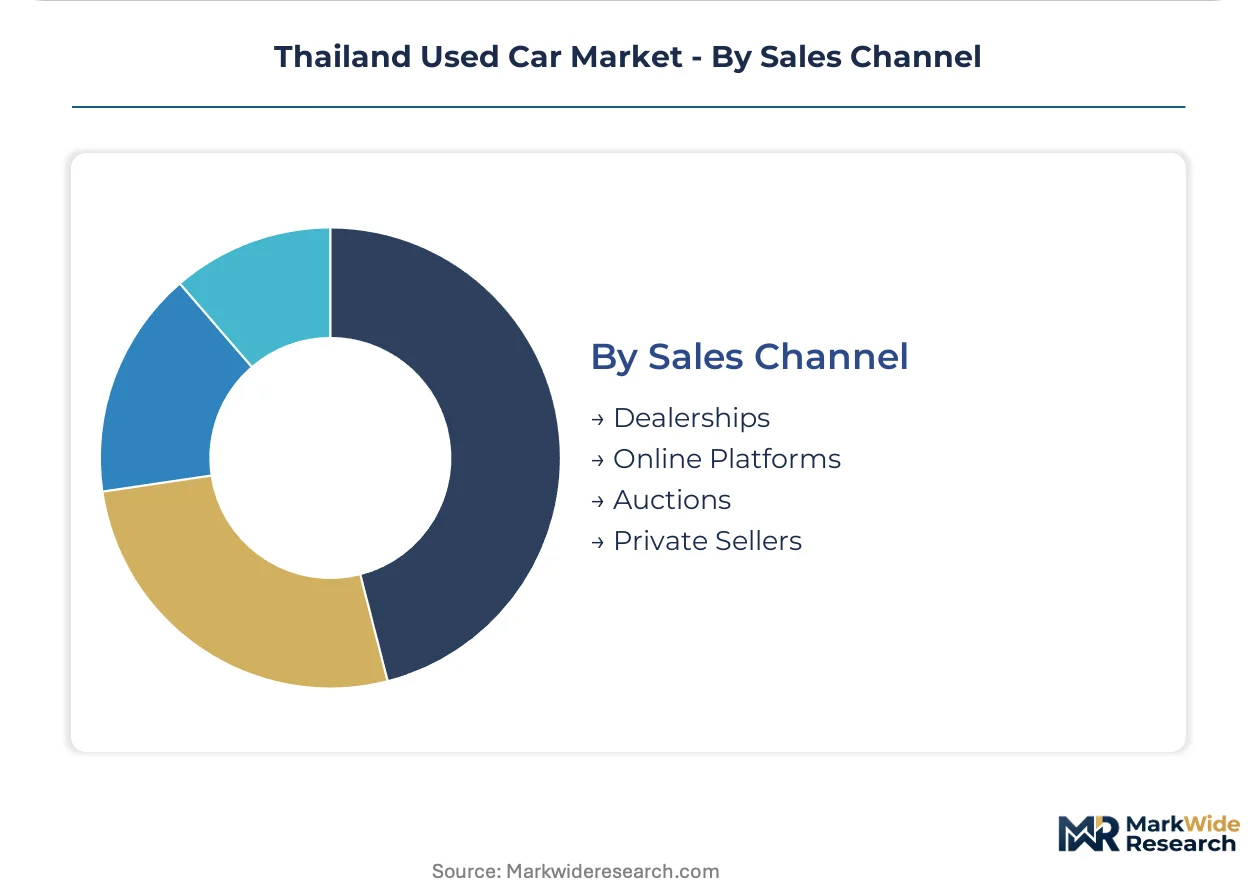
Sales Channel:
Channel selection shapes price transparency, financing integration, and delivery timeline compression, with digital platforms now capturing loan underwriting before physical inspection.
- Dealerships:Physical showrooms with captive financing and certification services. Franchise dealers anchor certified pre-owned volume in Greater Bangkok metropolitan area.
- Online Platforms:Aggregator marketplaces with price transparency and remote pre-approval workflows. Carsome's integrated online-to-offline logistics compress delivery timelines for first-time buyers.
- Auctions:Wholesale channels for dealer inventory acquisition and fleet disposal. Volume concentrates in Bangkok-based auction houses serving Eastern Economic Corridor commercial accounts.
- Private Sellers:Direct owner-to-buyer transactions without intermediary markup. Department of Land Transport digital title transfer pilots aim to reduce settlement friction for this channel.
Dealerships and Online Platforms split transaction value; Private Sellers still move the highest unit counts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's used car production—centered on fleet rotation and lease return refurbishment—outpaces domestic absorption, creating surplus inventory that flows toward neighboring ASEAN markets with less developed secondary vehicle infrastructure.
Greater Bangkok Metropolitan Area
Ride-hailing driver procurement and family sedan turnover dominate transaction velocity in this dense urban core. The Department of Land Transport's digital title transfer pilot programs reduce settlement friction for peer-to-peer sales. Franchise dealer networks in Bangkok and adjacent Samut Prakan anchor certified pre-owned certification volume.
Eastern Economic Corridor
Industrial logistics contracts in Chonburi and Rayong drive commercial pickup replacement cycles every four to five years. Board of Investment incentives for electric vehicle assembly redirect fleet operator attention toward hybrid used inventory. Factory zone expansion generates steady supply pipeline for refurbished commercial vehicles.
Northern Region
Provincial buyers in Chiang Mai and surrounding provinces favor SUVs for all-terrain capability and rural road conditions. Thai Automotive Institute inspection protocols for structural integrity tighten certification standards for elevated-ride-height vehicles. Independent dealers in this sub-region rely on non-certified inventory tiers for margin preservation.
Northeastern Region
First-time buyer concentration in Khon Kaen and Udon Thani sustains hatchback financing pre-approval rates. The Excise Department's engine-displacement-based transfer tax structures disproportionately burden larger vehicles in price-sensitive segments. Private seller channels move highest unit counts through informal networks.
Southern Region
Tourism-dependent coastal provinces generate irregular supply from rental fleet rotations in Phuket and Surat Thani. Online platform penetration lags northern and central regions due to lower digital banking adoption. Auction houses in Hat Yai serve cross-border commercial accounts with Myanmar and Malaysia.
Thailand Used Car Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Thailand's used car ecosystem, creating a tiered structure where captive finance arms and integrated logistics networks determine competitive position. The market fragments across franchise dealer networks, platform aggregators, and independent operators with distinct margin profiles. Three archetypes dominate: manufacturer-certified programs with warranty transferability, digital-first platforms with online-to-offline fulfillment, and independent dealers with flexible pricing. Consolidation pressures concentrate around M&A activity targeting regional logistics capabilities and strategic partnerships bundling inspection with financing.
Among platform-centric operators, Carsome (Thailand) Co., Ltd and Carro Thailand exemplify the digital-aggregator archetype with integrated logistics compression. Toyota Sure (Toyota Motor Thailand Co., Ltd.) anchors the manufacturer-certified tier with captive certification network density. These three occupy positions that represent divergent strategic bets on trust mechanism design—platform transparency versus brand-backed quality assurance.
| Leading Market Players |
|---|
| Cars24 Group (Thailand) Co., Ltd |
| Toyota Sure (Toyota Motor Thailand Co., Ltd.) |
| Carsome (Thailand) Co., Ltd |
| Carro Thailand |
| Honda Certified Used Car |
| iCarAsia (One2Car) |
| SiamMotorworld |
| Motors.co.th Limited |
| Pixy Asia Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
Certified vehicle inspector concentration in Greater Bangkok and Samut Prakan drives labor-cost differentials that widen spreads between certified pre-owned premiums and as-is transaction floors. The Eastern Economic Corridor's technician scarcity compresses refurbishment margins while elevating price tiers for verified commercial pickup inventory.
Pricing Analysis
Margin tightening in as-is private sales traces to odometer fraud detection costs and buyer trust erosion. Three-tier pricing structure across certified pre-owned, non-certified dealer, and as-is private tiers anchors the market, with certification grade and blockchain-verified service history as primary differentiation drivers. Cost-down pressure on independent dealers accelerates because online platform fee structures capture financing pre-approval revenue. First-time buyers in provincial hatchback segments exhibit highest price sensitivity; fleet operators procuring Eastern Economic Corridor commercial pickups show lowest.
Supply Chain Analysis
Dual-sourcing requirements from Board of Investment EV assembly incentives are mandating multi-supplier qualification for battery and powertrain components. Supply concentrates in Thailand's domestic refurbishment networks, Japanese OEM captive certification programs, and Chinese battery-electric component flows. Raw material dependencies include lithium-ion cells, steel body panels, and electronic control modules. Single-source vulnerability around hybrid battery replacement coverage creates procurement risk. Distribution runs through franchise dealer networks, platform aggregator logistics, and Bangkok-based auction houses serving cross-border ASEAN accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified pre-owned inventory scarcity props pricing premiums across Greater Bangkok, with Eastern Economic Corridor fleet rotation cycles constituting the dominant capacity bottleneck constraining commercial vehicle supply.
For Market Incumbents: Deploy blockchain-verified service history integration to defend against platform aggregator transparency threats. Deepen captive certification network density in Rayong and Chonburi industrial zones. Accelerate powertrain-specific warranty product development to capture hybrid battery replacement coverage premiums.
For New Entrants and Emerging Players: Begin with provincial SUV certification gaps in Chiang Mai and northern region structural integrity assessment demand. Target underpenetrated digital title transfer facilitation for private seller channels. Build inspection-logistics partnerships with Thailand Automotive Institute framework compliance as the anchor go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated online-to-offline logistics operators given Department of Land Transport digital registry pilots compressing settlement timelines. Long-term viability favors platform aggregators with captive financing tie-ins and regional auction house networks. Monitor hybrid battery state-of-health testing protocol standardization as the inflection signal for electric used vehicle velocity normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Network Expansion | Thai Automotive Institute compliance anchors quality perception in pickup and sedan segments. |
| Digital Title Transfer Integration | Department of Land Transport blockchain pilots reduce peer-to-peer transaction friction. |
| Powertrain-Specific Warranty Launch | Hybrid battery replacement coverage captures residual risk arbitrage from fuel cost savings. |
| Online-to-Offline Logistics Buildout | Integrated fulfillment compresses delivery timelines for first-time provincial buyers. |
| Eastern Economic Corridor Fleet Partnership | Industrial zone expansion near Chonburi generates commercial vehicle replacement pipeline. |
Study Parameters
Document review covered Department of Land Transport ownership transfer protocols, Excise Department tax liability structures, and Thailand Automotive Institute inspection frameworks, complemented by interviews with franchise dealer operations managers, platform aggregator logistics directors, certified pre-owned program managers, and Eastern Economic Corridor fleet procurement leads. Secondary validation drew from vehicle registration databases, auction house transaction records, and Board of Investment incentive disclosure filings. Bottom-up transaction volume modeling and top-down market sizing triangulation anchored value estimates.
Historical registration patterns cross-referenced against panel input from dealer network executives and ride-hailing fleet operators shaped the analytical framework. Segmentation dimensions modeled span vehicle type, fuel architecture, certification tier, and sales channel across the projection horizon. CAGRs derived from trend extrapolation adjusted for policy incentive phase-ins. Forecast inputs included BOI EV assembly incentive uptake trajectories and digital title transfer system deployment timelines.
Regulatory mandate delays, battery degradation testing protocol failures, and platform aggregator fee structure changes are the dominant revision risks. Deviation in Eastern Economic Corridor industrial expansion pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
United Kingdom Used Car Market
Used Vehicles
New Zealand Used Car Market
Used Vehicles
GCC Used Car Market
Used Vehicles
Global Online Second-Hand Car Trading Service Market
Used Vehicles
Used E-Scooter Market
Used Vehicles
Sri Lanka Used Car Market
Used Vehicles
Europe Used Car Market
Used Vehicles
Middle East and Africa Used Car Market
Used Vehicles
Portugal Used Car Market
Used Vehicles
Netherlands Used Car Market
Used Vehicles
Norway Used Car Market
Used Vehicles
Hong Kong Used Car Market
Used Vehicles
Kenya Used Car Market
Used Vehicles
Indonesia Used Car Market
Used Vehicles
Saudi Arabia Used Car Market
Used Vehicles
Spain Used Car Market