
 United States Used Car Market | 2026-2036
United States Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
United States Used Car Market Outlook
The Corporate Average Fuel Economy standard revision is hardening fleet procurement criteria across commercial buyers. CarMax Inc. anchors the national footprint through superstore saturation and captive financing infrastructure. Carvana Co. competes on digital retail density, leveraging proprietary logistics to sustain doorstep delivery economics. AutoNation Inc. dominates franchise-adjacent used operations, extending brand trust into certified pre-owned throughput.
Used cars comprise previously titled vehicles resold through secondary channels, typically assessed via odometer verification, vehicle history reporting, and multi-point mechanical inspection protocols. The primary commercial purpose centers on transportation access at depreciated cost structures beneath new vehicle equivalents. SUVs and trucks command structural preference in the vehicle type dimension, reflecting American buyer bias toward utility and towing capacity. Online platforms represent the fastest-expanding sales channel, disintermediating traditional lot visits through algorithmic pricing and remote fulfillment. Certified pre-owned inventory captures disproportionate margin pools by bridging warranty-backed assurance with below-new price positioning.
The National Highway Traffic Safety Administration enforces odometer disclosure and safety recall compliance, while the Federal Trade Commission's Used Car Rule mandates Buyer's Guide transparency on every transaction. State-level lemon laws and emissions testing regimes, notably California's CARB standards adopted by seventeen states, fragment regulatory exposure across inventory sourcing networks. Stakeholders must monitor electrification residual value curves and battery health certification protocols as the pre-owned fleet composition shifts.
Market Dynamics
The EPA's tightening emissions compliance timelines are forcing fleet operators and commercial buyers toward cleaner pre-owned inventory, compressing demand for older, higher-mileage vehicles while elevating certified pre-owned throughput.
Growth Catalysts
- CARB Standards Adoption:Seventeen states have adopted California's emissions framework, expanding the addressable market for low-emission used vehicles and creating regulatory pull for compliant inventory.
- Ride-Hailing Fleet Renewal:Cost-control pressures at Uber and Lyft are accelerating procurement of newer used vehicles with remaining factory warranty coverage.
- Digital Retail Infrastructure:Proprietary logistics networks and algorithmic pricing engines are collapsing the cost differential between remote fulfillment and traditional lot purchases.
Market Restraints
- Battery Health Uncertainty:Absence of standardized certification protocols for electric vehicle battery degradation is suppressing residual values and buyer confidence in pre-owned electrified inventory.
- Supply Concentration in Sun Belt States:Texas, Florida, and California account for disproportionate liquidity, leaving buyers in the Midwest and Northeast exposed to higher transport costs and thinner selection.
- FTC Buyer's Guide Friction:Mandatory disclosure requirements add administrative burden to peer-to-peer transactions, pushing volume toward dealer intermediaries.
Strategic Opportunities
- Battery Certification Standards:Early movers in EV battery health verification protocols will capture margin pools as electrified vehicles enter the secondary market in volume.
- Subscription-to-Ownership Conversion:Lease return channels and subscription fleet liquidations are creating captive supply of low-mileage, single-owner inventory.
- Rural Digital Penetration:Underdeveloped secondary markets in Appalachia and the Great Plains present first-mover advantage for remote appraisal and doorstep delivery models.
Industry Challenges
- Technician Shortage for Electrified Powertrains:Independent dealers lack trained staff to assess and recondition battery-electric and plug-in hybrid inventory, constraining participation in the fastest-growing vehicle category.
- Recall Tracking Complexity:NHTSA safety recall databases are incomplete for title-washed and salvage-rebuilt vehicles, exposing retailers to liability and consumers to undisclosed defects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Used Car Market |
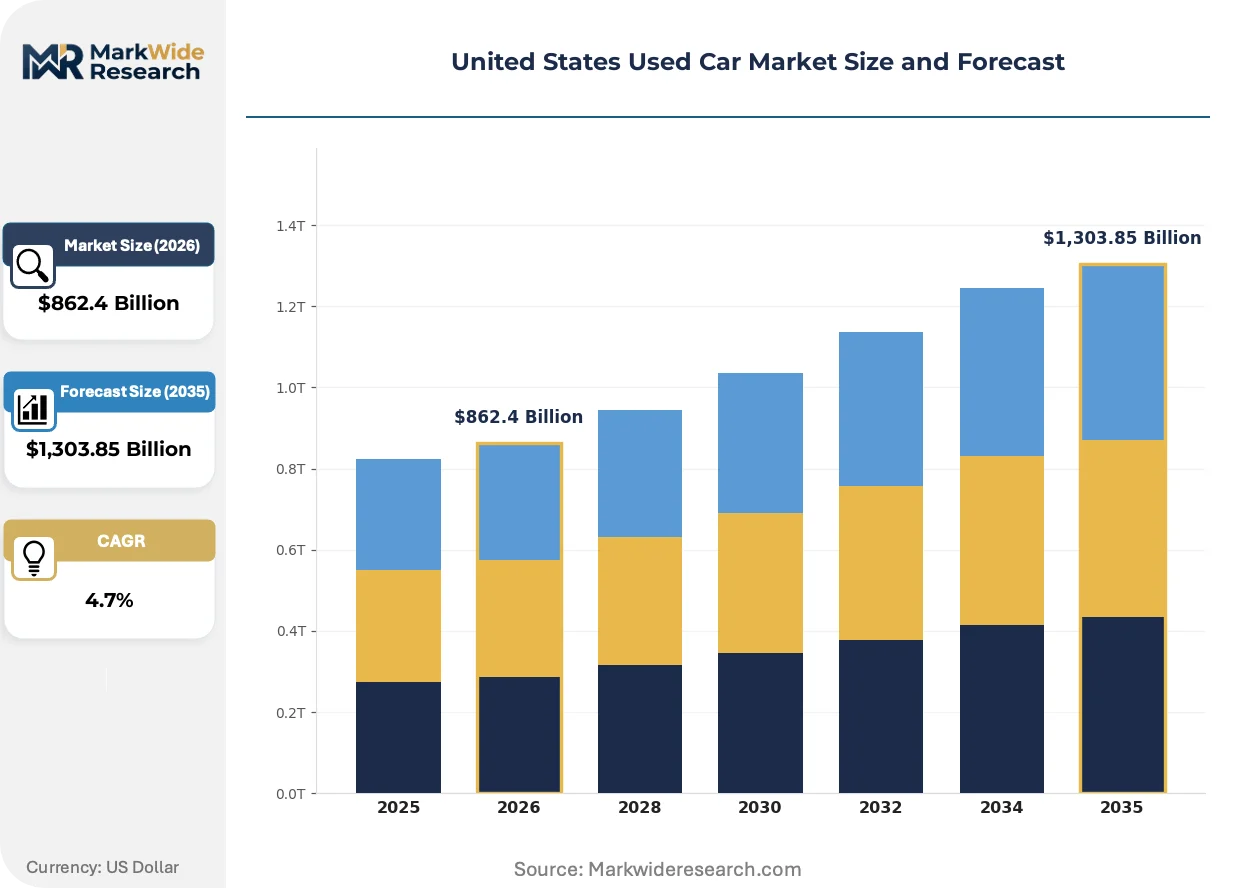
| Market Size in 2026 | $862.4 Billion |
| Market Size in 2035 | $1,303.85 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedans, SUVs, Trucks, Vans Sales Channel: Dealerships, Private Sellers, Auctions, Online Platforms Condition: Certified Pre-Owned, Used, Newer Used, Older Used Price Tier: Budget, Mid-Range, Luxury, Premium |
| Companies Covered | CarMax Inc., Carvana Co., AutoNation Inc., Asbury Automotive Group Inc., Group 1 Automotive Inc., Lithia Motors Inc., Penske Automotive Group Inc., Sonic Automotive Inc., Hendrick Automotive Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Used Car Market Strategic Shifts
Algorithmic pricing and remote fulfillment are collapsing the traditional dealership visit, while electrification and battery health transparency are rewriting valuation methodologies for the pre-owned fleet.
Blockchain-based vehicle history reporting is decentralizing trust away from centralized databases like Carfax and AutoCheck. Independent platforms are enabling peer-to-peer verification of odometer readings, service records, and accident history without intermediary fees. Fleet operators and digital retailers are adopting these tools to reduce data acquisition costs and accelerate transaction velocity.
The EPA's evolving Corporate Average Fuel Economy standards are hardening procurement criteria for commercial buyers. Fleet managers must now document compliance pathways for pre-owned acquisitions, favoring newer model years with advanced powertrains. California and its seventeen adopting states are experiencing accelerated turnover of compliant inventory as CARB-aligned deadlines approach.
Buyers are abandoning multi-dealer comparison shopping in favor of single-platform transaction completion. Digital retailers offering integrated financing, trade-in valuation, and at-home delivery are capturing preference share from franchise-adjacent operations. This channel consolidation is most pronounced in Texas and Florida, where population density and logistics infrastructure support same-week fulfillment economics.
United States Used Car Market Segmentation
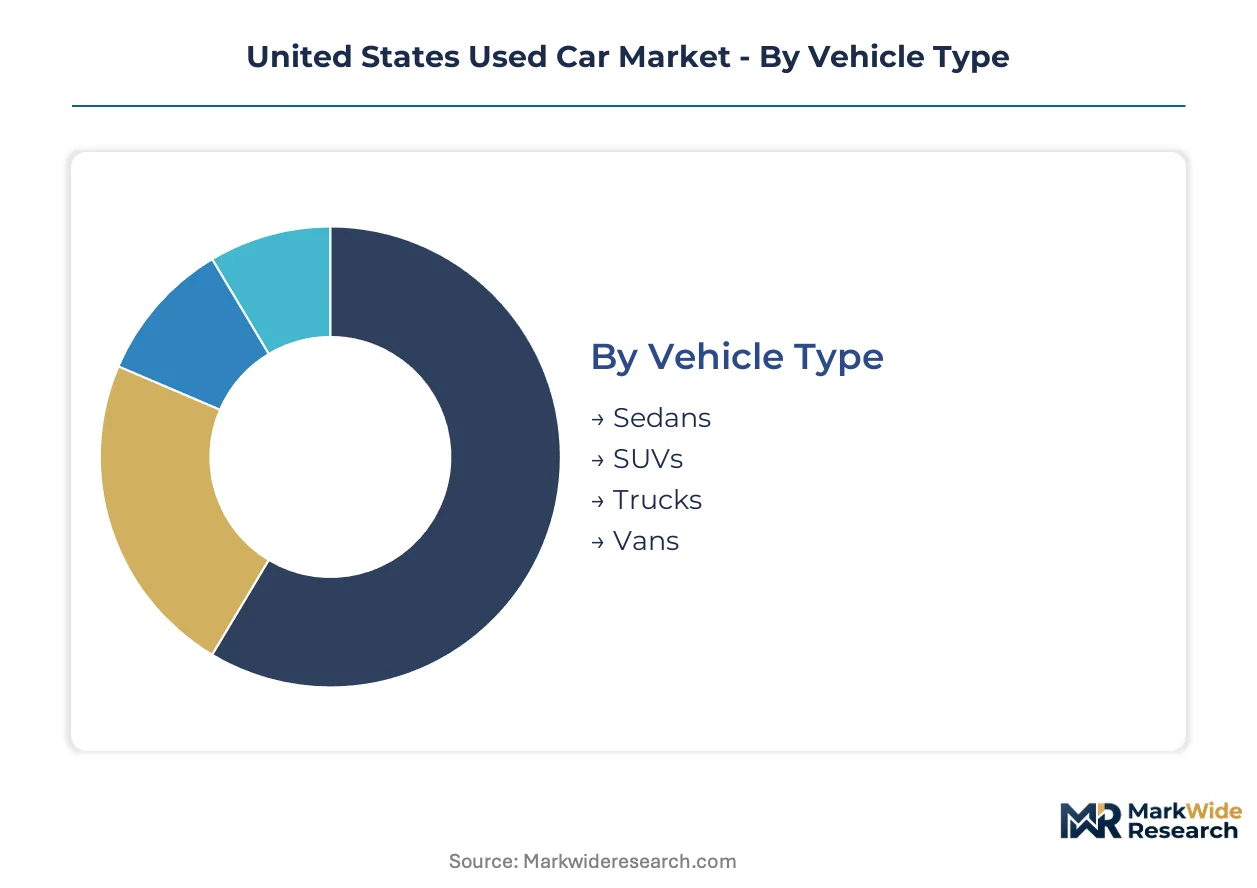
Segmentation in the United States used car market reveals how capital deployment, risk tolerance, and buyer sophistication fragment across distinct procurement channels. Dealers, fleet operators, and individual consumers each prioritize different vehicle attributes, creating parallel submarkets with divergent margin structures and inventory velocity.
Vehicle Type:
Capital intensity varies sharply across body styles, with trucks and SUVs demanding higher per-unit floorplan financing and reconditioning spend than passenger cars.
- SUVs:Unibody and body-on-frame configurations dominate suburban household replacement cycles. Texas and Florida dealerships report strongest throughput for three-row crossovers with towing packages, driven by interstate migration patterns and outdoor recreation demand.
- Trucks:Full-size and midsize pickup segments carry the highest average transaction prices and longest ownership horizons. Fleet operators in construction and energy services concentrate procurement in Texas and California markets where supply liquidity supports volume sourcing.
- Sedans:Passenger car inventory turns faster in urban coastal markets with parking constraints and fuel economy priorities.
- Vans:Commercial cargo and passenger configurations serve last-mile delivery contractors and small business fleets.
Trucks absorb the bulk of installed dealership capacity; SUVs are expanding most quickly.
Sales Channel:
Channel selection determines working capital requirements, with physical dealership networks carrying the heaviest real estate and inventory carrying costs.
- Dealerships:Franchise and independent lots provide mechanical inspection, financing facilitation, and trade-in absorption. Brick-and-mortar operations concentrate in Sun Belt metros where land costs support larger display inventories.
- Online Platforms:Digital retailers collapse geographic search costs through algorithmic matching and proprietary logistics. Carvana and similar operators leverage centralized reconditioning hubs to sustain doorstep delivery economics.
- Private Sellers:Peer-to-peer transactions minimize intermediary margins but impose buyer risk around title clarity and mechanical condition.
- Auctions:Wholesale channels including Manheim and ADESA supply dealer inventory through lane bidding and conditional sales.
Dealerships still transact the majority of volume; online platforms are climbing the fastest.
Condition:
Condition grading dictates reconditioning investment and warranty exposure, with certified inventory requiring the most intensive capital deployment.
- Certified Pre-Owned:Factory-backed programs mandate multi-point inspection, reconditioning to manufacturer standards, and extended warranty coverage. CARB-compliant vehicles in California command premium positioning due to emissions durability requirements.
- Newer Used:Low-mileage, single-owner inventory from lease returns and subscription fleet liquidations offers residual factory warranty protection.
- Used:Standard pre-owned vehicles without certification carry higher buyer risk and correspondingly compressed pricing.
- Older Used:High-mileage inventory serves credit-constrained buyers and secondary markets with thinner selection.
Certified Pre-Owned captures disproportionate margin pools; Newer Used is gaining share fastest.
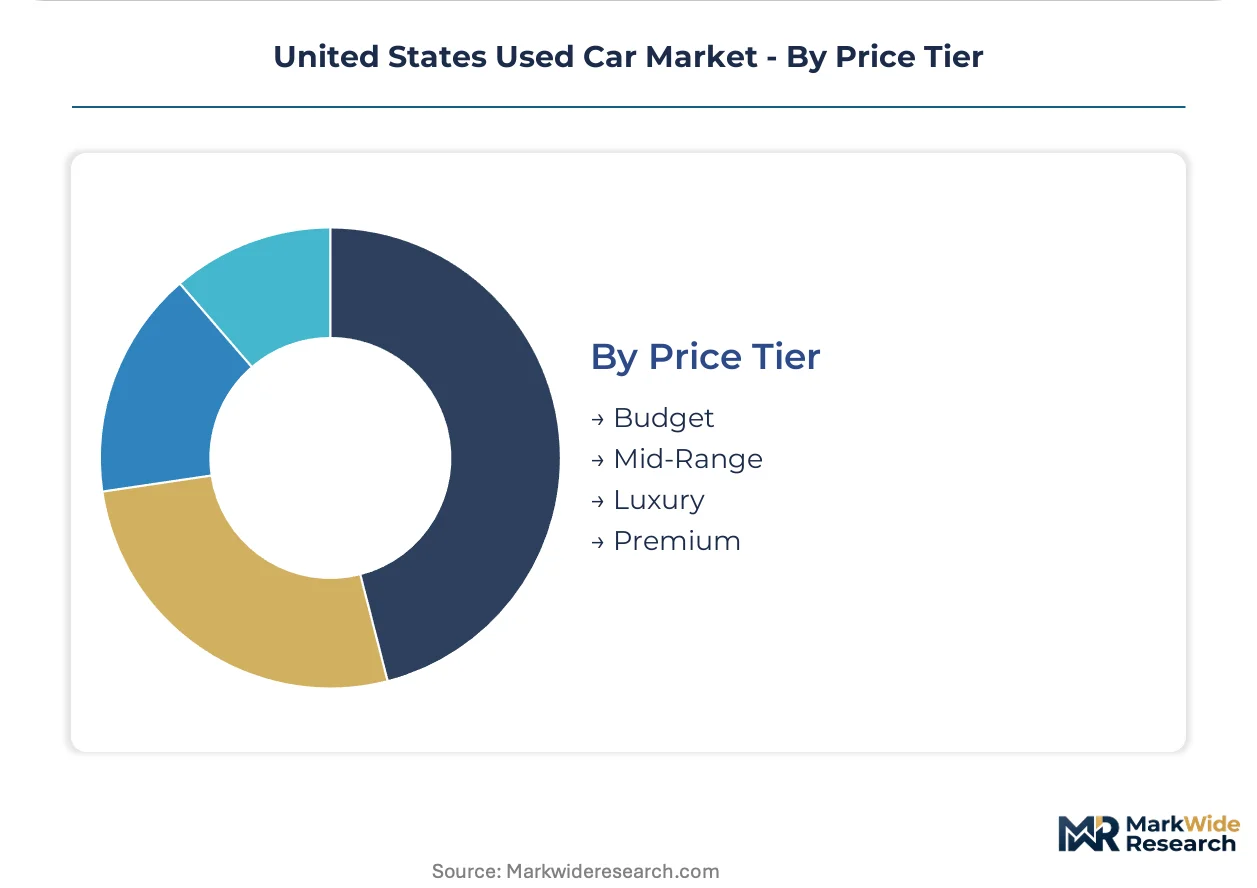
Price Tier:
Price stratification aligns with buyer credit profiles and intended use duration, with luxury segments requiring specialized appraisal expertise.
- Luxury:Premium marques including Mercedes-Benz, BMW, and Lexus retain value through brand equity and technology content. California and Florida markets show deepest liquidity for German and Japanese luxury inventory.
- Premium:Near-luxury brands bridge mass-market and entry-luxury positioning, appealing to aspirational trade-up buyers.
- Mid-Range:Mainstream brands including Toyota, Honda, and Ford constitute the transaction volume core.
- Budget:Sub-$15,000 inventory serves first-time buyers, cash purchasers, and subprime financing segments.
Mid-Range absorbs the bulk of transaction volume; Luxury is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors the nation's largest concentration of used truck and fleet vehicle transactions, with dealership density and energy sector procurement sustaining liquidity unmatched elsewhere.
Texas
Interstate migration from California and New York is flooding Dallas-Fort Worth and Houston with trade-in inventory. The Texas Commission on Environmental Quality enforces emissions testing in metro counties, compressing demand for older diesel trucks. San Antonio dealerships report fastest inventory turns for three-row SUVs serving expanding suburban households.
Florida
Retiree-driven replacement cycles in Tampa and Orlando sustain demand for low-mileage sedans and crossovers. The Florida Department of Highway Safety and Motor Vehicles mandates rebuilt title disclosure, raising transaction friction for salvage-history inventory. Miami-Dade operators concentrate on certified pre-owned luxury vehicles serving Latin American export demand.
California
CARB compliance deadlines are accelerating turnover of pre-2020 inventory in Los Angeles and San Francisco Bay Area markets. The California Air Resources Board enforces the nation's strictest used vehicle emissions standards, elevating pricing power for compliant SUVs and trucks. Central Valley dealers absorb price-sensitive demand for older used vehicles excluded from coastal metro markets.
Southeast
Atlanta and Charlotte logistics corridors enable rapid inventory redistribution across Georgia, South Carolina, and North Carolina. State lemon laws vary in coverage duration, fragmenting warranty exposure for multi-state operators. Nashville and Birmingham emerging as secondary sourcing hubs as primary market prices firm.
Midwest
Chicago and Detroit manufacturing heritage sustains technician density supporting complex reconditioning operations. Illinois and Michigan emissions testing regimes are less stringent than CARB states, preserving demand for older used vehicles. Cleveland and Indianapolis dealers face higher transport costs sourcing liquid inventory from Sun Belt markets.
United States Used Car Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and financing infrastructure. National superstore chains consolidate volume through captive lending and centralized reconditioning, while regional independents compete on local sourcing relationships and trade-in absorption. Three archetypes dominate: digital-native remote fulfillment operators, franchise-adjacent certified pre-owned specialists, and multi-state dealership groups leveraging scale purchasing. Competitive moves center on proprietary logistics network expansion and subscription fleet liquidation partnerships.
Within the national superstore tier, CarMax Inc. and Carvana Co. represent contrasting fulfillment models—physical saturation versus algorithmic remote delivery. AutoNation Inc. anchors the franchise-adjacent certified pre-owned segment through brand-aligned inspection protocols. These three operators exemplify how capital deployment in reconditioning infrastructure and financing captive creation separates margin tiers from commodity-positioned independents.
| Leading Market Players |
|---|
| CarMax Inc. |
| Carvana Co. |
| AutoNation Inc. |
| Asbury Automotive Group Inc. |
| Group 1 Automotive Inc. |
| Lithia Motors Inc. |
| Penske Automotive Group Inc. |
| Sonic Automotive Inc. |
| Hendrick Automotive Group |
| Others |
Value Chain & Pricing Dynamics
Fleet operators' tightening cost-control mandates are compressing procurement budgets for commercial used vehicle acquisitions, forcing supply networks to prioritize newer, low-mileage inventory with remaining factory warranty coverage and elevating transaction prices for compliant stock.
Pricing Analysis
Certification-backed throughput anchors value-based pricing in the United States used car market. Three-tier pricing structure across certified pre-owned, newer used, and standard used levels separates warranty-backed assurance from depreciation-exposed inventory. Price differentiation stems from CARB compliance status and reconditioning depth. Cost compression in standard used tiers is intensifying because EPA emissions timelines are disqualifying older powertrains. Subprime financing segments exhibit highest price sensitivity; fleet procurement managers show lowest.
Supply Chain Analysis
Dual-sourcing requirements from national dealership groups mandate multi-auction qualification across Manheim and ADESA networks to mitigate lane concentration risk. Wholesale supply concentrates in Texas, Florida, and California. Inventory sourcing rests on lease return channels, rental fleet liquidations, and trade-in absorption. Single-source vulnerability emerges from transport cost asymmetry favoring Sun Belt markets. Distribution runs through centralized reconditioning hubs feeding doorstep delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States used car market sits in a technology-transition phase as battery-electric and plug-in hybrid powertrains displace internal combustion engine dominance in secondary market flows.
For Market Incumbents: Hedge against electrification technician scarcity by building captive reconditioning partnerships with OEM-authorized service networks. Secure battery health certification capabilities before standardized protocols emerge, as independent dealers lacking EV assessment capacity face exclusion from fastest-growing vehicle categories. For New Entrants and Emerging Players: Launch via remote appraisal and doorstep delivery models targeting rural Appalachian and Great Plains markets where digital penetration remains underdeveloped. White-space concentration in secondary sourcing hubs like Nashville and Birmingham offers first-mover logistics infrastructure advantages. For Investors and Strategic Acquirers: The window for entry favors digital-native operators with proprietary logistics networks and subscription fleet liquidation partnerships. Battery certification standardization and CARB deadline acceleration serve as inflection indicators for portfolio rebalancing toward electrified inventory exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Health Certification Program | Early movers capture margin pools as EVs enter secondary market volume. |
| Subscription Fleet Liquidation Partnership | Captive supply of low-mileage, single-owner inventory secures reconditioning pipeline. |
| Rural Digital Penetration Expansion | Remote appraisal models collapse geographic search costs in underserved markets. |
| Proprietary Logistics Network Buildout | Doorstep delivery economics depend on centralized hub density and route optimization. |
| CARB-Compliant Inventory Concentration | Seventeen-state regulatory alignment elevates pricing power for compliant powertrains. |
Study Parameters
Document review covered NHTSA recall databases, EPA emissions compliance filings, and state-level DMV transaction records, complemented by interviews with dealership operations directors, fleet procurement managers, digital retail platform executives, and auction lane managers. Secondary validation drew from vehicle registration data, floorplan financing disclosures, and trade association volume reports. Bottom-up transaction modeling and top-down market sizing were triangulated against independent reconditioning cost benchmarks.
Cross-referencing historical pricing spreads with panel input from wholesale buyers informed the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle type, sales channel, condition grade, and price tier. CAGRs were derived from regression analysis of transaction velocity and inventory age curves. Electrification residual value trajectories and battery degradation assumptions served as category-specific forecast inputs.
EPA regulatory acceleration, battery certification protocol delays, and regional migration pattern shifts are the dominant revision risks to modeled outcomes. Deviation in electrification adoption timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Vintage Car Market
Used Vehicles
Russia Used Car Market
Used Vehicles
Ethiopia Used Car Market
Used Vehicles
Online Car Buying Market
Used Vehicles
GCC Used Car Market
Used Vehicles
France Used Car Market
Used Vehicles
Thailand Used Car Market
Used Vehicles
Italy Used Car Market
Used Vehicles
Germany Used Car Market
Used Vehicles
Indonesia Used Car Market
Used Vehicles
Philippines Used Car Market
Used Vehicles
Norway Used Car Market
Used Vehicles
Europe Used Car Market
Used Vehicles
Global Online Second-Hand Car Trading Service Market
Used Vehicles
Used E-Scooter Market
Used Vehicles
Japan Used Car Market