
 South Korea Used Car Market | 2026-2036
South Korea Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Used Car Market Insights
MFDS vehicle safety certification requirements and KBA-equivalent inspection protocols are shifting the cost-of-entry calculus for smaller dealers who must now invest in diagnostic infrastructure. KB Cha Cha Cha leverages its banking parentage to offer integrated financing that anchors customer retention across the transaction cycle. Encar dominates the digital auction layer, while K Car specializes in certified pre-owned inspection standards that differentiate its inventory quality.
A used car denotes a previously registered automobile that has undergone at least one ownership transfer, typically assessed through odometer verification, chassis integrity inspection, and powertrain diagnostic evaluation before re-entry into commercial circulation. These vehicles serve budget-constrained consumers and fleet operators seeking depreciated assets with retained functional utility. SUV listings command structural premium positioning due to family-buyer preference and residual value stability, while hybrid powertrains represent the fastest-growing fuel category as Seoul's emission-zone restrictions tighten. Online sales channels capture expanding margin pools by disintermediating traditional dealership overhead.
MFDS inspection mandates, Ministry of Environment emission-grade classifications, and Korea Consumer Agency disclosure requirements collectively shape product eligibility and seller liability across the resale chain. Seoul metropolitan emission zones now exclude certain diesel grades, redirecting demand toward certified hybrid and petrol inventory. Stakeholders must monitor regulatory calibration between inspection stringency and platform compliance costs to preserve transaction velocity without eroding dealer participation.
Market Dynamics
MFDS inspection mandates and Seoul's emission-zone restrictions are compressing dealer margins while redirecting inventory flows toward certified hybrid and petrol vehicles. The regulatory calibration between inspection stringency and platform compliance costs now determines which sellers can maintain transaction velocity.
Growth Catalysts
- MFDS Safety Certification:Mandatory diagnostic infrastructure investments by smaller dealers are filtering substandard inventory from metropolitan resale channels. This elevates average transaction quality and buyer confidence.
- Fleet Operator Procurement:Ride-hailing services and corporate fleet managers are expanding pre-owned vehicle acquisition as a depreciation-hedging strategy. Their volume purchasing stabilizes wholesale price floors.
- Digital Platform Penetration:Online auction and listing platforms in the greater Seoul metropolitan area are disintermediating traditional dealership overhead. This margin capture accelerates seller migration to digital channels.
Market Restraints
- Diagnostic Equipment Costs:MFDS-mandated inspection infrastructure requires capital outlays that strain smaller independent dealers. This cost barrier consolidates seller participation toward platform-backed operators.
- Seoul Emission-Zone Exclusions:Ministry of Environment diesel-grade restrictions render certain inventory ineligible for metropolitan resale. This geographic eligibility compression narrows addressable demand pools for affected vehicle categories.
- Residual Value Uncertainty:Battery degradation diagnostics for hybrid powertrains lack standardized assessment protocols. This information asymmetry depresses pricing transparency for the fastest-growing fuel category.
Strategic Opportunities
- Certified Pre-Owned Standards:Differentiated inspection protocols create quality-tier segmentation that commands pricing premiums. K Car's specialization in this layer demonstrates viable margin expansion.
- Integrated Financing Ecosystems:Banking-parented platforms can anchor customer retention across the full transaction cycle. This captive finance model reduces customer acquisition costs and default rates.
- Provincial Market Expansion:Digital platform penetration and vehicle turnover rates in non-Seoul provinces lag the capital region. This geographic underpenetration offers first-mover expansion corridors.
Industry Challenges
- Technician Certification Bottlenecks:MFDS-compliant diagnostic assessment requires specialized training that outpaces current vocational pipeline output. This skill scarcity inflates labor costs and inspection turnaround times.
- Legacy System Integration:Traditional auction houses and independent dealers face friction migrating inventory data to platform-native formats. This technical debt slows omnichannel deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Used Car Market |
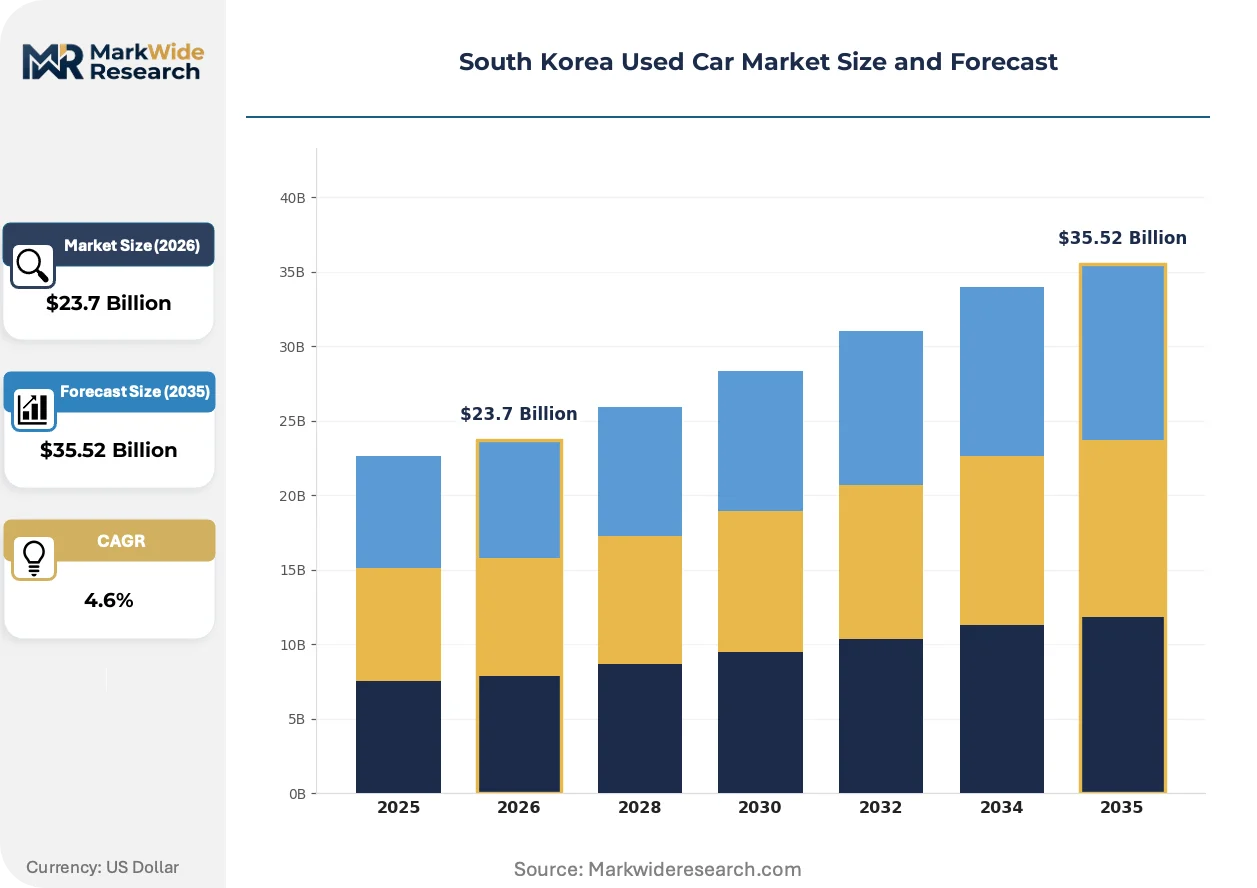
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $35.52 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Fuel Type: Petrol, Diesel, Hybrid, Electric Distribution Channel: Online Sales, Dealerships, Auctions, Private Sellers Condition: Certified Pre-Owned, As-Is, Damaged, refurbished |
| Companies Covered | KB Cha Cha Cha, K Car, Encar, Hyundai Glovis, HeyDealer, Used Car Korea, Be Forward, PicknBuy24, Han Sung Motor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Used Car Market Trends and Innovations
Platform-based transaction architectures are restructuring how inventory discovery, financing, and post-sale service bundle together. Three developments are compressing traditional dealer value capture.
AI-powered vehicle condition assessment is overtaking manual inspection protocols for initial listing quality grading. Fleet operators and digital platforms are adopting computer-vision diagnostics to standardize remote evaluation. This compression of assessment labor is enabling same-day listing velocity that manual processes cannot match.
Seoul's metropolitan emission-zone restrictions now exclude certain diesel grades entirely. The Ministry of Environment's classification framework redirects demand toward certified hybrid and petrol inventory. Dealers holding non-compliant stock must redirect toward provincial channels or absorb write-downs.
Subscription-based vehicle access models are fragmenting traditional ownership cycles among younger metropolitan buyers. Platform-native operators are bundling insurance, maintenance, and upgrade rights into monthly fees. This behavior shift is most visible in Seoul's dense apartment districts where parking scarcity and usage optimization outweigh ownership preference.
South Korea Used Car Market Segmentation
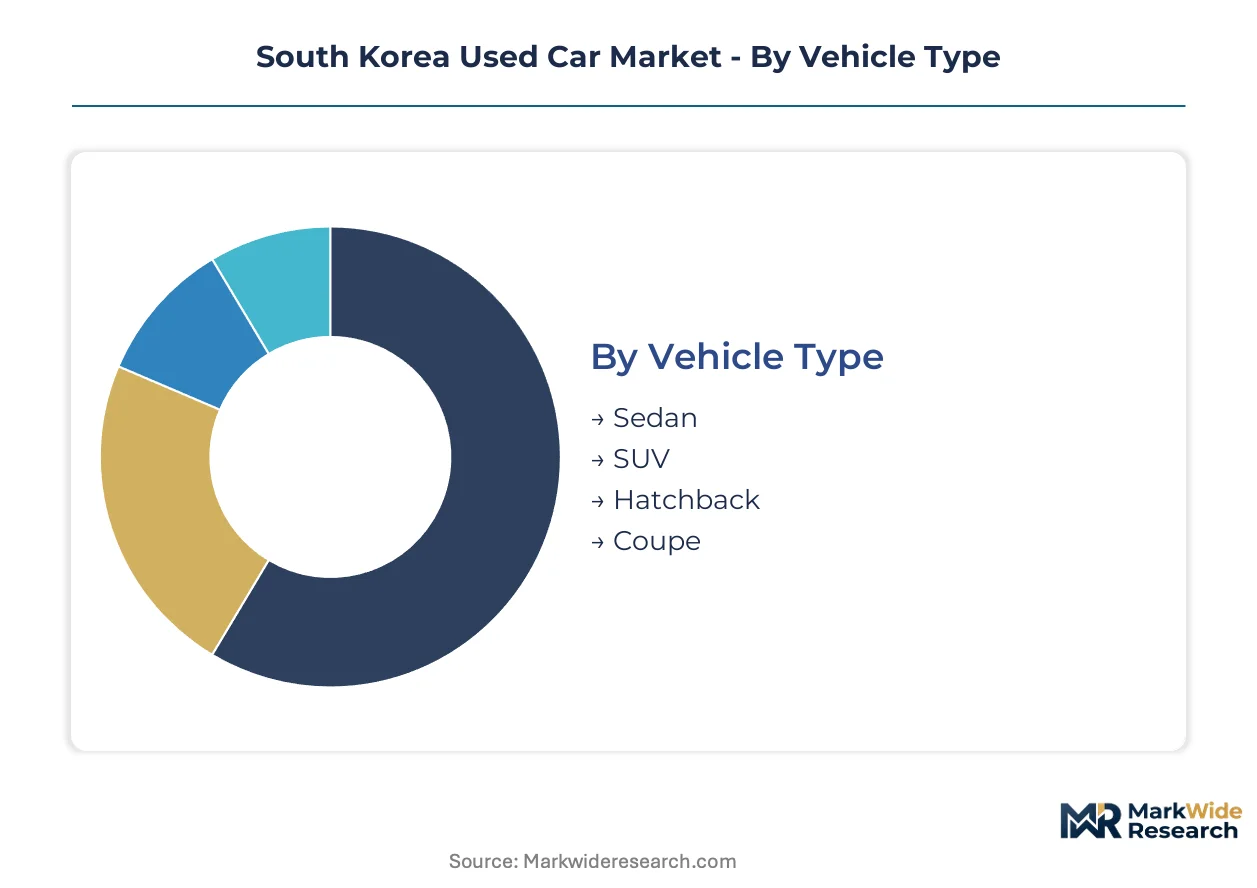
Segmentation in the South Korea used car market determines which inventory qualifies for Seoul's emission zones and which channels can absorb compliance costs. Understanding these divisions reveals where capital requirements concentrate and where margin expansion remains viable.
Vehicle Type:
Capital intensity varies sharply across body styles, with larger platforms demanding heavier reconditioning investments before MFDS certification.
- SUV:Higher ground clearance and structural reinforcements require specialized lift equipment and chassis inspection protocols. Family buyers in Seoul's satellite cities drive demand, though parking constraints in dense districts limit addressable households.
- Sedan:Three-box configurations dominate fleet operator procurement due to standardized maintenance schedules and parts availability. Corporate leasing returns feed steady wholesale volume into digital auction channels.
- Hatchback:Compact footprints suit younger metropolitan buyers facing parking scarcity; lower price points reduce financing friction.
- Coupe:Low-volume specialty segment with concentrated demand among enthusiast buyers; limited inspection infrastructure outside capital region.
SUV absorbs the bulk of installed reconditioning capacity; Hatchback is expanding most quickly among first-time metropolitan buyers.
Fuel Type:
Regulatory compliance costs stratify sharply across powertrain categories, with emission-grade classifications determining metropolitan eligibility.
- Hybrid:Dual-powertrain architectures require battery diagnostic infrastructure that smaller dealers cannot afford. Seoul's emission-zone restrictions redirect demand toward certified hybrid inventory, though residual value uncertainty persists without standardized degradation assessment.
- Petrol:Conventional internal combustion engines face lighter compliance burdens and maintain broad geographic eligibility. Provincial resale channels absorb significant petrol volume excluded from Seoul's stricter zones.
- Diesel:Ministry of Environment grade restrictions render certain diesel stock ineligible for metropolitan resale; dealers must redirect toward secondary cities or absorb write-downs.
- Electric:Battery state-of-health verification demands specialized equipment; limited charging infrastructure outside Seoul constrains buyer pools.
Petrol retains the deepest buyer pool across all provinces; Hybrid climbs the fastest as Seoul tightens emission-zone enforcement.
Distribution Channel:
Platform infrastructure investments separate scalable operators from margin-constrained traditional sellers.
- Online Sales:Digital-native platforms capture margin pools by disintermediating dealership overhead; same-day listing velocity exceeds manual auction processes.
- Dealerships:Brick-and-mortar operations bear fixed real estate costs that compress returns in price-transparent digital environments.
- Auctions:Wholesale price discovery remains concentrated among fleet operators and platform-backed dealers with volume purchasing power.
- Private Sellers:Peer-to-peer transactions bypass inspection mandates but carry information asymmetry risks that depress realized prices.
Online Sales captures the steepest expansion trajectory; Auctions retain dominant wholesale volume.
Condition:
Certification tier determines pricing power and buyer financing access.
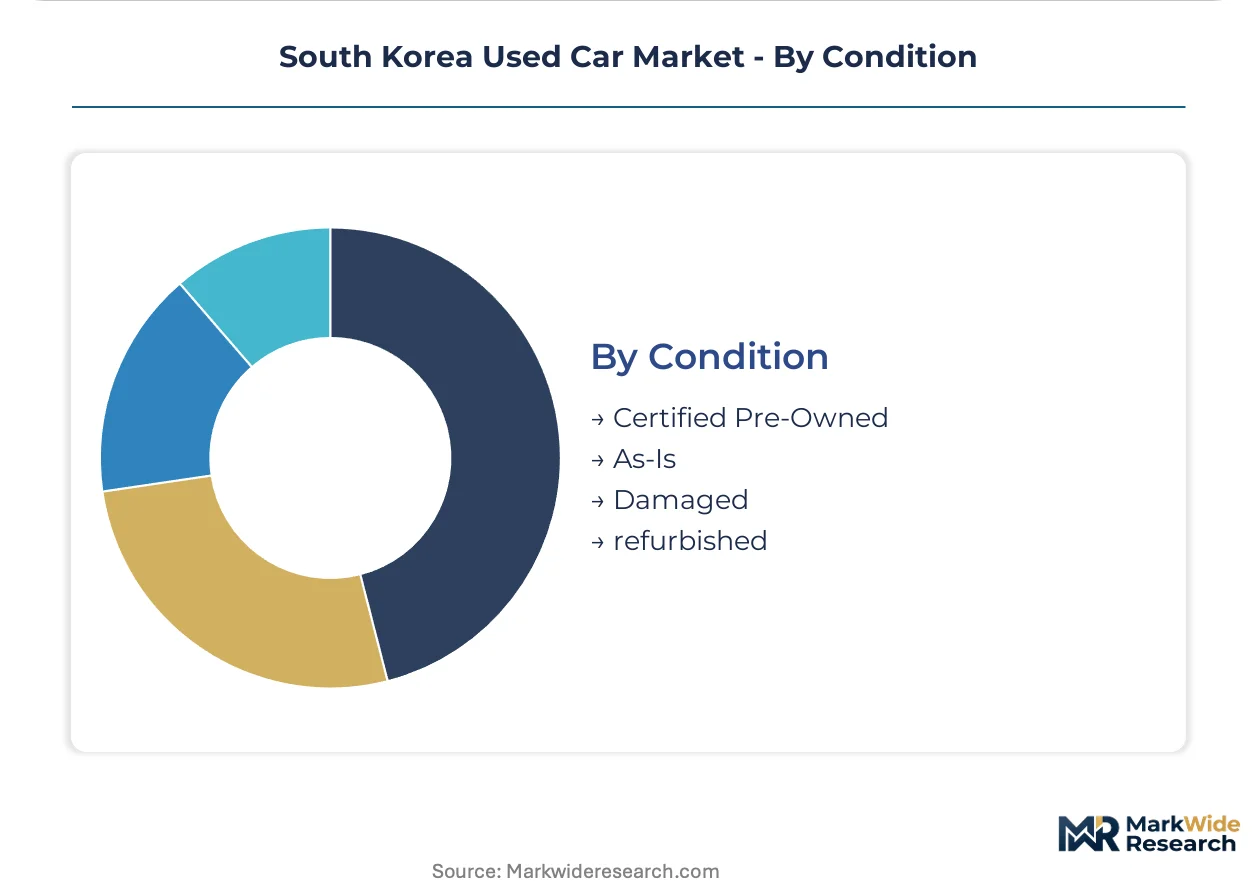
- Certified Pre-Owned:MFDS-compliant inspection protocols command structural premiums; integrated financing ecosystems anchor customer retention.
- As-Is:Unwarranted inventory trades at discount to certified stock; buyer assumes full mechanical risk.
- Damaged:Salvage-grade vehicles require disclosure compliance under Korea Consumer Agency requirements; specialized rebuilders dominate this layer.
- Refurbished:Post-collision restoration demands parts traceability documentation; warranty backing varies by rebuilder certification.
Certified Pre-Owned absorbs premium buyer demand; Refurbished gains traction among price-sensitive segments seeking near-new appearance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's green vehicle zones and MFDS inspection mandates concentrate transaction velocity in the capital region while compressing dealer margins in excluded areas.
Seoul Capital Area
Metropolitan emission-zone restrictions redirect demand toward certified hybrid and petrol inventory. MFDS safety certification requirements filter substandard vehicles from resale channels. Digital platform penetration and vehicle turnover rates in Seoul, Incheon, and Gyeonggi Province outpace all other regions.
Busan-Ulsan
Port logistics infrastructure supports import-export vehicle flows and wholesale auction activity. Ministry of Environment grade classifications determine which diesel stock qualifies for metropolitan resale versus provincial redirection. Ulsan's automotive manufacturing heritage sustains specialized reconditioning capacity for fleet operator procurement.
Daegu-Gyeongbuk
Lower real estate costs attract independent dealers displaced from Seoul's compliance-intensive environment. Korea Consumer Agency disclosure requirements apply uniformly but diagnostic infrastructure investments strain smaller operators. Daegu's emerging platform-backed dealer networks absorb inventory excluded from capital-region channels.
Daejeon-Sejong
Government administrative concentration generates steady corporate leasing returns feeding wholesale volume. Administrative vehicle fleets standardize on petrol and hybrid powertrains to maintain Seoul eligibility. Sejong's planned city design accommodates parking-scarce households receptive to subscription-based vehicle access models.
Gwangju-Honam
Agricultural and light industrial vehicle demand sustains diesel inventory absorption outside emission-restricted zones. Provincial resale channels capture volume rendered ineligible for metropolitan circulation. Gwangju's dealer base faces lower compliance costs but limited access to integrated financing ecosystems concentrated in the capital.
South Korea Used Car Market Competitive Landscape
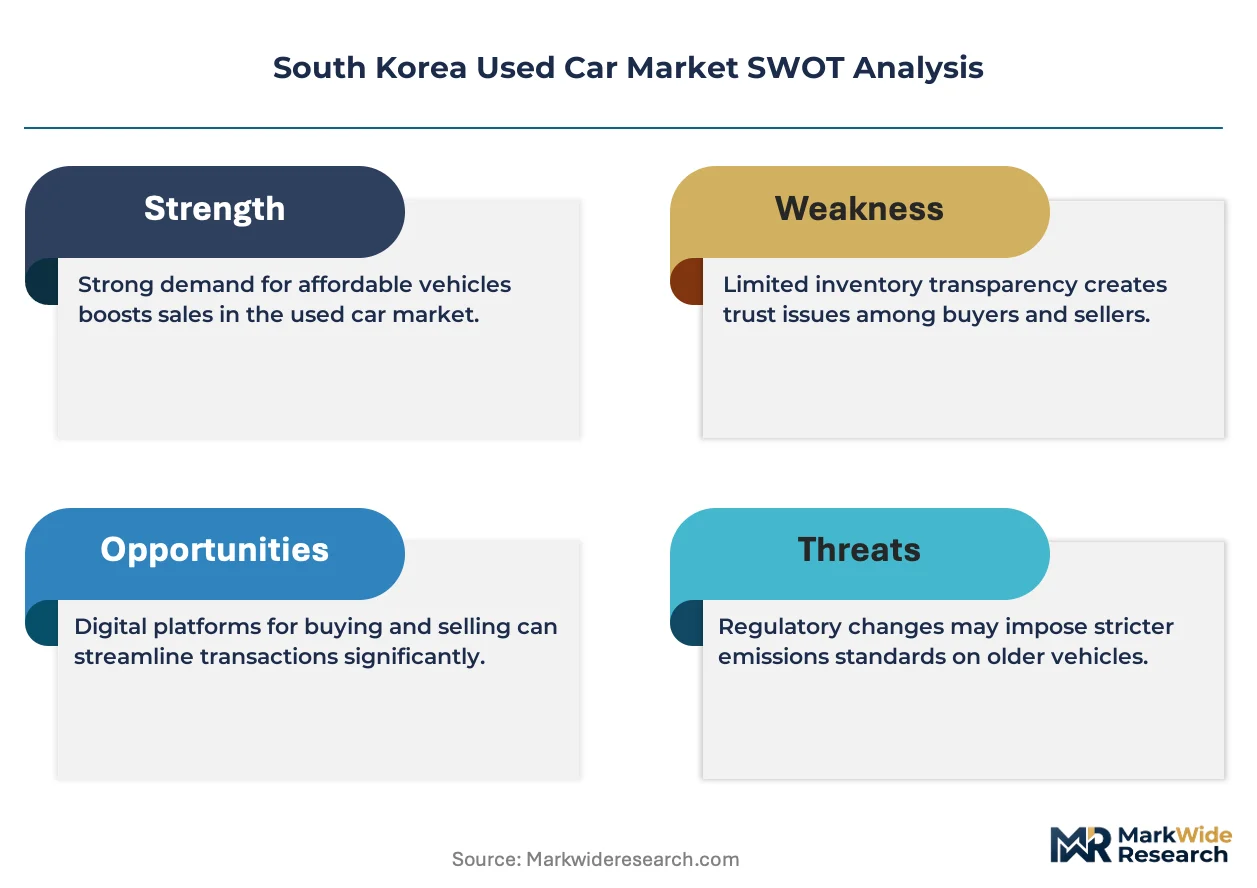
Diversified conglomerates compete with focused pure-play specialists across inspection, financing, and digital auction layers. Banking-parented platforms leverage captive finance to anchor customer retention, while automotive logistics arms exploit fleet procurement relationships. Three archetypes dominate: vertically integrated inspection-certification operators, banking-hybrid financing platforms, and digital-native auction exchanges. Competitive moves concentrate on diagnostic infrastructure buildout and provincial dealer network expansion.
Within the banking-hybrid tier, KB Cha Cha Cha exemplifies integrated financing ecosystems that reduce customer acquisition costs across transaction cycles. Encar and K Car occupy distinct positions in digital auction infrastructure and certified pre-owned inspection standards respectively. These three entities anchor the market's platform consolidation trajectory while smaller independents face MFDS-mandated capital barriers.
| Leading Market Players |
|---|
| KB Cha Cha Cha |
| K Car |
| Encar |
| Hyundai Glovis |
| HeyDealer |
| Used Car Korea |
| Be Forward |
| PicknBuy24 |
| Han Sung Motor |
| Others |
Pricing and Supply Chain Analysis
Steel price fluctuations cascade through South Korea's used car reconditioning sector, compressing margins for independent dealers while amplifying pricing power for platform-backed operators with captive body shop networks. The cost pass-through from sheet metal and catalytic converter materials stratifies final transaction prices across certified, as-is, and salvage-grade inventory tiers.
Pricing Analysis
Short lead-time premiums dominate transaction economics, with same-day certified inventory commanding structural markups over auction-cycle units requiring reconditioning. Three-tier pricing structure across certified pre-owned, standard inspected, and as-is economy levels reflects MFDS compliance cost absorption. Price differentiation hinges on diagnostic certification depth and integrated financing bundling. Cost compression in economy tiers intensifies because smaller dealers cannot amortize inspection infrastructure across volume. Fleet operators exhibit lowest price sensitivity; first-time metropolitan buyers face highest financing friction.
Supply Chain Analysis
Dual-sourcing requirements from fleet operators and platform aggregators mandate multi-dealer qualification, preventing single-source dependency in wholesale channels. Inventory concentration centers on Seoul, Incheon, and Gyeonggi Province for emission-compliant hybrid and petrol stock; Busan-Ulsan handles diesel redirection. Parts and reconditioning inputs draw from domestic suppliers, Japanese component manufacturers, and Chinese aftermarket producers. Single-source vulnerability persists in battery diagnostic equipment for hybrid certification. Distribution runs through digital auction platforms, dealership networks, and direct fleet procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's used car market sits in a technology-transition phase, with AI-powered condition assessment displacing manual inspection protocols and compressing traditional dealer value capture.
For Market Incumbents: Deploy diagnostic infrastructure scale as the anchor lever. Platform-backed operators should consolidate independent dealer networks facing MFDS capital barriers. Encar and K Car must deepen backward integration into reconditioning capacity to defend margin position against pure-play digital entrants. Certification investment in battery health assessment protocols addresses residual value uncertainty threatening hybrid category expansion. For New Entrants and Emerging Players: Provincial fleet operators outside Seoul's emission zones represent the most penetrable buyer archetype. Daegu-Gyeongbuk and Gwangju-Honam channels absorb diesel inventory excluded from metropolitan circulation, offering first-mover positioning. Subscription-based vehicle access models for parking-scarce Sejong households provide alternative revenue architecture bypassing traditional ownership cycle competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor platform-backed dealers with integrated financing ecosystems in Busan-Ulsan logistics corridors. Long-term viability hinges on regulatory compliance automation and provincial network density. The inflection signal to watch is MFDS inspection mandate enforcement intensity affecting smaller dealer survival rates.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Condition Assessment Deployment | Computer-vision diagnostics from Encar and K Car compress manual inspection labor and accelerate listing velocity. |
| Certified Pre-Owned Standard Expansion | MFDS-compliant inspection protocols from K Car create quality-tier segmentation commanding structural pricing premiums. |
| Integrated Financing Ecosystem Buildout | KB Cha Cha Cha's banking-parented model anchors customer retention and reduces acquisition costs across transaction cycles. |
| Provincial Dealer Network Consolidation | Platform-backed operators acquire independent dealers displaced by Seoul emission-zone restrictions and diagnostic capital barriers. |
| Battery Health Diagnostic Infrastructure | Specialized hybrid assessment equipment addresses residual value uncertainty in the fastest-growing fuel category. |
Research Methodology
Independent corroboration across dealership operations executives, fleet procurement managers, platform engineering leads, and MFDS compliance officers underwrites the qualitative findings. Secondary validation draws from Korea Consumer Agency disclosure filings, Ministry of Environment emission-grade classifications, vehicle registration databases, and digital platform transaction records. Bottom-up dealer network mapping and top-down market sizing triangulate volume and value estimates.
Comparable-period anchoring aligned the projection horizon to historical turnover velocity and regulatory implementation timelines. The analytical framework segments by vehicle type, fuel category, distribution channel, and certification condition across the modeling period. CAGRs derive from trend extrapolation adjusted for emission-zone enforcement intensity and platform penetration trajectories. Hybrid powertrain adoption curves and diagnostic infrastructure deployment rates feed category-specific growth inputs.
Revisions become necessary when MFDS inspection mandate calibration, Seoul emission-zone expansion, or battery diagnostic standardization materialize differently than assumed. Deviation in regulatory enforcement intensity or platform consolidation velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Used Cars in Russia Market
Used Vehicles
Myanmar Used Car Market
Used Vehicles
Oman Used Car Market
Used Vehicles
France Used Car Market
Used Vehicles
Russia Used Car Market
Used Vehicles
Middle East and Africa Used Car Market
Used Vehicles
Spain Used Car Market
Used Vehicles
South Africa Used Car Market
Used Vehicles
Singapore Used Car Market
Used Vehicles
Bangladesh Used Car Market
Used Vehicles
North America Used Truck Market
Used Vehicles
Malaysia Used Car Market
Used Vehicles
Japan Used Car Market
Used Vehicles
Nigeria Used Car Market
Used Vehicles
Brazil Used Car Market
Used Vehicles
Belgium Used Car Market