
 Italy Used Car Market | 2026-2036
Italy Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Used Car Market Outlook
Buyer fragmentation across digital-native consumers and small fleet operators is expanding the addressable market for used vehicle transactions. AUTO1 Group leverages its pan-European logistics platform to standardize pricing transparency across Italian regions. Brumbrum anchors its growth on subscription-to-ownership conversion models that reduce friction for younger demographics. BCA Italia dominates the auction channel, controlling wholesale supply flows into dealer networks.
Italy used cars comprise pre-owned passenger vehicles assessed by age, mileage, mechanical condition, and emissions compliance prior to resale. Vehicles undergo mandatory revisione inspections under Ministry of Transport protocols to verify roadworthiness and exhaust standards. SUVs and hybrids represent the fastest-expanding fuel-type and body-style intersections, as diesel retention weakens in urban zones. Online platforms capture disproportionate growth in the sales channel matrix, though dealerships sustain margin pools through financing attachment and certified pre-owned programs.
Italy's Ministry of Transport enforces periodic technical inspections that filter unsafe vehicles from circulation, while EU Green Deal emissions benchmarks push municipalities toward low-emission zones in Rome, Milan, and Naples. The national competition authority monitors platform pricing algorithms to prevent collusive behavior among consolidated dealers. Stakeholders must track how Turin and Bologna implement congestion charging, as these policies directly reshape vehicle depreciation curves and regional inventory allocation decisions.
Market Dynamics
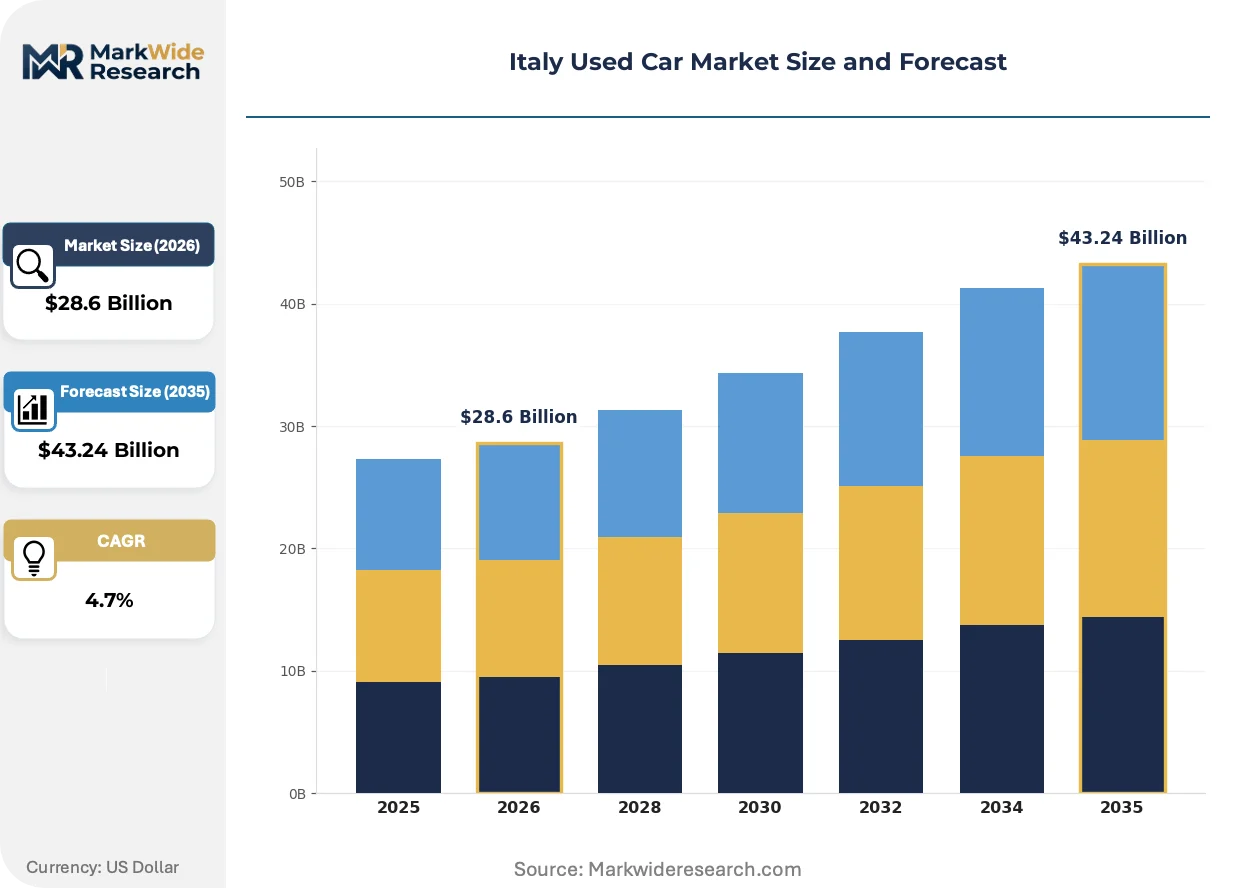
Italy's used car market is restructuring around EU Green Deal emissions benchmarks that compress diesel residual values while elevating hybrid and low-mileage petrol inventory premiums across northern industrial corridors.
Growth Catalysts
- EU-mandated CO2 standards:Fleet operators in Milan and Turin are accelerating replacement cycles to preempt Zona a Traffico Limitato restrictions, flooding the secondary market with three-to-five-year-old vehicles.
- Subscription-to-ownership conversion:Digital-native platforms are capturing first-time buyers through flexible tenure models that reduce upfront capital barriers for younger demographics in Bologna and Florence.
- Periodic revisione inspection protocols:Ministry of Transport enforcement is filtering unsafe vehicles from circulation, creating certified inventory scarcity that supports pricing discipline for compliant stock.
Market Restraints
- Diesel depreciation acceleration:Rome, Milan, and Naples low-emission zones are collapsing demand for pre-Euro 6 diesel powertrains, forcing inventory markdowns that erode dealer margin pools.
- Wholesale auction concentration:BCA Italia controls dominant auction flows into dealer networks, creating supply-side dependency that limits independent retailers' procurement flexibility.
- Emissions compliance verification costs:Revisione testing for CO2 and NOx thresholds adds per-unit inspection overhead that compresses profitability on sub-premium price-tier vehicles.
Strategic Opportunities
- Piedmont and Lombardy corridor expansion:Turin-Milan logistics density supports same-day inventory transfers that enable just-in-time restocking for suburban dealership networks.
- Hybrid powertrain arbitrage:EU Green Deal incentives are redirecting procurement toward petrol-electric vehicles that retain residual value advantage over pure combustion equivalents.
- Direct-to-consumer platform channels:Online marketplaces are disintermediating traditional dealer networks, capturing margin that previously accrued to physical showroom intermediaries.
Industry Challenges
- Technician specialization gaps:Hybrid and battery-electric diagnostics require training beyond traditional mechanical skill sets, creating service bottleneck risks for independent workshops.
- Inventory reconfiguration capex:Dealers must fund charging infrastructure and specialized tooling to support electrified used stock, straining balance sheets in fragmented retail networks.
- Platform algorithm compliance:National competition authority scrutiny of pricing algorithms demands legal oversight investment that disproportionately burdens mid-scale operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Used Car Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Hatchback, Sedan, SUV, Coupe Fuel Type: Petrol, Diesel, Electric, Hybrid Age Category: Less than 1 Year, 1-3 Years, 4-6 Years, Over 6 Years Sales Channel: Dealerships, Private Sellers, Online Platforms, Auctions |
| Companies Covered | Intergea Group, Penske Automotive Group, AUTO1 Group, brumbrum, Arval Service Lease Italia, Autotorino, Bossoni Group, BCA Italia, Porsche Holding, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Used Car Market Strategic Shifts
Digital transaction infrastructure and emissions-driven inventory stratification are compressing traditional dealer margins while elevating transparency and certification standards across Italian regions.
Telematics-integrated vehicle history reporting is electrifying trust formation between distant buyers and sellers. Platforms deploying real-time odometer verification and maintenance logging are accelerating cross-regional transactions that previously required physical inspection. This technology is electrifying price discovery by collapsing information asymmetries that once anchored local market fragmentation.
EU Green Deal low-emission zone mandates are forcing municipal implementation timelines that reshape depreciation curves. Rome's Zona a Traffico Limitato expansion and Milan's Area B restrictions are compressing diesel demand in urban cores while elevating hybrid premiums. Dealers in affected provinces are reallocating procurement toward Euro 6 petrol and petrol-electric inventory to preempt inventory stranding.
Subscription tenure flexibility is displacing traditional installment financing for entry-segment buyers. Younger demographics in university cities are prioritizing access over ownership, converting short-term subscriptions into eventual purchase decisions. This behavioral pivot is most visible in Bologna and Padua, where platform-native operators are capturing lifetime value through embedded financing transitions rather than upfront transaction margins.
Italy Used Car Market Segmentation
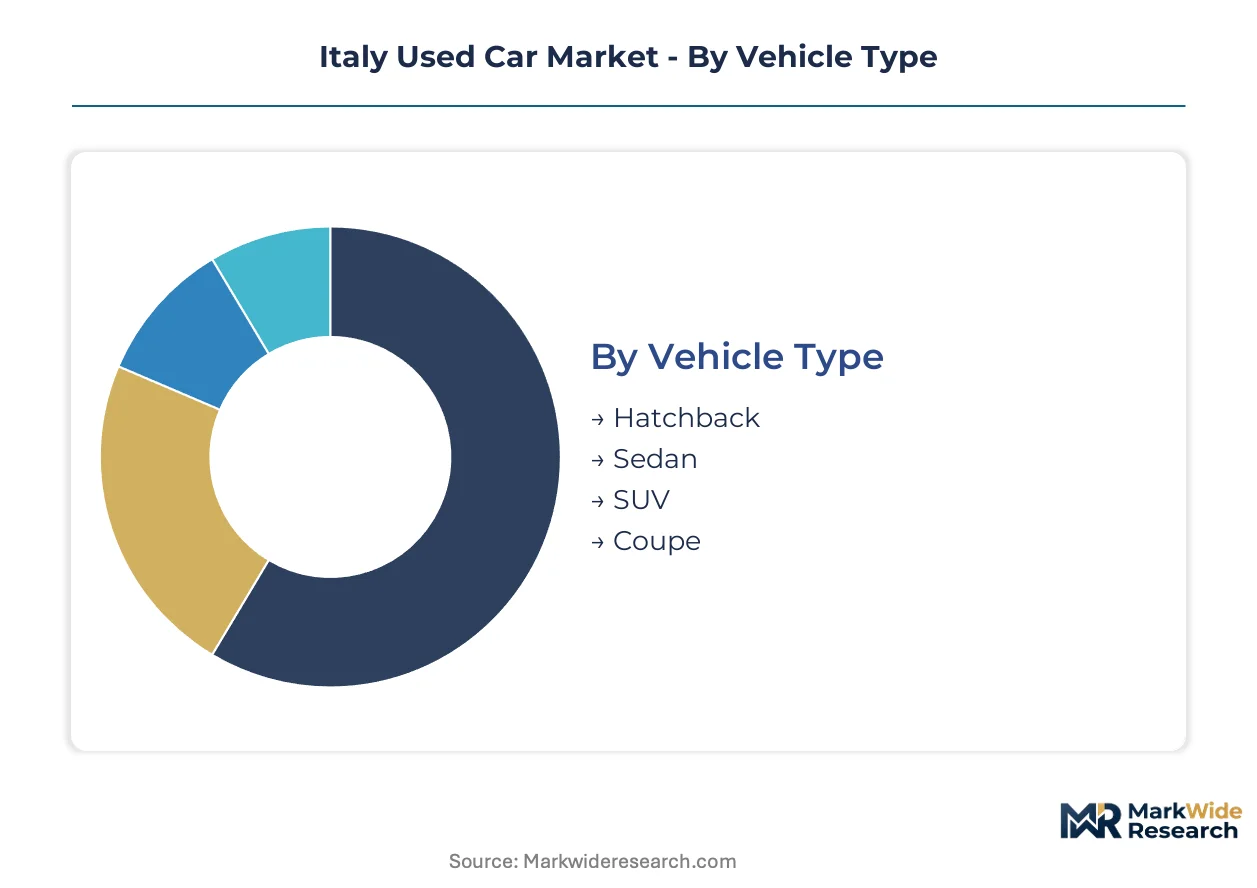
Segmentation in Italy's used car market reveals how EU emissions regulations and digital distribution are reshaping inventory allocation across vehicle types, fuel categories, and transaction channels. Understanding these divisions exposes where margin pools are concentrating and which buyer cohorts command pricing premiums.
Vehicle Type:
Standalone body-style segments dominate urban mobility applications, while embedded platform architectures support fleet standardization and logistics efficiency.
- Hatchback:Compact dimensions and maneuverability suit dense urban environments in Rome and Naples. Demand clusters among first-time buyers in university cities where parking scarcity elevates smaller footprints. Turin-based fleet operators favor hatchbacks for last-mile delivery contracts requiring frequent curb access.
- Sedan:Three-box architecture delivers superior aerodynamic efficiency and rear passenger comfort for intercity travel. Corporate procurement in Milan's financial district sustains residual values for executive-specification examples. Trunk capacity advantages support regional salesforce mobility requirements.
- SUV:Raised seating position and modular cargo configurations address family buyer priorities across suburban corridors.
- Coupe:Two-door proportions attract enthusiast demographics seeking differentiated styling in saturated markets.
Volume placements concentrate in Hatchback; the faster expansion belongs to SUV.
Fuel Type:
Cost-tier stratification separates compliance-premium powertrains from depreciation-exposed legacy technologies as municipalities harden emissions enforcement.
- Petrol:Spark-ignition engines offer lower upfront acquisition costs and simplified maintenance protocols for independent workshops. Euro 6 compliance shields residual values in Milan's Area B restriction zone. Bologna dealerships report petrol inventory turnover advantages over diesel equivalents.
- Hybrid:Petrol-electric architectures combine thermal efficiency with electric-only urban operation. Zona a Traffico Limitato exemptions in Rome and Florence drive procurement premiums for self-charging and plug-in variants. Fleet operators in Turin accelerate hybrid adoption to preempt operational restrictions.
- Diesel:Compression-ignition technology faces demand collapse in urban cores as low-emission zones expand.
- Electric:Battery-electric powertrains require charging infrastructure alignment that fragments addressable demand geographically.
Current inventory tilts toward Petrol; Hybrid is climbing the fastest as compliance premiums harden.
Age Category:
Application-driven maturity tiers separate warranty-protected recent stock from depreciation-stabilized older vehicles serving price-sensitive segments.
- Less than 1 Year:Nearly-new inventory originates from fleet defleeting and subscription program returns. Factory warranty coverage and minimal wear attract buyers seeking new-car experience at reduced capital outlay. Milan-based premium dealers specialize in this tier for corporate client acquisition.
- 1-3 Years:Post-lease returns flood wholesale channels with standardized specification and documented service history. BCA Italia auction volumes concentrate in this bracket, supplying dealer networks with reconditioning-ready stock. Depreciation curves flatten relative to first-year value collapse.
- 4-6 Years:Mechanical refresh cycles and revisione compliance requirements elevate transaction friction for this cohort.
- Over 6 Years:Price accessibility dominates buyer calculus as technology obsolescence and maintenance exposure intensify.
Dealer procurement concentrates in 1-3 Years; certified pre-owned programs are gaining share fastest in Less than 1 Year.
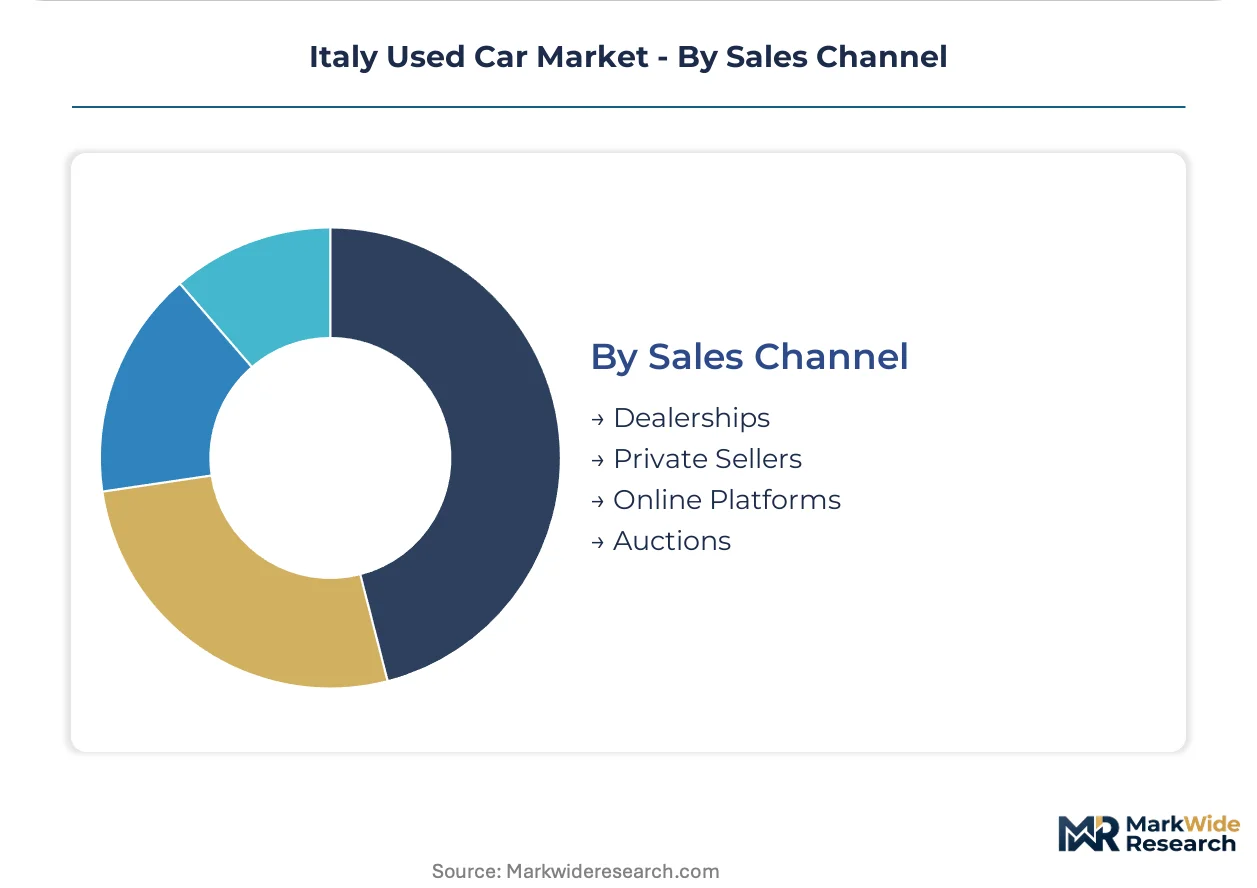
Sales Channel:
Customer-type fragmentation separates institutional buyers seeking procurement efficiency from individual consumers prioritizing transaction trust and financing integration.
- Dealerships:Physical showrooms combine vehicle presentation with captive financing and extended warranty attachment. Certified pre-owned programs leverage manufacturer backing to compress information asymmetries. Margin pools depend on F&I product penetration rather than unit front-end gross.
- Online Platforms:Digital marketplaces collapse search costs and expand geographic matching between dispersed buyers and sellers. AUTO1 Group's logistics infrastructure enables cross-regional transactions with standardized condition reporting. Younger demographics in Padua and Florence exhibit channel-native purchasing behavior.
- Private Sellers:Direct transactions eliminate intermediary margins but impose verification burdens on buyers.
- Auctions:Wholesale price discovery serves dealer inventory replenishment with velocity-driven lot turnover.
Transaction volume concentrates in Dealerships; Online Platforms are expanding most quickly among first-time buyer cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer demand concentrates in northern industrial corridors where fleet replacement cycles and emissions compliance intersect. Municipal low-emission zones are redrawing depreciation geography across sub-regional markets.
Lombardy
Milan's Area B restrictions compress diesel residual values while elevating hybrid premiums for corporate fleet operators. The metropolitan revisione enforcement protocols filter non-compliant inventory from circulation. Dealer networks in Monza-Brianza and Bergamo provinces reallocate procurement toward Euro 6 petrol-electric stock.
Piedmont
Turin-based automotive heritage sustains technician specialization pools that support electrified used vehicle reconditioning. The regional environmental agency aligns with EU Green Deal benchmarks to accelerate Zona a Traffico Limitato implementation. Inventory flows concentrate in the Turin-Alessandria corridor where same-day logistics enable just-in-time restocking.
Veneto
Padua and Verona university cities generate first-time buyer cohorts prioritizing subscription-to-ownership conversion models. Provincial transport authorities enforce periodic technical inspections that elevate certified pre-owned program penetration. Platform-native operators capture younger demographics through embedded financing transitions in the Veneto-Friuli logistics basin.
Emilia-Romagna
Bologna's congestion charging pilot reshapes vehicle depreciation curves for urban commuters. The regional competition authority monitors platform pricing algorithms alongside national regulators. Independent dealers in Modena and Parma face inventory reconfiguration capex demands as hybrid powertrain arbitrage intensifies.
Lazio
Rome's expanding Zona a Traffico Limitato collapses demand for pre-Euro 6 diesel powertrains in the capital metro. Ministry of Transport revisione protocols create certified inventory scarcity that supports pricing discipline. Suburban dealership networks in Fiumicino and Tivoli corridors pivot toward petrol and petrol-electric procurement.
Italy Used Car Market Competitive Environment
Pan-European platform operators anchor one tier; Italian specialist dealers and regional auction houses hold differentiated positions in procurement and fulfillment. Market structure tilts toward consolidation at the wholesale layer while retail fragmentation persists. Three archetypes dominate: logistics-integrated digital marketplaces, manufacturer-aligned certified pre-owned programs, and independent multi-site dealership groups. Competitive moves center on subscription-to-ownership conversion infrastructure and cross-regional inventory transfer capabilities.
Within the platform-operator tier, AUTO1 Group and brumbrum exemplify archetypes leveraging pan-European logistics density and digital-native customer acquisition respectively. BCA Italia occupies a position in wholesale auction channel control. These entities represent strategic positioning around transparency standardization, tenure flexibility, and supply-side velocity rather than traditional showroom margin extraction.
| Leading Market Players |
|---|
| Intergea Group |
| Penske Automotive Group |
| AUTO1 Group |
| brumbrum |
| Arval Service Lease Italia |
| Autotorino |
| Bossoni Group |
| BCA Italia |
| Porsche Holding |
| Others |
Value Chain & Pricing Dynamics
Logistics infrastructure costs cascade through Italy's used car market from northern corridor warehousing through suburban dealership networks, compressing margins on sub-premium inventory while elevating certified pre-owned premiums in Milan and Turin.
Pricing Analysis
Volume transactions cluster in standard-grade petrol hatchbacks where price competition intensifies among independent dealers, while margin pools concentrate in certified hybrid SUVs commanding premiums through EU Green Deal compliance. Price differentiation separates Euro 6-certified inventory from pre-compliant stock facing Zona a Traffico Limitato restrictions. Pricing pressure stems from diesel depreciation acceleration as Rome and Naples expand low-emission zones. First-time buyers in university cities exhibit highest price sensitivity; corporate fleet operators in Lombardy show lowest.
Supply Chain Analysis
Freight costs from Germany, France, and Spain shape cross-border wholesale economics for dealer networks sourcing reconditioned inventory through BCA Italia auction channels. Battery-electric and hybrid components draw from East Asian manufacturing hubs, creating lead-time exposure for electrified used vehicle refurbishment. Single-source vulnerability concentrates in telematics-integrated diagnostic tooling required for hybrid certification. Distribution runs through Turin-Milan logistics corridors enabling same-day inventory transfers to suburban dealerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's used car market operates as a supply-constrained environment where certified pre-owned inventory scarcity props pricing discipline and compresses procurement flexibility for independent retailers.
For Market Incumbents: Hedge diesel exposure by accelerating hybrid inventory reallocation ahead of Zona a Traffico Limitato expansion in Rome and Milan. Secure auction channel relationships with BCA Italia to preempt wholesale supply bottlenecks. Invest in technician certification for electrified powertrain diagnostics to capture service revenue from hybrid stock.
For New Entrants and Emerging Players: Digital-native platform partnerships offer lowest-friction entry into Bologna and Padua first-time buyer cohorts prioritizing subscription-to-ownership conversion. White-space opportunity concentrates in telematics-integrated vehicle history verification services that collapse cross-regional transaction friction. Direct-to-consumer financing attachment bypasses traditional dealer F&I margin extraction.
For Investors and Strategic Acquirers: Distressed-cycle entries favor hybrid-specialized dealer groups in Piedmont and Lombardy corridors where technician pools and logistics density create defensible positioning. Long-term viability hinges on electrification transition execution rather than combustion-era scale. Monitor Turin and Bologna congestion charging implementation timelines as inventory stranding inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription-to-Ownership Platform Development | Brumbrum's tenure flexibility captures lifetime value from Bologna and Padua demographics. |
| Pan-European Logistics Integration | AUTO1 Group's cross-border infrastructure standardizes condition reporting across Italian regions. |
| Certified Pre-Owned Program Expansion | Manufacturer-backed warranties compress information asymmetries for Milan corporate buyers. |
| Hybrid Powertrain Reconditioning Investment | Turin technician specialization pools support electrified inventory turnaround velocity. |
| Telematics-Integrated Vehicle History Reporting | Real-time odometer verification accelerates cross-regional transactions without physical inspection. |
Study Parameters
Multi-period observation of vehicle registration flows, auction volume patterns, and Zona a Traffico Limitato policy implementation anchored the trend analysis, supplemented by interviews with dealership operations managers, fleet procurement directors, platform engineering leads, and Ministry of Transport enforcement officials. Secondary validation drew from IHS Markit registration databases, EU Green Deal regulatory filings, and BCA Italia auction transaction records. Bottom-up dealer network surveys triangulated against top-down regional production and import statistics.
Input-output matrices modeled vehicle age, fuel type, body style, and sales channel interactions across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by emissions compliance premiums and digital channel penetration rates. Forecast inputs incorporated fleet replacement cycle timing, municipal low-emission zone expansion schedules, and subscription program defleet volumes.
Caveats apply where accelerated Zona a Traffico Limitato implementation or battery-electric technology obsolescence curves could materially shift the outlook for diesel and early hybrid residual values. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Qatar Used Car Market
Used Vehicles
Sri Lanka Used Car Market
Used Vehicles
Kuwait Used Car Market
Used Vehicles
Myanmar Used Car Market
Used Vehicles
United Arab Emirates Used Car Market
Used Vehicles
South Korea Used Car Market
Used Vehicles
Vietnam Used Car Market
Used Vehicles
Kenya Used Car Market
Used Vehicles
New Zealand Used Car Market
Used Vehicles
China Used Car Market
Used Vehicles
Germany Used Car Market
Used Vehicles
Ethiopia Used Car Market
Used Vehicles
Norway Used Car Market
Used Vehicles
Europe Used Car Market
Used Vehicles
France Used Car Market
Used Vehicles
Japan Used Car Market