
 Brazil Used Car Market | 2026-2036
Brazil Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Used Car Market Insights
Lease-to-own and fleet refinancing structures are reshaping competitive dynamics in Brazil's used car sector. Localiza leverages its captive fleet pipeline to sustain a steady supply of late-model inventory across major metropolitan areas. KAVAK competes through technology-led pricing algorithms that standardize vehicle valuations nationwide. Instacarro controls a digital-first channel that connects sellers directly to its refurbishment network, reducing traditional dealer intermediation.
A used car denotes a previously registered vehicle transferred through secondary ownership, typically assessed via odometer reading, structural integrity verification, and powertrain diagnostic evaluation before resale for personal or commercial mobility. The primary purpose centers on delivering accessible transportation at depreciated capital cost relative to new vehicle acquisition. Sedan and hatchback segments dominate volume in urban commuter corridors where parking constraints and fuel efficiency govern purchase decisions, while SUV demand accelerates fastest among suburban families seeking cabin versatility. Certified pre-owned vehicles command premium positioning through warranty-backed quality assurance, whereas online platforms capture expanding share by aggregating inspection data and financing pre-approval into unified digital workflows.
ANVISA coordinates with Brazil's national traffic department to enforce safety and environmental compliance standards for commercial vehicle resale, while state-level environmental agencies in São Paulo and Rio de Janeiro administer periodic emission testing that filters non-compliant units from formal channels. The central bank's credit policy directives shape consumer access to auto financing, directly conditioning purchase feasibility across income segments. Stakeholders must monitor how proposed federal vehicle traceability legislation alters documentation requirements and title-transfer velocity in informal sales corridors.
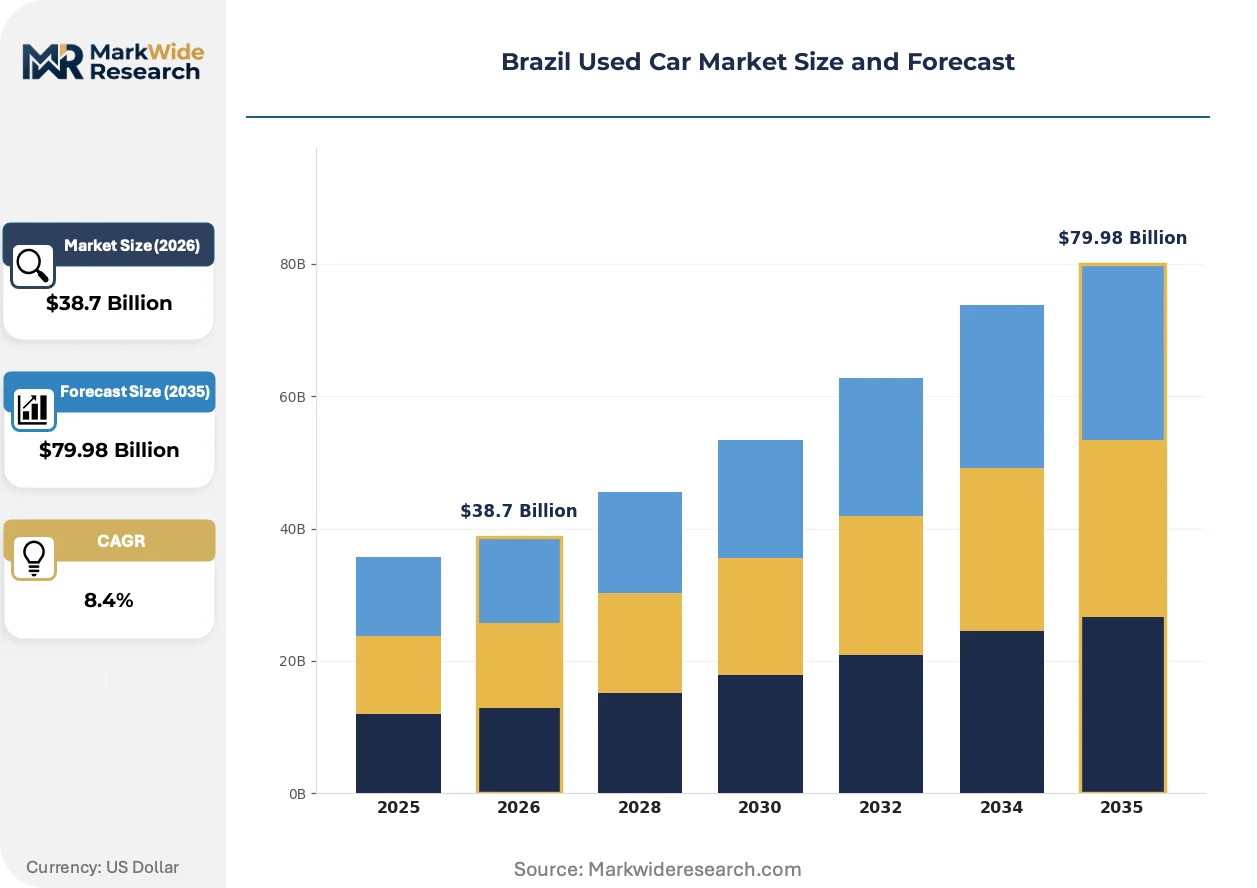
Market Dynamics
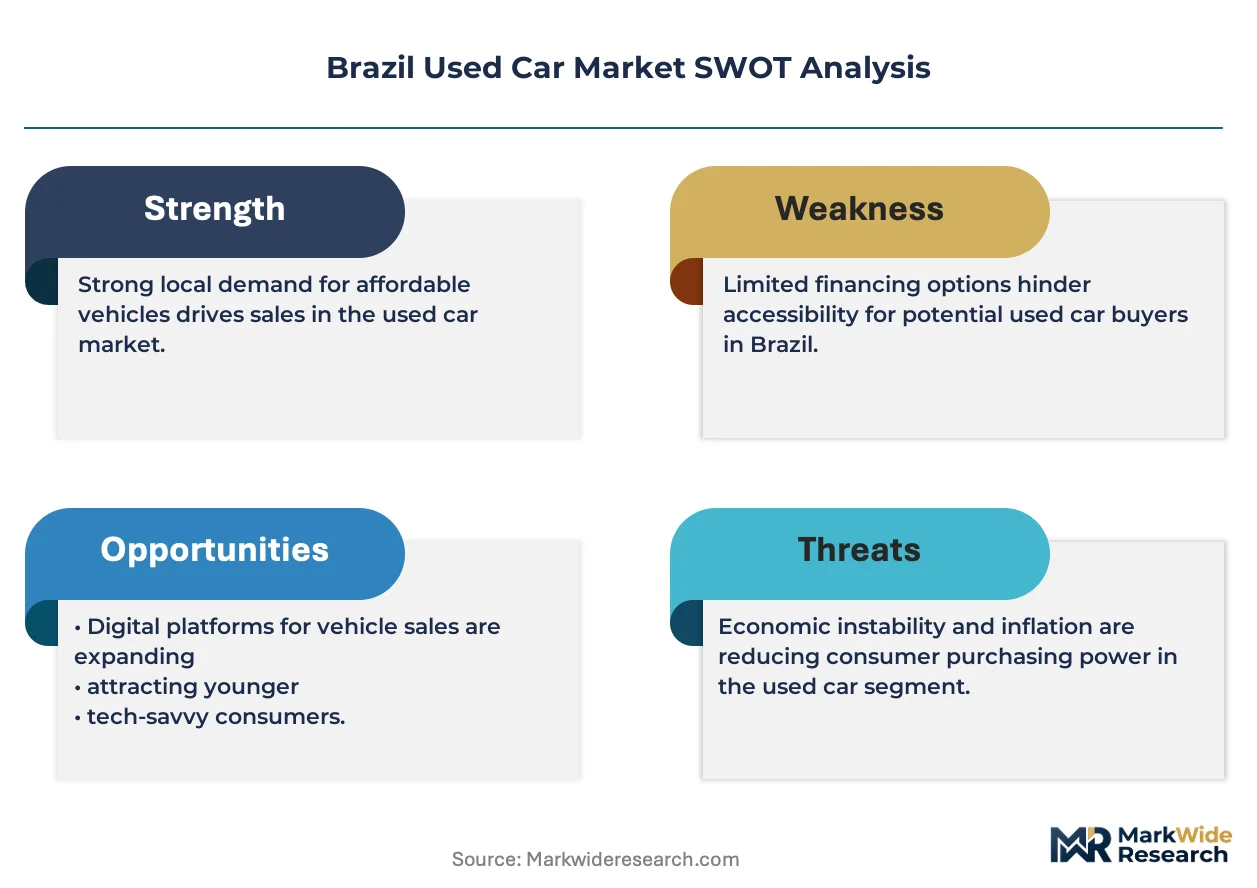
Fleet refinancing structures and captive lease pipelines are compressing traditional dealer intermediation, redirecting late-model inventory toward direct-to-consumer digital channels across São Paulo and Rio de Janeiro metropolitan corridors.
Growth Catalysts
- Ride-hailing fleet expansion:Drivers in São Paulo and Rio de Janeiro prioritize affordable, durable vehicles for commercial mobility, creating sustained demand for sub-100,000 kilometer inventory with verified maintenance histories.
- ANVISA-equivalent safety inspections:Mandatory structural integrity and powertrain diagnostic protocols are filtering substandard units from formal resale channels, elevating certified pre-owned premiums.
- Southeast industrial corridor concentration:São Paulo state's manufacturing density generates surplus corporate fleet turnover, feeding steady supply into secondary ownership pools.
Market Restraints
- Emission compliance fragmentation:State-level testing programs in Minas Gerais and Paraná create divergent eligibility standards, trapping non-compliant vehicles in informal sales corridors.
- Credit access stratification:Central bank policy directives constrain auto financing penetration among lower-income segments, capping addressable demand.
- Documentation velocity friction:Proposed federal vehicle traceability legislation threatens to slow title-transfer processes in cash-dominant informal transactions.
Strategic Opportunities
- Digital inspection aggregation:Platforms integrating odometer verification, structural diagnostics, and financing pre-approval into unified workflows capture share from traditional dealer networks.
- Suburban SUV penetration:Family buyers outside urban cores seek cabin versatility, accelerating demand for certified pre-owned sport utility vehicles with warranty-backed quality assurance.
- Refurbishment network control:Direct seller-to-refurbishment channel integration reduces intermediary markups and compresses time-to-market for reconditioned inventory.
Industry Challenges
- Diagnostic technician scarcity:Standardized powertrain evaluation and structural integrity verification require specialized labor pools that remain underdeveloped outside major metropolitan centers.
- Cross-state logistics coordination:Moving compliant inventory between Minas Gerais, Paraná, and São Paulo testing jurisdictions adds cost and documentation complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Used Car Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Pickup Fuel Type: Gasoline, Ethanol, Diesel, Electricity Condition: Certified Pre-Owned, Excellent, Good, Fair Sales Channel: Dealerships, Private Sales, Online Platforms, Auctions |
| Companies Covered | Griffe Auto, Localiza, KAVAK, VK Multimarcas, Ronaldo Veiculos, Instacarro, A R Box Multimarcas, Auto Sold Seminovos, Milano Multimarcas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Used Car Market Trends and Innovations
Technology-led pricing standardization and regulatory compliance digitization are restructuring how Brazilian buyers access, evaluate, and finance secondary vehicle ownership.
Automated valuation algorithms incorporating real-time depreciation curves, regional demand patterns, and refurbishment cost estimates are rendering obsolete the traditional negotiable sticker-price model at physical dealerships. Ride-hailing operators and fleet managers in São Paulo are adopting these tools fastest, compressing purchase decision cycles from days to hours. The structural consequence is margin compression for dealers reliant on information asymmetry.
ANVISA-coordinated safety protocols with Brazil's national traffic department are mandating digital documentation trails for structural integrity verification and odometer authentication. This regulatory architecture elevates compliance costs for informal sellers while creating certification premiums for platforms that integrate inspection data directly into listing workflows. The certified pre-owned segment is responding by consolidating around warranty-backed quality assurance as a differentiation mechanism.
Direct-to-consumer digital marketplaces are unbundling the traditional dealer bundle of sourcing, reconditioning, and financing. Sellers in Rio de Janeiro and São Paulo now transact directly with refurbishment networks and captive finance arms, bypassing intermediary markups. This channel shift is most visible among corporate fleet divestitures and ride-hailing driver acquisitions, where price transparency and speed outweigh relationship-based purchasing.
Brazil Used Car Market Segmentation
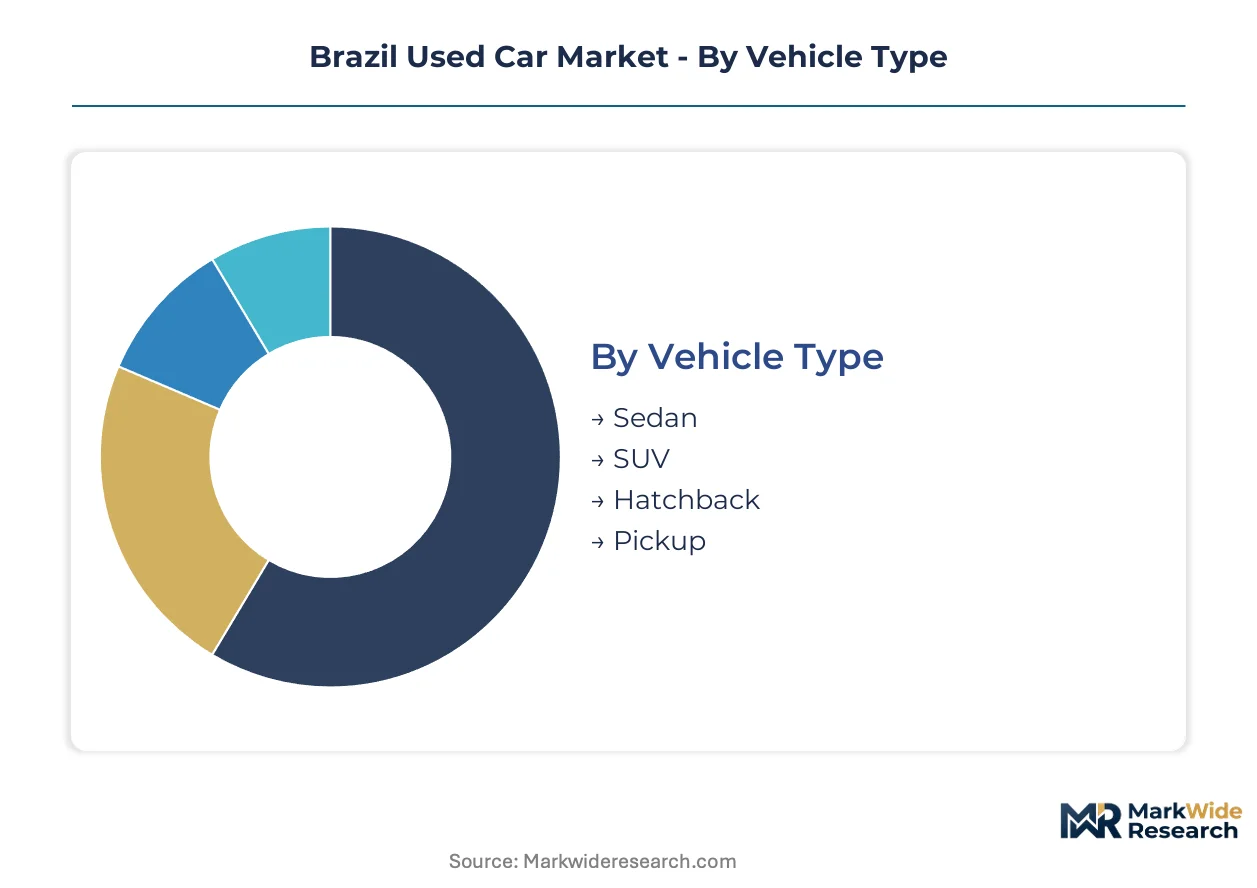
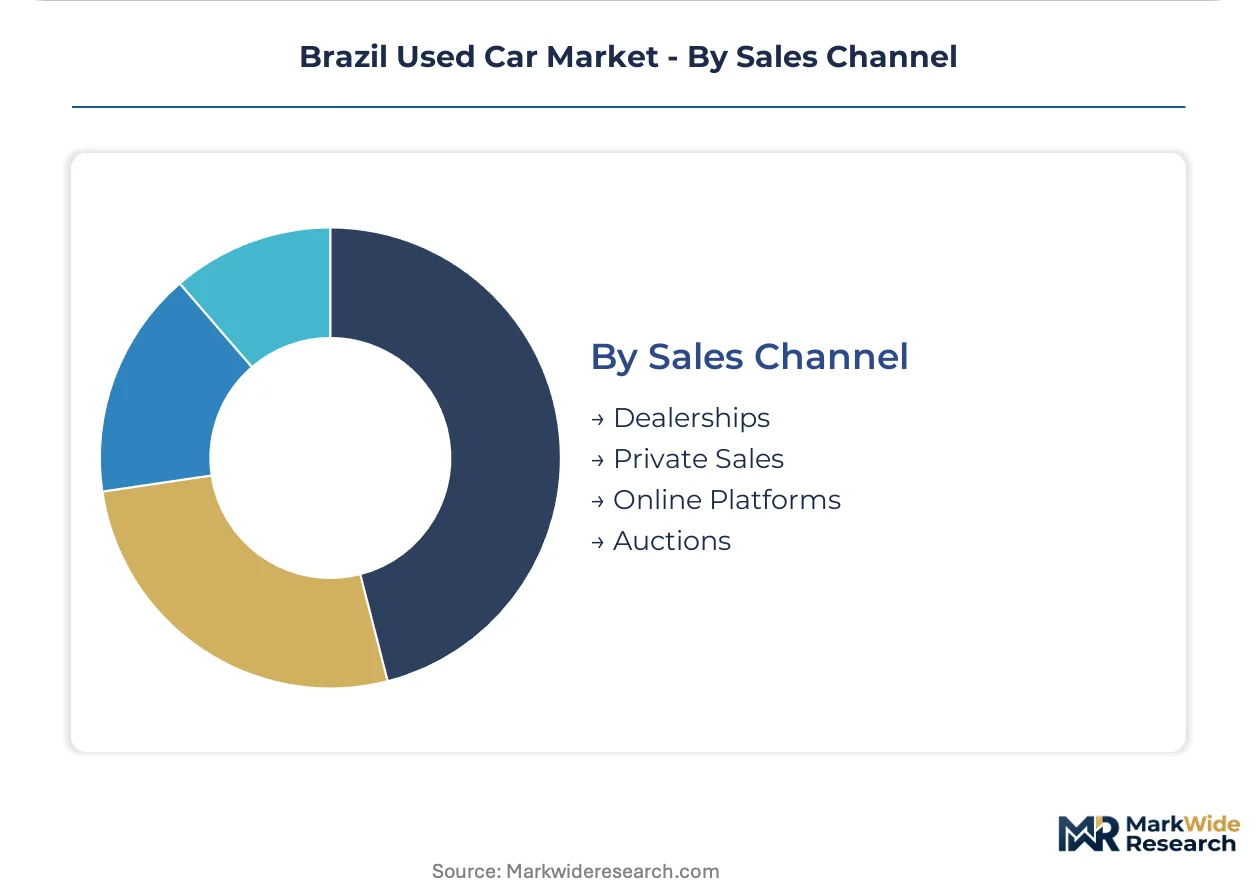
Segmentation in Brazil's used car market reveals how inventory velocity, pricing power, and channel strategy diverge across vehicle configurations and transaction formats. Understanding these splits enables stakeholders to align sourcing, refurbishment, and distribution investments with where demand concentrates.
Vehicle Type:
Inventory turnover cycles vary dramatically by body style, with compact urban configurations rotating fastest and utility-focused segments commanding extended holding periods.
- Sedan:Three-box passenger configurations with dedicated trunk compartments dominate São Paulo and Rio de Janeiro ride-hailing fleets due to passenger capacity and fuel efficiency requirements. Drivers in these metropolitan corridors prioritize sub-100,000 kilometer sedans with verified maintenance histories, compressing average days-on-lot for compliant units.
- SUV:Sport utility vehicles with elevated seating positions and expanded cargo capacity attract suburban family buyers outside urban cores seeking cabin versatility. Certified pre-owned SUVs with warranty-backed quality assurance command premium positioning in Paraná and Minas Gerais secondary markets.
- Hatchback:Compact two-box designs with integrated cargo areas address parking-constrained urban commuters in dense southeastern corridors.
- Pickup:Open-bed utility configurations serve commercial operators and rural buyers requiring load-hauling capability across Brazil's agricultural zones.
Sedan and hatchback configurations anchor the volume base while SUV demand gains share at the steepest rate among family-oriented suburban purchasers.
Fuel Type:
Powertrain diversification reflects Brazil's distinctive ethanol infrastructure and emerging electrification pressures across state-level emission jurisdictions.
- Gasoline:Internal combustion engines running on refined petroleum derivatives maintain broad compatibility with existing service networks nationwide.
- Ethanol:Flexible-fuel systems optimized for sugarcane-derived alcohol leverage Brazil's established distribution infrastructure and price-advantaged domestic supply.
- Diesel:Compression-ignition powertrains concentrate in commercial pickup and fleet applications where torque and durability outweigh fuel cost considerations.
- Electricity:Battery-electric drivetrains face constrained secondary market penetration pending charging infrastructure expansion and diagnostic technician availability outside metropolitan centers.
Ethanol-compatible powertrains dominate transaction velocity in southeastern corridors while electric drivetrains expand most quickly from minimal base.
Condition:
Certification tier determines financing accessibility and channel eligibility under tightening ANVISA-coordinated inspection protocols.
- Certified Pre-Owned:Warranty-backed vehicles passing standardized structural integrity and powertrain diagnostic protocols qualify for captive finance programs and digital platform aggregation. These units bypass informal sales corridors and command documented premiums in São Paulo's formal resale channels.
- Excellent:Low-mileage inventory with minimal cosmetic wear attracts price-sensitive buyers seeking near-new depreciation benefits without certification overhead.
- Good:Moderate wear vehicles with functional mechanical condition serve budget-constrained commuters in cash-dominant transactions.
- Fair:Higher-mileage units requiring visible reconditioning concentrate in auction channels and direct refurbishment network feeds.
Certified pre-owned inventory commands financing access advantages while excellent-condition units without formal certification expand most quickly through digital direct-to-consumer channels.
Sales Channel:
Channel selection shapes price transparency, transaction velocity, and regulatory compliance burden for sellers and buyers alike.
- Dealerships:Physical retail locations with captive finance relationships and on-site reconditioning facilities maintain relevance for buyers requiring test-drive validation and immediate documentation completion.
- Private Sales:Direct owner-to-buyer transactions dominate cash-dominant informal corridors but face escalating friction from proposed federal vehicle traceability legislation threatening title-transfer velocity.
- Online Platforms:Digital marketplaces integrating odometer verification, structural diagnostics, and financing pre-approval capture expanding share from traditional dealer networks in Rio de Janeiro and São Paulo metropolitan areas.
- Auctions:Wholesale disposal channels for fleet divestitures and trade-in inventory feed refurbishment networks with volume supply at compressed acquisition costs.
Dealerships anchor transaction volume in suburban and rural corridors while online platforms gain share at the steepest rate among metropolitan digital-native buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA-coordinated safety protocols and state-level emission testing programs are redistributing used vehicle liquidity across Brazil's sub-regional markets. Southeast industrial corridors generate surplus fleet inventory while compliance fragmentation traps non-compliant units in informal channels.
São Paulo
Ride-hailing fleet turnover and corporate divestitures feed steady supply into secondary channels. The state's environmental agency administers periodic emission testing that filters non-compliant units from formal resale. Greater São Paulo's manufacturing density concentrates refurbishment capacity and digital platform aggregation.
Minas Gerais
Belo Horizonte metropolitan buyers prioritize certified pre-owned SUVs with warranty-backed quality assurance for suburban family mobility. State-level testing programs create divergent eligibility standards from neighboring jurisdictions. The state's industrial corridor generates moderate fleet turnover feeding regional auction channels.
Rio de Janeiro
Ride-hailing drivers in the metropolitan area seek affordable sedans with verified maintenance histories for commercial mobility. State environmental agencies administer emission testing parallel to São Paulo protocols. Digital platforms capture expanding share from traditional dealer networks through integrated inspection and financing workflows.
Paraná
Curitiba and surrounding municipalities exhibit accelerating demand for ethanol-compatible powertrains leveraging Brazil's established distribution infrastructure. State-level emission compliance requirements diverge from São Paulo standards, complicating cross-border inventory movement. The state's agribusiness economy sustains pickup demand among commercial operators.
Rio Grande do Sul
Porto Alegre metropolitan buyers favor hatchback configurations addressing parking-constrained urban environments. State regulations align with federal ANVISA protocols without additional testing layers. The state's automotive heritage sustains specialized technician pools for powertrain diagnostic evaluation.
Brazil Used Car Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Brazil's used car sector. Fleet-originated inventory flows through captive pipelines toward direct-to-consumer platforms, compressing traditional dealer intermediation. Three archetypes dominate: fleet-captive disposers with steady late-model supply, technology-led pricing platforms standardizing nationwide valuations, and refurbishment-integrated digital channels reducing time-to-market. Competitive moves center on backward integration into captive fleet sourcing and technology licensing for diagnostic standardization.
Within the fleet-captive tier, Localiza anchors supply-side positioning through its captive pipeline structure. KAVAK and Instacarro occupy the technology-led platform tier, with the former exemplifying algorithmic pricing standardization and the latter representing direct seller-to-refurbishment channel integration. These three entities collectively illustrate how digital workflows and captive sourcing are restructuring competitive dynamics across São Paulo and Rio de Janeiro metropolitan corridors.
| Leading Market Players |
|---|
| Griffe Auto |
| Localiza |
| KAVAK |
| VK Multimarcas |
| Ronaldo Veiculos |
| Instacarro |
| A R Box Multimarcas |
| Auto Sold Seminovos |
| Milano Multimarcas |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in São Paulo's refurbishment network compresses acquisition premiums for compliant inventory while elevating margins for certified pre-owned units passing ANVISA-coordinated protocols. Fleet divestitures from the Southeast industrial corridor feed this capacity expansion, creating divergent pricing power between formal and informal channels.
Pricing Analysis
Certification level under ANVISA-coordinated safety protocols creates the primary spread between transaction tiers. Three-tier pricing structure across certified pre-owned, excellent-condition, and good-condition levels governs the Brazilian market, with warranty-backed certification commanding captive finance access. Price differentiation rests on diagnostic verification depth and emission compliance status across state jurisdictions. Pricing pressure stems from digital platform aggregation compressing information asymmetry that traditional dealers exploited. Ride-hailing drivers in São Paulo and Rio de Janeiro exhibit highest price sensitivity, while suburban family buyers in Paraná and Minas Gerais accept premiums for SUV cabin versatility.
Supply Chain Analysis
Extended payment terms from fleet operators to refurbishment networks anchor working capital flows across the Brazilian used car supply chain. Inventory concentration centers on São Paulo, Rio de Janeiro, and Minas Gerais as primary sourcing regions, with cross-state logistics feeding secondary markets. The supply chain draws from corporate fleet turnover, ride-hailing operator divestitures, and lease-return pipelines as core input streams. Single-source vulnerability concentrates in diagnostic technician pools specialized in powertrain evaluation and structural integrity verification. Distribution runs through digital platforms integrating inspection data with financing pre-approval, bypassing traditional dealer intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's used car market is recovering from cyclical compression as ride-hailing fleet expansion and corporate vehicle turnover reactivate inventory velocity across Southeast metropolitan corridors.
For Market Incumbents: Pre-empt margin erosion from technology-led pricing platforms by backward integration into captive fleet sourcing agreements with São Paulo industrial operators. Lock in refurbishment capacity through exclusive technician training pipelines before diagnostic labor scarcity intensifies. Channel control through direct seller-to-refurbishment workflows represents the critical defensive lever against digital platform disintermediation. For New Entrants and Emerging Players: Build out white-space presence in certified pre-owned SUV segments serving suburban family buyers in Paraná and Minas Gerais, where warranty-backed quality assurance remains underdeveloped relative to São Paulo saturation. Target ethanol-compatible powertrain refurbishment as the most penetrable technology tier given Brazil's established distribution infrastructure. A go-to-market angle anchored in state-level emission compliance navigation offers differentiation against national-platform standardization. For Investors and Strategic Acquirers: Capital is best deployed toward fleet-captive disposers with steady late-model supply pipelines and refurbishment-integrated digital channels reducing time-to-market. Long-term viability across the analysis window favors entities controlling backward integration into corporate fleet sourcing rather than pure pricing-platform plays. The signal to watch as inflection indicator is federal vehicle traceability legislation progress affecting title-transfer velocity in cash-dominant informal corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic Technician Training Pipeline | ANVISA-coordinated protocols require specialized labor pools that remain underdeveloped outside São Paulo. |
| Cross-State Compliance Navigation Platform | Minas Gerais and Paraná emission testing divergence creates arbitrage opportunity for inventory routing. |
| Captive Fleet Sourcing Agreement | Southeast industrial corridor manufacturing density generates surplus corporate turnover for steady supply. |
| Ethanol Powertrain Refurbishment Specialization | Brazil's sugarcane-derived alcohol infrastructure supports price-advantaged domestic fuel compatibility. |
| Direct-to-Consumer Digital Marketplace | Rio de Janeiro and São Paulo metropolitan buyers prioritize price transparency and speed over dealer relationships. |
Research Methodology
Desk research of vehicle registration databases, fleet operator financial disclosures, and ANVISA regulatory filings preceded structured interviews with used car platform executives, refurbishment network operators, and ride-hailing fleet managers across São Paulo and Rio de Janeiro. Secondary validation drew from central bank credit policy directives, state environmental agency testing protocols, and corporate fleet turnover reports. Bottom-up transaction volume estimates triangulated against top-down market value assessments derived from digital platform pricing data and dealer network surveys.
Assumptions held fixed include ANVISA-coordinated safety protocol enforcement intensity and central bank auto financing policy stance, while ride-hailing fleet growth trajectories and federal traceability legislation timelines varied across scenarios. The analytical framework modeled segmentation across vehicle type, fuel compatibility, certification tier, and sales channel throughout the forecast period. CAGRs were derived from regression analysis against macroeconomic indicators and fleet turnover velocity. Industry-specific inputs incorporated ethanol price differentials, emission compliance pass rates by state, and diagnostic technician availability indices.
Practitioners should monitor federal vehicle traceability legislation advancement and central bank credit policy shifts for early signals of channel liquidity disruption. Forecasts reflect assumptions about regulatory enforcement consistency and fleet operator divestiture patterns. Macroeconomic contraction, emission standard harmonization failure, or diagnostic technician pool collapse would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Spain Used Car Market
Used Vehicles
Used E-Scooter Market
Used Vehicles
Germany Used Car Market
Used Vehicles
Qatar Used Car Market
Used Vehicles
Global Online Second-Hand Car Trading Service Market
Used Vehicles
Russia Used Car Market
Used Vehicles
Finland Used Car Market
Used Vehicles
Malaysia Used Car Market
Used Vehicles
Bangladesh Used Car Market
Used Vehicles
Saudi Arabia Used Car Market
Used Vehicles
Oman Used Car Market
Used Vehicles
Switzerland Used Car Market
Used Vehicles
Online Car Buying Market
Used Vehicles
Indonesia Used Car Financing Market
Used Vehicles
Singapore Used Car Market
Used Vehicles
Australia Used Car Market