
 France Used Car Market | 2026-2036
France Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
France Used Car Market Analysis
The EU Green Deal's vehicle emissions targets is consolidating demand toward younger used cars with lower CO2 footprints. Aramis Group leverages its nationwide refurbishment centers to standardize quality across regional inventories. Leboncoin sustains dominant traffic in peer-to-peer transactions through its classifieds platform. Stellantis Spoticar anchors manufacturer-certified supply by integrating former fleet vehicles into its dealer network.
France's used car trade encompasses pre-owned passenger vehicles that have completed initial registration, typically evaluated by mileage accumulation, service history documentation, and structural integrity assessment prior to resale. These vehicles serve cost-conscious consumers, corporate fleet managers, and mobility-service operators seeking depreciated assets with verified operational remaining life. Hatchback and SUV segments command the largest transaction volumes, reflecting French buyer preference for urban maneuverability and family utility respectively. Online platforms represent the fastest-expanding sales channel, displacing traditional dealership foot traffic as digital verification tools reduce buyer risk perception.
France's national low-emission zone framework, administered through Crit'air vignette classification, restricts older diesel vehicles from accessing major city centers and directly shapes resale values by registration date. The country's national pharmaceutical regulator maintains no direct role here; rather, DGCCRF consumer protection standards and EU type-approval requirements govern disclosure obligations and warranty terms for dealers. Stakeholders must monitor the tightening schedule of metropolitan access restrictions, as each new ban wave will abruptly reprice affected vehicle cohorts and reshape inventory strategies across all sales channels.
Market Dynamics
France's Crit'air low-emission zone framework is systematically repricing vehicle cohorts by registration date, forcing inventory rotation toward younger used cars and compressing resale windows for older diesel assets.
Growth Catalysts
- Fleet electrification mandates:Corporate fleet operators facing total cost of ownership pressures are accelerating procurement of pre-owned hybrid and electric vehicles to meet internal sustainability targets without absorbing new-car depreciation.
- Île-de-France congestion pricing:Paris metropolitan access restrictions under Crit'air categories 3-5 are redirecting demand toward cleaner used cars that qualify for unrestricted urban entry, concentrating transaction velocity in compliant vehicle cohorts.
- Blockchain-based provenance verification:Digital service history immutability is reducing buyer risk perception and expanding online transaction willingness among previously dealership-dependent consumers.
Market Restraints
- Residual value volatility from regulatory cliff effects:Each scheduled Crit'air ban wave abruptly reprices affected diesel cohorts, creating inventory holding risk for dealers with aged stock.
- Refurbishment capacity concentration:Standardized quality preparation depends on a limited network of regional refurbishment centers, creating bottlenecks during demand surges.
- Substitution from mobility-as-a-service:Urban consumers in Paris, Lyon, and Marseille are substituting vehicle ownership with subscription-based car-sharing platforms for intermittent mobility needs.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur penetration gap:Secondary cities outside Paris orbit show lower digital transaction penetration and fragmented dealer consolidation, creating white space for platform expansion.
- Battery health certification standardization:Emerging EU battery passport requirements will create first-mover advantage for dealers investing in electric vehicle diagnostic infrastructure before mandate enforcement.
- Subscription-to-own financing hybrids:Flexible ownership models blending lease-like payments with purchase options are capturing younger demographics excluded from traditional auto financing.
Industry Challenges
- Electric vehicle technician scarcity:High-voltage system diagnostics and battery refurbishment require specialized training that existing mechanical workforce pipelines have not scaled to match.
- Cross-border title verification complexity:Import flows from neighboring EU member states create documentation friction under divergent national registration systems, slowing inventory velocity.
- Platform commission compression:Aggregator fee structures are squeezing dealer margins as price transparency intensifies inter-dealer competition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Used Car Market |
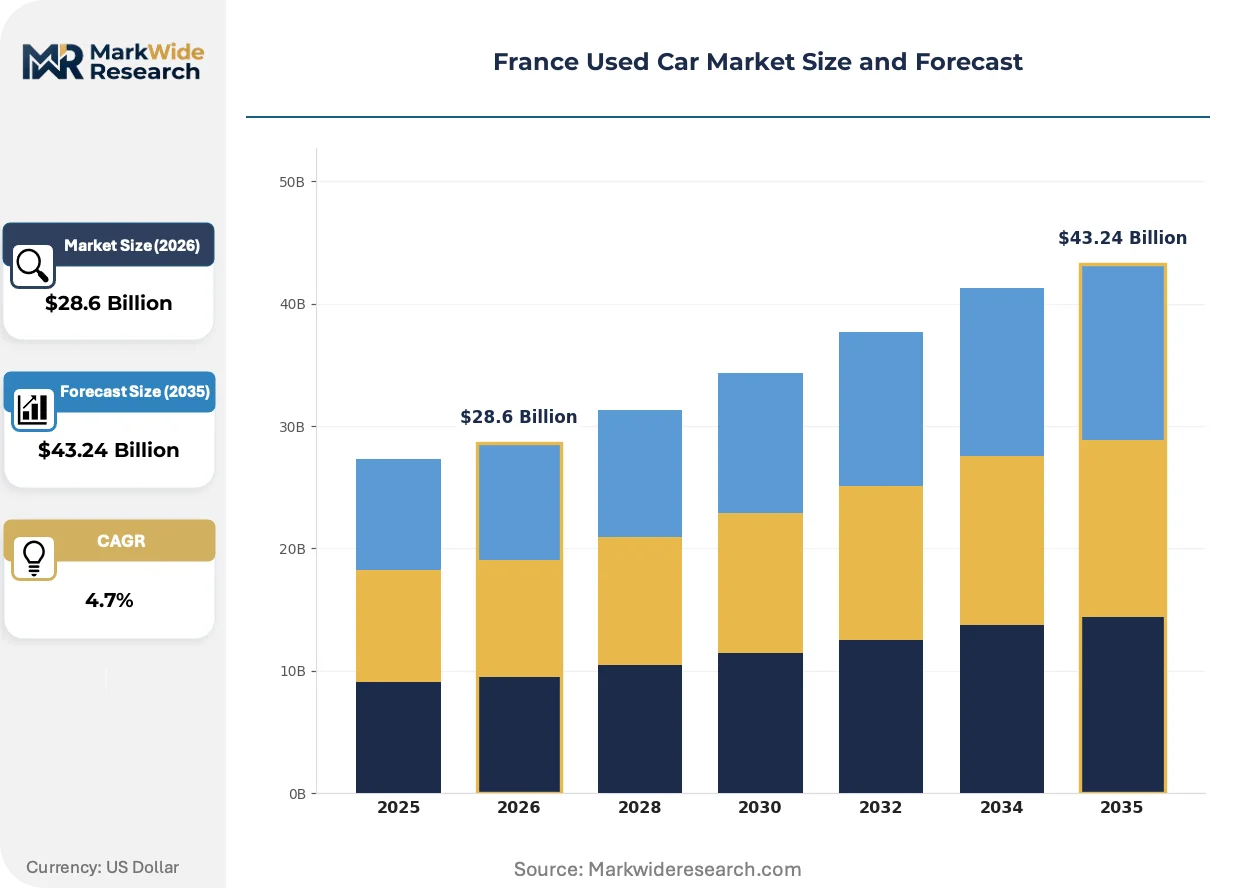
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, Hatchback, SUV, Coupe Fuel Type: Petrol, Diesel, Electric, Hybrid Age Category: Less than 3 Years, 3 to 5 Years, 5 to 10 Years, More than 10 Years Sales Channel: Dealerships, Online Platforms, Private Sellers, Auctions |
| Companies Covered | Leboncoin, Aramis Group, AutoScout24, Stellantis Spoticar, Auto1 Group, La Centrale, Reezocar, Heycar, BYmyCAR Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Used Car Market Emerging Trajectories
Digital verification infrastructure is compressing the traditional information asymmetry between buyers and sellers, enabling transaction migration from physical showrooms to remote purchasing workflows.
Artificial intelligence-powered damage assessment is automating condition grading through computer vision analysis of seller-submitted imagery. Regional dealer groups are deploying these tools to standardize remote appraisal consistency. This compression of evaluation labor is automating the preliminary inspection phase and reducing pre-listing preparation time from days to hours.
EU Green Deal vehicle emissions targets are consolidating demand toward younger used cars with verifiable CO2 footprints below fleet-average thresholds. DGCCRF disclosure obligations now require documented emissions classification in all dealer listings. The Île-de-France region exhibits the most pronounced demand rotation, with Crit'air 1 and 2 vehicles commanding transaction premiums over restricted categories.
Subscription-based ownership models are fragmenting traditional purchase behavior among urban professionals aged 25-40. Digital-native platforms displace dealership foot traffic through flexible tenure options and bundled maintenance. This shift concentrates in Paris and Lyon metropolitan zones where parking scarcity and access restrictions reduce pure ownership utility.
France Used Car Market Segmentation
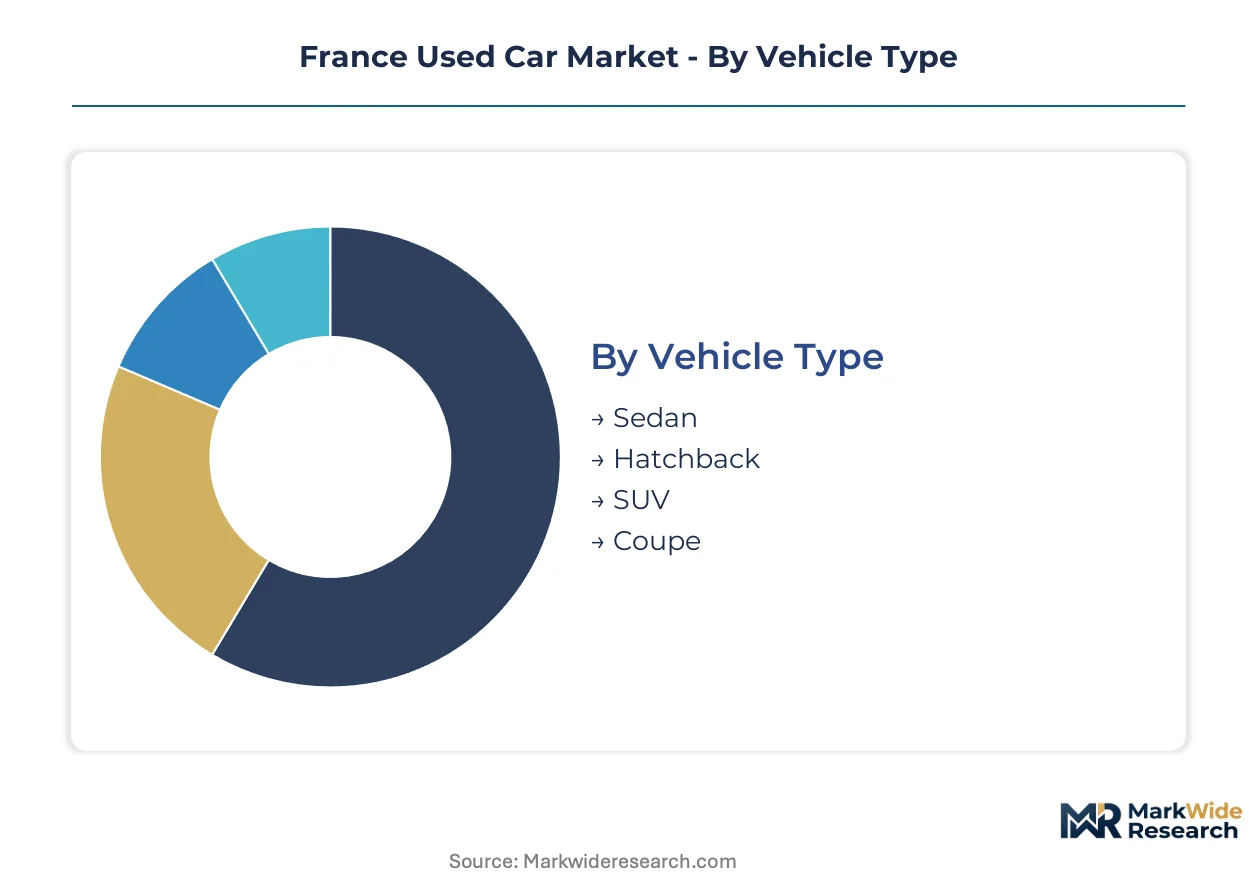
Segmentation in the France used car market reveals how Crit'air compliance, digital channel migration, and powertrain transitions are fragmenting demand across distinct buyer cohorts. Understanding these divisions enables inventory positioning that anticipates regulatory repricing events and channel preference shifts.
Vehicle Type:
Upgrade cycles from older sedans toward more versatile body styles are accelerating as families prioritize cargo capacity and urban maneuverability within emission-restricted zones.
- Sedan:Three-box configurations with dedicated trunk compartments retain corporate fleet preference for executive transport contracts. Demand concentrates in Île-de-France professional services sector where parking constraints favor compact sedan dimensions over larger alternatives.
- Hatchback:Two-box designs with integrated cargo areas dominate urban transaction volumes through superior parking efficiency and rear-seat flexibility. French buyers in Lyon and Marseille metropolitan zones favor this format for Crit'air-compliant daily commuting without sacrificing load practicality.
- SUV:Elevated seating positions and expanded cargo volumes command family buyer attention across Provence-Alpes-Côte d'Azur secondary cities where road trip utility outweighs urban parking penalties.
- Coupe:Two-door sport configurations with sloping rooflines attract enthusiast niches seeking depreciation-captured performance vehicles.
Volume placements concentrate in Hatchback; the faster expansion belongs to SUV.
Fuel Type:
Cost tier stratification separates compliance-premium powertrains from depreciating legacy technologies facing metropolitan access restrictions.
- Petrol:Internal combustion engines with gasoline fuel systems offer immediate Crit'air category 1-2 eligibility without battery replacement uncertainty. Transaction velocity runs highest in private seller channels where buyers prioritize purchase price minimization over lifetime fuel economics.
- Diesel:Compression-ignition engines with higher thermal efficiency face accelerating resale compression as Crit'air ban waves eliminate urban access eligibility. Inventory rotation pressures mount for dealers holding pre-2011 registrations now excluded from Paris, Lyon, and Grenoble centers.
- Electric:Battery-electric powertrains with zero tailpipe emissions command price premiums in Île-de-France where unrestricted access and parking incentives apply.
- Hybrid:Combined internal combustion and electric motor systems split demand between mild-hybrid cost efficiency and plug-in hybrid range flexibility.
Volume placements concentrate in Petrol; the steepest expansion trajectory belongs to Electric.
Age Category:
Application-driven selection separates warranty-protected recent registrations from value-optimized older assets with elevated mechanical risk.
- Less than 3 Years:Near-new vehicles retaining manufacturer warranty coverage capture corporate fleet rotation programs. Enterprise buyers in Paris accelerate procurement of this cohort to meet electrification mandates while avoiding new-vehicle depreciation absorption.
- 3 to 5 Years:Depreciation-stabilized assets with documented service histories balance purchase price against remaining operational life. Family buyers in Toulouse and Nantes metropolitan zones concentrate here for Crit'air-compliant second vehicles.
- 5 to 10 Years:Higher-mileage vehicles with compressed price points serve budget-constrained rural buyers outside low-emission zone jurisdictions.
- More than 10 Years:Vintage and utility-focused transactions occupy niche restoration and agricultural application segments.
Volume placements concentrate in 3 to 5 Years; the fastest share gain belongs to Less than 3 Years.
Sales Channel:
Customer type differentiation separates trust-seeking dealership patrons from price-sensitive digital natives and transaction-cost-minimizing private parties.
- Dealerships:Brick-and-mortar operations with physical inspection facilities and statutory warranty obligations retain risk-averse buyer segments. Provence-Alpes-Côte d'Azur penetration gaps persist where rural dealer consolidation lags urban density.
- Online Platforms:Digital marketplaces with remote verification tools and nationwide inventory aggregation are displacing traditional foot traffic. Younger demographics in Paris and Lyon exhibit highest transaction willingness through these channels.
- Private Sellers:Direct peer-to-peer transactions with minimal intermediary fees persist through classifieds platforms.
- Auctions:Wholesale disposal channels for fleet operators and financial institutions managing volume de-fleeting.
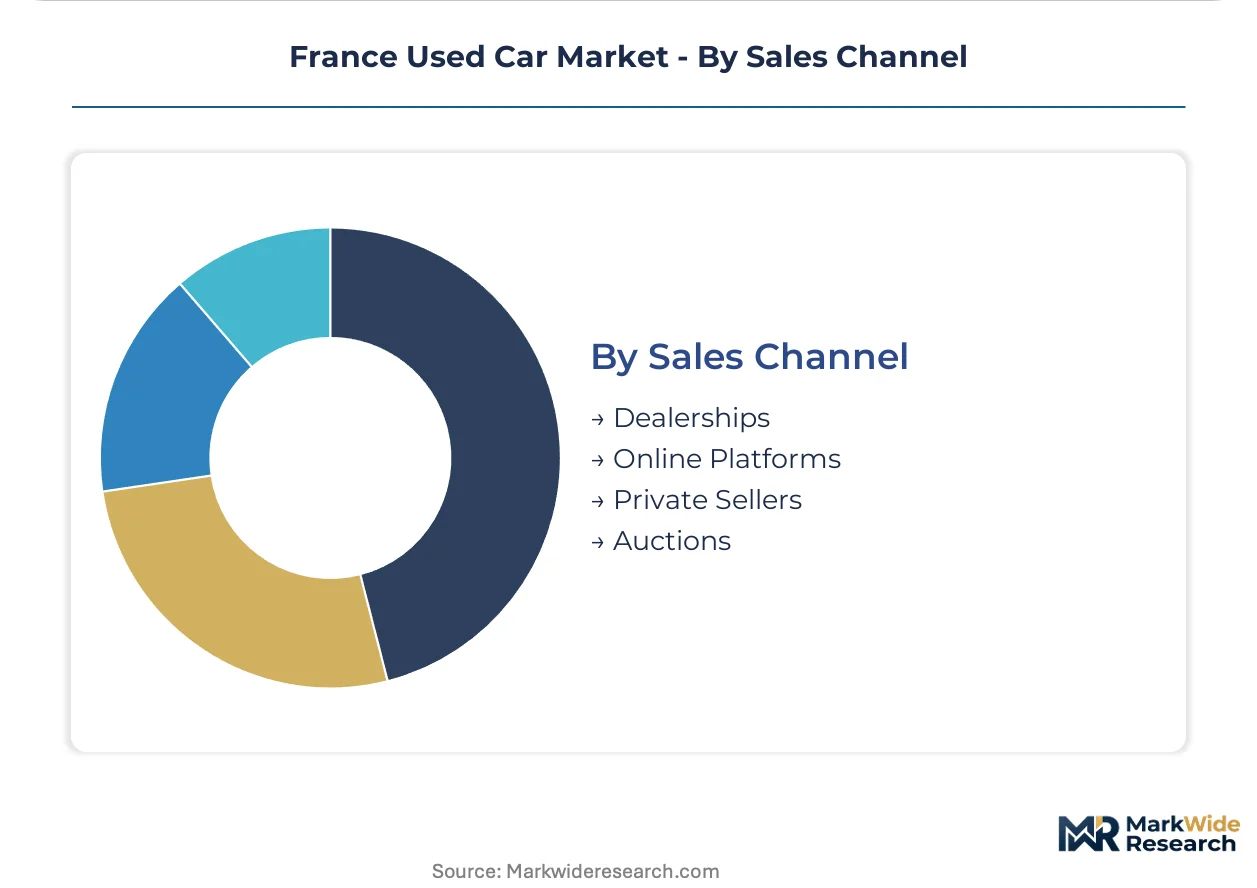
Volume placements concentrate in Dealerships; the fastest expansion belongs to Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France anchors France's used car transaction velocity through Paris metropolitan congestion pricing and Crit'air access restrictions that concentrate demand for compliant vehicle cohorts. The region's regulatory stringency creates pricing premiums for cleaner powertrains while compressing resale windows for restricted categories.
Île-de-France
Corporate fleet operators and ride-hailing services drive procurement of pre-owned hybrid and electric vehicles to meet sustainability mandates without absorbing new-car depreciation. The Crit'air framework administered by the Paris metropolitan authority restricts older diesel vehicles from accessing city centers and directly shapes resale values by registration date. Transaction concentration in Paris proper and inner-ring suburbs reflects parking scarcity and access restriction severity that reduce pure ownership utility.
Auvergne-Rhône-Alpes
Lyon metropolitan buyers prioritize hatchback configurations for Crit'air-compliant daily commuting without sacrificing load practicality for family use. The Grand Lyon's low-emission zone enforcement mirrors Paris scheduling and reprices diesel cohorts ahead of ban implementation. Inventory rotation pressures mount for dealers in Grenoble holding pre-2011 registrations now excluded from city center access.
Provence-Alpes-Côte d'Azur
Secondary cities outside Paris orbit show lower digital transaction penetration and fragmented dealer consolidation, creating white space for platform expansion. Marseille metropolitan access restrictions under Crit'air categories 3-5 redirect demand toward cleaner used cars. SUV segments command family buyer attention across the region where road trip utility outweighs urban parking penalties.
Hauts-de-France
Budget-constrained rural buyers outside low-emission zone jurisdictions sustain demand for higher-mileage vehicles with compressed price points. The Lille metropolitan zone's Crit'air implementation lags Paris and Lyon scheduling, creating temporary arbitrage windows for non-compliant inventory. Cross-border flows from Belgium create documentation friction under divergent national registration systems.
Nouvelle-Aquitaine
Bordeaux and Toulouse metropolitan zones concentrate family buyer demand in the 3 to 5 year age category for Crit'air-compliant second vehicles. The region's lower congestion pricing exposure preserves transaction velocity for older petrol powertrains excluded from Paris premiums. Rural agricultural applications sustain niche demand for vintage utility vehicles beyond standard depreciation curves.
France Used Car Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification and refurbishment depth, with manufacturer-backed programs commanding trust premiums over independent dealer networks. The market structure fragments across digital platforms, traditional dealership groups, and manufacturer-certified programs with divergent cost bases. Three archetypes dominate: classifieds aggregators with traffic scale, refurbishment-integrated dealer networks with quality standardization, and manufacturer-certified programs with warranty backing. Competitive moves concentrate on digital verification infrastructure deployment and regional refurbishment capacity expansion.
Within the classifieds aggregator tier, Leboncoin and La Centrale exemplify traffic-scale positioning that sustains dominant peer-to-peer transaction volumes. Aramis Group occupies a position in the refurbishment-integrated network archetype through its nationwide preparation centers. Stellantis Spoticar represents manufacturer-certified supply integration by anchoring former fleet vehicles within established dealer infrastructure.
| Leading Market Players |
|---|
| Leboncoin |
| Aramis Group |
| AutoScout24 |
| Stellantis Spoticar |
| Auto1 Group |
| La Centrale |
| Reezocar |
| Heycar |
| BYmyCAR Group |
| Others |
Supply Flow & Price Mechanics
Steel price index volatility cascades through France's used car refurbishment network, compressing margins at preparation centers and forcing tiered pricing stratification across certified and uncertified inventory tiers.
Pricing Analysis
Value-based pricing anchored to Crit'air compliance tier separates premium-grade certified pre-owned vehicles from standard independent dealer offerings. Certification level and refurbishment depth drive price differentiation, with manufacturer-backed programs commanding trust premiums over basic dealer preparation. Cost compression in the diesel segment intensifies as ban waves approach, eroding residual values for non-compliant cohorts. Fleet operators exhibit lowest price sensitivity due to total cost of ownership mandates, while private sellers in peer-to-peer channels show highest elasticity.
Supply Chain Analysis
Vehicle sourcing rests on former fleet disposals from Germany, Spain, and Italy feeding French refurbishment pipelines. Battery-electric and hybrid inventory draws from corporate electrification rotations, while petrol and diesel supply feeds from lease returns and rental fleet turnover. Single-source vulnerability concentrates in high-voltage diagnostic equipment for electric vehicle preparation. Distribution runs through regional refurbishment centers to dealership networks and digital platform fulfillment hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's used car market has become a vertical-integration race, with players capturing upstream refurbishment capacity and downstream digital channels to control quality certification and pricing power.
For Market Incumbents: Deploy captive refurbishment infrastructure to standardize quality across fragmented regional inventories. Stellantis Spoticar and Aramis Group already anchor preparation networks; competitors must match this scale to defend against platform commission compression. Accelerate battery health certification investment before EU battery passport mandates enforce diagnostic infrastructure requirements. For New Entrants and Emerging Players: Capture the Provence-Alpes-Côte d'Azur digital penetration gap where secondary cities show fragmented dealer consolidation and lower online transaction maturity. Marseille and Nice metropolitan zones offer white-space entry with subscription-to-own financing hybrids targeting younger demographics excluded from traditional auto financing. For Investors and Strategic Acquirers: Distressed-cycle entries favor refurbishment-integrated dealer networks in Auvergne-Rhône-Alpes where Grenoble's Crit'air implementation has repriced diesel inventory ahead of broader market adjustment. Long-term viability hinges on electric vehicle preparation capability scaling. Watch battery-electric transaction velocity in Île-de-France as the inflection signal for platform valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Refurbishment Capacity Expansion | Aramis Group's nationwide preparation centers standardize quality across regional inventories. |
| Digital Verification Infrastructure | Blockchain-based provenance tools reduce buyer risk perception and expand online transaction willingness. |
| Manufacturer-Certified Program Scaling | Stellantis Spoticar integrates former fleet vehicles into established dealer warranty networks. |
| Subscription-to-Own Financing Launch | Flexible ownership models capture demographics excluded from traditional auto financing in Paris and Lyon. |
| Battery Health Certification Investment | EU battery passport requirements create first-mover advantage for diagnostic infrastructure deployment. |
Methodological Framework
Independent corroboration across dealership operations data, digital platform transaction records, and fleet operator procurement disclosures underwrites the qualitative findings. Primary interviews with refurbishment center managers, used car procurement leads at corporate fleets, digital platform executives, and DGCCRF compliance officers combined with secondary validation from vehicle registration databases, Crit'air enforcement schedules, and EU Green Deal regulatory filings. Bottom-up transaction volume modeling and top-down market sizing triangulate to the segment outputs.
Rate-of-change decomposition separates volume growth from value-per-transaction expansion across the analysis window. Segmentation dimensions include vehicle type, fuel architecture, age category, and sales channel, with Crit'air compliance tier modeled as an overlay dimension affecting regional price realization. CAGRs derive from regression against macroeconomic drivers and regulatory enforcement schedules, with fleet electrification rotation rates and metropolitan access restriction timing as automotive-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal acceleration, battery-electric resale value stabilization, and Crit'air ban wave scheduling revisions. Forecasts reflect documented assumptions about fleet operator procurement behavior and digital platform penetration trajectories. Regulatory cliff effects, cross-border import documentation friction, and electric vehicle technician scarcity warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Vintage Car Market
Used Vehicles
Used E-Scooter Market
Used Vehicles
Australia Used Car Market
Used Vehicles
North America Used Truck Market
Used Vehicles
United Arab Emirates Used Car Market
Used Vehicles
United States Used Car Market
Used Vehicles
Used Semi Truck Market
Used Vehicles
Netherlands Used Car Market
Used Vehicles
United Kingdom Used Car Market
Used Vehicles
UAE Certified Pre-Owned Car Market
Used Vehicles
Bangladesh Used Car Market
Used Vehicles
Myanmar Used Car Market
Used Vehicles
Poland Used Car Market
Used Vehicles
Belgium Used Car Market
Used Vehicles
Switzerland Used Car Market
Used Vehicles
Finland Used Car Market