
 Global Animal Feed Dietary Fibers Market | 2026-2036
Global Animal Feed Dietary Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Animal Feed Dietary Fibers Market Analysis
Aquaculture and ruminant nutrition is realigning the buyer landscape for animal feed dietary fibers as producers seek gut health solutions that replace antibiotic growth promoters. Cargill leverages its global oilseed processing footprint to secure consistent supply of soy hulls and other fibrous coproducts for feed compounding. Archer Daniels Midland Company sustains its position through integrated carbohydrate science platforms that tailor soluble fiber grades for monogastric and ruminant species. Roquette Frères differentiates via pea and potato fiber extraction technologies originally developed for human nutrition, now adapted for premium feed applications.
Animal feed dietary fibers comprise complex polysaccharides and ligneous compounds resistant to endogenous enzymatic digestion, functioning primarily as fermentable substrates for hindgut or rumen microbiota to modulate digestive efficiency, satiety signaling, and metabolic waste output. Cellulose and hemicellulose fractions dominate volume flows due to their abundance in cereal grain processing residues and oilseed meals, though pectin concentrates command premium positioning in calf starter and transition cow diets where mucosal integrity and acidosis prevention carry high economic value. Poultry application segments show structural momentum as broiler integrators adopt insoluble fiber sources to improve gizzard development and nutrient retention density.
The EU Green Deal and F-Gas Regulation impose escalating emissions-accounting requirements on livestock supply chains, directly shaping fiber ingredient procurement specifications through carbon intensity scoring. The FDA and USDA jointly oversee feed ingredient safety via the Food Safety Modernization Act and the Association of American Feed Control Officials model regulations, creating compliance layers that favor suppliers with documented quality management systems. Stakeholders must monitor evolving methane quantification protocols and their translation into contracted feed specifications across integrated protein value chains.
Market Dynamics
The EU F-Gas Regulation and Green Deal are compressing methane accounting tolerances across livestock supply chains, forcing feed formulators to source verified low-carbon fiber ingredients with documented carbon intensity scores. This regulatory compression is restructuring procurement specifications and supplier qualification protocols.
Growth Catalysts
- EU F-Gas Regulation:Escalating emissions-accounting requirements for livestock operations are mandating verified low-carbon fiber sourcing, creating procurement pull for suppliers with documented carbon scoring systems.
- Ruminant nutrition science:Precision fermentation modeling is optimizing rumen function through targeted soluble fiber inclusion, reducing enteric methane output in dairy and beef operations.
- Brazil:Integrated protein producers are scaling precision nutrition programs for export-oriented beef and poultry supply chains, concentrating demand for high-fiber feed formulations.
Market Restraints
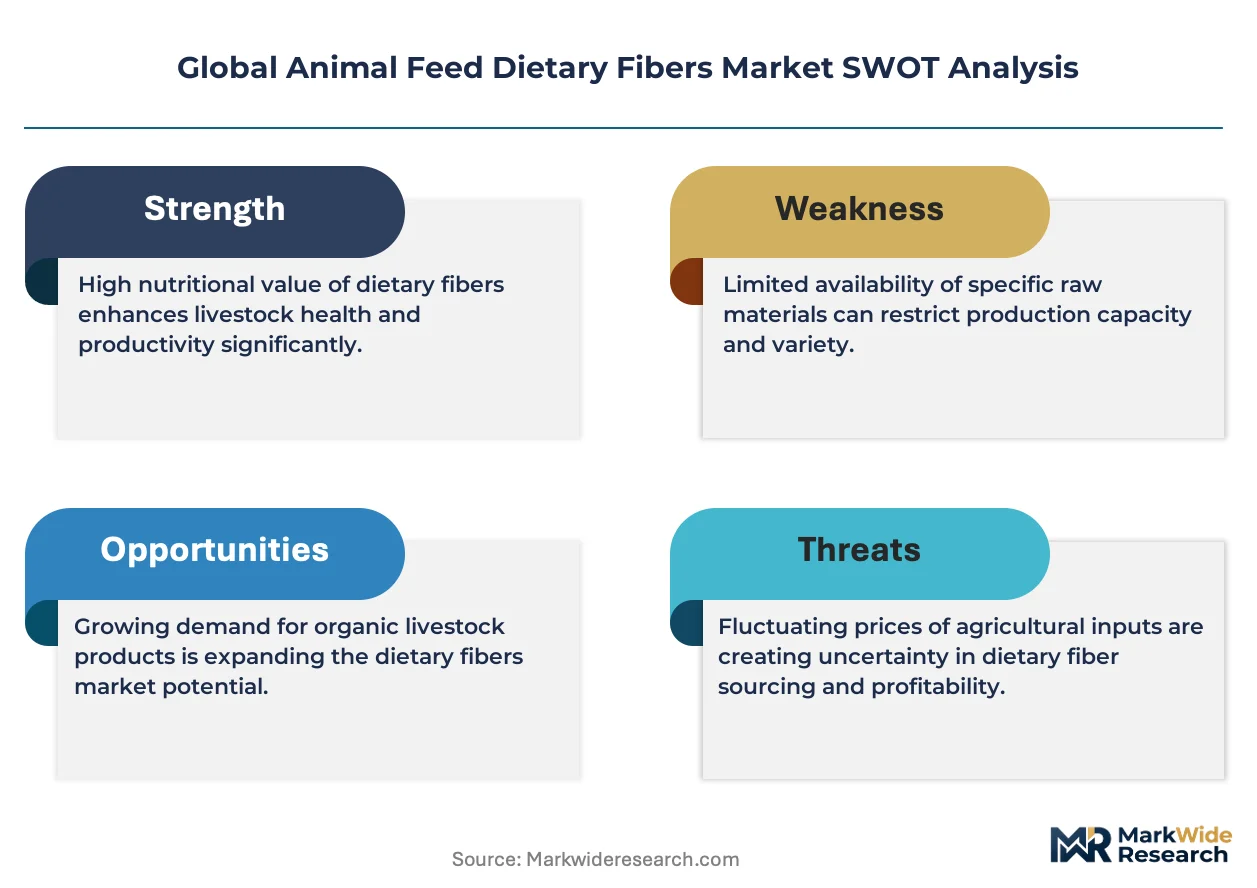
- Input cost volatility:Soy hull and wheat middling prices fluctuate with oilseed processing margins and grain harvest cycles, compressing formulator margins during commodity spikes.
- Supply concentration risk:Pea fiber extraction capacity clusters in northern France and Manitoba, creating geographic vulnerability for premium pectin concentrate supply.
- Technical limitation:Insoluble fiber inclusion above 8% in broiler diets degrades pellet durability and feed mill throughput, capping adoption rates in high-performance poultry operations.
Strategic Opportunities
- Vietnam:Underpenetrated aquaculture feed markets present white space for fermentable fiber solutions targeting shrimp gut health and disease resistance.
- CSRD alignment:Corporate Sustainability Reporting Directive scope expansion is creating demand for fiber ingredients with blockchain-verified supply chain emissions data.
- Near-infrared spectroscopy:Converging with AI-driven formulation software, this technology enables real-time fiber fraction optimization in feed mills.
Industry Challenges
- Microbiome modeling talent:Shortage of ruminant nutritionists trained in computational fermentation kinetics limits precision fiber dosing adoption.
- Carbon certification timelines:Third-party validation of feed ingredient carbon intensity under ISO 14067 protocols extends 14-18 months, delaying contract eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Animal Feed Dietary Fibers Market |
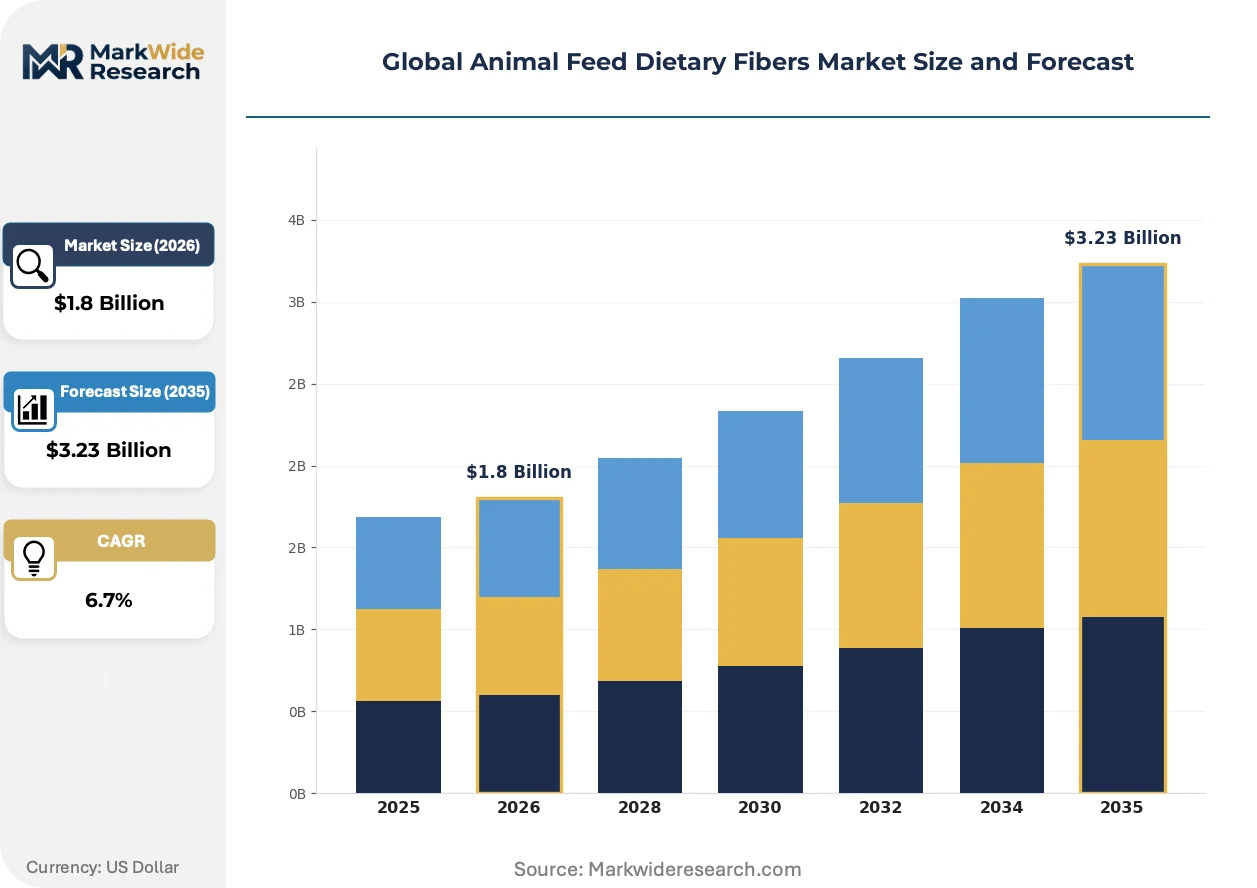
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulose, Hemicellulose, Lignin, Pectin Application: Poultry, Ruminants, Swine, Aquaculture Form: Powder, Granule, Pellet, Flake End User: Producers, Farm Owners, Distributors, Research Institutions |
| Companies Covered | Cargill, Archer Daniels Midland Company, Ingredion Incorporated, Bunge Limited, Nutreco, DuPont de Nemours, Roquette Frères, Kerry Group, Alltech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Animal Feed Dietary Fibers Market Emerging Trajectories
Active ingredient fractionation and in-vitro fermentation modeling are displacing empirical formulation approaches, enabling species-specific fiber blends with quantified microbiome outcomes. These capabilities are compressing the gap between human nutrition science and animal feed applications.
Enzymatic fiber modification technology is absorbing capital from major oilseed processors seeking to upgrade soy hulls from bulk filler to functional prebiotic ingredients. Poultry integrators in the southeastern United States are adopting these modified fractions at pilot scale. The technology is absorbing margin pressure from commodity soy meal volatility by creating premium-priced soluble fiber concentrates with documented butyrate production rates.
REACH authorization requirements for novel feed additives are extending substance approval timelines to 36-48 months, forcing European formulators to rely on legacy fiber sources. This regulatory friction is diverting innovation investment toward jurisdictions with streamlined novel ingredient pathways. South American feed compounders are capturing displaced European R&D spending by hosting accelerated safety trials under ANVISA protocols.
Buyer concentration among integrated protein producers is consolidating procurement decisions into centralized nutrition teams with dedicated fiber specialists. Traditional distributor networks are losing share to direct supplier relationships with documented quality management systems. This channel compression is most visible in Brazil, where JBS and BRF have internalized feed formulation capabilities and now contract fiber suppliers on multi-year volume agreements with embedded carbon clauses.
Global Animal Feed Dietary Fibers Market Segmentation
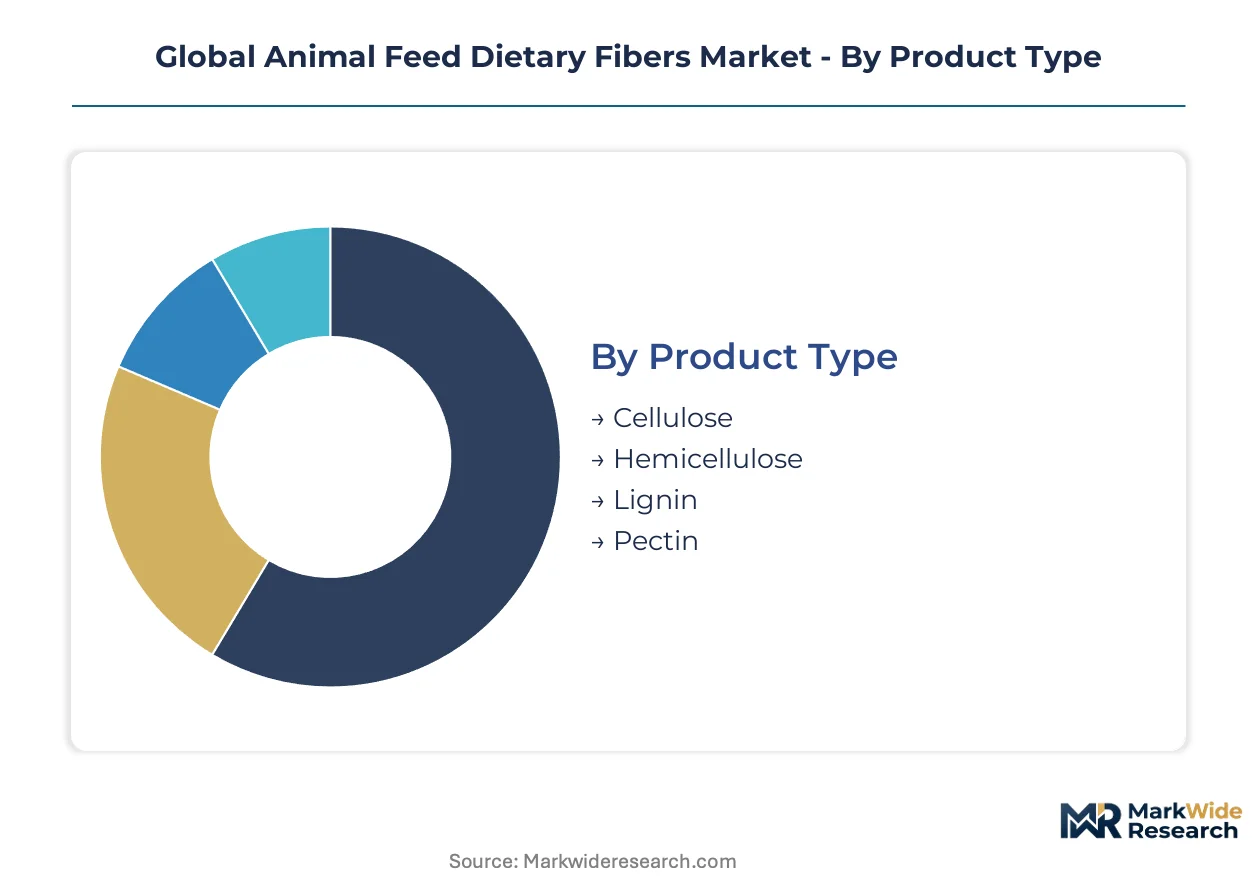
Animal feed dietary fibers demand heterogeneous specification profiles across species, processing formats, and buyer sophistication levels. Segmentation reveals where functional differentiation commands premium positioning versus commodity bulk flows.
Product Type:
Customization intensity spans from standardized bulk cellulose to precision-extracted pectin concentrates with documented fermentation kinetics.
- Cellulose:Crystalline and amorphous glucose polymer fractions derived from cereal processing residues and cottonseed linters. Dairy operations in Wisconsin and Bavaria standardize on this insoluble fiber source for rumen fill and dry matter intake management, with procurement specifications tightening around ash content and particle size distribution.
- Hemicellulose:Branched heteropolysaccharides (xylose, arabinose, mannose backbones) abundant in soy hulls and wheat bran. Broiler integrators in São Paulo state are expanding inclusion rates for gizzard development and nutrient retention, though pellet durability constraints cap formulations at 6-8% inclusion.
- Lignin:Phenolic polymer matrix providing structural rigidity to plant cell walls, functionally inert in monogastric digestion. Serves primarily as low-cost filler in ruminant maintenance rations where energy dilution benefits body condition scoring.
- Pectin:Galacturonic acid-rich soluble fiber extracted from citrus peels and sugar beet pulp. Calf starter formulations in the Netherlands and Pennsylvania specify high-methoxyl grades for mucosal integrity and acidosis prevention during weaning transitions.
Leading the category by volume: Cellulose. Growing fastest: Pectin.
Application:
Species-specific digestive physiology dictates fiber functionality requirements and formulation complexity tiers.
- Poultry:Insoluble fiber sources improve gizzard musculature and reverse peristalsis for enhanced nutrient retention. Southeastern US broiler operations are adopting enzymatically modified soy hull fractions at commercial scale.
- Ruminants:Fermentable fiber optimization drives rumen pH stability and methane mitigation. EU F-Gas Regulation compliance is mandating verified low-carbon sourcing for dairy and beef supply chains.
- Swine:Soluble fiber inclusion modulates hindgut fermentation and manure consistency. Nursery diet specifications in Denmark emphasize fermentable substrates for gut health replacement of antibiotic growth promoters.
- Aquaculture:Shrimp and salmon formulations utilize prebiotic fiber fractions for disease resistance. Vietnamese aquafeed producers represent underpenetrated white space for gut health solutions.
Volume concentration: Ruminants. Steepest expansion trajectory: Aquaculture.
Form:
Processing format determines handling economics, inclusion uniformity, and feed mill throughput compatibility.
- Powder:Fine-milled fractions for premix and liquid feed applications. Precision dosing in automated systems favors this format for soluble fiber concentrates.
- Granule:Agglomerated particles balancing flowability and dissolution kinetics. Standard for ruminant TMR inclusion across North American dairy operations.
- Pellet:Compressed fiber sources integrated into complete feeds. Broiler operations prioritize this format for mechanized feeding systems, though high inclusion degrades pellet durability.
- Flake:Thin-layer dried products from beet pulp and citrus processing. Calf starter applications in France and Germany specify flaked formats for palatability and hydration capacity.
Highest throughput efficiency: Granule. Premium pricing capture: Powder.
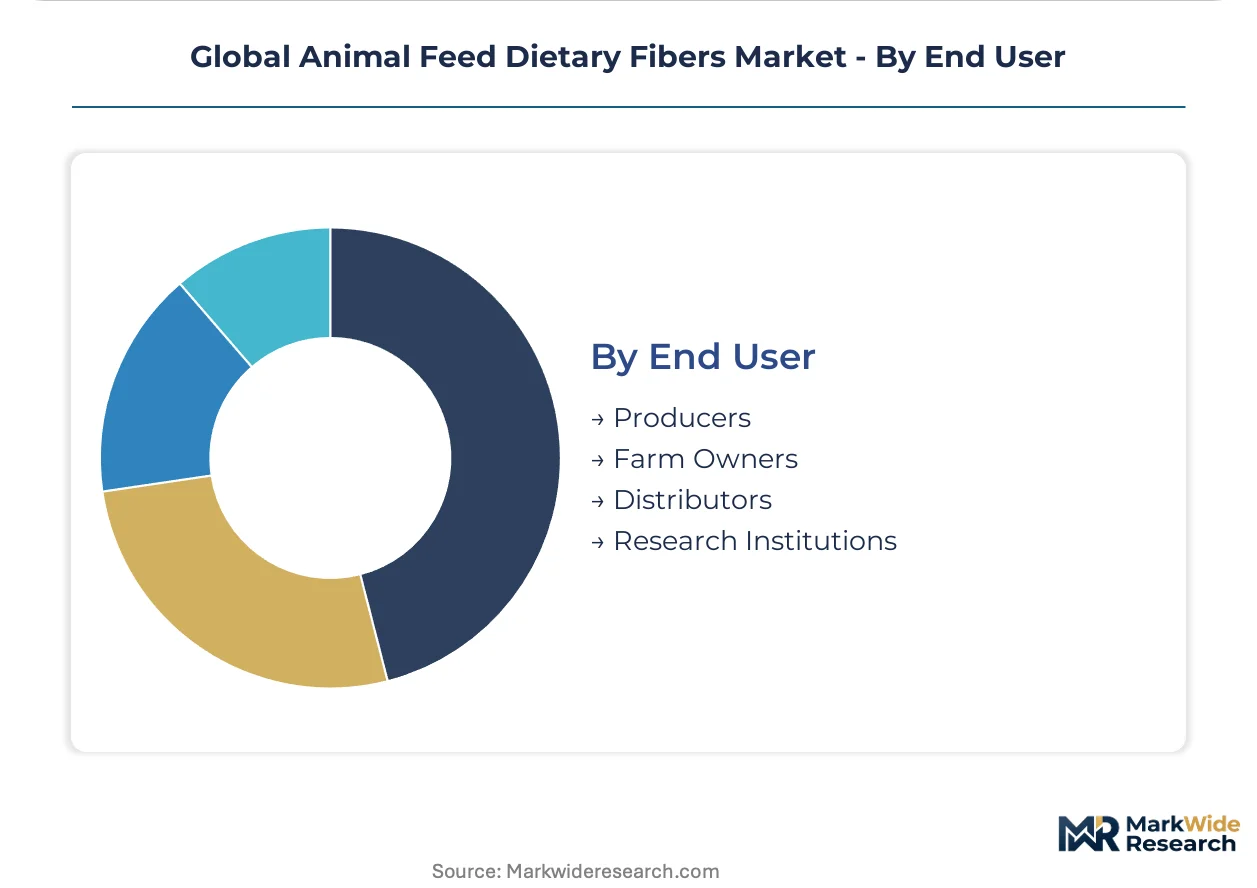
End User:
Buyer sophistication and procurement centralization create distinct service requirements and contract structures.
- Producers:Integrated protein companies with internalized nutrition teams and multi-year fiber supply agreements. JBS and BRF in Brazil contract directly with suppliers on volume commitments with embedded carbon clauses.
- Farm Owners:Independent operations purchasing through distributor networks or cooperative buying groups. Specification adherence and local technical support drive supplier selection.
- Distributors:Intermediary channels consolidating fragmented demand, losing share to direct supplier relationships as buyer concentration advances.
- Research Institutions:Universities and contract research organizations sourcing characterized fiber fractions for fermentation modeling and microbiome studies. Small volumes, high documentation requirements.
Contract value concentration: Producers. Fastest relationship growth: Research Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in agricultural processing corridors while consumption gravitates toward intensive livestock regions with tightening emissions regulations. Brazil and the United States dominate supply-side fiber extraction from oilseed and grain processing, whereas European and Asian markets drive specification intensity for verified low-carbon ingredients.
United States
Dairy operations in Wisconsin and California expand fermentable fiber inclusion to optimize rumen function and meet processor sustainability requirements. The FDA and USDA jointly oversee feed ingredient safety through the Food Safety Modernization Act and AAFCO model regulations. Iowa and Illinois soybean processing clusters supply soy hull fractions to domestic compounders and export markets.
Brazil
Integrated protein producers JBS and BRF scale precision nutrition programs for export-oriented beef and poultry supply chains. ANVISA protocols attract displaced European R&D investment for accelerated novel ingredient safety trials. São Paulo state broiler integrators adopt enzymatically modified fiber fractions at commercial pilot scale.
Germany
Dairy cooperatives in Bavaria and Lower Saxony standardize on insoluble cellulose sources for dry matter intake management. The EU F-Gas Regulation and Green Deal mandate verified low-carbon fiber sourcing with documented carbon intensity scores. Northern feed mills near Hamburg and Bremen consolidate procurement through centralized nutrition teams.
Netherlands
Calf starter formulations specify high-methoxyl pectin grades for mucosal integrity during weaning transitions. The EU Green Deal compresses methane accounting tolerances across livestock supply chains. Wageningen University clusters drive fermentation modeling research with contract research organizations.
Vietnam
Underpenetrated aquaculture feed markets present expansion opportunities for fermentable fiber solutions targeting shrimp gut health. The country's national feed safety regulator maintains streamlined novel ingredient pathways relative to European timelines. Mekong Delta processing facilities import soluble fiber concentrates for premium shrimp formulations.
Global Animal Feed Dietary Fibers Market Vendor Landscape
Top-tier vendors anchor integrated oilseed processing, while mid-tier specialists extract premium fractions from pulse and tuber streams. The vendor base stratifies across three capability tiers: global grain traders with captive coproduct supply, regional compounders with formulation expertise, and technology licensors with enzymatic modification platforms. Dominant competitive moves include backward integration into oilseed crushing assets and multi-year supply agreements with embedded carbon clauses.
Within the integrated processor tier, Cargill leverages its global oilseed footprint to secure consistent soy hull supply, while Archer Daniels Midland Company sustains position through carbohydrate science platforms. Roquette Frères occupies a specialist position, adapting pea and potato fiber extraction technologies from human nutrition applications to premium feed segments.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Bunge Limited |
| Nutreco |
| DuPont de Nemours |
| Roquette Frères |
| Kerry Group |
| Alltech |
| Others |
Supply Flow & Price Mechanics
Integrated protein producers in Brazil and the United States concentrate procurement decisions into centralized nutrition teams, forcing contract-based long-term offtake structures with embedded carbon clauses onto fiber suppliers. This buyer consolidation compresses margin capture for mid-tier extractors while rewarding integrated processors with captive oilseed crushing assets.
Pricing Analysis
Margin tightening in premium pectin concentrates reflects supply concentration in northern France and Manitoba, where extraction capacity bottlenecks prop pricing power for functional fiber grades. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14067-certified carbon-scored ingredients from commodity cellulose fillers. Cost-down pressure on soy hull fractions accelerates because oilseed processing margin volatility transmits directly into coproduct pricing. Independent farm owners exhibit highest price sensitivity, while JBS and BRF nutrition teams prioritize verified low-carbon sourcing over unit cost.
Supply Chain Analysis
Direct-to-producer channels handle integrated buyer demand, displacing traditional distributor networks across North American and South American feed markets. Supply concentrates in Brazil, the United States, and northern France, where oilseed crushing clusters and pulse processing facilities anchor fiber extraction capacity. Raw material flows draw from soy hulls, wheat middlings, and sugar beet pulp, with enzymatic modification technology upgrading bulk fractions into functional prebiotics. Single-source vulnerability in pea fiber extraction creates geographic risk for premium pectin concentrate supply. Distribution runs through multi-year volume agreements with quality management system documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Premium pectin concentrate supply bottlenecks in northern France and Manitoba prop pricing power for certified suppliers, creating defensive moats around functional fiber extraction capacity.
For Market Incumbents: Hedge margin compression from commodity soy hull volatility by accelerating enzymatic modification technology deployment to upgrade bulk coproducts into premium soluble fiber concentrates with documented butyrate production rates. Secure backward integration into oilseed crushing assets in Iowa and Illinois soybean processing clusters to captive supply of fibrous coproducts. Defend position against South American feed compounders capturing displaced European R&D investment by embedding blockchain-verified carbon scoring into existing quality management systems. For New Entrants and Emerging Players: Begin with Vietnamese aquaculture feed markets, where underpenetrated shrimp gut health applications present white space for fermentable fiber solutions without entrenched supplier relationships. Target Mekong Delta processing facilities importing soluble fiber concentrates as initial anchor customers. Pursue ANVISA protocol advantages for accelerated novel ingredient safety trials relative to European REACH authorization timelines, positioning enzymatic modification platforms for premium shrimp formulations. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap enzymatic modification technology licensors in South America, where ANVISA regulatory arbitrage attracts displaced European innovation investment. Long-term viability over the projection horizon rests on fiber fractionation capabilities converging with AI-driven formulation software for real-time optimization. Monitor methane quantification protocol standardization across EU F-Gas Regulation compliance frameworks as inflection indicator for contracted feed specification intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill and ADM secure captive soy hull supply through Iowa and Illinois processing clusters. |
| Enzymatic Modification Technology Deployment | Upgrades bulk cellulose fractions into premium prebiotic concentrates with documented fermentation kinetics. |
| Blockchain-Verified Carbon Scoring Implementation | Aligns supplier qualification with EU F-Gas Regulation emissions-accounting requirements for dairy operations. |
| ANVISA Protocol Acceleration | Brazilian compounders capture displaced European R&D investment through streamlined novel ingredient pathways. |
| Near-Infrared Spectroscopy Integration | Converges with AI-driven formulation software for real-time fiber fraction optimization in feed mills. |
Methodological Framework
Trade databases, oilseed processing industry reports, and EU regulatory filings formed the secondary backbone, cross-referenced against primary interviews with ruminant nutritionists, feed procurement managers at integrated protein producers, enzymatic modification technology developers, and ANVISA regulatory affairs specialists. Bottom-up volume modeling from fiber extraction capacity data triangulated against top-down expenditure analysis from livestock operations sustainability disclosures.
Historical trendline analysis of soy hull and wheat middling price cycles informed elasticity assumptions across the projection horizon. Segmentation dimensions modeled include product type tier, species application, processing format, and buyer sophistication level. CAGRs derived from compound growth trajectory analysis of oilseed coproduct value capture and precision nutrition program adoption rates. Forecast inputs incorporated EU F-Gas Regulation compliance timeline acceleration and Brazil integrated protein producer procurement centralization patterns.
Underlying measurement precision varies by segment; pectin concentrate volumes carry tighter precision than commodity cellulose flows given extraction capacity concentration. Forecasts reflect assumptions around methane quantification protocol standardization and carbon certification timeline compression. Periodic stress-testing of base assumptions is recommended against regulatory enforcement intensity and oilseed processing margin volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Vietnam Floriculture Market
Agriculture and Agri Products
UAE Agriculture Market
Agriculture and Agri Products
GCC Compound Feed Market
Agriculture and Agri Products
China Animal Protein Market
Agriculture and Agri Products
Russia Compound Feed Market
Agriculture and Agri Products
Global Commercial Seaweeds Market
Agriculture and Agri Products
United Kingdom Animal Protein Market
Agriculture and Agri Products
American Ginseng Market
Agriculture and Agri Products
Alfalfa Pellets Market
Agriculture and Agri Products
Africa Olive Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
Centella Asiatica Market
Agriculture and Agri Products
Tissue Cultured Date Palm Market
Agriculture and Agri Products
North America Bee Products Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
Philippines Feed Industry Market