
 Battery Pack for Marine Hybrid and Full Electric Propulsion Market | 2026-2036
Battery Pack for Marine Hybrid and Full Electric Propulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Pack for Marine Hybrid and Full Electric Propulsion Market Analysis
Market Dynamics
Marine battery systems engineering talent is collapsing across European shipyards, constraining installation throughput and extending delivery timelines for hybrid retrofits. Siemens Energy leverages its shore-to-ship power heritage to anchor large-format naval architecture projects. Corvus Energy dominates Nordic ferry electrification through its Oslo-centered manufacturing footprint. CATL extends its automotive cell scale into maritime-certified pack assembly, competing on cost at the expense of local service density.
Technology and Segmentation
Battery pack for marine hybrid and full electric propulsion refers to integrated electrochemical storage systems housed in IP-rated enclosures with active thermal management, typically delivering 500 kWh to 10 MWh per vessel for diesel-electric hybrid or zero-emission operation. Lithium-ion chemistry leads commercial installations due to proven cycle life and declining cell cost curves, while solid-state architectures attract R&D capital for their energy density advantages in space-constrained hull designs. Commercial vessels generate the dominant revenue pool today, though fishing trawlers represent a faster-growing application as coastal nations restrict emissions in territorial waters.
Regulatory Environment
The International Maritime Organization enforces carbon intensity indicator thresholds that ratchet tighter through 2030, forcing shipping companies to document emissions reductions or face operational penalties. EPA and EU MRV frameworks impose parallel reporting obligations on vessels calling at US and European ports, creating overlapping compliance costs that accelerate capital shifts toward electrification. Stakeholders must monitor how port infrastructure electrification timelines synchronize with vessel replacement cycles to avoid stranded asset risk in hybrid configurations.
Market Dynamics
The International Maritime Organization's carbon intensity indicator thresholds are compressing vessel replacement cycles and forcing capital reallocation toward electrochemical propulsion systems before shore infrastructure matures.
Growth Catalysts
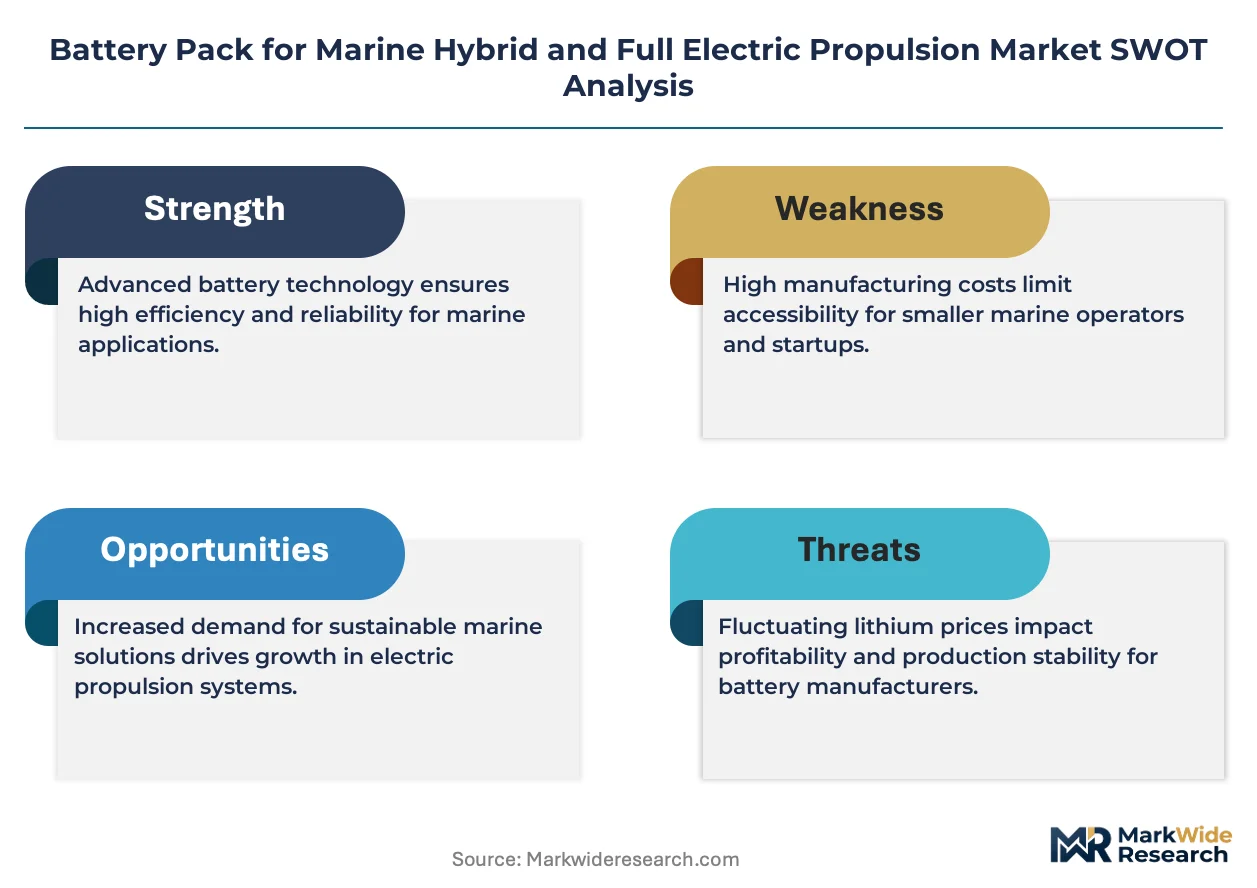
- Norway's zero-emission fjord mandate:Coastal regulations require emission-free operation in UNESCO-protected waterways, compelling ferry operators to procure battery-dominant hybrid architectures ahead of vessel end-of-life.
- Lithium iron phosphate cell chemistry:Thermal stability and extended cycle life are displacing NMC formulations in commercial marine applications where safety certification dominates procurement criteria.
- EU Green Deal maritime funding:The European Commission's Innovation Fund channels capital toward port electrification and vessel retrofit projects, reducing payback periods for battery system investments.
Market Restraints
- Cobalt and nickel price volatility:Cell cost instability constrains pack pricing predictability for shipyards bidding fixed-price newbuild contracts.
- Nordic manufacturing concentration:Corvus Energy and Siemens Energy anchor production in Norway and Germany, creating geographic supply vulnerability for Asia-Pacific and North American fleet operators.
- Energy density limitations:Lithium-ion gravimetric performance caps usable range for long-haul shipping routes, preserving diesel dominance in deep-sea segments.
Strategic Opportunities
- Japan's coastal cargo electrification:METI subsidies for short-sea shipping battery retrofits remain underpenetrated relative to Nordic adoption curves.
- Solid-state battery convergence:Sulfide electrolyte architectures paired with silicon anodes promise 40% volume reduction for space-constrained engine rooms.
- California port incentive stacking:The state's Harbor Craft Regulation layers with IRA clean vessel tax credits, creating exceptional project economics for terminal tug operators.
Industry Challenges
- Marine electrical systems engineering scarcity:Shipyards in Germany and the Netherlands report 18-month backlogs for certified battery integration specialists, constraining installation throughput.
- DNV and Lloyd's Register certification timelines:Type approval processes for novel thermal management configurations extend 14-22 months, delaying commercial deployment of next-generation pack designs.
- Shipyard legacy diesel-electric integration:Retrofit projects require mechanical and control system reconciliation between existing gensets and new battery inverters, multiplying commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Pack for Marine Hybrid and Full Electric Propulsion Market |
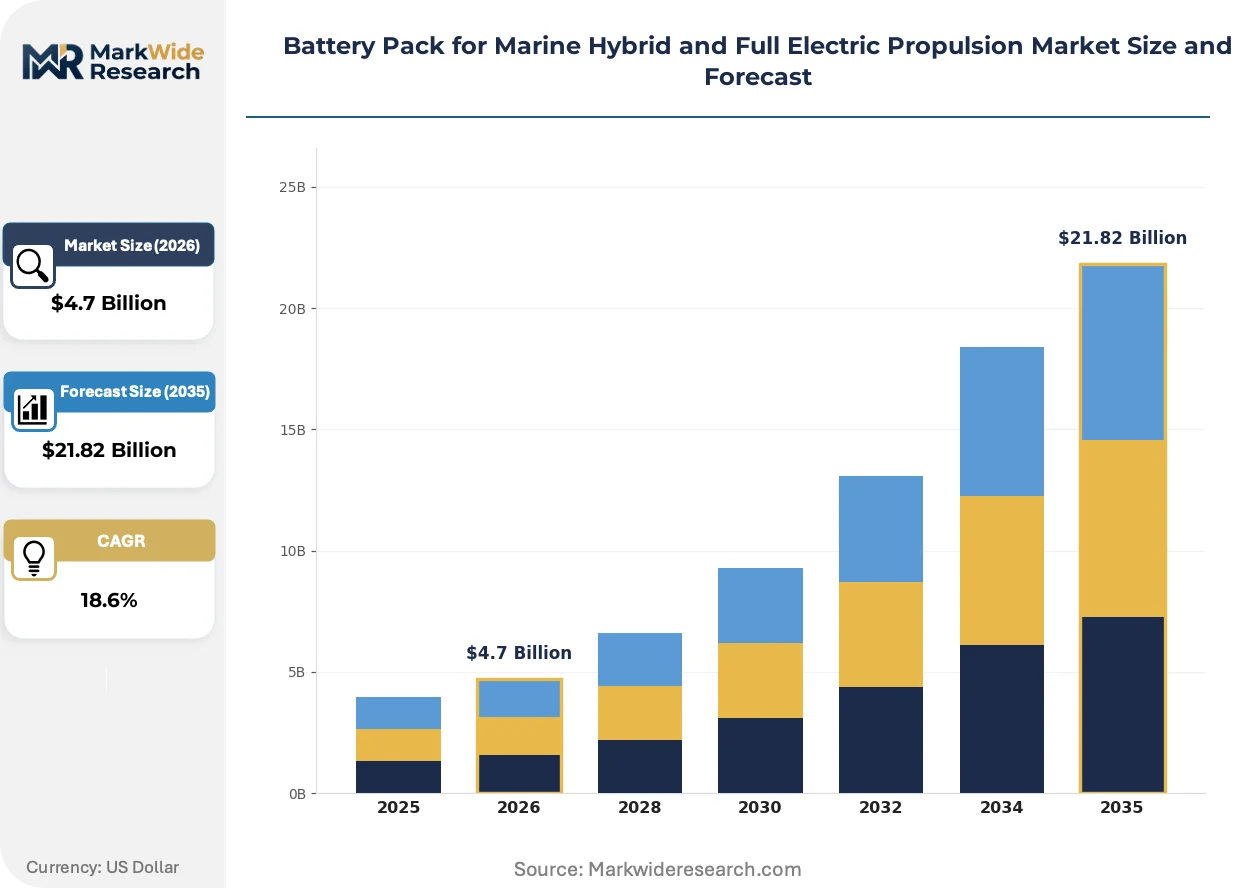
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel Metal Hydride, Lead Acid, Solid State Technology: Rechargeable, Ultracapacitor, BMS Integration, Energy Density Application: Commercial Vessels, Recreational Boats, Fishing Trawlers, Cargo Ships End User: Shipping Companies, Private Owners, Fisheries, Environmental Agencies |
| Companies Covered | Siemens Energy, Toshiba Corporation, Corvus Energy, AYK Energy, Saft Groupe SA, CATL, Leclanché SA, Torqeedo GmbH, EnerSys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Pack for Marine Hybrid and Full Electric Propulsion Market Emerging Trajectories
Battery pack architectures are fragmenting across chemistries and thermal management approaches as shipyards confront divergent operational profiles and certification requirements across vessel classes.
Modular containerized battery systems are decomposing the traditional monolithic pack design. Norwegian ferry operators now specify 20-foot ISO container units that shipyards integrate as plug-in power modules rather than custom hull-embedded installations. This standardization compresses yard time and enables mid-life capacity upgrades without vessel drydocking.
The EU's Fit for 55 package extends emissions trading to maritime transport, forcing Mediterranean cruise operators to document carbon reductions or purchase allowances. Shipowners are responding by specifying hybrid configurations that optimize battery dispatch during port approaches and coastal transits where regulatory scrutiny concentrates.
Charter contract structures now unbundle propulsion system performance risk from hull leases. Greek and Singapore-based shipowners demand battery availability guarantees from system integrators, transferring operational risk and requiring predictive maintenance platforms that monitor cell degradation in real time. This shift is most visible in Northern Europe's short-sea container trades where fuel cost pass-through mechanisms have collapsed.
Battery Pack for Marine Hybrid and Full Electric Propulsion Market Segmentation
Marine battery procurement diverges sharply across vessel classes and operational profiles, with regulatory pressure and duty-cycle requirements fragmenting technology choices. Shipyards must reconcile certification complexity against cell chemistry trade-offs when specifying systems for hybrid retrofits versus full-electric newbuilds.
Product Type:
IMO carbon intensity thresholds and coastal zero-emission mandates create divergent chemistry requirements across route lengths and regulatory zones.
- Lithium-ion:Dominates commercial installations through proven cycle life and declining cell costs. Norwegian ferry operators specify NMC and LFP variants for UNESCO fjord routes where emission-free operation is compulsory.
- Solid State:Sulfide electrolyte architectures paired with silicon anodes promise 40% volume reduction for space-constrained engine rooms. Japanese and Korean shipyards pilot these systems for coastal cargo vessels where energy density premiums justify early adoption costs.
- Nickel Metal Hydride:Retains niche presence in small recreational craft where thermal stability outweighs gravimetric performance penalties.
- Lead Acid:Persists in auxiliary power and emergency backup roles aboard legacy vessels with limited integration budgets.
Established volume favors Lithium-ion; emerging adoption favors Solid State.
Technology:
Integration depth separates cost tiers, with full system architectures commanding premium positioning over component-level supply.
- BMS Integration:Cell-level monitoring and predictive thermal management have become procurement differentiators. DNV and Lloyd's Register certification timelines for novel BMS configurations extend 14-22 months, delaying deployment of next-generation designs.
- Rechargeable:Standard electrochemical storage architectures serve hybrid retrofits where shore power availability constrains operational profiles.
- Ultracapacitor:Bridge power for peak shaving and harbor maneuvering where rapid charge acceptance complements lithium-ion base loads.
- Energy Density:Gravimetric performance specifications determine route feasibility for long-haul applications, preserving diesel dominance in deep-sea segments where cell mass exceeds hull capacity.
Procurement concentrates in BMS Integration for newbuilds; Rechargeable systems dominate retrofit economics.
Application:
Duty-cycle intensity and regulatory exposure create four distinct specification clusters across marine operational categories.
- Commercial Vessels:Ferries and short-sea container ships generate dominant revenue through fleet-scale procurement. EU Green Deal maritime funding channels capital toward port electrification and retrofit projects, reducing payback periods for battery investments in this segment.
- Fishing Trawlers:Coastal emissions restrictions in territorial waters accelerate electrification faster than fleet replacement cycles would predict. Mediterranean and North Sea regulators now mandate zero-emission operation within 12-nautical-mile zones.
- Cargo Ships:Long-haul routes face energy density constraints that limit battery economics to hybrid configurations for port approaches and coastal transits.
- Recreational Boats:Marina infrastructure gaps and seasonal usage patterns constrain adoption outside premium yacht segments.
Commercial Vessels anchor current revenue; Fishing Trawlers climb the fastest as territorial water restrictions tighten.
End User:
Capital structure and risk tolerance fragment procurement behavior across owner categories.
- Shipping Companies:Charter contract innovations now unbundle propulsion performance risk from hull leases. Greek and Singapore-based operators demand battery availability guarantees, transferring operational risk to system integrators.
- Fisheries:Cooperative ownership structures and seasonal cash flows favor subsidized retrofit programs over newbuild electrification.
- Private Owners:Premium yacht specifications drive early adoption of solid-state prototypes where cost sensitivity is lowest.
- Environmental Agencies:Research vessel procurement establishes demonstration platforms for novel chemistries and thermal management approaches.
Shipping Companies concentrate procurement volume; Environmental Agencies provide technology validation pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian shipyards command 35-40% pricing premiums over Asian competitors due to DNV certification density, while Chinese pack assemblers undercut Nordic rates by capturing automotive cell scale. This asymmetry fragments procurement patterns across ferry operators and cargo fleets.
Norway
UNESCO fjord mandates and zero-emission waterway regulations drive battery-dominant ferry procurement at volumes unmatched globally. The Norwegian Maritime Authority enforces strict emission-free operational windows in Geirangerfjord and Nærøyfjord. Bergen and Oslo anchor competing manufacturing clusters where Corvus Energy and Siemens Energy maintain production footprints.
Germany
Shore-to-ship power heritage and naval architecture expertise position German integrators for large-format commercial vessel projects. The EU Green Deal maritime funding channels capital toward port electrification and retrofit programs through KfW development bank facilities. Hamburg and Bremen concentrate shipyard capacity where battery system engineering talent scarcity has extended project timelines.
China
Automotive lithium-ion cell scale extends into maritime-certified pack assembly through cost-competitive manufacturing bases. The Ministry of Industry and Information Technology oversees dual carbon goals that accelerate coastal cargo electrification pilots. Ningbo and Shenzhen host pack integration facilities where CATL leverages captive cell supply for price positioning.
Japan
Coastal short-sea shipping routes present underpenetrated retrofit opportunities relative to Nordic adoption curves. METI subsidies for battery propulsion systems reduce payback periods for regional cargo operators. Yokohama and Nagasaki maintain shipyard networks where solid-state battery R&D converges with maritime certification pathways.
United States
California port incentive stacking creates exceptional project economics for terminal tug and harbor craft electrification. The EPA Harbor Craft Regulation layers with IRA clean vessel tax credits to compress capital recovery timelines. Los Angeles and Long Beach anchor demand concentration where regulatory compliance timelines synchronize with fleet replacement cycles.
Battery Pack for Marine Hybrid and Full Electric Propulsion Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the marine battery pack segment. Nordic specialists anchor premium-tier positioning through DNV and Lloyd's Register certification density, while Asian cell manufacturers compete on pack-level cost at reduced local service density. The market structures around three archetypes: integrated energy conglomerates with shore-power heritage, pure-play maritime battery specialists, and automotive cell scale players extending into marine assembly. Dominant competitive moves include geographic manufacturing expansion to escape Nordic supply vulnerability and strategic partnerships between shipyards and system integrators to secure installation capacity.
Within the integrated energy tier, Siemens Energy represents the shore-to-ship power heritage archetype through its large-format naval architecture project anchoring. Among maritime pure-plays, Corvus Energy and AYK Energy occupy positions exemplifying Nordic certification density and specialized marine focus. CATL sits within the automotive scale extension archetype, leveraging captive lithium-ion cell supply to compress pack pricing for cost-sensitive fleet operators.
| Leading Market Players |
|---|
| Siemens Energy |
| Toshiba Corporation |
| Corvus Energy |
| AYK Energy |
| Saft Groupe SA |
| CATL |
| Leclanché SA |
| Torqeedo GmbH |
| EnerSys |
| Others |
Supply Flow & Price Mechanics
DNV and Lloyd's Register certification timelines gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified pack assemblers while allowing Nordic specialists to sustain rate premiums through documented safety architectures.
Pricing Analysis
Geographic price spreads between Norwegian and Chinese pack integrators exceed 35 percent for equivalent capacity configurations. Pricing stratifies across DNV-certified premium tiers, Lloyd's Register mid-tiers, and uncertified economy assemblies where automotive cell repurposing dominates. Cost compression in the economy tier is intensifying because CATL leverages captive lithium-ion supply to undercut regional service density. Ferry operators in Northern Europe show lowest price sensitivity due to zero-emission mandate compliance deadlines, while Asian cargo fleets exhibit highest sensitivity to per-kWh capital outlay.
Supply Chain Analysis
China and South Korea anchor cell production through CATL and LG Energy Solution manufacturing scale, while Norway and Germany concentrate pack integration and thermal management system assembly. The supply chain draws from lithium carbonate feedstock anchored in Chile and Australia, nickel laterite from Indonesia, and copper busbar fabrication concentrated in Chinese industrial zones. Single-source vulnerability in maritime-certified BMS semiconductor supply creates chokepoint exposure for European integrators. Distribution runs through shipyard direct procurement for newbuilds and system integrator retrofit channels for hybrid conversions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is cycling through a capital recovery phase as IMO carbon intensity deadlines force vessel replacement ahead of historical scrappage curves.
For Market Incumbents: Secure installation capacity through captive engineering partnerships with German and Dutch shipyards, where certified battery integration specialist backlogs now extend eighteen months. Defend margin position by deepening backward integration into thermal management component production rather than sourcing from automotive-tier suppliers exposed to cell chemistry volatility. Prioritize DNV type approval maintenance for next-generation solid-state architectures before certification queues lengthen further. For New Entrants and Emerging Players: Lloyd's Register fast-track certification for containerized plug-in battery modules offers entry velocity without competing for scarce hull-embedded integration talent. Target Japan's coastal cargo retrofit segment, where METI subsidies remain underpenetrated relative to Nordic adoption curves and local pack assembly capacity is limited. Lead with modular 20-foot ISO container specifications that compress shipyard time and enable mid-life capacity upgrades without drydocking. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across containerized battery system manufacturing as standardization reduces custom engineering content per unit. Five-to-ten-year viability favors pure-play maritime battery specialists with established certification density over automotive scale players lacking local service networks. Monitor DNV and Lloyd's Register approval timeline compression as the signal indicating competitive moat durability for incumbent Nordic integrators.| Strategic Initiative | Industry Significance |
|---|---|
| Containerized Pack Standardization | 20-foot ISO modular formats compress Norwegian ferry yard time and enable mid-life capacity swaps. |
| Backward Integration into Thermal Management | In-house production of liquid cooling loops protects margins from automotive supplier price volatility. |
| DNV Type Approval Fast-Tracking | Accelerated certification pathways for solid-state architectures capture premium positioning before competitors queue. |
| Shipyard Engineering Partnerships | Captive installation capacity agreements with German yards lock in throughput amid eighteen-month specialist backlogs. |
| Japan Coastal Retrofit Channel Development | METI-subsidized short-sea cargo routes offer white-space expansion with limited local pack assembly competition. |
Methodological Framework
Desk research of IMO regulatory filings, EU MRV emissions databases, and shipyard order books preceded structured interviews with ferry fleet operations directors, marine battery system integrators, shipyard project managers, and port authority electrification planners. Secondary validation drew from DNV maritime certification records, Lloyd's Register type approval registries, and national maritime authority subsidy disbursement reports. Bottom-up vessel deployment tallies triangulated against top-down battery capacity installation estimates across the analysis window.
Variance decomposition across chemistry type, vessel class, and regional regulatory cluster shaped the analytical framework for value and volume projections throughout the forecast period. CAGRs were derived from segmented deployment curves weighted by route electrification mandates and shore power infrastructure buildout timelines. Forecast inputs incorporated ferry replacement cycle acceleration under UNESCO fjord mandates and fishing trawler territorial water restriction enforcement intensity across Mediterranean and North Sea jurisdictions.
Decision-makers should treat outputs as directional under assumptions of sustained IMO carbon intensity threshold tightening and EU Green Deal maritime funding continuity; material deviation in regulatory enforcement stringency or subsidy program extension would warrant model refresh. Recalibration cycles align with material shifts in certification timeline duration, cell chemistry cost curves, and coastal zero-emission mandate geographic expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Global Automotive Lead Acid Batteries Market
Batteries
Zinc Carbon Battery Market
Batteries
Lead Acid Battery Market
Batteries
Portable Battery Market
Batteries
Europe Rechargeable Battery Market
Batteries
Heavy-Duty Truck Megapack Battery Systems Market
Batteries
Europe Battery Systems for Electric Vehicles Market
Batteries
East Asia Battery Market
Batteries
Portable Battery Pack Market
Batteries
Modular Battery Pack Market
Batteries
Global Industrial Battery Market
Batteries
North America Lead-Acid Battery Separator for SLI Applications Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Lithium Carbon Monofluoride Battery Market
Batteries
Middle East and Africa Battery Market
Batteries
India Lead-Acid Battery Separator for SLI Applications Market