
 Solar Powered Agricultural Dryer Market | 2026-2036
Solar Powered Agricultural Dryer Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Powered Agricultural Dryer Market Analytics
Market Context
Modular kit configurations is shifting buyer choice from centralized systems toward expandable tray-and-chamber units that smallholders assemble incrementally. SolarDryer Technologies, Inc. leverages this trend through scalable designs that accommodate harvest volume swings. GrainPro Inc anchors its position with hermetic storage integration that extends the usable window for dried commodities. Rudra Solar Energy dominates India's distributed manufacturing base with localized fabrication that reduces logistics costs for rural buyers.
Technical Definition and Segment Structure
A solar powered agricultural dryer harnesses thermal energy from photovoltaic or direct-solar collection to reduce moisture content in harvested crops, typically operating between 40°C and 70°C with airflow rates calibrated to commodity-specific safe drying curves. Its primary commercial purpose is to arrest fungal proliferation and aflatoxin generation while preserving germination viability and nutritional density for grains, fruits, and vegetables. Batch dryers occupy the largest installed base due to lower capital barriers and simpler maintenance protocols among small-scale operators. Continuous dryers represent the fastest-expanding configuration as commercial cooperatives seek throughput parity with conventional fuel-fired alternatives. Remote-controlled operation modes command premium positioning by enabling moisture monitoring and automated vent adjustment that reduces labor tethering and over-drying losses.
Regulatory Environment and Outlook
Kenya's Energy Regulatory Authority and India's Ministry of New and Renewable Energy shape product standards through solar thermal performance certification and subsidy eligibility criteria that filter market access. The FAO-WHO Codex Alimentarius framework on mycotoxin limits indirectly propels dryer demand by tightening acceptable moisture thresholds for traded commodities. Stakeholders must monitor how evolving carbon credit methodologies for avoided post-harvest loss could unlock new revenue streams for dryer operators in voluntary offset markets.
Market Dynamics
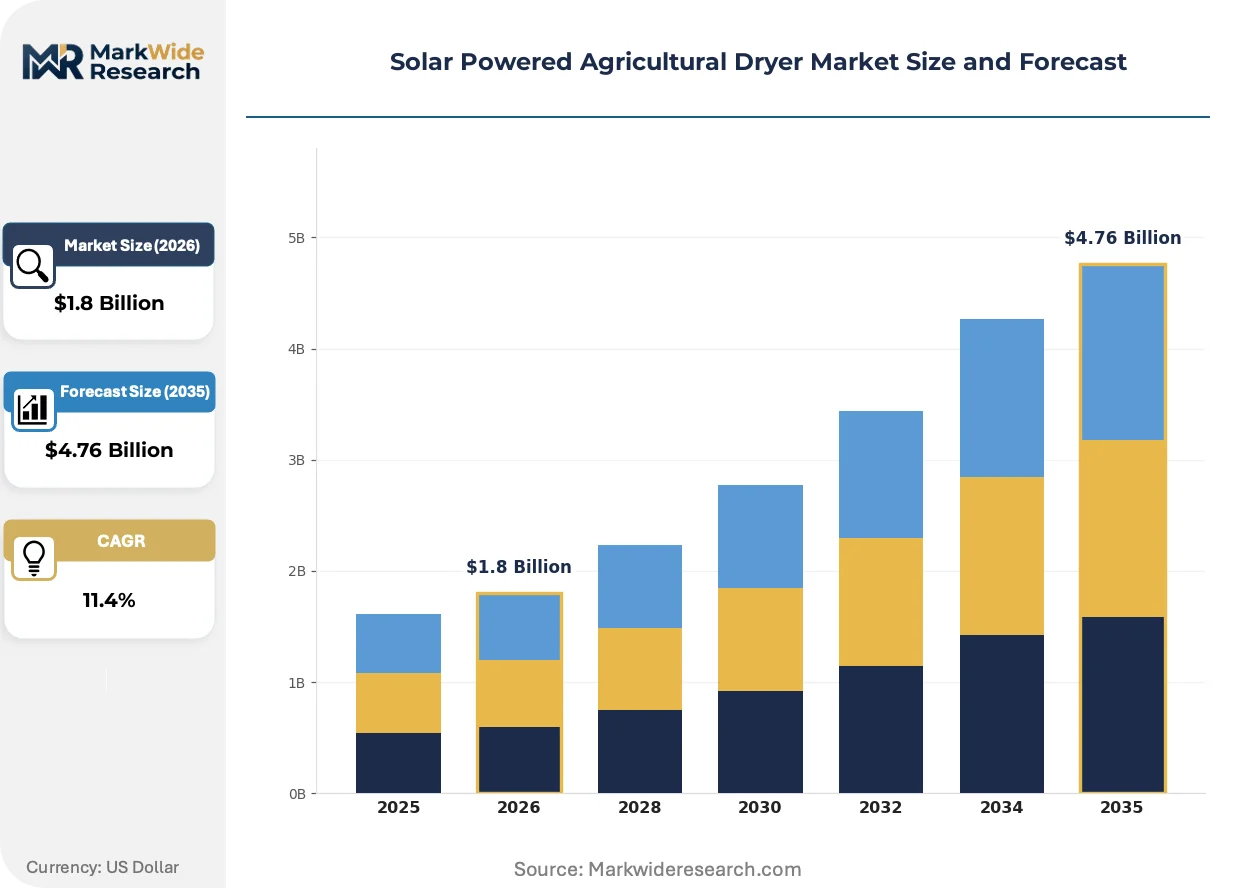
Modular photovoltaic-thermal hybrid designs are compressing capital barriers for smallholder cooperatives, redirecting procurement from centralized fuel-fired kilns toward distributed solar drying infrastructure that scales with harvest cycles.
Growth Catalysts
- Kenya's Energy Regulatory Authority solar thermal certification:Standardized performance benchmarks reduce buyer uncertainty and accelerate commercial deployment across East African grain value chains.
- Cassava and maize post-harvest loss reduction mandates:National food security programs in Nigeria and Tanzania prioritize decentralized drying infrastructure to meet export mycotoxin thresholds.
- Photovoltaic cost compression:India's PLI scheme for domestic solar manufacturing lowers panel acquisition costs for rural dryer assemblers.
Market Restraints
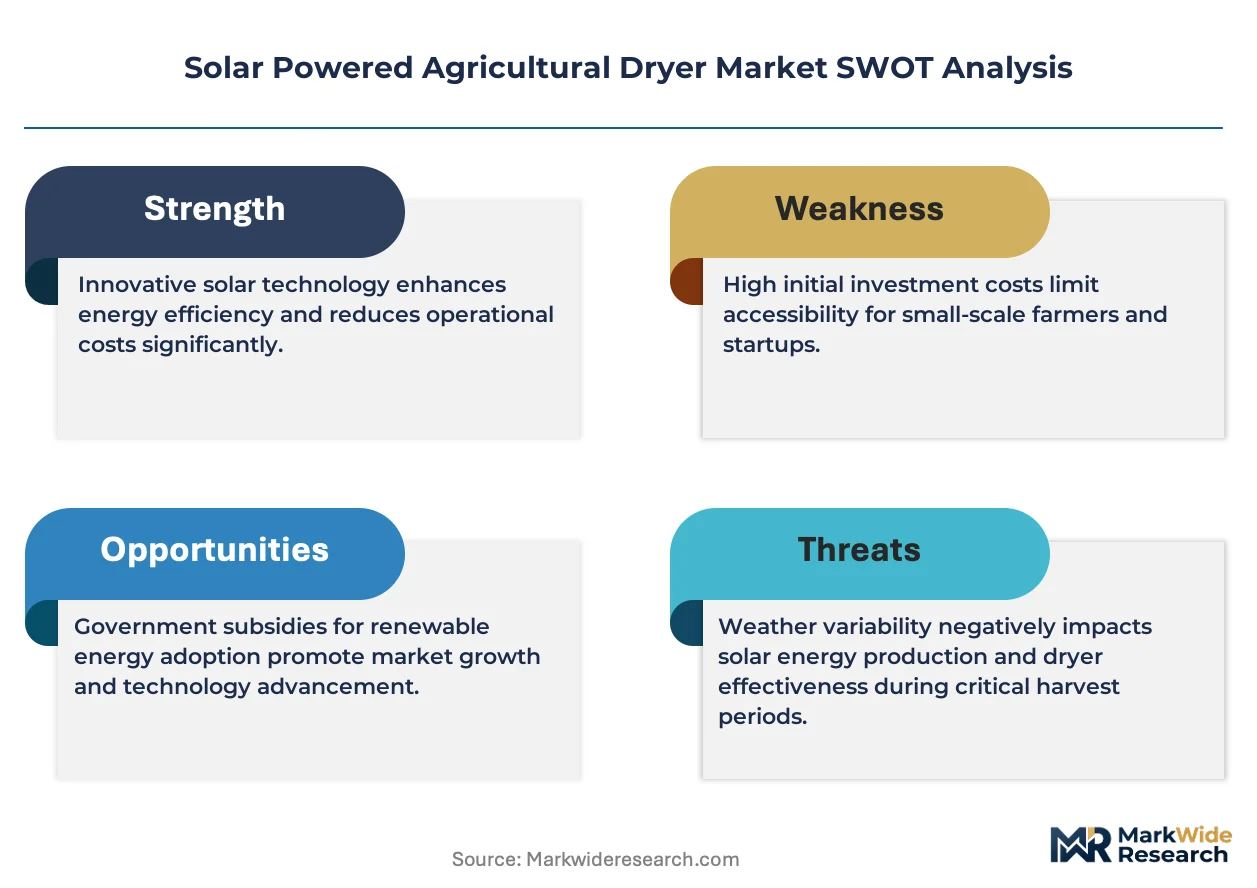
- Seasonal irradiance volatility:Intermittent solar resource availability in equatorial high-rainfall zones forces backup thermal integration, elevating system complexity.
- Specialized technician scarcity:Rural service networks lack trained personnel for photovoltaic array maintenance and humidity sensor calibration.
- Conventional LPG-fired dryer substitution:Established fossil fuel infrastructure in commercial milling clusters delays solar transition timelines.
Strategic Opportunities
- Carbon credit methodology development:Emerging voluntary offset protocols for avoided post-harvest loss create revenue stacking potential for cooperative dryer operators.
- Hermetic storage-drying integration:Converging moisture management and sealed storage technologies extend commodity shelf life and capture premium grades.
- Remote monitoring service contracts:Cellular-enabled moisture telemetry enables predictive maintenance subscriptions that reduce smallholder labor tethering.
Industry Challenges
- FAO-WHO Codex Alimentarius compliance documentation:Mycotoxin testing protocols and traceability systems demand capital investment beyond core drying hardware.
- Multi-vendor system integration:Assembled tray-and-chamber configurations from disparate suppliers create interoperability failures in airflow control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Powered Agricultural Dryer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Dryer, Continuous Dryer, Hybrid Dryer, Portable Dryer End Use Industry: Agriculture, Horticulture, Food Processing, Food Storage Operation Mode: Manual, Automatic, Semi-Automatic, Remote-Controlled Capacity: Small Scale, Medium Scale, Large Scale, Industrial Scale |
| Companies Covered | SolarFlex, SolarDryer Technologies, Inc., GrainPro Inc, SunDry Innovations, Alvan Blanch Development Company Limited, Rudra Solar Energy, JUA Technologies, Arka Innovations, S4S Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Powered Agricultural Dryer Market Evolving Landscape
Active innovation centers on three vectors: photovoltaic-thermal hybrid architectures, regulatory alignment with food safety frameworks, and procurement model evolution toward service-based access. These shifts collectively reduce capital intensity while embedding quality assurance into drying operations.
Photovoltaic-thermal (PVT) collector technology captures electrical and thermal energy simultaneously, boosting system efficiency for batch configurations. Smallholder cooperatives in Tanzania and Nigeria are piloting these hybrid units for dual-purpose crop drying and battery charging. This convergence with mobile payment platforms enables pay-per-use dryer access that sidesteps upfront capital requirements.
India's Ministry of New and Renewable Energy revised solar thermal performance standards to include agricultural dryer-specific testing protocols, filtering subsidy eligibility toward certified equipment. The regulation compresses market access timelines for domestic manufacturers while elevating technical documentation burdens for importers. Rural distribution networks are responding by consolidating around BIS-certified fabricators with localized assembly capacity.
Cooperative buyers are fragmenting procurement across multiple component vendors rather than purchasing turnkey systems, assembling tray-and-chamber units incrementally based on harvest forecasts. Equipment distributors in Kenya are unbundling after-sales service from hardware sales, offering remote moisture monitoring subscriptions. This behavioral shift is most pronounced in cassava value chains where harvest volume unpredictability makes fixed-capacity investments economically precarious.
Solar Powered Agricultural Dryer Market Segmentation
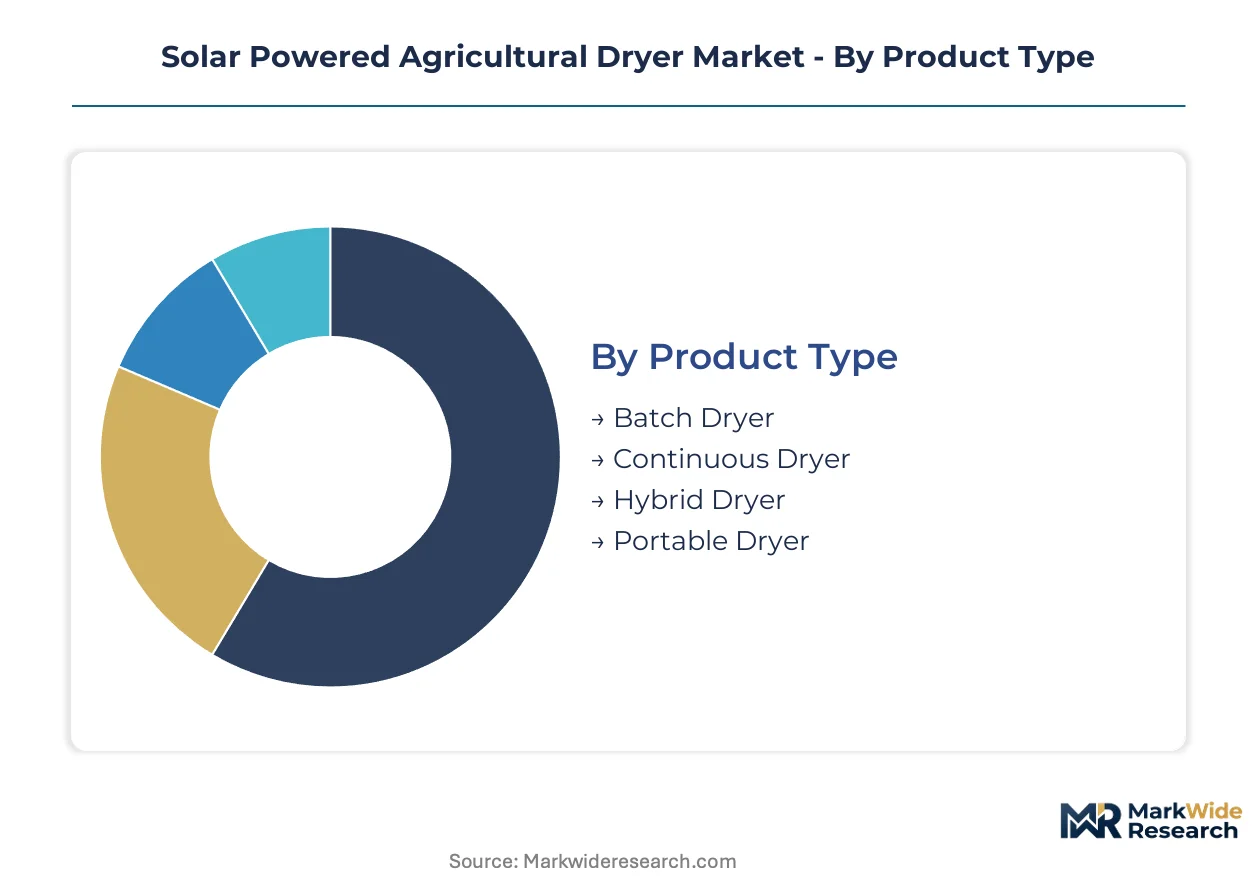
Segmentation in the solar powered agricultural dryer market reveals how capital constraints, labor availability, and harvest scale dictate procurement patterns across smallholder cooperatives and commercial operators. Buyers prioritize modular configurations that align drying capacity with seasonal volume fluctuations rather than fixed infrastructure investments.
Product Type:
Capital barriers and harvest predictability drive product selection, with buyers balancing throughput requirements against maintenance complexity and technician availability in rural service networks.
- Batch Dryer:Units process discrete loads in insulated chambers with photovoltaic thermal collectors, typically achieving 40°C to 70°C operating temperatures. Smallholder cooperatives in Kenya and Tanzania favor these configurations for cassava and maize value chains where harvest timing is irregular and capital reserves are limited. Volume sits with Batch Dryer; growth tilts toward Hybrid Dryer.
- Continuous Dryer:Conveyor-based systems enable uninterrupted processing with higher throughput parity against conventional fuel-fired alternatives. Commercial cooperatives in Nigeria deploy these units where harvest consolidation and export mycotoxin compliance demand consistent drying curves.
- Hybrid Dryer:Photovoltaic-thermal architectures capture electrical and thermal energy simultaneously, boosting efficiency for operators seeking dual-purpose crop drying and battery charging capacity.
- Portable Dryer:Collapsible tray-and-chamber designs enable seasonal relocation across multiple farm clusters, reducing per-unit capital exposure for cooperatives with dispersed membership.
Procurement concentrates on batch configurations; continuous systems are climbing the fastest as commercial cooperatives scale operations.
End Use Industry:
Moisture management requirements and regulatory exposure vary sharply across value chains, with mycotoxin thresholds and export certification demands filtering equipment selection.
- Agriculture:Grain and tuber operations dominate installed base, with Kenya's Energy Regulatory Authority certification requirements shaping equipment standards for maize and cassava processors seeking market access.
- Horticulture:Fruit and vegetable drying demands precise humidity control to preserve nutritional density and visual grade for premium export markets.
- Food Processing:Midstream operators integrate drying with value-added processing, requiring throughput consistency that favors continuous configurations with automated moisture monitoring.
- Food Storage:Hermetic storage integration extends shelf life for dried commodities, with GrainPro Inc anchoring positioning through converged moisture management and sealed storage technologies.
Agriculture commands current volume; Food Processing is expanding most quickly as commercial cooperatives vertically integrate into value-added operations.
Operation Mode:
Labor tethering and over-drying risk determine automation investment, with cellular connectivity enabling new service-based revenue models for equipment distributors.
- Manual:Vent adjustment and load rotation require continuous operator presence, limiting throughput but eliminating sensor calibration dependencies in technician-scarce rural networks.
- Automatic:Programmable controllers maintain temperature and airflow setpoints without intervention, reducing labor costs for cooperatives with predictable harvest schedules.
- Semi-Automatic:Hybrid interfaces allow operator override of automated sequences, balancing labor flexibility with consistency for smallholders managing multiple crop types.
- Remote-Controlled:Cellular-enabled moisture telemetry enables predictive maintenance subscriptions and automated vent adjustment, commanding premium positioning by reducing over-drying losses and labor tethering for dispersed operations.
Manual systems retain volume leadership; Remote-Controlled modes are gaining share fastest as pay-per-use platforms sidestep upfront capital barriers.
Capacity:
Harvest consolidation patterns and cooperative membership scale dictate capacity selection, with modular expansion preferred over fixed industrial investments.
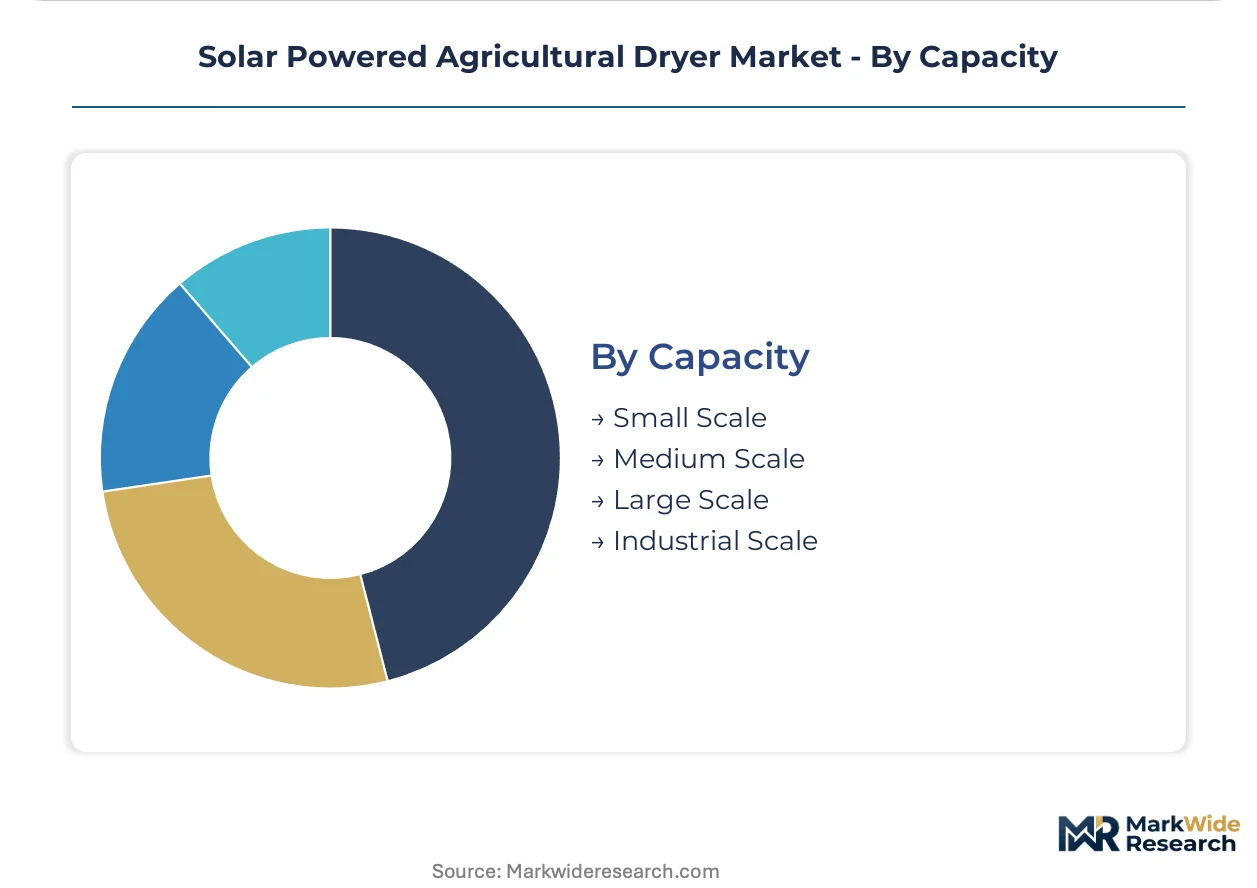
- Small Scale:Tray-and-chamber units serve individual smallholders or micro-cooperatives with sub-tonne daily throughput, assembled incrementally from multiple component vendors.
- Medium Scale:Configurable chamber arrays accommodate harvest volume swings for village-level cooperatives in Tanzania and Nigeria, where cassava harvest unpredictability makes fixed-capacity investments economically precarious.
- Large Scale:Dedicated drying facilities serve district-level cooperatives with centralized collection and quality grading infrastructure.
- Industrial Scale:Continuous throughput systems rival conventional fuel-fired kilns for commercial milling clusters, though LPG infrastructure delays solar transition timelines in established processing hubs.
Small Scale dominates current deployment; Medium Scale shows the steepest expansion trajectory as decentralized post-harvest infrastructure gains priority across sub-Saharan grain value chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in India and China where solar panel manufacturing compresses hardware costs, while consumption tilts toward sub-Saharan Africa where decentralized drying infrastructure addresses post-harvest loss. Grid instability and mycotoxin compliance drive procurement patterns across equatorial grain belts.
Kenya
Cassava and maize cooperatives anchor demand in the Rift Valley and Western provinces where harvest timing is irregular. The Energy Regulatory Authority solar thermal certification filters subsidy eligibility toward standardized equipment. Nairobi-based distributors unbundle after-sales service from hardware, offering remote moisture monitoring subscriptions to village-level processors.
India
The PLI scheme for domestic solar manufacturing lowers photovoltaic acquisition costs for rural dryer assemblers in Gujarat and Tamil Nadu. BIS-certified fabricators consolidate around localized assembly capacity that reduces logistics costs for agricultural belts. Maharashtra and Karnataka see rising deployment of tray-and-chamber units among horticulture cooperatives.
Nigeria
National food security programs prioritize decentralized drying infrastructure to meet export mycotoxin thresholds for cassava value chains. The country's agricultural development agencies channel financing toward medium-scale continuous configurations in the Middle Belt. Kano and Kaduna host emerging clusters where commercial cooperatives seek throughput parity with conventional fuel-fired alternatives.
Tanzania
Photovoltaic-thermal hybrid pilots among smallholder cooperatives in the Lake Zone enable dual-purpose crop drying and battery charging. Harvest volume unpredictability makes fixed-capacity investments economically precarious, favoring modular expansion. Dodoma and Mbeya see concentration of pay-per-use platforms that sidestep upfront capital barriers through mobile payment integration.
Solar Powered Agricultural Dryer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the solar powered agricultural dryer market. The vendor base spans solar equipment manufacturers diversifying into agricultural applications and dedicated dryer fabricators with localized assembly networks. Three archetypes dominate: integrated solar-thermal technology developers, modular kit assemblers serving smallholder cooperatives, and hermetic storage convergers extending moisture management into sealed preservation. Capacity expansion and geographic licensing partnerships represent the primary competitive moves as players seek fabrication proximity to high-growth equatorial markets.
Among India-based fabricators, Rudra Solar Energy occupies a position within the distributed manufacturing archetype, while SolarDryer Technologies, Inc. exemplifies scalable design specialization for incremental assembly. GrainPro Inc anchors the hermetic storage convergence tier, representing integrated moisture management and sealed storage positioning.
| Leading Market Players |
|---|
| SolarFlex |
| SolarDryer Technologies, Inc. |
| GrainPro Inc |
| SunDry Innovations |
| Alvan Blanch Development Company Limited |
| Rudra Solar Energy |
| JUA Technologies |
| Arka Innovations |
| S4S Technologies |
| Others |
Value Network & Pricing Analysis
FAO-WHO Codex Alimentarius mycotoxin compliance thresholds gate qualified supply and premium-tier pricing access for solar dryer manufacturers serving export-oriented cooperatives in Kenya, Nigeria, and Tanzania. Equipment certified under Kenya's Energy Regulatory Authority solar thermal standards commands price premiums, while uncertified kit assemblers compete on acquisition cost for domestic-market buyers.
Pricing Analysis
Price erosion across economy-tier batch configurations traces to India's PLI scheme compressing photovoltaic panel costs for rural assemblers. Three-tier pricing structure across premium, standard, and economy levels separates remote-controlled continuous systems with cellular telemetry from semi-automatic chamber units and manual tray configurations. Cost-down pressure on mid-scale hybrid dryers accelerates because smallholder cooperatives in Tanzania and Nigeria fragment procurement across multiple component vendors. Village-level processors exhibit highest price sensitivity, while commercial milling clusters in Nigeria's Middle Belt prioritize throughput consistency over acquisition cost.
Supply Chain Analysis
Photovoltaic module supply rests on Indian and Chinese manufacturing clusters where domestic content requirements and scale economies concentrate production. Aluminum framing, humidity sensors, and thermal insulation materials draw from localized fabrication networks in Gujarat, Tamil Nadu, and Guangdong. Single-source vulnerability sits with imported sensor calibration equipment for remote-controlled operation modes. Distribution runs through Nairobi-based distributors unbundling hardware from after-sales service subscriptions, with emerging direct-to-cooperative channels in Tanzania's Lake Zone bypassing traditional equipment dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photovoltaic-thermal hybrid architectures are displacing conventional fuel-fired kilns across sub-Saharan grain value chains, compressing transition timelines for established processing infrastructure.
For Market Incumbents: Anchor certification investment under Kenya's Energy Regulatory Authority and India's BIS standards to defend subsidy eligibility against emerging kit assemblers. Deepen backward integration into localized aluminum fabrication and thermal insulation production to offset logistics cost disadvantages against Rudra Solar Energy's distributed manufacturing base. Prioritize remote monitoring service contracts as a recurring revenue buffer against hardware margin compression. For New Entrants and Emerging Players: Mobile payment-integrated pay-per-use platforms offer the most penetrable route into Tanzania's cassava cooperatives where harvest volume unpredictability deters capital purchase. Target medium-scale modular configurations in Nigeria's Middle Belt where national food security programs channel financing toward decentralized drying infrastructure. Pursue pilot partnerships with agricultural development agencies to secure reference installations before scaling commercial deployment. For Investors and Strategic Acquirers: Carbon credit methodology registration for avoided post-harvest loss is the leading indicator that cooperative dryer operators will unlock revenue stacking potential in voluntary offset markets. Long-term viability favors fabricators with captive supply of BIS-certified components and established cellular telemetry integration. Watch for Kenya's Energy Regulatory Authority expanding certification requirements to hybrid configurations as the inflection signal for consolidation toward standardized equipment providers.| Strategic Initiative | Industry Significance |
|---|---|
| Photovoltaic-Thermal Hybrid Product Launch | Dual-purpose crop drying and battery charging captures Tanzania cooperative pilots. |
| Remote Monitoring Service Subscription | Cellular-enabled moisture telemetry reduces labor tethering for dispersed operations. |
| BIS Certification Investment | Indian Ministry of New and Renewable Energy subsidy eligibility filters market access. |
| Hermetic Storage Technology Integration | GrainPro Inc anchors positioning through converged moisture management and sealed preservation. |
| Localized Assembly Capacity Expansion | Gujarat and Tamil Nadu fabrication reduces logistics costs for rural agricultural belts. |
Research Methodology
Trade databases, solar equipment customs records, and agricultural ministry subsidy disbursement reports formed the secondary backbone, cross-referenced against primary interviews with dryer fabricators, cooperative procurement officers, and agricultural development agency program managers. Bottom-up and top-down triangulation validated installed base estimates across Kenya, Nigeria, Tanzania, and India.
Bottom-up modeling aggregated segment-level deployment trajectories across batch, continuous, hybrid, and portable configurations, while top-down analysis calibrated aggregate market evolution against photovoltaic cost compression curves and regulatory subsidy timelines. Segmentation dimensions included product type, operation mode, capacity tier, and end-use value chain. CAGRs derived from fitted growth curves incorporating India's PLI scheme impact, Kenya's Energy Regulatory Authority certification expansion, and FAO-WHO Codex Alimentarius compliance adoption rates across the projection horizon.
The model holds under continued photovoltaic cost compression and stable subsidy frameworks; deviation in carbon credit methodology adoption or tariff escalation on Chinese aluminum inputs would shift cooperative procurement patterns. Forecasts reflect documented assumptions about irradiance stability, technician training network expansion, and mobile payment platform penetration. A small set of named triggers—carbon credit registration velocity, BIS certification timeline compression, and Nigeria's export mycotoxin enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Pulp Wash Equipment Market
Agricultural Processing Equipment
Grain Handling Equipment Market
Agricultural Processing Equipment
Destemmer Machine Market
Agricultural Processing Equipment
North America Feed Pelletizing Agent Market
Agricultural Processing Equipment
Asia-Pacific Agricultural Shredder Machine Market
Agricultural Processing Equipment
Global Grain and Seed Cleaning Equipment Market
Agricultural Processing Equipment
Rice Milling Machinery Market
Agricultural Processing Equipment
China Agricultural Shredder Machine Market
Agricultural Processing Equipment
Meat Processing Equipment Market
Agricultural Processing Equipment
Industrial Shelling Machines Market
Agricultural Processing Equipment
Meat Dicing Machine Market
Agricultural Processing Equipment
Asia-Pacific Meat Processing Equipment Market
Agricultural Processing Equipment
Sugarcane Harvesters Market
Agricultural Processing Equipment
Defeathering Machine Market
Agricultural Processing Equipment
Color Sorter Market
Agricultural Processing Equipment
Harvesters Market