
 Asia-Pacific Meat Processing Equipment Market | 2026-2036
Asia-Pacific Meat Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Meat Processing Equipment Market Insights
Stainless steel with enhanced nickel content is recalibrating equipment longevity standards across the Asia-Pacific Meat Processing Equipment landscape. Marel leverages its integrated software-hardware platforms to dominate precision cutting workflows in Australia and New Zealand. GEA Group anchors its position through advanced chilling system engineering that serves large-scale beef processors in Japan. JBT Corporation differentiates via vacuum packaging technology leadership that extends shelf-life compliance for Southeast Asian exporters.
Asia-Pacific meat processing equipment encompasses machinery designed to transform raw animal protein into standardized food products through mechanical cutting, thermal treatment, temperature control, and protective atmosphere packaging, typically constructed from food-grade stainless steel with surfaces meeting sub-micron roughness specifications to prevent bacterial adhesion. Cutting machines occupy the largest installed base due to universal deployment across beef, poultry, and pork operations, though automation technology represents the fastest-expanding segment as labor costs climb in Thailand and Indonesia. Vacuum packaging commands premium margins because export certification to Japan and South Korea demands precise oxygen residual thresholds that only integrated sealing systems reliably achieve.
SAMR's food safety enforcement in China and Japan's METI energy-efficiency standards for industrial refrigeration are accelerating equipment replacement cycles among mid-tier processors. Australia's HACCP-aligned export protocols and New Zealand's MPI dairy-meat cross-compliance rules further shape product specification requirements for regional suppliers. Stakeholders must monitor how Indonesia's forthcoming national halal certification mandates will reshape equipment sanitization protocols and line segregation architectures across multi-species facilities.
Market Dynamics
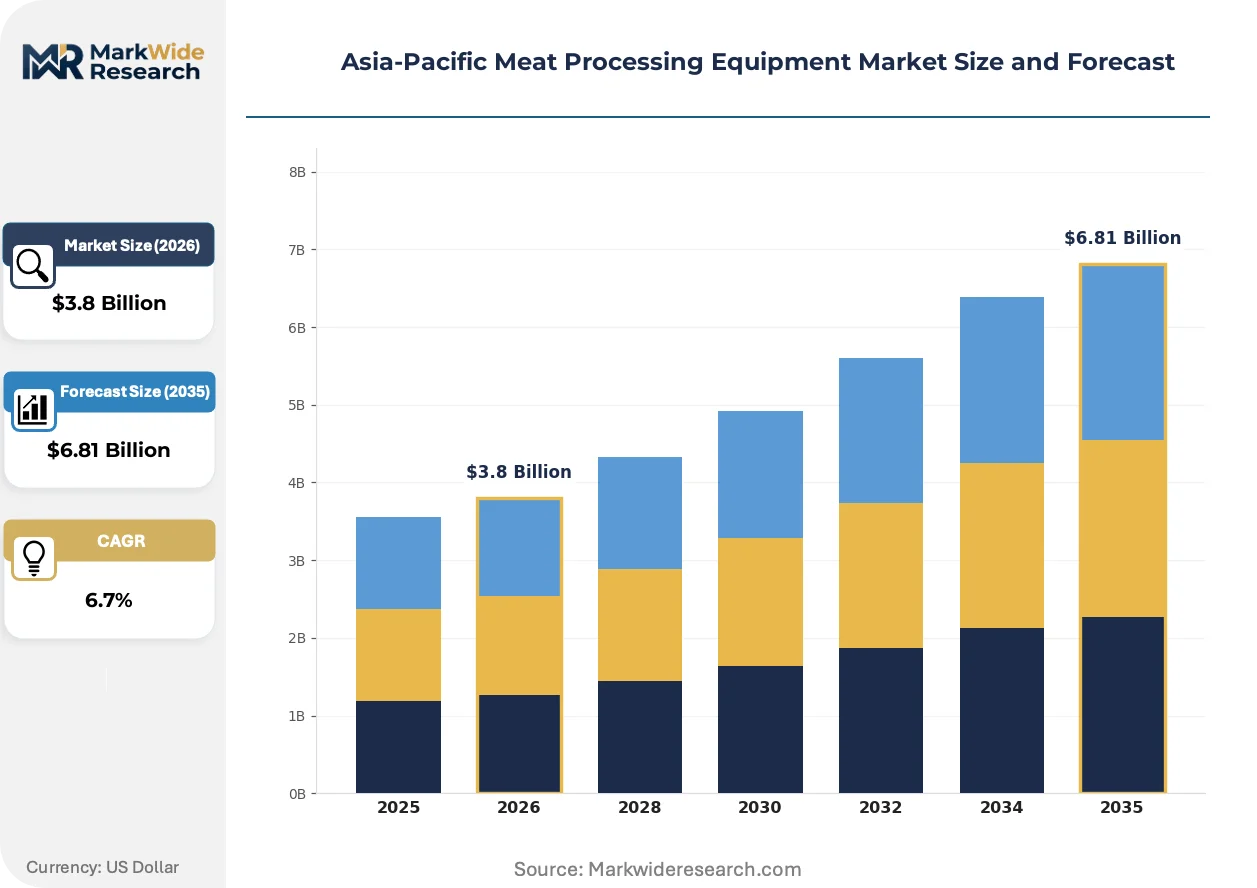
China's SAMR food safety enforcement is compressing replacement cycles for legacy equipment across mid-tier processing facilities, forcing capital redeployment toward automated chilling and vacuum packaging systems that satisfy export-grade compliance thresholds.
Growth Catalysts
- Automated cutting workflows:Labor cost escalation in Thailand and Indonesia is accelerating deployment of precision slicing and portioning systems that reduce manual handling while improving yield consistency.
- SAMR food safety protocols:China's updated enforcement regime mandates equipment surface roughness standards and bacterial adhesion prevention, compelling facility-wide upgrades.
- Vietnam's export poultry sector:Processors are integrating chilling and vacuum packaging lines to access premium Japanese and South Korean distribution channels with residual oxygen compliance.
Market Restraints
- Nickel alloy cost volatility:Stainless steel with enhanced nickel content faces input price swings that compress equipment margins and extend procurement timelines for regional fabricators.
- Technical service fragmentation:After-sales support networks remain sparse in secondary Indonesian and Philippine markets, limiting uptime guarantees for complex multi-station lines.
- Energy-efficiency retrofit friction:Japan's METI standards for industrial refrigeration create compliance gaps for aging facilities unable to absorb chiller replacement capex.
Strategic Opportunities
- Halal certification mandates:Indonesia's forthcoming national halal requirements will drive demand for line segregation architectures and specialized sanitization protocols in multi-species plants.
- Software-hardware convergence:Integrated platforms combining cutting automation with real-time yield analytics offer white space for vendors serving Australian and New Zealand beef processors.
- Cross-border service unbundling:Remote diagnostics and predictive maintenance subscriptions represent untapped revenue streams for equipment suppliers penetrating Vietnam's export corridor.
Industry Challenges
- Automation engineering talent scarcity:Facilities in Indonesia and the Philippines struggle to recruit technicians capable of programming and maintaining integrated cutting-chilling-packaging lines.
- Legacy system integration complexity:Mid-tier Chinese processors face prolonged downtime when retrofitting SAMR-compliant surfaces onto existing grinding and mixing equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Meat Processing Equipment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cutting Machines, Grinders, Mixers, Slicing Equipment End User: Food Manufacturers, Restaurants, Retailers, Caterers Technology: Automation, Vacuum Packaging, Chilling Systems, Cooking Equipment Application: Beef Processing, Poultry Processing, Seafood Processing, Processed Meat |
| Companies Covered | Marel, GEA Group, JBT Corporation, Illinois Tool Works, Middleby Corporation, Heat and Control, BAADER, Handtmann, Mainca, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Meat Processing Equipment Market Trends and Innovations
Equipment intelligence is converging with food-grade materials science to reshape how processors balance throughput, compliance, and energy intensity across heterogeneous protein operations.
Hyperspectral imaging for real-time fat-to-lean ratio analysis is converging with automated blade adjustment systems in Australian and New Zealand beef facilities, enabling portioning accuracy that satisfies retail chain specifications while reducing giveaway. Large-scale processors are adopting this technology at pilot scale now, with full-line deployment expected to compress yield variance premiums within two procurement cycles.
Japan's METI energy-efficiency standards for industrial refrigeration are forcing chiller replacement decisions ahead of scheduled end-of-life, particularly affecting beef and pork operations with legacy ammonia systems. Facilities are responding by specifying variable-speed compressors and heat recovery integration that satisfy both METI thresholds and Australia's HACCP-aligned export protocols for cross-certified product streams.
Service contracting preferences among Southeast Asian exporters are migrating from capital purchase with warranty toward performance-guaranteed uptime agreements that bundle maintenance, spare parts, and remote monitoring. This shift is most visible in Vietnam's poultry export corridor, where processors prioritize equipment vendors offering guaranteed throughput rates over lowest initial acquisition cost, reflecting pressure from Japanese and South Korean buyers for supply continuity assurance.
Asia-Pacific Meat Processing Equipment Market Segmentation
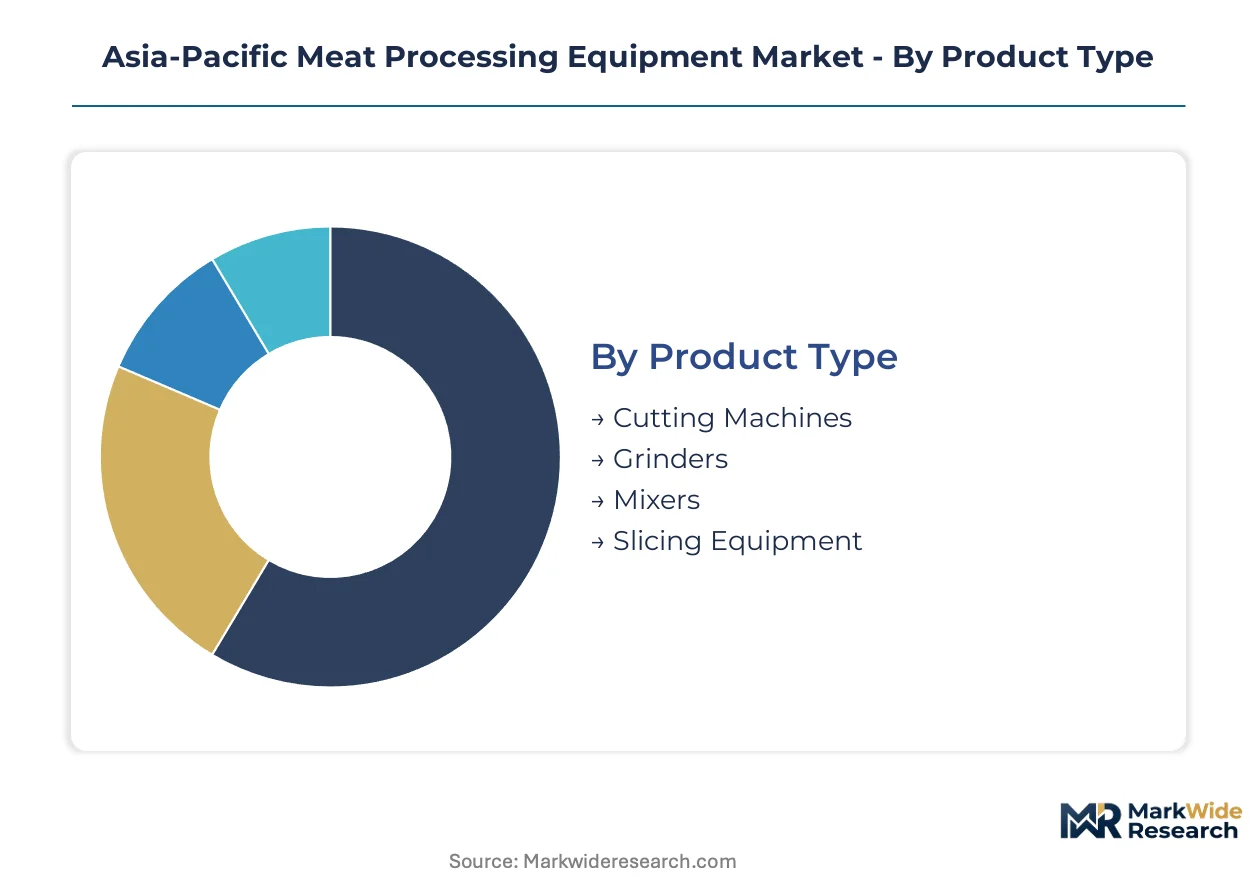
Equipment specification diverges sharply between volume-driven commodity operations and precision-oriented export certification in Asia-Pacific protein processing. Segmentation reveals how capital allocation priorities shift across regulatory environments and customer value chains.
Product Type:
Volume dominance sits with universal cutting infrastructure, while premium margins concentrate in integrated automation platforms that compress labor exposure.
- Cutting Machines:Universal deployment across beef, poultry, and pork operations with surfaces engineered to sub-micron roughness specifications for bacterial adhesion prevention. China's SAMR enforcement is compressing replacement cycles for legacy grinding and mixing equipment, forcing facility-wide upgrades toward export-grade compliance thresholds.
- Slicing Equipment:Precision portioning systems with real-time blade adjustment capabilities serve Australian and New Zealand beef processors facing retail chain yield specifications. Hyperspectral imaging integration is expanding most quickly in these facilities to reduce giveaway and satisfy premium distribution channel requirements.
- Grinders:Mechanical reduction systems for particle size standardization in processed meat applications, with demand concentrating in Thailand's expanding sausage and patty manufacturing base.
- Mixers:Batch and continuous blending equipment for emulsion stability and protein extraction, critical for Vietnam's export-oriented poultry further-processing lines.
Today's leader: Cutting Machines. Tomorrow's challenger: Slicing Equipment.
End User:
Capital deployment intensity correlates with export certification burden and supply chain integration depth.
- Food Manufacturers:Large-scale integrated processors with multi-station lines spanning cutting, chilling, and vacuum packaging for cross-border distribution. Indonesia's forthcoming national halal certification mandates are reshaping equipment sanitization protocols and line segregation architectures across their multi-species facilities.
- Retailers:Central kitchen and private-label processing operations requiring portion consistency and extended shelf-life compliance for Japanese and South Korean distribution channels. These buyers prioritize guaranteed throughput rates over lowest initial acquisition cost, reflecting pressure from premium market buyers for supply continuity assurance.
- Restaurants:Mid-scale preparation equipment for portion control and menu standardization, with procurement concentrated in urban clusters across Thailand and Indonesia.
- Caterers:Batch-scale thermal treatment and holding equipment for institutional feeding operations, serving government and corporate contract segments with lower automation penetration.
Food Manufacturers command the steepest expansion trajectory. Retailers represent the margin capture opportunity.
Technology:
Automation platforms absorb capital priority as labor costs climb, while energy efficiency compliance accelerates refrigeration replacement ahead of scheduled end-of-life.
- Automation:Integrated software-hardware platforms combining precision cutting with real-time yield analytics, deployed most intensively where technician scarcity constrains manual operation in Indonesia and the Philippines. Labor cost escalation in Thailand and Indonesia is accelerating deployment that reduces manual handling while improving yield consistency.
- Vacuum Packaging:Integrated sealing systems achieving precise oxygen residual thresholds for export certification to Japan and South Korea. Vietnam's export poultry sector is integrating these lines to access premium distribution channels with residual oxygen compliance requirements.
- Chilling Systems:Temperature control infrastructure with variable-speed compressors and heat recovery integration satisfying Japan's METI energy-efficiency standards and Australia's HACCP-aligned export protocols.
- Cooking Equipment:Thermal treatment systems for pathogen reduction and product stabilization, with specification divergence between domestic market compliance and export-grade validation requirements.
Automation platforms attract the majority of new capital. Vacuum Packaging delivers the premium margin expansion.
Application:
Species-specific processing requirements drive equipment specification divergence across halal certification, thermal treatment protocols, and packaging integration.
- Poultry Processing:High-throughput chilling and vacuum packaging integration serving Vietnam's export corridor to Japanese and South Korean buyers. Processors in this segment seek equipment vendors offering guaranteed throughput rates and remote diagnostics capabilities.
- Beef Processing:Precision cutting and portioning systems with hyperspectral imaging for real-time fat-to-lean ratio analysis, concentrated in Australian and New Zealand facilities serving retail chain specifications.
- Processed Meat:Emulsion stability equipment for sausage, patty, and further-processed product manufacturing, with demand expanding in Thailand's domestic market and export-oriented operations.
- Seafood Processing:Specialized chilling and protective atmosphere packaging for aquatic protein shelf-life extension, with lower automation penetration compared to terrestrial protein operations.
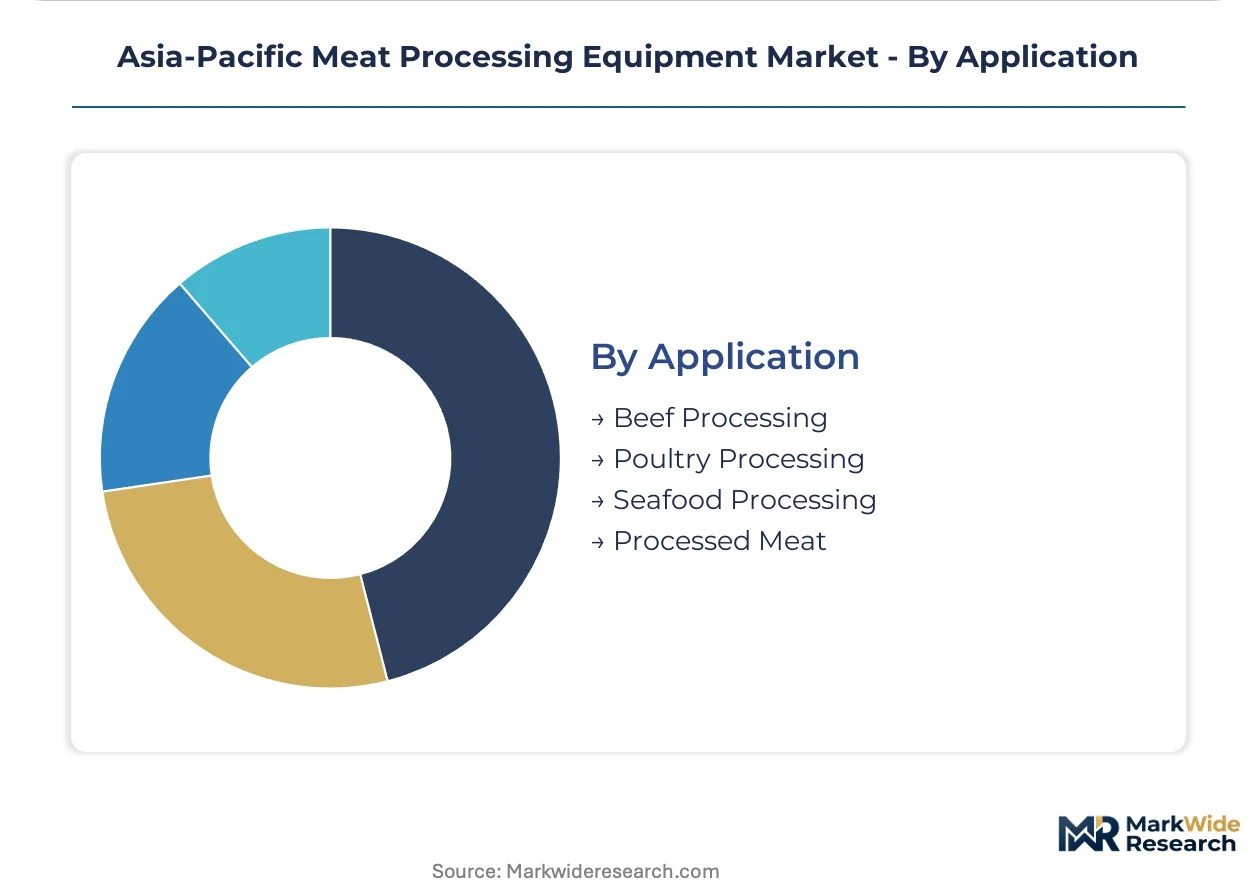
Poultry Processing leads capital absorption. Beef Processing commands the technology premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pearl River Delta industrial corridor concentrates China's most intensive meat processing equipment procurement activity, driven by export-oriented protein facilities upgrading chilling and vacuum packaging infrastructure to satisfy Japanese and South Korean buyer specifications.
China
SAMR's updated food safety enforcement mandates sub-micron surface roughness standards for bacterial adhesion prevention, compelling mid-tier processors across Shandong and Sichuan provinces to replace legacy grinding and mixing equipment ahead of scheduled end-of-life cycles.
Vietnam
Export poultry processors in the Mekong Delta are integrating automated chilling lines with vacuum packaging systems to access premium Japanese distribution channels requiring precise residual oxygen thresholds. Ho Chi Minh City anchors this equipment procurement corridor, with facilities prioritizing vendors offering guaranteed throughput rates.
Japan
METI energy-efficiency standards for industrial refrigeration are accelerating chiller replacement decisions among large-scale beef processors in Hokkaido and Kyushu, particularly affecting facilities with aging ammonia systems unable to absorb variable-speed compressor retrofit costs.
Australia
HACCP-aligned export protocols are shaping equipment specifications for beef processors in Queensland and New South Wales, where hyperspectral imaging integration for real-time fat-to-lean ratio analysis is expanding to satisfy retail chain yield consistency requirements.
Indonesia
Thailand and Indonesia's labor cost escalation is accelerating automated cutting deployment, while Jakarta processors prepare for forthcoming national halal certification mandates that will reshape line segregation architectures and sanitization protocols across multi-species facilities.
Asia-Pacific Meat Processing Equipment Market Competitive Landscape
Technology licensing dominates the current landscape as regional fabricators seek software-hardware convergence capabilities from established European and North American platforms. The market structure consolidates around three tiers: integrated multinational platforms with full-line automation capabilities, mid-scale regional specialists serving single-species processors, and local fabricators competing on procurement timelines and customization flexibility. Strategic archetypes include precision cutting innovators, chilling system engineers, and vacuum packaging integration specialists. M&A activity and capacity expansion into Vietnam's export corridor represent the dominant competitive moves.
Among integrated platform providers, Marel anchors the precision cutting workflow segment through its software-hardware convergence capabilities, while GEA Group occupies a position exemplifying advanced chilling system engineering for large-scale beef operations. JBT Corporation represents the vacuum packaging technology tier, with its positioning reflecting Southeast Asian exporter demand for shelf-life compliance systems. These three entities collectively illustrate how multinational specialists are defending margin positions through service contracting migration toward performance-guaranteed uptime agreements.
| Leading Market Players |
|---|
| Marel |
| GEA Group |
| JBT Corporation |
| Illinois Tool Works |
| Middleby Corporation |
| Heat and Control |
| BAADER |
| Handtmann |
| Mainca |
| Others |
Pricing and Supply Chain Analysis
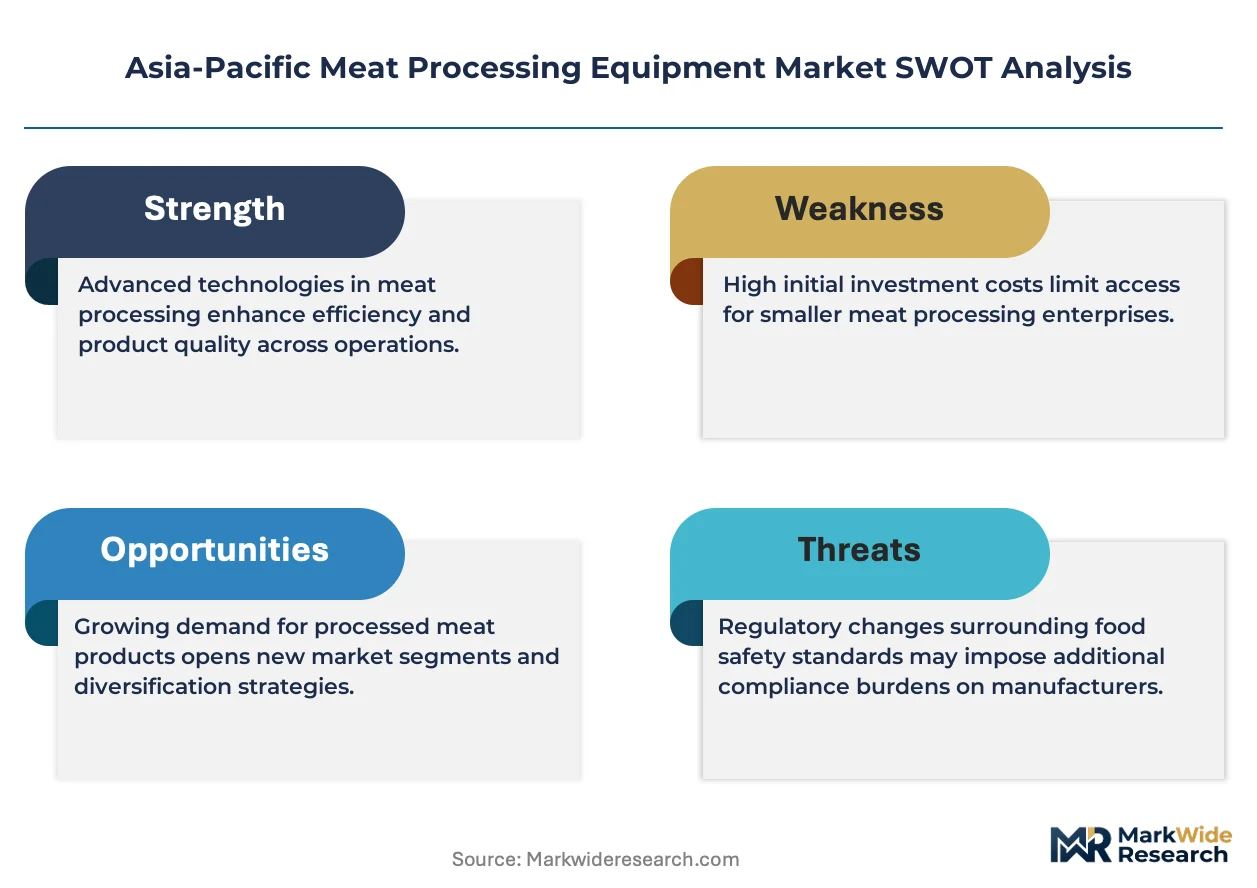
Hyperspectral imaging integration in Australian beef facilities is simultaneously compressing yield variance premiums and concentrating procurement leverage among integrated platform vendors capable of bundling hardware with real-time analytics software.
Pricing Analysis
Input-cost pass-through from nickel alloy volatility in stainless steel fabrication is compressing margins for regional equipment fabricators unable to hedge commodity exposure. Price differentiation centers on certification grade for Japanese and South Korean export compliance versus domestic-market equipment with lower sanitization specifications. Pricing pressure stems from Vietnamese poultry processors prioritizing guaranteed throughput rates over lowest initial acquisition cost. Small-scale Indonesian fabricators exhibit the highest price sensitivity, while Australian and New Zealand beef processors demonstrate willingness to pay premiums for yield analytics integration.
Supply Chain Analysis
Stainless steel feedstock supply rests on Chinese mills, Indonesian nickel ore processing, and Japanese specialty alloy refiners serving high-nickel content specifications. Critical component dependencies include German-engineered variable-speed compressors for METI-compliant chilling systems, Danish precision cutting blade assemblies, and vacuum pump technologies from European suppliers. Single-source vulnerability concentrates in advanced sealing system electronics for oxygen residual threshold compliance. Distribution runs through direct vendor relationships with large-scale food manufacturers and regional distributor networks serving mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on automation software subscription revenue displacing transactional equipment sales, with labor cost escalation in Thailand and Indonesia accelerating buyer willingness to accept performance-guaranteed uptime contracts.
For Market Incumbents: Deepen backward integration into stainless steel fabrication to offset nickel alloy cost volatility compressing regional competitor margins. Anchor service contracting migration toward remote diagnostics subscriptions that lock in recurring revenue streams and raise switching costs for Vietnamese export poultry processors. Prioritize certification pre-engineering for Indonesia's forthcoming halal mandates to capture line segregation architecture upgrades ahead of competitor response cycles. For New Entrants and Emerging Players: Begin with aftermarket service unbundling in secondary Indonesian and Philippine markets where technical support networks remain sparse and incumbent uptime guarantees are weakest. Target mid-tier Chinese processors facing SAMR compliance-driven replacement cycles with retrofit-focused surface engineering solutions rather than full-line automation. Pursue white-label partnerships with regional fabricators to compress go-to-market timelines against integrated multinational platforms. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional specialists serving single-species processors with limited software-hardware convergence capabilities. Long-term viability favors acquisition targets with installed base density in Vietnam's export corridor enabling service revenue migration. Watch Indonesian halal certification implementation timing as inflection trigger for sanitization protocol and line segregation equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Hardware Platform Integration | Combines precision cutting automation with real-time yield analytics for Australian beef processors. |
| Remote Diagnostics Subscription Launch | Captures recurring revenue from Vietnamese poultry exporters prioritizing supply continuity assurance. |
| Halal Certification Pre-Engineering | Positions vendors for Indonesia's national mandate reshaping multi-species facility architectures. |
| Backward Integration into Alloy Fabrication | Hedges nickel cost volatility threatening margins of stainless steel equipment fabricators. |
| Performance-Guaranteed Uptime Contracting | Shifts revenue model from capital sale to service bundles for Southeast Asian export processors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at Australian beef processors, procurement leads at Vietnamese poultry exporters, maintenance directors at Indonesian multi-species facilities, and aftermarket service heads at regional equipment distributors with secondary validation through customs trade data, SAMR regulatory filings, METI energy-efficiency standard documents, and industry association equipment shipment reports. Bottom-up installation base estimates and top-down protein production capacity analysis provided cross-verification.
Comparable historical periods anchored the projection horizon against prior equipment replacement cycles triggered by regulatory enforcement waves. Segmentation modeling spanned product type, end-user category, technology tier, and species-specific application across the analysis window. CAGRs derived from equipment shipment trajectories, protein production forecasts, and capital expenditure intention surveys. Industry-specific inputs included labor cost indices for Thailand and Indonesia, nickel alloy price series, and halal certification implementation timelines.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting Vietnamese export access, unanticipated SAMR enforcement intensity variations, and disruptive protein alternative substitution rates. Forecasts reflect documented assumptions about regulatory implementation pacing and commodity price stabilization. A small set of named triggers warrants ongoing watch: Indonesian halal mandate finalization, Japanese METI standard revision cycles, and nickel supply disruption events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Cashew Processing Machine Market
Agricultural Processing Equipment
Hemp Processing Equipment Market
Agricultural Processing Equipment
Defeathering Machine Market
Agricultural Processing Equipment
Destemmer Machine Market
Agricultural Processing Equipment
Corn Wet-Milling Market
Agricultural Processing Equipment
Harvesters Market
Agricultural Processing Equipment
Rice Milling Machinery Market
Agricultural Processing Equipment
China Agricultural Shredder Machine Market
Agricultural Processing Equipment
Egg Processing Machine Market
Agricultural Processing Equipment
Screw Press Dewatering Machine Market
Agricultural Processing Equipment
Poultry Processing Equipment Market
Agricultural Processing Equipment
Maize Milling Machine Market
Agricultural Processing Equipment
Grain Handling Equipment Market
Agricultural Processing Equipment
Oil Mill Machine Market
Agricultural Processing Equipment
Global Agricultural Harvesting Machinery Market
Agricultural Processing Equipment
Global Rice Milling Market