
 Harvesters Market | 2026-2036
Harvesters Market Size, Share, and Industry Trends Forecast 2026-2036
Harvesters Market Analysis
Dealer networks for harvester sales is narrowing as manufacturers consolidate distribution in key agricultural belts. AGCO Corporation leverages its Challenger and Fendt brand architecture to sustain premium positioning across North American and European markets. Deere & Company anchors its competitive stance through Precision Agriculture integration, bundling telemetry with combine sales. Kubota dominates compact harvester segments in Asia, where smallholder mechanization accelerates.
Harvesters are self-propelled or trailed machines engineered to cut, thresh, clean, and store grain in a single pass, with rotor speeds typically ranging from 450 to 1,200 rpm and grain tank capacities spanning 6,000 to 20,000 liters depending on model class. Self-propelled configurations command the largest value share due to their throughput advantage in large-scale commercial farming, while electric and hybrid technology segments attract capital as battery energy density improves for field equipment. Small and medium size classes serve cooperatives and agricultural contractors who prioritize transportability and lower capital commitment across fragmented landholdings.
The EPA in the United States enforces Tier 4 Final emission limits that shape engine architecture and after-treatment costs for equipment sold into the Corn Belt and Great Plains. Europe's Stage V standards, administered by member state type-approval authorities, extend particulate matter and NOx controls that push manufacturers toward hybrid powertrains. India's Central Pollution Control Board is drafting emission norms for agricultural equipment that will determine market access timing for domestic and imported harvesters. Stakeholders must track regulatory divergence between jurisdictions to optimize powertrain development spending and certification sequencing.
Market Dynamics
Stage V emission standards across Europe and Tier 4 Final limits in the United States are forcing fundamental powertrain redesigns, compressing development timelines and elevating certification costs for manufacturers serving commercial farming operations.
Growth Catalysts
- Labor scarcity in Brazilian commercial agriculture:Mechanized acreage expansion accelerates as farm wages rise and seasonal worker availability contracts, pulling self-propelled harvester demand into soy and corn belts.
- India's draft agricultural equipment emission norms:Anticipatory purchasing by Punjab and Haryana wheat-rice cooperatives ahead of Central Pollution Control Board implementation creates near-term equipment turnover.
- Telemetry bundling:Precision Agriculture integration raises equipment utilization rates and residual values, justifying capital deployment from large-scale operators.
Market Restraints
- After-treatment cost inflation:Diesel particulate filters and selective catalytic reduction systems add substantial material cost to engine architecture, squeezing margin on mid-size harvester classes.
- Dealer network consolidation:Distribution narrows to agricultural belts with proven volume density, leaving fragmented landholding regions with sparse service coverage and extended parts lead times.
- Battery energy density limitations:Field equipment electrification stalls below 200 kWh practical storage, constraining electric segment penetration to compact models with limited run-time requirements.
Strategic Opportunities
- Smallholder mechanization corridors:India's eastern states and Bangladesh delta regions present underpenetrated demand for sub-100 horsepower compact harvesters with transport-optimized dimensions.
- Hybrid powertrain development:Convergence of electric auxiliary drives with downsized diesel prime movers enables Stage V compliance without full electrification capex burden.
- Cooperative financing channels:Agricultural credit unions in Brazil's Mato Grosso and Goiás states expand equipment leasing products, lowering capital barriers for mid-scale operators.
Industry Challenges
- Embedded software certification:Functional safety validation for autonomous steering and yield mapping systems extends type-approval timelines, delaying model launches in regulated markets.
- Rotor dynamics engineering talent:Specialized expertise in threshing cylinder optimization and grain loss minimization concentrates at legacy manufacturers, constraining new entrant technical capability.
- Legacy fleet interoperability:Telemetry retrofits for decade-old combines face CAN bus protocol fragmentation, complicating unified fleet management for mixed-vintage operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Harvesters Market |
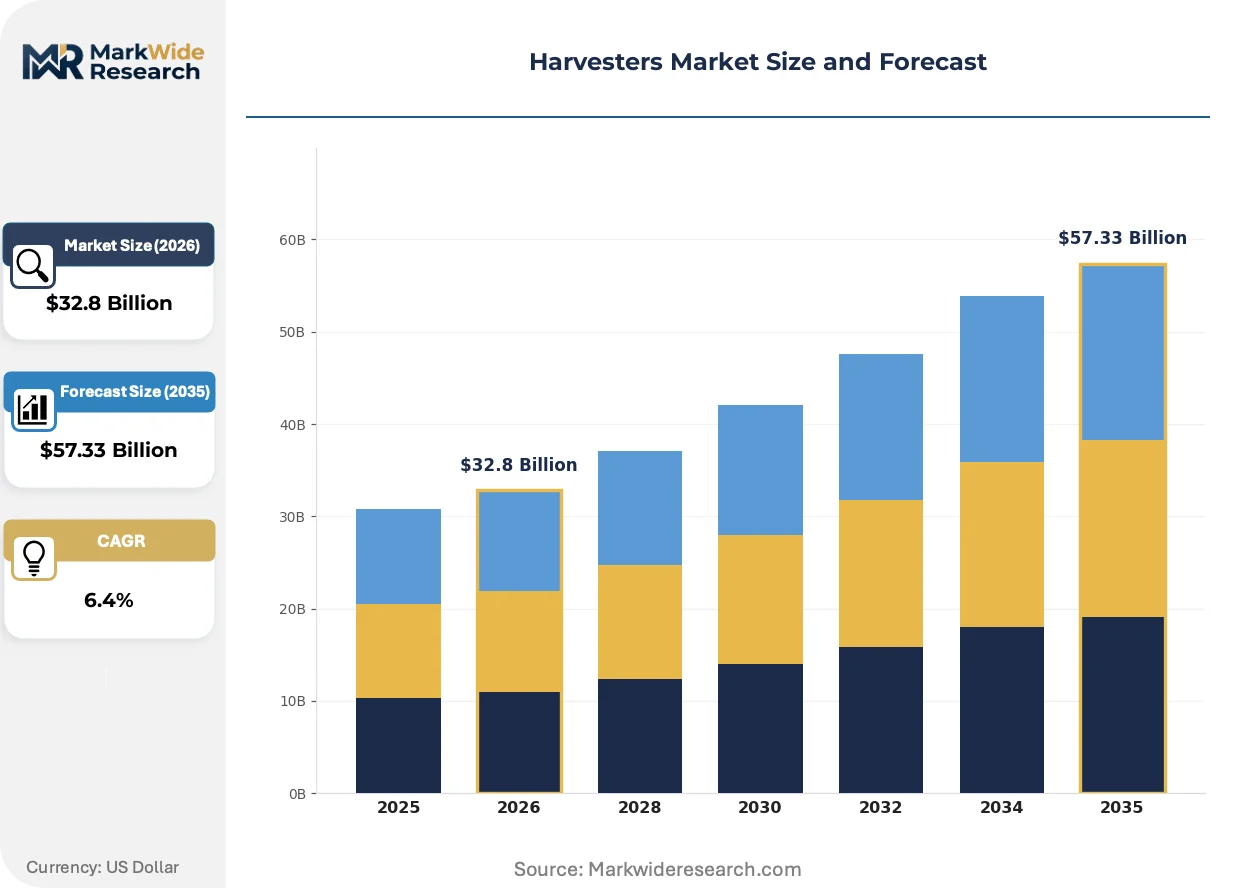
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Propelled, Pull-Type, Tow-Behind, Mounted End User: Commercial Farming, Cooperatives, Agricultural Contractors, Hobby Farmers Technology: Mechanical, Pneumatic, Electric, Hybrid Size: Small, Medium, Large, Extra Large |
| Companies Covered | AGCO Corporation, Zoomlion, Deere & Company, Mahindra & Mahindra, SDF Group, CNH Industrial, Kubota, Yanmar, CLAAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Harvesters Market Emerging Trajectories
Digital twin architectures and real-time yield mapping are compressing the feedback loop between field performance and equipment configuration, shifting competitive advantage toward data-integrated product ecosystems.
Virtual combine simulation is virtualizing pre-season setup optimization. North American large-scale operators deploy software replicas of their machines to model crop flow dynamics and calibrate rotor speeds before physical field entry. This capability is virtualizing traditional dealer field support relationships, compressing service revenue pools while locking in software subscription retention.
Europe's Stage V emission standards, enforced by member state type-approval authorities, mandate particulate number limits and real-driving emission monitoring. Engine manufacturers respond with hybrid architectures that downsize diesel displacement while adding electric boost for peak load conditions. Premium self-propelled segments absorb these powertrain costs most readily, widening price stratification against economy-class competitors.
Service unbundling accelerates as agricultural contractors separate maintenance contracts from original equipment purchases. Independent service networks in Australia's wheat belt and Canada's prairie provinces now compete for aftermarket revenue previously captured by manufacturer-dealer channels. This restructuring pressures OEM parts pricing power while elevating technician certification requirements for third-party providers.
Harvesters Market Segmentation
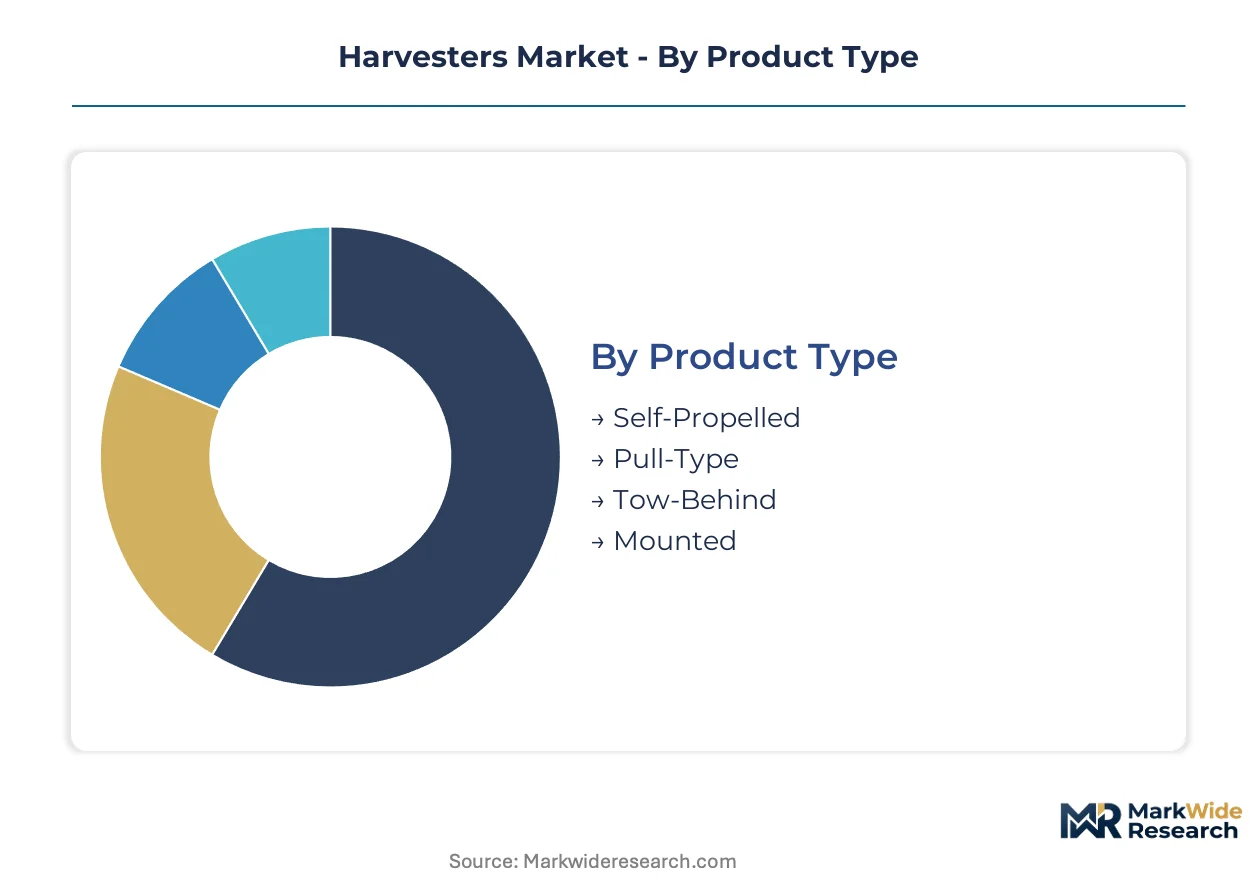
Harvester segmentation reflects divergent mechanization pathways across farm scale and powertrain maturity. Equipment configuration and technology tier determine capital deployment patterns from Brazilian soy operations to Indian rice cooperatives.
Product Type:
Use cases span autonomous field operations to tractor-dependent harvesting across fragmented landholdings and consolidated commercial acreage.
- Self-Propelled:Integrated chassis houses engine, threshing mechanism, grain tank, and unloading auger in a single mobile unit. Demand concentrates in Brazil's Mato Grosso soy belt and US Corn Belt operations where 12+ hour daily runtimes justify capital intensity. Labor scarcity in commercial agriculture accelerates replacement cycles.
- Pull-Type:Threshing and cleaning mechanism trails behind tractor power source, reducing upfront capital outlay. Adoption clusters among mid-scale cooperatives in India's Punjab and Haryana states where wheat-rice intensity demands seasonal equipment access without full ownership burden.
- Tow-Behind:Transport-optimized dimensions enable road-legal movement between dispersed fields. Agricultural contractors in Australia's wheat belt deploy these for multi-farm service coverage.
- Mounted:Compact units attach to three-point hitch systems on sub-100 horsepower tractors. Smallholder mechanization corridors in Bangladesh delta regions favor this entry-level configuration.
Established volume favors Self-Propelled; emerging adoption favors Mounted.
End User:
Customer economics range from yield-maximizing telemetry integration to seasonal rental utilization across ownership models.
- Commercial Farming:Large-scale operators deploy precision agriculture bundles combining telemetry, autonomous steering, and real-time yield mapping. Deere & Company anchors competitive positioning through software subscription retention in North American and European markets.
- Cooperatives:Shared equipment pools spread capital burden across member farms with fragmented landholdings. India's Central Pollution Control Board draft emission norms trigger anticipatory purchasing in Punjab and Haryana ahead of compliance deadlines.
- Agricultural Contractors:Service-based revenue models prioritize transportability and rapid field-to-field deployment. Independent maintenance networks in Canada's prairie provinces now compete for aftermarket revenue.
- Hobby Farmers:Subsistence and lifestyle operations drive compact harvester demand with limited runtime requirements. Battery energy density constraints constrain electric segment penetration to this price-sensitive tier.
Capital deployment concentrates with Commercial Farming; service model innovation favors Agricultural Contractors.
Technology:
Powertrain architecture responds to Stage V and Tier 4 Final emission limits while electric segments await energy density breakthroughs.
- Mechanical:Conventional diesel-mechanical drive systems dominate installed base with proven field reliability. Legacy fleet interoperability challenges complicate telemetry retrofits for decade-old combines.
- Pneumatic:Compressed air systems enable precise header height control and residue distribution. European manufacturers integrate these auxiliary functions into premium self-propelled configurations.
- Electric:Battery-powered units serve compact segments with sub-4 hour runtime requirements. Energy density limitations below 200 kWh practical storage stall penetration in large-scale grain handling.
- Hybrid:Downsized diesel prime movers combine with electric boost for peak load conditions. Stage V compliance without full electrification capex burden drives development investment from AGCO Corporation and Kubota.
Mechanical retains installed base dominance; hybrid architectures gain fastest regulatory-driven share.
Size:
Physical dimensions correlate with grain tank capacity, rotor throughput, and transport logistics constraints across operating environments.
- Small:Sub-6,000 liter grain tanks and sub-3 meter headers navigate narrow paddy fields and orchard configurations. Eastern Indian states present underpenetrated demand for transport-optimized compact harvesters.
- Medium:6,000-12,000 liter capacity balances field productivity with road-legal transport dimensions. Cooperatives and contractors prioritize this segment for multi-crop flexibility.
- Large:12,000-20,000 liter tanks with 7+ meter headers maximize daily throughput in uniform crop conditions. Brazilian commercial soy and corn operations pull demand as mechanized acreage expands.
- Extra Large:Maximum rotor speeds exceeding 1,000 rpm and 20,000+ liter capacity serve continuous harvest logistics. Premium self-propelled segments absorb powertrain cost inflation most readily.
Medium size sustains cooperative procurement; Extra Large commands technology integration premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA enforces Tier 4 Final emission limits that reshape equipment architecture for harvesters sold into the Corn Belt and Great Plains, establishing the regulatory baseline against which other jurisdictions calibrate their own standards.
United States
Commercial farming operations across Iowa and Illinois deploy precision agriculture bundles combining telemetry with combine sales. The EPA's Tier 4 Final standards mandate diesel particulate filters and selective catalytic reduction systems that elevate engine costs. Nebraska and Kansas grain handling corridors concentrate demand for large-capacity self-propelled configurations.
Brazil
Labor scarcity in Mato Grosso and Goiás soy belts accelerates mechanized acreage expansion as farm wages rise. ANVISA coordinates with environmental regulators on equipment import standards. Agricultural credit unions in the Center-West region expand equipment leasing products for mid-scale operators.
Germany
Stage V emission standards administered by the KBA extend particulate number limits and real-driving emission monitoring to non-road mobile machinery. Baden-Württemberg and Bavaria host engineering clusters developing hybrid powertrain architectures. Premium self-propelled segments absorb powertrain cost inflation most readily in these manufacturing zones.
India
Punjab and Haryana wheat-rice cooperatives drive anticipatory equipment purchasing ahead of Central Pollution Control Board emission norm implementation. BIS certification requirements determine market access timing for domestic and imported harvesters. Eastern states present underpenetrated demand for sub-100 horsepower compact harvesters with transport-optimized dimensions.
China
Smallholder mechanization corridors in the Yangtze River Delta and North China Plain pull demand for compact mounted configurations. MIIT oversees equipment standards under national agricultural mechanization programs. Shandong and Henan provinces concentrate manufacturing capacity for entry-level harvester classes serving domestic and export markets.
Harvesters Market Vendor Landscape
Full-line agricultural equipment conglomerates and specialized harvesting technology firms split the market along integration depth and application focus. Consolidation pressures favor entities with captive engine development and software subscription ecosystems. Two archetypes dominate: vertically integrated machinery groups controlling powertrain-to-telemetry stacks, and regional specialists optimizing transport-optimized dimensions for smallholder corridors. Competitive moves center on hybrid powertrain licensing partnerships and precision agriculture software bundling.
Within the full-line tier, AGCO Corporation and Deere & Company exemplify vertically integrated positions spanning premium brand architectures. Kubota occupies a compact-specialist anchor in Asian smallholder mechanization corridors. These three entities represent contrasting geographic and scale positioning without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| AGCO Corporation |
| Zoomlion |
| Deere & Company |
| Mahindra & Mahindra |
| SDF Group |
| CNH Industrial |
| Kubota |
| Yanmar |
| CLAAS |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Shandong and Henan manufacturing clusters compresses supplier margins while simultaneously enabling aggressive export pricing into Southeast Asian and African markets, creating divergent pricing postures between surplus-origin and deficit-destination regions. This utilization asymmetry forces OEMs to arbitrage component sourcing across geographies while defending premium positioning in regulated markets through certification-tier differentiation.
Pricing Analysis
North American Corn Belt pricing runs 15-25% above comparable Brazilian soy belt transactions after accounting for Tier 4 Final compliance costs and telemetry bundling. Three-tier pricing structure across premium, standard, and economy levels separates Deere and AGCO's precision-agriculture-integrated offerings from Kubota's compact-specialist positioning and Chinese OEM entry-level exports. Cost compression in mid-size mechanical-drive classes intensifies as Indian and Chinese manufacturers expand into cooperative procurement channels. Hobby farmers and smallholder cooperatives exhibit highest price sensitivity, while large-scale commercial operators prioritize total cost of ownership metrics including residual value and software subscription lock-in.
Supply Chain Analysis
Export-control restrictions on high-performance hydraulic systems and precision sensor arrays limit technology flows from Germany and Japan into Chinese manufacturing operations. Component supply concentrates in Germany for Stage V-certified engine architectures, China for steel-intensive threshing mechanisms, and Japan for compact transmission systems. Raw material dependencies include specialized alloy steels for rotor cylinders, rare-earth elements for electric auxiliary drives, and high-grade rubber compounds for track systems. Single-source vulnerability concentrates in precision yield-mapping sensor supply from German engineering clusters. Distribution runs through manufacturer-captive dealer networks in North America and Europe, shifting toward independent agricultural equipment traders in emerging mechanization corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The harvesters market is recovering from a cyclical trough driven by deferred replacement demand in Brazilian and North American commercial farming operations. Equipment age profiles and emission regulation deadlines are synchronizing to pull forward capital deployment across multiple geographies.
For Market Incumbents: Build telemetry ecosystem moats by bundling precision agriculture subscriptions with hardware sales to raise switching costs. Deepen backward integration into engine architecture to capture after-treatment margin compression from Tier 4 Final and Stage V compliance costs. Expand certified remanufacturing capacity in Mato Grosso and Iowa to defend against independent service network encroachment in aftermarket revenue pools.
For New Entrants and Emerging Players: Pursue compact harvester white space in India's eastern states and Bangladesh delta regions where sub-100 horsepower mechanization accelerates. Target cooperative financing channel partnerships in Brazil's Center-West to bypass established dealer network barriers. Anchor go-to-market strategy through agricultural credit union leasing products that lower capital barriers for mid-scale operators.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid powertrain development programs as Stage V compliance demands dual-architecture engineering. Long-term viability favors entities controlling software subscription ecosystems rather than pure hardware manufacturers. Acquisition target archetype: regional specialists with transport-optimized compact platforms and established smallholder channel relationships. Monitor battery energy density breakthroughs above 200 kWh practical storage as the signal indicating electric segment viability expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain Development | Stage V compliance without full electrification capex burden attracts AGCO and Kubota investment. |
| Precision Agriculture Bundling | Telemetry integration raises equipment utilization rates and residual values for Deere's North American customers. |
| Cooperative Financing Expansion | Agricultural credit unions in Mato Grosso lower capital barriers for mid-scale Brazilian operators. |
| Compact Platform Localization | Sub-100 horsepower harvester production in Shandong serves Yangtze River Delta smallholder mechanization. |
| Independent Service Network Buildout | Third-party maintenance certification in Australia's wheat belt pressures OEM parts pricing power. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with combine fleet managers at large-scale commercial operations, agricultural cooperative procurement officers in Punjab and Haryana, OEM product strategy directors, and independent service network technicians in Australia's wheat belt. Secondary validation drew from EPA Tier 4 Final regulatory filings, KBA Stage V type-approval documentation, Central Pollution Control Board draft norm releases, customs trade data for harvester component flows, and SEC 10-K equipment segment disclosures. Bottom-up equipment shipment data triangulated against top-down agricultural mechanization expenditure surveys.
Calibration against historical replacement cycles and emission regulation implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type configuration, powertrain technology tier, grain tank capacity class, end-user ownership model, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating equipment age profile analysis and cooperative financing penetration rates. Forecast inputs included labor scarcity indices in Brazilian commercial agriculture and draft emission norm implementation probability assessments for Indian markets.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese OEMs into premium self-propelled segments or accelerated battery energy density breakthroughs would shift outcomes. Material shifts in Central Pollution Control Board implementation timelines or Brazil's agricultural credit policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Destoner Machine Market
Agricultural Processing Equipment
Rotary Drum Dryers Market
Agricultural Processing Equipment
Global Threshers Market
Agricultural Processing Equipment
Corn Wet-Milling Market
Agricultural Processing Equipment
Meat Cutting Machine Market
Agricultural Processing Equipment
Global Agricultural Harvesting Machinery Market
Agricultural Processing Equipment
Cashew Processing Machine Market
Agricultural Processing Equipment
Dal Mill Machine Market
Agricultural Processing Equipment
Global Egg Processing Market
Agricultural Processing Equipment
Oil Mill Machine Market
Agricultural Processing Equipment
Industrial Shelling Machines Market
Agricultural Processing Equipment
Solar Herbs Dryer Market
Agricultural Processing Equipment
Manure Handling Equipment Market
Agricultural Processing Equipment
Rice Processing Machine Market
Agricultural Processing Equipment
Meat and Poultry Processing Equipment Market
Agricultural Processing Equipment
Meat Processing Equipment Market