
 Sugarcane Harvesters Market | 2026-2036
Sugarcane Harvesters Market Size, Share, and Industry Trends Forecast 2026-2036
Sugarcane Harvesters Market Analytics
The EU Green Deal is pivoting import requirements toward sustainably sourced sugar, compelling growers in supplier nations to adopt mechanized harvesting that eliminates pre-harvest cane burning. Deere & Company leverages its precision agriculture ecosystem to bundle harvesters with telemetry and fleet management tools. Grupo Jacto anchors its position through deep aftermarket service networks across Latin American cane regions. CNH Industrial N.V. competes via Case IH with specialized high-flotation tracks for wet-field conditions.
Sugarcane harvesters are self-propelled or towed agricultural machines equipped with basecutter blades, crop dividers, and cleaning systems that sever, gather, and clean stalks in a single pass, typically processing 50-100 tonnes per hour depending on row spacing and topping height. Self-propelled harvesters dominate commercial plantation deployments where daily throughput dictates fleet economics, while towed units sustain relevance among smaller cooperatives seeking lower capital outlay. GPS Navigation technology is displacing manual steering in premium configurations, though mechanical harvesting remains the volume standard across developing cane belts.
EPA emission standards for off-road diesel equipment and Brazil's CONAMA resolutions on agricultural burning shape engine certification requirements and harvester design specifications in the Americas. India's CEA rural electrification programs and the country's ethanol blending roadmap influence cooperative purchasing cycles and financing availability. Stakeholders must monitor how carbon border adjustment mechanisms in European destination markets redirect investment toward harvester fleets that can document full mechanization and zero-burn sourcing.
Market Dynamics
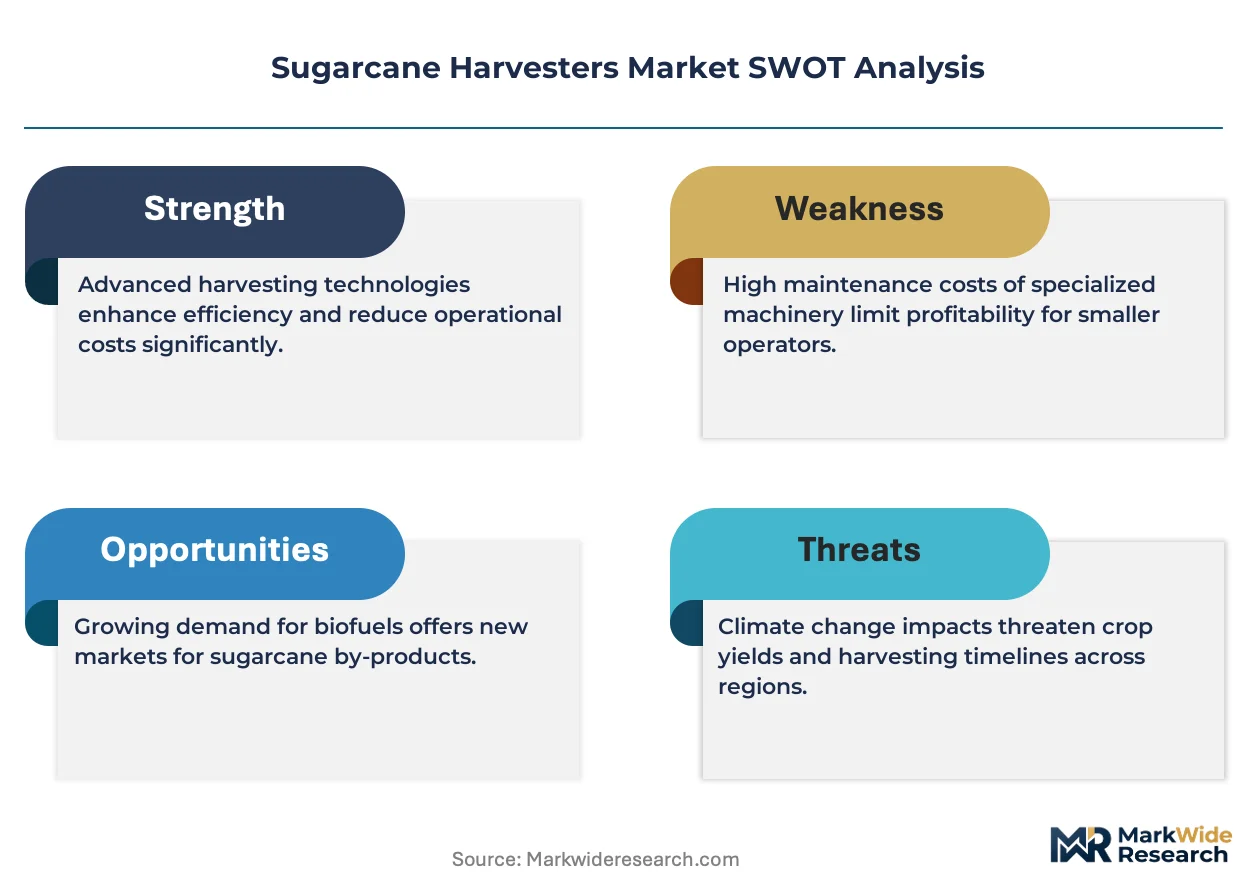
Mechanization pressure from Brazil's burning restrictions and India's ethanol mandates is compressing replacement cycles for harvester fleets, forcing capital deployment toward higher-throughput self-propelled units.
Growth Catalysts
- Brazil's CONAMA resolutions:Tightening agricultural burning restrictions in Center-South cane belts eliminate manual pre-harvest field preparation, mandating mechanized whole-stalk harvesting systems.
- India's ethanol blending roadmap:Cooperative mills face crushing capacity expansion deadlines, accelerating fleet turnover toward machines capable of 80+ tonnes per hour throughput.
- EU Green Deal import standards:European destination markets now require documented zero-burn sourcing certificates, compelling supplier nations to mechanize harvest documentation.
Market Restraints
- Steel and hydraulic component volatility:Harvester manufacturing depends on specialized high-tensile alloys and precision hydraulic systems subject to commodity price swings.
- Aftermarket parts concentration:Critical replacement components for basecutter blades and cleaning fans concentrate among Brazilian and German specialized foundries.
- High-flotation track technical limits:Wet-field performance requirements in tropical monsoon zones exceed current track flotation specifications without soil compaction trade-offs.
Strategic Opportunities
- Thailand's mechanization gap:Smallholder-dominated cane regions remain 60% manually harvested, creating first-mover advantage for compact self-propelled units with localized service networks.
- Telematics-converged fleet management:Integration of GPS guidance with real-time yield mapping and fuel monitoring creates recurring revenue streams beyond equipment sales.
- India's PLI scheme for farm machinery:Production-linked incentives for domestic manufacturing reduce import duty exposure for multinational assemblers establishing local plants.
Industry Challenges
- Mechatronics technician scarcity:Precision agriculture systems require hybrid mechanical-electronic diagnostic skills rarely available in rural cane belt labor pools.
- CE certification timeline compression:European carbon border documentation requirements demand retroactive supply chain auditing that legacy fleet operators cannot execute rapidly.
- Legacy mechanical steering integration:GPS autosteer retrofits face compatibility failures with hydraulic control architectures from 2010-era harvester platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugarcane Harvesters Market |
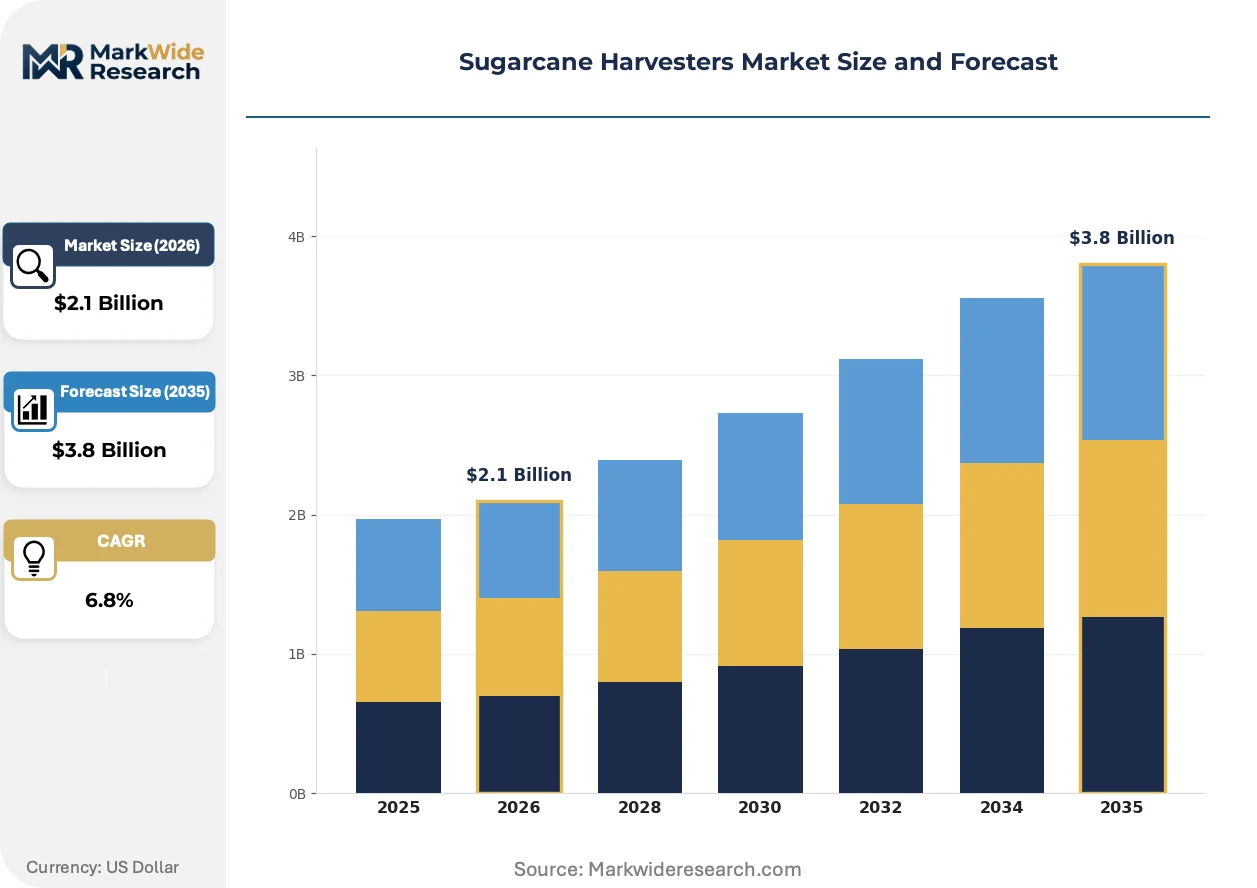
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Propelled Harvesters, Towed Harvesters, Hand-Held Harvesters, Automated Harvesting Systems Technology: Mechanical Harvesting, Hydraulics, Robotics, GPS Navigation End User: Farmers, Agricultural Cooperatives, Large Estates, Contractors Application: Small Scale Farming, Commercial Plantations, Organic Farming, Ethanol Production |
| Companies Covered | Zoomlion Heavy Industry Science and Technology Co., Ltd., Grupo Jacto, Deere & Company, Jiangsu World Agriculture Machinery Co., Ltd, Tirth Agro Technology Private Limited, CNH Industrial N.V., Case IH, Kartar Agro Industries Private Limited, AGCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugarcane Harvesters Market Evolving Landscape
Digital integration and powertrain electrification are restructuring how harvester fleets are deployed, maintained, and financed across tropical cane belts.
Harvesting system architecture is modularizing around swappable crop divider and basecutter configurations that adapt row spacing without full machine replacement. Large plantation operators in Brazil's São Paulo state now specify quick-change modules to compress inter-harvest downtime. This standardization is modularizing supplier ecosystems, allowing specialized component manufacturers to enter without full-harvester capability.
EPA Tier 4 Final and Stage V emission standards for off-road diesel equipment are forcing exhaust after-treatment retrofits and DEF infrastructure investments. Engine certification complexity has extended development cycles by 18-24 months for new harvester platforms. Case IH and John Deere are responding with dedicated emissions compliance engineering centers in Moline and Horizontina.
Cooperative purchasing consortia are displacing individual mill procurement committees across Maharashtra and Uttar Pradesh. Bulk fleet orders negotiated through regional sugar federations extract volume discounts and standardized service terms previously reserved for multinational plantation operators. This concentration is most visible in western India's Marathwada cluster, where three cooperatives now coordinate 40-unit annual acquisitions.
Sugarcane Harvesters Market Segmentation
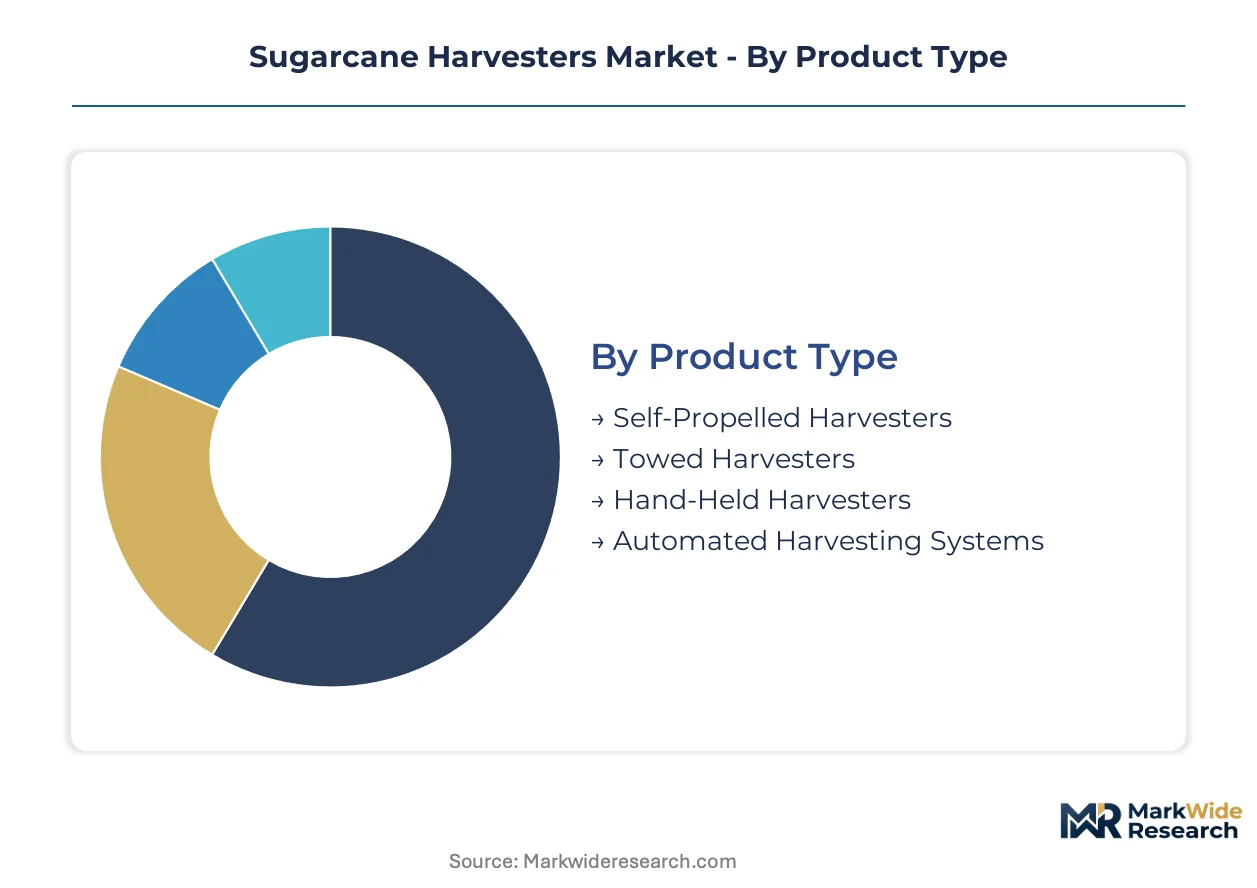
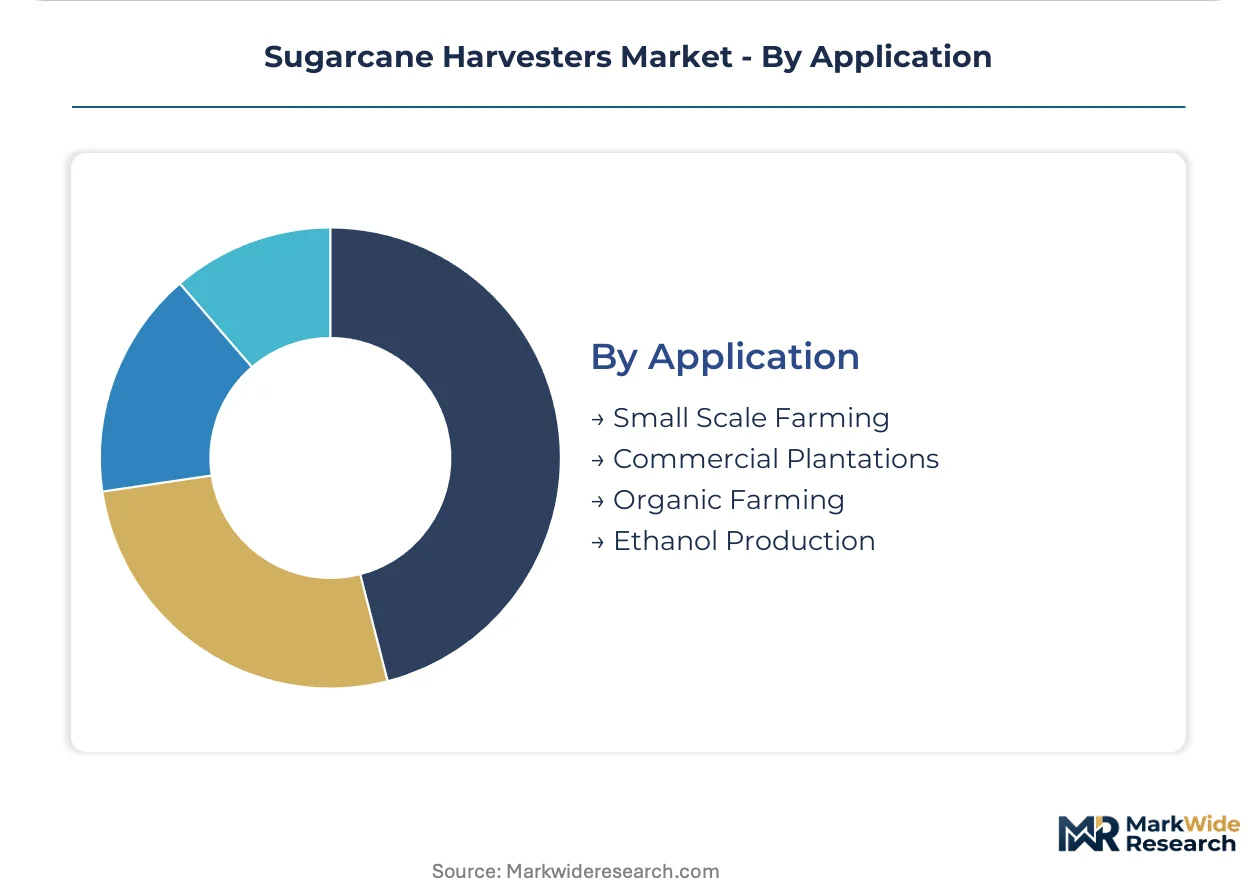
Fleet replacement cycles in Brazil and India are fragmenting demand across machine classes, with burning restrictions and ethanol mandates forcing distinct technology choices by operation scale. Segmentation reveals where capital concentrates versus where financing constraints persist.
Product Type:
Upgrade cycles favor machines that eliminate manual field preparation while containing capital exposure per hectare harvested.
- Self-Propelled Harvesters:These machines integrate basecutter blades, crop dividers, and cleaning systems in a single chassis, processing 50-100 tonnes per hour depending on row spacing. Demand concentrates in Brazil's Center-South cane belt where CONAMA burning restrictions mandate mechanized whole-stalk harvesting and daily throughput dictates fleet economics.
- Towed Harvesters:Lower capital outlay units hitch to tractor power take-off systems, preserving relevance among smaller cooperatives in India's Uttar Pradesh and Maharashtra states where crushing capacity expansion deadlines strain financing capacity.
- Hand-Held Harvesters:Portable gasoline or battery-powered units serve smallholder plots under five hectares across Thailand's northeast region where mechanization penetration remains limited.
- Automated Harvesting Systems:Experimental platforms incorporating machine vision and robotic topping arms undergo field trials in São Paulo state research stations.
Volume placements concentrate in self-propelled configurations; the faster expansion belongs to towed units as cooperative purchasing consortia spread capital constraints across smaller operations.
Technology:
Cost tiers separate precision agriculture investments from mechanical reliability standards across plantation operator budgets.
- Mechanical Harvesting:Conventional hydraulic steering and manual topper adjustment dominate developing cane belts where technician scarcity limits electronics maintenance capability.
- Hydraulics:High-pressure systems drive basecutter blade oscillation and cleaning fan operation, with component sourcing concentrated among Brazilian and German specialized foundries creating aftermarket parts vulnerability.
- Robotics:Autonomous stalk detection and automated topping height adjustment reduce cane loss in variable terrain, gaining traction in large São Paulo estates where labor cost escalation justifies premium capital deployment.
- GPS Navigation:Autosteer systems displace manual steering in premium configurations, though 2010-era hydraulic control architectures resist retrofit compatibility.
Procurement splits between mechanical reliability in volume segments and precision agriculture premiums where yield documentation supports EU Green Deal zero-burn certification.
End User:
Customer type determines financing access and fleet scale economics across tropical cane belts.
- Farmers:Individual owner-operators under 50 hectares rely on contractor services or hand-held equipment, constrained by credit access and harvest window compression risks.
- Agricultural Cooperatives:Regional sugar federations in western India's Marathwada cluster now coordinate bulk fleet orders, extracting volume discounts previously reserved for multinational plantation operators.
- Large Estates:Corporate operators in Brazil's São Paulo state specify quick-change crop divider modules to compress inter-harvest downtime and maximize asset utilization.
- Contractors:Mobile harvesting service providers deploy across multiple smallholder fields, prioritizing machine transportability and rapid row-spacing reconfiguration.
Margin capture concentrates with large estates; the steepest expansion trajectory belongs to cooperative purchasing consortia as India's ethanol blending roadmap accelerates fleet turnover.
Application:
Volume scale and certification requirements create divergent equipment specifications across end-use destinations.
- Small Scale Farming:Plots under 20 hectares sustain demand for towed and hand-held configurations where capital constraints outweigh labor cost pressures.
- Commercial Plantations:Large-scale operators require 80+ tonnes per hour throughput machines to meet crushing capacity expansion deadlines in India and Brazil.
- Organic Farming:Certification bodies mandate documented zero-burn sourcing, compelling mechanized harvest documentation that GPS-enabled fleets provide.
- Ethanol Production:Dedicated biofuel mills prioritize harvesting speed over sugar content preservation, favoring high-capacity self-propelled units with aggressive cleaning fan settings.
Equipment placements concentrate in commercial plantation configurations; certification-driven mechanization is climbing fastest among organic supply chains serving European destination markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil harvests more raw sugarcane tonnage than any nation, yet India consumes the largest share of processed sugar domestically. This production-consumption divide shapes divergent equipment specifications across tropical cane belts. Mechanization pressure concentrates where labor costs escalate and environmental regulations tighten pre-harvest field preparation.
Brazil
São Paulo state's Center-South cane belt drives fleet replacement toward 80+ tonnes per hour self-propelled units as CONAMA resolutions eliminate pre-harvest burning. The RenovaBio program mandates ethanol production documentation that mechanized harvesting supports. Ribeirão Preto anchors equipment deployment density, with plantation operators specifying quick-change crop divider modules to compress inter-harvest downtime.
India
Cooperative mills in Maharashtra and Uttar Pradesh face crushing capacity expansion deadlines under the ethanol blending roadmap, accelerating turnover toward higher-throughput machines. The CEA rural electrification programs and PLI scheme for farm machinery reshape financing availability and domestic assembly incentives. The Marathwada cluster now coordinates bulk fleet orders through regional sugar federations, extracting volume discounts previously reserved for multinational estates.
Thailand
Smallholder-dominated northeast cane regions remain 60% manually harvested, creating first-mover openings for compact self-propelled configurations with localized service networks. The Board of Investment promotes agricultural mechanization through tax incentives, though credit access constraints persist among plots under 20 hectares. Khon Kaen province exemplifies the mechanization gap, where contractor services bridge capital constraints for individual growers.
China
Guangxi Zhuang Autonomous Region concentrates domestic cane production, with state-owned farms piloting automated harvesting systems incorporating machine vision. The Ministry of Agriculture and Rural Affairs subsidizes precision agriculture equipment under rural revitalization programs. Nanning anchors manufacturing clusters for towed harvester components serving Southeast Asian export markets.
Australia
Queensland's Burdekin and Herbert River districts deploy high-flotation track configurations for wet-field conditions during monsoon harvest windows. The Great Barrier Reef protection regulations restrict pre-harvest burning, mandating full mechanization with documented zero-burn sourcing. Mackay hosts service networks for precision agriculture retrofits that support EU Green Deal export certification requirements.
Sugarcane Harvesters Market Competitive Landscape
The competitive structure tilts toward diversified agricultural equipment conglomerates with precision agriculture ecosystems. Three tiers separate premium self-propelled manufacturers from regional towed-harvester specialists and emerging automation-focused entrants. Consolidation pressure intensifies as emission compliance costs and telematics development cycles favor scale. Dominant competitive moves include strategic partnerships for localized service network expansion and portfolio diversification into fleet management software subscriptions.
Within the diversified equipment conglomerate tier, Deere & Company and CNH Industrial N.V. exemplify positioning through bundled telemetry and precision agriculture platforms. Grupo Jacto anchors the Latin American regional specialist archetype with deep aftermarket service penetration across Brazilian cane belts. Zoomlion Heavy Industry Science and Technology Co., Ltd. represents the scale-driven Chinese manufacturing segment with domestic supply chain integration for cost-competitive towed configurations. Jiangsu World Agriculture Machinery Co., Ltd. and Tirth Agro Technology Private Limited occupy positions among Asia-Pacific regional fabricators targeting cooperative purchasing consortia in India and Southeast Asian smallholder markets.
| Leading Market Players |
|---|
| Zoomlion Heavy Industry Science and Technology Co., Ltd. |
| Grupo Jacto |
| Deere & Company |
| Jiangsu World Agriculture Machinery Co., Ltd |
| Tirth Agro Technology Private Limited |
| CNH Industrial N.V. |
| Case IH |
| Kartar Agro Industries Private Limited |
| AGCO Corporation |
| Others |
Value Network & Pricing Analysis
Captive in-house production of high-tensile basecutter alloys and precision hydraulic systems anchors supply positioning for Brazilian and German specialized foundries, granting these upstream controllers pricing power over harvester OEMs facing EPA Tier 4 Final and Stage V compliance cost inflation. This backward integration into critical components insulates tier-one suppliers from commodity steel volatility while concentrating margin capture at the sub-assembly level.
Pricing Analysis
Margin tightening in self-propelled configurations reflects steel and hydraulic component volatility alongside extended engine certification cycles. Three-tier pricing structure across premium GPS-enabled fleets, standard mechanical-harvesting units, and economy towed configurations separates large São Paulo estates from Indian cooperative consortia and Thai smallholder contractors. Cost-down pressure on towed harvesters accelerates because India's PLI scheme for farm machinery redirects import substitution toward domestic assembly. Agricultural cooperatives in Maharashtra exhibit highest price sensitivity; multinational plantation operators in Brazil's Center-South cane belt show least sensitivity due to crushing capacity expansion deadlines.
Supply Chain Analysis
Mechatronics technician scarcity in Brazilian cane belt municipalities and Indian rural districts strains final assembly capacity despite component availability. Manufacturing concentrates in Brazil, Germany, and China, with specialized foundries in Ribeirão Preto and Horizontina feeding South American demand while Nanning anchors Chinese towed-harvester component clusters. Raw material dependencies center on high-tensile steel alloys, precision hydraulic systems, and DEF infrastructure for exhaust after-treatment. Single-source vulnerability concentrates in Brazilian aftermarket parts for basecutter blades and cleaning fans. Distribution runs through regional sugar federations in India and plantation operator procurement committees in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Harvesting equipment manufacturing is consolidating around vertical-integration races into precision agriculture software and captive aftermarket service networks, with players pursuing downstream control over telematics-converged fleet management as the decisive margin lever.
For Market Incumbents: Deploy telematics platform bundling to lock in recurring revenue beyond equipment sales and capture cooperative purchasing consortia migrating toward standardized fleet terms. Defensive moves require emission compliance engineering center expansion in Moline and Horizontina to compress 18-24 month development cycles, alongside quick-change crop divider module standardization to eliminate inter-harvest downtime threats from modular competitors. Threat substitution emerges from automated harvesting systems incorporating machine vision undergoing São Paulo field trials. For New Entrants and Emerging Players: The 40% price-point gap between premium GPS-autosteer self-propelled units and economy towed harvesters in Thailand's northeast cane belt exposes white-space opportunity. Target compact self-propelled configurations with localized service networks in Khon Kaen province where 60% manual harvesting persists. Penetrate through contractor service provider channels prioritizing machine transportability and rapid row-spacing reconfiguration over plantation direct sales. For Investors and Strategic Acquirers: Exit pathways concentrate in precision agriculture software specialists with proven GPS-yield mapping integration and established Brazilian or Indian service network density. Long-term viability over the projection horizon favors targets with backward integration into hydraulic component manufacturing or captive DEF infrastructure deployment. Acquisition archetype: regional fabricators with PLI scheme qualification and cooperative federation procurement relationships. Watch India's ethanol blending roadmap crushing capacity deadlines as inflection signal for fleet replacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Creates recurring revenue streams beyond equipment sales for Deere and CNH Industrial precision agriculture ecosystems. |
| Backward Integration into Hydraulic Components | Reduces single-source vulnerability to Brazilian and German specialized foundries for basecutter blade supply. |
| Quick-Change Module Standardization | Compresses inter-harvest downtime for São Paulo plantation operators maximizing asset utilization rates. |
| Emissions Compliance Engineering Center Expansion | Addresses EPA Tier 4 Final and Stage V certification complexity extending harvester platform development cycles. |
| Cooperative Purchasing Consortium Penetration | Captures bulk fleet order volume discounts previously reserved for multinational plantation operators in India. |
Research Methodology
Trade association filings, agricultural equipment registration databases, and customs import records formed the secondary backbone, supplemented by equipment manufacturer technical documentation and regional sugar federation procurement disclosures. Primary interviews with plantation operations managers, cooperative mill procurement committees, aftermarket service network heads, and precision agriculture systems engineers combined with secondary validation. Bottom-up triangulation across machine class shipment data and top-down reconciliation against crushing capacity expansion announcements anchored volume estimates.
Bottom-up modeling of self-propelled, towed, hand-held, and automated harvesting system shipments by throughput capacity tier, technology configuration, and end-user scale across the projection horizon generated baseline volume estimates. Segmentation dimensions included product type, technology tier, end-user archetype, and application destination. CAGRs derived from fleet replacement cycle compression analysis under Brazil's CONAMA burning restrictions and India's ethanol blending mandates. Industry-specific inputs incorporated RenovaBio program documentation requirements and EU Green Deal zero-burn certification demand trajectories.
Inputs from cooperative procurement committees and plantation operator technical staffs were available through the study window; gaps in real-time yield mapping adoption rates and GPS autosteer retrofit penetration introduce uncertainty bands around precision agriculture revenue projections. Forecasts reflect assumptions regarding CONAMA resolution enforcement timelines and PLI scheme disbursement continuity. Material deviation in Brazilian burning restriction penalties or Indian ethanol blending deadline extensions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Screw Press Dewatering Machine Market
Agricultural Processing Equipment
Grain Processing Equipment Market
Agricultural Processing Equipment
Meat Dicing Machine Market
Agricultural Processing Equipment
Global Nut Processing Equipment Market
Agricultural Processing Equipment
Destemmer Machine Market
Agricultural Processing Equipment
Global Rice Milling Market
Agricultural Processing Equipment
Harvesters Market
Agricultural Processing Equipment
Rice Polishing Machines Market
Agricultural Processing Equipment
Egg Processing Machine Market
Agricultural Processing Equipment
Rice Milling Machines Market
Agricultural Processing Equipment
Solar Powered Agricultural Dryer Market
Agricultural Processing Equipment
Cashew Processing Machine Market
Agricultural Processing Equipment
Industrial Shelling Machines Market
Agricultural Processing Equipment
Color Sorter Market
Agricultural Processing Equipment
Global Dry Milling Market
Agricultural Processing Equipment
Corn Wet-Milling Market