
 North America Feed Pelletizing Agent Market | 2026-2036
North America Feed Pelletizing Agent Market Size, Share, and Industry Trends Forecast 2026-2036
North America Feed Pelletizing Agent Market Analytics
Distributor networks across the Great Plains and Southeastern feed corridors is fragmenting as direct-to-mill procurement platforms gain share. BASF SE leverages its technical service infrastructure to anchor relationships with integrated poultry operators. Kemin Industries Inc. differentiates through species-specific formulation support, while Archer Daniels Midland Company competes on backward integration into corn wet-milling feedstock supply.
Feed pelletizing agents encompass binders, lubricants, and functional additives that reduce fines, improve pellet durability, and optimize extrusion throughput in compound feed manufacturing; lignosulfonate and bentonite clay formulations typically achieve pellet durability indices above ninety percent in standard broiler rations. Binder chemistry dominates value capture in the product type dimension, reflecting higher per-ton pricing and technical specification requirements from export-certified feed mills. Poultry application volumes lead absolute consumption, though aquaculture-grade coating agents represent the fastest margin expansion trajectory as marine feed producers adopt water-stable pellet technologies.
FDA enforcement of the Food Safety Modernization Act elevates documentation burdens for imported additive chemistries, while EPA discharge permits constrain binder manufacturing co-product streams in the Ohio River Valley. The Canadian Food Inspection Agency maintains parallel but non-identical approval pathways that complicate cross-border product registration for U.S. suppliers. Stakeholders must monitor pending state-level PFAS testing mandates that could disqualify certain petrochemical-derived lubricant chemistries from pet food and specialty livestock channels.
Market Dynamics
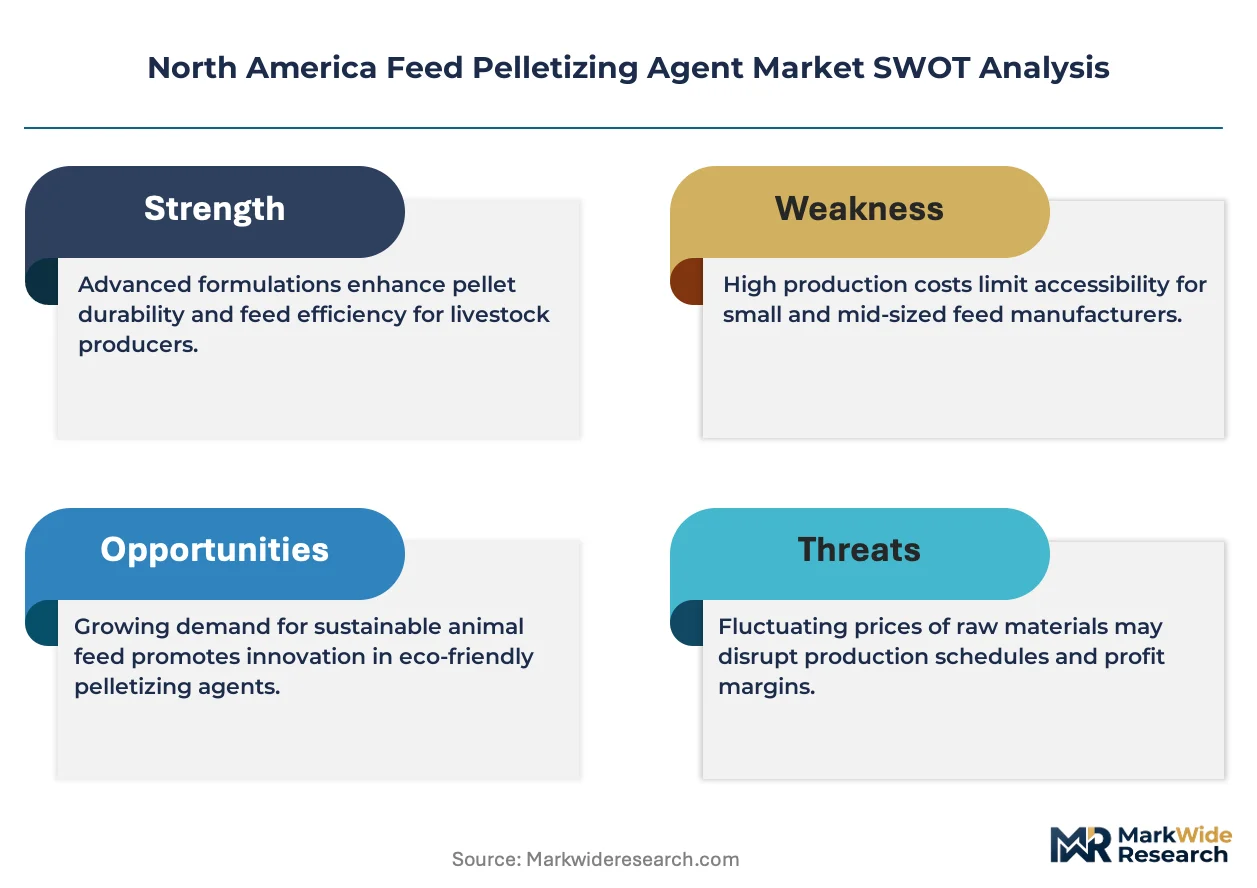
FDA enforcement of the Food Safety Modernization Act compels additive traceability upgrades across U.S. feed manufacturing, forcing binder suppliers to restructure documentation systems and quality assurance protocols.
Growth Catalysts
- Protein Output Targets:Livestock feed manufacturers in the United States are expanding binder procurement to meet rising domestic and export protein production goals. Corn-belt processing corridors concentrate demand for high-durability pellet formulations.
- FSMA Traceability Mandates:The FDA's feed safety modernization protocols elevate documentation requirements, creating pull for certified additive suppliers with validated supply chain systems. Export-certified feed mills prioritize compliant binder chemistries.
- Aquaculture Water-Stable Technologies:Marine feed producers across the Pacific Northwest and Gulf Coast are adopting specialized coating agents. Water-stable pellet innovations drive margin expansion in this application segment.
Market Restraints
- Petrochemical Lubricant Disqualification Risk:Pending state-level PFAS testing mandates threaten to exclude certain synthetic lubricant chemistries from pet food and specialty livestock channels. Formulation switches impose reformulation costs.
- Cross-Border Registration Friction:The Canadian Food Inspection Agency maintains parallel but non-identical approval pathways that complicate product registration for U.S. suppliers seeking market access.
- Co-Product Stream Constraints:EPA discharge permits limit binder manufacturing co-product streams in the Ohio River Valley, capping production expansion at existing facilities.
Strategic Opportunities
- Species-Specific Formulation Services:Technical support infrastructure anchored to poultry, swine, and ruminant nutrition science creates differentiation. Integrated operators value binder suppliers with in-house veterinary nutrition expertise.
- Direct-to-Mill Procurement Platforms:Digital procurement channels are fragmenting traditional distributor networks across the Great Plains and Southeastern feed corridors. Platform economics favor suppliers with technical service depth.
- Backward Integration into Feedstock Supply:Corn wet-milling operations offer captive lignosulfonate and starch-based binder feedstocks. Control over raw material sourcing compresses input cost volatility.
Industry Challenges
- Veterinary Nutritionist Talent Scarcity:Formulation support teams require cross-trained professionals spanning animal science, polymer chemistry, and regulatory compliance. Recruitment lags behind service expansion needs.
- Legacy System Integration Complexity:Traceability upgrades must interface with existing mill control systems and ERP platforms. Custom API development extends implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Feed Pelletizing Agent Market |
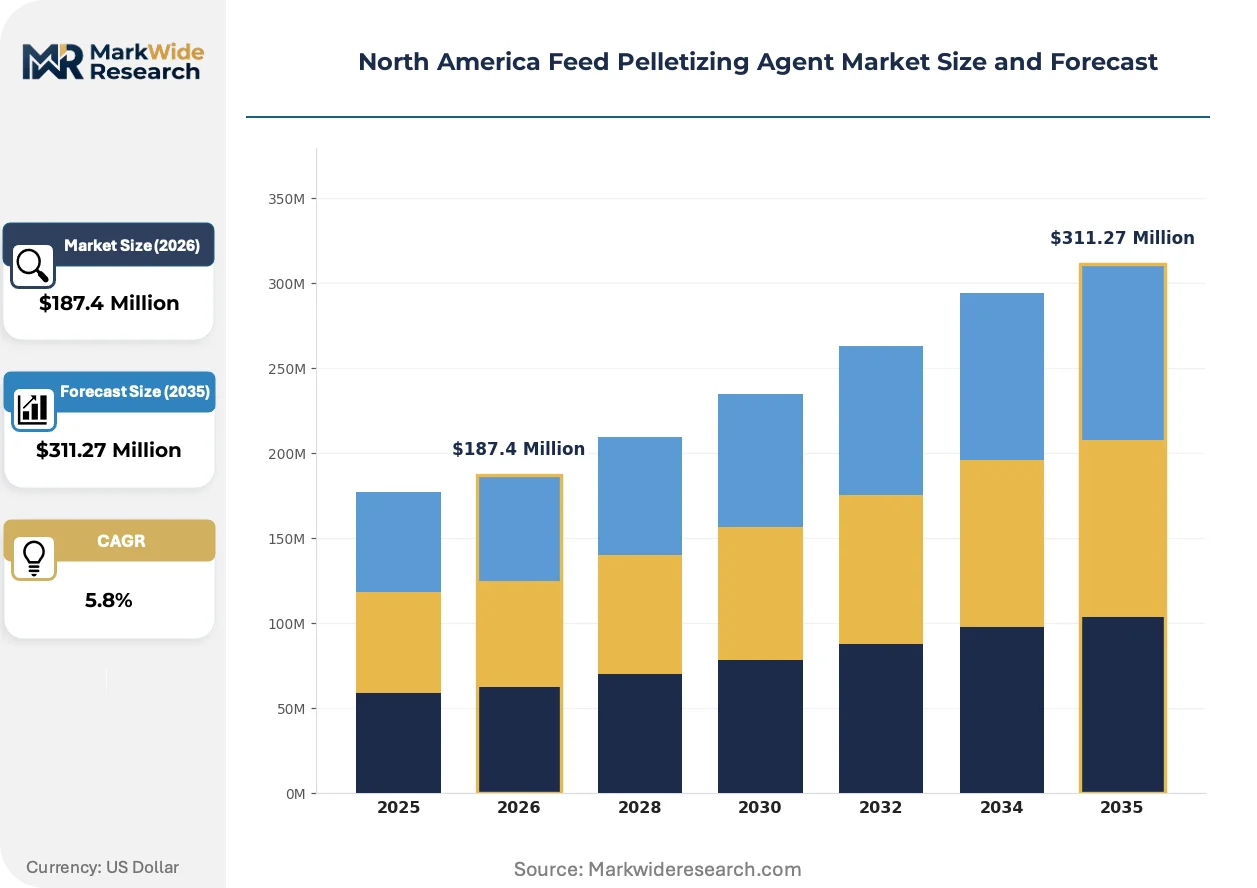
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Binder, Lubricant, Additive, Coating Agent Application: Aquaculture, Livestock, Poultry, Pet Food Form: Granular, Powder, Liquid, Pastes End User: Feed Manufacturers, Farms, Research Institutions, Distributors |
| Companies Covered | Archer Daniels Midland Company, Adisseo SAS, BASF SE, Kemin Industries Inc., Cra-Vac Industries Inc., Uniscope Inc., Borregaard AS, EW Nutrition, Bentonite Performance Minerals LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Feed Pelletizing Agent Market Evolving Landscape
Formulation chemistry and procurement infrastructure are undergoing parallel transformation. Binder performance specifications tighten while purchasing channels digitize, compressing margins for intermediaries and rewarding technical service capabilities.
Lignosulfonate-bentonite hybrid binders are collapsing the performance gap between mineral and organic formulations in standard broiler rations. Integrated poultry operators in the U.S. Southeast are accelerating adoption of these chemistries. The technology is collapsing premium pricing tiers for conventional bentonite clay as durability indices above ninety percent become table stakes.
The EPA's evolving PFAS discharge monitoring framework is reshaping lubricant chemistry portfolios across the Ohio River Valley manufacturing cluster. Petrochemical-derived coating agents face phased substitution pressure. Aquaculture-grade producers in the Pacific Northwest are pivoting fastest toward bio-based alternatives to preempt regulatory disqualification.
Feed mill procurement teams are consolidating supplier relationships around technical service depth rather than transactional pricing. Direct platform purchasing displaces layered distributor networks in the Midwest corn belt. This concentration is most visible among top-twenty integrated poultry operators with captive nutrition science teams.
North America Feed Pelletizing Agent Market Segmentation
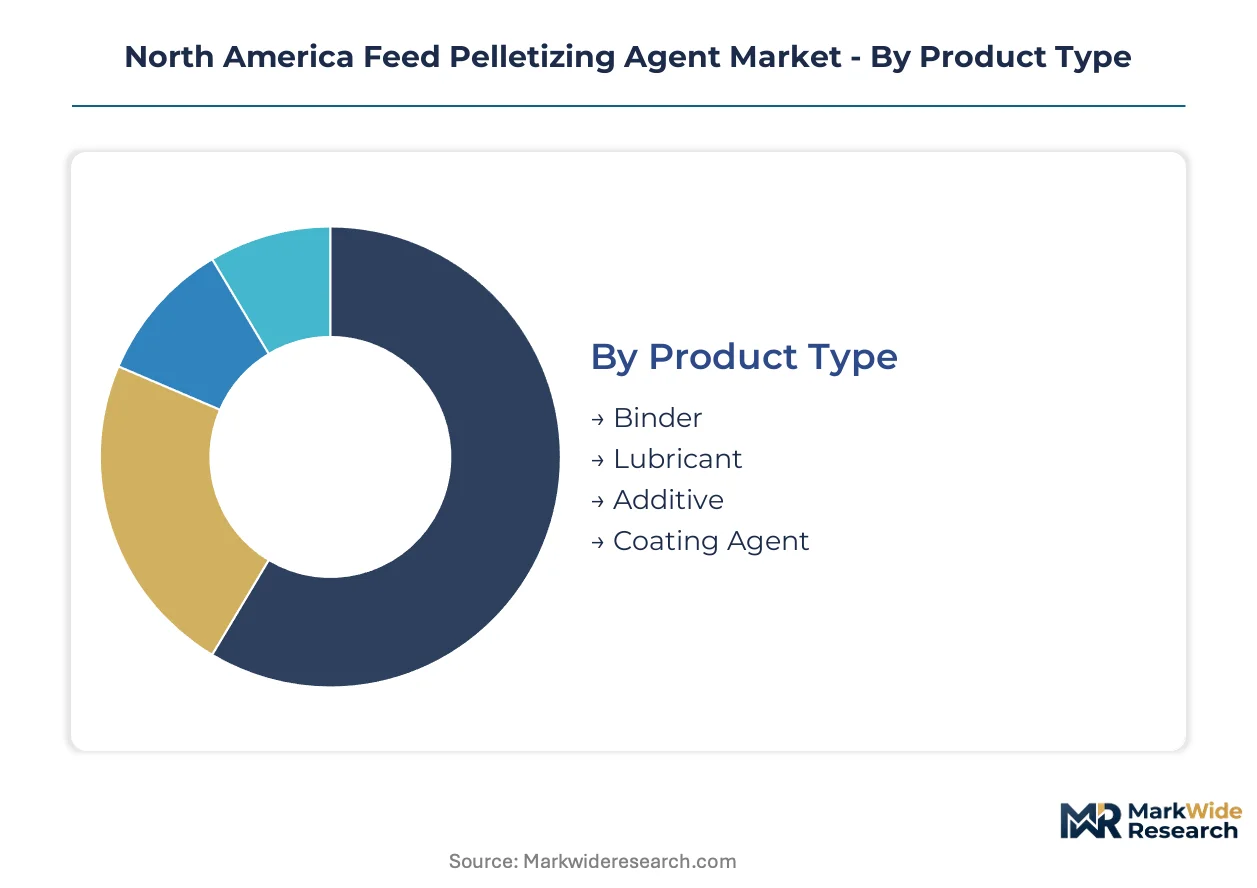
Feed pelletizing agent procurement patterns diverge sharply across product chemistry and end-use specifications. Manufacturers configure formulation portfolios around species-specific durability requirements and mill processing economics rather than uniform commodity supply.
Product Type:
Cost tier stratification in pelletizing chemistry separates mineral-derived commodities from performance-premium organic formulations.
- Binder:Lignosulfonate and bentonite clay formulations dominate tonnage throughput in standard broiler rations, achieving pellet durability indices above ninety percent. U.S. Midwest corn-belt processing corridors concentrate procurement for high-volume livestock operations facing export certification requirements.
- Lubricant:Petrochemical-derived and bio-based coating agents reduce die wear and extrusion energy consumption in high-throughput mill operations. EPA discharge monitoring frameworks in the Ohio River Valley manufacturing cluster are accelerating formulation switches toward plant-derived alternatives.
- Additive:Functional chemistries including moisture conditioners and antioxidants optimize shelf stability and nutrient retention.
- Coating Agent:Water-stable technologies serve aquaculture-grade specifications in Pacific Northwest and Gulf Coast marine feed operations.
Binder holds installed capacity. Coating Agent is rotating up the share rankings.
Application:
Volume concentration across species segments reflects protein output targets and regulatory stringency tiers.
- Poultry:Integrated operators in the U.S. Southeast and Midwest drive absolute consumption volumes for high-durability formulations. FDA FSMA traceability mandates elevate documentation requirements for export-certified mills serving this channel.
- Aquaculture:Marine feed producers adopt specialized water-stable pellet technologies with the steepest expansion trajectory in margin contribution. Washington State and Louisiana processing facilities anchor demand for coating agent innovation.
- Livestock:Cattle and swine operations in the Great Plains prioritize cost-optimized binder systems for dry feed rations.
- Pet Food:Specialty channels face pending state-level PFAS testing mandates that threaten disqualification of certain synthetic lubricant chemistries.
Poultry commands current volume leadership. Aquaculture is climbing the fastest in value contribution.
Form:
Physical state selection hinges on mill equipment configuration and batch processing versus continuous extrusion workflows.
- Powder:Dry lignosulfonate and bentonite blends integrate into premix systems across corn-belt feed manufacturing facilities. Bulk handling infrastructure favors powder logistics for high-tonnage livestock operations.
- Liquid:Pumpable lubricant and coating systems enable precision dosing in automated extrusion lines. Gulf Coast aquaculture processors specify liquid application for water-stable coating uniformity.
- Granular:Free-flowing particulate forms reduce dust generation in handling and storage environments.
- Pastes:High-viscosity formulations target niche specialty feed applications requiring targeted adhesion properties.
Powder maintains equipment compatibility advantages. Liquid is gaining share fastest in automated mill upgrades.
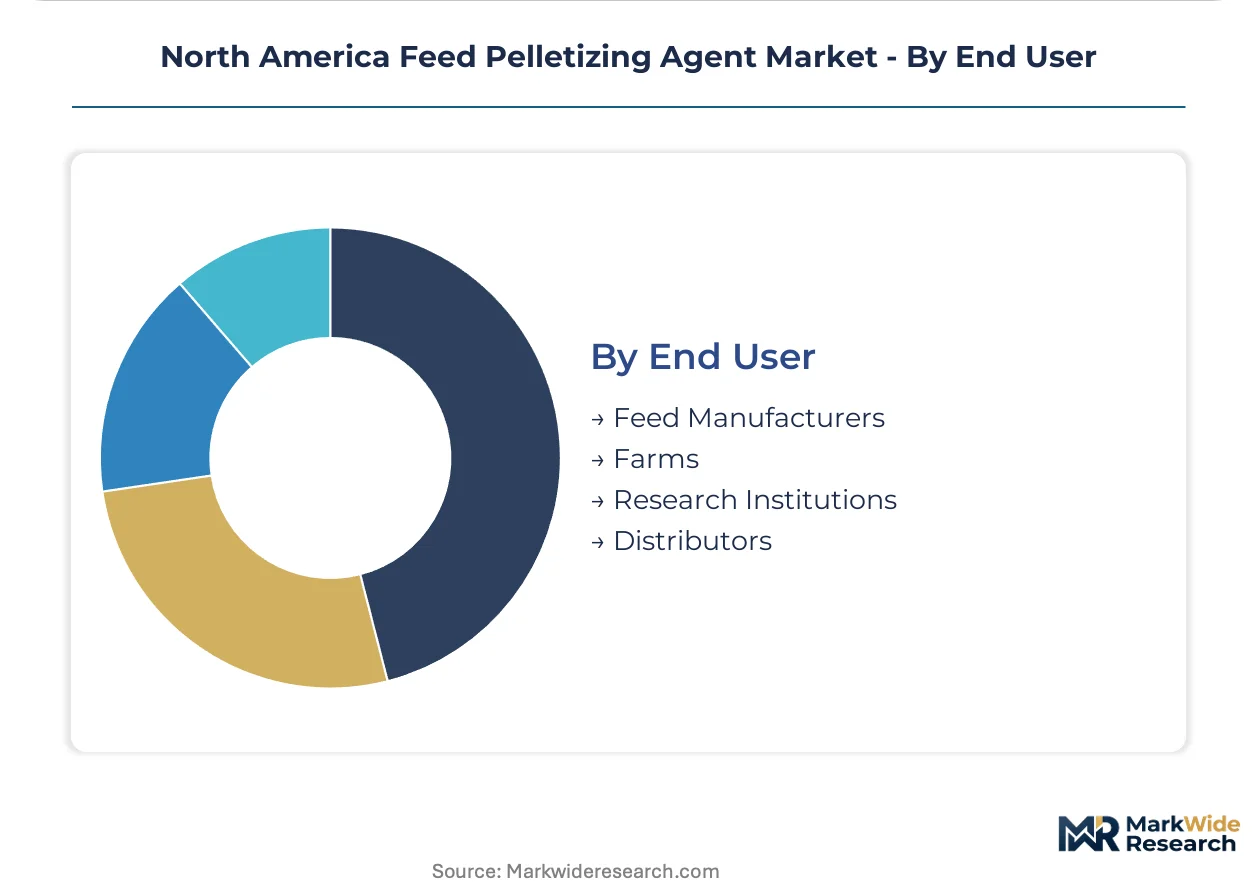
End User:
Customer type determines technical service intensity and procurement channel structure.
- Feed Manufacturers:Integrated poultry operators with captive nutrition science teams consolidate supplier relationships around formulation support depth rather than transactional pricing. Direct-to-mill procurement platforms fragment traditional distributor networks across the Great Plains and Southeastern corridors.
- Farms:Smaller-scale operations rely on distributor intermediaries for blended product access and technical guidance.
- Research Institutions:Veterinary schools and feed science centers pilot novel binder chemistries and durability testing protocols.
- Distributors:Intermediary networks face margin compression as digital procurement channels displace layered wholesale relationships.
Feed Manufacturers anchor technical service investment. Distributors are rotating down the value chain as platform purchasing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing leverage concentrates in the U.S. Midwest corn-belt processing corridor, while Canadian suppliers absorb cross-border registration friction that compresses margin capture. Mexico's livestock feed expansion generates volume pull without corresponding premium capture.
United States
Integrated poultry operators in the U.S. Southeast and Midwest drive absolute consumption volumes for high-durability pellet formulations. FDA FSMA traceability mandates elevate documentation requirements for export-certified mills serving this channel. Corn-belt processing facilities in Iowa and Illinois anchor demand concentration as livestock feed manufacturers expand binder procurement to meet protein output targets.
Canada
Livestock operations across the Prairie Provinces prioritize cost-optimized binder systems for cattle and swine feed rations. The Canadian Food Inspection Agency maintains parallel but non-identical approval pathways that complicate product registration for U.S. suppliers seeking market access. Ontario feed manufacturing clusters face documentation burdens for imported additive chemistries under CFIA enforcement protocols.
Mexico
Poultry and livestock feed producers in the Bajío Region and Northern Border States scale compound feed manufacturing to serve domestic protein demand. Mexico's national agricultural health authority operates feed additive registration frameworks that diverge from U.S. FDA protocols. Guanajuato and Querétaro processing corridors concentrate procurement for standard broiler rations without premium-tier specification requirements.
North America Feed Pelletizing Agent Market Competitive Landscape
Integrated nutrition-science providers and commodity-chemical suppliers split the market into distinct service-intensity tiers. Structure consolidates around three to five dominant technical-service platforms with captive formulation expertise, while regional distributors face margin compression from direct-to-mill procurement channels. Strategic archetypes include backward-integrated feedstock controllers, species-specific formulation specialists, and digital procurement platform operators. Competitive moves center on technical-service infrastructure expansion and supply-chain digitization investments.
Among North American chemical and agricultural conglomerates, Archer Daniels Midland Company, BASF SE, and Kemin Industries Inc. exemplify divergent competitive positioning. Archer Daniels Midland anchors the backward-integration archetype through corn wet-milling feedstock control. BASF SE occupies the technical-service-depth tier with infrastructure anchored to integrated poultry operators. Kemin Industries represents the species-specific formulation specialist model with veterinary nutrition science integration.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Adisseo SAS |
| BASF SE |
| Kemin Industries Inc. |
| Cra-Vac Industries Inc. |
| Uniscope Inc. |
| Borregaard AS |
| EW Nutrition |
| Bentonite Performance Minerals LLC |
| Others |
Value Network & Pricing Analysis
Undercapacity in Ohio River Valley lignosulfonate production constrains supplier flexibility and elevates pricing leverage for backward-integrated corn wet-milling operators. FDA FSMA traceability mandates add documentation cost layers that feed through to configured-to-order premium tiers while standard binder formulations face margin compression from direct-to-mill procurement digitization.
Pricing Analysis
Configured-to-order premium spreads widen as export-certified feed mills demand species-specific formulation support and validated supply chain documentation. Three-tier pricing structure across premium, standard, and economy levels separates aquaculture-grade coating agents with water-stable performance guarantees from commodity bentonite clay for livestock rations. Cost compression in standard broiler binder tiers intensifies because direct platform purchasing eliminates distributor markups. Integrated poultry operators with captive nutrition science teams exhibit lowest price sensitivity; smaller Great Plains cattle feedlots demonstrate highest.
Supply Chain Analysis
Tariff exposure between the United States and Canada complicates cross-border additive registration and fragments procurement scale economics. Raw material sourcing draws from domestic corn wet-milling byproducts, imported bentonite clay deposits, and bio-based lubricant feedstocks. Single-source vulnerability concentrates in specialty aquaculture coating agent precursors. Distribution runs through direct-to-mill digital platforms for top-twenty integrated operators and layered distributor networks for smaller farms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary nutritionist talent scarcity constrains technical service expansion across formulation support teams. Cross-trained professionals spanning polymer chemistry, animal science, and FDA compliance protocols command premium compensation that compresses service-margin economics.
For Market Incumbents: Insulate margin position by deepening backward integration into corn wet-milling feedstock supply and accelerating species-specific formulation infrastructure for aquaculture-grade coating agents. PFAS regulatory disqualification risk threatens synthetic lubricant portfolios; bio-based alternative R&D investment defends against state-level testing mandates. For New Entrants and Emerging Players: Establish a beachhead in Pacific Northwest marine feed coating agent segments where water-stable technology adoption outpaces incumbent technical service capacity. Mexican Bajío Region poultry operations present underpenetrated volume opportunity with lower certification barriers than export-certified U.S. mills. Digital procurement platform partnerships bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aquaculture-grade coating agent manufacturing as EPA discharge permit constraints limit Ohio River Valley expansion. Long-term viability favors targets with captive lignosulfonate feedstock access and in-house veterinary nutrition expertise. Monitor CFIA-U.S. FDA regulatory harmonization progress as cross-border registration simplification signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Corn wet-milling control compresses input cost volatility for lignosulfonate binders. |
| Species-Specific Formulation Services | Veterinary nutrition expertise anchors relationships with integrated poultry operators. |
| Direct-to-Mill Procurement Platform | Digital channels displace distributor intermediaries across Midwest corn-belt corridors. |
| Bio-Based Lubricant Transition | Plant-derived alternatives preempt EPA PFAS discharge monitoring disqualification. |
| Cross-Border Registration Harmonization | CFIA-FDA alignment simplifies product approval for U.S. suppliers entering Canada. |
Research Methodology
The analysis maps binder chemistry tiers, lubricant formulation classes, and coating agent performance specifications, each validated through feed mill procurement directors, veterinary nutritionists, and regulatory compliance officers. Primary fieldwork combined structured interviews with technical service heads at integrated poultry operators and secondary validation through FDA FSMA guidance documents, EPA discharge permit databases, and CFIA additive approval registries. Bottom-up volume modeling triangulated against top-down corn-belt processing capacity estimates.
Assumptions held feed safety modernization enforcement intensity and protein output target trajectories fixed across the projection horizon while varying PFAS regulatory adoption timing and aquaculture water-stable technology penetration rates. Segmentation dimensions modeled include product chemistry class, species application, physical form factor, and end-user procurement channel structure. CAGRs derived from installed capacity utilization trends and mill upgrade cycle timing. Industry-specific forecast inputs incorporated corn wet-milling byproduct availability and marine feed production expansion.
Sensitivities concentrate around state-level PFAS testing mandate adoption schedules and CFIA cross-border registration pathway simplification. Forecasts reflect documented assumptions regarding FDA enforcement consistency and export certification demand growth. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Animal Feed Processing Equipment Market
Agricultural Processing Equipment
Global Threshers Market
Agricultural Processing Equipment
Shelling Machine Market
Agricultural Processing Equipment
Rotary Drum Dryers Market
Agricultural Processing Equipment
Global Dry Milling Market
Agricultural Processing Equipment
Grain Handling Equipment Market
Agricultural Processing Equipment
Feed Screw Barrel Market
Agricultural Processing Equipment
Global Feed Processing Market
Agricultural Processing Equipment
Corn Wet-Milling Market
Agricultural Processing Equipment
Solar Powered Agricultural Dryer Market
Agricultural Processing Equipment
Asia-Pacific Meat Processing Equipment Market
Agricultural Processing Equipment
Meat Processing Equipment Market
Agricultural Processing Equipment
Cassava Processing Market
Agricultural Processing Equipment
Cashew Processing Machine Market
Agricultural Processing Equipment
Manure Handling Equipment Market
Agricultural Processing Equipment
Color Sorter Market