
 Pulp Wash Equipment Market | 2026-2036
Pulp Wash Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Pulp Wash Equipment Market Analysis
Buyer concentration among integrated pulp-to-paper groups is expanding as Latin American and Southeast Asian producers merge fiber sourcing with captive washing capacity. Valmet leverages its fiberline automation portfolio to anchor long-term service contracts across Nordic and South American mill upgrades. ANDRITZ competes through chemical recovery integration, bundling wash stages with evaporation and lime kiln systems. Kadant Inc. specializes in doctoring and filtration accessories that extend washer run-time between maintenance cycles.
Pulp wash equipment comprises pressure screens, vacuum drum washers, dilution control systems, and stock preparation cleaners engineered to remove dissolved organics, lignin residues, and extractives from chemical or mechanical pulp slurries before bleaching or papermaking. Continuous washers dominate capital expenditure among greenfield kraft mills due to throughput advantages above 1,500 air-dried metric tonnes per day. Biological wash technology represents the fastest-growing segment as enzymatic pretreatment reduces chlorine dioxide demand and effluent toxicity. Small-scale and custom-scale installations serve specialty pulp producers in flax, hemp, and dissolving wood pulp niches where batch flexibility outweighs unit cost economics.
EPA effluent limitation guidelines for pulp and paper mills in the United States enforce Best Available Technology standards on biological oxygen demand and adsorbable organic halogen discharge, directly shaping washer specification and caustic recovery design. China's MEE enforces stricter COD limits on Yangtze River basin mills, forcing retrofits of older vacuum washer lines with closed-loop pressure systems. ECHA REACH restrictions on formaldehyde-based biocides in European pulp imports are redirecting formulation choices toward enzyme-based wash aids. Stakeholders must monitor how carbon border adjustment mechanisms and evolving water-stress indices redirect greenfield investment toward regions with lower regulatory compliance cost trajectories.
Market Dynamics
China's MIIT water-efficiency mandates are compressing replacement cycles for vacuum washer lines as pulp mills face tightening COD discharge limits on the Yangtze River basin, forcing capital redeployment toward closed-loop pressure systems.
Growth Catalysts
- Eucalyptus pulp corridor expansion:Brazil's kraft capacity additions by Arauco and Suzano are driving greenfield washer installations for bleached hardwood pulp output.
- EPA effluent limitation guidelines:Best Available Technology standards on biological oxygen demand are mandating upgraded caustic recovery and wash stage specifications across US mills.
- Enzymatic pretreatment adoption:Biological wash technology is reducing chlorine dioxide demand and effluent toxicity in tissue and packaging paper manufacturing.
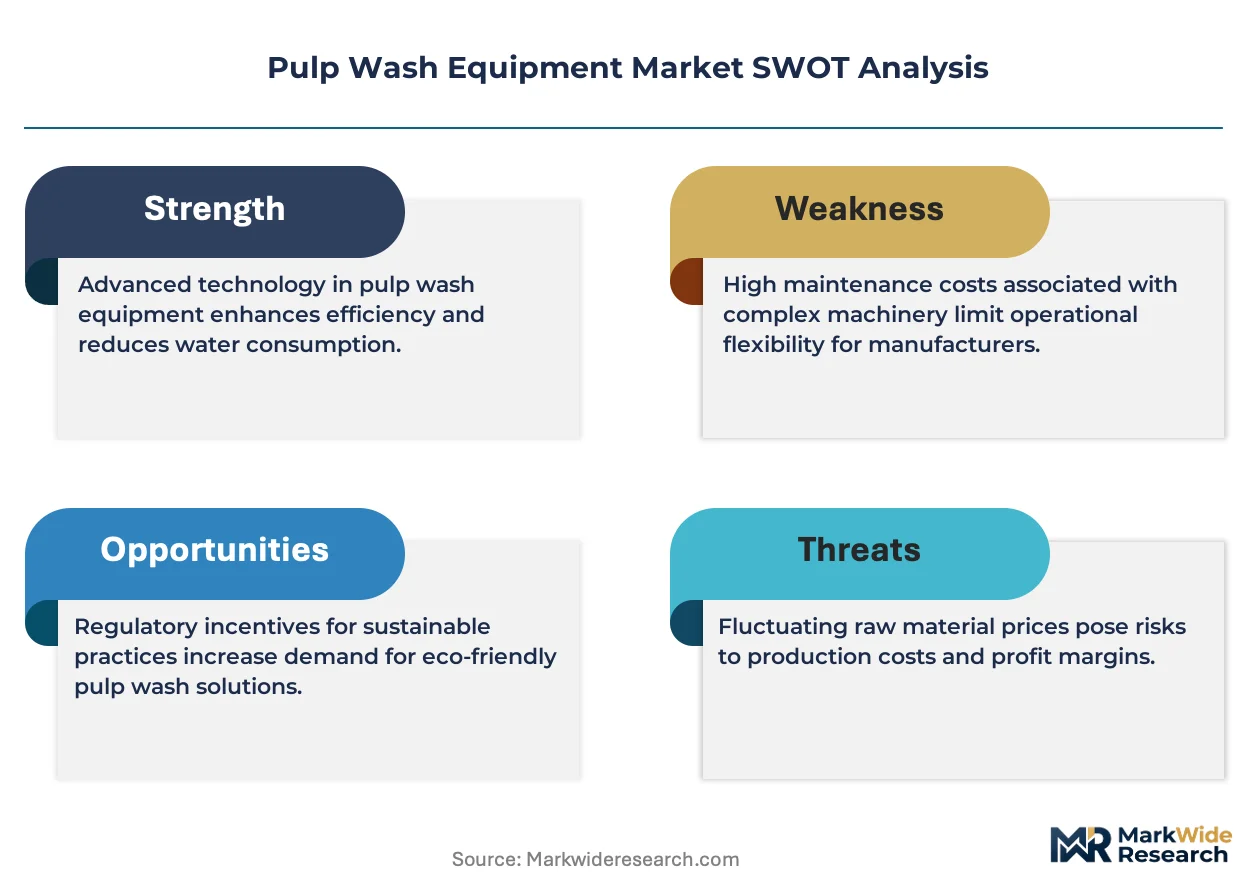
Market Restraints
- Stainless steel input volatility:Pressure screen and vacuum drum washer fabrication depends on nickel and chromium price swings that compress equipment margin buffers.
- Specialized fabricator concentration:Nordic and South American mill upgrade markets rely on a narrow supplier base for high-tonnage continuous washer systems.
- Legacy vacuum washer technical ceiling:Older open-loop designs cannot achieve the water-recirculation ratios demanded by China's MEE river basin standards.
Strategic Opportunities
- Flax and hemp specialty pulp niches:Small-scale batch washer installations serve dissolving wood pulp producers where flexibility outweighs unit cost economics.
- ECHA REACH biocide restrictions:Formaldehyde-based wash aid prohibitions are redirecting formulation demand toward enzyme-based alternatives in European import supply chains.
- Automation-service bundling:Fiberline control system integration creates multi-year service contract anchors beyond initial equipment sale.
Industry Challenges
- Process control engineering talent scarcity:Dilution control system commissioning requires specialized expertise in pulp consistency measurement that outpaces training pipeline output.
- Legacy DCS integration friction:New pressure screen installations must interface with decades-old distributed control architectures without disrupting continuous kraft line operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulp Wash Equipment Market |
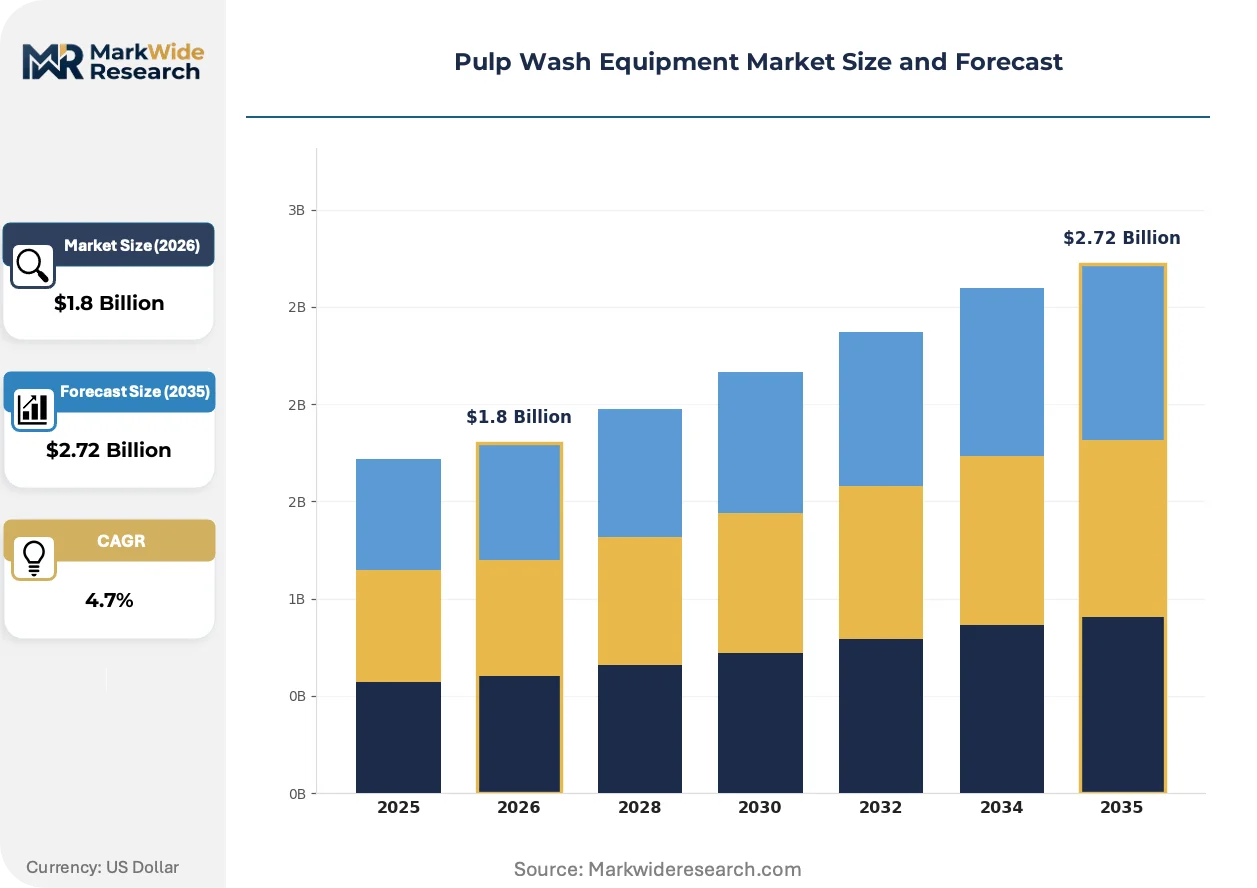
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Washers, Continuous Washers, Vacuum Washers, Pressure Washers Technology: Chemical Wash, Mechanical Wash, Thermal Wash, Biological Wash End User: Pulp Mills, Paper Manufacturers, Recycling Facilities, Industrial Plants Capacity: Small Scale, Medium Scale, Large Scale, Custom Scale |
| Companies Covered | Valmet, ANDRITZ, Kadant Inc., GL&V, Leizhan, Wenrui, Zhengzhou Guangmao Machinery Manufacture Co. Ltd, Shandong Hantong Aote Machinery Co. Ltd, China National Building Material International Equipment Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulp Wash Equipment Market Emerging Trajectories
Equipment architecture is fragmenting into configurable subsystems as pulp mills demand faster reconfiguration between hardwood, softwood, and recycled fiber slurries without full line shutdowns.
Enzymatic wash aid delivery systems are modularizing across Nordic and South American kraft mills. Bleached pulp producers in the eucalyptus corridor are piloting plug-and-play enzyme dosing skids that slot between existing vacuum drum stages. This architecture is modularizing capital deployment, allowing mills to stage biological upgrades without committing to full fiberline rebuilds.
China's MEE Yangtze River basin COD limits are forcing closed-loop pressure washer retrofits that eliminate open dilution discharge. Mills in Hubei and Jiangsu provinces are replacing atmospheric vacuum washers with pressurized displacement systems that recirculate filtrate through multi-stage countercurrent washing. The packaging paper segment bears the steepest compliance cost burden, with integrated producers absorbing engineering validation timelines that stretch eighteen to twenty-four months.
Buyer concentration among integrated pulp-to-paper groups is compressing vendor negotiation cycles as Latin American and Southeast Asian producers merge fiber sourcing with captive washing capacity. Equipment procurement is consolidating under single-source framework agreements that bundle pressure screens, vacuum drums, and stock preparation cleaners. Brazil's eucalyptus corridor exhibits the most pronounced procurement consolidation, with Arauco and Suzano negotiating multi-mill supply contracts that displace spot purchasing.
Pulp Wash Equipment Market Segmentation
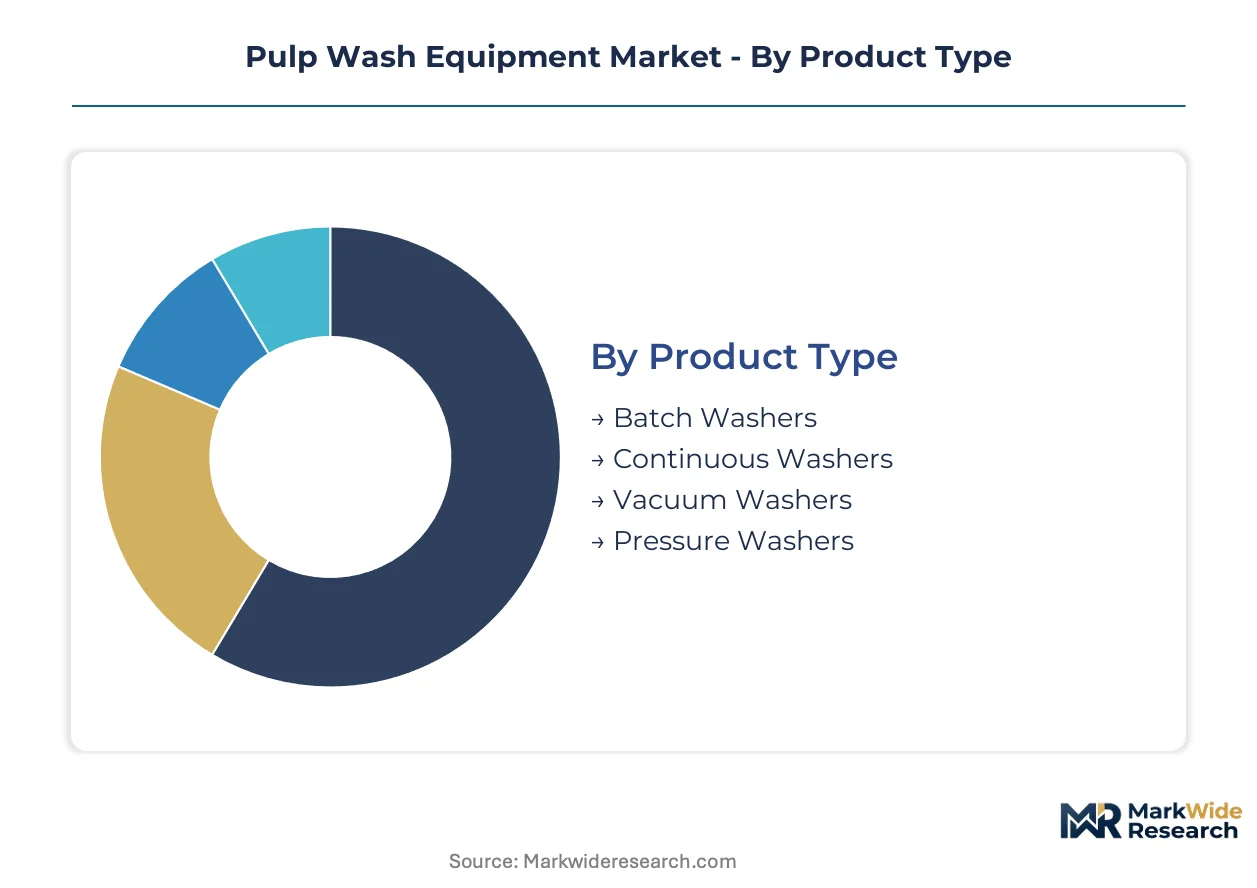
Pulp wash equipment segmentation tracks how capital deployment splits between high-throughput continuous systems and flexible batch configurations. Equipment specification varies sharply by fiber type, regulatory jurisdiction, and integration depth with chemical recovery loops.
Product Type:
Mill operators select washer architecture based on daily tonnage targets and water-recirculation mandates from basin-specific regulators.
- Continuous Washers:These systems process slurry through uninterrupted countercurrent stages, achieving extraction efficiency above 98% for lignin and dissolved organics. Demand concentrates among greenfield kraft mills in Brazil's eucalyptus corridor, where Arauco and Suzano specify units exceeding 1,500 air-dried metric tonnes per day to match bleached hardwood pulp expansion timelines.
- Vacuum Washers:Atmospheric drum designs rely on differential pressure to dewater pulp mat while diluting carryover chemicals. China's MEE Yangtze River basin discharge rules are forcing replacement cycles across Hubei and Jiangsu provinces, as open-loop vacuum lines cannot achieve the closed water-recirculation ratios now mandated for COD compliance.
- Batch Washers:Intermittent operation suits specialty pulp producers requiring frequent fiber changeovers.
- Pressure Washers:Pressurized displacement systems eliminate atmospheric discharge points entirely.
Continuous washers lead volumes today; pressure washers are gaining share fastest.
Technology:
Wash chemistry selection determines chlorine dioxide consumption, effluent toxicity profiles, and compatibility with enzymatic pretreatment stages.
- Biological Wash:Enzymatic pretreatment deploys cellulase and xylanase cocktails to hydrolyze lignin-carbohydrate complexes before chemical bleaching. Nordic tissue producers are piloting plug-and-play enzyme dosing skids that slot between existing vacuum drum stages, cutting chlorine dioxide demand while meeting EPA Best Available Technology standards for adsorbable organic halogen discharge.
- Chemical Wash:Caustic extraction and oxidative stages remain dominant for virgin kraft pulp, particularly where high brightness targets exceed 90% ISO.
- Mechanical Wash:High-consistency refining and screening reduce chemical load but limit final pulp cleanliness.
- Thermal Wash:Steam conditioning softens lignin structure prior to alkaline extraction.
Chemical wash dominates current installation bases; biological wash is expanding most quickly.
End User:
Buyer concentration varies by vertical integration depth and captive pulp requirements.
- Pulp Mills:Standalone chemical pulp producers specify multi-stage wash lines as core fiberline assets.
- Paper Manufacturers:Integrated pulp-to-paper groups bundle washer procurement under framework agreements spanning pressure screens, vacuum drums, and stock preparation cleaners.
- Recycling Facilities:Deinking operations require specialized cleaners for adhesive and ink particle removal.
- Industrial Plants:Non-paper cellulose applications in textiles and specialty chemicals drive small-scale batch installations.
Pulp mills anchor equipment demand today; paper manufacturers are consolidating procurement fastest.
Capacity:
Scale selection reflects tension between unit cost economics and operational flexibility.
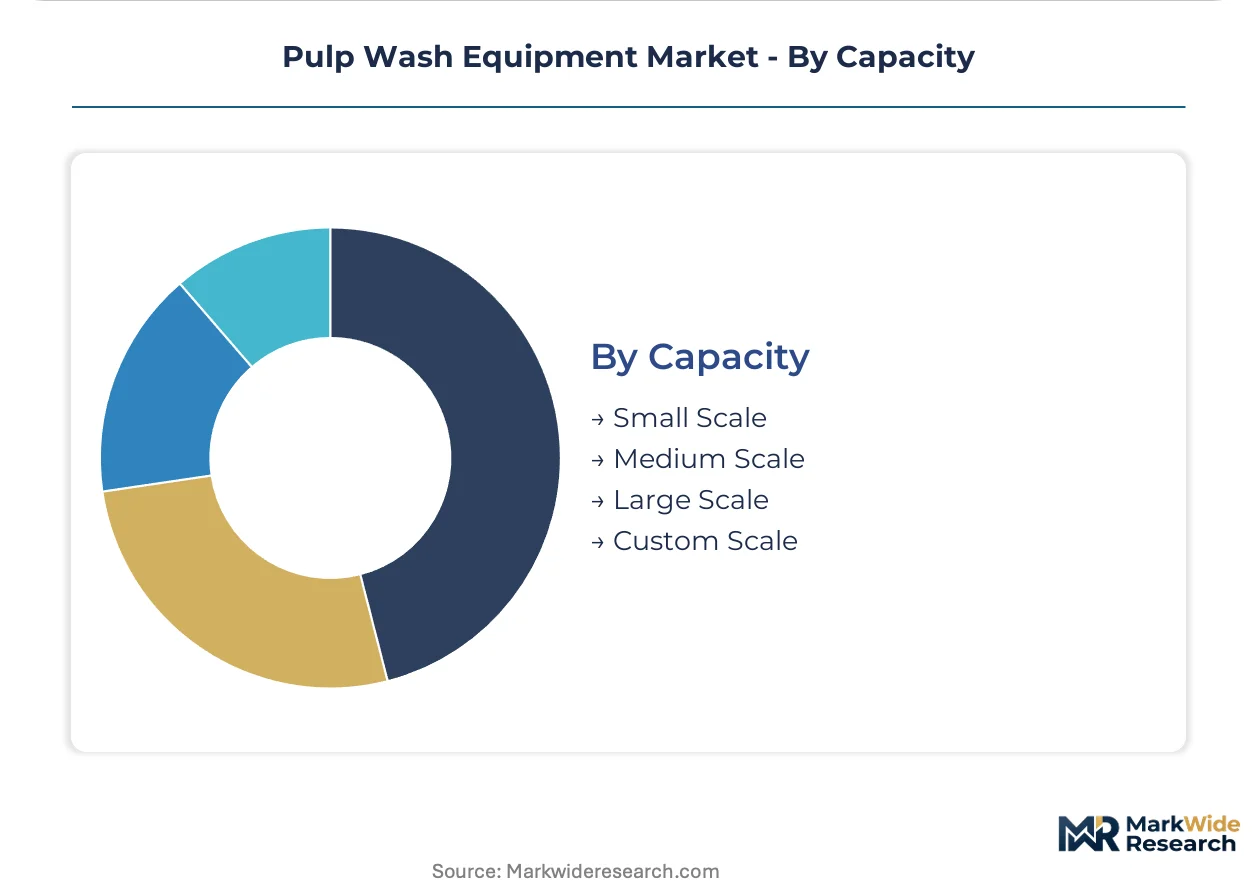
- Large Scale:Systems above 1,000 tonnes per day dominate greenfield kraft investments.
- Custom Scale:Engineered configurations serve dissolving wood pulp, flax, and hemp niches where batch flexibility outweighs throughput optimization. European specialty fiber producers are specifying modular washer skids that reconfigure between hardwood, softwood, and agricultural residue slurries without full line shutdowns.
- Small Scale:Pilot and demonstration lines support process development and niche product trials.
- Medium Scale:Mid-range units serve regional packaging paper producers balancing capital constraints against quality targets.
Large scale systems command the installed base; custom scale configurations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's eucalyptus pulp corridor commands capital deployment intensity unmatched by European retrofit cycles, while China's Yangtze River basin mandates are compressing equipment replacement timelines faster than North American regulatory pacing.
United States
Integrated pulp-to-paper groups in the Southeast and Pacific Northwest are modernizing kraft lines to meet EPA Best Available Technology standards for biological oxygen demand. The agency's effluent limitation guidelines directly shape washer specifications and caustic recovery design across Wisconsin and Georgia mill clusters. Packaging paper producers in the Great Lakes region absorb extended engineering validation timelines stretching eighteen to twenty-four months for closed-loop system retrofits.
China
MIIT water-efficiency mandates and MEE COD discharge limits on the Yangtze River basin are forcing replacement of atmospheric vacuum washer lines. Mills in Hubei and Jiangsu provinces deploy pressurized displacement systems that recirculate filtrate through multi-stage countercurrent washing. The packaging paper segment bears the steepest compliance cost burden as integrated producers absorb stretched engineering timelines.
Brazil
Arauco and Suzano are scaling kraft line capacity in the eucalyptus corridor, driving greenfield washer installations for bleached hardwood pulp output exceeding 1,500 air-dried metric tonnes per day. ANVISA biocide registration requirements intersect with ECHA REACH-aligned import standards, redirecting formulation choices toward enzyme-based wash aids. São Paulo state anchors procurement consolidation through multi-mill framework agreements that displace spot purchasing.
Germany
Nordic tissue producers pilot plug-and-play enzyme dosing skids between existing vacuum drum stages, cutting chlorine dioxide demand while meeting ECHA REACH restrictions on formaldehyde-based biocides. The KBA environmental compliance framework shapes equipment validation protocols for cross-border pulp equipment certification. Baden-Württemberg engineering clusters specialize in dilution control system commissioning for consistency measurement precision.
Sweden
Valmet leverages its fiberline automation portfolio to anchor long-term service contracts across Nordic mill upgrades, bundling pressure screens with distributed control system integration. The Swedish Chemicals Agency enforces REACH-aligned substance restrictions that redirect wash aid formulation demand. Stockholm-region engineering centers concentrate process control talent for pulp consistency measurement systems that outpace training pipeline output elsewhere.
Pulp Wash Equipment Market Vendor Landscape
Nordic producers anchor the automation-integrated tier; Chinese fabricators hold the cost-optimized mid-market segment. The supplier base concentrates around high-tonnage continuous washer systems for greenfield kraft mills, with specialized fabricators serving batch flexibility niches. Two strategic archetypes dominate: full-fiberline integrators bundling wash stages with chemical recovery loops, and component specialists extending washer run-time through doctoring and filtration accessories. Competitive moves center on framework agreement consolidation and enzymatic pretreatment technology licensing.
Within the full-line integration tier, Valmet and ANDRITZ represent contrasting geographic anchoring strategies, with the former concentrating Nordic and South American service contract penetration and the latter competing through chemical recovery bundling. Kadant Inc. occupies the component specialist position, exemplifying the filtration accessory archetype that extends maintenance intervals. Among China-based fabricators, Leizhan and Wenrui sit within the cost-optimized equipment segment serving regional packaging paper retrofit demand.
| Leading Market Players |
|---|
| Valmet |
| ANDRITZ |
| Kadant Inc. |
| GL&V |
| Leizhan |
| Wenrui |
| Zhengzhou Guangmao Machinery Manufacture Co. Ltd |
| Shandong Hantong Aote Machinery Co. Ltd |
| China National Building Material International Equipment Co. Ltd |
| Others |
Supply Flow & Price Mechanics
China's MEE Yangtze River basin COD discharge mandates gate qualified supply for closed-loop pressure washer systems and anchor premium-tier pricing access for fabricators with validated water-recirculation engineering. Equipment procurement from certified suppliers commands pricing power as mills absorb extended validation timelines for compliance-bound retrofits.
Pricing Analysis
Capacity additions in Brazil's eucalyptus corridor are reshaping price floors for high-tonnage continuous washer systems. Three-tier pricing structure across premium, standard, and economy levels separates fiberline-integrated automation bundles from component-only supply. Cost compression in standard-tier vacuum drum retrofits is intensifying because Chinese fabricators are scaling cost-optimized output for regional packaging paper demand. Integrated pulp-to-paper groups exhibit lowest price sensitivity; specialty flax and hemp producers face acute budget constraints.
Supply Chain Analysis
Process control engineering talent scarcity in Baden-Württemberg and Stockholm-region clusters is constraining commissioning capacity for dilution control systems. Fabrication draws from Finland, Sweden, and Germany for high-specification pressure screens; stainless steel inputs hinge on nickel and chromium supply volatility from Indonesian and Russian sources. Single-source vulnerability concentrates in specialized vacuum drum casting capacity. Distribution runs through mill-direct framework agreements anchored by multi-year service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as enzymatic pretreatment specifications displace commodity chemical wash configurations across bleached pulp corridors.
For Market Incumbents: Deepen fiberline automation bundling to lock in service contract renewals before Chinese fabricators close the cost gap on mid-range pressure systems. Threat from enzyme-dosing skid modularization demands accelerated R&D in plug-and-play biological upgrade architectures. Priority lever rests on vertical integration of dilution control commissioning talent pools. For New Entrants and Emerging Players: Digital-channel routes through remote diagnostics platforms offer white-space entry into legacy DCS integration friction. Target specialty pulp niches in European flax and hemp where batch flexibility requirements outstrip incumbent attention. Go-to-market angle centers on configurable subsystems enabling fiber changeover without line shutdowns. For Investors and Strategic Acquirers: Roll-up economics work for component specialists with filtration accessory portfolios because maintenance-interval extension commands recurring revenue streams. Long-term viability frames around enzymatic wash aid formulation licensing rather than equipment-only plays. Signal to watch: ANVISA biocide registration alignment with ECHA REACH standards redirecting formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme Dosing Skid Modularization | Plug-and-play biological upgrades reduce chlorine dioxide demand for Nordic tissue producers. |
| Closed-Loop Pressure System Retrofit | Yangtze River basin mills replace vacuum washers to meet MEE COD discharge limits. |
| Framework Agreement Consolidation | Arauco and Suzano bundle multi-mill procurement displacing spot purchasing in São Paulo. |
| Dilution Control Talent Acquisition | Process control engineering scarcity in Stockholm-region clusters constrains commissioning capacity. |
| Service Contract Anchoring | Valmet leverages fiberline automation portfolios to secure multi-year Nordic mill upgrades. |
Methodological Framework
Coverage spans Brazil's eucalyptus corridor, China's Yangtze River basin, Nordic kraft mill clusters, and US Southeast integrated pulp-to-paper groups, with primary inputs from each. Interviews with fiberline engineering directors, pulp mill maintenance heads, OEM procurement teams, and aftermarket service managers combined with trade flow data from pulp and paper industry associations, customs records for stainless steel equipment imports, and SEC filings from publicly traded suppliers. Bottom-up equipment shipment tallies triangulated against top-down capital expenditure estimates from mill expansion announcements.
Granularity-level modeling tracked continuous versus batch washer architectures, biological versus chemical wash technology splits, and custom-scale versus large-scale capacity tiers across the projection horizon. CAGRs derived from installed base replacement cycles, greenfield capacity timelines, and regulatory compliance deadlines. Industry-specific inputs included EPA effluent limitation guideline enforcement pacing and MIIT water-efficiency mandate implementation schedules.
The model assumes a particular technology adoption path; alternative pathways for enzymatic pretreatment diffusion would alter the outlook. Forecasts reflect assumptions around stainless steel price stability and process control engineering training pipeline output. Material deviation in MEE discharge standard enforcement or nickel supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Global Dry Milling Market
Agricultural Processing Equipment
Solar Herbs Dryer Market
Agricultural Processing Equipment
Dal Mill Machine Market
Agricultural Processing Equipment
Global Nut Processing Equipment Market
Agricultural Processing Equipment
Hemp Processing Equipment Market
Agricultural Processing Equipment
Harvesting Machinery Market
Agricultural Processing Equipment
Defeathering Machine Market
Agricultural Processing Equipment
Meat and Poultry Processing Equipment Market
Agricultural Processing Equipment
Corn Thresher Market
Agricultural Processing Equipment
Seed Processing Equipment Market
Agricultural Processing Equipment
Manure Handling Equipment Market
Agricultural Processing Equipment
Harvesters Market
Agricultural Processing Equipment
North America Feed Pelletizing Agent Market
Agricultural Processing Equipment
Maize Milling Machine Market
Agricultural Processing Equipment
Japan Agricultural Shredder Machine Market
Agricultural Processing Equipment
Global Agricultural Harvesting Machinery Market