
 Remote Renewable Management Systems Market | 2026-2036
Remote Renewable Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Renewable Management Systems Market Outlook
EU Green Deal compliance is hardening the cost-of-entry calculus for new entrants seeking to serve European renewable operators. Siemens leverages its digital grid software stack to anchor utility-scale deployments across multiple continents. Schneider Electric competes through integrated edge-to-cloud architectures that span solar and storage assets. ABB differentiates with hardened automation protocols purpose-built for hydroelectric telemetry in remote terrain.
Remote Renewable Management Systems denote software-hardware platforms that aggregate telemetry from geographically dispersed generation assets—typically ingesting SCADA streams, meteorological feeds, and inverter data at sub-second intervals—to dispatch commands that stabilize output and extend equipment life. Their primary purpose is to replace on-site technical crews with centralized control rooms capable of managing thousands of distributed units. Solar Management and Energy Storage command the largest current revenue pools as photovoltaic plus battery configurations dominate new capacity additions. AI Integration represents the fastest-expanding technology segment, with algorithms now predicting inverter failures before thermal thresholds trigger shutdowns. Cloud Computing deployments are maturing fastest among utilities with established fiber backbones, while Edge Computing gains traction where latency constraints rule out round-trip data center routing.
FERC Order 2222 in the United States compels grid operators to accommodate aggregated distributed energy resources, directly expanding the addressable base for management platforms. The EU AI Act imposes risk-classification requirements on automated dispatch algorithms, adding compliance layers that favor established vendors with dedicated regulatory teams. ISO 27001 certification has become a de facto gate for utility procurement tenders across multiple jurisdictions. Stakeholders must weigh whether to build proprietary AI stacks or absorb third-party models whose transparency documentation may not satisfy emerging algorithmic accountability rules.
Market Dynamics
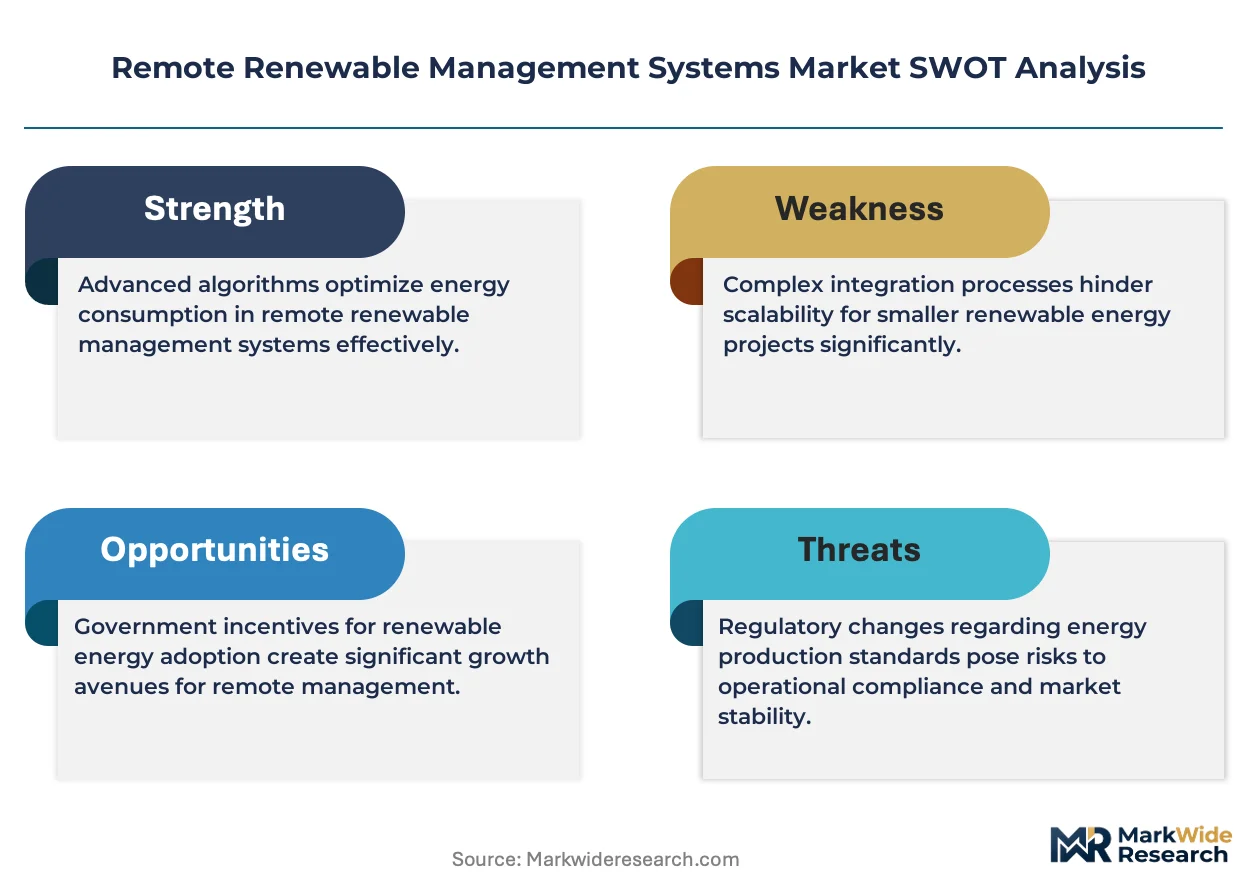
Grid decentralization is fragmenting generation assets across thousands of distributed nodes, forcing management platforms to ingest telemetry from heterogenous equipment stacks rather than centralized plant architectures.
Growth Catalysts
- FERC Order 2222:This US mandate compels regional transmission organizations to clear aggregated distributed energy resources into wholesale markets, expanding the addressable base for remote management software.
- AI Integration:Predictive algorithms now forecast inverter thermal failures before shutdown thresholds trigger, extending equipment life and reducing truck rolls to remote solar farms.
- Factory-linked microgrids:Germany's industrial corridor is concentrating demand for unified management layers that coordinate solar generation with battery storage and load scheduling.
Market Restraints
- EU AI Act compliance costs:Risk-classification requirements for automated dispatch algorithms add regulatory layers that favor established vendors with dedicated compliance teams.
- Fiber backbone dependency:Cloud computing deployments mature fastest where utilities own established fiber networks, leaving rural operators with higher latency constraints.
- Silicon supply concentration:Inverter manufacturing relies on concentrated semiconductor foundry capacity, exposing management system deployments to upstream component volatility.
Strategic Opportunities
- Edge Computing convergence:Latency-sensitive hydroelectric telemetry in remote terrain is driving adoption of hardened automation protocols that process data locally before cloud synchronization.
- EU Green Deal interoperability mandates:Cross-border renewable flow requirements create specification gaps that new entrants can fill with compliance-first platform architectures.
- India's CEA grid codes:Evolving standards for distributed solar integration present white space for management vendors offering localized SCADA aggregation.
Industry Challenges
- ISO 27001 certification timelines:Utility procurement tenders across multiple jurisdictions now require this security standard as a de facto gate, extending sales cycles for uncertified vendors.
- SCADA-to-cloud integration complexity:Legacy plant control systems use proprietary protocols that resist standard API extraction, forcing expensive middleware development.
- Algorithmic transparency documentation:Emerging accountability rules for automated dispatch decisions demand audit trails that third-party AI models often lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Renewable Management Systems Market |
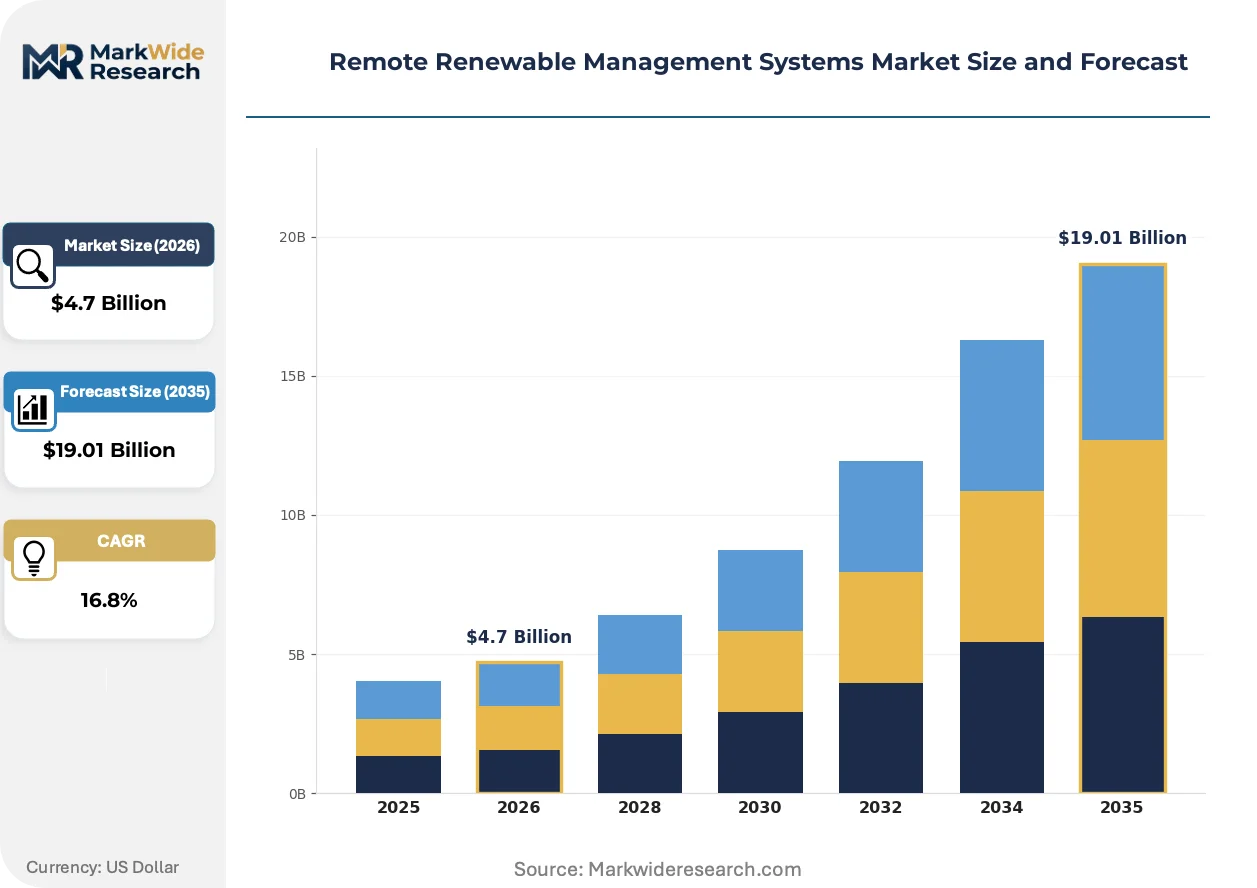
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $19.01 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Management, Wind Management, Hydro Management, Energy Storage End User: Utilities, Industrial Facilities, Commercial Enterprises, Residential Users Technology: IoT Solutions, Data Analytics, Cloud Computing, AI Integration Deployment Model: On-premise, Cloud-based, Hybrid, Edge Computing |
| Companies Covered | Siemens, ABB, General Electric, Transition Technologies MS, Enbridge Inc., Hitachi Ltd., Schneider Electric, SolarEdge, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Renewable Management Systems Market Strategic Shifts
Telemetry ingestion architectures are bifurcating between sub-second edge processing for critical stability commands and batch cloud analytics for predictive maintenance, reshaping how vendors partition their software stacks.
Digital twin technology is modularizing renewable asset management by creating virtual replicas of physical inverters, transformers, and meteorological sensors. Utilities with hybrid solar-storage portfolios are deploying these twins to simulate dispatch scenarios before executing commands. This approach is modularizing what were previously monolithic control platforms into composable microservices.
The EU AI Act's risk-classification framework is segmenting automated dispatch algorithms into tiers requiring escalating documentation. High-risk classification for grid-stabilizing commands now mandates human-in-the-loop overrides and algorithmic impact assessments. European renewable operators are responding by bifurcating procurement between established vendors with regulatory teams and newer entrants lacking compliance infrastructure.
Buyer contracting patterns are compressing from perpetual licenses toward subscription models tied to managed megawatt capacity. Independent power producers in deregulated US markets are leading this shift, unbundling software from hardware procurement to align costs with operational cash flows. This rotation is most visible in Texas and California, where merchant solar developers prioritize operational expenditure structures over capital-intensive ownership models.
Remote Renewable Management Systems Market Segmentation
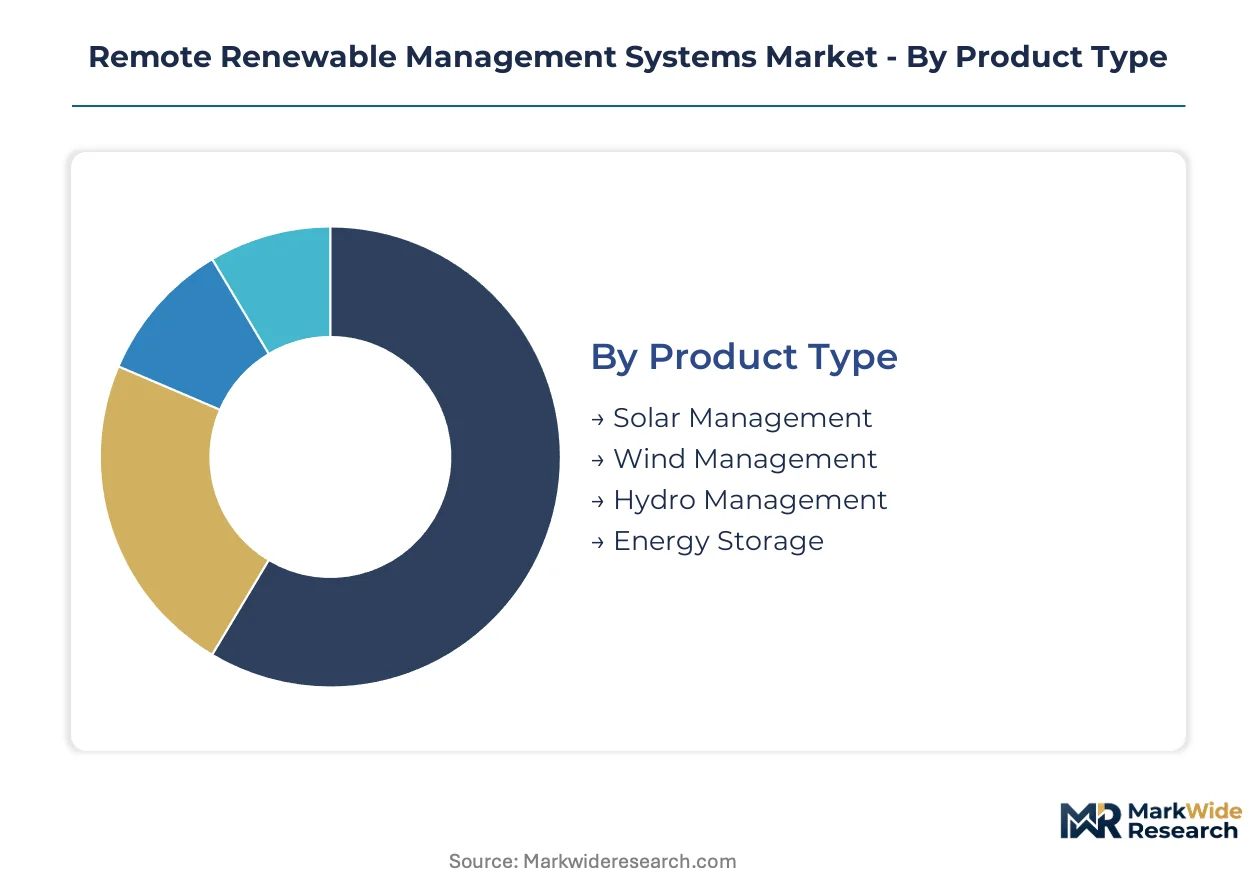
Remote renewable management systems fragment across four distinct dimensions that shape procurement priorities and vendor positioning. Product type segmentation reflects the underlying generation technology being monitored, while deployment model choices determine latency performance and capital structure. Technology and end-user splits reveal where AI capabilities and regulatory compliance create differentiation.
Product Type:
Volume concentration favors solar and storage combinations, while hydro commands premium pricing due to terrain complexity and telemetry hardening requirements.
- Solar Management:Platforms ingest sub-second inverter data streams and meteorological feeds to dispatch curtailment commands during grid instability. Demand concentrates in Germany's industrial corridor where factory-linked microgrids require unified coordination layers for photovoltaic plus battery configurations.
- Energy Storage:Battery management systems orchestrate charge-discharge cycles against wholesale price signals and grid frequency deviations. Procurement is accelerating among Texas and California merchant solar developers prioritizing operational expenditure structures over capital-intensive ownership models.
- Wind Management:Turbine control platforms aggregate nacelle telemetry, pitch angle data, and wake effect measurements across offshore and onshore arrays.
- Hydro Management:Hardened automation protocols process telemetry from remote terrain installations where fiber backbones remain absent.
Mature deployment sits with Solar Management. Newer deployment is concentrated in Energy Storage.
End User:
Procurement authority splits between regulated utilities with fiber infrastructure and independent producers seeking managed service contracts.
- Utilities:Grid operators deploy enterprise-scale platforms managing thousands of distributed assets through centralized control rooms. North American utilities expanding remote monitoring procurement drive volume as FERC Order 2222 compels accommodation of aggregated distributed energy resources into wholesale markets.
- Industrial Facilities:Factory-linked microgrids in manufacturing corridors coordinate on-site generation with production schedules and demand response programs. Germany's Ruhr and Bavarian industrial clusters exhibit the steepest expansion trajectory for unified management layers.
- Commercial Enterprises:Corporate offtakers with renewable energy certificates to manage deploy lighter platforms focused on bill optimization and sustainability reporting.
- Residential Users:Aggregated home battery and rooftop solar installations feed into virtual power plant architectures managed by third-party operators.
Established procurement sits with Utilities. Emerging procurement is concentrated in Industrial Facilities.
Technology:
Capability layering separates commodity connectivity from predictive intelligence, with AI commanding implementation premiums.
- AI Integration:Machine learning algorithms forecast inverter thermal failures before shutdown thresholds trigger, extending equipment life and reducing truck rolls. EU AI Act risk-classification requirements favor established vendors with dedicated compliance teams and algorithmic impact assessment capabilities.
- Cloud Computing:Centralized data lakes enable cross-fleet analytics and model training at scale. Maturity concentrates among utilities with established fiber backbones, leaving rural operators constrained by latency.
- IoT Solutions:Sensor networks and gateway hardware provide foundational telemetry ingestion from geographically dispersed assets.
- Data Analytics:Descriptive dashboards and reporting tools support operational visibility without predictive capabilities.
Proven implementation sits with Cloud Computing. Accelerating implementation is concentrated in AI Integration.
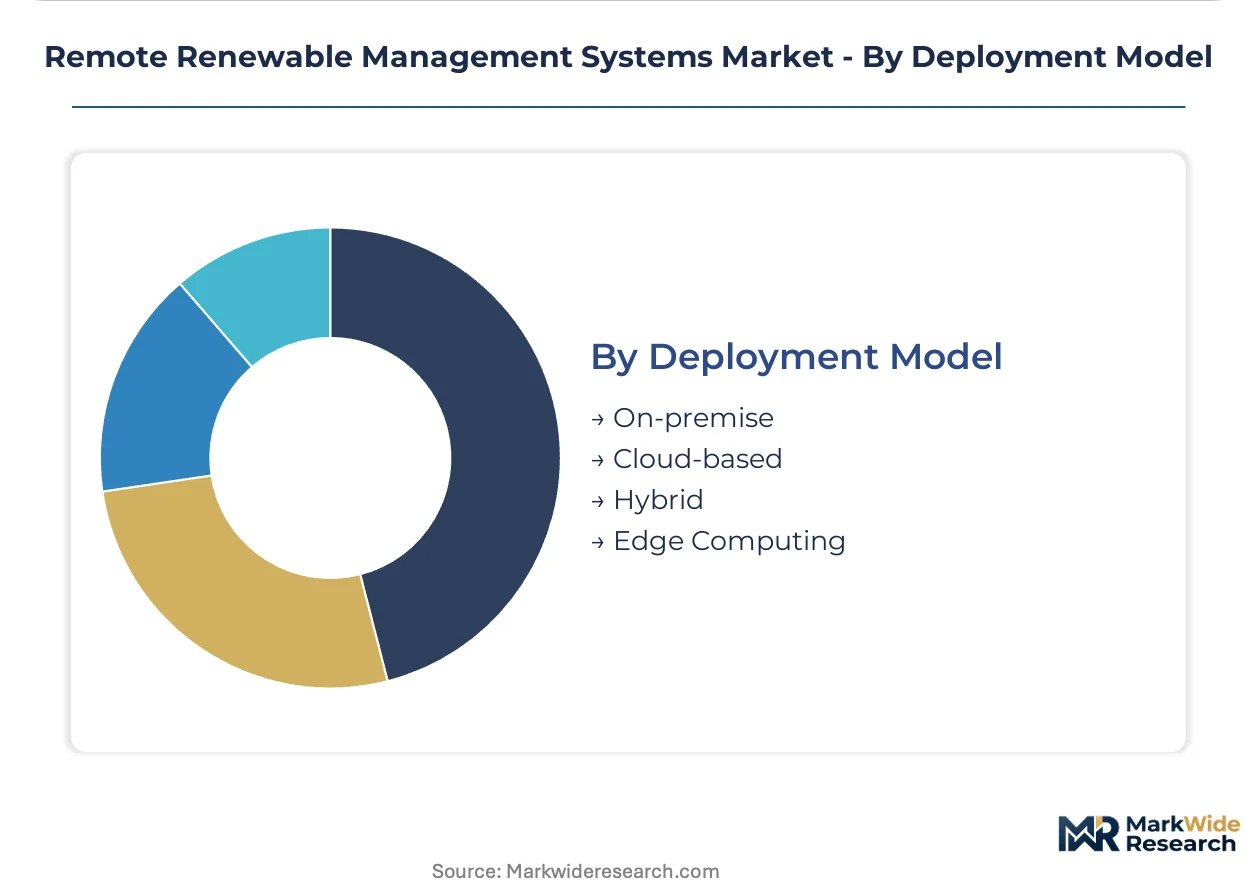
Deployment Model:
Latency requirements and connectivity availability drive partitioning between edge-local processing and centralized analytics.
- Edge Computing:Hardened automation protocols process critical stability commands locally before cloud synchronization, eliminating round-trip data center latency. Adoption concentrates in remote hydroelectric terrain where fiber infrastructure remains absent and millisecond response times prove essential.
- Hybrid:Architectures bifurcate processing between sub-second edge commands and batch cloud analytics for predictive maintenance, reshaping vendor software stack partitioning.
- Cloud-based:Fully centralized deployments mature fastest where utilities own established fiber networks and latency constraints remain permissive.
- On-premise:Air-gapped installations persist in security-critical environments requiring ISO 27001 certification as a procurement gate.
Early adoption sits with On-premise. Expanding adoption is concentrated in Hybrid configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's renewable energy parks under the Solar Parks Scheme concentrate procurement for centralized management platforms. Brazil's distributed generation regulatory framework accelerates microgrid deployments across industrial zones. China's dual carbon policy mandates drive telemetry standardization for provincial grid operators.
United States
FERC Order 2222 compels regional transmission organizations to clear aggregated distributed energy resources into wholesale markets. The Inflation Reduction Act extends tax credits for standalone battery storage installations. Texas and California merchant solar developers prioritize operational expenditure structures over capital-intensive ownership models.
Germany
The EU Green Deal tightens interoperability mandates for cross-border renewable flows. The EU AI Act imposes risk-classification requirements on automated dispatch algorithms. Factory-linked microgrids in the Ruhr and Bavarian industrial clusters concentrate demand for unified management layers coordinating solar generation with battery storage.
India
The Central Electricity Authority evolves grid codes for distributed solar integration. The PLI scheme incentivizes domestic manufacturing of solar modules and battery cells. Gujarat and Rajasthan renewable energy parks deploy SCADA aggregation platforms managing thousands of geographically dispersed photovoltaic units.
Brazil
ANESEL regulates distributed generation net metering for commercial and industrial consumers. The national biofuels policy extends to hybrid renewable configurations requiring unified telemetry. São Paulo state industrial zones deploy microgrid management systems coordinating on-site solar with grid backup.
China
MIIT issues standards for industrial internet platforms connecting distributed energy assets. Provincial grid operators under State Grid Corporation mandate telemetry standardization for renewable integration. The Yangtze River Delta manufacturing corridor concentrates deployments of edge computing protocols for latency-sensitive dispatch commands.
Remote Renewable Management Systems Market Competitive Environment
German producers anchor one tier; US specialists hold differentiated positions in utility-scale software stacks. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates with digital grid portfolios, pure-play renewable software vendors, and automation specialists with hardened telemetry protocols. Competitive moves center on M&A for AI capabilities and strategic partnerships for cloud infrastructure access.
Within the diversified industrial tier, Siemens and ABB exemplify archetypes leveraging established regulatory compliance teams to navigate EU AI Act requirements. Schneider Electric occupies a position bridging edge-to-cloud architectures. These three European-headquartered entities represent the established vendor cohort favored by utility procurement tenders requiring ISO 27001 certification as a de facto gate.
| Leading Market Players |
|---|
| Siemens |
| ABB |
| General Electric |
| Transition Technologies MS |
| Enbridge Inc. |
| Hitachi Ltd. |
| Schneider Electric |
| SolarEdge |
| Honeywell International Inc. |
| Others |
Value Chain & Pricing Dynamics
Utility procurement officers with fiber infrastructure anchor pricing power in this market, commanding subscription-based SaaS tiers that bundle predictive maintenance with managed megawatt capacity. Their concentration in North America and Germany compresses margins for vendors lacking ISO 27001 certification, while rural operators with latency constraints absorb premium edge-computing deployments.
Pricing Analysis
Short lead-time premiums dominate vendor quotations, with utilities requiring sub-90-day deployment windows paying 15-25% above baseline subscription rates. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled predictive platforms from basic SCADA aggregation and open-source telemetry tools. Pricing pressure stems from independent power producers in Texas and California prioritizing operational expenditure structures over capital-intensive perpetual licenses. Merchant solar developers exhibit the highest price sensitivity, while German industrial facilities with factory-linked microgrids absorb premium coordination layers without significant negotiation.
Supply Chain Analysis
Semiconductor foundry capacity in Taiwan, South Korea, and China anchors inverter manufacturing, exposing management system deployments to upstream component volatility. Hardened automation protocols for hydroelectric telemetry draw from German industrial automation specialists and Japanese precision sensor producers. Single-source vulnerability concentrates in AI accelerator chips for edge-computing nodes, where NVIDIA and Qualcomm architectures dominate renewable-specific workloads. Distribution runs through systems integrators with utility relationships rather than direct vendor-to-operator channels, extending sales cycles but reducing customer acquisition costs for platform providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized AI engineering talent scarcity props pricing for algorithmic compliance capabilities, constraining vendor capacity expansion and sustaining margin premiums for established players with dedicated regulatory teams.
For Market Incumbents: Deploy certification-first platform architectures to capture EU Green Deal interoperability mandates before compliance costs harden further. Siemens and Schneider Electric should deepen backward integration into edge-computing hardware to reduce dependency on third-party NVIDIA accelerators. ABB must anchor hydroelectric telemetry positions against cloud-native entrants lacking hardened automation protocols for remote terrain. For New Entrants and Emerging Players: Rural utilities with satellite backhaul represent the most penetrable buyer archetype, as latency constraints exclude established cloud-centric vendors from these deployments. India's evolving CEA grid codes present white space for SCADA aggregation specialists offering localized compliance documentation. A partnership-first go-to-market angle with regional systems integrators bypasses direct certification timelines while building utility reference accounts. For Investors and Strategic Acquirers: The window for entry favors pure-play AI vendors with algorithmic impact assessment capabilities ahead of EU AI Act enforcement expansion. Long-term viability centers on acquisition targets bridging edge-to-cloud architectures rather than single-stack specialists. Watch FERC Order 2222 implementation velocity across regional transmission organizations as the signal indicating wholesale market access expansion for aggregated distributed energy resources.| Strategic Initiative | Industry Significance |
|---|---|
| AI Compliance Infrastructure Buildout | EU AI Act risk-classification mandates require dedicated algorithmic audit teams for grid-stabilizing commands. |
| Edge Computing Hardware Integration | Hardened automation protocols for remote hydroelectric terrain reduce round-trip latency below millisecond thresholds. |
| Subscription Model Transition | Texas and California merchant solar developers prioritize operational expenditure alignment with operational cash flows. |
| Cross-Border Interoperability Certification | EU Green Deal specifications for renewable flow coordination create procurement gates favoring pre-certified vendors. |
| Utility-Scale Systems Integrator Partnership | North American fiber-backbone utilities consolidate procurement through established channel relationships with grid operators. |
Study Parameters
Multi-period observation of inverter failure prediction accuracy and SCADA-to-cloud integration deployment timelines anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation drew from FERC filings, EIA distributed generation databases, IEA renewable integration reports, and EU AI Act implementation guidance. Bottom-up capacity installation tracking across Germany's industrial corridor and Texas merchant solar developments triangulated against top-down vendor revenue segmentation.
Segment-weighting across the projection horizon applied differential growth assumptions to AI Integration versus Cloud Computing deployment models, with hydroelectric edge-computing protocols modeled separately from fiber-backbone utility installations. CAGRs derived from capacity expansion pipelines, regulatory mandate implementation schedules, and technology substitution curves for predictive maintenance algorithms. Forecast inputs incorporated silicon supply concentration volatility and EU AI Act compliance timeline uncertainty.
Revisions become necessary when semiconductor foundry capacity allocations shift, FERC Order 2222 implementation stalls at regional transmission organizations, or EU AI Act enforcement priorities redirect toward lower-risk algorithm classifications. Forecasts reflect assumptions about fiber infrastructure buildout velocity and satellite backhaul cost trajectories for remote terrain deployments. A small set of named triggers—tariff exposure on Chinese inverters, NVIDIA accelerator chip availability, and CEA grid code finalization in India—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Asia-Pacific Exhaust Heat Recovery System Market
Energy Management
Microgrid Control System Market
Energy Management
Electric Service Companies (Escos) Market
Energy Management
Middle East and Africa Energy Management Systems Market
Energy Management
Smart Power Management Market
Energy Management
Thermostat Market
Energy Management
Power SCADA Market
Energy Management
Heat Meter Market
Energy Management
Industrial Demand Response Management Systems Market
Energy Management
Australia Energy-As-A-Service Market
Energy Management
Smart Energy Solutions Market
Energy Management
European Building Energy Management Systems Market
Energy Management
Demand Response Management System Market
Energy Management
Global Utility Asset Management Market
Energy Management
South Korea Residential Heat Pump Market
Energy Management
Europe Energy Management Systems Market