
 Greenhouse Kit Market | 2026-2036
Greenhouse Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Greenhouse Kit Market Analytics
Capital-intensity divergence between mass-market assemblers and engineered-system suppliers is bifurcating the competitive landscape. Palram/Canopia leverages its vertically integrated polycarbonate extrusion to control material cost and delivery timelines for frame-kit buyers. BC Greenhouses anchors its position through custom-engineered glass structures for commercial growers in temperate climates. Exaco (Riga Greenhouses) differentiates via heavy-duty Nordic-rated insulation systems that sustain premium pricing in northern latitudes.
A greenhouse kit constitutes a prefabricated enclosure system combining structural framing, transparent cladding, and climate-control interfaces designed to regulate temperature, humidity, and light transmission for plant cultivation. Polycarbonate-panel kits dominate volume shipments due to impact resistance and diffused-light performance, while glass configurations command margin pools among research facilities requiring optical clarity. Hydroponic-integrated kits represent the fastest-expanding product type as soilless cultivation protocols displace traditional substrate methods in commercial operations. Educational institutions increasingly specify modular DIY installations that accommodate curriculum rotation without permanent foundation work.
EPA agricultural runoff guidelines and OSHA workplace-safety standards shape enclosure specifications and ventilation mandates for commercial installations in the United States. The EU Green Deal and national building codes in Germany and France impose energy-efficiency thresholds on permanent greenhouse structures, filtering market access for non-compliant imports. Stakeholders must monitor evolving municipal zoning for accessory agricultural structures, as local land-use decisions increasingly determine addressable market scope for residential and small-commercial kit suppliers.
Market Dynamics
Climate volatility is compressing outdoor growing windows and forcing commercial operators toward controlled-environment systems that buffer yield against weather shocks. This structural pressure is redirecting capital from open-field infrastructure into enclosed horticulture at an accelerating pace.
Growth Catalysts
- EU Green Deal Farm to Fork:Chemical-use reduction mandates are redirecting investment toward soilless cultivation protocols that minimize pesticide dependency.
- Urban farming ordinances:Municipal zoning reforms in the United States are legalizing accessory agricultural structures on residential and light-commercial parcels.
- Polycarbonate extrusion scale:Captive polymer supply chains are compressing material costs and shortening delivery timelines for frame-kit assemblers.
Market Restraints
- Glass input cost volatility:Float glass prices swing with natural gas and soda ash markets, compressing margins for premium-cladding suppliers.
- Foundation permanence requirements:German and French building codes classify permanent greenhouse structures as taxable real property, raising capital-recovery hurdles.
- High-tunnel substitute threat:Unheated polyethylene tunnels capture price-sensitive volume in temperate zones with mild shoulder seasons.
Strategic Opportunities
- Educational modular DIY:Curriculum-rotation specifications from universities and K-12 districts are opening non-permanent installation demand.
- Hydroponic-integrated convergence:Nutrient-film technique and deep-water culture systems bundled with enclosure kits are displacing substrate-based protocols.
- OSHA ventilation mandates:Workplace-safety standards for commercial agricultural operations are mandating engineered airflow systems that favor kit suppliers with climate-control interfaces.
Industry Challenges
- Controlled-environment agriculture skill scarcity:Commercial operators lack personnel trained in integrated pest management and environmental setpoint optimization.
- Foundation-work capex intensity:Permanent structures require engineered footings and utility trenching that extend payback periods for mid-scale growers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greenhouse Kit Market |
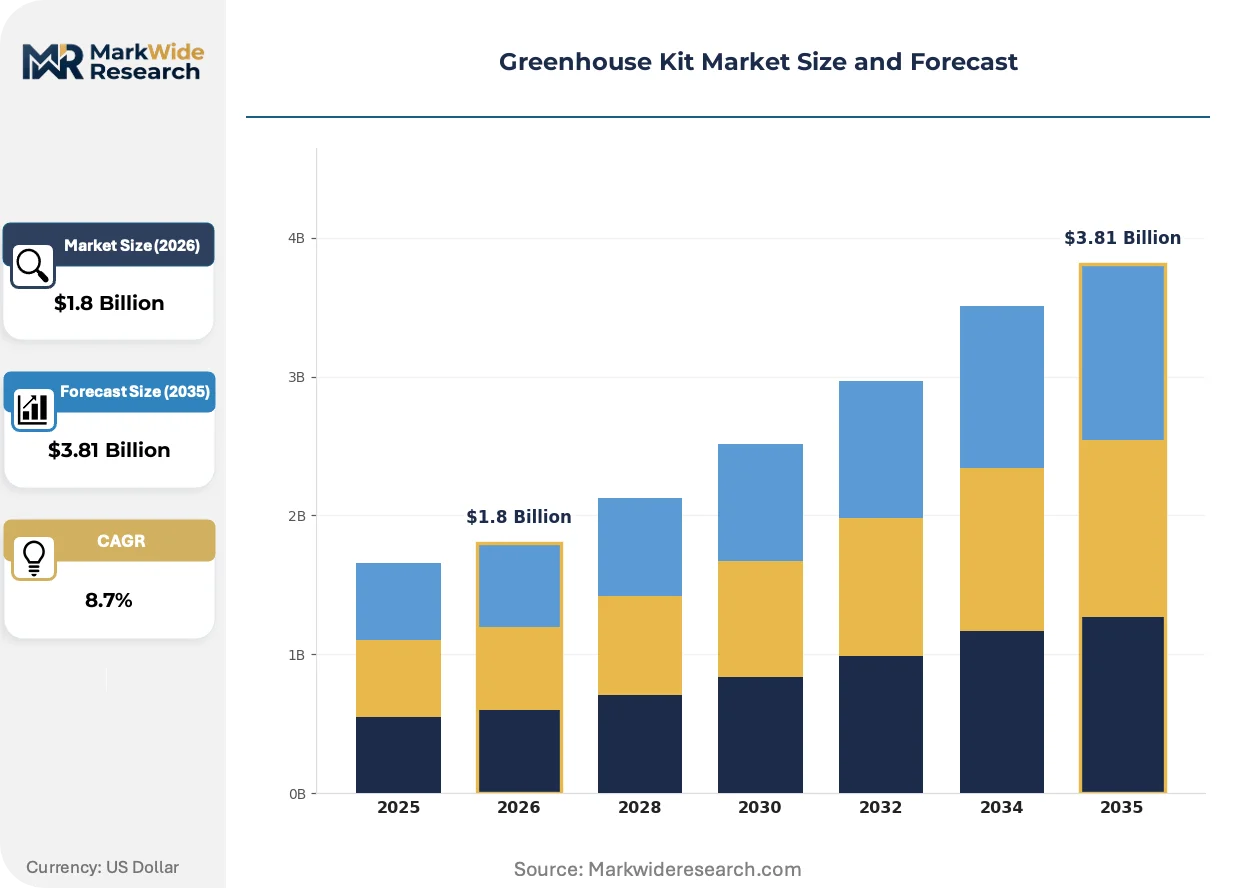
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Kits, Frame Kits, Hydroponic Kits, High Tunnel Kits Material: Polycarbonate, Glass, PVC, Aluminum End User: Home Gardeners, Commercial Growers, Educational Institutions, Research Facilities Installation: DIY, Professional Setup, Modular, Detached |
| Companies Covered | Planta Greenhouses, BC Greenhouses, Grandio Greenhouses, Gothic Arch Greenhouses, Yoderbilt Greenhouses, Changzhou Growell Garden Products, Exaco (Riga Greenhouses), Atlas Manufacturing, Palram/Canopia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greenhouse Kit Market Evolving Landscape
Automation and sensor integration are redefining what buyers expect from enclosure systems, shifting competitive advantage from material durability toward data-driven climate management. Suppliers must now bundle hardware with environmental control logic to maintain relevance.
Diffused-light polycarbonate paneling is bifurcating the commercial grower segment from research-facility buyers. Commercial operators prioritize impact resistance and thermal insulation over optical clarity, accepting light-scattering properties that accelerate vegetative growth. Research institutions and breeding programs reject these panels, demanding glass configurations that preserve spectral accuracy for phenotyping work. This technical divide is forcing suppliers to maintain dual product architectures rather than converging on a single cladding standard.
EPA agricultural runoff guidelines are tightening enclosure specifications for commercial installations in the United States. The rules mandate impermeable flooring and contained irrigation drainage that prevent nutrient leaching into watersheds. Glasshouse operators in California and Florida are retrofitting capture systems or specifying new builds with integrated sump infrastructure. Compliance timelines are compressing procurement cycles as growers accelerate replacement schedules to avoid penalty exposure.
Direct-to-grower e-commerce channels are disintermediating traditional agricultural supply distributors for residential and small-commercial kit buyers. Amazon and specialty horticulture platforms now capture specification traffic that previously flowed through county extension offices and farm-supply cooperatives. This channel shift concentrates in the United States and Canada, where parcel logistics infrastructure supports flat-pack shipping of frame components. Distributors are responding with value-added services—site planning, permit navigation, installation crews—that resist pure-product commoditization.
Greenhouse Kit Market Segmentation
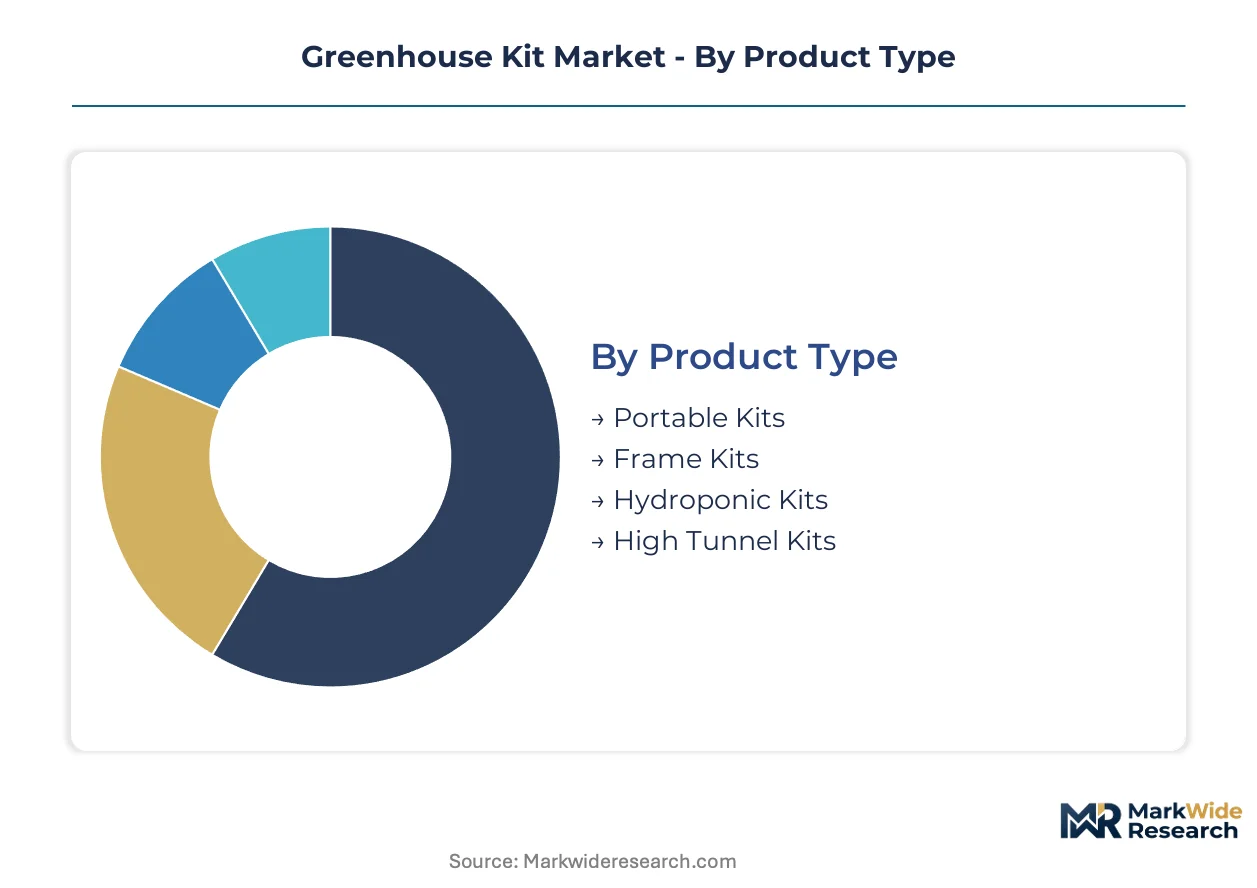
Greenhouse kit segmentation reflects divergent compliance burdens and capital-intensity thresholds across buyer categories. Regulatory frameworks from EPA, EU Green Deal, and municipal zoning codes filter product eligibility by installation permanence and material specification.
Product Type:
EPA agricultural runoff guidelines and EU energy-efficiency codes create divergent product eligibility by installation permanence and climate-control integration.
- Frame Kits:Structural assemblies combining metal or timber framing with polycarbonate or glass cladding dominate commercial procurement. Demand concentrates in the United States where mid-scale growers seek permanent foundations to satisfy USDA conservation program requirements and extend growing seasons against climate volatility.
- Hydroponic Kits:Enclosure systems bundled with nutrient-film technique or deep-water culture infrastructure eliminate soil substrate. Commercial operators in the Netherlands and Denmark deploy these configurations to meet EU Green Deal Farm to Fork chemical-reduction mandates while maximizing yield per square meter.
- Portable Kits:Lightweight collapsible structures target residential gardeners facing restrictive municipal accessory structure ordinances.
- High Tunnel Kits:Unheated polyethylene-covered hoops compete on price in temperate zones with mild shoulder seasons.
Established volume favors frame kits; emerging adoption favors hydroponic kits.
Material:
Cost tier stratification separates premium cladding from mass-market alternatives based on thermal performance and optical clarity requirements.
- Polycarbonate:Extruded twin-wall or multi-wall panels deliver impact resistance and diffused light transmission. Commercial growers in Germany prioritize these specifications to satisfy national building code energy-efficiency thresholds while reducing heating loads during winter production cycles.
- Glass:Tempered or laminated float configurations preserve spectral accuracy for phenotyping and controlled-environment research. Research facilities in Switzerland and Austria specify glass despite higher capital costs to maintain optical clarity for breeding program protocols.
- PVC:Resin-based framing and cladding targets price-sensitive residential segments with limited durability expectations.
- Aluminum:Extruded structural members provide corrosion resistance in high-humidity cultivation environments.
Margin concentration sits with glass; shipment volume concentrates in polycarbonate.
End User:
Application maturity separates institutional procurement cycles from residential impulse purchasing patterns.
- Commercial Growers:Professional horticulture operations demand engineered climate control and compliance documentation. Operators in Spain and Italy scale protected agriculture investments as drought frequency intensifies and open-field risk premiums expand.
- Educational Institutions:Universities and K-12 districts specify modular DIY installations accommodating curriculum rotation. Demand clusters in the United States where urban farming programs integrate greenhouse modules into STEM education mandates without triggering permanent building code classification.
- Home Gardeners:Residential consumers drive seasonal purchasing peaks through direct-to-consumer channels.
- Research Facilities:Agricultural universities and breeding programs require spectral precision and environmental setpoint repeatability.
Procurement stability favors commercial growers; specification flexibility favors educational institutions.
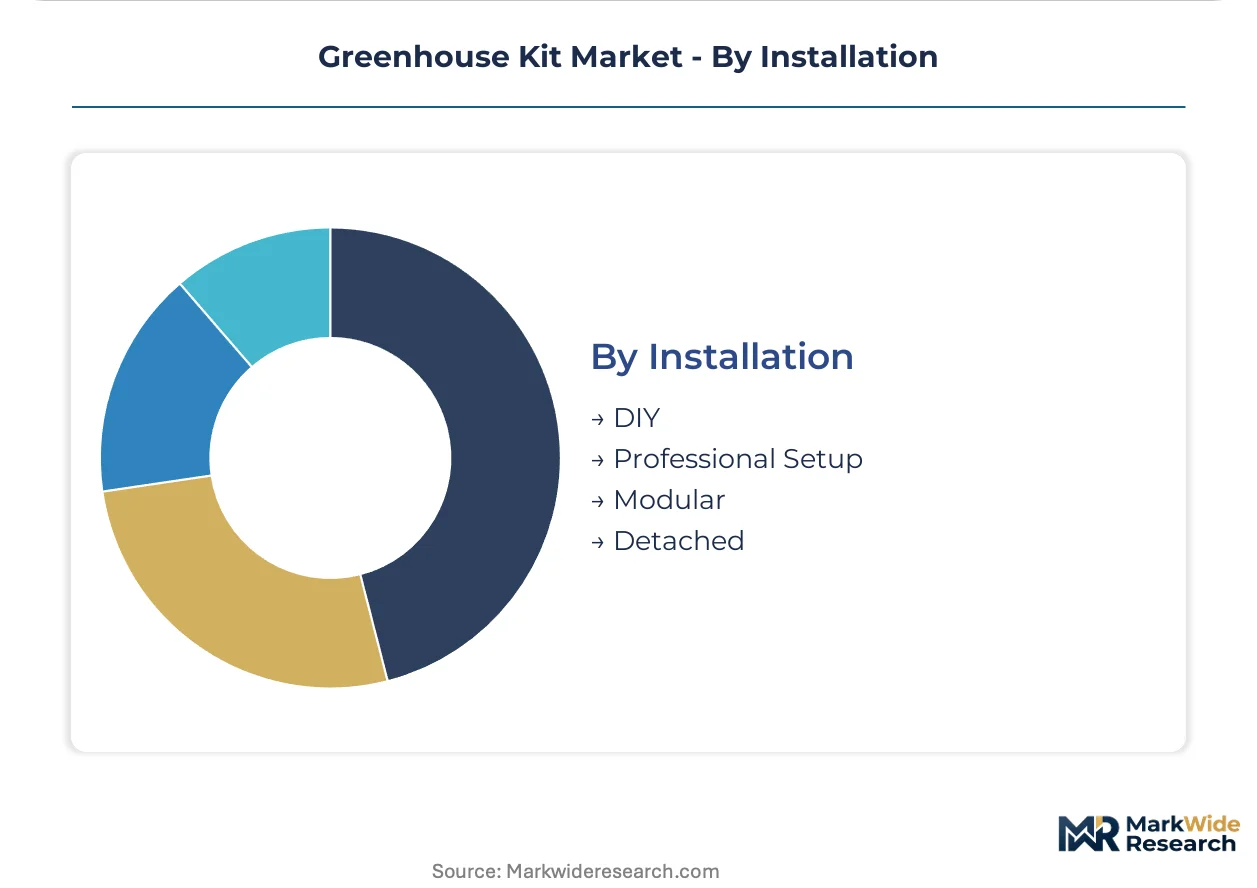
Installation:
Customer capability and capital availability determine foundation permanence and professional service attachment rates.
- DIY:Flat-pack assemblies with pre-cut components and instructional documentation target capable residential buyers. Adoption concentrates in Canada where parcel logistics infrastructure supports component shipping and municipal zoning permits accessory structures without engineered footing requirements.
- Professional Setup:Turnkey installation services including site preparation, foundation work, and utility trenching address commercial operators lacking construction expertise. French and German building codes classify permanent greenhouse structures as taxable real property, elevating the importance of professional compliance documentation.
- Modular:Reconfigurable panel systems allow dimension adjustment without structural demolition.
- Detached:Standalone structures separate from primary buildings satisfy fire code setback requirements.
Service revenue concentrates in professional setup; volume expansion favors DIY configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in greenhouse kit components track polycarbonate resin supply chains from Germany and China toward assembly points in North America and Northern Europe. Trade balances favor manufacturing economies with captive polymer extrusion capacity, while consumption gravity concentrates in jurisdictions with protective agricultural policy incentives and climate volatility premiums.
United States
Urban farming ordinances in cities like Denver and Minneapolis legalize accessory agricultural structures on residential parcels, expanding addressable demand for mid-scale kit installations. USDA conservation program requirements channel commercial growers toward permanent foundation specifications that qualify for federal cost-share assistance. The Great Lakes region anchors volume consumption as Michigan and Ohio growers scale protected agriculture to buffer against erratic spring frost patterns.
Germany
National building codes classify permanent greenhouse structures as taxable real property, elevating compliance documentation requirements for commercial operators. The EU Green Deal Farm to Fork strategy tightens chemical-use reduction targets, redirecting capital toward controlled-environment horticulture with integrated hydroponic protocols. Bavaria and North Rhine-Westphalia concentrate demand as regional agricultural banks extend preferential lending terms for energy-efficient enclosure investments.
Netherlands
Commercial operators deploy hydroponic-integrated kits to maximize yield per square meter within the country's dense agricultural land constraints. National energy-efficiency mandates for permanent structures filter market access toward suppliers with documented thermal performance certification. The Westland municipality anchors greenhouse cluster density, with local zoning authorities streamlining permit pathways for soilless cultivation infrastructure.
Canada
Municipal zoning in Ontario and British Columbia permits accessory agricultural structures without engineered footing requirements, reducing capital barriers for residential adopters. Parcel logistics infrastructure supports flat-pack shipping of frame components from domestic fabricators to remote northern communities. The Prairie Provinces exhibit accelerating commercial adoption as grain operators diversify into protected vegetable production to capture premium winter market pricing.
Australia
Drought frequency intensification in New South Wales and Victoria drives open-field growers toward enclosed systems with precision irrigation control. State-level water-use regulations mandate contained drainage infrastructure that favors kit specifications with integrated sump systems. The Adelaide Plains concentration of protected horticulture operators sources polycarbonate-clad structures from Asian supply chains to minimize freight cost exposure.
Greenhouse Kit Market Competitive Landscape
Concentration sits with vertically integrated polycarbonate extruders and custom-engineered glass structure specialists. The vendor base separates into three functional tiers: mass-market assemblers competing on delivery velocity and component standardization; premium-system engineers capturing margin through climate-control integration and compliance documentation; and regional fabricators serving price-sensitive agricultural cooperatives with simplified hoop-house configurations. Dominant competitive moves include backward integration into polymer resin supply chains and strategic partnerships with hydroponic equipment distributors to bundle enclosure systems with soilless cultivation infrastructure.
Among North American fabricators, BC Greenhouses and Gothic Arch Greenhouses exemplify the premium-engineering archetype through custom-specified glass configurations for research and commercial breeding programs. Palram/Canopia anchors the mass-market tier with captive polycarbonate extrusion capacity that compresses material cost and delivery timelines for frame-kit buyers. Exaco, operating the Riga Greenhouses line, occupies a defensible position in northern-latitude markets through heavy-duty insulation specifications that sustain premium pricing in cold-climate jurisdictions.
| Leading Market Players |
|---|
| Planta Greenhouses |
| BC Greenhouses |
| Grandio Greenhouses |
| Gothic Arch Greenhouses |
| Yoderbilt Greenhouses |
| Changzhou Growell Garden Products |
| Exaco (Riga Greenhouses) |
| Atlas Manufacturing |
| Palram/Canopia |
| Others |
Value Network & Pricing Analysis
Polycarbonate panel substitution for glass cladding simultaneously shifts supply geography toward German and Chinese extrusion hubs and compresses per-unit material economics for frame-kit assemblers. This substitution dynamic concentrates pricing power with vertically integrated polymer suppliers while fragmenting margin pools across downstream fabricators.
Pricing Analysis
Commercial growers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on thermal certification grade and climate-control interface sophistication. Pricing pressure stems from float glass input cost volatility tied to natural gas and soda ash markets. Residential DIY buyers exhibit highest price sensitivity, while research facilities purchasing glass configurations show minimal elasticity.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for polycarbonate resin shipments. Manufacturing concentrates in Germany, China, and the United States. Raw material dependencies include polycarbonate resin, aluminum extrusions, and tempered float glass. Single-source vulnerability sits with German polymer extruders serving premium-cladding specifications. Distribution runs through direct-to-grower e-commerce channels and agricultural supply cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Greenhouse kit penetration remains early-cycle as urban farming ordinances expand addressable demand for residential and mid-scale commercial installations. EU Green Deal chemical-reduction mandates accelerate soilless cultivation protocol adoption.
For Market Incumbents: Shield margin pools by deepening backward integration into polycarbonate resin supply chains and accelerating hydroponic-equipment bundling. Polyethylene high-tunnel substitutes threaten price-sensitive volume in temperate zones. Climate-control interface R&D investment preserves premium positioning against mass-market assemblers.
For New Entrants and Emerging Players: Differentiate on modular DIY configurations for educational institutions facing curriculum-rotation requirements. White-space concentrates in Canadian and Australian residential segments with permissive municipal zoning. Go-to-market leverage through Amazon and specialty horticulture platforms bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: EU Green Deal Farm to Fork implementation reshapes the acquisition landscape toward hydroponic-integrated kit suppliers. Long-term viability favors targets with documented thermal performance certification and soilless cultivation equipment partnerships. Watch EPA agricultural runoff guideline enforcement timelines as inflection indicator for commercial replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polycarbonate Extrusion | Captive resin supply compresses material costs for Palram/Canopia and German fabricators. |
| Hydroponic Equipment Bundling | Nutrient-film technique convergence displaces substrate-based protocols in Netherlands operations. |
| Direct-to-Grower E-Commerce Expansion | Amazon and specialty platforms disintermediate county extension office distribution channels. |
| Educational Modular DIY Development | K-12 STEM mandates and university curriculum rotation drive non-permanent installation demand. |
| Energy-Efficiency Certification Investment | German and French building code compliance elevates taxable real property documentation requirements. |
Research Methodology
A standing panel of commercial greenhouse operators, agricultural extension officers, polycarbonate extrusion plant managers, and hydroponic equipment distributors provided ongoing calibration across the study. Primary fieldwork combined structured interviews with secondary validation against customs trade data, EPA regulatory filings, EU Green Deal implementation documents, and SEC disclosures from listed materials suppliers. Bottom-up shipment tallies and top-down consumption estimates underwent iterative reconciliation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling captured product type, material specification, end-user category, and installation method dimensions. CAGRs derived from year-over-year growth rate interpolation. Industry-specific forecast inputs included municipal zoning ordinance adoption timelines and EU Farm to Fork chemical-reduction target trajectories.
Material uncertainties — climate volatility severity, float glass price swings, and municipal zoning reversals — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement continuity and polymer supply chain stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Plows Market
Agricultural Equipment
Compost Turning Machine Market
Agricultural Equipment
Global Drip Emitters Market
Agricultural Equipment
Stock Tanks Market
Agricultural Equipment
Gardening Equipment Market
Agricultural Equipment
Agricultural Pumps Market
Agricultural Equipment
Harrows Market
Agricultural Equipment
Air Seeder Market
Agricultural Equipment
Battery Powered Cultivators Market
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Pond Aeration System Market
Agricultural Equipment
Agricultural Ventilation Fans Market
Agricultural Equipment
Agriculture Evaporative Cooling Pad Market
Agricultural Equipment
Bulk Reception Feeder Market
Agricultural Equipment
United States Grain Storage Silos Market
Agricultural Equipment
Solar Fruit Dryer Market