
 Special Purpose Electric Vehicle Market | 2026-2036
Special Purpose Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Special Purpose Electric Vehicle Market Intelligence
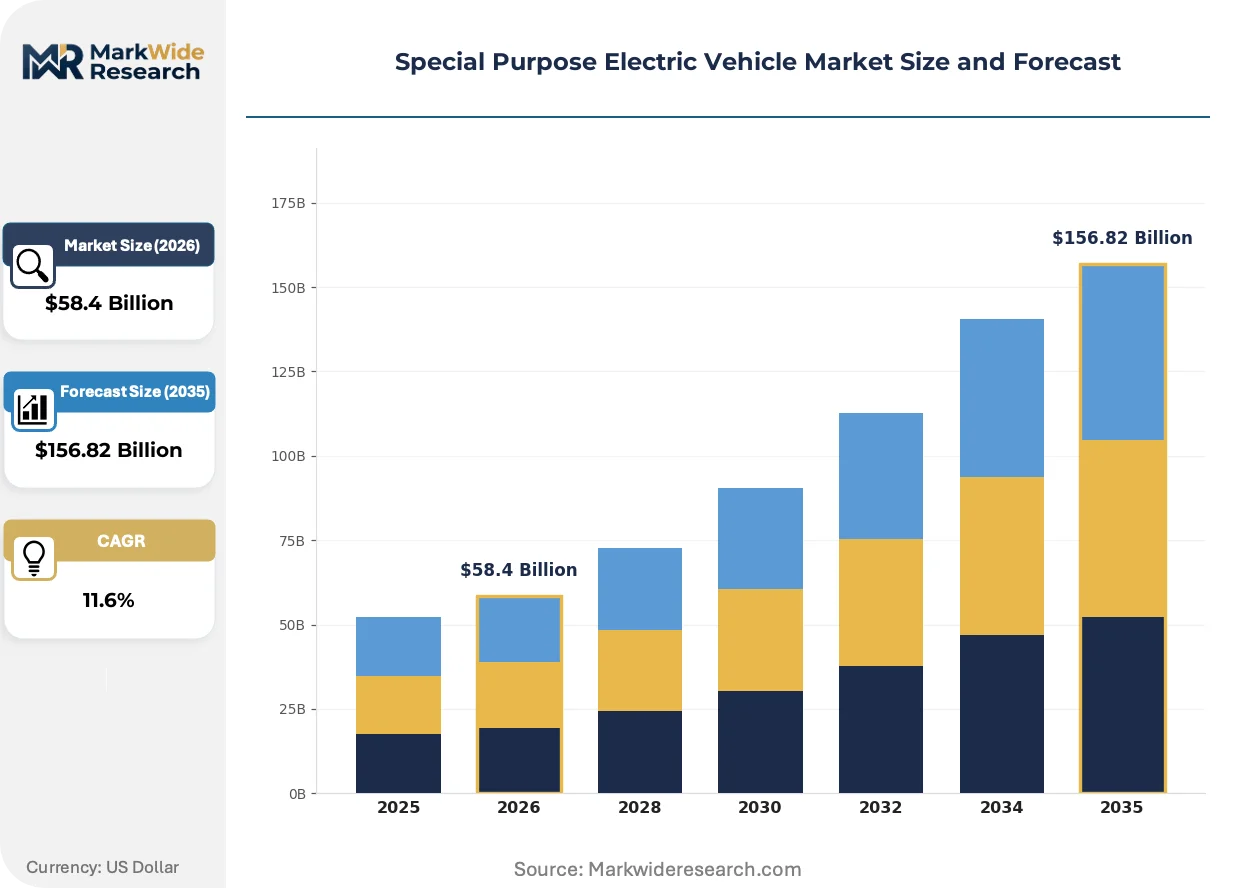
The substitution of traditional steel with lightweight carbon fiber composites in chassis manufacturing is shifting the fundamental cost-to-performance equation for specialized electric vehicles. This material change allows for greater payload capacity and extended operational range. Rivian specializes in high-performance utility vehicles designed for rugged environments. BYD Company leverages its extensive battery production scale for commercial applications, while Ford Motor Company positions its electrified Pro series to serve existing fleet customers.
Special purpose electric vehicles are conveyances engineered for specific commercial, industrial, or municipal functions, powered entirely or partially by an electric drivetrain. These vehicles are optimized for particular duty cycles, often featuring customized chassis and power take-off capabilities not found in consumer models. The battery electric technology segment commands the largest share, supported by expanding charging infrastructure. Within applications, electric delivery vans for last-mile delivery and utility vehicles for municipal services represent high-volume and high-growth areas.
Regulatory mandates are a primary market accelerant. The US EPA’s stringent emissions standards for commercial trucks and the EU Green Deal's objectives for zero-emission urban logistics create protected demand for electric models. In parallel, China's dual carbon goals drive significant procurement of electric vehicles by municipal services and state-owned enterprises. Navigating divergent charging infrastructure standards and grid capacity limitations remains a critical challenge for manufacturers scaling their operations across regions.
Market Dynamics
The market's fundamental trajectory is being defined by regulatory pressure, which is creating a protected and non-discretionary demand for electric models in commercial and municipal fleets, effectively mandating a technology shift away from internal combustion engines.
Growth Catalysts
- EU Green Deal Mandates:Regulations targeting zero-emission urban logistics create a guaranteed market for electric delivery vans and utility vehicles in European cities, forcing fleet turnover regardless of short-term economic cycles.
- Lightweight Composite Materials:The adoption of carbon fiber and other advanced composites in chassis and body construction enables higher payload capacities and extends vehicle range, directly improving the operational economics for logistics and service fleets.
- State-Directed Procurement:China's dual carbon goals and municipal-level policies are driving large-scale, mandated procurement of electric vehicles for sanitation, public works, and other state-owned enterprise functions, creating significant volume.
Market Restraints
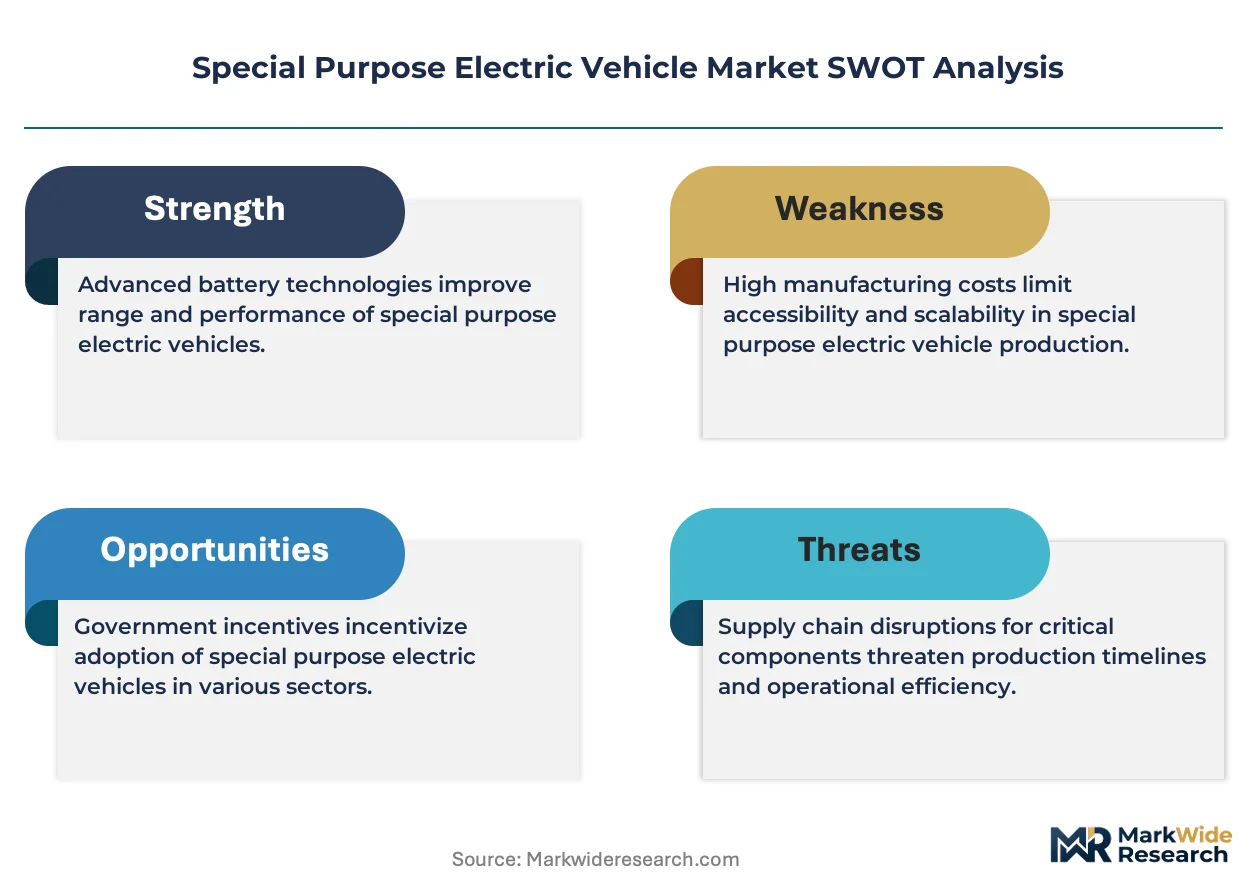
- High Battery Costs:The substantial upfront cost of high-capacity battery packs remains a significant barrier to adoption, making the total acquisition cost for specialized EVs considerably higher than their diesel counterparts.
- Charging Infrastructure Gaps:The lack of widespread, high-power charging infrastructure capable of supporting commercial duty cycles, particularly in depots and remote worksites, limits operational feasibility and creates range anxiety for fleets.
- Divergent Technical Standards:Conflicting charging connector and communication standards, such as CCS in Europe and North America versus GB/T in China, increase manufacturing complexity and limit the interoperability of global vehicle fleets.
Strategic Opportunities
- Niche Application Electrification:There is significant white space in electrifying high-torque, off-road applications such as specialized agricultural machinery, airport ground support equipment, and vehicles for the mining sector.
- Vehicle-to-Grid (V2G) Services:Integrating V2G capabilities allows fleet vehicles to function as distributed energy resources, providing grid stabilization services and creating new revenue streams for operators by selling power back during peak times.
- Emerging Market Urbanization:Rapidly urbanizing cities in regions like Southeast Asia and Latin America present an opportunity as they seek to combat severe air pollution through policies that favor electric municipal and logistics vehicles.
Industry Challenges
- Battery Supply Chain Volatility:Manufacturers face significant challenges in securing a stable and cost-effective supply of critical battery raw materials, including lithium, cobalt, and nickel, exposing them to price fluctuations and geopolitical risks.
- Auxiliary System Integration:Integrating power take-off (PTO) systems required for specialized equipment like hydraulic lifts, refrigeration units, or compactors with the high-voltage electric drivetrain is a complex engineering challenge.
- Specialized Technician Scarcity:A shortage of technicians trained in high-voltage battery system maintenance and diagnostics hinders the scalability of service and repair networks, impacting vehicle uptime and operator confidence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Special Purpose Electric Vehicle Market |
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $156.82 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Utility Vehicles, Delivery Vans, Emergency Vehicles, Agricultural Tractors, Mining Vehicles Technology: Battery Electric, Fuel Cell Electric, Hybrid Electric, Solar Electric, Supercapacitor Electric Application: Last Mile Delivery, Disaster Response, Crop Management, Underground Operations, Urban Maintenance End User: Logistics Providers, Fire Departments, Farm Operators, Mining Contractors, Municipal Services |
| Companies Covered | Tesla, BYD Company, General Motors, Volkswagen Group, Ford Motor Company, Hyundai Motor Group, Rivian, NIO, BMW Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Special Purpose Electric Vehicle Market Strategic Shifts & Innovations
A dual evolution in vehicle architecture and digital service layers is occurring. Hardware is becoming more modular to support customization, while software and telematics are enabling new operational models focused on total cost of ownership and asset utilization.
Modular Platforms and Customization
Modular battery and "skateboard" chassis platforms provide a standardized, scalable foundation for a wide array of specialized vehicle bodies. Commercial fleet operators and custom vehicle body builders are adopting these platforms to accelerate development timelines and reduce engineering costs. This approach is rewriting the cost-to-performance equation for custom vehicles, shifting production from bespoke engineering to a model of configurable mass production.
Regulatory Acceleration of Fleet Turnover
Stringent emissions standards from bodies like the US EPA for commercial vehicles are establishing firm deadlines for phasing out diesel engines. These regulations create a compulsory replacement cycle, forcing fleet operators to allocate capital towards zero-emission vehicle procurement to ensure compliance. The medium-duty truck segment, especially for urban utility and last-mile delivery, is the most directly impacted, spurring focused investment in compliant electric models.
Shift to Service-Based Consumption Models
Fleet operators are increasingly exploring subscription-based consumption models that bundle the vehicle, charging infrastructure, software, and maintenance into a single operating expense. This "Vehicle-as-a-Service" (VaaS) approach disrupts the traditional direct sales channel by shifting the financial burden from a large capital expenditure to a predictable monthly fee. The trend is most visible within the European last-mile delivery sector, where optimizing total cost of ownership is a primary competitive factor.
Special Purpose Electric Vehicle Market Segmentation
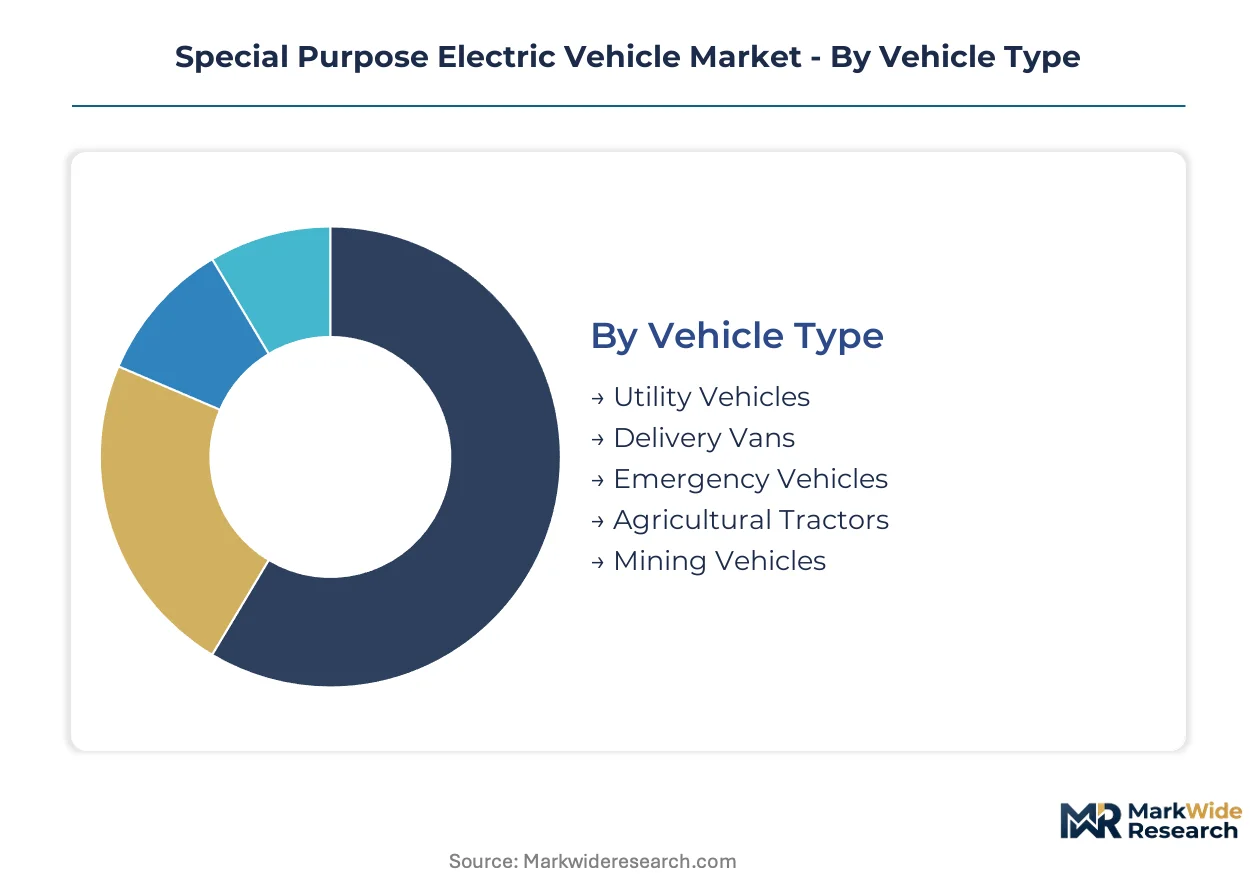
The segmentation of the Special Purpose Electric Vehicle Market provides a granular view of the diverse product offerings and their specific applications. Analyzing these distinct categories helps stakeholders understand where demand is concentrating and how various technologies and end-user requirements shape market dynamics.
Vehicle Type:
The market for special purpose electric vehicles exhibits a clear dichotomy between high-volume utility models and specialized, lower-volume variants, influencing both manufacturing scale and operational deployment.
- Utility Vehicles:These robust vehicles are engineered for demanding tasks in municipal services, construction, and infrastructure maintenance, often featuring specialized power take-off capabilities. Demand for electric utility vehicles is strong in China, where municipal policies favor electrification for urban maintenance fleets.
- Delivery Vans:Optimized for last-mile logistics, these vehicles prioritize cargo capacity, maneuverability, and frequent stop-start cycles in urban environments. The EU Green Deal mandates are accelerating the adoption of electric delivery vans for zero-emission urban logistics across Europe.
- Emergency Vehicles:This segment includes electric ambulances, police cruisers, and fire trucks, requiring high performance and reliability for critical response situations.
- Agricultural Tractors:Electrified tractors offer quieter operation and reduced emissions for farming activities, driven by sustainability goals and precision agriculture needs.
- Mining Vehicles:Designed for harsh underground and surface mining operations, these electric vehicles improve air quality and reduce operational costs in controlled environments.
Mature deployment sits with Delivery Vans. Newer deployment is concentrated in Agricultural Tractors.
Technology:
Technology segmentation highlights varying levels of maturity and cost across different electric drivetrain solutions, directly impacting market penetration and infrastructure requirements.
- Battery Electric:These vehicles rely solely on rechargeable battery packs to power an electric motor, offering zero tailpipe emissions and high energy efficiency. Expanding charging infrastructure, particularly for commercial depots, supports the continued dominance of battery electric technology.
- Fuel Cell Electric:Generating electricity onboard from hydrogen through a fuel cell, these vehicles offer extended range and faster refueling times, making them suitable for heavy-duty applications. Challenges include the high cost of hydrogen production and the nascent refueling infrastructure.
- Hybrid Electric:Combining an internal combustion engine with an electric motor, hybrid electric vehicles provide a bridge solution, reducing emissions and extending range.
- Solar Electric:Incorporating photovoltaic panels to supplement battery charging, solar electric vehicles extend operational range and reduce reliance on grid power for specific duty cycles.
- Supercapacitor Electric:Utilizing supercapacitors for rapid energy storage and release, these systems are ideal for applications requiring frequent braking and acceleration, enhancing energy recovery.
Battery Electric technology currently dominates due to established infrastructure. Fuel Cell Electric solutions are gaining traction for heavy-duty applications.
Application:
Application areas for special purpose electric vehicles span critical urban services and demanding industrial operations, each presenting unique duty cycle and performance requirements.
- Last Mile Delivery:This application focuses on efficient, emission-free transportation of goods from distribution centers to end consumers in urban and suburban areas. Regulatory mandates like the EU Green Deal are driving significant investment in electric delivery vans for this segment.
- Urban Maintenance:Vehicles for waste collection, street sweeping, and public utility repair fall into this category, benefiting from quiet operation and zero emissions in densely populated areas. China's municipal policies are a major driver for electric urban maintenance fleets.
- Disaster Response:Electric vehicles provide reliable, quiet, and emission-free transport for emergency personnel and equipment during critical situations, often requiring specialized power outlets.
- Crop Management:Electric agricultural vehicles are used for tasks such as spraying, harvesting, and field monitoring, contributing to sustainable farming practices and reducing operational noise.
- Underground Operations:Electric vehicles in mining and tunneling improve air quality, reduce ventilation costs, and enhance worker safety in enclosed environments.
Last Mile Delivery applications are driving significant fleet electrification. Underground Operations present a substantial opportunity for zero-emission vehicle integration.
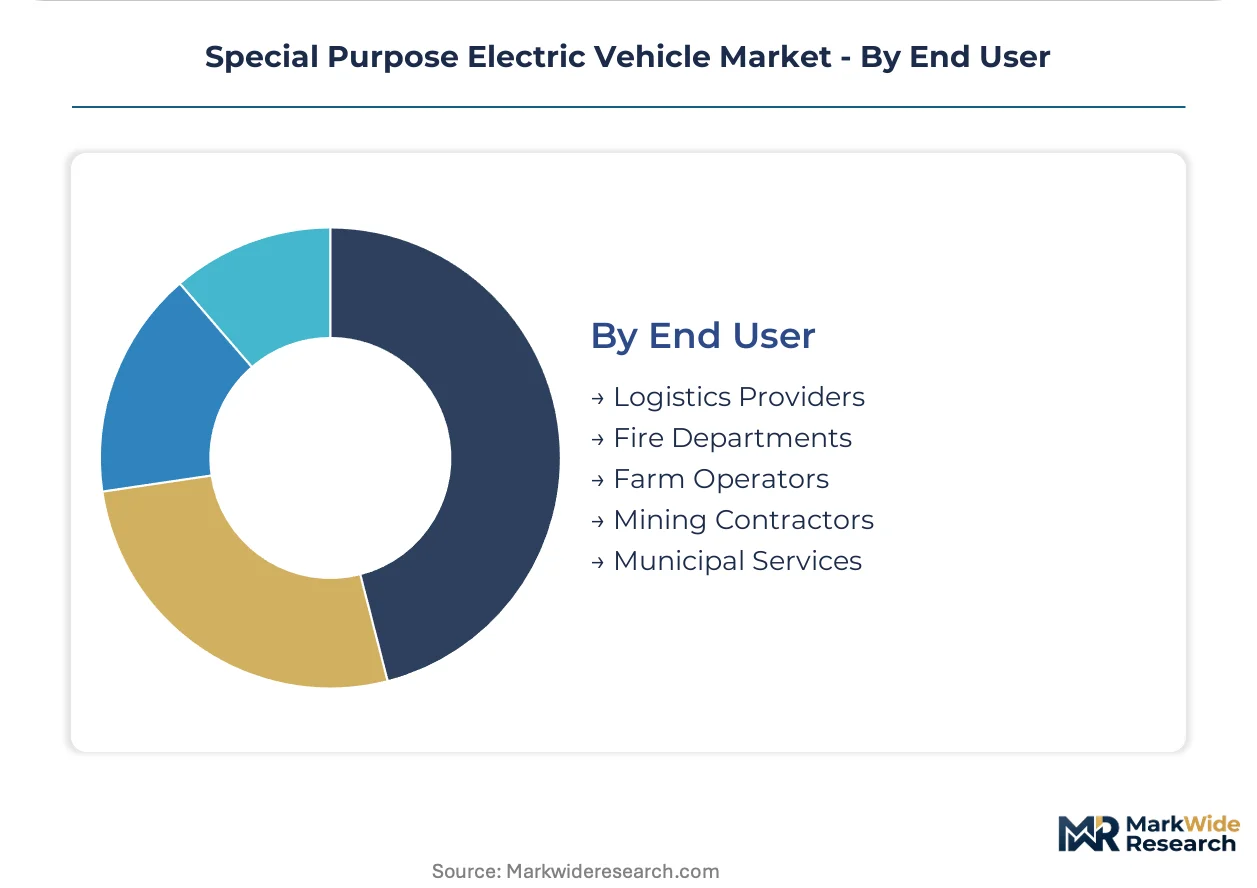
End User:
The end-user landscape for special purpose electric vehicles is diverse, encompassing both private sector logistics and public sector municipal services with distinct procurement priorities.
- Logistics Providers:Companies specializing in parcel and freight delivery are rapidly electrifying their fleets to meet sustainability targets and reduce operational costs. Fleet operators are exploring Vehicle-as-a-Service models to manage acquisition and maintenance expenses.
- Municipal Services:Government entities and public works departments procure electric vehicles for urban maintenance, sanitation, and public safety. China's dual carbon goals are driving significant procurement of electric vehicles by state-owned enterprises for municipal functions.
- Fire Departments:These organizations are adopting electric fire trucks and support vehicles to reduce emissions and noise during emergency responses.
- Farm Operators:Agricultural businesses are investing in electric tractors and utility vehicles to enhance sustainability, reduce fuel consumption, and comply with environmental regulations.
- Mining Contractors:Companies engaged in mineral extraction are integrating electric heavy equipment to improve air quality, reduce noise pollution, and enhance safety in mining operations.
Logistics Providers are rapidly electrifying their fleets to meet emissions targets. Farm Operators are increasingly considering electric options for sustainable agricultural practices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global demand for special purpose electric vehicles concentrates significantly in urban centers driven by regulatory mandates. China's municipal policies and the EU Green Deal are compelling rapid fleet electrification. This shift prioritizes zero-emission solutions for logistics and public services.
China
Demand for electric utility vehicles in China is strong, particularly for urban maintenance and public works. China's dual carbon goals drive significant procurement of electric vehicles by state-owned enterprises. Yangtze River Delta cities are seeing large-scale electric vehicle procurement for sanitation and public service fleets.
United States
The United States market exhibits robust demand for electric delivery vans and commercial utility trucks. The US EPA's stringent emissions standards for commercial trucks establish a compulsory replacement cycle. California mandates and incentives are accelerating electric truck adoption in major logistics and distribution hubs.
Germany
Germany's market for special purpose electric vehicles is propelled by stringent environmental targets for urban logistics. The EU Green Deal mandates for zero-emission urban logistics create a guaranteed market for electric delivery vans. Cities like Berlin are implementing policies favoring electric delivery vans for inner-city operations and public utilities.
India
Rapid urbanization and the need to combat severe air pollution drive the demand for electric logistics and municipal vehicles in India. The National Electric Mobility Mission Plan promotes electric vehicle adoption across various segments. Delhi and Mumbai are witnessing increased deployment of electric delivery vans to address air quality concerns in congested areas.
France
France shows a growing demand for electric vehicles in urban logistics and municipal services, aligning with national environmental commitments. The EU Green Deal and local low-emission zone regulations create protected demand for electric models. Paris is actively electrifying its municipal service fleet to reduce urban emissions and noise pollution.
Special Purpose Electric Vehicle Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, creating a fragmented market structure with emerging consolidation. This market features several strategic archetypes, including established automotive OEMs, specialized EV pure-plays, and niche vehicle converters. Dominant competitive moves include strategic partnerships for advanced technology integration and capacity expansion in battery production.
At the scale-driven end, BYD Company occupies a position anchored by its integrated battery production capabilities for commercial applications. Ford Motor Company exemplifies the legacy automotive OEM adapting its existing fleet offerings with its electrified Pro series. Rivian represents the EV pure-play specializing in high-performance utility vehicles designed for rugged environments. This mix reflects the diverse approaches to electrifying special purpose vehicles.
| Leading Market Players |
|---|
| Tesla |
| BYD Company |
| General Motors |
| Volkswagen Group |
| Ford Motor Company |
| Hyundai Motor Group |
| Rivian |
| NIO |
| BMW Group |
| Others |
Cost & Logistics Intelligence
Lithium carbonate price fluctuations directly cascade through the special purpose electric vehicle market, influencing battery pack costs and ultimately vehicle acquisition prices. This dynamic shapes the competitive landscape, where supply chain resilience increasingly determines long-term pricing stability for fleet operators.
Pricing Analysis
Volume sales in the special purpose electric vehicle market often yield lower per-unit margins compared to highly customized, low-volume applications. The dominant pricing structure is a hybrid model, combining per-unit transactional sales for standard models with subscription-based Vehicle-as-a-Service (VaaS) for fleet operators. Price differentiation stems from customization levels for specific duty cycles and the depth of after-sales service and maintenance packages. Pricing pressure stems from the high initial battery costs, which are slowly softening as battery technology matures. Logistics providers exhibit the highest price sensitivity, driven by total cost of ownership considerations, while emergency services prioritize reliability over upfront cost.
Supply Chain Analysis
Direct-to-fleet channels and OEM dealer networks manage the distribution of special purpose electric vehicles to end-users. Geographic supply concentration for critical battery components centers on China, which dominates processing of raw materials like lithium from Australia and cobalt from the Democratic Republic of Congo. Key raw material dependencies include lithium, nickel, and cobalt for battery manufacturing, alongside carbon fiber for lightweight chassis construction. Battery supply chain volatility, including geopolitical risks and material scarcity, represents a significant structural risk. OEMs increasingly seek to diversify sourcing and establish long-term supply agreements for these essential inputs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is currently in a technology-transition phase, with battery electric drivetrains displacing legacy internal combustion engines across diverse applications.
For Market Incumbents:Anticipate continued regulatory pressure for zero-emission vehicles, particularly in urban logistics and municipal services. Invest in modular platform development to support a wider array of specialized vehicle bodies and reduce engineering costs. Deepen vertical integration into battery component manufacturing or secure long-term supply agreements to mitigate raw material price volatility, a key threat to margin stability. Focus R&D on advanced power take-off (PTO) integration for specialized equipment, a critical lever for utility vehicle performance.
For New Entrants and Emerging Players:A significant price-point gap exists between premium, highly customized electric vehicles and more accessible, standardized options. Target underserved niche applications requiring high torque or specific duty cycles, such as specialized agricultural machinery or airport ground support equipment. Penetrate the market by offering comprehensive Vehicle-as-a-Service (VaaS) models that bundle vehicle, charging, and maintenance into a predictable operating expense. Focus go-to-market strategies on regions with strong government incentives or strict emission mandates, like European urban centers.
For Investors and Strategic Acquirers:Distressed-cycle entries favor acquirers with strong balance sheets to consolidate specialized EV pure-plays in key technology areas. The long-term viability of this market hinges on the continued expansion of charging infrastructure and the reduction of battery costs over the next decade. Identify acquisition targets with proprietary battery management systems or advanced power take-off (PTO) integration capabilities. A key signal to watch is the widespread adoption of vehicle-to-grid (V2G) technology, which could unlock significant new revenue streams for fleet operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Development | Accelerates product development cycles for specialized vehicle variants, expanding market reach. |
| Battery Supply Chain Diversification | Mitigates geopolitical risks and raw material price volatility for critical components. |
| Vehicle-as-a-Service (VaaS) Rollout | Reduces upfront capital expenditure for fleet operators, accelerating adoption rates. |
| Advanced PTO System Integration | Enhances functionality for utility and municipal vehicles, meeting specific operational demands. |
| Targeted Niche Electrification | Unlocks new market segments with high-torque, off-road requirements, expanding application scope. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, providing foundational market sizing and trend analysis. Primary research involved interviews with industry stakeholders, including fleet managers, OEM product development executives, battery technology specialists, and municipal procurement officers. This approach ensured a robust triangulation of volume and value outputs across the analysis window.
Market modeling integrated data across vehicle type, technology, application, and end-user segments at a granular level. The analytical framework projected future growth rates by assessing regulatory impacts, technological advancements, and economic factors influencing demand. Compound Annual Growth Rates (CAGRs) were derived from a comprehensive analysis of historical data and forward-looking market drivers. Key forecast inputs included projected battery cost reductions and charging infrastructure expansion rates.
Inputs from public financial reports, academic studies, and government policy documents were available through the study window; gaps in emerging market data introduce uncertainty bands around specific regional forecasts. Forecasts reflect assumptions regarding technological evolution and regulatory stability over the projection horizon. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
Electric Vehicle Electronic Expansion Valve (EXV) Market
Electric Vehicles
United Kingdom E-Bike Market
Electric Vehicles
Mexico Electric Bus Market
Electric Vehicles
Global Electric Classic Car Market
Electric Vehicles
Commercial Electric Vehicle Resistive Braking System Market
Electric Vehicles
Mexico Electric Car Market
Electric Vehicles
Lithium Battery Electric Scooters Market
Electric Vehicles
Germany Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
Compact E-Scooter Market
Electric Vehicles
Electric Vehicle Relay Market
Electric Vehicles
India Solar E-Bike Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
India Electric Vehicle Market