
 Global Feed Palatability Enhancers Market | 2026-2036
Global Feed Palatability Enhancers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Feed Palatability Enhancers Market Analysis
Modular flavor dosing systems is decoupling bulk concentrate supply from on-farm blending decisions, letting integrators customize palatability profiles by barn or growth phase. Kemin Industries leverages its vertically integrated botanical extraction infrastructure to control raw material quality for natural flavor lines. Kerry Group anchors European supply through regional flavor compounding facilities that compete on formulation speed and sensory validation services.
Feed palatability enhancers comprise flavor-active compounds, acidifiers, and sweetening agents added to animal diets to stimulate voluntary feed intake and mask off-flavors from functional ingredients like medications or alternative proteins. Manufacturing typically involves spray-drying of liquid flavor precursors onto porous carriers or direct extrusion into fat-coated granules to protect volatile compounds through pelleting temperatures. Natural flavors and acidifiers together command the dominant share of value, with acidifiers pulling ahead in antibiotic-free poultry systems where gut health and taste masking must coincide. Liquid forms lead in aquaculture application due to uniform dispersion in extruded feeds, while powder and granule forms dominate land-animal premix channels where dry blending compatibility determines adoption.
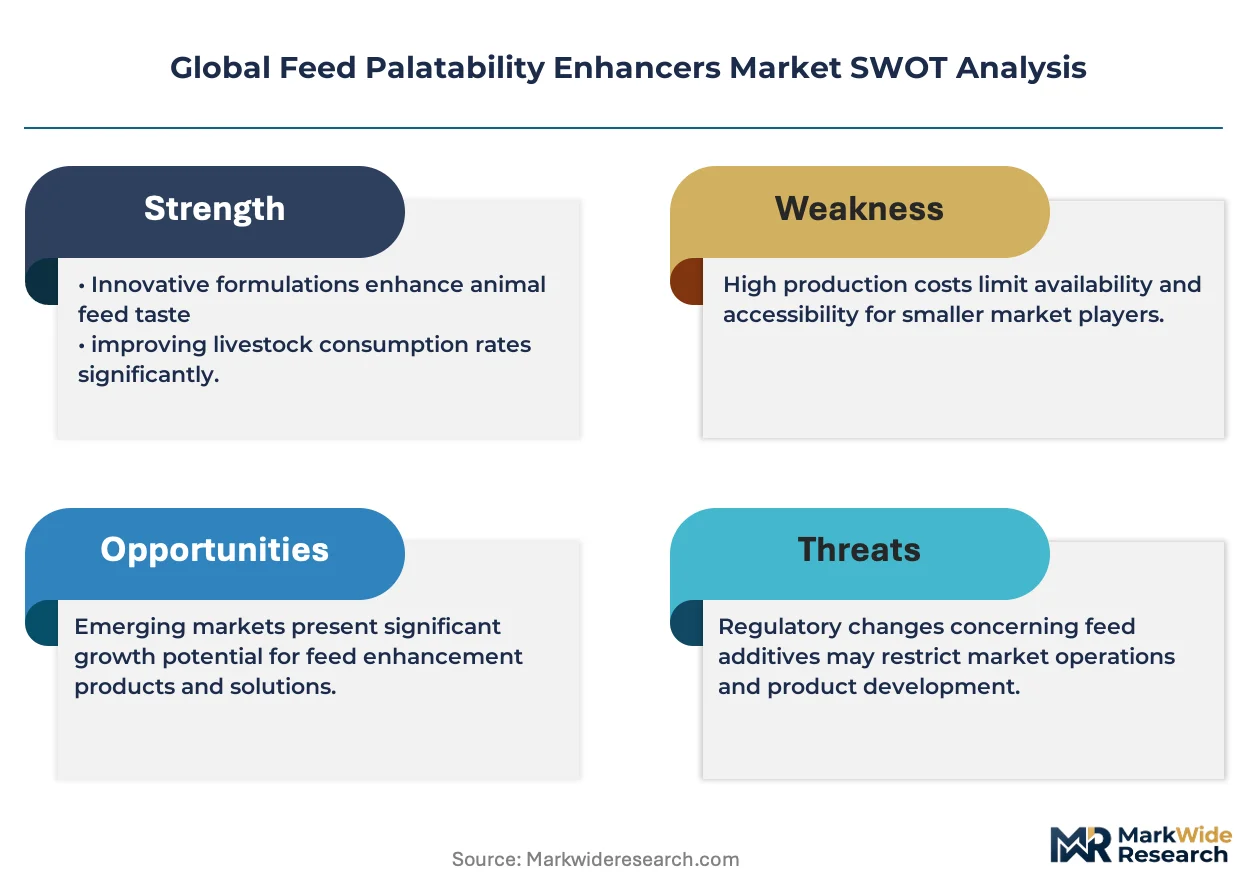
EFSA and the EU Green Deal framework restrict synthetic flavorant approvals and mandate environmental footprint disclosures that favor botanical-sourced alternatives. FDA's GRAS self-affirmation pathway and China's MEE pollution controls on chemical manufacturing jointly shape where new production capacity locates and which chemistries achieve scale. Stakeholders must track how divergent regulatory timelines across these jurisdictions affect product registration costs and first-mover positioning in antibiotic-free segments.
Market Dynamics
Antibiotic-free poultry mandates are compressing approval timelines for natural palatability solutions while concentrating procurement authority among integrated protein processors.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Mandatory reduction targets for synthetic additives in livestock feed are redirecting formulation R&D toward botanical extraction pathways and clean-label ingredient portfolios.
- High-density poultry operations:Automated feeding systems in Brazil and Thailand require consistent intake rates that flavor-enhanced diets deliver, driving volume commitments from integrators.
- Acidifier technology:Dual-function acidifiers that simultaneously mask off-flavors and support gut health are capturing preference in antibiotic-free broiler programs.
Market Restraints
- Botanical raw material volatility:Weather-dependent harvests of vanilla, citrus, and herb extracts in Madagascar and India create input cost instability for natural flavor lines.
- EFSA additive approval timelines:Novel flavorant authorizations under EU 1831/2003 require 18-36 month safety evaluations that delay product commercialization.
- Synthetic flavor substitution pressure:Cost-competitive artificial alternatives from Chinese chemical manufacturers undercut natural product margins in price-sensitive aquaculture segments.
Strategic Opportunities
- Vietnam aquaculture expansion:Shrimp and pangasius feed producers lack localized palatability testing infrastructure, creating first-mover openings for technical service partnerships.
- Modular on-farm dosing systems:Precision agriculture integrators in the Netherlands and Denmark are piloting barn-level flavor customization that decouples concentrate supply from blending decisions.
- China dual carbon goals:MEE pollution controls on chemical manufacturing are elevating capital requirements for synthetic flavor production, advantaging botanical-sourced alternatives with lower environmental footprints.
Industry Challenges
- Sensory validation capability gaps:Standardized palatability testing protocols require trained panels and controlled facilities that remain scarce outside Western Europe and North America.
- Cross-regulatory registration complexity:Divergent data requirements between FDA GRAS self-affirmation and EFSA full authorization force duplicate toxicology studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Feed Palatability Enhancers Market |
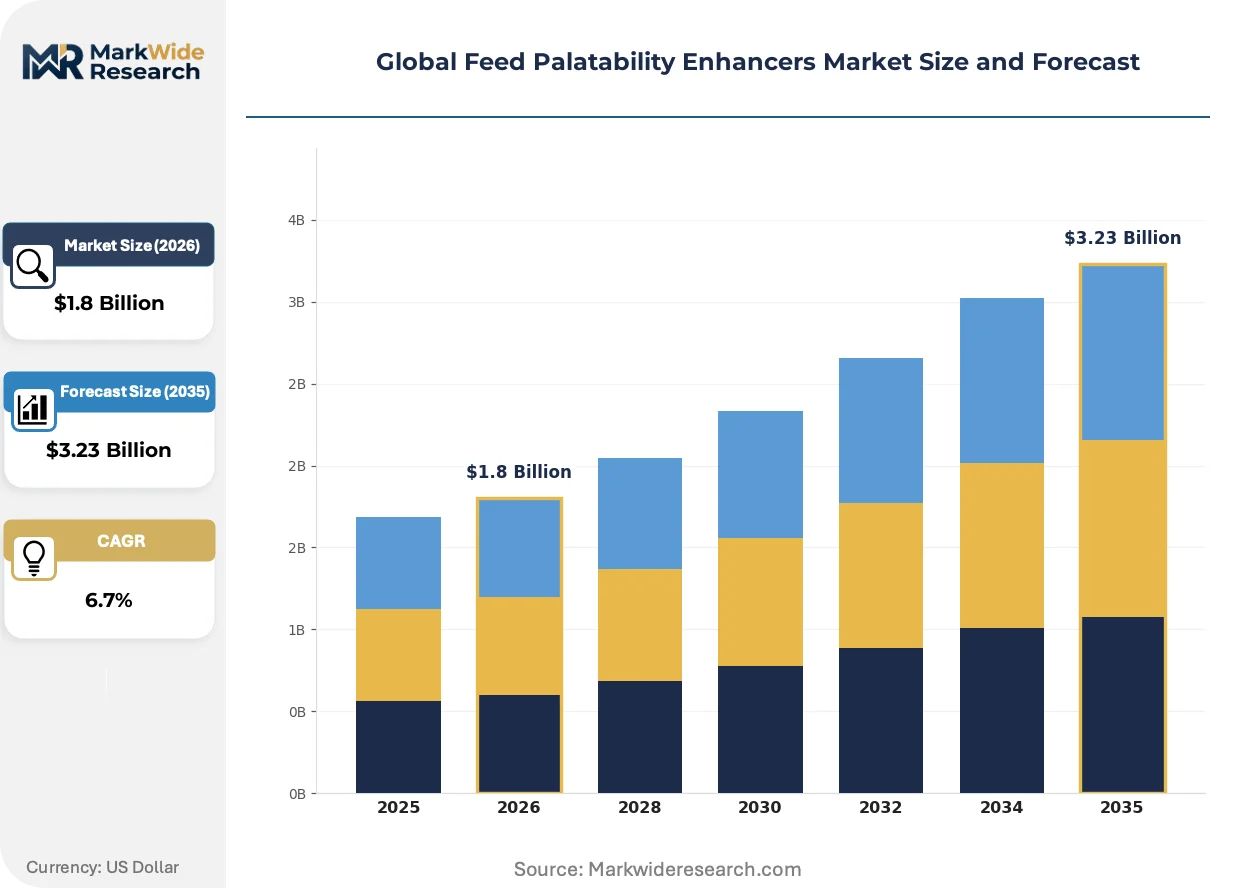
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Natural Flavors, Artificial Flavors, Sweeteners, Acidifiers Application: Poultry, Swine, Ruminants, Aquaculture Form: Liquid, Powder, Granule, Pellet Distribution Channel: Direct Sales, Retail, E-commerce, Distributors |
| Companies Covered | Associated British Foods Plc, Kemin Industries Inc., Kerry Group Plc, Kent Nutrition Group, Elanco Animal Health, Symrise AG, Adisseo France SAS, Cargill, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Feed Palatability Enhancers Market Emerging Trajectories
Encapsulation technologies and precision delivery systems are redrawing competitive boundaries between ingredient suppliers and equipment manufacturers.
Microencapsulation via fat-matrix spray chilling is expanding into high-temperature pelleting applications previously dominated by liquid flavor systems. Poultry integrators in Poland and Spain are adopting these protected formats to preserve volatile compounds through extrusion. The technology is expanding into aquaculture premix channels where thermal stability requirements have historically limited flavor adoption.
EFSA's 2023 guidance on botanical additive characterization is tightening identity-preservation requirements for natural flavor supply chains. Manufacturers must now document geographic origin and extraction method for each raw material batch. European compound feed producers are responding by qualifying dual-source suppliers and investing in blockchain traceability systems.
Buyer consolidation among Brazilian and Thai protein processors is compressing supplier negotiation cycles from annual to quarterly terms. Long-term flavor supply agreements with fixed pricing are giving way to index-linked contracts tied to botanical commodity futures. This shift is most visible in Sao Paulo state, where three integrated poultry groups now control over sixty percent of regional feed additive procurement decisions.
Global Feed Palatability Enhancers Market Segmentation
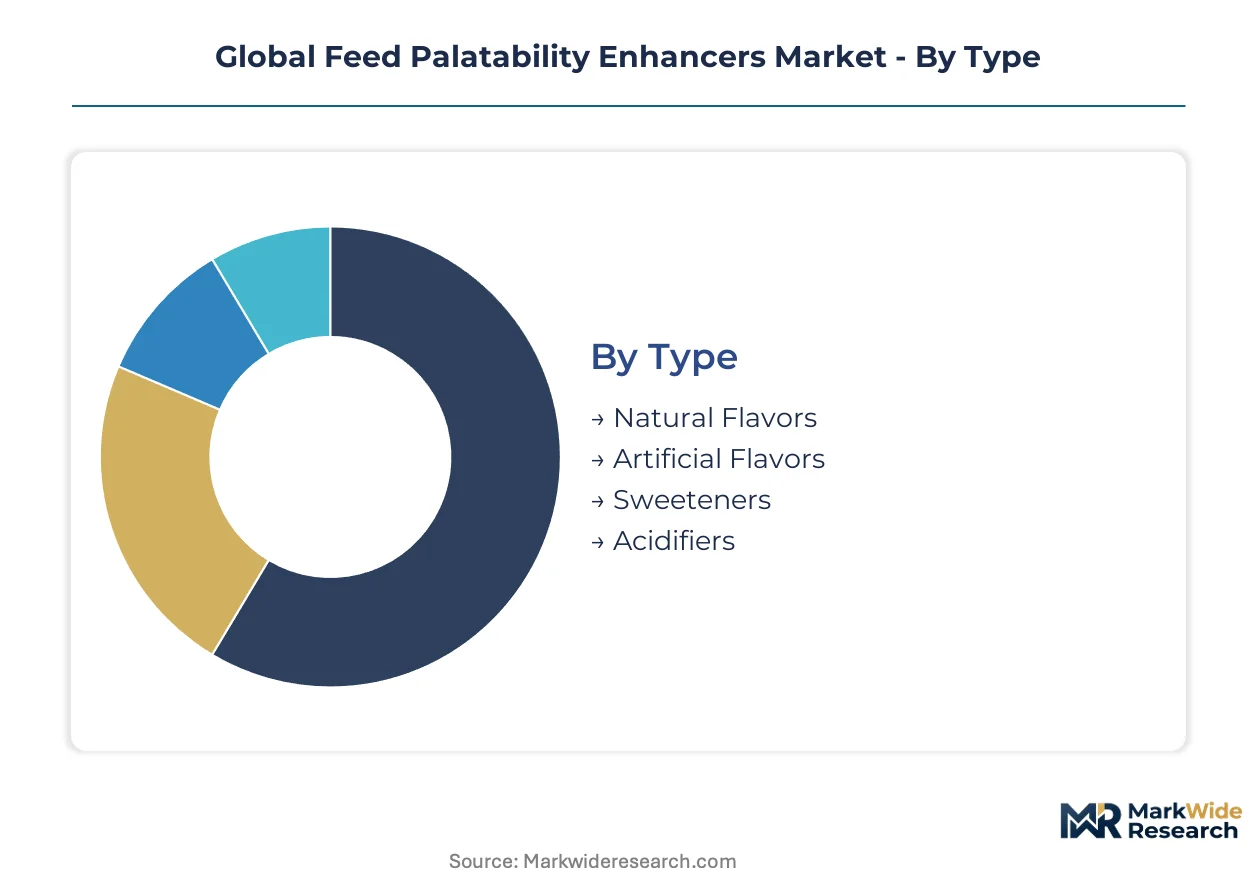
Feed palatability enhancers segment across multiple dimensions that determine formulation economics, regulatory pathways, and customer procurement behavior. Understanding these divisions reveals where margin pools concentrate and which technology platforms command pricing power.
Type:
Supply concentration in botanical extraction infrastructure favors producers with captive raw material sourcing and vertical control over quality verification.
- Natural Flavors:Derived from vanilla, citrus, and herb extracts through steam distillation or cold-pressing methods. EU Green Deal mandates in Germany and France are compressing procurement toward botanical alternatives as EFSA tightens synthetic additive approvals. Madagascar and Indian harvest volatility creates input cost instability that favors multi-source qualification strategies.
- Artificial Flavors:Chemically synthesized esters, aldehydes, and ketones manufactured through catalytic processes. Chinese MEE pollution controls are elevating capital requirements for new production capacity, pushing cost-sensitive aquaculture buyers toward Southeast Asian suppliers with legacy chemical manufacturing assets.
- Sweeteners:Saccharin, neotame, and stevia glycosides that mask bitter notes from medications or alternative proteins.
- Acidifiers:Organic acids and acid salts that simultaneously improve taste profiles and support gut health in antibiotic-free programs.
Today's leader: Natural Flavors. Tomorrow's challenger: Acidifiers.
Application:
End-use concentration among integrated protein processors in Brazil and Thailand determines volume allocation and technical service intensity.
- Poultry:High-density broiler operations in Sao Paulo state and Thailand's central plains require consistent intake rates that automated feeding systems demand. Flavor-enhanced diets reduce feed conversion ratio variance across growth phases.
- Aquaculture:Shrimp and pangasius producers in Vietnam's Mekong Delta lack localized palatability testing infrastructure, creating first-mover openings for technical partnerships.
- Swine:Sow and nursery diets in Denmark and the Netherlands utilize precision dosing systems for barn-level customization.
- Ruminants:Beef and dairy operations in Argentina and Australia apply flavors to mask off-notes from urea and alternative protein sources in total mixed rations.
Poultry commands current procurement volumes. Aquaculture offers the steepest expansion trajectory.
Form:
Manufacturing process selection hinges on thermal stability requirements through pelleting and extrusion stages.
- Liquid:Uniform dispersion in aquaculture extruded feeds dominates Vietnamese and Indonesian shrimp feed channels. Spray application onto finished pellets preserves volatile compounds but requires specialized dosing equipment.
- Powder:Dry blending compatibility with premix concentrates serves land-animal nutrition programs in Poland and Spain where batch flexibility matters.
- Granule:Fat-coated carriers protect flavors through high-temperature pelleting in Brazilian poultry operations.
- Pellet:Direct incorporation into complete feeds for ruminant applications in Argentina's Pampas region.
Liquid leads aquaculture adoption. Granule formats are gaining share fastest in high-temperature poultry applications.
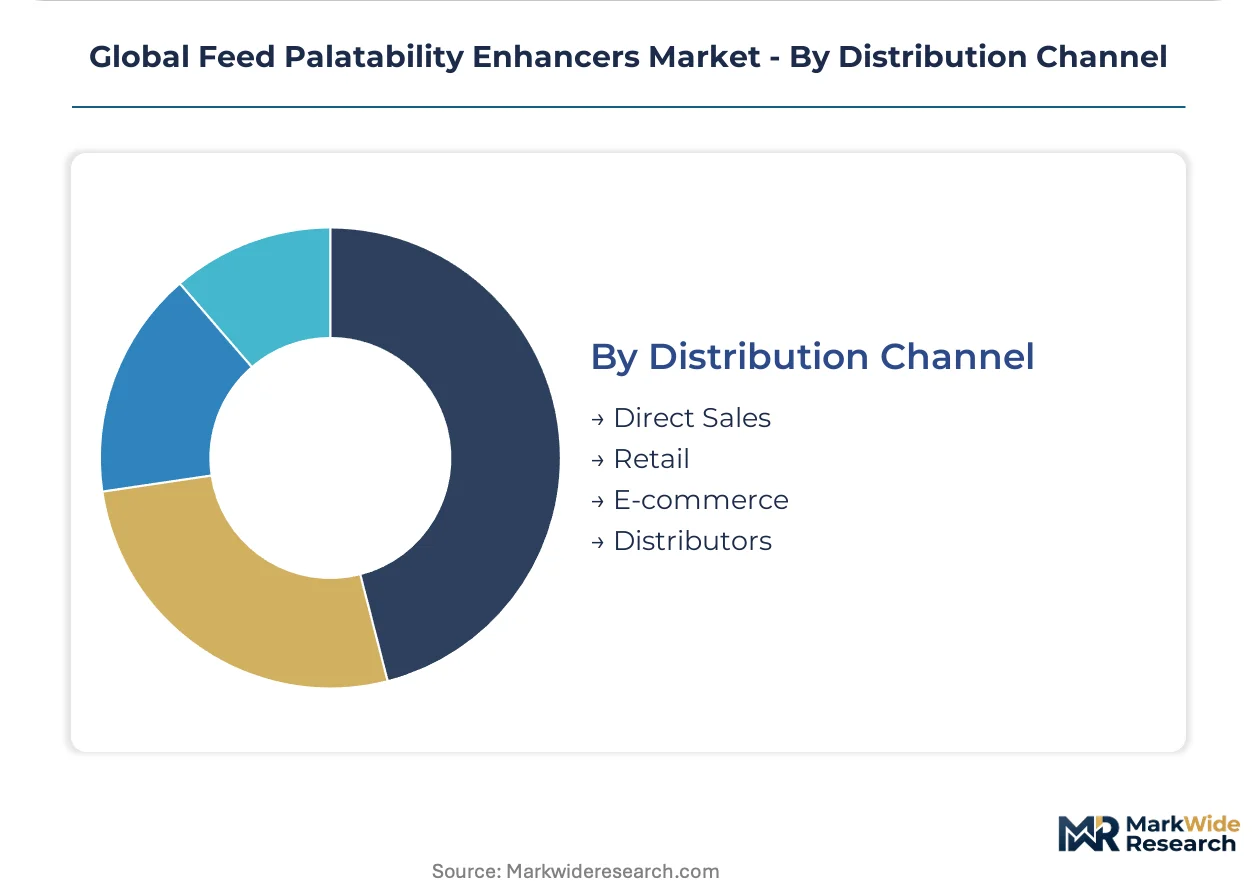
Distribution Channel:
Buyer consolidation is compressing negotiation cycles and favoring direct relationships over intermediary layers.
- Direct Sales:Quarterly index-linked contracts with Brazilian integrators replacing annual fixed-price agreements. Technical service bundling with flavor supply creates switching costs.
- Distributors:Regional compound feed manufacturers in Vietnam and Poland rely on local inventory and formulation support.
- Retail:Small-scale livestock producers in India's Maharashtra and Karnataka states purchase through agricultural supply cooperatives.
- E-commerce:Emerging channel for specialty acidifiers and natural flavors among European organic livestock producers.
Direct Sales dominates procurement value. E-commerce represents the fastest-growing channel for specialty natural products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed palatability enhancers originated in Western European compound feed manufacturing during the 1970s, when Dutch and German nutritionists first systematized flavor addition to mask medication bitterness in intensive livestock operations. The industry subsequently dispersed to Brazil, Thailand, and Vietnam as protein production consolidated in tropical zones.
United States
Poultry integrators in Georgia and Arkansas deploy automated feeding systems that require consistent intake rates, driving procurement of flavor-enhanced diets. FDA's GRAS self-affirmation pathway accelerates novel flavorant commercialization compared to European timelines. Chicago-area feed compounders maintain technical service partnerships with flavor suppliers to customize barn-level palatability profiles.
Brazil
São Paulo state processors control over sixty percent of regional feed additive procurement through quarterly index-linked contracts replacing annual fixed-price agreements. ANVISA regulates additive safety under Mercosur harmonization protocols that diverge from EFSA standards. Campinas and Sorocaba clusters concentrate integrated poultry testing laboratories where palatability validation occurs.
Germany
EU Green Deal Farm to Fork Strategy mandates synthetic additive reduction targets that redirect R&D toward botanical extraction pathways. EFSA approval timelines of 18-36 months delay novel flavorant authorization under EU 1831/2003. Lower Saxony's compound feed belt around Hanover and Oldenburg anchors natural flavor qualification programs.
Vietnam
Shrimp and pangasius feed producers in the Mekong Delta lack localized palatability testing infrastructure, creating technical service gaps. The country's Ministry of Agriculture and Rural Development aligns feed additive regulations with ASEAN harmonization frameworks. Can Tho and An Giang provinces concentrate aquaculture feed manufacturing where liquid flavor dispersion systems dominate extruded feed channels.
China
MEE pollution controls on chemical manufacturing elevate capital requirements for synthetic flavor production, advantaging botanical-sourced alternatives. NMPA and SAMR jointly oversee feed additive registration under GB standards that increasingly reference environmental footprint criteria. Shandong Peninsula feed clusters around Qingdao are retrofitting facilities to handle natural extract supply chains.
Global Feed Palatability Enhancers Market Vendor Landscape
The competitive structure tilts toward diversified nutrition conglomerates with captive botanical extraction infrastructure. Tier-one suppliers compete on formulation speed and sensory validation services, while mid-scale specialists differentiate through regional flavor compounding proximity. Three archetypes dominate: vertically integrated botanical processors, regional formulation service providers, and diversified animal health conglomerates. M&A activity concentrates on botanical extraction assets, and capacity expansion favors Southeast Asian locations with legacy chemical manufacturing infrastructure.
Within the diversified nutrition tier, Kerry Group Plc and Cargill exemplify archetypes combining global supply reach with regional formulation agility. Kemin Industries Inc. occupies a distinct position anchored in vertically controlled botanical extraction infrastructure. Associated British Foods Plc represents the integrated food-to-feed conglomerate model with backward integration into flavor precursor supply chains.
| Leading Market Players |
|---|
| Associated British Foods Plc |
| Kemin Industries Inc. |
| Kerry Group Plc |
| Kent Nutrition Group |
| Elanco Animal Health |
| Symrise AG |
| Adisseo France SAS |
| Cargill |
| DuPont |
| Others |
Supply Flow & Price Mechanics
Natural-certification premiums versus commodity-grade synthetic alternatives bifurcates procurement economics, with EU Green Deal compliance tiers commanding supply chain investments in traceable botanical sourcing while price-sensitive aquaculture buyers in Southeast Asia draw from legacy chemical manufacturing clusters in China and Indonesia.
Pricing Analysis
Index-linked quarterly contracts replacing annual fixed-price agreements dominate Brazilian poultry procurement, with price differentiation anchored in botanical commodity futures volatility and EFSA certification status. Cost compression in synthetic flavor lines stems from Chinese MEE pollution controls elevating capital requirements, while natural product margins face pressure from Madagascar vanilla harvest instability. Aquaculture feed producers exhibit highest price sensitivity, whereas European compound feed manufacturers prioritize sensory validation services over unit cost.
Supply Chain Analysis
Botanical raw material supply rests on Madagascar vanilla estates, Indian citrus extract processors, and Brazilian herb cultivation cooperatives as primary geographic nodes. Steam distillation equipment, cold-pressing infrastructure, and spray-drying capacity constitute critical manufacturing dependencies. Single-source vulnerability concentrates in Madagascar's cyclone-exposed vanilla belt, where weather disruptions propagate through global natural flavor pricing. Distribution runs through direct technical service relationships with integrated protein processors in São Paulo state and regional distributors serving Vietnam's Mekong Delta aquaculture compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as antibiotic-free protein mandates institutionalize flavor-enhanced feed formulations across integrated poultry operations. Protein processor consolidation compresses supplier negotiation cycles and rewards scale.
For Market Incumbents: Lock in captive botanical extraction capacity through backward integration into Madagascar and Indian raw material sourcing to defend margin position against harvest volatility. Anchor technical service partnerships with Brazilian integrators undergoing quarterly contract transitions to create switching costs that emerging regional formulators cannot replicate.
For New Entrants and Emerging Players: The premium-to-economy price gap in Vietnamese aquaculture creates entry opportunity for technical service partnerships filling localized palatability testing infrastructure gaps. Target shrimp and pangasius feed producers in Can Tho and An Giang provinces with liquid flavor dispersion system pilots bundled with sensory validation protocols.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale botanical extraction specialists possessing EFSA-qualifiable supply chains and existing relationships with European compound feed manufacturers. Five-to-ten-year viability hinges on EU Green Deal implementation pace; monitor EFSA authorization timeline compression for novel natural flavorants as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Extraction | Captive supply of Madagascar vanilla and Indian citrus extracts insulates margin from commodity futures volatility. |
| Regional Flavor Compounding Facility Expansion | Proximity to Lower Saxony compound feed belt accelerates EFSA-compliant formulation turnaround for European integrators. |
| Microencapsulation Technology Licensing | Fat-matrix spray chilling patents unlock high-temperature pelleting applications previously dominated by liquid systems. |
| Technical Service Partnership in Vietnam | Localized palatability testing infrastructure addresses Mekong Delta aquaculture's sensory validation capability gap. |
| Blockchain Traceability System Deployment | EFSA's 2023 botanical additive characterization guidance mandates geographic origin documentation for each raw material batch. |
Methodological Framework
Bottom-up poultry and aquaculture feed volume modeling reconciled against top-down botanical extraction capacity tracking forms the analytical core of this study. Primary interviews with compound feed procurement directors, flavor supplier technical service heads, and EFSA regulatory affairs specialists combined with secondary validation from EU 1831/2003 authorization databases, Brazilian ANVISA additive registries, and Chinese MEE pollution control disclosure filings. Triangulation across these sources ensures segmentation outputs reflect actual procurement behavior rather than manufacturer shipment claims.
Historical trendline analysis of natural versus synthetic flavor adoption rates across antibiotic-free broiler programs established baseline growth patterns projected across the analysis window. Segmentation modeling incorporated type distinctions, application channels, form factors, and distribution methodologies as structural dimensions. CAGRs derived from weighted average of bottom-up volume build and top-down spending allocation, with sensitivity testing against botanical commodity price scenarios and regulatory authorization timeline variations.
Caveats apply where EFSA additive approval delays, Madagascar vanilla harvest failures, or Chinese environmental enforcement intensity could materially shift the outlook. Forecasts reflect assumptions about continued protein processor consolidation and EU Green Deal implementation trajectory. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Asia-Pacific Feed Premix Market
Agricultural Chemicals
Artificial Humus Market
Agricultural Chemicals
Strobilurin Fungicide Market
Agricultural Chemicals
Agricultural Antibacterials Market
Agricultural Chemicals
Poultry Feed Premix Market
Agricultural Chemicals
India Fungicide Market
Agricultural Chemicals
Global Fertigation and Chemigation Market
Agricultural Chemicals
North America Feed Enzymes Market
Agricultural Chemicals
South America Feed Minerals Market
Agricultural Chemicals
Animal Feed Enzymes Market
Agricultural Chemicals
Global Crop Oil Concentrates Market
Agricultural Chemicals
Europe Feed Premix Market
Agricultural Chemicals
Stored Grain Insecticides Market
Agricultural Chemicals
Asia-Pacific Feed Antibiotics Market
Agricultural Chemicals
Feed Amino Acids Market
Agricultural Chemicals
Asia Pacific Feed Pelletizing Agents Market