
 Digital Synthesizers Market | 2026-2036
Digital Synthesizers Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Synthesizers Market Insights
CE marking under the EU Radio Equipment Directive is bifurcating the competitive landscape between manufacturers with dedicated European compliance teams and smaller entrants forced to outsource certification. Roland Corporation leverages its vertical integration across DSP chip design and final assembly to sustain margin control in premium workstation tiers. Yamaha Corporation anchors global volume through educational institutional contracts that lock in multi-year refresh cycles. Korg Inc. differentiates via compact form-factor specialization that navigates Japan's stringent electrical appliance recycling obligations.
A digital synthesizer is an electronic musical instrument that generates audio signals through digital signal processing, typically employing sample rates of 44.1 kHz or higher and polyphony counts ranging from 16 to 256 simultaneous voices for studio and stage applications. Subtractive architectures still dominate unit shipments among hobbyist buyers, while wavetable engines capture expanding share in sound design workflows where timbral morphing proves essential. FM synthesizers occupy a mature niche in retro-oriented production circles, though software-hardware hybrid implementations are repositioning this category for film scoring applications requiring precise harmonic control.
FCC Part 15 emissions compliance gates US market access for devices with wireless MIDI or Bluetooth connectivity, while Japan's Radio Law and METI technical standards impose parallel certification burdens on Asian manufacturers. The EU Green Deal's expanding scope for electronics durability standards is forcing redesign cycles that favor modular architectures and replaceable components. Stakeholders must monitor how divergent regulatory timelines across Washington, Brussels, and Tokyo reshape where R&D investment flows and which product architectures achieve cross-regional scale.
Market Dynamics
Modular hardware-software hybrid architectures are forcing incumbents to restructure R&D allocation as film scoring studios demand seamless DAW integration alongside tactile control surfaces.
Growth Catalysts
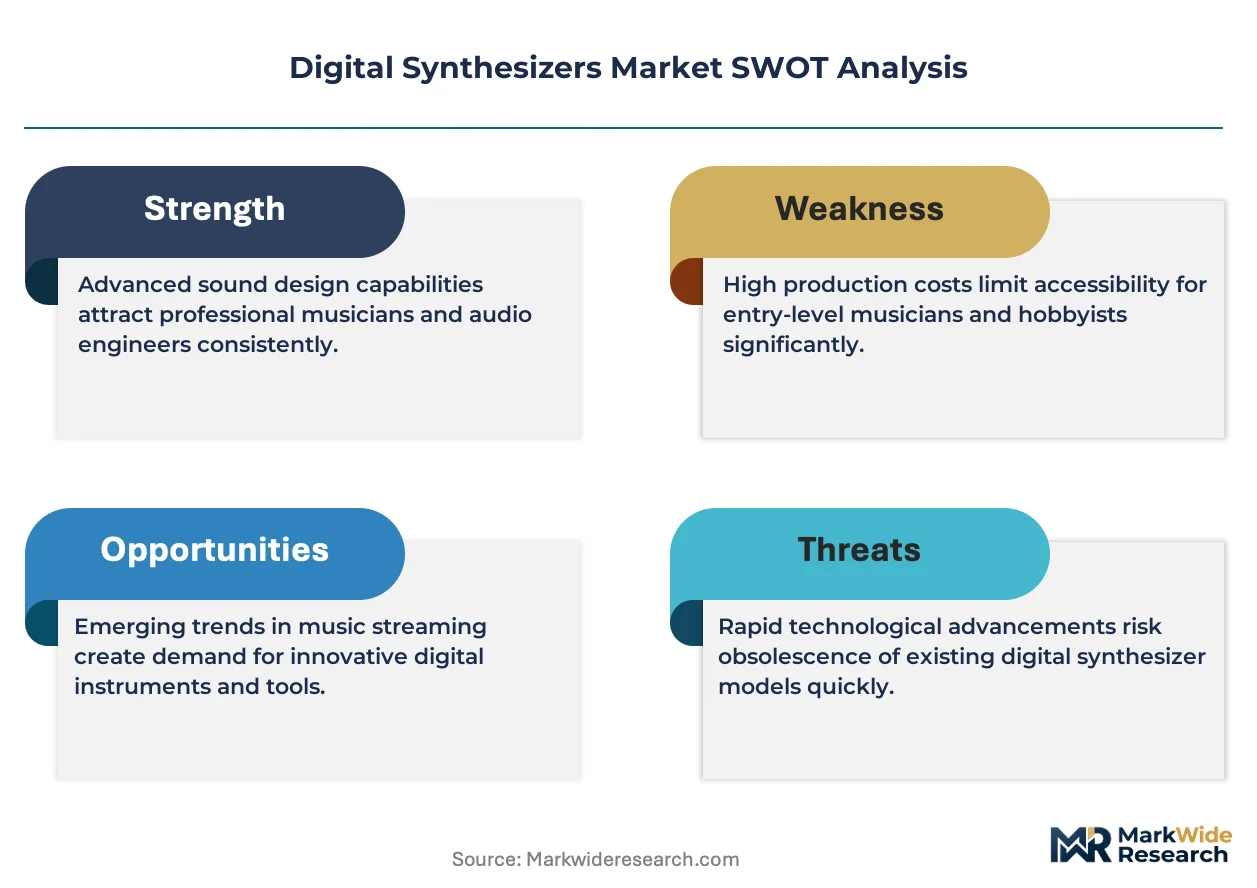
- EU Ecodesign for Sustainable Products Regulation:Mandates for replaceable power supplies and recyclable chassis materials are accelerating modular design adoption among European manufacturers.
- Educational institutional procurement:Multi-year refresh cycles for music technology programs in Japan and the United States lock in predictable hardware demand.
- Wavetable engine advancement:Timbre-morphing capabilities are displacing subtractive synthesis in sound design workflows for streaming content production.
Market Restraints
- DSP chip supply concentration:Fabrication capacity bottlenecks in Taiwan constrain polyphony scaling for premium workstation tiers.
- Parallel certification burdens:FCC Part 15, Japan Radio Law, and CE marking requirements under the Radio Equipment Directive extend time-to-market by 8-14 months for wireless-enabled models.
- Software emulation substitution:Native Instruments and Spectrasonics plugins replicate vintage hardware architectures at marginal cost.
Strategic Opportunities
- India's BIS certification pathway:Formalized electrical safety standards create first-mover advantage for brands establishing local assembly partnerships.
- Bluetooth LE Audio integration:Wireless MIDI latency below 10ms enables stage applications previously reserved for cabled connections.
- EU Green Deal durability standards:Modular architectures with field-replaceable keybeds and displays align with emerging repairability mandates.
Industry Challenges
- Analog circuit emulation expertise:Shortage of engineers proficient in modeling transistor saturation and filter nonlinearities delays product pipelines.
- Legacy system integration:DIN-sync and CV/gate compatibility requirements complicate firmware architecture for hybrid analog-digital instruments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Synthesizers Market |
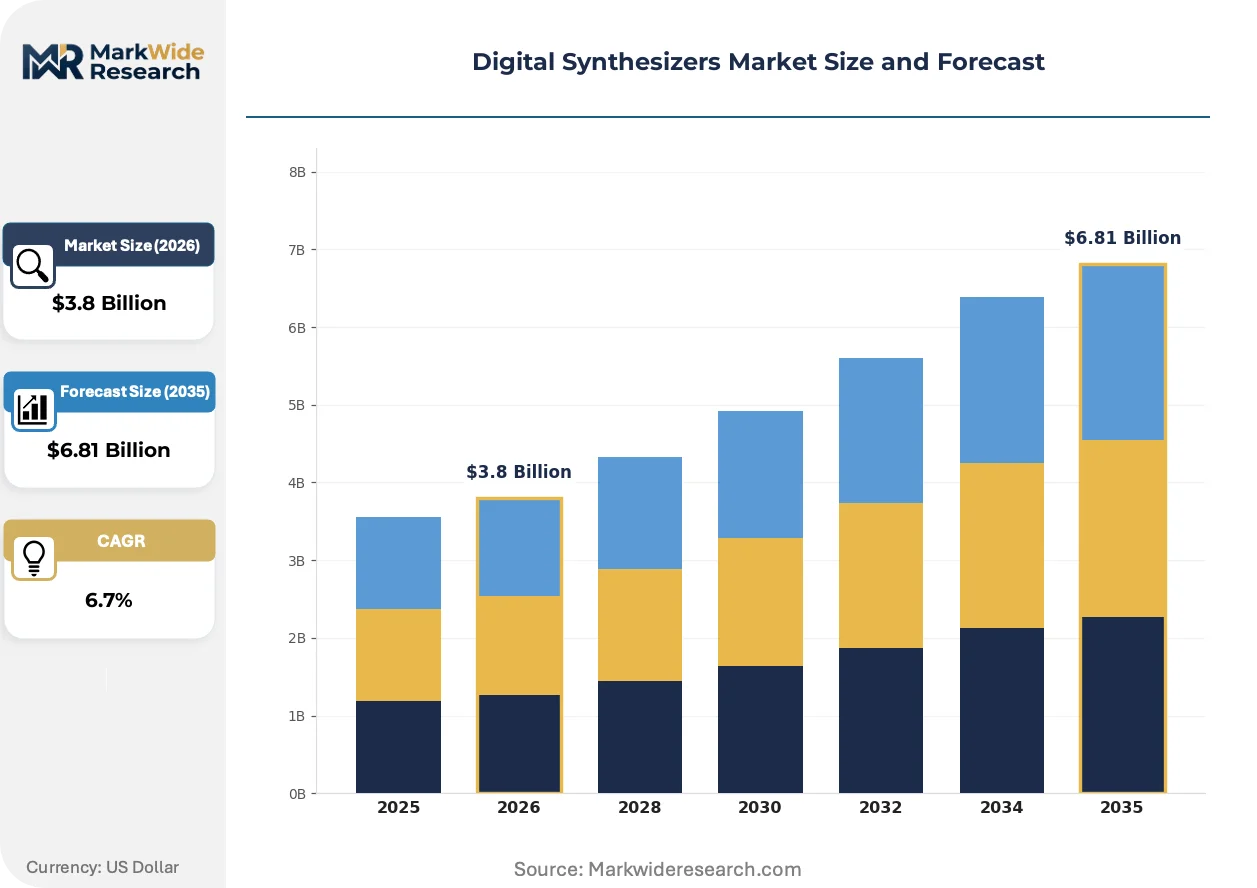
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Subtractive, Wavetable, FM Synthesizers Application: Music Production, Live Performance, Sound Design, Film Scoring End User: Professional Musicians, Audio Engineers, Hobbyists, Educational Institutions Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Rental Services |
| Companies Covered | Roland Corporation, Yamaha Corporation, Korg Inc., Moog Music Inc., Arturia SAS, Behringer, Native Instruments GmbH, Elektron, Nord, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Synthesizers Market Trends and Innovations
Physical modeling synthesis is migrating from academic research into commercial instruments as compute efficiency improves. This shift compresses the boundary between sample-based and algorithmic sound generation.
FPGA-based voice architectures are decomposing the traditional DSP-centric design paradigm. Boutique manufacturers in Berlin and Tokyo are adopting programmable logic for per-voice filter customization. This approach is decomposing economies of scale that previously favored ASIC-based designs from vertically integrated competitors.
The EU Green Deal's expanding electronics durability standards are forcing chassis redesign cycles. Manufacturers must now document mean-time-between-failure for encoders, keybeds, and display modules. Premium workstation tiers face the steepest compliance costs due to component density and repair access requirements.
Direct-to-consumer channel expansion is fragmenting traditional distributor relationships. Smaller manufacturers in the United States and Germany are bypassing regional music retailers through Kickstarter pre-orders and subscription-based sound pack ecosystems. Japan remains the exception, where physical instrument retail chains maintain cultural lock-in through hands-on demonstration floors.
Digital Synthesizers Market Segmentation
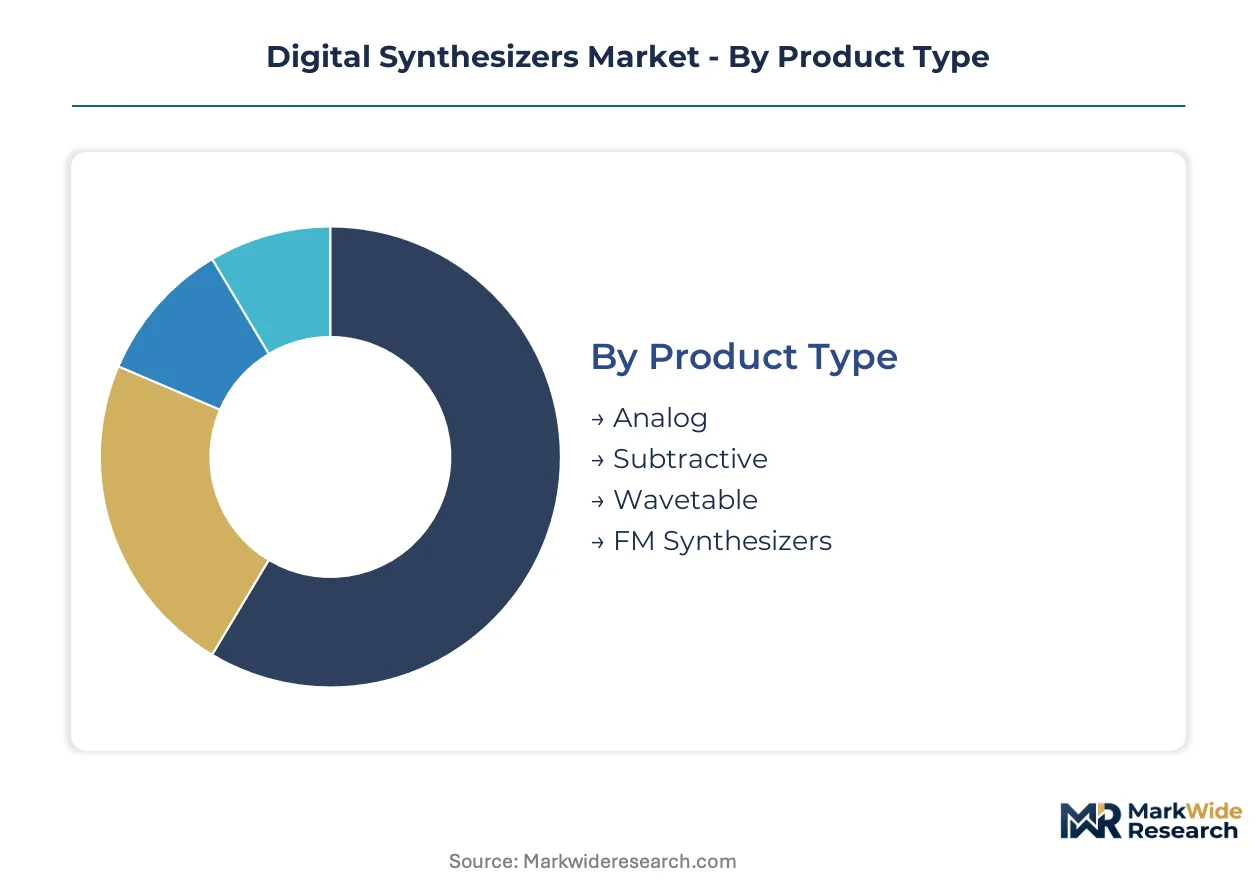
Segment boundaries in digital synthesizers reflect divergent certification requirements across wireless connectivity tiers and power supply architectures. Manufacturers must align product portfolios with distinct regulatory pathways rather than uniform global specifications.
Product Type:
FCC Part 15 emissions thresholds split development investment between cabled-only architectures and Bluetooth-enabled variants requiring extended validation cycles.
- Subtractive Synthesizers:Voltage-controlled filter emulations dominate hobbyist unit shipments due to intuitive signal-flow architecture. Los Angeles film scoring studios favor hardware implementations over software emulation for tactile real-time manipulation during orchestral recording sessions.
- Wavetable Synthesizers:Timbre-morphing engines operate at sample rates exceeding 44.1 kHz with 256-voice polyphony for streaming content production workflows. Japan's METI technical standards for electrical appliance recycling favor modular chassis designs that accommodate field-swappable wavetable ROM cartridges.
- Analog Synthesizers:Discrete transistor ladder filters require specialized fabrication partnerships with Japanese semiconductor foundries for matched component pairs.
- FM Synthesizers:Digital operator algorithms face substitution pressure from Native Instruments FM8 software emulation at marginal cost points.
Subtractive architectures handle the majority of throughput; wavetable configurations are expanding most quickly on share.
Application:
Cost tier stratification separates studio-grade workstations from stage-optimized performance units with hardened chassis and redundant power supplies.
- Music Production:DAW-integrated hardware controllers with motorized faders and OLED parameter displays anchor professional studio configurations. Educational institutions in Japan lock in multi-year refresh cycles through Yamaha institutional procurement contracts.
- Film Scoring:Hybrid analog-digital architectures demand DIN-sync and CV/gate compatibility for legacy modular system integration. London scoring stages require CE-marked wireless MIDI implementations under EU Radio Equipment Directive compliance timelines.
- Live Performance:Road-hardened enclosures with reinforced keybeds and spill-resistant surfaces target touring musician replacement cycles.
- Sound Design:Granular synthesis engines with real-time spectral manipulation serve post-production houses in Berlin and Tokyo.
Music production absorbs the dominant share of R&D allocation; film scoring shows the steepest expansion trajectory as streaming content budgets climb.
End User:
Customer type determines margin structure through volume scale and service attachment rates rather than hardware specifications alone.
- Professional Musicians:Touring artists prioritize sub-10ms Bluetooth LE Audio latency for stage freedom previously reserved for cabled connections. Roland's vertical integration across DSP design and final assembly sustains premium tier margin control for this segment.
- Educational Institutions:Multi-year refresh cycles for music technology programs in Japan and the United States generate predictable hardware demand with extended payment terms.
- Audio Engineers:Post-production professionals require calibrated frequency response documentation for studio monitor matching.
- Hobbyists:Entry-level purchasers drive subtractive architecture unit volumes through online retail channels with minimal service revenue attachment.
Educational institutions anchor volume throughput; professional musicians command the highest per-unit margin contribution.
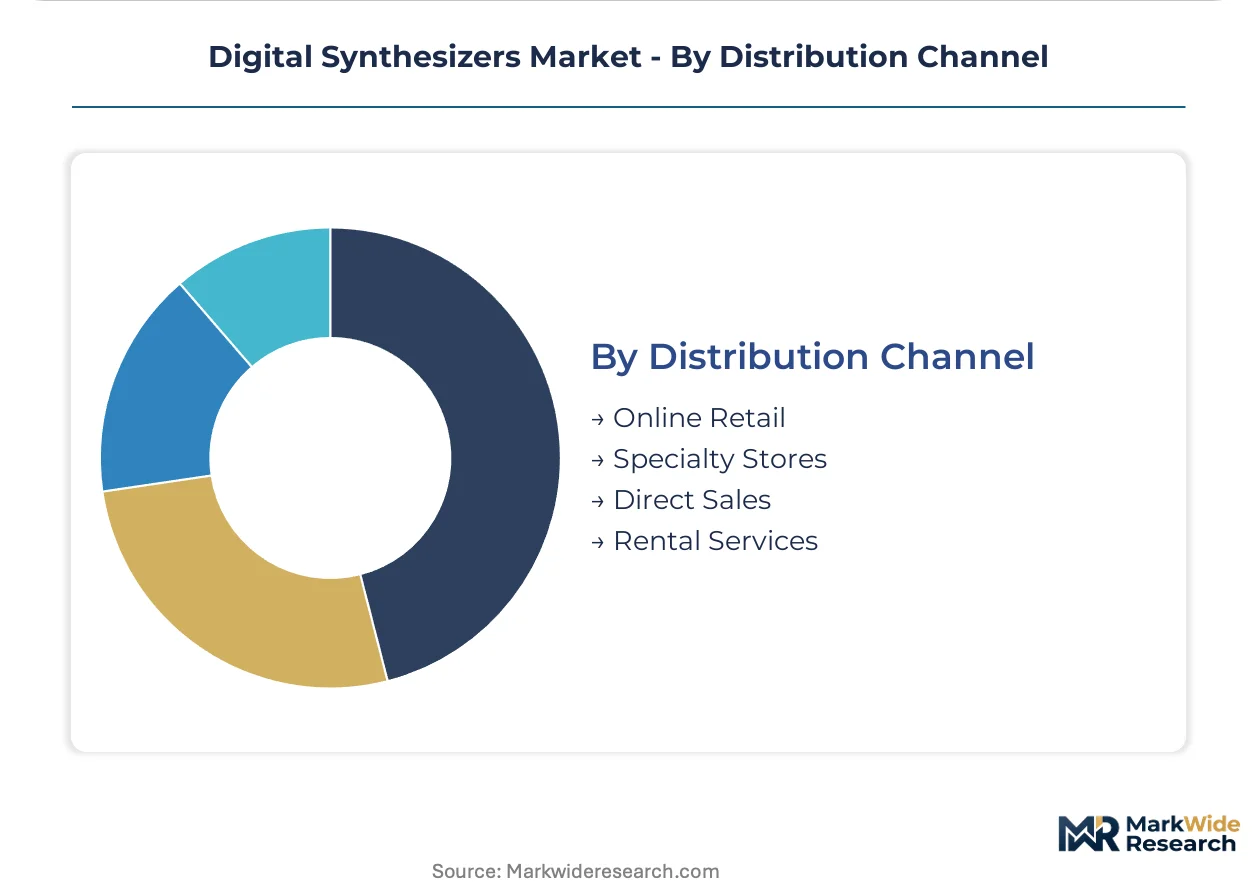
Distribution Channel:
Supply concentration in Taiwan for FPGA voice architectures favors direct manufacturer relationships over distributor intermediaries for technical support depth.
- Online Retail:Kickstarter pre-orders and subscription-based sound pack ecosystems enable smaller German and United States manufacturers to bypass traditional music retailer markups.
- Specialty Stores:Japan's physical instrument retail chains maintain cultural lock-in through hands-on demonstration floors that software emulation cannot replicate.
- Direct Sales:Enterprise procurement for film scoring studios in Los Angeles and London bypasses retail markup for volume workstation deployments.
- Rental Services:Festival and tour logistics providers in Nashville and Manchester handle depreciation risk for short-term professional engagements.
Online retail channels are gaining share fastest; specialty stores retain defensive positioning in Japan's domestic market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 15 emissions standards in the United States, Japan's Radio Law compliance timelines, and the EU Green Deal's durability mandates are redrawing where manufacturers concentrate R&D investment and certification resources. These regulatory divergences fragment product architectures and reshape competitive positioning across major demand centers.
United States
Los Angeles film scoring studios drive premium hardware procurement for tactile orchestral recording workflows. FCC Part 15 certification gates market access for Bluetooth-enabled stage instruments, extending validation cycles. Nashville's touring musician ecosystem sustains replacement demand for road-hardened performance synthesizers with redundant power supplies.
Japan
Domestic supply chain depth at Roland and Yamaha anchors cultural preference for physical instruments over software emulation. METI technical standards and electrical appliance recycling obligations favor modular chassis designs with field-replaceable components. Tokyo's educational institutional procurement locks in multi-year refresh cycles through volume contracts.
Germany
Post-production houses in Berlin adopt granular synthesis engines for streaming content sound design workflows. CE marking under the EU Radio Equipment Directive bifurcates compliance capabilities between established manufacturers and smaller entrants. Bavaria's boutique FPGA specialists decompose traditional DSP-centric design paradigms for per-voice filter customization.
United Kingdom
London scoring stages require CE-marked wireless MIDI implementations under EU Radio Equipment Directive timelines despite post-Brexit regulatory divergence. Educational technology programs in Manchester and Birmingham generate predictable institutional demand. British rental services handle depreciation risk for festival and touring professional engagements.
India
BIS certification formalization for electrical safety standards creates first-mover advantage for brands establishing local assembly partnerships. Music technology education expansion in Mumbai and Bangalore drives entry-level subtractive synthesizer demand. Domestic procurement channels remain underdeveloped, favoring online retail penetration over specialty store networks.
Digital Synthesizers Market Competitive Landscape
Listed leaders compete with private specialists across certification capability and vertical integration depth, producing a tiered structure where scale advantages clash with boutique agility. The vendor base concentrates around three strategic archetypes: vertically integrated workstation manufacturers, compact form-factor specialists, and software-hardware hybrid platforms. Capacity expansion in FPGA voice architectures and strategic partnerships for DSP chip supply security represent the dominant competitive moves.
Among Japanese incumbents, Roland Corporation exemplifies vertical integration across DSP design and final assembly, while Yamaha Corporation anchors global volume through educational institutional relationships. Korg Inc. occupies a position within the compact specialization tier, navigating stringent domestic recycling obligations through modular chassis engineering.
| Leading Market Players |
|---|
| Roland Corporation |
| Yamaha Corporation |
| Korg Inc. |
| Moog Music Inc. |
| Arturia SAS |
| Behringer |
| Native Instruments GmbH |
| Elektron |
| Nord |
| Others |
Pricing and Supply Chain Analysis
FCC Part 15 emissions compliance gates US market access for Bluetooth-enabled instruments while simultaneously stratifying price tiers between cabled-only architectures and wireless-validated variants. This regulatory threshold concentrates margin capture among manufacturers with dedicated certification teams, forcing smaller entrants into outsourced validation that compresses pricing flexibility.
Pricing Analysis
Certification level creates the primary spread between premium wireless workstations and entry-level cabled units. Three-tier pricing structure across premium, standard, and economy levels reflects polyphony count, chassis modularity, and after-sales service bundling. Cost compression in entry-level subtractive synthesizers intensifies as software emulation from Native Instruments and Spectrasonics replicates vintage architectures at marginal cost points. Educational institutions exhibit lowest price sensitivity due to multi-year procurement contracts, while hobbyist buyers drive volume through online retail channels with minimal service attachment.
Supply Chain Analysis
Taiwan Strait fabrication bottlenecks constrain DSP chip supply for premium workstation tiers, forcing Roland and Yamaha to secure multi-year foundry allocations. Voice architecture production draws from Taiwan for ASIC fabrication, Japan for discrete analog component matching, and Germany for FPGA programmable logic specialization. Single-source vulnerability concentrates in 5nm-class DSP wafer supply, with earthquake risk at Hsinchu Science Park threatening polyphony scaling roadmaps. Distribution runs through direct manufacturer relationships for enterprise film scoring deployments, while specialty retail chains anchor Japan's domestic channel structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital synthesizer demand follows cyclical refresh patterns tied to educational institutional procurement calendars and touring musician replacement cycles. Post-pandemic return to live performance is accelerating hardware procurement from Nashville and London rental services.
For Market Incumbents: Shield premium tier margins by accelerating backward integration into FPGA voice architecture design, reducing dependence on Taiwan foundry allocation cycles. Secure DIN-sync and CV/gate compatibility patents to complicate firmware architecture for hybrid analog-digital entrants. Software emulation from Spectrasonics and Native Instruments threatens hardware attachment rates in home studio segments.
For New Entrants and Emerging Players: Lead with India's BIS certification pathway to establish local assembly partnerships before formalized electrical safety standards mature. Target granular synthesis engines for Berlin and Tokyo post-production houses where timbral morphing commands premium positioning. Kickstarter pre-orders with subscription-based sound pack ecosystems bypass traditional retailer markups and build direct customer relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across FPGA-based boutique manufacturing as programmable logic displaces ASIC economies of scale. Long-term viability favors modular architecture specialists with documented mean-time-between-failure compliance for EU Green Deal durability mandates. Monitor Bluetooth LE Audio latency benchmarks below 10ms as the signal indicating stage-application market readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Architecture Redesign | EU Green Deal durability mandates force field-replaceable component documentation for premium workstations. |
| Bluetooth LE Audio Integration | Sub-10ms wireless MIDI latency unlocks stage applications previously reserved for cabled connections. |
| Educational Institutional Procurement | Multi-year refresh cycles in Japan and the United States generate predictable hardware demand with extended payment terms. |
| FPGA Voice Architecture Adoption | Programmable logic decomposes ASIC scale advantages for Berlin and Tokyo boutique manufacturers. |
| Direct-to-Consumer Channel Expansion | Kickstarter pre-orders and subscription sound packs fragment traditional distributor relationships in the United States and Germany. |
Research Methodology
A spread of perspectives from DSP chip procurement managers, film scoring studio technical directors, educational institutional buyers, and musical instrument retail category heads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FCC Part 15 filings, METI technical standard registrations, EU Radio Equipment Directive certification databases, and customs trade records for semiconductor component flows. Bottom-up shipment triangulation across subtractive, wavetable, and FM architecture categories was cross-checked against top-down value estimates from manufacturer revenue disclosures.
Segmentation dimensions modeled include synthesis architecture type, wireless connectivity tier, application workflow, end-user category, and distribution channel structure across the projection horizon. CAGRs were derived from weighted average growth trajectories across these dimensions, with particular sensitivity to educational procurement cycle timing and film scoring studio hardware refresh patterns. FPGA adoption curves and software emulation substitution rates served as industry-specific forecast inputs.
Underlying assumptions cover sustained Taiwan foundry allocation stability, EU Ecodesign implementation timelines, and Bluetooth LE Audio chipset availability, with deviation risk concentrated in DSP supply disruption and regulatory divergence across Washington, Brussels, and Tokyo. Revision becomes warranted when wireless MIDI certification timelines extend beyond 14 months or when educational procurement budgets contract below replacement cycle maintenance levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Electronic Weighing Machines Market
Electronic Devices & Electrical Systems
Global Automotive Electronic Devices Market
Electronic Devices & Electrical Systems
USB Devices Market
Electronic Devices & Electrical Systems
Global Sequence of Events Recorder Market
Electronic Devices & Electrical Systems
Multi-Effects Processor Market
Electronic Devices & Electrical Systems
Blu-Ray Media and Devices Market
Electronic Devices & Electrical Systems
Electronic Latching System Market
Electronic Devices & Electrical Systems
Electronic Skin Market
Electronic Devices & Electrical Systems
Smart Wiring Devices Market
Electronic Devices & Electrical Systems
Electronic Load Market
Electronic Devices & Electrical Systems
Intelligent Electronic Devices Market
Electronic Devices & Electrical Systems
High Current Springs Market
Electronic Devices & Electrical Systems
Function Generator Market
Electronic Devices & Electrical Systems
Global Hybrid Devices Market
Electronic Devices & Electrical Systems
Global Volt/VAR Management Market
Electronic Devices & Electrical Systems
Workstation Market