
 Time and Attendance Software Market | 2026-2036
Time and Attendance Software Market Size, Share, and Industry Trends Forecast 2026-2036
Time and Attendance Software Market Intelligence
EU GDPR compliance around employee biometric data is hardening requirements for consent management and audit trails across European deployments. UKG leverages its workforce management heritage to compete on integrated compliance architectures. ADP, Inc. anchors North American payroll-attendance convergence through embedded tax engines. SAP SE extends its ERP dominance by bundling time modules into broader human capital management suites.
Time and attendance software automates labor hour capture, absence tracking, and shift scheduling through biometric terminals, mobile geofencing, or web-based punch interfaces, typically integrating with payroll and ERP systems via API protocols. Cloud-based deployment leads new procurement cycles as SMEs abandon on-premises maintenance burdens for subscription elasticity. Biometric tracking features command premium positioning where Manufacturing and Healthcare verticals face strict OSHA and FDA workforce accountability requirements.
The US Department of Labor enforces Fair Labor Standards Act recordkeeping through audit-ready digital logs, while EU GDPR and Germany's Federal Data Protection Act constrain biometric storage architectures. India's proposed Digital Personal Data Protection Bill will reshape how multinationals configure cloud instance residency for South Asian workforces. Stakeholders must weigh regulatory fragmentation against platform consolidation when selecting deployment architectures.
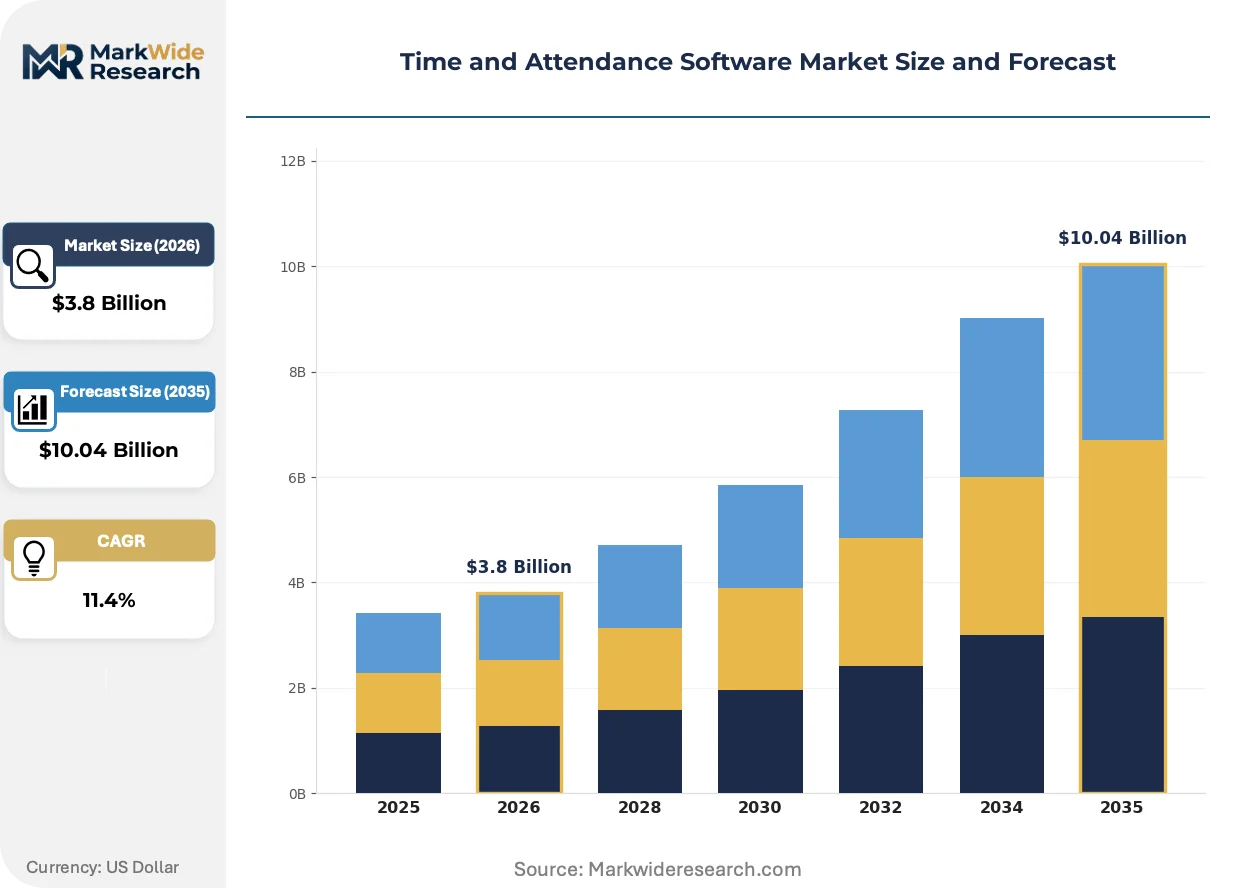
Market Dynamics
Workforce digitization mandates across healthcare and manufacturing verticals are compressing replacement cycles for legacy punch-clock systems, forcing buyers toward biometric and geofencing architectures that satisfy audit-ready compliance requirements.
Growth Catalysts
- OSHA Recordkeeping Mandates:US healthcare systems face intensified workforce accountability requirements, accelerating biometric terminal deployment across hospital networks and long-term care facilities.
- GDPR Consent Frameworks:European employers must implement granular audit trails for biometric data storage, creating structured demand for consent-management modules.
- Cloud Subscription Elasticity:SMEs across Germany and France are abandoning on-premises maintenance burdens in favor of SaaS deployment models with API-native payroll integration.
Market Restraints
- Biometric Hardware Cost Concentration:Fingerprint and facial recognition terminal supply concentrates among East Asian component fabricators, exposing buyers to input cost volatility and extended lead times.
- Data Residency Fragmentation:India's proposed Digital Personal Data Protection Bill and divergent EU member-state implementations force multinationals to maintain geographically siloed cloud instances, inflating architectural complexity.
- Legacy System Entrenchment:Decades-old punch-clock infrastructure in US manufacturing and logistics facilities creates technical debt that slows cloud migration timelines and integration budgets.
Strategic Opportunities
- Mobile Geofencing Expansion:Construction and field services segments in Australia and Canada remain underpenetrated by automated attendance capture, presenting white space for GPS-boundary solutions.
- AI-Driven Scheduling Convergence:Machine learning algorithms for predictive shift optimization are merging with core time-capture platforms, enabling new pricing tiers for workforce analytics.
- API Ecosystem Integration:Embedded connectivity with ERP and HCM suites creates channel opportunities through system integrators and vertical-specific deployment partners.
Industry Challenges
- Biometric Data Security Expertise Gap:Mid-market employers lack in-house cybersecurity talent to configure encryption standards and breach-response protocols for fingerprint and facial templates.
- Multi-Jurisdiction Compliance Synchronization:Multinationals must reconcile Germany's Federal Data Protection Act constraints with US state-level biometric privacy laws, complicating single-platform deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Time and Attendance Software Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, Mobile Customer Type: SMEs, Large Enterprises, Educational Institutions, Government Agencies Feature: Biometric Tracking, Mobile Access, Reporting Tools, Integration Capabilities Industry Vertical: Retail, Healthcare, Manufacturing, Hospitality |
| Companies Covered | UKG, ADP, Inc., Workday, Inc., SAP SE, Oracle Corporation, Dayforce, Inc., Paycom Software, Inc., Paylocity, ATOSS Software AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Time and Attendance Software Market Strategic Shifts & Innovations
Biometric authentication architectures are merging with workforce analytics platforms, compressing the boundary between time capture and predictive labor optimization. This convergence is restructuring vendor competitive positioning and buyer procurement evaluation criteria.
Facial recognition terminals with liveness detection are converging with thermal scanning modules for health screening, creating unified workforce entry points. Healthcare systems in the United States are adopting these combined units at accelerated pace to satisfy both attendance accuracy and infection-control protocols. This fusion is enabling premium pricing tiers that bundle access control, time capture, and wellness monitoring into single capital expenditures.
EU GDPR enforcement actions against employers for inadequate biometric consent documentation are hardening audit requirements across member states. France's CNIL and Germany's data protection authorities have issued specific guidance on employee notification and withdrawal mechanisms. Manufacturing and logistics employers with cross-border workforces are responding by procuring platforms with built-in consent workflow engines and automated retention-deletion schedules.
Buyer evaluation cycles are compressing as finance and HR stakeholders jointly mandate total-cost-of-ownership analyses that include integration labor and compliance risk. Large employers in the United Kingdom are replacing siloed time-tracking evaluations with unified workforce management platform selections. This behavioral shift favors vendors with pre-certified SAP and Oracle connectors over point-solution specialists lacking ERP ecosystem depth.
Time and Attendance Software Market Segmentation
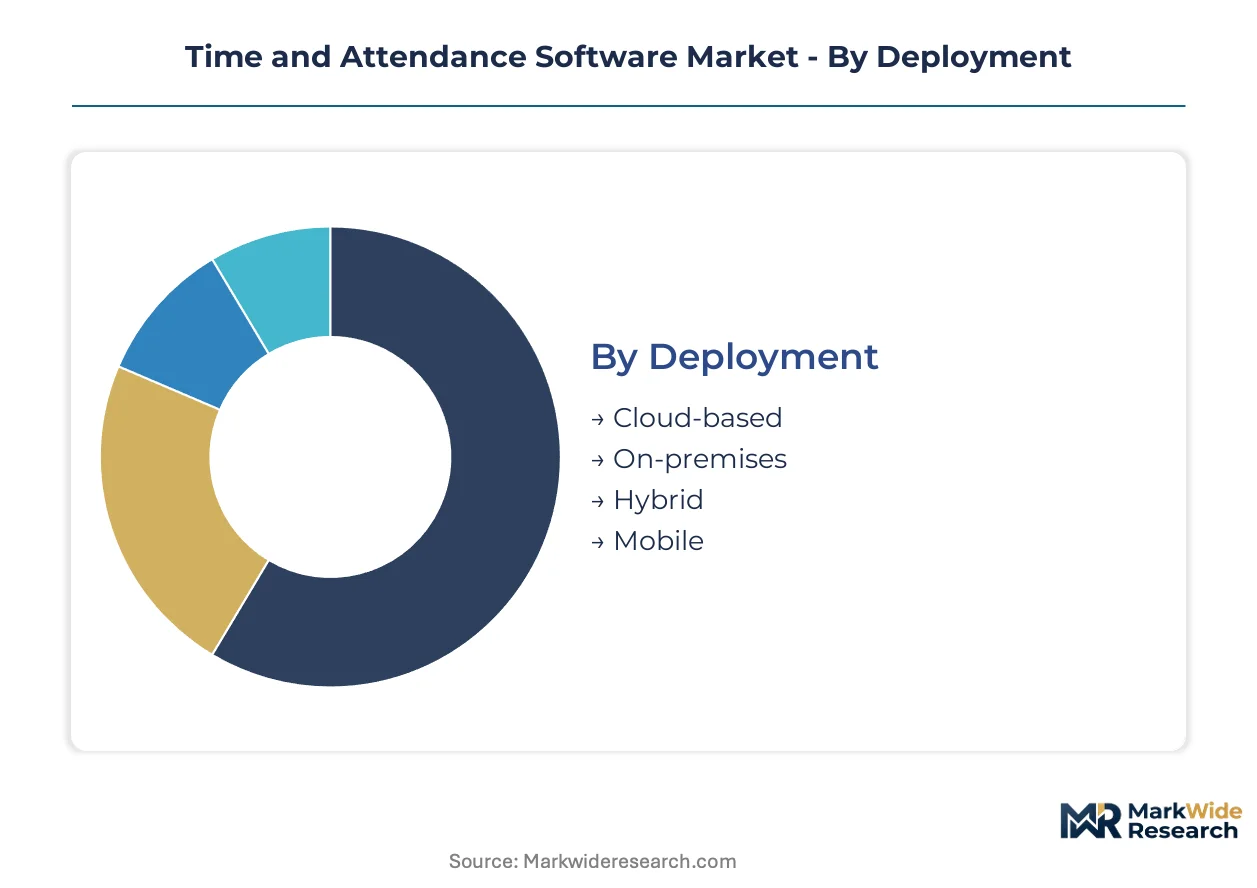
Deployment architecture and customer scale fundamentally reshape vendor pricing power and integration complexity in time and attendance software. Biometric feature depth and vertical regulatory exposure further stratify competitive positioning across buyer segments.
Deployment:
Cloud infrastructure concentration among hyperscale providers is compressing SaaS delivery costs while fragmenting data residency compliance architectures.
- Cloud-based:Multi-tenant architectures with API-native payroll connectors dominate new procurement cycles. US healthcare systems and German manufacturing SMEs are migrating from legacy systems to subscription models that offload infrastructure maintenance and accelerate OSHA-compliant audit trails.
- On-premises:Single-tenant installations persist where air-gapped security or custom ERP integration requirements override cloud elasticity. Defense contractors and critical infrastructure operators in France and Japan maintain captive server farms to satisfy national cybersecurity frameworks.
- Hybrid:Split configurations synchronize edge biometric terminals with cloud analytics layers, accommodating mixed regulatory jurisdictions. Multinationals operating across EU GDPR zones and US state biometric laws deploy this architecture to localize sensitive template storage.
- Mobile:GPS geofencing and smartphone punch interfaces serve distributed field workforces without fixed terminal infrastructure. Construction and logistics operators in Australia and Canada are expanding deployment of boundary-based attendance capture.
Cloud-based deployments absorb the bulk of installed capacity; mobile solutions are expanding most quickly.
Customer Type:
Procurement sophistication and compliance risk exposure scale directly with organizational headcount and regulatory scrutiny intensity.
- SMEs:Subscription elasticity and rapid deployment without IT specialization drive adoption. French and German mid-market manufacturers are abandoning spreadsheet-based tracking for SaaS platforms with pre-configured GDPR consent workflows.
- Large Enterprises:Global HCM suite integration and multi-jurisdiction compliance synchronization dominate evaluation criteria. UK-based multinationals are consolidating siloed time-tracking systems into unified workforce management platforms with SAP-certified connectors.
- Educational Institutions:Semester-based scheduling complexity and student-worker hour limits create specialized absence-tracking requirements. US universities deploy biometric terminals to manage research grant labor accountability.
- Government Agencies:Civil service rule engines and public audit transparency mandates necessitate hardened retention architectures. Federal contractors in the United States maintain DOL-inspection-ready digital logs with immutable timestamp verification.
Large enterprises command the deepest integration budgets; SMEs are climbing the fastest as cloud accessibility erodes historical barriers.
Feature:
Biometric hardware supply concentration in East Asian component markets is inflating feature premiums and extending procurement lead times.
- Biometric Tracking:Fingerprint and facial recognition terminals with liveness detection satisfy FDA and OSHA workforce accountability mandates. US hospital networks are deploying combined thermal scanning units that fuse attendance capture with infection-control protocols.
- Mobile Access:Smartphone-based punch interfaces with geofencing boundaries serve distributed workforces without fixed infrastructure investment. Field services segments in Canada and Australia remain underpenetrated by automated capture solutions.
- Reporting Tools:Pre-configured audit trails and customizable dashboards address DOL Fair Labor Standards Act recordkeeping requirements. HR stakeholders in the United Kingdom are mandating total-cost-of-ownership analyses that include compliance risk quantification.
- Integration Capabilities:API-native connectivity with ERP and payroll systems eliminates manual data re-entry and reconciliation errors. German employers prioritize platforms with ATOSS-compatible connectors to preserve existing workforce management investments.
Biometric tracking absorbs the bulk of feature investment; mobile access is gaining share fastest as distributed work models normalize.
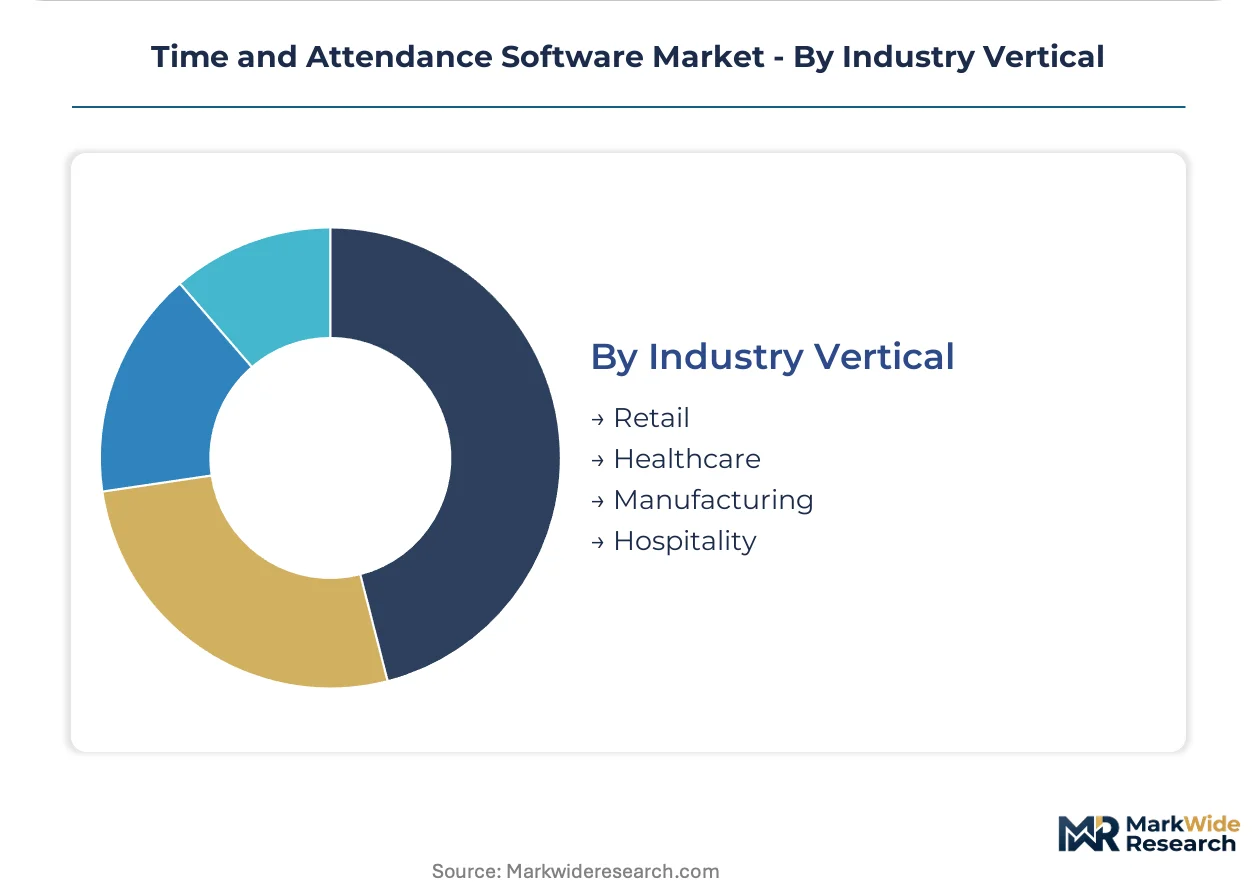
Industry Vertical:
Regulatory enforcement intensity and workforce digitization maturity create divergent replacement cycles across end-use sectors.
- Retail:High-turnover hourly workforces and multi-location coordination drive demand for rapid onboarding and shift-swapping functionality. US and UK retail chains are deploying mobile-first platforms to accommodate gig-economy scheduling flexibility.
- Healthcare:Joint Commission accreditation requirements and OSHA recordkeeping mandates enforce biometric accountability for clinical staff. Hospital networks across the United States are replacing legacy badge systems with facial recognition terminals.
- Manufacturing:Shift-based production schedules and union contract compliance create complex overtime calculation requirements. German automotive suppliers integrate time modules directly into SAP ERP suites to maintain labor cost visibility.
- Hospitality:Seasonal demand volatility and tip-credit wage calculations necessitate granular hour tracking with audit-ready documentation. French hotel chains are implementing GDPR-compliant consent workflows for biometric data collection.
Healthcare commands the steepest compliance-driven investment; hospitality is expanding most quickly as post-pandemic service recovery accelerates workforce rebuilding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors cloud-native workforce management development, with SaaS providers clustering along the Peninsula corridor to serve distributed enterprise clients.
United States
Hospital networks in Texas and Florida are replacing legacy badge systems with biometric terminals to satisfy OSHA recordkeeping mandates. The Department of Labor enforces Fair Labor Standards Act compliance through audit-ready digital logs. Healthcare systems across the Sun Belt are deploying combined thermal scanning and facial recognition units at facility entry points.
Germany
Automotive suppliers in Stuttgart and Munich are integrating time modules directly into SAP ERP suites. The Federal Data Protection Act constrains biometric storage architectures, forcing granular consent workflows. ATOSS Software AG anchors regional competition from its Munich base, serving mid-market manufacturers abandoning on-premises maintenance.
United Kingdom
Large employers in London are consolidating siloed time-tracking systems into unified workforce management platforms. GDPR enforcement actions from the Information Commissioner's Office harden audit requirements for biometric consent documentation. Financial services firms in the City are mandating total-cost-of-ownership analyses that include compliance risk quantification.
India
IT services campuses in Bengaluru and Hyderabad are expanding cloud-based attendance capture for hybrid workforces. The proposed Digital Personal Data Protection Bill will reshape cloud instance residency configurations for South Asian operations. Multinationals are maintaining geographically siloed deployments to satisfy emerging data localization requirements.
Australia
Construction and mining operators in Western Australia are deploying GPS geofencing solutions for remote site workforces. The Fair Work Ombudsman enforces recordkeeping standards through digital audit trails. Field services segments remain underpenetrated by automated capture, presenting expansion opportunities for mobile-first platforms.
Time and Attendance Software Market Key Industry Players
The competitive structure tilts toward ERP-integrated suite providers with pre-certified connectors. Consolidation pressure favors vendors bundling time modules into broader human capital management platforms. Three archetypes dominate: payroll-native incumbents with embedded tax engines, ERP-extenders leveraging certified ecosystem connectivity, and cloud-native specialists with API-first architectures. Dominant competitive moves include strategic partnerships with system integrators and vertical-specific deployment alliances.
Among payroll-native incumbents, ADP, Inc. and Paycom Software, Inc. exemplify the convergence of tax engine depth with attendance automation. UKG occupies a position within the integrated compliance architecture tier, leveraging workforce management heritage. ATOSS Software AG represents the regional specialist archetype, anchoring German-speaking market procurement discussions through localized deployment expertise.
| Leading Market Players |
|---|
| UKG |
| ADP, Inc. |
| Workday, Inc. |
| SAP SE |
| Oracle Corporation |
| Dayforce, Inc. |
| Paycom Software, Inc. |
| Paylocity |
| ATOSS Software AG |
| Others |
Cost & Logistics Intelligence
Healthcare procurement mandates for OSHA-compliant biometric terminals are forcing software vendors to absorb hardware cost volatility while maintaining subscription price stability. European GDPR consent workflow requirements add implementation service premiums that cloud-native providers must bundle without breaking mid-market price thresholds.
Pricing Analysis
Outcome-based pricing anchored to audit-ready compliance certification commands sustained premiums in regulated verticals. Three-tier pricing structure across premium, standard, and economy levels stratifies by biometric hardware inclusion, API integration depth, and managed service bundling. Cost compression in the economy tier intensifies because hyperscale cloud infrastructure commoditizes base SaaS delivery. Mid-market SMEs exhibit highest price sensitivity, while hospital networks and federal contractors accept premium positioning for liability reduction.
Supply Chain Analysis
Fingerprint and facial recognition sensor supply rests on Taiwanese semiconductor fabricators, South Korean image sensor specialists, and Chinese terminal assembly operations. Cloud infrastructure draws from hyperscale data center operators across the United States, Ireland, and Singapore. Single-source vulnerability concentrates in East Asian biometric component fabrication, exposing buyers to extended procurement timelines. Distribution runs through system integrators and vertical-specific deployment partners rather than direct software licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric hardware supply concentration props software pricing by limiting rapid feature commoditization. Capacity bottlenecks in East Asian component markets sustain vendor negotiation leverage against margin erosion.
For Market Incumbents: Lock in long-term supply agreements with Taiwanese sensor fabricators to insulate against lead time volatility. Deepen API certification investments with SAP and Oracle to entrench ecosystem switching costs against cloud-native challengers. Prioritize German and US healthcare verticals where compliance complexity creates durable pricing power. For New Entrants and Emerging Players: System integrators specializing in construction and field services represent the most accessible channel partnership archetype. White space concentrates in Australian mining operations and Canadian logistics networks where GPS geofencing penetration remains limited. A mobile-first deployment angle bypasses capital-intensive biometric terminal competition. For Investors and Strategic Acquirers: The window for entry favors cloud-native specialists with pre-built GDPR consent engines and healthcare compliance certifications. Long-term viability hinges on platform consolidation into broader HCM suites rather than standalone point solutions. Watch for OSHA enforcement intensity as the inflection indicator accelerating replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Hardware Supply Agreement | Long-term sensor contracts with Taiwanese fabricators reduce cost volatility exposure. |
| GDPR Consent Workflow Certification | Pre-certified audit engines accelerate European healthcare procurement cycles. |
| SAP ERP Connector Development | Certified integration preserves incumbent positioning in German manufacturing accounts. |
| Mobile Geofencing Platform Launch | GPS-boundary solutions capture underpenetrated Australian construction segments. |
| Strategic Partnership with System Integrators | Channel alliances with vertical specialists accelerate field services penetration. |
Research Approach
SEC filings, hyperscaler infrastructure disclosures, and EU regulatory guidance documents formed the secondary backbone for market sizing validation. Primary interviews with workforce management software executives, hospital procurement directors, German manufacturing IT leads, and system integration specialists combined with bottom-up and top-down triangulation to anchor segmentation assumptions.
Historical trendline analysis across deployment model adoption curves informed the projection framework. Segmentation dimensions modeled include cloud versus on-premises architecture, organization scale tier, vertical regulatory exposure, biometric feature depth, and regional compliance pattern. CAGRs derived from fitted growth curves incorporating cloud subscription elasticity and biometric hardware replacement cycles across the analysis window.
Caveats apply where India's Digital Personal Data Protection Bill implementation or EU GDPR enforcement intensity shifts could materially shift the outlook. Forecasts reflect assumptions about healthcare OSHA mandate continuity and East Asian component supply stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Construction and Design Software Market
Software & Services
Global Application Management Services Market
Software & Services
Adaptive Learning Software Market
Software & Services
Product Optimization Software Market
Software & Services
Global Online Community Management Software Market
Software & Services
Global Server Management Software Market
Software & Services
Email Applications Market
Software & Services
Russian IT Software and Services Market
Software & Services
Custom Software Development Market
Software & Services
Open Stack Service Market
Software & Services
Category Management Software Market
Software & Services
Partner Ecosystem Platform Software Market
Software & Services
Global Storm Tracking Apps Market
Software & Services
Global Ad Server Software Market
Software & Services
Visitor Identification Software Market
Software & Services
Labor Management Software Market