
 Global Application Management Services Market | 2026-2036
Global Application Management Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Application Management Services Market Analysis
Modular service bundling is recalibrating how enterprises procure application support, shifting from monolithic annual contracts toward componentized SLAs that separate infrastructure monitoring from code-level maintenance. Accenture leverages its multi-cloud orchestration capabilities to anchor premium engagements across North American financial institutions. Deloitte competes through embedded compliance advisory within its AMS retainers, while Cognizant specializes in legacy modernization workstreams that reduce technical debt for manufacturing clients.
Application management services encompass the ongoing monitoring, optimization, incident resolution, and lifecycle governance of software applications across enterprise environments, typically delivered through remote operations centers with defined mean-time-to-resolution thresholds and automated remediation protocols. Enterprise applications command the largest share of contracted value due to their integration complexity and regulatory exposure, while cloud services represent the fastest-expanding category as organizations repatriate workloads from aging data centers. Public cloud deployment models attract the highest growth velocity among delivery options, though hybrid architectures retain margin superiority given their customization requirements and dedicated engineering coverage.
The EU AI Act, GDPR, and ISO 27001 standards collectively elevate compliance costs for AMS providers serving European-headquartered clients, creating certification barriers that favor established operators with dedicated risk management practices. India's BIS cybersecurity guidelines and the US SEC disclosure rules for material cybersecurity incidents further fragment regulatory requirements across delivery geographies. Stakeholders must evaluate whether their governance frameworks can accommodate divergent jurisdictional mandates without fragmenting service consistency.
Market Dynamics
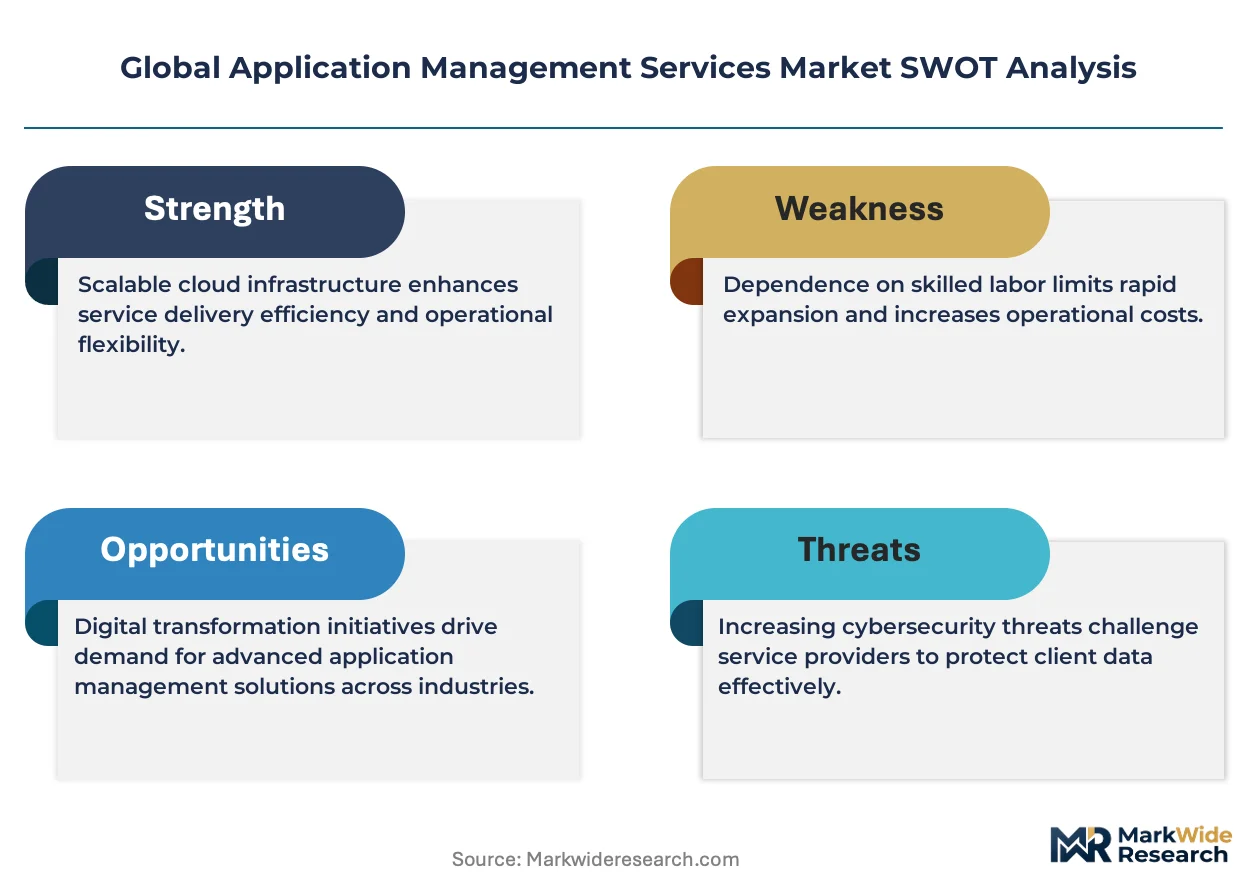
Modular service bundling is fragmenting traditional annual contracts into componentized SLAs, forcing providers to unbundle infrastructure monitoring from code-level maintenance and price each layer separately. This structural decomposition is compressing margins for monolithic vendors while rewarding specialists with discrete technical competencies.
Growth Catalysts
- EU AI Act compliance mandates:European-headquartered enterprises must embed algorithmic governance into application lifecycles, creating sustained demand for compliance-integrated AMS retainers.
- Cloud repatriation from aging data centers:Financial services institutions in the United States are accelerating workload migration to public cloud environments, requiring continuous optimization and incident resolution services.
- ISO 27001 certification requirements:India's BIS cybersecurity guidelines and global information security standards are elevating procurement thresholds, favoring established operators with dedicated risk management practices.
Market Restraints
- Specialized engineering talent scarcity:Deep expertise in legacy COBOL and mainframe systems commands premium compensation, inflating delivery costs for manufacturing sector modernization projects.
- Regulatory fragmentation across delivery geographies:Divergent compliance requirements between GDPR in Europe, SEC disclosure rules in the United States, and BIS guidelines in India fragment service consistency and elevate governance overhead.
- Hybrid cloud complexity premiums:Custom integration requirements for hybrid architectures retain margin superiority but constrain scalability compared to standardized public cloud offerings.
Strategic Opportunities
- Technical debt reduction workstreams:Manufacturing clients in Germany seek legacy modernization services that streamline aging application portfolios and reduce maintenance burden.
- Embedded compliance advisory services:EU AI Act and GDPR convergence creates white space for providers bundling regulatory interpretation with operational support.
- AI-driven automated remediation:Convergence of machine learning with robotic process automation enables predictive incident resolution, compressing mean-time-to-recovery thresholds for enterprise applications.
Industry Challenges
- Multi-jurisdictional certification timelines:Providers must maintain parallel compliance certifications across ISO 27001, GDPR, and sector-specific frameworks, extending credentialing cycles and resource allocation.
- Legacy system integration complexity:Mainframe and distributed computing environments resist seamless cloud-native refactoring, demanding specialized bridging architectures that prolong project durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Application Management Services Market |
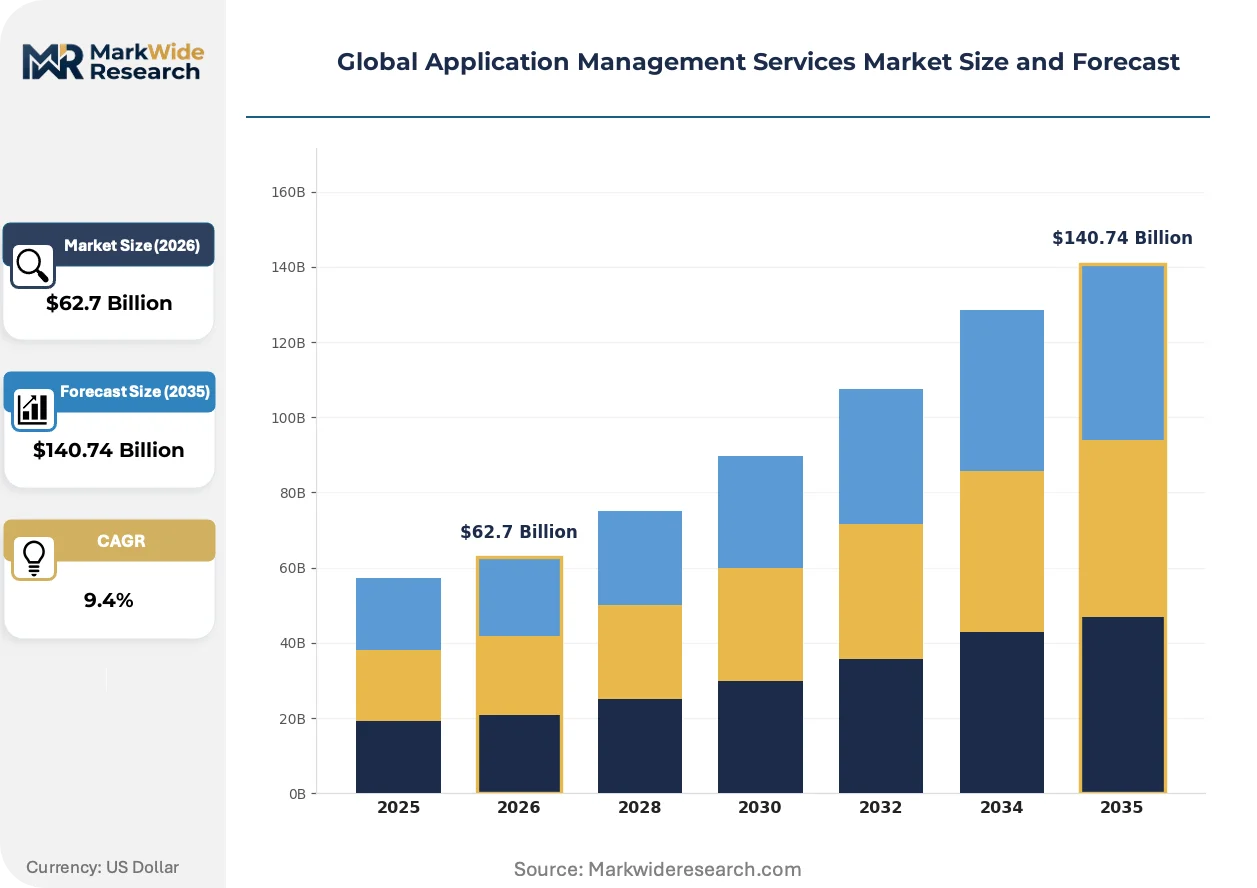
| Market Size in 2026 | $62.7 Billion |
| Market Size in 2035 | $140.74 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Services, Mobile Applications, Web Applications, Enterprise Applications Deployment Model: On-Premises, Hybrid, Public Cloud, Private Cloud Client Type: Small Enterprises, Medium Enterprises, Large Enterprises, Government Industry Vertical: Healthcare, Financial Services, Manufacturing, Retail |
| Companies Covered | Oracle Corporation, Deloitte, Accenture, Capgemini, Cognizant, Infosys, SAP, Fujitsu, Atos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Application Management Services Market Emerging Trajectories
Observability platforms are consolidating telemetry streams across distributed systems, compressing the distinction between monitoring and management functions. This technological convergence is redefining service boundaries and enabling predictive operational models.
AIOps platforms are unifying log analytics, metric correlation, and event management into single-pane visibility layers. Large financial institutions in the United States are deploying these systems at enterprise scale, replacing fragmented toolchains. This consolidation is compressing vendor counts per engagement while elevating technical performance guarantees.
The EU AI Act's algorithmic transparency requirements are mandating documentation and audit trails for automated decision systems. European enterprises must now embed explainability mechanisms into application architectures, reshaping development and maintenance workflows. Financial services and healthcare verticals face the steepest compliance gradients, driving preference for providers with established risk management practices.
Enterprise buyers are unbundling after-sales support from initial implementation contracts, procuring monitoring and optimization through separate competitive processes. This disintermediation of service packaging is most pronounced among North American financial institutions, which now evaluate infrastructure monitoring and code-level maintenance through distinct RFP streams. Procurement teams are compressing contract durations and introducing performance-based termination clauses.
Global Application Management Services Market Segmentation
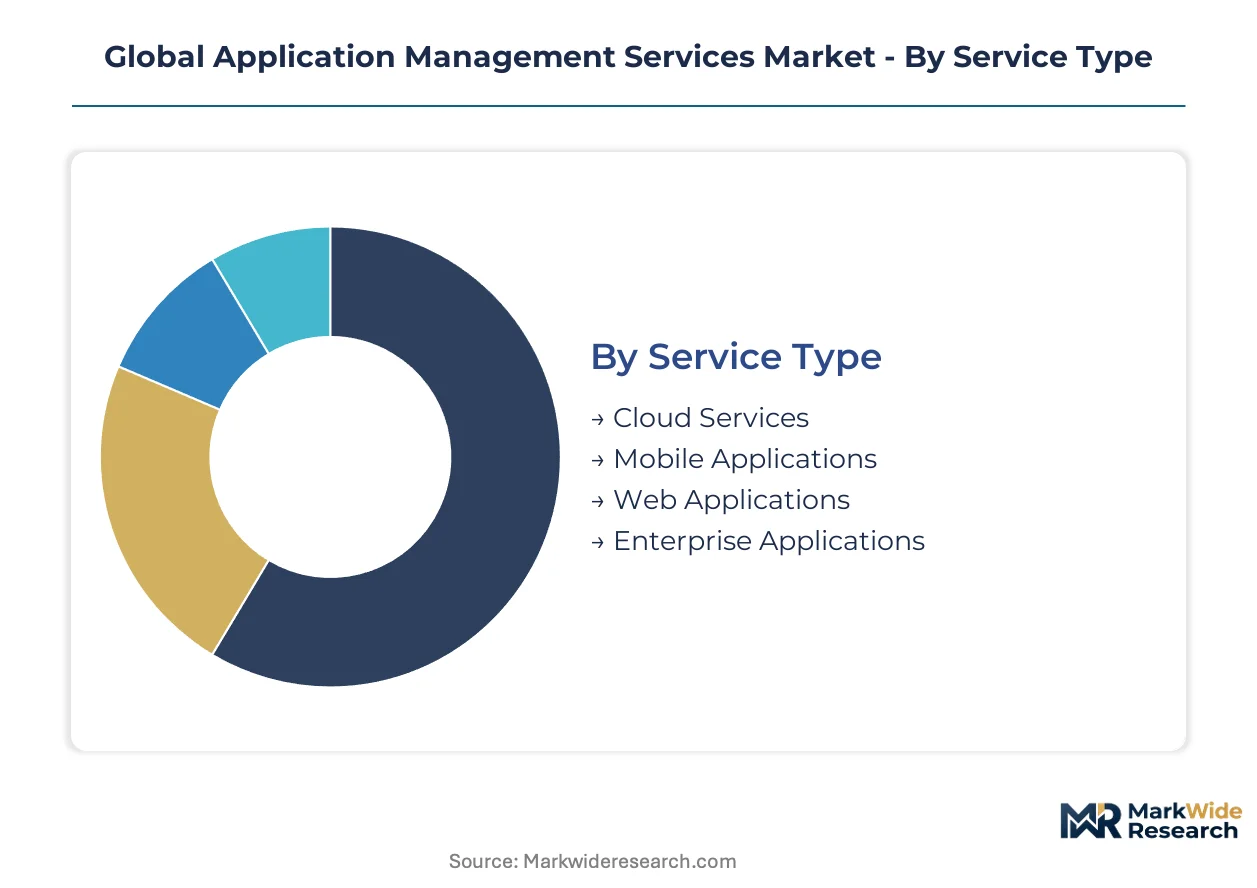
Segmentation in application management services reveals divergent capital requirements and margin profiles across delivery architectures. Providers calibrate resource allocation based on integration complexity, regulatory exposure, and automation potential within each segment cluster.
Service Type:
Capital intensity varies sharply across service categories, with enterprise applications demanding dedicated engineering teams and compliance infrastructure while cloud services leverage standardized tooling.
- Enterprise Applications:Complex ERP, CRM, and SCM systems requiring deep customization and continuous governance. Financial services institutions in the United States concentrate procurement here due to regulatory audit requirements and integration density with legacy infrastructure.
- Cloud Services:Workload migration, optimization, and multi-cloud orchestration delivered through automated pipelines. German manufacturing clients are accelerating adoption to repatriate aging data center operations and reduce technical debt.
- Web Applications:Customer-facing portals and e-commerce platforms with defined uptime SLAs.
- Mobile Applications:iOS and Android deployment management with over-the-air update distribution.
Enterprise applications absorb the bulk of installed capacity; cloud services are expanding most quickly.
Deployment Model:
Margin structures diverge based on customization depth, with hybrid architectures commanding premium pricing against standardized public cloud offerings.
- Hybrid:Integrated on-premises and cloud environments requiring bespoke bridging architectures and dedicated engineering coverage. Large enterprises across India and Germany favor this model for sensitive workloads falling under BIS cybersecurity guidelines and GDPR data residency requirements.
- Public Cloud:Standardized AWS, Azure, and GCP consumption with automated remediation protocols. United States financial institutions are consolidating procurement here to accelerate cloud repatriation timelines.
- Private Cloud:Single-tenant infrastructure with dedicated hardware isolation.
- On-Premises:Legacy data center maintenance with limited automation leverage.
Hybrid deployments retain margin superiority; public cloud is climbing the fastest.
Client Type:
Procurement sophistication scales with organizational complexity, driving distinct service packaging and contract structures across the client spectrum.
- Large Enterprises:Multi-year retainers with embedded compliance advisory and dedicated account engineering. These clients in Germany and the United States unbundle monitoring from maintenance through separate RFP processes.
- Government:Federally mandated security classifications and audit trail requirements. Indian government contracts under BIS guidelines emphasize ISO 27001 certification as a procurement threshold.
- Medium Enterprises:Standardized service tiers with modular component selection.
- Small Enterprises:Shared service desk models with automated ticketing and limited customization.
Large enterprises anchor contracted value; government verticals show steepest expansion trajectory.
Industry Vertical:
Regulatory exposure and application criticality create tiered pricing power across vertical markets, with compliance-integrated offerings commanding sustained premiums.
- Financial Services:Algorithmic trading platforms, core banking systems, and payment infrastructure under SEC disclosure rules and EU AI Act governance. United States institutions prioritize operational resilience and mean-time-to-recovery guarantees.
- Healthcare:Electronic health records and clinical decision support systems with HIPAA and GDPR convergence. European providers embed explainability mechanisms to satisfy algorithmic transparency mandates.
- Manufacturing:Legacy modernization and technical debt reduction for industrial control systems.
- Retail:Omnichannel commerce platforms with seasonal demand scaling requirements.
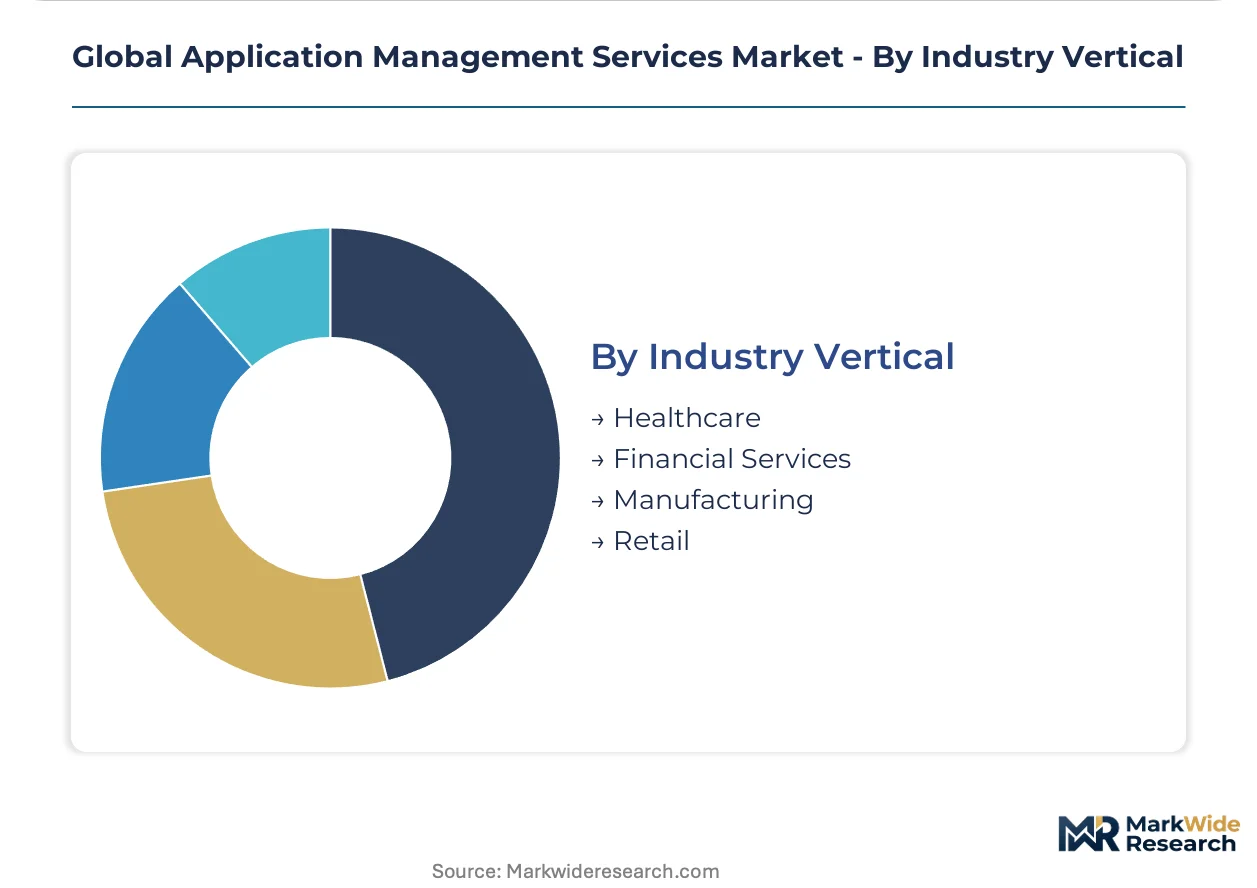
Financial services concentrates procurement value; healthcare is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and Germany concentrate AMS delivery capacity, with software technology parks in Bangalore and Hyderabad offering tax holidays that attract global providers. These zones anchor regional service delivery networks spanning regulatory jurisdictions.
United States
Financial services institutions in New York and Chicago drive enterprise application outsourcing demand. SEC disclosure rules for material cybersecurity incidents elevate procurement thresholds. The Boston-Washington corridor concentrates cloud migration projects as insurers and asset managers repatriate aging data center workloads.
Germany
Manufacturing clients in Bavaria and Baden-Württemberg prioritize legacy modernization to reduce technical debt. GDPR compliance mandates reshape service architectures for European-headquartered enterprises. The Frankfurt-Rhine-Main region hosts specialized AMS operations serving automotive and industrial machinery verticals.
India
Bangalore, Hyderabad, and Pune anchor global delivery centers for multi-cloud orchestration and legacy COBOL maintenance. BIS cybersecurity guidelines and ISO 27001 certification requirements favor established operators with dedicated risk management practices. Mumbai's financial district generates domestic demand for compliance-integrated retainers.
United Kingdom
London's fintech cluster accelerates adoption of AIOps platforms for algorithmic trading infrastructure. The UK Information Commissioner's Office enforces GDPR-aligned data governance standards. Edinburgh and Manchester host secondary delivery hubs supporting enterprise application lifecycle management.
Japan
Tokyo-Osaka manufacturing corridors demand hybrid cloud integration for industrial control systems. METI's cybersecurity frameworks for critical infrastructure elevate procurement scrutiny. Nagoya's automotive engineering base sustains specialized technical debt reduction workstreams.
Global Application Management Services Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered service categories. The market exhibits moderate consolidation with established IT services firms holding premium positions in compliance-intensive verticals. Three archetypes dominate: global consulting networks with embedded advisory capabilities, offshore-centric delivery specialists with scale advantages, and cloud-native technology providers with platform integration expertise. Competitive moves center on modular service unbundling and geographic certification expansion to satisfy multi-jurisdictional requirements.
Among consulting-network anchors, Deloitte and Accenture occupy positions at the advisory-integrated end of the spectrum, exemplifying providers that bundle regulatory interpretation with operational support. Cognizant represents the offshore-centric delivery model with concentrated legacy modernization capabilities. These three firms illustrate how competitive positioning diverges between compliance-heavy European engagements and scale-driven North American outsourcing contracts.
| Leading Market Players |
|---|
| Oracle Corporation |
| Deloitte |
| Accenture |
| Capgemini |
| Cognizant |
| Infosys |
| SAP |
| Fujitsu |
| Atos |
| Others |
Supply Flow & Price Mechanics
Large enterprises in the United States and Germany command procurement leverage through unbundled RFP processes, forcing providers toward componentized SLAs that separate infrastructure monitoring from code-level maintenance. This buyer concentration anchors pricing power with procurement sophistication, compressing margins for monolithic vendors while rewarding specialists with discrete technical competencies.
Pricing Analysis
Short lead-time premiums for compliance-integrated retainers under EU AI Act mandates command substantial pricing power against standardized offerings. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and customization depth, with ISO 27001-certified engagements capturing sustained premiums. Cost compression in cloud migration services is intensifying because hyperscaler automation reduces engineering hours per workload. Small enterprises exhibit highest price sensitivity, while financial services institutions in the United States show lowest elasticity due to regulatory audit requirements.
Supply Chain Analysis
Workforce availability constraints in India's Bangalore and Hyderabad technology corridors elevate compensation premiums for legacy COBOL and mainframe specialists. Supply concentration rests on India for offshore delivery, Germany for embedded compliance advisory, and the United States for multi-cloud orchestration. Talent pipelines, certification infrastructure, and regulatory interpretation capabilities constitute critical inputs. Single-source vulnerability in legacy system expertise prolongs project durations for manufacturing modernization. Distribution runs through direct enterprise sales teams and specialized channel partners serving vertical markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around providers with multi-jurisdictional certification portfolios, as regulatory fragmentation forces smaller operators toward exit or acquisition. EU AI Act compliance timelines and ISO 27001 credentialing cycles create asymmetric pressure favoring established players with dedicated risk management practices.
For Market Incumbents: Extend certification coverage across GDPR, SEC disclosure rules, and BIS cybersecurity guidelines to defend against offshore specialists capturing standardized cloud work. Backward integration into AIOps platform development reduces third-party tooling dependencies and elevates technical performance guarantees. Accenture's multi-cloud orchestration capabilities and Deloitte's embedded compliance advisory illustrate defensive positioning that compresses competitor margins. For New Entrants and Emerging Players: Enter via technical debt reduction workstreams for German manufacturing clients seeking legacy modernization, where incumbent capacity constraints create execution gaps. AI-driven automated remediation for predictive incident resolution represents the most penetrable white space, with robotic process automation convergence enabling compressed mean-time-to-recovery thresholds. Channel partnerships with hyperscalers accelerate credentialing and reduce customer acquisition costs. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier AMS providers in India with ISO 27001 certification and concentrated legacy maintenance capabilities, as BIS guidelines elevate procurement thresholds. Long-term viability hinges on algorithmic governance integration for EU AI Act compliance, with five-to-ten-year windows favoring operators with established European risk management practices. Watch hyperscaler partnership announcements as inflection indicators for platform-dependent specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdictional Certification Expansion | Parallel ISO 27001, GDPR, and SEC compliance credentials unlock European and North American financial services procurement. |
| AIOps Platform Integration | Single-pane visibility layers replace fragmented toolchains at United States financial institutions, compressing vendor counts. |
| Legacy Modernization Specialist Acquisition | COBOL and mainframe expertise commands premium compensation in German manufacturing technical debt reduction programs. |
| Embedded Compliance Advisory Bundling | EU AI Act algorithmic governance interpretation creates white space for advisory-integrated AMS retainers. |
| Hyperscaler Channel Partnership | AWS, Azure, and GCP alliances accelerate credentialing and reduce customer acquisition costs for cloud migration services. |
Methodological Framework
Multi-period observation of cloud repatriation timelines, compliance certification cycles, and modular contract unbundling anchored the trend analysis, supplemented by interviews with AMS delivery heads, enterprise IT procurement officers, regulatory compliance leads, and platform engineering directors. Secondary validation drew from SEC 10-K filings, EU regulatory impact assessments, BIS guideline documentation, and hyperscaler capex disclosures. Bottom-up service-type modeling and top-down regional demand aggregation provided triangulation across projection scenarios.
Segment-weighting approaches calibrated enterprise application, cloud service, and web application categories by integration complexity and automation potential. Deployment model segmentation across hybrid, public cloud, private cloud, and on-premises architectures captured margin structure divergence. Client type and industry vertical dimensions modeled procurement sophistication scaling with organizational complexity. CAGRs derived from adoption curve analysis and regulatory mandate implementation timelines across the analysis window, with workforce availability constraints and certification backlog data informing capacity-side adjustments.
Revisions become necessary when EU AI Act enforcement intensity, SEC cybersecurity disclosure rule expansion, or BIS guideline amendment timelines materialize differently than baseline assumptions. Forecasts reflect documented projections contingent on these regulatory implementation trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Middle East HR Payroll Software Market
Software & Services
Global Storm Tracking Apps Market
Software & Services
Pure Play Software Testing Market
Software & Services
Global Board Management Software Market
Software & Services
Account-Based Data Software Market
Software & Services
Global Furniture Manufacturing Software Market
Software & Services
Content Distribution Software Market
Software & Services
Global Nosql Software Market
Software & Services
Time Series Databases Software Market
Software & Services
Appointment Scheduling Software Market
Software & Services
Global Open API Market
Software & Services
Optical Coatings Design Software Market
Software & Services
Vlog Editing Software Market
Software & Services
Global Claims Processing Software Market
Software & Services
HSM-As-A-Service Market
Software & Services
Self-Storage Software Market