
 Workshop Management Software Market | 2026-2036
Workshop Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Workshop Management Software Market Analytics
Skilled automotive technician shortages across North America and Europe is collapsing workshop throughput capacity and forcing owners toward automation-heavy software stacks. Shopmonkey leverages cloud-native architecture to capture independent garage operators seeking minimal IT overhead. Tekmetric anchors its position through deep DMS integrations that sustain dealer group loyalty. AutoLeap competes aggressively on pricing transparency tools that differentiate its platform for smaller fleet operators.
Workshop management software encompasses integrated digital platforms that coordinate repair scheduling, parts inventory, technician dispatch, and customer billing through centralized databases accessible via desktop and mobile endpoints. These systems typically employ real-time synchronization protocols and RESTful APIs to ensure data consistency across multi-location operations, serving primarily to maximize bay utilization and reduce administrative labor in high-volume maintenance environments. Cloud-based deployment leads functional adoption as workshops abandon server maintenance burdens, while inventory management modules capture disproportionate margin attention from parts-heavy operators. Appointment scheduling functionality grows fastest among hybrid fleet-service centers balancing retail walk-ins with contracted maintenance windows.
FCC guidelines on connected vehicle data access shape how workshop platforms integrate telematics feeds, while GDPR compliance requirements in Europe constrain customer data retention policies across CRM modules. ISO 27001 certification has become a de facto procurement filter for enterprise fleet buyers evaluating vendor security posture. Stakeholders must weigh API ecosystem breadth against vertical feature depth when selecting platforms for multi-site consolidation.
Market Dynamics
Cloud-native architectures are decomposing legacy on-premise installations across independent garages and fleet operators, forcing vendors to rebuild pricing models around API consumption rather than perpetual licenses.
Growth Catalysts
- Connected vehicle telematics mandates:FCC guidelines on data access rights are compelling fleet operators to adopt platforms that ingest real-time diagnostic feeds for predictive maintenance scheduling.
- Technician labor scarcity:Collapsing throughput capacity across North American service bays is accelerating automation investments in dispatch optimization and digital work-order routing.
- Multi-location consolidation:Unified platform demand from service groups operating across Germany, Australia, and the United States is pulling vendors toward centralized database architectures with mobile endpoints.
Market Restraints
- GDPR compliance friction:European customer data retention constraints are extending CRM module development cycles and limiting cross-border data synchronization capabilities.
- Legacy system entrenchment:Dealer groups with deep DMS integrations face high switching costs that anchor incumbent vendors and compress pricing flexibility for challengers.
- Input cost volatility:Cloud infrastructure spend fluctuations are pressuring vendor margins and forcing tiered service packaging that fragments feature access for smaller operators.
Strategic Opportunities
- Underpenetrated Australian independent sector:Fragmented garage networks outside major metros present white-space for mobile-first platforms with minimal IT overhead requirements.
- API ecosystem convergence:Integration between workshop management systems and parts procurement marketplaces is creating new revenue streams through transaction fee capture.
- ISO 27001 procurement filtering:Enterprise fleet buyers are mandating certification as a de facto security threshold, creating competitive moats for compliant vendors.
Industry Challenges
- Technician onboarding complexity:Cloud-native interfaces require digital literacy that exceeds the skill profile of aging automotive workforces, extending training cycles and depressing initial utilization rates.
- Multi-vendor integration timelines:RESTful API standardization remains incomplete across parts suppliers, telematics providers, and accounting systems, forcing custom development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workshop Management Software Market |
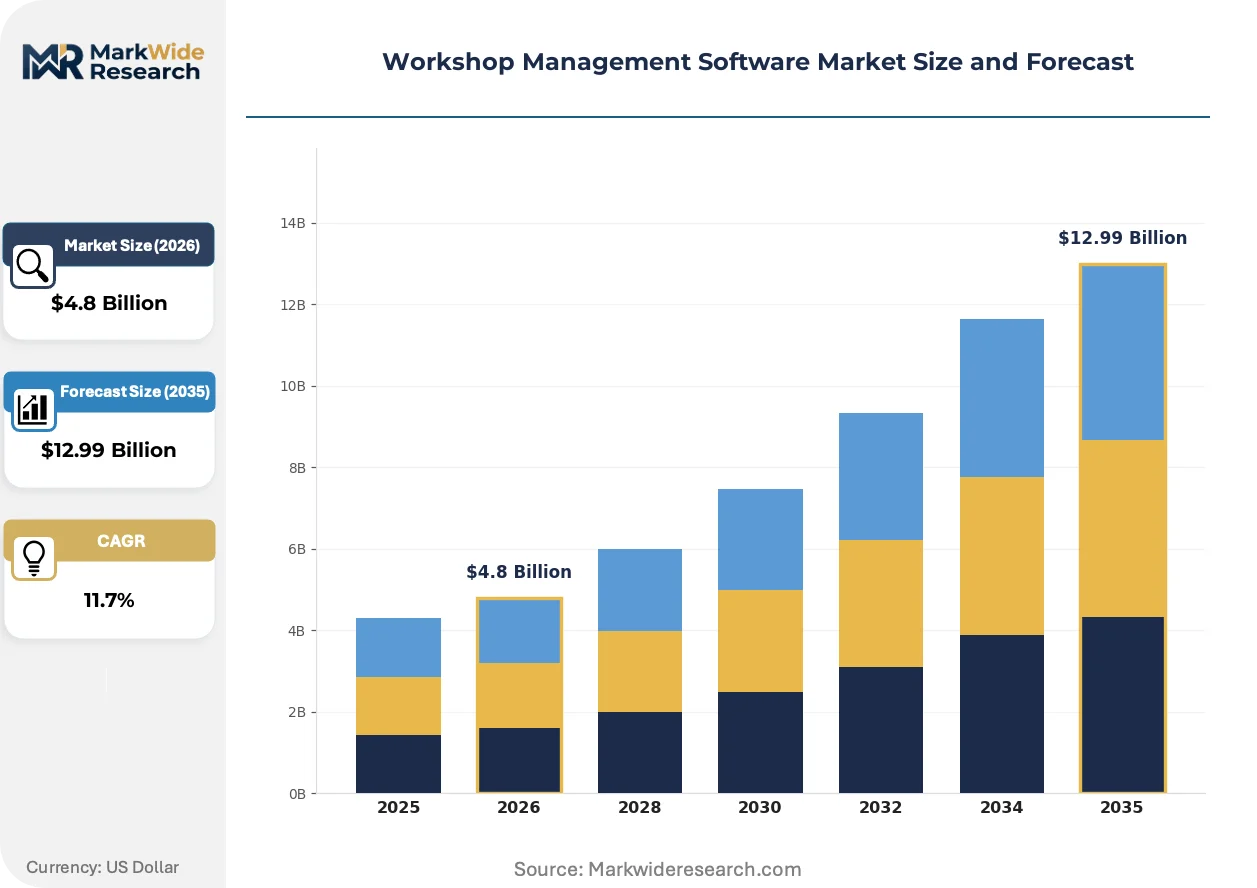
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Mobile End User: Automobile Workshops, Service Centers, Fleet Management, Independent Garages Functionality: Inventory Management, Appointment Scheduling, Invoicing, Customer Relationship Management Integration Level: Third-Party Integrations, API Availability, Payment Gateways, Reporting Tools |
| Companies Covered | Shopmonkey, Tekmetric, AutoLeap, GaragePlug, Shop Boss, Workshop Software, ProShop ERP, FleetMinder, Orion Dealer Management Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workshop Management Software Market Evolving Landscape
Real-time synchronization protocols and mobile-first interfaces are compressing the gap between diagnostic event and service dispatch, reshaping how workshops prioritize bay allocation and parts procurement.
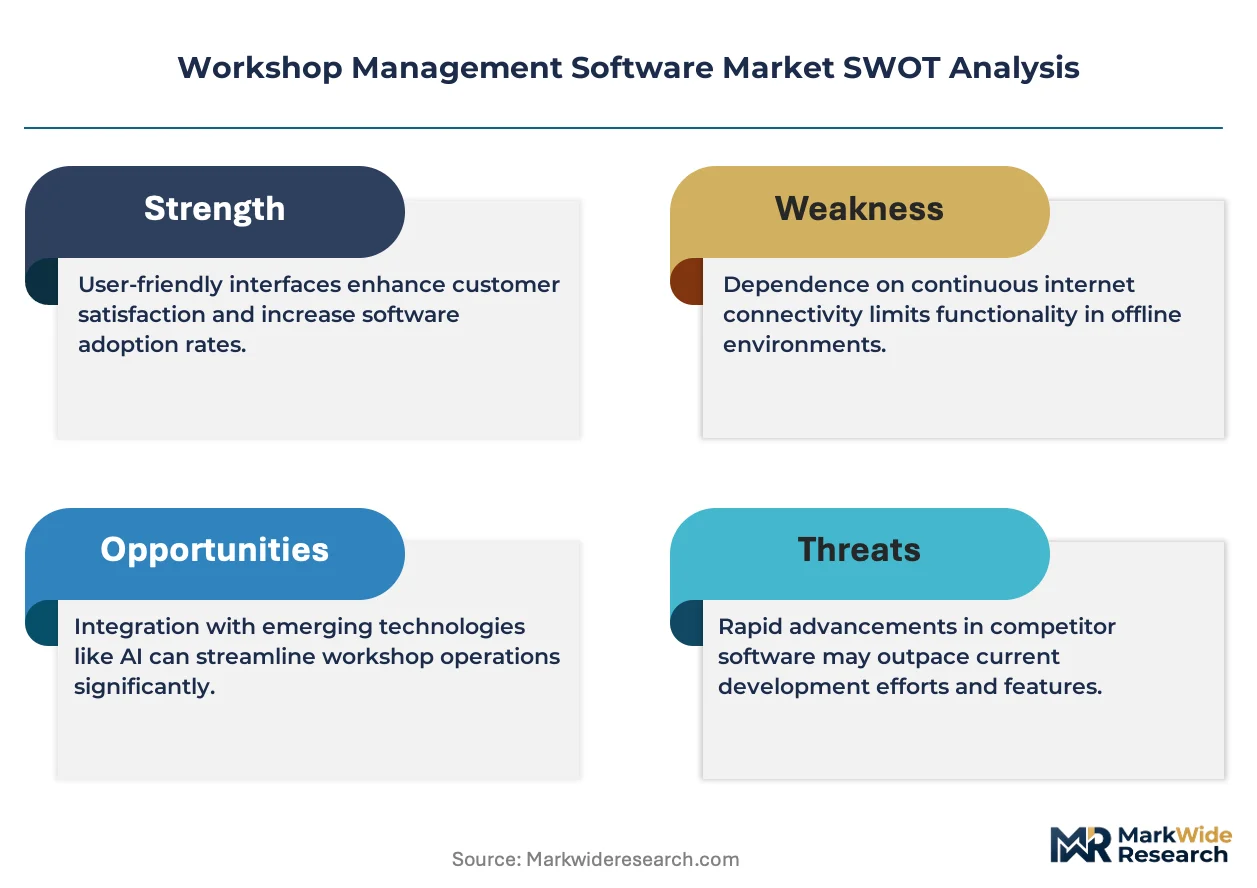
Microservices-based backend architecture is decomposing monolithic workshop platforms into modular components that garages can license selectively. Independent operators in high-labor-cost markets are adopting these stripped-down configurations fastest. This decomposition is enabling point-solution vendors to penetrate segments previously locked behind full-suite contracts.
GDPR data retention policies are constraining how European platforms architect customer history modules, forcing shorter default retention windows and explicit consent workflows. Workshop operators in Germany and France are responding by segmenting CRM databases geographically and investing in automated deletion pipelines. The compliance burden falls heaviest on multi-national service groups with centralized data lakes.
Fleet procurement officers are consolidating vendor relationships and demanding outcome-based contracts tied to vehicle uptime metrics rather than per-seat licensing. This compression of the buying cycle is displacing month-to-month SaaS subscriptions with annual commitments that bundle software, support, and training. The shift is most visible among logistics operators in the United States managing mixed passenger and commercial fleets.
Workshop Management Software Market Segmentation
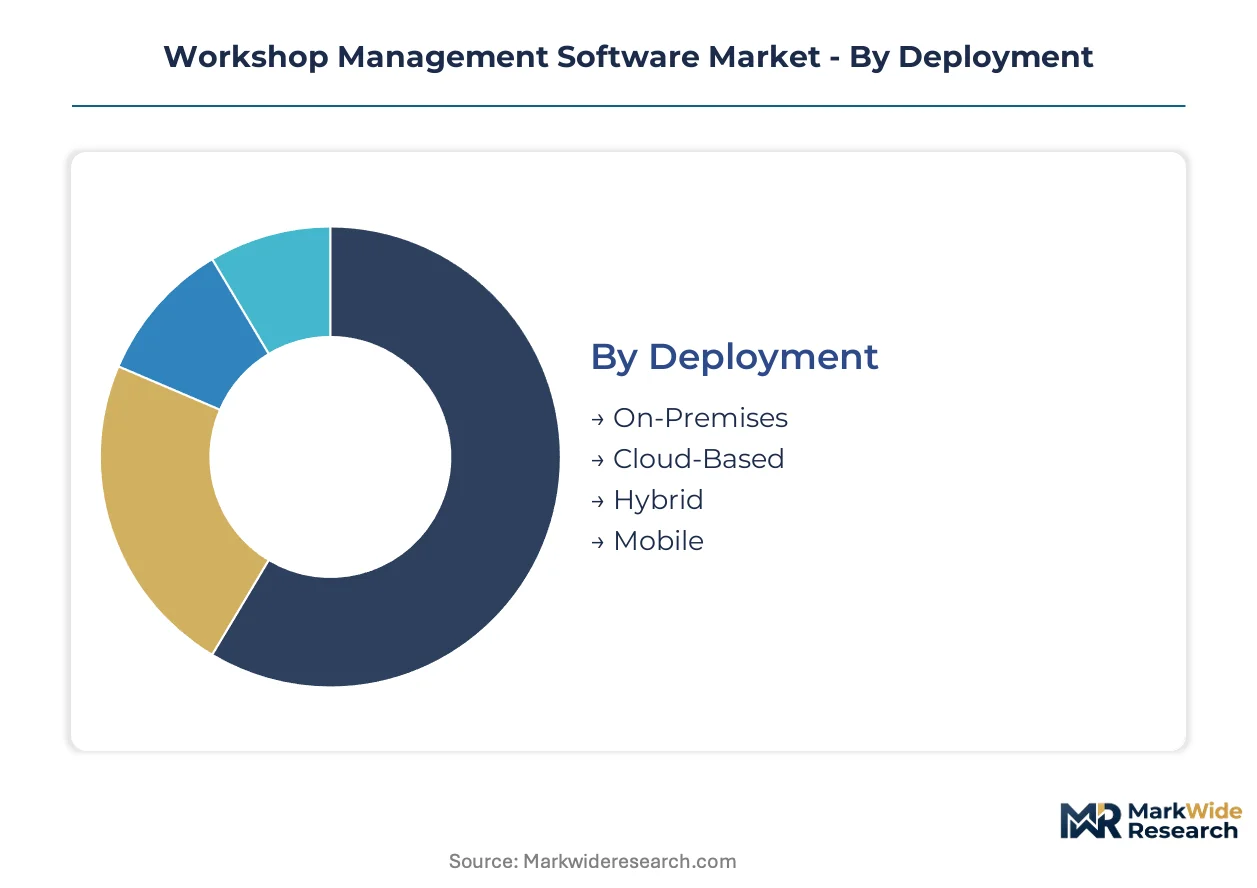
Workshop management software purchasing splits sharply between legacy server installations and cloud-native subscriptions, with channel strategy determining how vendors allocate sales resources across direct, partner, and marketplace routes. Deployment choice dictates integration complexity, support overhead, and customer lifetime value calculations for platform providers.
Deployment:
Cloud-based platforms flow predominantly through direct digital channels and value-added resellers, while on-premises installations rely on systems integrators with regional implementation capacity.
- On-Premises:Perpetual-licensed software requiring local server infrastructure and dedicated IT maintenance staff. Dealer groups in Germany with deep DMS entrenchment anchor residual demand here, constrained by high switching costs and capital lock-in.
- Cloud-Based:Subscription-priced platforms with browser and mobile access, automatic updates, and API-first architecture. Independent garages across Australia and the United States are migrating fastest, drawn by minimal upfront investment and remote technician access.
- Hybrid:Split configurations keeping sensitive customer data on local servers while pushing scheduling and billing to cloud endpoints. Fleet operators in regulated industries favor this model for GDPR compartmentalization.
- Mobile:Native iOS and Android applications for field technicians and service advisors. Smaller independent operators with single-bay operations adopt these for work-order capture without desktop dependency.
By volume, Cloud-Based leads. By growth pace, Mobile is expanding most quickly.
End User:
Customer type determines pricing tier tolerance, with enterprise fleet buyers demanding outcome-based contracts and small garages prioritizing per-seat affordability.
- Automobile Workshops:Full-service repair facilities handling diverse vehicle makes and models. Workshops in the United States concentrate demand here, pressured by technician scarcity to automate dispatch and inventory workflows.
- Service Centers:Brand-affiliated or specialized maintenance operations with standardized procedures. Volume concentrates among multi-location groups in Germany seeking unified platform control across regional networks.
- Fleet Management:In-house maintenance operations for logistics, rental, and corporate vehicle pools. Australian mining and transport fleets drive adoption of telematics-integrated platforms for predictive scheduling.
- Independent Garages:Owner-operated repair shops without manufacturer affiliation. Fragmented networks outside major metros present white-space for mobile-first platforms with minimal IT overhead requirements.
Fleet Management commands the highest contract values. Independent Garages show the steepest expansion trajectory as digital literacy spreads among smaller operators.
Functionality:
Module selection tracks margin pressure points, with parts-heavy operators prioritizing inventory tools and customer-facing businesses investing in scheduling and CRM.
- Inventory Management:Real-time parts tracking, supplier integration, and automated reorder thresholds. This module captures disproportionate attention from Australian workshops managing complex supply chains across remote locations.
- Appointment Scheduling:Online booking, bay allocation, and technician dispatch optimization. Hybrid fleet-service centers in the United States balance retail walk-ins with contracted maintenance windows through these tools.
- Invoicing:Digital estimate generation, payment processing, and accounting system sync. GDPR compliance requirements in Europe constrain data retention policies here, forcing explicit consent workflows.
- Customer Relationship Management:Service history tracking, marketing automation, and retention analytics. German workshops segment databases geographically to satisfy shorter default retention windows mandated by regulators.
Inventory Management generates the highest attach rates. Appointment Scheduling is climbing the fastest as real-time synchronization protocols mature.
Integration Level:
Technical openness determines platform stickiness, with API breadth becoming the primary procurement filter for buyers consolidating vendor relationships.
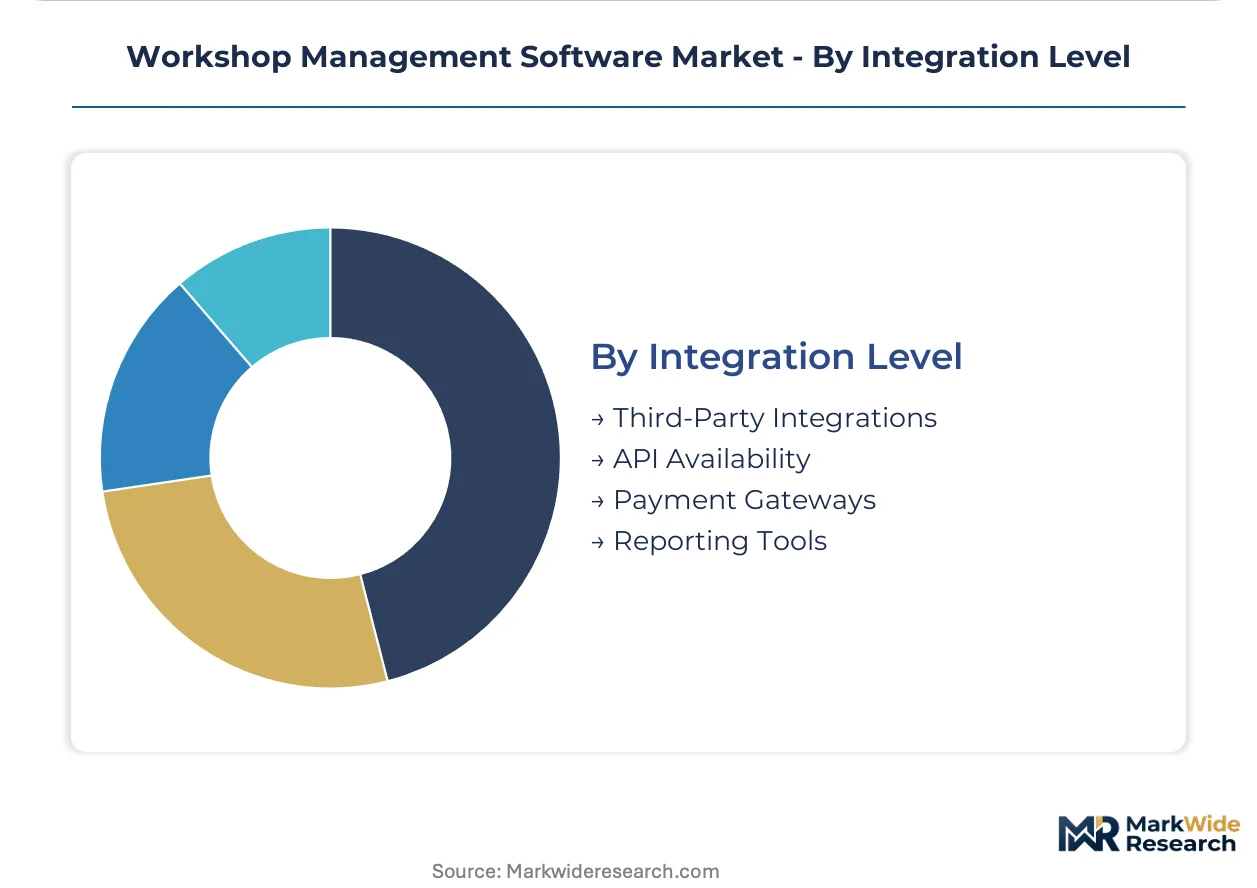
- Third-Party Integrations:Pre-built connectors to accounting, telematics, and parts procurement systems. Enterprise fleet buyers in the United States mandate extensive integration catalogs as a de facto security threshold.
- API Availability:RESTful endpoints enabling custom development and data exchange. Incomplete standardization across parts suppliers and telematics providers forces custom development timelines for each deployment.
- Payment Gateways:Embedded card processing, buy-now-pay-later options, and automated reconciliation. Small garages prioritize this functionality to compress cash conversion cycles.
- Reporting Tools:Dashboards, customizable analytics, and regulatory compliance documentation. Fleet procurement officers increasingly demand outcome-based contracts tied to vehicle uptime metrics rather than per-seat licensing.
Third-Party Integrations dominate procurement checklists. API Availability is gaining share fastest as microservices architecture decomposes monolithic platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC guidelines on connected vehicle data access anchor procurement priorities in the United States, while GDPR compliance requirements reshape European platform architectures. Cloud migration concentrates demand across specific national markets where fleet operators and multi-location service groups seek unified control.
United States
Independent garages across Texas and the Midwest accelerate digital scheduling adoption as technician labor scarcity collapses bay throughput capacity. FCC telematics mandates compel fleet operators to ingest real-time diagnostic feeds for predictive maintenance. Dallas-Fort Worth logistics clusters drive outcome-based contract demand tied to vehicle uptime metrics.
Germany
Service centers in Bavaria and Baden-Württemberg seek unified platform control across regional networks fragmented by legacy DMS entrenchment. GDPR data retention constraints force shorter default windows and explicit consent workflows in CRM modules. Stuttgart automotive clusters respond by segmenting databases geographically and investing in automated deletion pipelines.
Australia
Mining and transport fleets in Western Australia and Queensland adopt telematics-integrated platforms for predictive scheduling across remote locations. The country's national data protection regulator shapes customer history module architectures with strict retention requirements. Sydney and Melbourne service groups anchor cloud-native procurement as fragmented independent networks outside major metros present white-space for mobile-first platforms.
United Kingdom
Multi-location service groups in the Midlands and Southeast balance retail walk-ins with contracted maintenance windows through real-time synchronization protocols. The Information Commissioner's Office constrains cross-border data synchronization capabilities for platforms serving Northern Ireland and continental operations. London fleet operators compress buying cycles toward annual commitments bundling software, support, and training.
Canada
Dealer groups in Ontario and Quebec face high switching costs from deep DMS integrations that anchor incumbent vendors. Health Canada guidelines on connected vehicle data access shape how workshop platforms integrate diagnostic feeds. Calgary and Edmonton independent garages migrate fastest to cloud-based deployment drawn by minimal upfront investment and remote technician access.
Workshop Management Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on API breadth and vertical feature depth. The upper tier commands enterprise fleet contracts through ISO 27001 certification and outcome-based pricing models. Specialist players penetrate independent garage segments with stripped-down microservices configurations. M&A activity consolidates regional implementation capacity while technology licensing agreements accelerate RESTful API standardization across parts procurement marketplaces.
Within the cloud-native tier, Shopmonkey and AutoLeap exemplify platforms capturing independent operators seeking minimal IT overhead, while Tekmetric anchors a position through deep integration archetypes that sustain dealer group loyalty. These three companies represent divergent strategic postures: mobile-first penetration, pricing transparency differentiation, and incumbent entrenchment through DMS connectivity. Their collective positioning illustrates how vendor selection criteria fragment across customer scale and technical sophistication requirements.
| Leading Market Players |
|---|
| Shopmonkey |
| Tekmetric |
| AutoLeap |
| GaragePlug |
| Shop Boss |
| Workshop Software |
| ProShop ERP |
| FleetMinder |
| Orion Dealer Management Systems |
| Others |
Value Network & Pricing Analysis
Annual commitment bundling locks in multi-year platform access and price predictability for fleet operators consolidating vendor relationships across the United States, Germany, and Australia. This contract structure anchors procurement negotiations while compressing cash conversion cycles for smaller independent garages migrating from perpetual licenses.
Pricing Analysis
United States cloud-native deployments command premium subscription tiers against Australian mobile-first configurations, reflecting divergent labor cost structures and IT overhead tolerance. Three-tier pricing structure across premium, standard, and economy levels segments by integration complexity and ISO 27001 certification status. Cost compression in entry tiers is intensifying because hyperscaler infrastructure spend volatility forces vendors to fragment feature packaging. Independent garages with single-bay operations exhibit highest price sensitivity; enterprise fleet buyers with uptime-based outcome contracts show lowest.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for hardware-dependent on-premises installations serving German dealer groups. Cloud infrastructure provisioning concentrates in the United States, Ireland, and Singapore, with API gateway dependencies resting on hyperscaler edge locations. Single-source vulnerability permeates telematics module integration where FCC-compliant data feed protocols lack standardized alternatives. Distribution runs through direct digital channels for cloud subscriptions and value-added reseller networks for hybrid deployments requiring regional implementation capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Workshop management software sits in early-cycle expansion as technician labor scarcity across North America and Europe collapses bay throughput capacity and forces automation adoption. Independent garage digital literacy gaps are compressing, accelerating addressable market penetration beyond fleet operators.
For Market Incumbents: Secure ISO 27001 certification moats to defend enterprise fleet procurement thresholds against cloud-native challengers. Deepen DMS integration stickiness in German dealer groups where legacy system entrenchment creates high switching cost barriers. Prioritize API ecosystem breadth as the primary defensive lever against modular point-solution vendors decomposing full-suite contracts. For New Entrants and Emerging Players: Anchor in Australian independent garages outside Sydney and Melbourne metros where fragmented networks present white-space for mobile-first platforms with minimal IT overhead. Target predictive maintenance scheduling modules for mining and transport fleets in Western Australia and Queensland. Lead with transparent pricing tools that differentiate against incumbent opacity in smaller fleet operator segments. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native platforms with RESTful API architectures and established hyperscaler partnerships that enable rapid geographic scaling without capital-heavy infrastructure buildout. Long-term viability across the analysis window favors vendors capturing transaction fee streams from parts procurement marketplace integrations. Watch technician onboarding completion rates as the critical signal for platform utilization stickiness and customer lifetime value expansion.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Pre-built connectors to telematics providers and parts marketplaces capture transaction fee revenue streams. |
| ISO 27001 Certification Investment | Enterprise fleet procurement officers mandate this security threshold as a de facto vendor filter. |
| Mobile-First Platform Development | Native iOS and Android applications penetrate single-bay independent garages with zero desktop dependency. |
| Predictive Maintenance Module Launch | FCC telematics data access guidelines compel fleet operators toward real-time diagnostic feed integration. |
| Geographic Data Segmentation | GDPR-compliant database compartmentalization enables European multi-location service group expansion. |
Research Methodology
Two parallel data streams informed the analysis: structured conversations with automotive service directors, fleet procurement officers, platform engineers, and integration specialists; and secondary validation through SEC SaaS vendor filings, hyperscaler infrastructure spend disclosures, FCC regulatory dockets, and GDPR implementation guidance documents. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against aggregate cloud software spending patterns anchored volume estimates.
Across the analysis window, the forecasting framework modeled deployment architecture, end-user scale tier, functional module attach rates, integration complexity depth, and regional regulatory compliance burden. CAGRs derived from segment-level growth trajectory synthesis and technology diffusion curve positioning. Forecast inputs included technician labor scarcity indices, connected vehicle telematics penetration assumptions, and multi-location service group consolidation velocity.
Decision-makers should treat outputs as directional under sustained cloud migration momentum and stable hyperscaler pricing; material deviation would warrant model refresh. Specific risks include abrupt GDPR enforcement escalation, FCC telematics mandate delays, or acute technician training pipeline recovery that moderates automation urgency. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Computer Software Market
Software & Services
Push Notifications Software Market
Software & Services
Global Chemical Software Market
Software & Services
Sales Platforms Software Market
Software & Services
Legal Software Market
Software & Services
Global Process Mining Software Market
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
Remote Sensing Software Market
Software & Services
Problem Management Software Market
Software & Services
Payroll and HR Software Market
Software & Services
Application Virtualization Market
Software & Services
Simulation Software Market
Software & Services
Global Portal Software Market
Software & Services
Global Web Scraper Software Market
Software & Services
Open Stack Service Market
Software & Services
Global Managed File Transfer (MFT) Software and Service Market