
 Lawn Care Software Market | 2026-2036
Lawn Care Software Market Size, Share, and Industry Trends Forecast 2026-2036
Lawn Care Software Market Foresight
The lawn care software market is pivoting between premium enterprise suites and lean commodity tools built for solo operators. ServiceTitan leverages deep integration with accounting and payment systems to dominate the high-end commercial segment. Jobber sustains broad appeal across mid-sized landscaping firms with balanced scheduling and CRM functionality. LMN differentiates through specialized estimating and job-costing features tailored to design-build landscape professionals.
Lawn care software encompasses cloud-based, on-premises, and hybrid platforms that automate route optimization, crew dispatch, invoicing, and customer retention for green-industry service providers. Core technical specifications include GPS-enabled fleet tracking, real-time job-status updates, and two-way SMS communication between office staff and field crews. Cloud-based deployment leads current uptake among landscape professionals seeking mobile-first access without server maintenance burdens. Residential end-user adoption is accelerating fastest as homeowner associations and property management groups demand digital service records and automated billing transparency.
The EPA enforces Clean Water Act provisions affecting pesticide application documentation, while OSHA standards govern crew safety training logs that software platforms increasingly digitize. State-level departments of agriculture in Florida, Texas, and California impose varying licensing and reporting requirements that vendors must accommodate. Buyers should scrutinize whether a platform's compliance modules map to their specific regulatory geography before committing to multi-year contracts.
Market Dynamics
Cloud migration is compressing deployment cycles for lawn care operators while EPA water runoff documentation mandates force software stack upgrades across compliance-sensitive states. The tension between franchise standardization and independent operator flexibility shapes vendor product roadmaps.
Growth Catalysts
- EPA Clean Water Act enforcement:Digitized pesticide application logging requirements push operators toward integrated compliance modules.
- Route optimization algorithms:Machine learning-driven dispatch systems cut fuel costs and crew overtime for multi-vehicle fleets.
- Homeowner association procurement:Texas and Florida HOAs now mandate digital service records and automated billing transparency from contracted landscapers.
Market Restraints
- Input cost volatility:SaaS subscription pricing fluctuates with cloud infrastructure costs passed through from AWS and Azure.
- Technical limitation:Offline functionality gaps persist in rural coverage zones where cellular connectivity fails.
- Regulatory friction:State-by-state licensing variations force vendors to maintain fragmented compliance templates.
Strategic Opportunities
- Underpenetrated geography:Canadian prairie provinces show minimal software adoption among independent snow-and-lawn hybrid operators.
- Technology convergence:IoT soil sensors paired with automated irrigation scheduling create bundled service offerings.
- Regulatory tailwind:OSHA's proposed digitization mandate for crew safety training logs opens new compliance module demand.
Industry Challenges
- Integration complexity:Legacy accounting systems require costly API bridges for data synchronization.
- Talent scarcity:Field technicians resist mobile app adoption, creating change management burdens for office staff.
- Certification timelines:State agriculture department integrations delay go-live dates by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lawn Care Software Market |
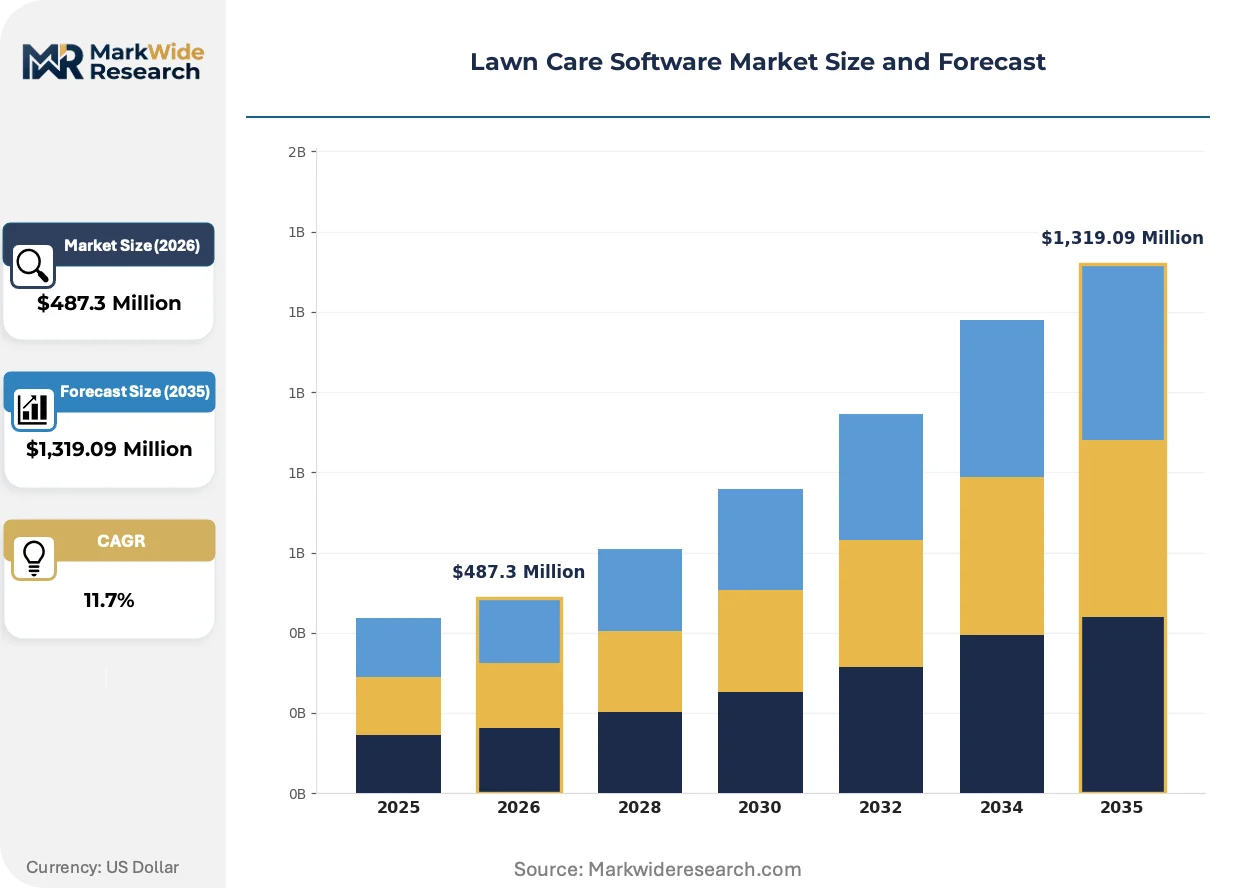
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Residential, Commercial, Government, Landscape Professionals Functionality: Scheduling, Billing, Customer Relationship Management, Inventory Management Integration: Accounting Software, GPS Tracking, Payment Processing, CRM Solutions |
| Companies Covered | Jobber, ServiceTitan, RealGreen, LMN, Service Autopilot, Aspire Software, Arborgold, LawnPro Software, WorkWave, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lawn Care Software Market Shifts & Advancements
Edge computing architectures and embedded compliance automation are compressing the gap between field data capture and back-office decision-making. Vendors race to embed regulatory logic directly into workflow engines.
Mobile-first Progressive Web Applications are decentralizing software access for field crews who lack corporate device provisioning. Solo operators and franchise subcontractors adopt lightweight browser-based tools faster than native app deployments. This shift is decentralizing purchasing authority from IT departments to individual crew leads.
EPA's evolving stormwater documentation rules now require timestamped geolocation data for every chemical application. Landscape firms must retrofit legacy workflows with GPS-stamped audit trails or risk permit revocation. Commercial operators in Florida and California face the steepest compliance retrofit costs.
Subscription fatigue among mid-sized landscaping firms is fragmenting procurement into modular point solutions rather than enterprise suites. Buyers unbundle scheduling from billing from CRM, selecting best-of-breed tools per function. This pattern concentrates in the Midwest where operator margins face pressure from fuel and labor inflation.
Lawn Care Software Market Segmentation
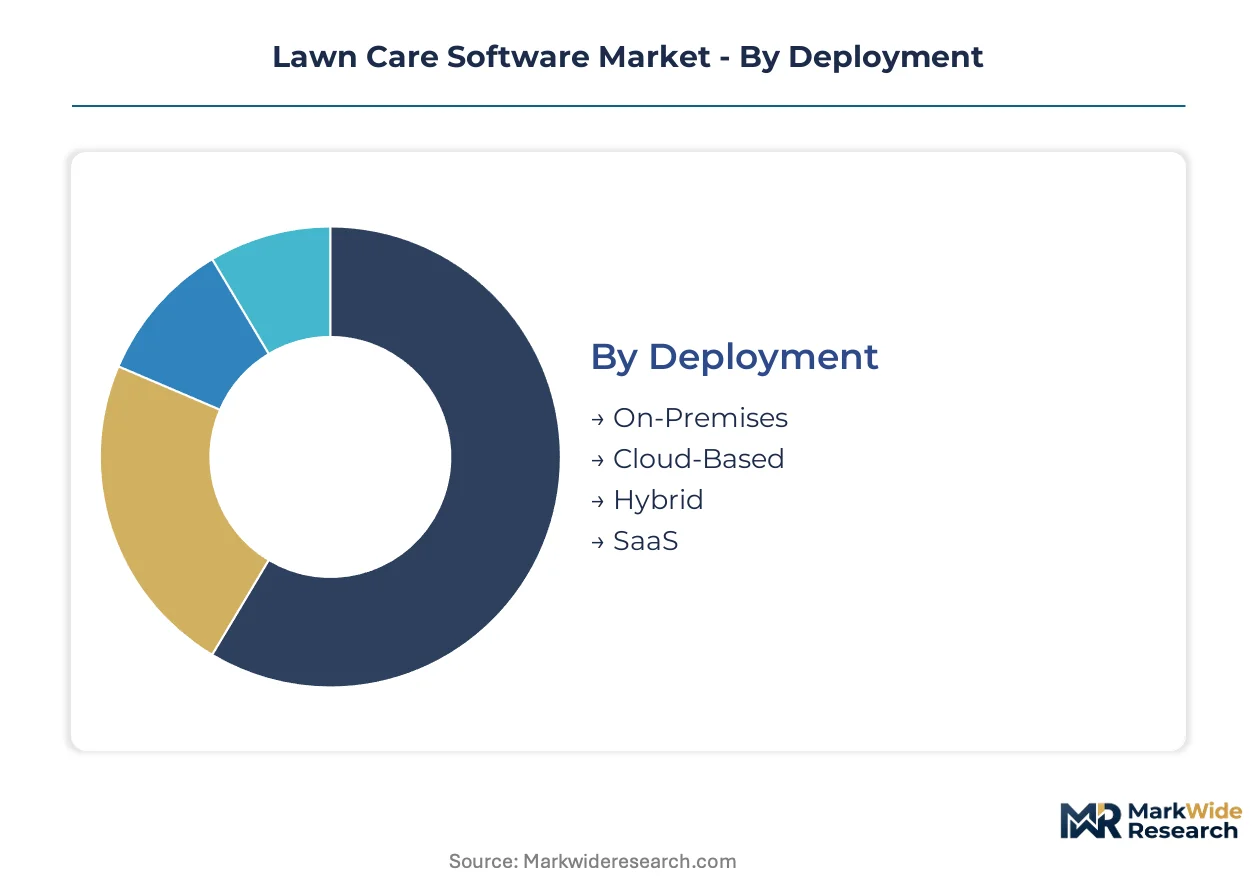
Segmentation in lawn care software reveals how operational scale and technical maturity shape purchasing decisions. Deployment architecture determines total cost of ownership, while integration depth separates standalone tools from embedded enterprise systems.
Deployment:
Cloud-based platforms dominate new installations, though hybrid architectures persist among operators with legacy server investments.
- On-Premises:Legacy server installations retain traction among large franchise networks with dedicated IT staff and data sovereignty requirements. Demand concentrates in the upper Midwest where multi-decade operators resist cloud migration due to unreliable rural broadband infrastructure.
- Cloud-Based:Browser-native platforms with mobile-first design enable real-time crew dispatch without local server maintenance. Texas and Florida operators lead adoption, driven by HOA mandates for digital service records and automated billing transparency.
- Hybrid:Split architectures keep sensitive customer data on local servers while pushing field operations to cloud endpoints. Appeals to mid-sized firms navigating EPA compliance documentation requirements.
- SaaS:Subscription models with per-user or per-crew pricing lower entry barriers for seasonal operators. Solo practitioners in Arizona and Colorado favor this model for its month-to-month flexibility.
Volume placements concentrate in Cloud-Based; the faster expansion belongs to SaaS.
End User:
Customer type dictates feature prioritization, from route density algorithms for high-volume residential fleets to compliance modules for government contractors.
- Residential:Platforms optimize for dense route clustering and automated recurring billing. Homeowner associations in Texas and Florida now mandate digital service records from contracted providers.
- Commercial:Enterprise-grade tools handle multi-site portfolios with specialized estimating and job-costing workflows. Landscape professionals serving retail and office complexes drive specification requirements.
- Government:Rigid procurement protocols and EPA stormwater documentation mandates shape vendor selection. Municipal park departments require timestamped geolocation data for chemical applications.
- Landscape Professionals:Design-build specialists need integrated CAD compatibility and material takeoff calculators. This segment shows highest willingness to pay for specialized functionality.
Commercial deployments generate largest contract values; residential subscriptions are climbing fastest.
Functionality:
Core module selection reveals whether buyers prioritize revenue capture, operational efficiency, or customer retention.
- Scheduling:Route optimization algorithms cut fuel costs and crew overtime for multi-vehicle fleets. Machine learning dispatch systems concentrate demand among operators with 10-plus crews.
- Billing:Automated invoicing with integrated payment processing reduces accounts-receivable cycles. Essential for operators managing hundreds of recurring residential accounts.
- Customer Relationship Management:Lead tracking and automated follow-up sequences support growth-focused mid-sized firms. Integration with marketing automation tools differentiates premium tiers.
- Inventory Management:Chemical tracking with lot-number traceability satisfies EPA pesticide documentation requirements. Critical for operators in Florida and California facing steep compliance retrofit costs.
Billing modules capture widest adoption; inventory management shows steepest expansion trajectory.
Integration:
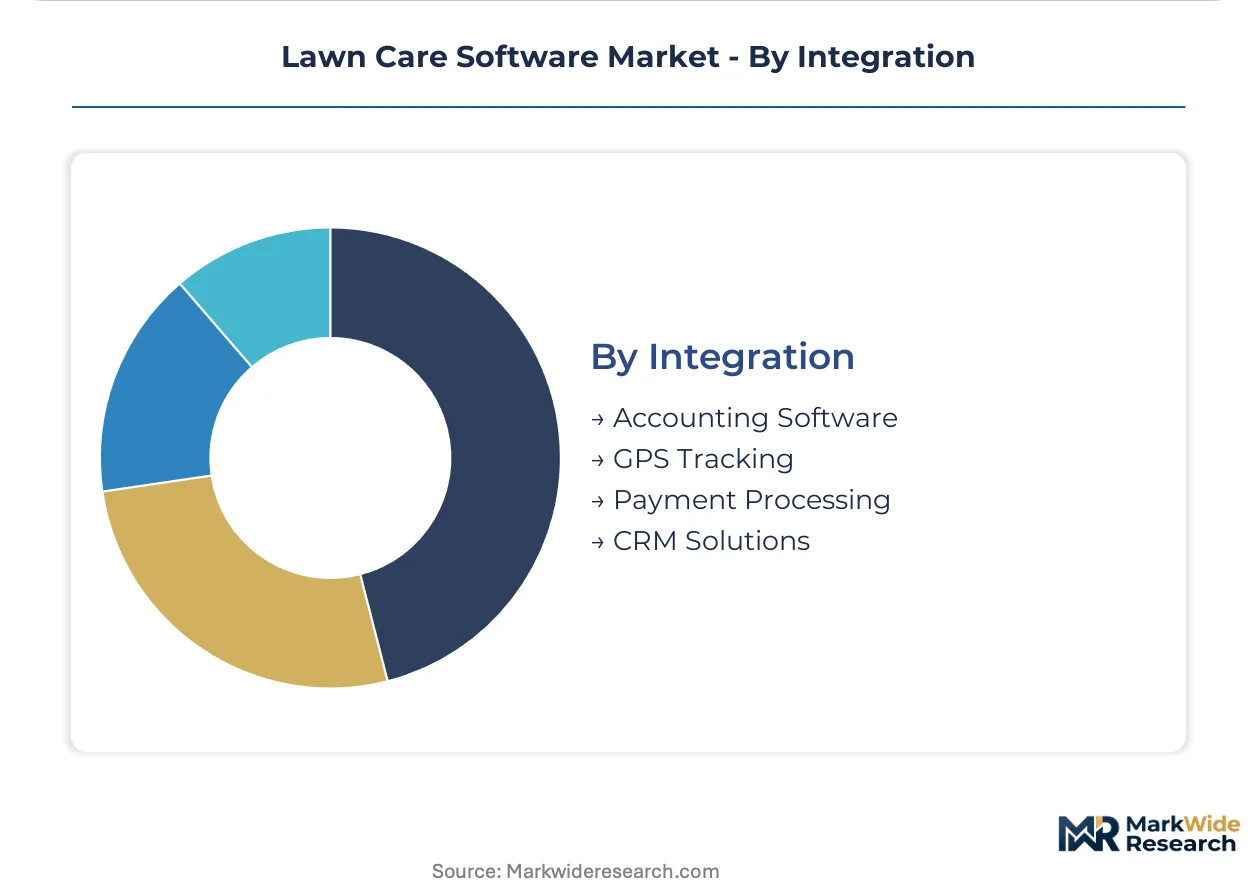
Third-party connectivity depth separates point solutions from platform ecosystems, with accounting and payment bridges commanding premium pricing.
- Accounting Software:API bridges to QuickBooks and Sage eliminate double-entry for bookkeepers. Legacy system synchronization remains a primary implementation pain point.
- GPS Tracking:Real-time fleet visibility enables dynamic rerouting and theft recovery. Timestamped geolocation data now mandatory for EPA stormwater compliance in chemical application logging.
- Payment Processing:Embedded card-present and ACH capabilities accelerate cash collection. Square and Stripe integrations dominate among independent operators.
- CRM Solutions:Bidirectional sync with Salesforce or HubSpot supports enterprise sales workflows. Franchise networks prioritize this integration for centralized lead management.
Payment processing integrations reach deepest penetration; GPS tracking is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dallas-Fort Worth anchors North American lawn care software procurement, where franchise networks and independent operators cluster around commercial landscaping corridors. EPA compliance mandates and HOA digital record requirements reshape procurement patterns across metro markets.
United States
Texas and Florida operators drive cloud adoption through homeowner association mandates for automated billing transparency. EPA Clean Water Act enforcement requires timestamped geolocation data for pesticide applications in stormwater-sensitive jurisdictions. Dallas-Fort Worth and Orlando metropolitan areas concentrate franchise headquarters seeking enterprise-grade compliance modules.
Canada
Prairie provinces exhibit minimal software penetration among snow-and-lawn hybrid operators despite operational scale. Health Canada and PMRA documentation requirements for chemical tracking lag behind US digitization timelines. Calgary and Edmonton service corridors present expansion targets for vendors offering seasonal subscription flexibility.
United Kingdom
Mid-sized landscaping firms in Greater London and Southeast England prioritize modular scheduling tools over integrated suites. GDPR data sovereignty requirements favor EU-hosted cloud infrastructure for customer record management. Manchester and Birmingham commercial districts concentrate demand for fleet tracking among multi-site property maintenance contracts.
Germany
Baden-Württemberg and Bavaria landscape professionals exhibit strong preference for on-premises data storage amid strict federal privacy enforcement. REACH chemical documentation standards exceed EPA stringency for material traceability. Stuttgart and Munich industrial suburbs host design-build specialists requiring CAD-integrated estimating platforms.
Australia
New South Wales and Victoria operators adopt mobile-first dispatch tools for dispersed suburban service territories. State-level environmental protection agencies mandate digital waste tracking for green waste removal contractors. Sydney and Melbourne metropolitan sprawl creates route optimization demand exceeding North American density models.
Lawn Care Software Market Competitive Landscape
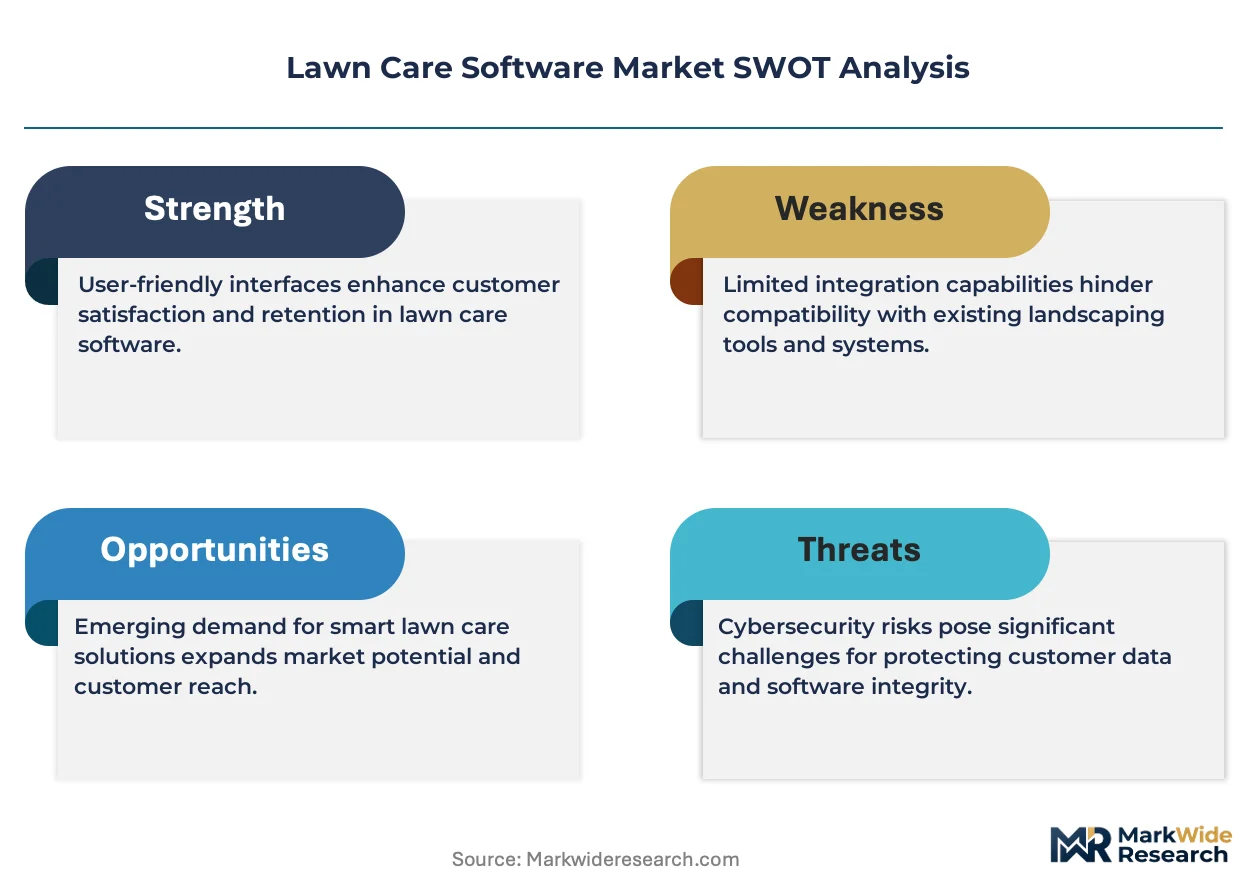
Capital-heavy platform developers compete with asset-light specialized vendors across deployment architectures. Market structure fragments across three tiers: enterprise suites commanding annual contracts above fifty thousand dollars, mid-market integrated platforms, and solo-operator SaaS tools. Strategic archetypes include vertical specialists emphasizing compliance automation, horizontal generalists spanning adjacent trades, and franchise-centric standardization providers. Consolidation pressure manifests through API acquisition strategies and white-label partnership networks.
Within the vertical specialist tier, ServiceTitan and LMN exemplify divergent positioning archetypes. ServiceTitan anchors the high-end commercial segment through deep accounting system integration. LMN occupies a specialized position among design-build landscape professionals with job-costing functionality. Jobber represents the balanced mid-market vector with scheduling-CRM convergence for scaling independents.
| Leading Market Players |
|---|
| Jobber |
| ServiceTitan |
| RealGreen |
| LMN |
| Service Autopilot |
| Aspire Software |
| Arborgold |
| LawnPro Software |
| WorkWave |
| Others |
Supply & Pricing Matrix
EPA Clean Water Act digitization mandates gate qualified supply for lawn care software vendors serving stormwater-sensitive jurisdictions, with timestamped geolocation compliance modules commanding premium-tier pricing access from commercial operators in Florida and California facing permit revocation risks.
Pricing Analysis
Per-crew throughput metrics anchor value-based pricing for multi-vehicle fleet operators seeking fuel and overtime reductions. Three-tier pricing structure across premium, standard, and economy levels separates enterprise compliance suites from modular SaaS tools for solo practitioners. Cost compression in the mid-market tier intensifies because AWS and Azure infrastructure pass-throughs fluctuate with cloud compute pricing. Franchise networks show least price sensitivity due to standardization requirements; independent seasonal operators in Arizona and Colorado demand month-to-month flexibility.
Supply Chain Analysis
Reverse-logistics flows for field hardware refreshes and legacy server decommissioning create secondary service revenue streams for hybrid deployment vendors. Software development concentrates in the United States, India, and Canada, with cloud infrastructure sourcing from AWS, Azure, and Google Cloud Platform. Raw material dependencies include silicon for mobile device endpoints, lithium for fleet tracking hardware, and rare earth elements for GPS module components. Single-source vulnerability rests on hyperscaler concentration for cloud hosting. Distribution runs through direct vendor sales teams, value-added resellers, and franchise network procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lawn care software functions as a consolidation play where EPA compliance retrofit costs and subscription fatigue force subscale point-solution vendors toward acquisition or exit.
For Market Incumbents: Cement platform stickiness by embedding OSHA safety training digitization ahead of proposed federal mandates, neutralizing emerging vertical specialists. Deepen API bridge investments to QuickBooks and Sage ecosystems, locking bookkeeper workflows against horizontal generalists. Franchise standardization requirements in Texas and Florida create channel control leverage.
For New Entrants and Emerging Players: The mid-market price-point gap between ServiceTitan enterprise suites and lean solo-operator tools offers white-space entry for design-build specialists needing CAD-integrated estimating. Canadian prairie provinces present underpenetrated geography for snow-and-lawn hybrid operators lacking seasonal subscription flexibility. Target Calgary and Edmonton service corridors with month-to-month SaaS positioning.
For Investors and Strategic Acquirers: OSHA's proposed crew safety training digitization mandate is the leading indicator that compliance module depth will separate viable platforms from commodity scheduling tools. Acquisition targets should demonstrate EPA stormwater documentation integration and state agriculture department certification pipelines. Long-term viability favors vendors with embedded regulatory logic rather than retrofitted compliance layers.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep API bridges to QuickBooks and Sage eliminate double-entry friction for bookkeeper-centric buyers. |
| Geographic Expansion | Calgary and Edmonton corridors offer first-mover advantage among snow-and-lawn hybrid operators. |
| Product Launch | OSHA-compliant safety training modules capture preemptive demand ahead of federal digitization mandates. |
| Strategic Partnership | White-label arrangements with franchise networks accelerate standardization-driven procurement velocity. |
| Acquisition of Specialist Firm | CAD-integrated estimating capabilities address design-build landscape professional willingness-to-pay premiums. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this lawn care software analysis, combined with primary interviews with green-industry software executives, franchise operations directors, independent landscaping firm owners, and state agriculture department licensing administrators. EPA enforcement documentation, HOA procurement guidelines, and cloud infrastructure capex disclosures from hyperscalers supplemented bottom-up and top-down triangulation.
Data-stream reconciliation across deployment architecture, end-user scale, and functional module segmentation shaped the analytical framework throughout the projection horizon. CAGRs derived from installed base growth, subscription renewal velocity, and compliance-driven upgrade cycles. Inputs included route density algorithms, crew dispatch automation penetration, and timestamped geolocation adoption for pesticide documentation.
Inputs from EPA enforcement records and state agriculture department filings were available through the study window; gaps in Canadian prairie province operator surveys introduce uncertainty bands around northern expansion trajectories. Forecasts reflect assumptions regarding HOA mandate propagation and OSHA digitization timeline adoption. Material deviation in EPA stormwater rule enforcement or hyperscaler pricing volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Data Quality Software Market
Software & Services
Architecture, Engineering, and Construction (AEC) Software Market
Software & Services
Global Guidewire Market
Software & Services
Network Bandwidth Management Software Market
Software & Services
India HR Payroll Software Market
Software & Services
Point Cloud Processing Software Market
Software & Services
Application Development and Deployment Software Market
Software & Services
Africa HR Payroll Software Market
Software & Services
Data Conversion Services Market
Software & Services
Multiexperience Development Platforms Market
Software & Services
3D Modeling Software Market
Software & Services
Global Employee Engagement Software Market
Software & Services
Global Enterprise Architecture Tools Market
Software & Services
Global Software Resellers Market
Software & Services
User Retention Software Market
Software & Services
HVAC Solution Software Market