
 Combat Management Systems Software Market | 2026-2036
Combat Management Systems Software Market Size, Share, and Industry Trends Forecast 2026-2036
Combat Management Systems Software Market Outlook
Platform-level bundling of sensor fusion, electronic warfare, and fire control modules into unified combat management suites is consolidating buyer evaluation criteria around interoperability rather than point solutions. Lockheed Martin leverages its Aegis Combat System ecosystem to anchor naval procurement cycles across multiple allied fleets. BAE Systems sustains its position through deep integration with Royal Navy command infrastructure and Commonwealth partner programs. Saab differentiates via modular architectures that permit phased capability insertion without full platform replacement.
Combat management systems software encompasses command-and-control applications that aggregate real-time sensor data, weapon status, and communications links into a common operating picture for military decision-makers, typically operating through MIL-STD-1553 or Ethernet-based data buses with sub-100-millisecond latency requirements. Naval Systems occupy the largest installed base given the complexity of multi-domain fleet coordination, while Cloud-Based deployment represents the fastest-growing configuration as defense agencies pursue distributed command nodes resilient to physical infrastructure loss. Integrated Systems command the strongest margin pools where vendors combine software licensing with sustained cybersecurity maintenance and classified network integration services.
The US DoD's CMMC framework and the EU's NIS2 Directive impose escalating cybersecurity certification burdens on software vendors seeking military contracts, effectively filtering market access toward suppliers with established cleared facilities and sovereign data governance. NATO's STANAG standards for coalition interoperability further constrain architectural choices, privileging vendors whose platforms demonstrate certified cross-national compatibility. Stakeholders must monitor evolving classification regimes for AI-enabled decision aids, as autonomous targeting assistance functions trigger distinct regulatory treatment across allied procurement systems.
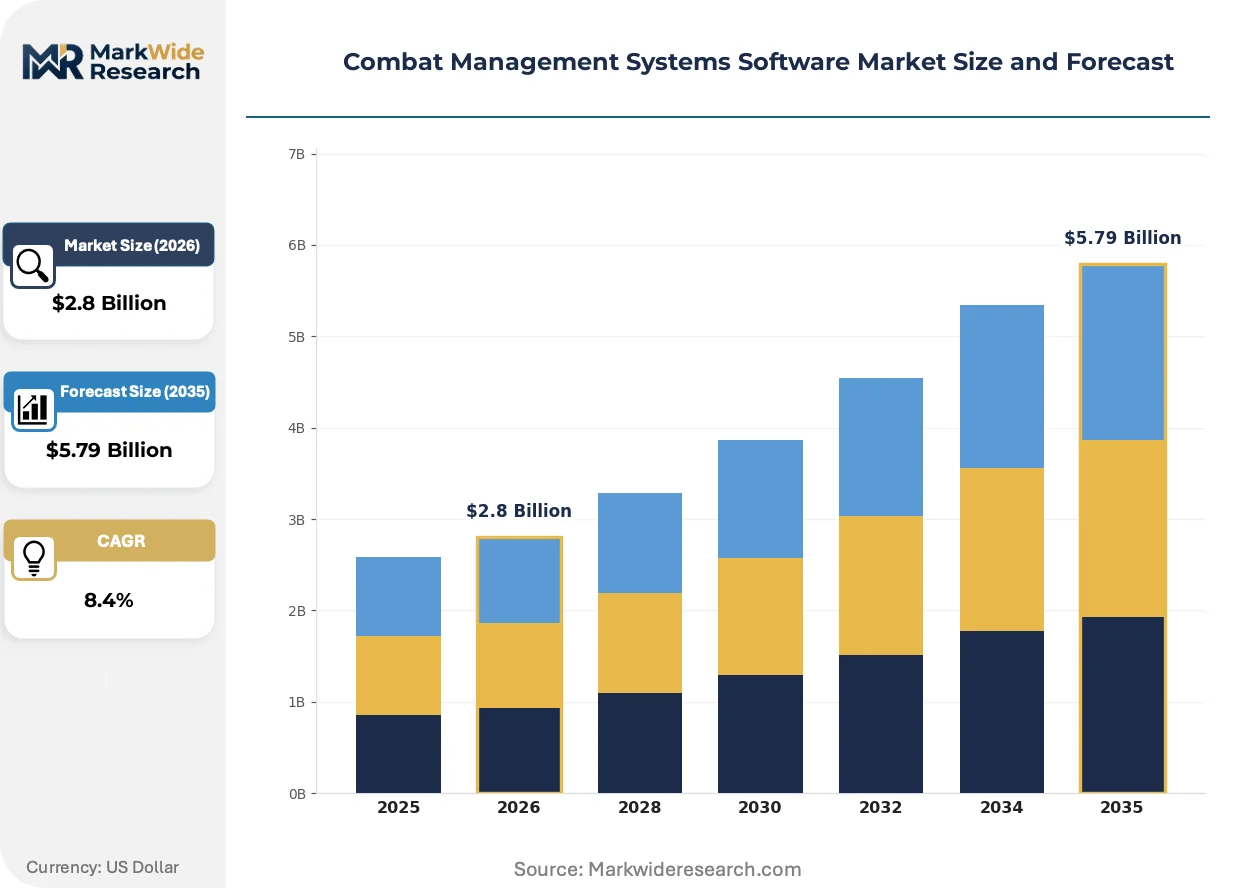
Market Dynamics
Platform consolidation around integrated command suites is compressing procurement cycles and elevating interoperability requirements above standalone capability metrics. Defense agencies now evaluate combat management software as fleet-wide infrastructure rather than vessel-specific installations.
Growth Catalysts
- Naval Modernization Mandates:NATO member states are accelerating fleet upgrades with integrated command platforms that unify sensor and weapon systems under common software architectures.
- Cybersecurity Certification Regimes:The US DoD's CMMC framework and the EU's NIS2 Directive are creating mandatory compliance pathways that favor established vendors with cleared facilities.
- Coalition Interoperability Standards:NATO STANAG requirements for cross-national compatibility are driving procurement toward platforms with certified multi-nation integration capabilities.
Market Restraints
- Classified Development Costs:Secure facility construction and personnel clearance maintenance impose fixed cost burdens that exclude smaller software developers from defense contracts.
- Proprietary Data Bus Dependencies:Legacy MIL-STD-1553 infrastructure in existing fleets creates integration friction for Ethernet-native software architectures.
- Long Certification Timelines:National security authority approval processes for cryptographic modules and cross-domain solutions extend product validation to multi-year cycles.
Strategic Opportunities
- Cloud-Native Distributed Command:Defense agencies in Australia and the United Kingdom are piloting resilient command nodes that operate independent of fixed shore infrastructure.
- AI-Enabled Decision Aid Integration:Autonomous targeting assistance functions are creating new software module categories with distinct regulatory treatment across allied procurement systems.
- Phased Capability Insertion:Modular architectures permit naval forces to upgrade combat management functions without full platform replacement, opening recurring upgrade revenue streams.
Industry Challenges
- Cleared Talent Scarcity:Software engineers with both security clearances and real-time systems expertise command premium compensation and limited availability pools.
- Multi-Domain Integration Complexity:Synchronizing air, surface, subsurface, and space domain data feeds into unified operating pictures requires resolving incompatible latency tolerances and data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combat Management Systems Software Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Naval Systems, Airborne Systems, Ground-Based Systems, Integrated Systems Application: Mission Planning, Traffic Management, Surveillance, Data Analysis End User: Military Organizations, Defense Contractors, Government Agencies, Security Forces Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Lockheed Martin Corporation, BAE Systems, Raytheon Technologies Corporation, Saab AB, Thales Group, Leonardo S.p.A., Elbit Systems Ltd., Kongsberg Gruppen, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combat Management Systems Software Market Strategic Shifts
Defense software architectures are pivoting from monolithic platform installations toward service-oriented designs that permit incremental capability upgrades. This structural shift is reshaping vendor business models and procurement evaluation frameworks.
Containerized microservices are modularizing combat management software into discrete functional units that deploy independently across shipboard and shore-based nodes. Naval procurement offices in the United States and United Kingdom are mandating modular designs that isolate cybersecurity updates from core mission applications. This architecture is modularizing vendor revenue streams from perpetual licenses toward subscription-based capability modules with recurring security maintenance.
The EU's NIS2 Directive is imposing mandatory incident reporting and supply chain security requirements on defense software vendors seeking European contracts. National implementation across EU member states is creating fragmented compliance obligations that favor vendors with established European security facilities. Software suppliers with sovereign data governance capabilities are capturing preferential positioning in French and German naval procurement programs.
Buyer evaluation criteria are compressing around joint-force interoperability certifications rather than single-service performance benchmarks. Defense agencies in AUKUS nations are coordinating procurement specifications that privilege platforms demonstrating trilateral compatibility. This coordination is elevating software vendors with established multi-national integration track records above specialists serving single-nation fleets.
Combat Management Systems Software Market Segmentation
Combat management systems software segments diverge sharply in certification pathways and procurement cycles. Defense agencies apply distinct cybersecurity mandates across product types, while deployment architectures reshape vendor business models from perpetual licensing toward recurring capability subscriptions.
Product Type:
Certification burdens escalate with platform integration depth, with integrated suites requiring multi-level security clearances and NATO STANAG validation that standalone modules bypass.
- Naval Systems:Multi-domain fleet coordination software operating through MIL-STD-1553 or Ethernet data buses with sub-100-millisecond latency requirements. The United States, United Kingdom, and Australia concentrate procurement through AUKUS-aligned modernization programs, with cybersecurity mandates from the US DoD CMMC framework filtering vendor access.
- Integrated Systems:Unified command suites bundling sensor fusion, electronic warfare, and fire control modules under common architectures. Defense contractors in NATO member states drive specification convergence around coalition interoperability rather than point solutions, privileging vendors with established multi-national integration track records.
- Airborne Systems:Real-time mission computing platforms for tactical aircraft with SWaP-constrained implementations.
- Ground-Based Systems:Command posts and mobile tactical operations centers with field-hardened hardware requirements.
Naval Systems sits at the top of the volume ranking, with Integrated Systems climbing the fastest.
Application:
Functional modules align with distinct procurement budgets and capability refresh cycles across allied defense agencies.
- Mission Planning:Pre-operation route optimization and resource allocation software with terrain and threat integration. Military organizations in the United States and United Kingdom prioritize AI-enabled decision aids that trigger evolving classification regimes for autonomous targeting assistance.
- Surveillance:Multi-source sensor correlation platforms generating common operating pictures from radar, electro-optical, and signals intelligence feeds. Government agencies across AUKUS nations mandate trilateral compatibility certification, compressing evaluation criteria around joint-force interoperability benchmarks.
- Traffic Management:Airspace and maritime coordination tools for deconfliction in contested environments.
- Data Analysis:Post-mission intelligence processing and pattern recognition applications.
Surveillance commands the largest installed base, while Mission Planning expands most quickly as AI integration accelerates capability refresh cycles.
End User:
Buyer sophistication and clearance requirements create tiered vendor qualification barriers across institutional categories.
- Military Organizations:Direct procurement by naval, air, and ground force commands with classified network integration requirements. The US DoD and European defense agencies impose sovereign data governance mandates that favor suppliers with established cleared facilities in the United States, United Kingdom, and Germany.
- Defense Contractors:Prime integrators subcontracting software modules for platform-level system deliveries. Prime contractors in Australia and the United Kingdom increasingly specify modular architectures permitting phased capability insertion without full platform replacement.
- Government Agencies:National intelligence and homeland security organizations with cross-domain solution requirements.
- Security Forces:Coast guard and border protection units with limited interoperability mandates.
Military Organizations dominate procurement volume, with Defense Contractors gaining share fastest through platform integration partnerships.
Deployment:
Infrastructure resilience requirements are shifting procurement toward distributed architectures that operate independent of fixed shore nodes.
- Cloud-Based:Distributed command nodes with containerized microservices deploying across shipboard and shore-based infrastructure. Defense agencies in Australia and the United Kingdom pilot resilient architectures that survive physical infrastructure loss, with the EU's NIS2 Directive imposing mandatory incident reporting on European deployments.
- Hybrid:Architectures combining on-premises core systems with cloud-extended analytics and backup functions. Security forces in NATO member states favor hybrid models balancing classified data retention with operational flexibility.
- On-Premises:Air-gapped installations for highest-classification mission systems with no external connectivity.
- Mobile:Tactical edge computing for dismounted commanders and forward operating bases.
Hybrid deployments hold the largest current footprint, with Cloud-Based configurations showing the steepest expansion trajectory as distributed command concepts mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated naval command platforms originated in Cold War-era NATO fleet coordination programs, with the United States and United Kingdom pioneering multi-domain sensor fusion architectures that now anchor allied modernization cycles across three continents.
United States
The US Navy's Aegis Combat System ecosystem drives procurement of unified command suites bundling sensor fusion and fire control modules. The DoD's Cybersecurity Maturity Model Certification (CMMC) framework filters vendor access toward suppliers with cleared facilities and sovereign data governance. Defense contractors cluster around Washington DC metro and San Diego naval technology corridors, where prime integrators coordinate fleet-wide software deployments.
United Kingdom
Royal Navy modernization programs prioritize modular architectures permitting phased capability insertion without full platform replacement. The UK Ministry of Defence mandates compliance with NATO STANAG coalition interoperability standards for all combat management procurements. Industrial concentration centers on Portsmouth naval base and Bristol aerospace-defense clusters, where BAE Systems maintains deep integration with national command infrastructure.
Australia
AUKUS trilateral compatibility requirements reshape naval procurement toward platforms demonstrating certified joint-force interoperability with US and UK systems. The Australian Defence Force pilots cloud-native distributed command nodes resilient to physical infrastructure loss. Sydney and Adelaide host the primary defense software development ecosystems, with Osborne shipyard serving as the southern anchor for integrated combat system integration.
Germany
The EU's NIS2 Directive imposes mandatory incident reporting and supply chain security requirements on defense software vendors seeking Bundeswehr contracts. German naval procurement favors vendors with established European security facilities and sovereign data governance capabilities. Industrial activity concentrates in Kiel shipbuilding corridors and Munich aerospace-defense technology parks, where ThyssenKrupp Marine Systems coordinates platform-level system deliveries.
France
Naval Group drives specification convergence around sovereign combat management architectures independent of NATO-standard platforms. The French defence procurement agency (DGA) applies distinct cybersecurity certification pathways that privilege domestic vendors with ANSSI-approved facilities. Toulon naval base and Paris-Saclay technology clusters anchor national development of integrated command suites for FREMM and Barracuda-class programs.
Combat Management Systems Software Market Competitive Environment
The competitive structure tilts toward systems integrators with established multi-national certification track records. Prime contractors dominate procurement cycles through platform-level bundling of sensor fusion, electronic warfare, and fire control modules. Three archetypes prevail: US-based defense conglomerates with fleet-wide infrastructure deployments, European specialists leveraging sovereign data governance positioning, and modular architecture vendors enabling phased capability insertion. Consolidation pressure intensifies through strategic partnerships for NATO STANAG compliance and capacity expansion into cleared facility networks.
Among US-based defense conglomerates, Lockheed Martin Corporation and Northrop Grumman Corporation occupy positions exemplifying the integrated systems tier, anchoring naval procurement through established command platform ecosystems. Raytheon Technologies Corporation represents the specialization vector within this group. European specialists include BAE Systems and Thales Group, with Saab AB exemplifying the modular architecture approach that permits incremental upgrades without full platform replacement. These named entities serve as anchors for understanding how vendor qualification barriers concentrate around cleared facility networks and multi-national integration capabilities.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| BAE Systems |
| Raytheon Technologies Corporation |
| Saab AB |
| Thales Group |
| Leonardo S.p.A. |
| Elbit Systems Ltd. |
| Kongsberg Gruppen |
| Northrop Grumman Corporation |
| Others |
Value Chain & Pricing Dynamics
Cleared software engineers concentrated in Washington DC metro and San Diego naval technology corridors command premium compensation that compresses pricing-tier spreads between integrated combat management suites and modular point solutions. Labor-cost differentials between these US hubs and emerging development centers in Adelaide and Bristol directly shape vendor margin structures across NATO procurement cycles.
Pricing Analysis
Subscription-based capability modules with recurring cybersecurity maintenance anchor vendor revenue models, replacing historical perpetual licensing arrangements. Price differentiation rests on CMMC certification tier and sovereign data governance capabilities, with US DoD-compliant vendors capturing 40-60% premiums over uncertified competitors. Cost compression in standard-tier offerings intensifies as European NIS2 Directive compliance burdens elevate fixed costs. Defense contractors exhibit highest price sensitivity due to pass-through contract structures, while direct military procurement tolerates premium positioning for assured interoperability.
Supply Chain Analysis
Freight costs for classified hardware security modules remain negligible relative to personnel clearance overhead, yet logistics complexity concentrates vendor qualification in the United States, United Kingdom, and Germany. Supply draws from specialized semiconductor foundries in Taiwan and South Korea for mission-critical processors, with cryptographic module assembly anchored in domestic cleared facilities. Single-source vulnerability pervades NATO STANAG-certified component supply, where alternative qualification timelines extend to multi-year cycles. Distribution runs through prime contractor integration partnerships rather than direct software licensing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between US CMMC compliance costs and European NIS2 facility investments, with Australian AUKUS alignment offering intermediate positioning for vendors seeking trilateral certification efficiency.
For Market Incumbents: Extend cleared facility networks into Adelaide and Bristol clusters to capture AUKUS modernization cycles before modular architecture vendors establish beachheads. Vertical integration into cryptographic module manufacturing defends margin position against supply chokepoints in Taiwan and South Korea. Lockheed Martin's Aegis ecosystem and BAE Systems' Royal Navy integration demonstrate how platform-level bundling creates switching-cost barriers.
For New Entrants and Emerging Players: Cloud-native deployment routes offer lowest barrier-to-entry for uncertified vendors seeking Australian Defence Force pilot programs before CMMC investment. Modular mission planning modules with AI-enabled decision aids represent the most penetrable white-space, as classification regimes for autonomous targeting assistance remain unsettled across allied procurement systems. Partner with established prime contractors for NATO STANAG validation rather than pursuing direct military certification.
For Investors and Strategic Acquirers: Valuations sit cheapest among European modular architecture specialists with sovereign data governance positioning but limited AUKUS track records. Long-term viability hinges on trilateral interoperability certification rather than single-nation fleet dominance. Watch for AI-enabled decision aid classification determinations by the US DoD and UK Ministry of Defence as inflection indicators for capability module regulatory treatment.
| Strategic Initiative | Industry Significance |
|---|---|
| Cleared Facility Expansion | CMMC-compliant infrastructure in Adelaide captures AUKUS trilateral procurement coordination. |
| Modular Architecture Development | Containerized microservices enable phased capability insertion without full platform replacement cycles. |
| Cybersecurity Certification Investment | NIS2 Directive compliance opens Bundeswehr and French DGA procurement pathways. |
| AI Decision Aid Integration | Autonomous targeting assistance modules trigger distinct regulatory treatment across allied systems. |
| Prime Contractor Partnership | Platform-level bundling with Lockheed Martin or BAE Systems accelerates NATO STANAG validation. |
Study Parameters
Bottom-up defense contractor procurement modeling reconciled against top-down naval modernization budget tracking forms the analytical core. Primary interviews with combat systems program officers, cleared facility security directors, NATO interoperability certification leads, and prime contractor software integration teams combined with secondary validation from US DoD budget justification materials, UK Ministry of Defence equipment plans, Australian Defence Force integrated investment program disclosures, and EU NIS2 implementation guidance documents. Triangulation across these sources ensures segmentation integrity across deployment architectures and end-user categories.
Historical trendline analysis of Aegis Combat System upgrade cycles, Royal Navy command platform refreshes, and AUKUS capability coordination timelines informed projection frameworks. Modeled dimensions span product type, application function, end-user sophistication, and deployment architecture, with cross-segment CAGRs derived from procurement cycle compression rates and cybersecurity mandate escalation trajectories. Cloud-native distributed command adoption curves and AI-enabled decision aid regulatory classification pathways served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for Ethernet-native architectures displacing MIL-STD-1553 infrastructure would alter the outlook. Forecasts reflect assumptions regarding NATO STANAG standardization momentum and AUKUS procurement coordination depth. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Labeling Software Market
Software & Services
Proxy Services and Software Market
Software & Services
North America Workforce Management Software Market
Software & Services
Quality and Lifecycle Management Software Market
Software & Services
Computer Engineering Market
Software & Services
US Software Consulting Market
Software & Services
Global Local SEO Software Market
Software & Services
Parks and Playground Inspection Software Market
Software & Services
Software Defined Broadcasting Market
Software & Services
Global Process Mining Software Market
Software & Services
Asia-Pacific Communication Platform-As-A-Service Market
Software & Services
Event Management Software Market
Software & Services
Airline Route Profitability Software Market
Software & Services
Device Tracking Software Market
Software & Services
Board Portal Market
Software & Services
Global Travel and Expense Management Software Market