
 Global Guidewire Market | 2026-2036
Global Guidewire Market Size, Share, and Industry Trends Forecast 2026-2036
Global Guidewire Market Foresight
Modular guidewire configurations with exchangeable tip designs is broadening physician choice across complex lesion subsets. Boston Scientific Corporation leverages integrated catheter-guidewire ecosystems to sustain procedural workflow control in electrophysiology labs. Medtronic anchors its position through specialized coronary guidewire portfolios optimized for chronic total occlusion interventions. Abbott differentiates via proprietary tip load and torque response technologies that compete on navigational precision in tortuous anatomy.
A guidewire is a thin, flexible medical device typically constructed from stainless steel or nitinol core wires with polymer jacketing and hydrophilic or hydrophobic coatings, designed to navigate vascular channels and provide rail support for catheter delivery during minimally invasive procedures. The device transmits rotational force from the proximal handpiece to the distal tip while maintaining column strength to resist buckling during advancement through stenosed vessels. Deployment through cloud-based inventory management systems is gaining traction as hospitals integrate consignment models with real-time usage tracking across cath lab networks. Application in property and casualty insurance segments for surgical complication coverage represents an emerging cross-sector demand vector as procedural volume data feeds risk analytics platforms.
The FDA enforces Class II medical device controls requiring 510(k) clearance for guidewire innovations, while the EU MDR mandates enhanced clinical evidence and post-market surveillance for coronary intervention devices sold in Europe. Japan's PMDA maintains distinct biocompatibility testing protocols that shape product registration timelines and material selection for manufacturers targeting Japanese interventional cardiologists. Stakeholders must monitor evolving reimbursement thresholds for percutaneous coronary intervention procedures as payers in Germany and the United States tighten evidence requirements for novel wire technologies.
Market Dynamics
The Global Guidewire Market is experiencing structural pressure from the migration toward outpatient-based catheterization labs, where procedure economics favor single-use disposables over reusable systems and inventory velocity trumps capital equipment depreciation cycles.
Growth Catalysts
- Chronic Total Occlusion Interventions:Aging patient demographics in the United States, Germany, and Japan are expanding the addressable pool for complex revascularization procedures requiring specialized guidewire platforms.
- EU MDR Compliance Deadlines:Enhanced clinical evidence requirements for coronary intervention devices are accelerating replacement cycles as hospitals upgrade to certified inventory before enforcement windows close.
- Nitinol Core Wire Technology:Superelastic nickel-titanium alloys with hydrophilic polymer coatings are improving lesion crossing success rates in tortuous vascular anatomy, driving physician preference shifts.
Market Restraints
- Nickel Price Volatility:Nitinol production depends on nickel feedstock subject to commodity market fluctuations, compressing margin stability for manufacturers with fixed-price hospital contracts.
- Supply Concentration in Japan:PMDA biocompatibility testing protocols create registration bottlenecks that limit qualified suppliers for Japanese interventional cardiologists.
- Reimbursement Compression:Tightening evidence requirements for percutaneous coronary intervention procedures in Germany and the United States are extending sales cycles for novel wire technologies.
Strategic Opportunities
- Cloud-Based Inventory Management:Consignment models with real-time usage tracking across cath lab networks are creating new service revenue streams and locking in procurement relationships.
- Property and Casualty Insurance Integration:Procedural volume data feeds into surgical complication coverage analytics, opening cross-sector demand from risk underwriting platforms.
- Exchangeable Tip Designs:Modular guidewire configurations are broadening physician choice across complex lesion subsets while reducing total inventory SKUs per hospital system.
Industry Challenges
- 510(k) Clearance Timelines:FDA Class II medical device controls require substantial equivalence demonstrations that delay product launches and extend development burn rates.
- Interventional Cardiologist Training Gaps:Complex chronic total occlusion techniques require specialized skills that outpace fellowship program curriculum updates, limiting addressable procedure volume.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Guidewire Market |
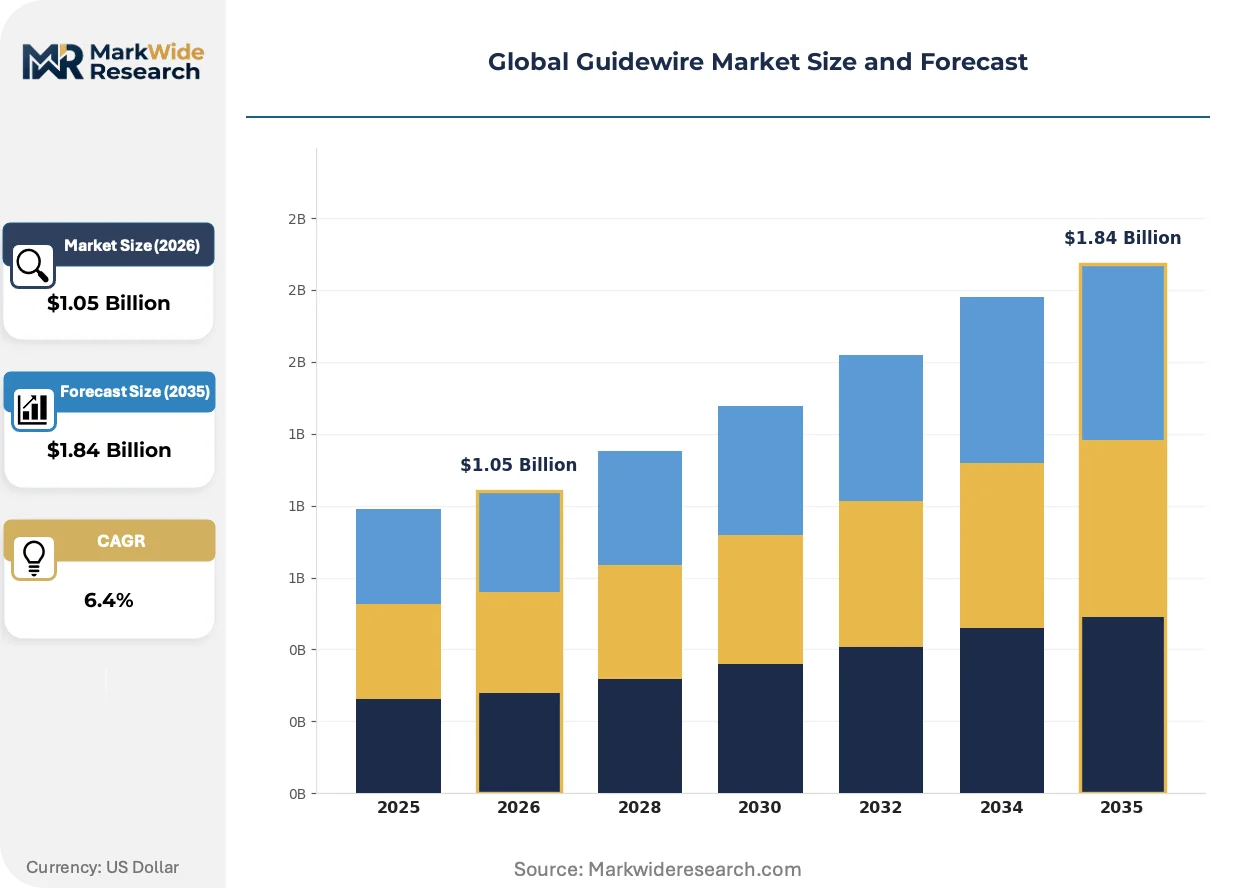
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Virtualized, Hosted Solution Offering: Claim Management, Billing & Payments, Policy Administration, Risk Analytics, Customer Engagement Application: Property & Casualty, Life Insurance, Reinsurance, Workers Compensation, Specialty Lines End User: Insurance Carriers, Brokers, Third-Party Administrators, Underwriters, Actuarial Firms |
| Companies Covered | Boston Scientific Corporation, Medtronic, Abbott, Cook Medical, Teleflex Incorporated, Cardinal Health, Merit Medical Systems, Terumo Medical Corporation, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Guidewire Market Shifts & Advancements
Guidewire architecture is fragmenting into componentized subsystems that separate core mechanical properties from distal tip characteristics, enabling procedure-specific customization without full device replacement.
Polymer jacketing with tunable hydrophilic coating gradients is modularizing the traditional stainless-steel guidewire paradigm. Tertiary hospital interventional cardiology suites are adopting these platforms fastest, particularly in the United States and Japan where procedure complexity justifies premium configurations. This technology is modularizing purchasing decisions away from monolithic wire families toward mix-and-match tip-core combinations that reduce inventory carrying costs.
EU MDR post-market surveillance mandates for coronary intervention devices are reshaping clinical evidence obligations across European markets. Manufacturers must now maintain active implant registries and periodic safety update reports that extend product lifecycle management costs. High-complexity chronic total occlusion portfolios face the steepest compliance burden, prompting portfolio rationalization among mid-tier suppliers.
Hospital procurement departments are consolidating vendor relationships through integrated catheter-guidewire ecosystem contracts that bundle disposable pricing with capital equipment service agreements. This behavior compresses standalone wire supplier access, particularly in German and Japanese hospital networks where group purchasing organizations wield concentrated negotiating leverage. Electrophysiology labs represent the most visible battleground for these bundled procurement contests.
Global Guidewire Market Segmentation
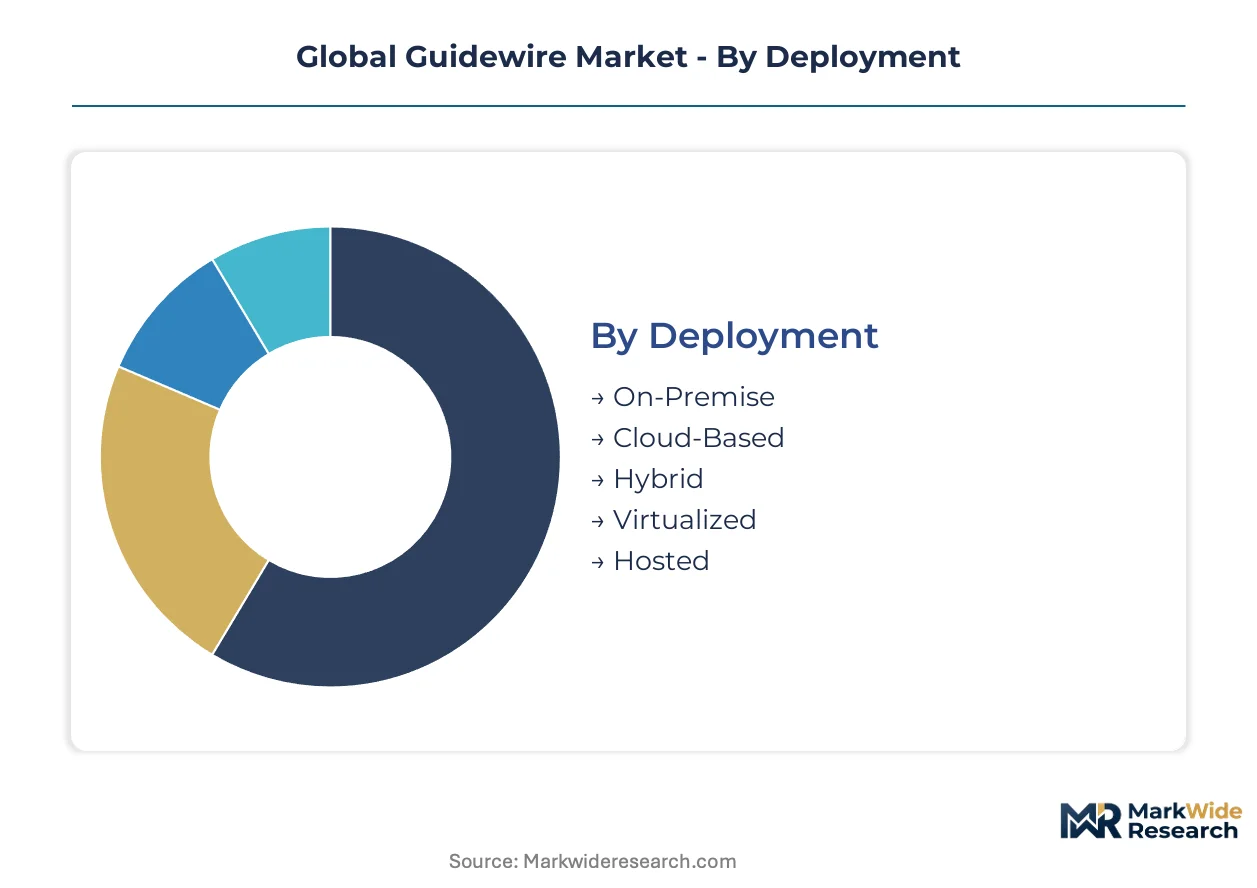
Guidewire market segmentation reveals how deployment architecture, solution depth, and buyer sophistication stratify purchasing decisions across insurance technology ecosystems. Understanding these divides illuminates where vendor consolidation versus specialization wins.
Deployment:
Volume deployments favor standardized infrastructure, while premium configurations demand bespoke integration layers.
- On-Premise:Dedicated hardware installations within carrier data centers deliver maximum data sovereignty and latency control for core policy systems. Large North American and European carriers with legacy mainframe dependencies sustain demand despite cloud migration pressure.
- Cloud-Based:Multi-tenant SaaS architectures eliminate capital expenditure cycles and accelerate feature deployment through continuous delivery pipelines. Mid-market carriers in the United States and Germany are concentrating procurement here, driven by IT headcount constraints and faster implementation timelines.
- Hybrid:Split workloads between on-premise core systems and cloud-native extensions balance regulatory compliance with innovation velocity.
- Virtualized:Containerized deployments across private infrastructure abstract hardware dependencies while preserving carrier-controlled environments.
- Hosted:Single-tenant managed services offload operational burden without surrendering infrastructure isolation.
Today's leader: On-Premise. Tomorrow's challenger: Cloud-Based.
Solution Offering:
Carriers prioritize modules that compress policy lifecycle duration from quote to bind.
- Claim Management:End-to-end loss notification, adjudication, and settlement workflows with embedded fraud detection algorithms. North American property and casualty carriers drive replacement cycles here, seeking to reduce loss adjustment expense ratios through straight-through processing automation.
- Policy Administration:Product configuration engines, rating, and issuance systems form the transactional core of carrier operations. German and Japanese insurers maintain the most complex product catalogs, sustaining demand for high-flexibility policy administration platforms.
- Billing & Payments:Premium collection, commission disbursement, and reconciliation modules with multi-currency support.
- Risk Analytics:Predictive modeling and catastrophe aggregation tools for underwriting portfolio optimization.
- Customer Engagement:Portal and mobile interfaces for policyholder self-service and agent collaboration.
Claim Management commands current procurement budgets; Risk Analytics is climbing the fastest as catastrophe modeling demands intensify.
Application:
Line-of-business complexity determines implementation scope and integration architecture.
- Property & Casualty:Multi-peril personal and commercial lines with rapid product iteration cycles and catastrophe-exposed portfolios. United States carriers dominate this segment, where severe weather frequency and litigation cost inflation drive technology replacement urgency.
- Life Insurance:Long-duration contracts with mortality risk modeling and complex illustration requirements. Japanese life carriers sustain specialized demand for legacy policy administration modernization.
- Reinsurance:Treaty and facultative placement systems with bordereau management and retrocession tracking.
- Workers Compensation:State-specific regulatory filing and medical cost containment workflows.
- Specialty Lines:Marine, aviation, and energy risks requiring bespoke coverage structures and Lloyd's market integration.
Property & Casualty anchors vendor revenue; Specialty Lines offers the steepest expansion trajectory through delegated authority platform growth.
End User:
Buyer type dictates procurement authority and implementation risk tolerance.
- Insurance Carriers:Direct writers and mutuals with full technology ownership and multi-year transformation budgets. Tier-one carriers in Germany and the United States consolidate vendor relationships through enterprise-wide platform commitments.
- Brokers:Intermediaries requiring placement, servicing, and commission accounting systems for multiple carrier panels. Large retail brokers in London and New York drive demand for consolidated placement platforms.
- Third-Party Administrators:Claims outsourcing specialists needing scalable workflow engines across multiple carrier clients.
- Underwriters:Managing general agents and coverholders with delegated authority requiring rapid product deployment capabilities.
- Actuarial Firms:Consulting organizations delivering reserving and pricing analyses with data aggregation and visualization tools.
Insurance Carriers retain procurement dominance; Brokers are gaining share fastest as intermediary consolidation creates enterprise-scale technology buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Interventional cardiology suites in tertiary hospitals first achieved scale in the United States during the 1980s, establishing the procedural templates and device specifications that later diffused to Germany and Japan. These three markets now concentrate the majority of specialized guidewire procurement.
United States
Aging demographics expand eligible patient pools for chronic total occlusion interventions at Cleveland Clinic and Mayo Clinic networks. FDA 510(k) clearance pathways shape product launch timelines for nitinol-core devices. The Texas Medical Center in Houston anchors high-volume adoption of hydrophilic-coated platforms.
Germany
EU MDR compliance deadlines accelerate hospital inventory replacement cycles ahead of enforcement windows. Heidelberg University Hospital and Charité Berlin drive demand for modular exchangeable-tip configurations. The Rhine-Ruhr metropolitan cluster concentrates catheterization lab procurement authority.
Japan
PMDA biocompatibility testing protocols create registration bottlenecks that limit qualified suppliers. Tokyo's Juntendo University Hospital and Osaka University Hospital favor superelastic nickel-titanium alloys for tortuous anatomy navigation. The Kanto region dominates interventional cardiologist training program enrollment.
United Kingdom
NHS England procurement frameworks consolidate vendor relationships through integrated catheter-guidewire ecosystem contracts. Guy's and St Thomas' NHS Foundation Trust in London pilots cloud-based inventory management with real-time usage tracking. The Oxford-Cambridge-London golden triangle attracts electrophysiology lab specialization.
Switzerland
Swissmedic maintains distinct post-market surveillance requirements that extend product lifecycle management costs. University Hospital Zurich and Geneva University Hospitals prioritize navigational precision in tortuous anatomy procedures. The Basel-Zurich corridor concentrates medical device regulatory consulting expertise.
Global Guidewire Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coating technology sophistication and lesion-crossing performance. The vendor base concentrates around integrated catheter-guidewire ecosystems and specialized coronary portfolios. Three archetypes dominate: diversified medical technology conglomerates with full procedural workflow control, mid-cap interventional specialists with chronic total occlusion focus, and Japanese precision manufacturers with PMDA-optimized biocompatibility profiles. Competitive moves center on bundled procurement contests and cloud-based inventory management service layers that lock in hospital system relationships.
Among diversified medical technology conglomerates, Boston Scientific Corporation, Medtronic, and Abbott exemplify the integrated ecosystem archetype. These Massachusetts-, Ireland-, and Illinois-based entities occupy positions where procedural workflow control extends beyond discrete device sales into capital equipment service agreements and real-time usage analytics. Their scale anchors enterprise-wide platform commitments at tier-one hospital networks.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Abbott |
| Cook Medical |
| Teleflex Incorporated |
| Cardinal Health |
| Merit Medical Systems |
| Terumo Medical Corporation |
| Olympus Corporation |
| Others |
Supply & Pricing Matrix
Nickel price volatility on the London Metal Exchange cascades through nitinol alloy production into tiered guidewire pricing, compressing margin stability for manufacturers locked into fixed-price hospital contracts while rewarding those with backward-integrated feedstock control.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates hydrophilic-coated nitinol platforms from basic stainless-steel configurations from commodity uncoated wires. Price differentiation hinges on FDA 510(k) clearance tier and procedural complexity rating, with chronic total occlusion portfolios commanding the widest spreads. Cost compression in the economy tier is intensifying because German and Japanese group purchasing organizations consolidate vendor relationships. Ambulatory surgery centers exhibit the highest price sensitivity, while tertiary hospital electrophysiology labs absorb premium configurations with limited negotiation leverage.
Supply Chain Analysis
Dual-sourcing requirements from United States hospital networks mandate PMDA-qualified Japanese suppliers alongside EU MDR-certified European manufacturers, fragmenting procurement authority across regulatory jurisdictions. Nitinol feedstock draws from nickel mining concentrates in Indonesia and Russia, with superelastic wire drawing concentrated in Japan and Germany. Single-source vulnerability persists in hydrophilic polymer coatings, where proprietary formulations lock buyers into specific vendor ecosystems. Distribution runs through consignment models with real-time usage tracking across integrated catheter-guidewire ecosystem contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between United States FDA 510(k) pathways and Japan's PMDA biocompatibility testing protocols creates cost and timeline differentials that reward manufacturers with dual-registration capabilities and penalize single-market players.
For Market Incumbents: Anchor ecosystem control through integrated catheter-guidewire procurement contracts that bundle disposable pricing with capital equipment service agreements, neutralizing standalone wire supplier threats. Deepen backward integration into nitinol alloy production to offset nickel commodity volatility and secure margin stability against fixed-price hospital commitments.
For New Entrants and Emerging Players: Capture cloud-based inventory management service layers as entry wedges, offering real-time usage analytics to mid-tier hospital systems neglected by conglomerate vendor consolidation. Target ambulatory catheterization labs in the United States with modular exchangeable-tip configurations that reduce inventory carrying costs and accelerate procurement decisions outside GPO-dominated networks.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap interventional specialists possessing chronic total occlusion portfolios and active PMDA registrations, as EU MDR compliance deadlines force portfolio rationalization among sub-scale competitors. Watch PMDA registration timeline compression as the inflection signal indicating Japanese market access premium expansion or contraction.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Expedited clearance pathways compress product launch timelines for nitinol-core devices in United States tertiary networks. |
| CE Marking Pathway Investment | EU MDR clinical evidence requirements anchor European hospital upgrade cycles ahead of enforcement windows. |
| Hospital System Partnership | Integrated catheter-guidewire ecosystem contracts with Cleveland Clinic and Mayo Clinic networks lock in procurement relationships. |
| Software Companion Development | Cloud-based inventory management platforms with real-time usage tracking create recurring service revenue streams. |
| Reimbursement Strategy | CMS Medicare coverage alignment for percutaneous coronary intervention procedures shapes physician adoption curves. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation through FDA 510(k) filings, PMDA registration databases, hospital procurement records, and EU MDR notified body certificates. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored market sizing across the analysis window.
Segment-weighted forecasting applied deployment architecture, solution depth, coating technology tier, and regional regulatory cluster dimensions throughout the projection horizon. CAGRs derived from procedure volume elasticity to aging demographic penetration rates and technology replacement cycle acceleration, with nickel price trajectory and reimbursement threshold evolution as sensitivity inputs.
EU MDR enforcement delays, PMDA registration backlog resolution, and nickel commodity price spikes are the dominant revision risks to the outlook. Deviation in PMDA timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
HACCP Software Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Global Customer Journey Mapping Software Market
Software & Services
Data Integration Software/Tool Market
Software & Services
Electronic Batch Records Market
Software & Services
Compensation Software Market
Software & Services
Urban Planning Software and Services Market
Software & Services
Global Handyman Software Market
Software & Services
Global Webinar Software Market
Software & Services
Global Retail Management Systems Software Market
Software & Services
Labor Management Software Market
Software & Services
Lighting Control Software Market
Software & Services
Contract Abstraction Software Market
Software & Services
Collaborative Applications Market
Software & Services
Global Florist Software Market
Software & Services
Production Optimization Software Market