
 Digital Illustration App Market | 2026-2036
Digital Illustration App Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Illustration App Market Outlook
Freemium-to-subscription conversion models are reconfiguring capital requirements for new entrants in the digital illustration space. Adobe Inc. leverages its Creative Cloud ecosystem to sustain recurring revenue across professional tiers. Procreate anchors premium mobile workflows for iPad-dependent illustrators. Krita Foundation competes through open-source distribution that eliminates licensing friction for hobbyists and educators.
Digital illustration apps are software platforms that enable image creation through vector mathematics, raster pixel manipulation, or procedural 3D geometry, typically supporting pressure-sensitive stylus input, layer-based compositing, and color spaces such as RGB or CMYK for print-ready output. Their primary commercial purpose spans concept art, editorial illustration, UI/UX asset generation, and animated content production. Vector graphics dominates enterprise licensing due to scalability demands in branding and packaging workflows. Mobile apps represent the fastest-expanding technology segment as tablet processors now match desktop rendering performance for most illustration tasks. Subscription services concentrate margin pools through predictable annual commitments from professional users.
The Federal Trade Commission scrutinizes auto-renewal billing practices within app store ecosystems, directly affecting how developers structure trial-to-paid transitions. The EU AI Act imposes transparency requirements on generative features embedded in illustration tools, shaping R&D roadmaps for European market compliance. ISO standards for color management govern cross-platform file fidelity that professional clients demand. Stakeholders must weigh regulatory compliance costs against the competitive necessity of integrating AI-assisted generation into core feature sets.
Market Dynamics
Generative AI integration is compressing production timelines for freelance illustrators and design studios, forcing established platforms to restructure subscription tiers around assisted workflows rather than pure tool access.
Growth Catalysts
- Cloud Rendering Infrastructure:Distributed GPU clusters eliminate local hardware requirements for independent artists in Brazil and Southeast Asia, expanding addressable creator pools.
- EU AI Act Transparency Mandates:Disclosure requirements for generative outputs are accelerating development of provenance-tracking features that enterprise clients now specify in procurement contracts.
- Freelance Platform Expansion:Design marketplaces are bundling illustration tools into creator dashboards, embedding software access directly inside gig economy workflows.
Market Restraints
- Input Cost Volatility:Cloud compute pricing fluctuations directly pressure margins for browser-based rendering services dependent on AWS, Azure, or Google Cloud spot instances.
- Supply Concentration Risk:Pressure-sensitive stylus technology concentrates among three component suppliers in Taiwan and South Korea, creating single-source vulnerabilities for tablet-dependent apps.
- Technical Limitation:Vector-raster file interoperability gaps persist across Procreate, Adobe Illustrator, and Affinity Designer, forcing manual asset reconstruction in multi-tool workflows.
Strategic Opportunities
- Underpenetrated Geography:India's tier-two cities show minimal professional illustration software adoption despite 400,000+ design graduates annually entering freelance markets.
- Technology Convergence:Real-time collaboration layers merging vector editing with video conferencing are displacing static file handoffs in remote studio environments.
- Regulatory Tailwind:Japan's METI digital skills certification program subsidizes software licensing for SMEs, creating funded entry paths for mid-tier platform vendors.
Industry Challenges
- Skill Gap in AI-Assisted Workflows:Traditional illustrators lack training in prompt engineering and generative control parameters, slowing enterprise adoption despite tool availability.
- Certification Timeline Compression:ISO color management compliance cycles now overlap with annual platform updates, forcing redundant re-certification for print-service integrations.
- IP Licensing Complexity:Training data provenance disputes surrounding generative models create legal exposure for platforms embedding AI features without clear rights chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Illustration App Market |
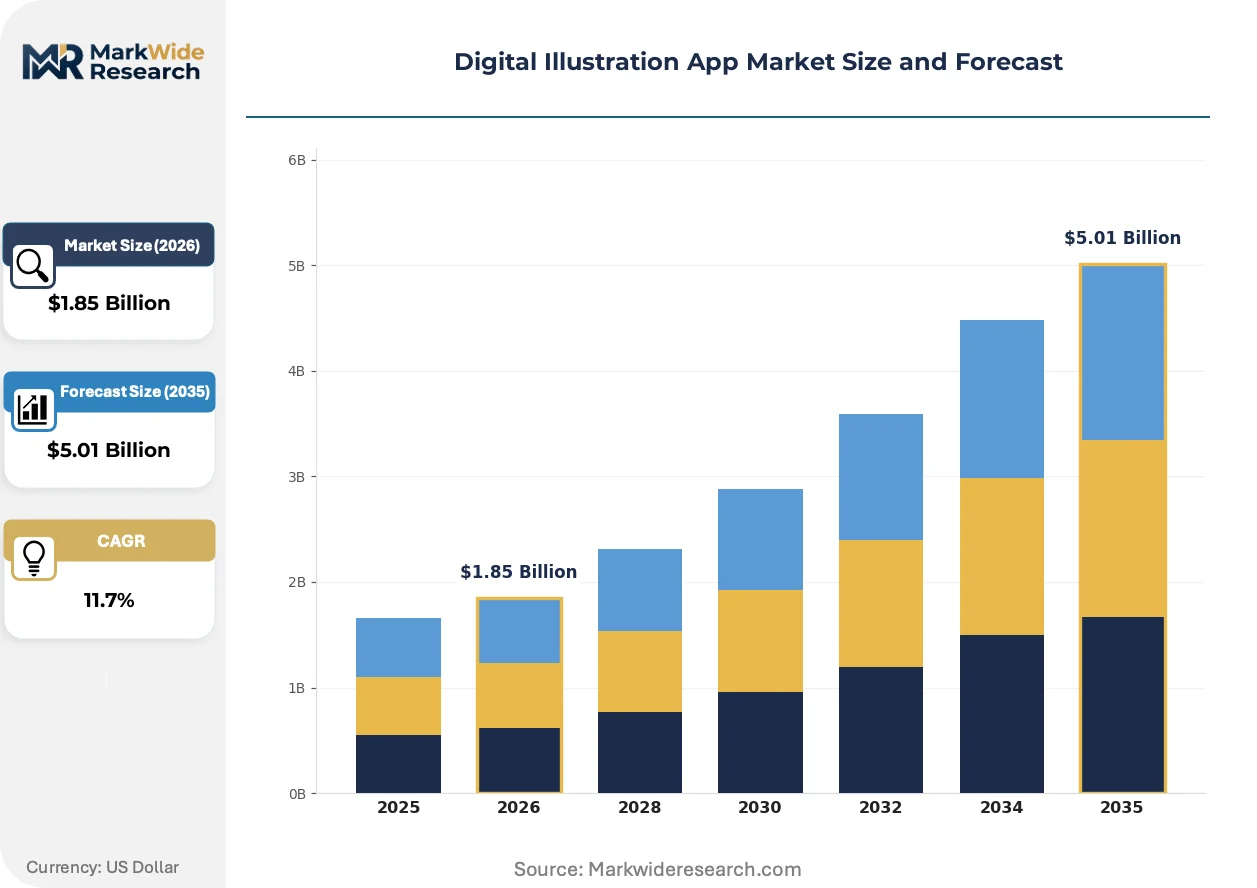
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.01 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vector Graphics, Raster Graphics, 3D Modeling, Animation End User: Professional Artists, Hobbyists, Designers, Educators Technology: Cloud-Based, Desktop Software, Mobile Apps, Mixed Reality Distribution Channel: Direct Downloads, App Stores, Subscription Services, Bundled Offerings |
| Companies Covered | Adobe Inc., Corel Corporation, Autodesk Inc., CELSYS Inc., Ibis Inc., MediBang Inc., Procreate, Krita Foundation, Serif Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Illustration App Market Strategic Shifts
Workflow automation is redefining how illustration assets move from concept to production, collapsing handoff friction between creators and their commercial clients.
Neural style transfer is digitizing the labor-intensive process of aesthetic adaptation across brand guidelines. Marketing agencies in Germany and the United States are deploying these tools to localize campaign visuals for regional markets without retaining additional illustrators. The technology is digitizing what previously required days of manual reinterpretation into sub-hour turnaround cycles.
The EU AI Act's transparency requirements are mandating embedded metadata standards for AI-generated image outputs. European publishers and advertising networks must now verify content provenance to satisfy platform liability rules. French creative studios are restructuring approval workflows to accommodate automatic tagging systems that document human versus machine contribution.
Subscription unbundling is fragmenting how professional illustrators acquire capability. Individual creators in Canada and Australia are assembling toolchains from specialized single-function apps rather than accepting comprehensive suites with redundant features. This pattern concentrates payment flows toward narrowly scoped utilities with superior interoperability rather than ecosystem lock-in.
Digital Illustration App Market Segmentation
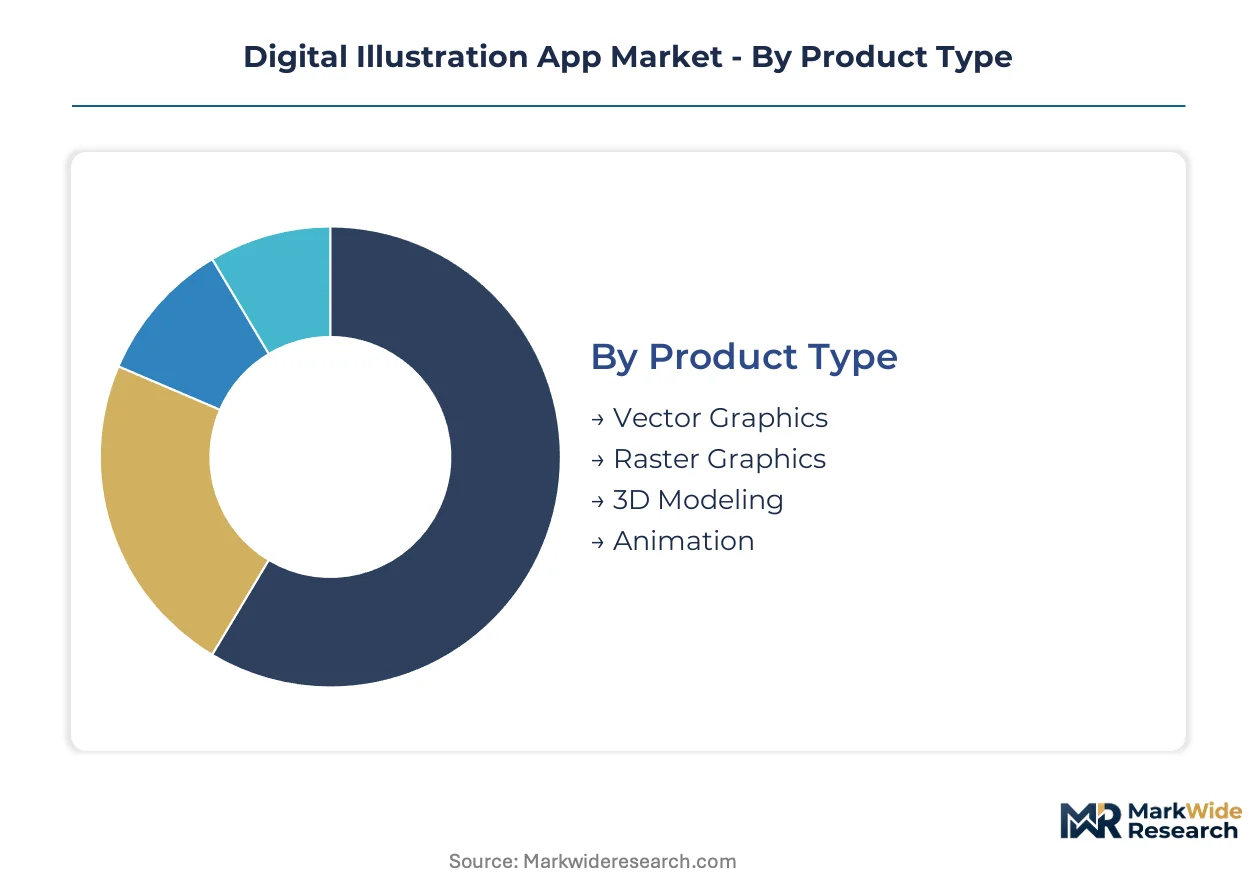
Segmentation in digital illustration apps reveals how technical specifications, user sophistication, and delivery mechanisms create distinct margin pools. Each dimension shapes procurement patterns and platform development priorities differently.
Product Type:
Mature vector workflows coexist with emerging 3D capabilities as studios diversify output requirements across static and immersive media.
- Vector Graphics:Mathematical path-based rendering enables infinite scalability without resolution loss. Demand concentrates among branding agencies in Germany and the United States, where logo and packaging workflows require CMYK-ready output for print production.
- Raster Graphics:Pixel-based manipulation supports organic brushwork and photographic compositing through layer-based architectures. Professional concept artists in Japan and Canada drive adoption, prioritizing pressure-sensitive stylus responsiveness for texture work.
- 3D Modeling:Procedural geometry tools enable volumetric asset creation for game engines and AR applications.
- Animation:Timeline-based keyframe systems support motion graphics and character rigging for streaming content pipelines.
Vector Graphics retains volume leadership; 3D Modeling holds the steepest expansion curve.
End User:
Cost tier differentiation separates enterprise procurement from individual creator spending patterns.
- Professional Artists:Full-time illustrators require color-calibrated workflows, asset management systems, and client collaboration tools. Studios in France and the United Kingdom specify ISO-compliant color management in vendor contracts.
- Designers:UX practitioners and graphic designers prioritize interoperability with prototyping tools and design system libraries. Demand clusters in South Korea's tech sector and Sweden's startup ecosystem.
- Hobbyists:Casual creators drive freemium conversion metrics through mobile-first interfaces.
- Educators:K-12 and university programs require volume licensing with curriculum integration and student progress tracking.
Designers retain volume leadership; Professional Artists hold the steepest expansion curve.
Technology:
Volume distribution across deployment models reflects hardware access patterns and connectivity infrastructure quality.
- Cloud-Based:Browser-rendered interfaces eliminate local GPU requirements through distributed compute clusters. Independent artists in Brazil and Indonesia access capabilities previously requiring workstation investments.
- Mobile Apps:Tablet-optimized touch interfaces with Apple Pencil and S Pen support enable portable production workflows. Procreate's iPad dominance anchors this segment's premium positioning.
- Desktop Software:Native applications leverage local hardware acceleration for complex layer stacks and high-resolution output.
- Mixed Reality:Spatial computing interfaces enable 3D sculpting in immersive environments using hand tracking and gesture controls.
Desktop Software retains volume leadership; Cloud-Based holds the steepest expansion curve.
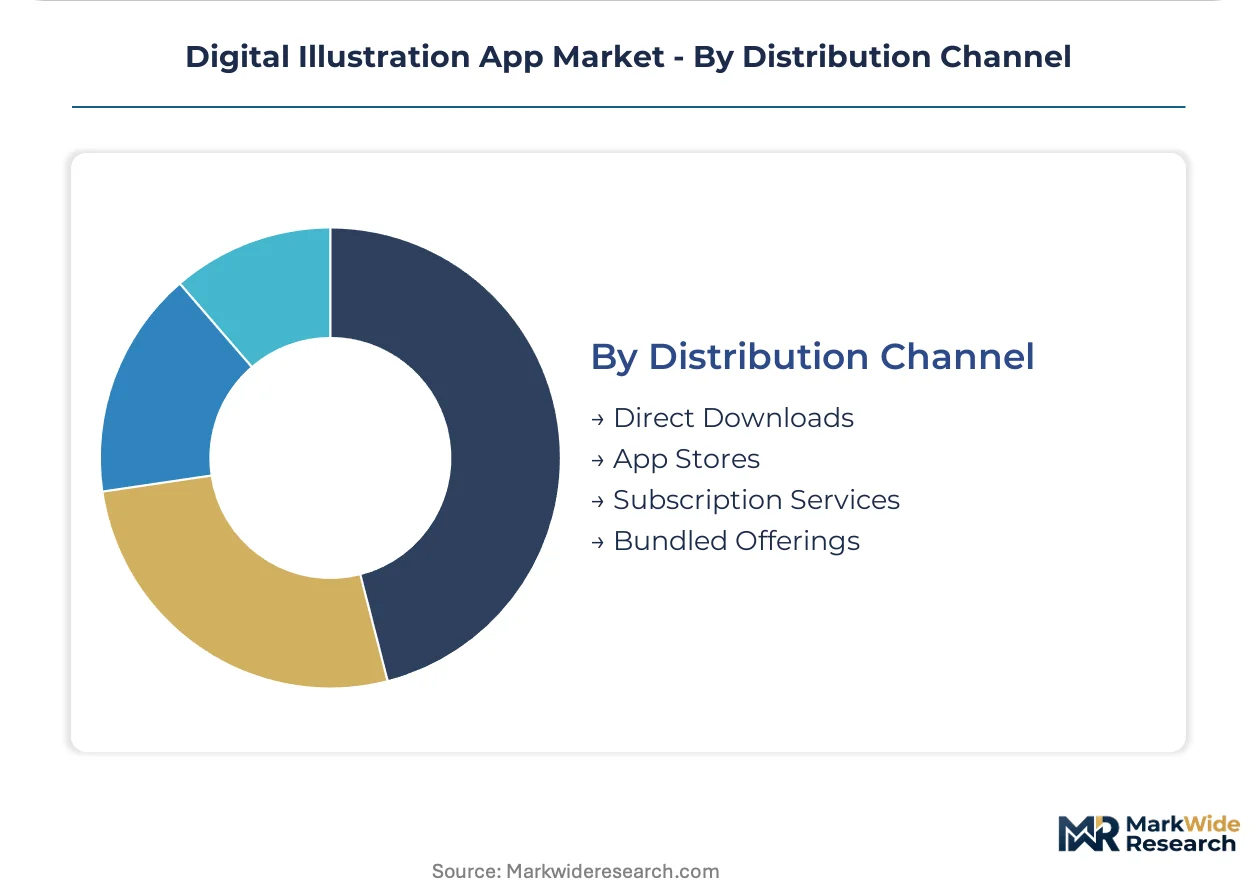
Distribution Channel:
Margin structures vary dramatically between direct relationships and platform-mediated transactions.
- Subscription Services:Recurring revenue models with tiered capability access dominate professional user acquisition. Adobe's Creative Cloud exemplifies annual commitment structures that reduce churn.
- App Stores:Apple App Store and Google Play commission structures shape pricing for mobile-first products. Discovery algorithms determine visibility for independent developers.
- Direct Downloads:Developer-controlled distribution bypasses platform fees but requires independent payment processing and update infrastructure.
- Bundled Offerings:Hardware manufacturers and freelance platforms include software access as value-added components.
Subscription Services retains volume leadership; Bundled Offerings holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government digital skills subsidies and freelance platform expansion are reconfiguring geographic adoption patterns for illustration software. National regulators impose divergent compliance burdens on generative AI features. Creative industry clusters concentrate demand in specific metropolitan corridors.
United States
Professional design studios and freelance illustrators drive subscription revenue concentration. The FTC scrutinizes auto-renewal billing practices in app store ecosystems, forcing developers to restructure trial-to-paid transitions. Los Angeles and New York anchor motion graphics and editorial illustration workflows respectively.
Germany
Branding agencies and packaging designers require CMYK-ready vector output for print production. REACH and RoHS compliance frameworks govern hardware peripherals used in stylus-dependent workflows. Berlin's startup ecosystem incubates browser-based collaborative tools targeting remote studio environments.
Japan
Concept artists and manga studios prioritize pressure-sensitive stylus responsiveness for texture work. METI's digital skills certification program subsidizes software licensing for SMEs, creating funded entry paths for mid-tier vendors. Tokyo's animation production houses integrate illustration tools with streaming content pipelines.
South Korea
UX practitioners and tech sector designers demand interoperability with prototyping tools. The country's national technology regulator enforces data localization requirements for cloud-rendered creative assets. Seoul's gaming studios drive 3D modeling adoption for real-time engine integration.
India
Tier-two cities show minimal professional software adoption despite substantial design graduate output entering freelance markets. BIS standards for electronics peripherals influence stylus hardware certification requirements. Bangalore's tech workforce and Mumbai's advertising clusters represent contrasting adoption profiles.
Digital Illustration App Market Competitive Environment
On the supply side, the industry is tiered between comprehensive ecosystem providers, specialized mobile-native platforms, and open-source community projects. Strategic archetypes include subscription-anchored suites, hardware-coupled premium apps, and zero-licensing-cost alternatives. Dominant competitive moves center on generative AI feature integration and cloud collaboration layer deployment.
Within the ecosystem-provider tier, Adobe Inc. exemplifies recurring revenue concentration through bundled creative suites. Procreate occupies a position as the premium mobile-native standard for tablet-dependent professionals. Krita Foundation represents the open-source archetype eliminating licensing friction for educational and hobbyist segments.
| Leading Market Players |
|---|
| Adobe Inc. |
| Corel Corporation |
| Autodesk Inc. |
| CELSYS Inc. |
| Ibis Inc. |
| MediBang Inc. |
| Procreate |
| Krita Foundation |
| Serif Labs |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific shipping lanes from Taiwan and South Korea carry pressure-sensitive stylus components that concentrate supply-side leverage among three hardware vendors, translating directly into tiered SaaS pricing power for tablet-dependent platforms and forcing browser-based alternatives toward cost-plus models to offset cloud compute volatility.
Pricing Analysis
Certification level creates the primary spread between enterprise and individual tiers, with ISO-compliant color management suites commanding subscription premiums from French and German design studios while freemium mobile apps absorb hobbyist price sensitivity through ad-supported entry points. Adobe's annual commitment structure anchors professional tier stability, though cost compression in mid-market cloud rendering is intensifying because AWS spot instance volatility pressures browser-native competitors. Freelance illustrators in Brazil and Southeast Asia exhibit highest price elasticity, while bundled hardware-software offerings from Procreate lock in lowest churn among iPad-dependent professionals.
Supply Chain Analysis
Foxconn and Pegatron concentration in Taiwan and China dominates tablet manufacturing assembly, with Wacom and Elan Microelectronics drawing from single-source capacitive sensor foundries in South Korea and Japan. Stylus tip materials and GPU cloud clusters represent critical input dependencies, while tariff exposure on Taiwanese semiconductor components threatens margin stability for hardware-coupled software vendors. Distribution runs through Apple App Store and Google Play commission structures for mobile-first products, with direct enterprise licensing bypassing platform fees for volume procurement by design studios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Creator workflow fragmentation is opening niche entry points as subscription unbundling drives Canadian and Australian illustrators toward specialized single-function tools rather than comprehensive suites.
For Market Incumbents: Build ecosystem lock-in through generative AI feature integration that embeds proprietary training data pipelines, defending against open-source alternatives like Krita Foundation by accelerating ISO color management re-certification cycles and securing exclusive stylus hardware partnerships with Taiwan-based component suppliers to tighten supply-side control. For New Entrants and Emerging Players: Establish a beachhead in India's tier-two cities by bundling curriculum-integrated tools with METI-style government subsidy programs, targeting the 400,000 annual design graduates entering freelance markets with mobile-first cloud rendering that eliminates local GPU investment and leverages browser-native accessibility over established desktop incumbents. For Investors and Strategic Acquirers: Cloud-native collaborative platforms with real-time vector-video convergence capabilities represent the highest-conviction acquisition archetype, with long-term viability hinging on generative provenance-tracking compliance as the EU AI Act expands disclosure mandates; watch for inflection when Japanese animation studios begin specifying automatic human-machine contribution tagging in vendor procurement contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Feature Integration | Adobe and Procreate embed assisted workflows to restructure subscription tiers around output velocity rather than pure tool access. |
| Cloud Collaboration Layer Deployment | Browser-based platforms merge vector editing with video conferencing to displace static file handoffs in remote German studios. |
| Hardware-Coupled Premium Positioning | Tablet-native apps leverage Apple Pencil and S Pen exclusivity to anchor pricing power against cross-platform alternatives. |
| Open-Source Distribution Expansion | Krita Foundation eliminates licensing friction to capture educational procurement and hobbyist segments in price-sensitive geographies. |
| Regulatory Compliance Certification | ISO color management and EU AI Act provenance tracking become table stakes for enterprise contracts with French publishers. |
Study Parameters
Operator-level perspectives from creative directors at design studios, platform engineering leads at cloud rendering providers, procurement officers at freelance marketplaces, and curriculum coordinators at Indian design institutes anchored the qualitative base, triangulated against SEC filings from Adobe and Autodesk, App Store revenue disclosures, EU AI Act regulatory texts, and METI subsidy program documentation to validate market sizing through bottom-up creator population estimates and top-down subscription revenue aggregation.
Scenario-bracketing across cloud compute cost volatility, generative AI adoption velocity, and hardware component supply disruption framed the analytical envelope over the projection horizon, with segmentation modeling across vector-raster-3D product types, professional-hobbyist-educator end users, and desktop-mobile-cloud deployment modes. CAGRs derived from installed base growth rates multiplied by average revenue per user trajectories, incorporating stylus hardware shipment forecasts and freelance platform expansion timelines as industry-specific inputs.
Stress conditions across AWS-GCP-Azure pricing cycles, Taiwan semiconductor export restrictions, and EU AI Act enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of generative feature adoption rates in enterprise contracts and cloud rendering margin compression indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
3PL Software Market
Software & Services
MES Software Market
Software & Services
Codeless Testing Market
Software & Services
Computational Medicine and Drug Discovery Software Market
Software & Services
Global AR Game Engine Software Market
Software & Services
Middle East HR Payroll Software Market
Software & Services
AR Remote Collaboration Software Market
Software & Services
Global Automation Software Market
Software & Services
Smartphone Applications Market
Software & Services
Global Log Management Software Market
Software & Services
Plant Design Software Market
Software & Services
SAP Digital Services Ecosystem Market
Software & Services
Shift Planning Software Market
Software & Services
Enterprise Software Market
Software & Services
Content Marketing Software Market
Software & Services
Global Data Governance Software Market