
 Lease Accounting Software Market | 2026-2036
Lease Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Lease Accounting Software Market Outlook
Healthcare and financial services is restructuring lease accounting procurement patterns as hospital networks and banking groups consolidate real estate and equipment portfolios under unified platforms. LeaseAccelerator leverages deep compliance automation to anchor enterprise relationships across regulated industries. FinQuery sustains competitive positioning through specialized workflow tools for mid-market lease administrators. Nakisa Lease Accounting dominates international deployment scenarios with multi-entity consolidation capabilities.
Lease accounting software comprises configurable platforms that automate recognition, measurement, and disclosure of lease obligations under standards such as IFRS 16 and ASC 842, typically integrating general ledger APIs, amortization engines, and right-of-use asset registers. Its primary commercial purpose centers on eliminating manual spreadsheet dependency while ensuring audit-ready financial statement accuracy. Cloud-based and SaaS solutions within the solution segment are capturing expanding margin pools as subscription economics replace perpetual license models. The enterprise end-user category leads absolute spending, though SMB uptake is accelerating as tiered pricing broadens platform accessibility.
The SEC enforces ASC 842 disclosure requirements for US registrants, while the IASB governs IFRS 16 applicability across jurisdictions including the European Union and Canada, collectively elevating software procurement from discretionary IT spend to audit-mandated infrastructure. The FASB's ongoing agenda reviews may introduce further lease classification refinements that reshape platform feature requirements. Stakeholders must monitor convergence between lease accounting modules and broader ERP ecosystems to anticipate integration-driven vendor selection criteria.
Market Dynamics
Compliance mandates from the SEC and IASB have transformed lease accounting software from discretionary IT spend into audit-mandated infrastructure, compressing procurement cycles and elevating automation requirements across Fortune 500 finance departments.
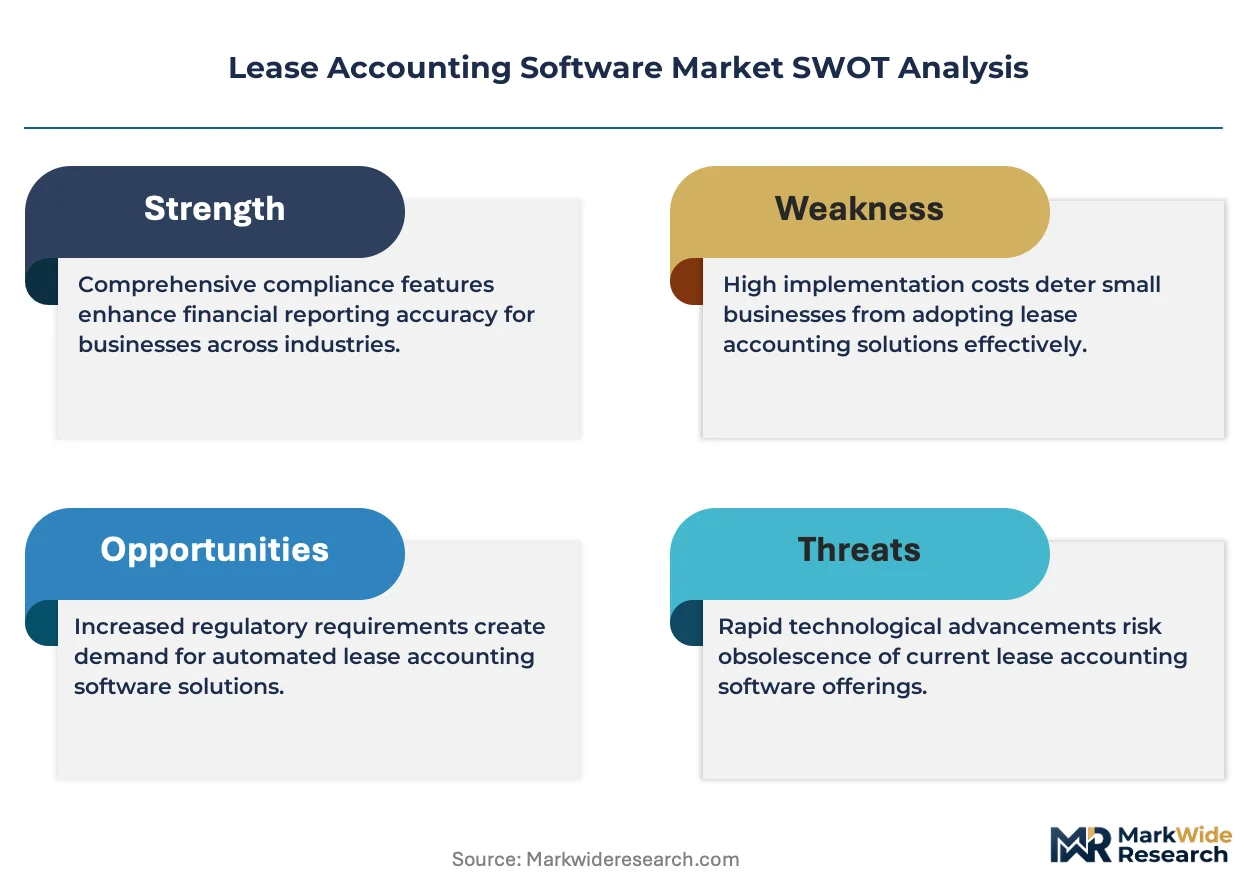
Growth Catalysts
- IFRS 16 and ASC 842:Mandatory disclosure standards in the European Union and United States force public registrants to abandon spreadsheet-based tracking, creating immediate replacement demand for certified platforms.
- Healthcare consolidation:Hospital networks merging real estate and equipment portfolios under unified ownership structures require centralized lease administration systems to maintain audit readiness.
- Cloud migration:SaaS delivery models are displacing on-premise perpetual licenses, lowering entry barriers for mid-market firms and expanding addressable demand.
Market Restraints
- Implementation complexity:Data migration from legacy ERP systems and fragmented lease repositories demands specialized consulting resources, extending deployment timelines and inflating total cost of ownership.
- Vendor concentration:Enterprise-grade functionality remains concentrated among a handful of specialized providers, limiting price competition and buyer negotiation leverage.
- Skills scarcity:Shortages of accountants trained in both lease standards and system configuration create bottlenecks that delay platform go-live dates.
Strategic Opportunities
- Mid-market penetration:Tiered subscription pricing enables vendors to capture previously unserved segments among sub-$500 million revenue firms with simplified compliance workflows.
- Embedded analytics:Convergence of lease data with treasury management and ESG reporting modules creates cross-sell potential within existing customer bases.
- API ecosystem expansion:Native integrations with Workday, SAP, and Oracle Cloud are becoming selection criteria, rewarding platforms with robust connector libraries.
Industry Challenges
- Interoperability friction:Custom integrations with heterogeneous legacy general ledger systems consume disproportionate engineering resources and generate implementation delays.
- Standard interpretation variance:Divergent auditor interpretations of lease classification criteria across jurisdictions force vendors to maintain multiple calculation engines, complicating product architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lease Accounting Software Market |
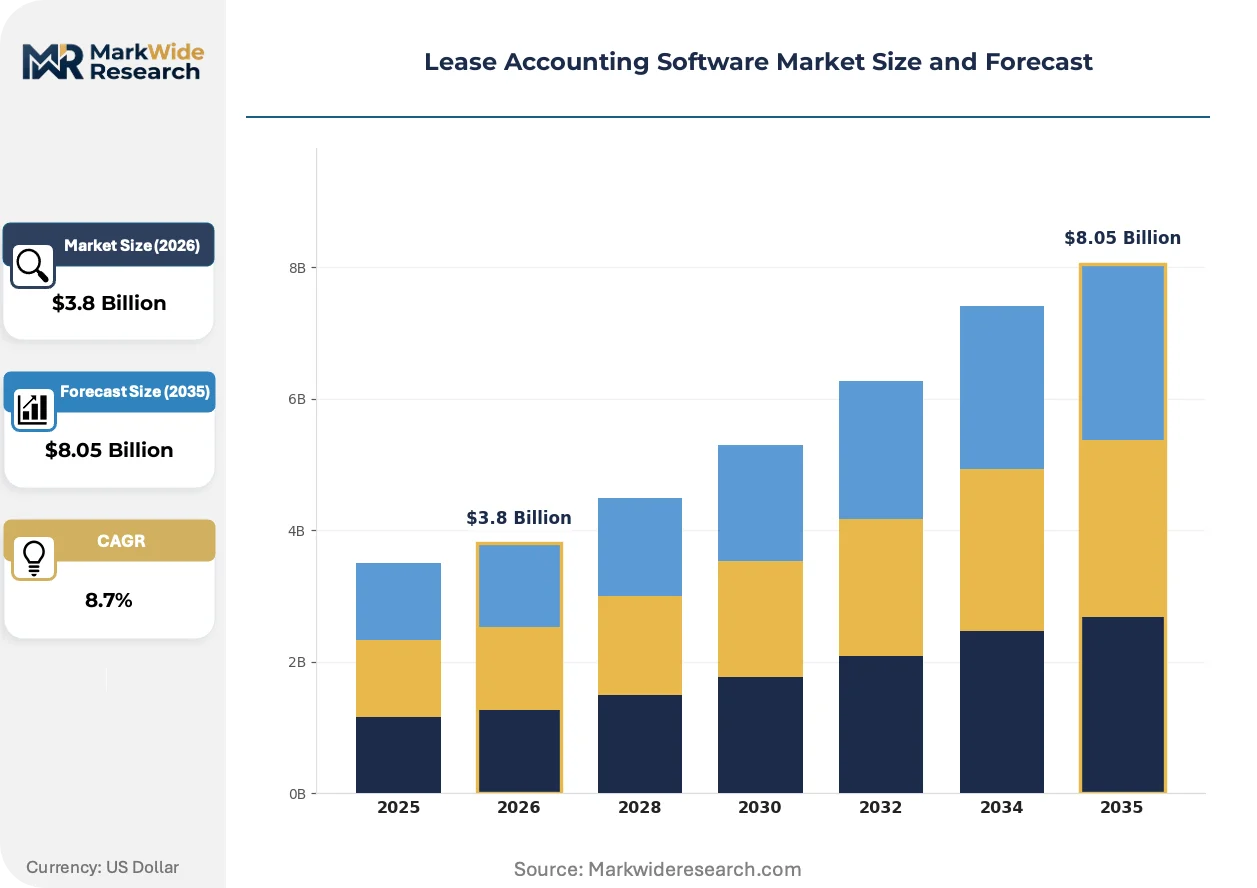
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Cloud-Based, On-Premise, Hybrid, SaaS End User: Enterprise, SMBs, Government, Non-Profit Deployment Model: Public Cloud, Private Cloud, Managed Services, Self-Hosted Feature: Compliance Tracking, Reporting, Integration, Workflow Automation |
| Companies Covered | LeaseAccelerator, Nakisa Lease Accounting, FinQuery, Trullion, MRI Software, Visual Lease, Crunchafi, Spacebase, LeaseQuery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lease Accounting Software Market Strategic Shifts
Artificial intelligence and machine learning capabilities are embedding into lease abstraction and data extraction workflows, compressing manual entry requirements while elevating accuracy benchmarks for audit documentation.
Natural language processing engines are integrating contract parsing functionality directly into ingestion pipelines. Large hospital systems and real estate investment trusts are deploying these tools to accelerate lease data migration from unstructured document repositories. This compression of manual abstraction labor is reallocating implementation budgets toward configuration and training phases.
The SEC's ongoing enforcement of ASC 842 disclosure requirements is tightening audit scrutiny over lease liability calculations. Public registrants in the United States are responding by procuring platforms with built-in audit trail documentation and automated variance reporting. Financial services firms with complex equipment leasing operations face the steepest compliance burden and are prioritizing solutions with embedded controls testing.
Subscription pricing models are displacing perpetual license structures across the buyer base. Chief financial officers at mid-market enterprises are favoring operating expense treatment and predictable renewal cycles over capital-intensive upfront commitments. This preference shift is most visible in the United States, where SaaS penetration among sub-$1 billion revenue firms has accelerated markedly since the standards took effect.
Lease Accounting Software Market Segmentation
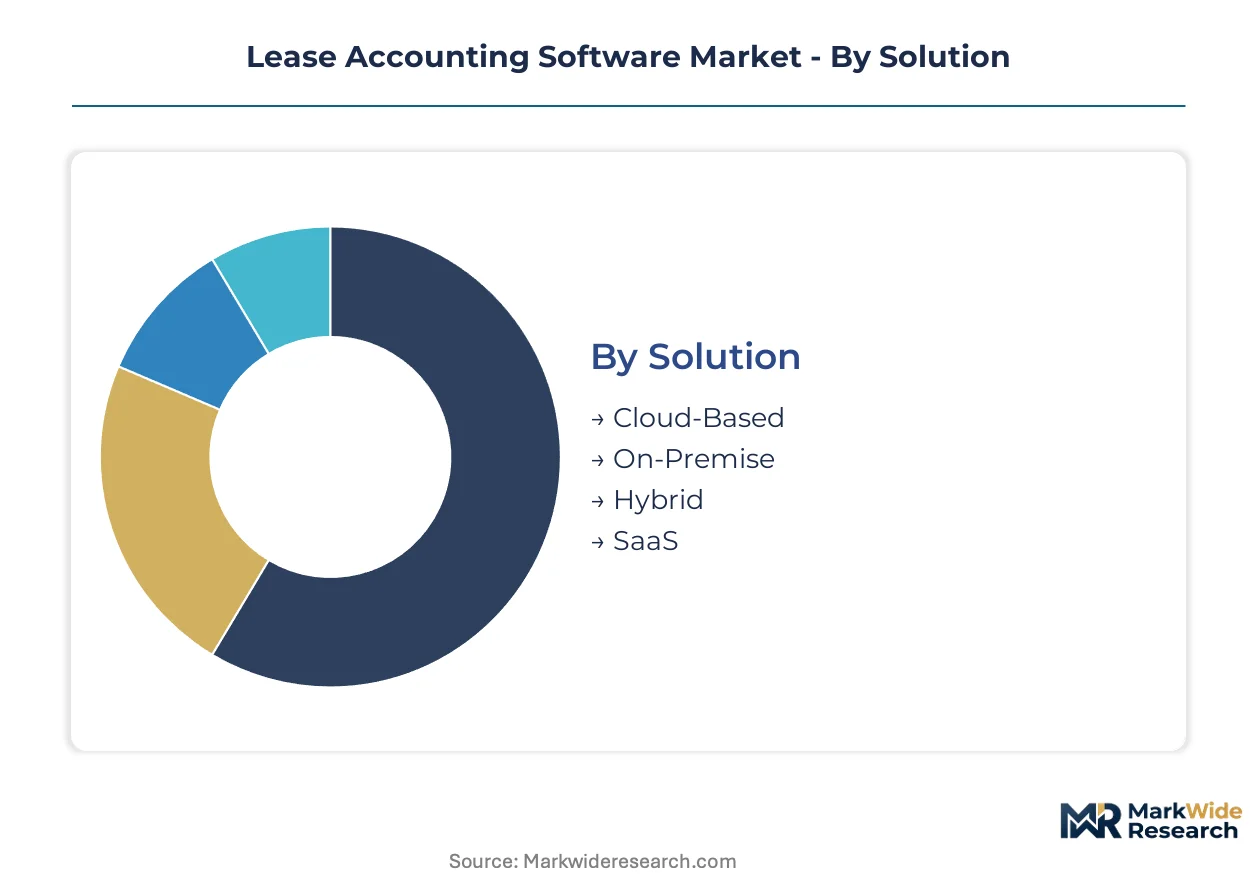
Segmentation reveals how procurement priorities diverge across buyer types and technical requirements in lease accounting. Cloud delivery models and compliance automation features command premium positioning as finance departments abandon legacy spreadsheet infrastructure.
Solution:
Upgrade cycles from on-premise perpetual licenses to subscription models are compressing replacement timelines across the buyer base.
- Cloud-Based:Multi-tenant architectures with automatic standard updates eliminate version fragmentation. United States hospital networks and financial services firms concentrate procurement here, driven by SEC audit scrutiny over ASC 842 disclosure accuracy.
- SaaS:Subscription economics transform capital expenditure into operating expense treatment. Mid-market enterprises in Canada and Germany favor this model for predictable renewal cycles and reduced IT overhead.
- On-Premise:Single-tenant installations persist among defense contractors and sovereign wealth funds with data residency mandates.
- Hybrid:Split configurations separate sensitive lease data on local servers while pushing analytics to cloud environments.
Cloud-Based sits at the top of the volume ranking, with SaaS climbing the fastest.
End User:
Cost tier differentiation separates comprehensive platforms from streamlined offerings across revenue thresholds.
- Enterprise:Fortune 500 lease portfolios demand multi-entity consolidation, complex equipment leasing workflows, and embedded controls testing. United States registrants face the steepest compliance burden under SEC enforcement.
- SMBs:Sub-$500 million revenue firms require simplified compliance workflows with tiered subscription pricing. Adoption accelerates as entry barriers fall.
- Government:Public sector procurement emphasizes audit trail documentation and appropriations fund tracking.
- Non-Profit:Grant-funded organizations prioritize donor restriction compliance and board reporting transparency.
Enterprise dominates absolute spending, with SMBs expanding most quickly.
Deployment Model:
Application criticality determines infrastructure control requirements across regulated industries.
- Public Cloud:Shared infrastructure delivers cost efficiency for non-sensitive lease portfolios. European Union firms navigate GDPR data localization alongside IFRS 16 compliance.
- Private Cloud:Dedicated environments satisfy banking regulators in Switzerland and Germany. Isolated tenant architectures support complex intercompany lease structures.
- Managed Services:Third-party administration handles system maintenance and standard updates. Resource-constrained finance departments in Australia and Brazil outsource operational burden.
- Self-Hosted:Complete infrastructure control appeals to nuclear utilities and national postal services with sovereignty requirements.
Public Cloud leads deployment volume, with Private Cloud gaining share fastest among regulated sectors.
Feature:
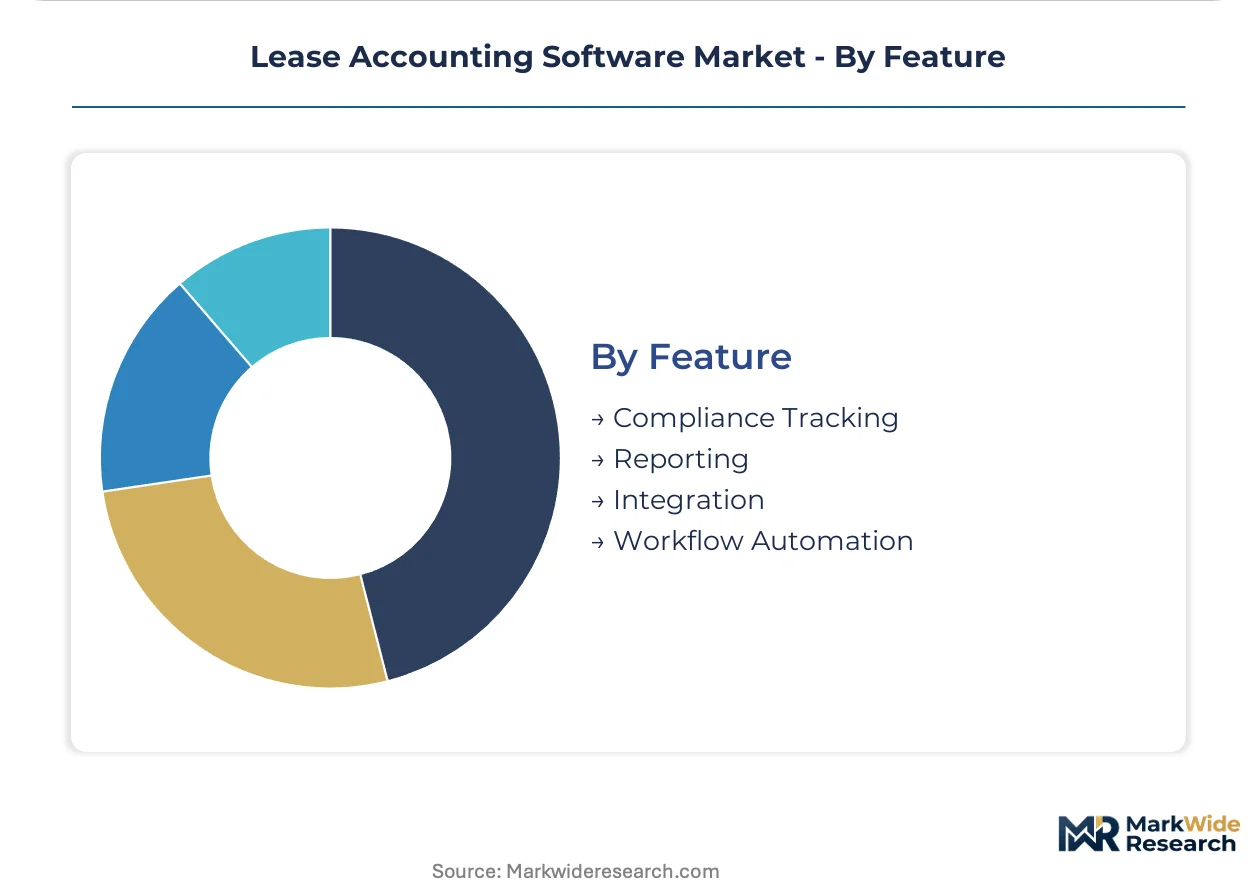
Margin concentration follows automation depth, with compliance modules commanding premium pricing over basic reporting.
- Compliance Tracking:Built-in calculation engines for IFRS 16 and ASC 842 lease classification eliminate auditor interpretation variance. Mandatory disclosure standards in the United States and European Union elevate this to core infrastructure.
- Workflow Automation:Natural language processing engines parse unstructured lease contracts, compressing manual abstraction labor. Large hospital systems deploy these tools to accelerate data migration.
- Reporting:Automated variance reporting and audit trail documentation satisfy tightening SEC scrutiny over lease liability calculations.
- Integration:Native APIs with SAP, Oracle Cloud, and Workday become selection criteria as finance departments converge lease data with broader ERP ecosystems.
Compliance Tracking sits at the top of the volume ranking, with Workflow Automation climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fortune 500 finance departments across the United States drive the dominant share of enterprise software procurement for lease accounting compliance. Regulatory mandates from the SEC and IASB have compressed implementation timelines across North America and Western Europe. Cloud migration patterns vary significantly by jurisdiction, with data residency requirements shaping deployment architecture decisions.
United States
SEC enforcement of ASC 842 disclosure requirements has transformed software procurement from discretionary IT spend into audit-mandated infrastructure. Hospital networks in Texas and financial services firms in New York face the steepest compliance burdens and prioritize platforms with embedded controls testing. Chicago-based real estate investment trusts deploy natural language processing tools to accelerate lease data migration from unstructured document repositories.
Germany
IFRS 16 applicability across the European Union elevates software procurement priority for DAX-listed industrial conglomerates with complex equipment leasing portfolios. The Federal Financial Supervisory Authority (BaFin) scrutinizes lease liability calculations at Frankfurt-headquartered banking groups. Munich-based automotive manufacturers consolidate multi-entity lease structures under unified platforms to satisfy auditor interpretation requirements.
United Kingdom
Consolidation of real estate portfolios among London-based financial services firms drives demand for multi-entity consolidation capabilities. The Financial Conduct Authority coordinates with international standard-setters on disclosure enforcement timelines. Manchester hospital networks merge equipment leases under centralized administration systems to maintain NHS audit readiness.
Canada
Mid-market enterprises in Toronto and Vancouver favor SaaS delivery models for predictable renewal cycles and reduced IT overhead. Health Canada aligns pharmaceutical lease disclosure requirements with international standards. Calgary energy firms with complex equipment leasing operations prioritize solutions with automated variance reporting for tightening audit scrutiny.
Japan
METI guidance on lease standard convergence prompts Tokyo-headquartered manufacturers to abandon spreadsheet-based tracking for certified platforms. Osaka-based trading houses with international real estate portfolios require multi-currency calculation engines. Nagoya automotive suppliers consolidate lease administration across ASEAN subsidiaries under unified cloud architectures.
Lease Accounting Software Market Competitive Environment
Compliance automation dominates the current landscape as vendors differentiate through embedded calculation engines and audit trail documentation. The vendor base concentrates among specialized providers with deep regulatory expertise rather than generalist ERP platforms. Three strategic archetypes have emerged: compliance-first specialists, mid-market workflow optimizers, and international multi-entity consolidators. M&A activity and API ecosystem expansion represent the dominant competitive vectors as platforms race to integrate with Workday, SAP, and Oracle Cloud.
Within the compliance-first tier, LeaseAccelerator and Nakisa Lease Accounting exemplify divergent geographic positioning strategies. LeaseAccelerator anchors enterprise relationships across United States regulated industries through deep automation of ASC 842 requirements. Nakisa Lease Accounting occupies a position serving international deployment scenarios with multi-entity consolidation capabilities for European and Asian headquarters operations. FinQuery represents the mid-market workflow optimizer archetype, sustaining competitive positioning through specialized tools for lease administrators at sub-$500 million revenue firms.
| Leading Market Players |
|---|
| LeaseAccelerator |
| Nakisa Lease Accounting |
| FinQuery |
| Trullion |
| MRI Software |
| Visual Lease |
| Crunchafi |
| Spacebase |
| LeaseQuery |
| Others |
Value Chain & Pricing Dynamics
Compliance-automation depth bifurcates vendor pricing power, with ASC 842-certified platforms commanding subscription premiums while spreadsheet-replacement tools compete on entry-tier SaaS economics. This tier divergence concentrates margin capture among United States-based specialists with embedded SEC audit trail capabilities, while mid-market challengers absorb pricing pressure through simplified workflow bundles that sacrifice multi-entity consolidation depth.
Pricing Analysis
Input-cost pass-through from specialized accountant labor and compliance-engineering talent anchors subscription pricing across the vendor base. Three-tier pricing structure across premium, standard, and economy levels separates enterprise multi-entity deployments from mid-market SaaS tiers and basic disclosure-reporting modules. Cost compression in the economy tier intensifies because offshore development centers in India and Poland replicate core calculation engines. Mid-market enterprises with sub-$500 million revenue demonstrate highest price sensitivity, while Fortune 500 finance departments prioritize audit-readiness over unit economics.
Supply Chain Analysis
Regional distribution centers for cloud infrastructure concentrate in the United States, Ireland, and Singapore, with latency-sensitive financial services workloads demanding edge presence in Frankfurt and Tokyo. Software development draws from specialized compliance-engineering talent pools in Boston, London, and Bangalore, while customer success operations source from Sydney and São Paulo. Single-source vulnerability concentrates in hyperscaler compute contracts with AWS, Azure, and Google Cloud. Distribution runs through direct enterprise sales teams for Fortune 500 accounts, supplemented by channel partners for mid-market penetration in Canada and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge between United States compliance premiums and European mid-market pricing gaps, with German automotive and British financial services buyers absorbing 15-20% cost differentials for equivalent ASC 842 functionality.
For Market Incumbents: Acquire natural-language-processing lease abstraction engines to neutralize implementation timeline advantages from AI-native entrants. Consolidate channel partnerships with Workday and SAP integration specialists before mid-market challengers capture API ecosystem slots. Defensive positioning against FinQuery's workflow specialization requires embedding similar administrator-centric tools without sacrificing enterprise audit depth. For New Entrants and Emerging Players: Sub-$100 million revenue professional services firms in Canada and Australia represent underserved buyer archetypes with unmet compliance automation needs. White-space concentration appears in hybrid deployment configurations serving defense contractors with data residency mandates. Go-to-market execution should anchor on managed services bundling that outsources lease administration entirely, bypassing internal IT procurement friction. For Investors and Strategic Acquirers: Consolidation pressure builds where vendor count exceeds sustainable differentiation in mid-market SaaS tiers. Long-term viability across the analysis window favors platforms with embedded ERP connector libraries and recurring revenue concentration above 85%. Acquisition target archetype: compliance-first specialists with ASC 842 certification depth and Fortune 500 logo concentration. Signal to watch: mid-market churn rates accelerating toward 20% annual thresholds as tiered pricing commoditizes basic functionality.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Workday and SAP connectors satisfy Fortune 500 procurement checklists. |
| Acquisition of Specialist Firm | Lease abstraction AI targets compress hospital system implementation timelines. |
| Geographic Expansion | Toronto and Vancouver offices capture Canadian mid-market SaaS substitution. |
| Product Launch | Embedded ESG reporting modules unlock cross-sell within existing customer bases. |
| Strategic Partnership | Big Four audit firm alliances accelerate ASC 842 certification credibility. |
Study Parameters
Direct dialogue with CFOs at Fortune 500 lease-intensive corporations, compliance officers at hospital networks, IT procurement leads at financial services firms, and implementation specialists at Big Four accounting firms grounded qualitative assessment. Secondary validation drew from SEC 10-K lease disclosure filings, IASB implementation guidance documents, Gartner software procurement surveys, and hyperscaler SaaS revenue segment disclosures. Bottom-up and top-down triangulation reconciled vendor-reported subscription metrics with buyer-reported implementation spend patterns.
Segmentation outputs across deployment model, organization size, vertical concentration, and regional regulatory cluster dimensions structured the analytical framework. CAGRs were derived from logistic adoption curves fitted to compliance mandate enforcement timelines, with cloud migration velocity and mid-market penetration rates serving as primary forecast inputs. The projection horizon spans the interval between ASC 842 full enforcement and anticipated FASB lease classification refinement cycles.
Underlying measurement precision varies by segment; enterprise cloud deployments carry tighter precision than hybrid on-premise configurations. Forecasts reflect documented assumptions regarding SEC enforcement consistency and IASB interpretation convergence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Production Optimization Software Market
Software & Services
Global Retail Management Systems Software Market
Software & Services
Global Charity Accounting Software Market
Software & Services
United Arab Emirates (UAE) Cloud Accounting Software Market
Software & Services
SAP Digital Services Ecosystem Market
Software & Services
Freight Management Software Market
Software & Services
Enterprise Performance Management (EPM) Software Market
Software & Services
Structured Data Management Software Market
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
Global Architecture Software Market
Software & Services
North America Telecom Expense Management Services Software Market
Software & Services
Global Online Form Builder Software Market
Software & Services
Codeless Testing Market
Software & Services
Specification Management Software Market
Software & Services
Automotive Dealer Management Systems (DMS) Market
Software & Services
Middle East and Africa Digital Signage Software Market