
 Embedded Operating Systems Market | 2026-2036
Embedded Operating Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Operating Systems Market Insights
ISO 26262 ASIL-D certification is unwinding legacy procurement patterns across the automotive embedded stack. Wind River Systems leverages its VxWorks pedigree to dominate aerospace and defense contracts requiring DO-178C traceability. Green Hills Software anchors the safety-critical segment through INTEGRITY-178B deployments in avionics and medical infusion pumps. QNX Software Systems specializes in automotive digital cockpit integration, sustaining BlackBerry's relevance despite handset retreat.
An embedded operating system is a compact, deterministic software kernel engineered for resource-constrained microcontrollers and processors, typically requiring sub-millisecond interrupt latency and memory footprints below 256 KB; its primary purpose is to guarantee predictable task scheduling, hardware abstraction, and fault isolation for mission-critical devices. Real-Time OS deployments lead in industrial automation due to deterministic control requirements, while Safety-Critical OS platforms command premium pricing in medical devices and autonomous vehicles where failure modes must demonstrate quantifiable risk mitigation. Edge Computing deployments represent the fastest-growing deployment category as factory operators and OEMs push inference workloads closer to sensors to reduce cloud dependency and latency.
FDA 21 CFR Part 820 quality system regulations and IEC 62304 medical device software standards shape validation requirements for embedded OS vendors serving healthcare OEMs, while the EU Cyber Resilience Act imposes mandatory security update obligations on connected device manufacturers. NHTSA FMVSS guidelines and ISO 26262 together force automotive suppliers to maintain auditable software supply chains from kernel to application layer. Stakeholders must monitor how functional safety certification timelines interact with accelerated product cycles in automotive and medical verticals.
Market Dynamics
Functional safety certification mandates are compressing procurement cycles across automotive and medical verticals, forcing OEMs to abandon legacy kernels for pre-certified platforms that accelerate time-to-market while satisfying ISO 26262 and IEC 62304 traceability requirements.
Growth Catalysts
- EU Cyber Resilience Act:Mandatory security update obligations for connected device manufacturers are accelerating replacement of unmaintained legacy kernels with vendor-supported commercial platforms across industrial IoT deployments.
- Automotive OEM consolidation:Tier-1 suppliers in Germany's Stuttgart-Munich corridor are standardizing on safety-certified platforms to reduce supplier qualification overhead for autonomous drive systems.
- Edge inference workloads:Factory operators are deploying RTOS kernels with hardware-accelerated neural network libraries to execute machine vision models locally, reducing cloud egress costs and control loop latency.
Market Restraints
- Certification cost concentration:ASIL-D and SIL-3 validation expenses exceed seven figures per platform variant, freezing out mid-tier vendors and consolidating supply around incumbents with amortized safety libraries.
- Semiconductor foundry concentration:Advanced automotive-grade MCU tape-outs depend on Taiwan-based fabrication capacity, exposing kernel vendors to allocation volatility during node transitions.
- Legacy codebase entrenchment:Decades of proprietary driver investments in homegrown schedulers create switching friction that delays commercial RTOS adoption in industrial equipment.
Strategic Opportunities
- RISC-V architecture migration:Open instruction set architectures are enabling custom silicon with integrated safety monitors, creating openings for kernel vendors to offer pre-integrated hardware-software certification packages.
- Medical device software-as-a-service:FDA 21 CFR Part 820 compliant kernel subscriptions with continuous validation documentation are penetrating infusion pump and imaging equipment markets previously served by perpetual licenses.
- India PLI scheme for automotive electronics:Production-linked incentives for advanced driver assistance systems are attracting kernel vendors to establish local engineering centers serving domestic OEMs and export markets.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 and IEC 61508 certified developers command premium compensation that strains vendor margins and extends hiring timelines for customer support teams.
- Multi-core determinism verification:Cache coherency protocols and memory bandwidth contention in heterogeneous SoCs complicate worst-case execution time analysis required for safety certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Operating Systems Market |
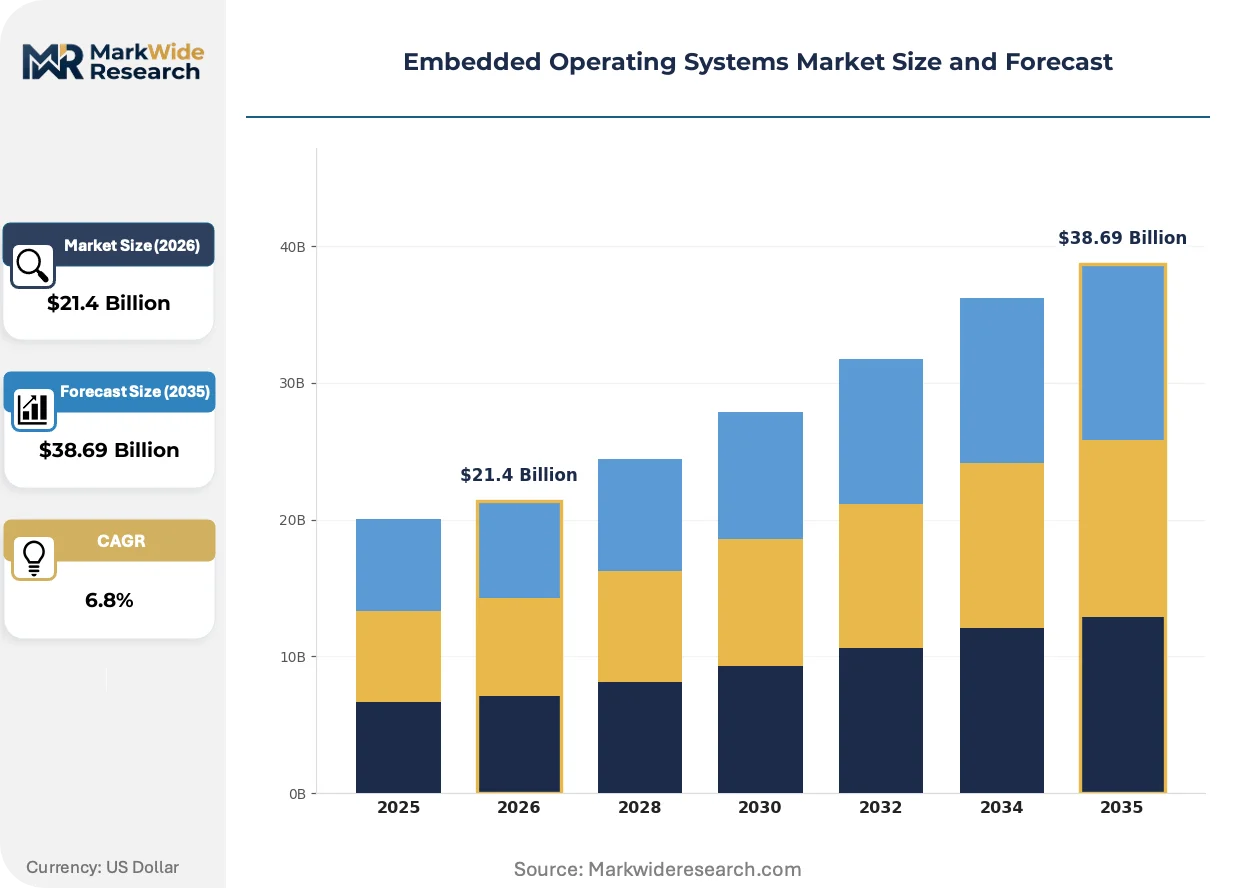
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $38.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Real-Time OS, Safety-Critical OS, General-Purpose OS, Network OS End User: Automotive, Consumer Electronics, Industrial Automation, Medical Devices Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Edge Computing Technology: Linux, RTOS, VxWorks, FreeRTOS |
| Companies Covered | Wind River Systems, Segger, Green Hills Software, FreeRTOS (Amazon), Express Logic, Sysgo, Mentor Graphics, Zephyr Project, QNX Software Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Operating Systems Market Trends and Innovations
Deterministic virtualization and containerized deployment models are redefining how safety-critical workloads coexist with general-purpose applications on shared automotive compute domains.
Hypervisor-based separation kernels are displacing bare-metal RTOS deployments in zonal automotive architectures, enabling consolidation of instrument cluster, infotainment, and ADAS functions onto single SoCs while maintaining freedom-from-interference guarantees. German OEMs are mandating these configurations for next-generation E/E architectures, compressing addressable market for standalone RTOS licenses in digital cockpit applications.
The EU Cyber Resilience Act imposes mandatory vulnerability disclosure and patch timelines on connected device manufacturers, forcing embedded OS vendors to restructure maintenance contracts around continuous security validation. Medical device and industrial automation segments are absorbing compliance costs through subscription pricing models that bundle kernel updates with regulatory documentation refresh cycles.
Automotive procurement teams are consolidating vendor relationships around platforms offering pre-integrated safety certification evidence, displacing multi-vendor kernel strategies that required duplicate validation efforts. Tier-1 suppliers in Germany and Japan are reducing qualified vendor lists from five-plus to two preferred partners, concentrating contract value with vendors possessing comprehensive ASIL-D toolchains and regional engineering support.
Embedded Operating Systems Market Segmentation
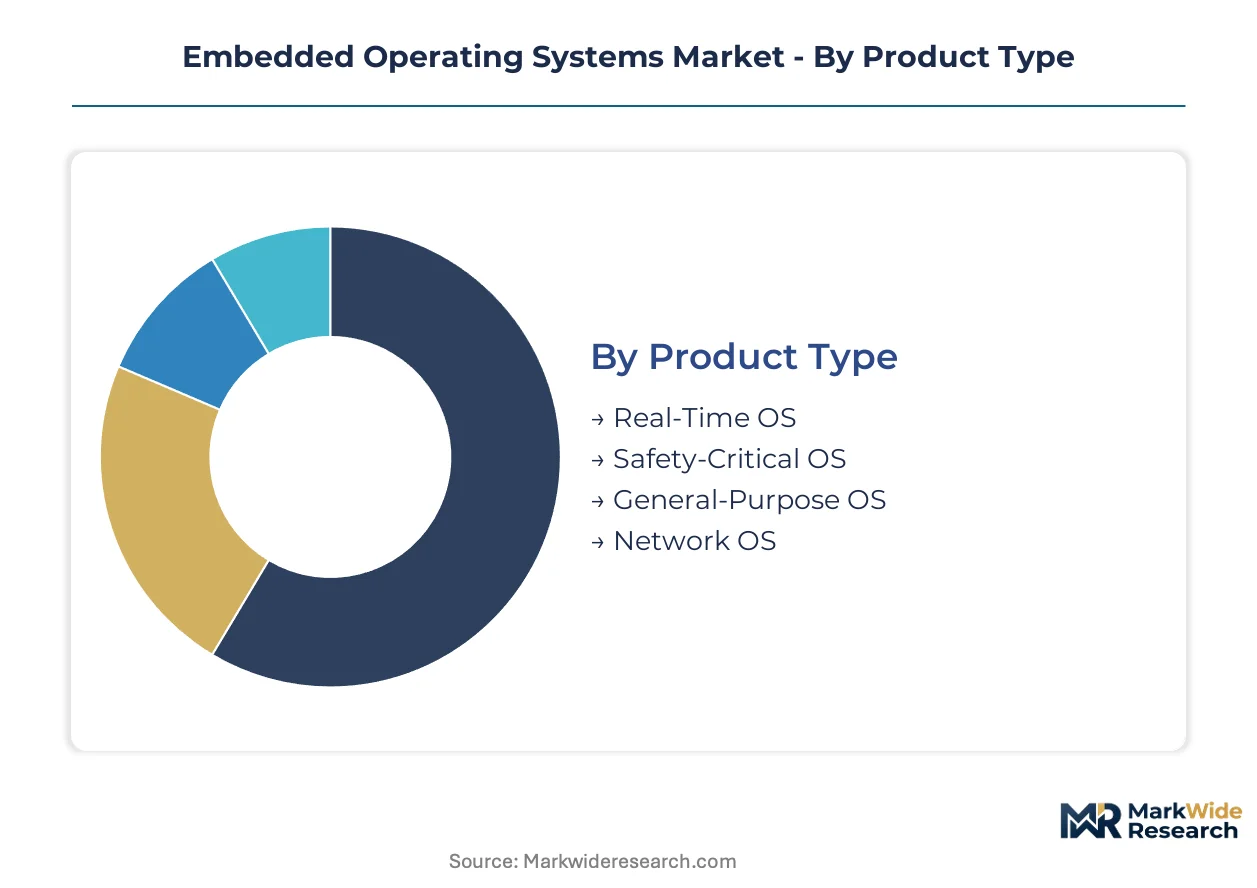
Embedded operating system procurement varies sharply by deployment context, with safety certification requirements and latency constraints dictating kernel selection across automotive, medical, and industrial verticals. Channel strategies diverge between direct OEM engagements for safety-critical platforms and distributor-led volume sales for general-purpose deployments.
Product Type:
Channel mix splits between long-cycle direct sales for certified platforms and high-velocity distributor relationships for commodity kernels serving non-critical applications.
- Real-Time OS:Deterministic schedulers guarantee sub-millisecond interrupt response for motion control and robotics. Factory automation OEMs in Germany's Stuttgart corridor are standardizing on pre-certified RTOS bundles to compress qualification timelines for IEC 61508 compliance.
- Safety-Critical OS:Formal verification and ASIL-D/SIL-3 evidence packages dominate automotive and avionics procurement. These platforms command premium pricing through direct vendor relationships, with NHTSA FMVSS traceability requirements forcing Tier-1 suppliers toward consolidated single-source strategies.
- General-Purpose OS:Linux derivatives serve non-deterministic workloads in consumer electronics and enterprise edge devices through distributor and cloud marketplace channels.
- Network OS:Lightweight stacks optimized for protocol handling in telecommunications infrastructure and IoT gateways, deployed through systems integrator partnerships.
By volume, General-Purpose OS leads. By growth pace, Safety-Critical OS is ahead.
End User:
Cost tier stratification separates safety-certified premium platforms from volume-optimized commodity kernels across vertical applications.
- Automotive:Zonal E/E architectures and autonomous drive systems require ASIL-B through ASIL-D certified kernels. German OEM consolidation around Stuttgart and Munich is compressing supplier lists to two preferred partners per platform generation.
- Medical Devices:FDA 21 CFR Part 820 and IEC 62304 validation documentation drive subscription pricing for infusion pumps and diagnostic imaging equipment. Kernel vendors bundle continuous compliance refresh cycles with maintenance contracts.
- Industrial Automation:PLC and motion control systems deploy RTOS kernels through systems integrator channels, with legacy codebase entrenchment delaying commercial platform adoption.
- Consumer Electronics:Cost-sensitive wearable and smart home devices utilize stripped-down Linux or FreeRTOS distributions through high-volume semiconductor distributor relationships.
Automotive generates the highest revenue per socket. Medical Devices show the steepest expansion trajectory as continuous validation subscriptions displace perpetual licenses.
Deployment:
Application requirements dictate whether workloads execute on bare metal, virtualized substrates, or distributed edge-cloud configurations.
- Edge Computing:Hardware-accelerated neural network libraries enable local inference for machine vision and predictive maintenance. Factory operators in Japan and Germany are deploying RTOS kernels with tensor processing unit integration to eliminate cloud dependency.
- On-Premises:Bare-metal and hypervisor-based separation kernels serve safety-critical functions requiring deterministic isolation. German OEMs mandate these configurations for instrument cluster and ADAS consolidation onto single SoCs.
- Hybrid Solutions:Partitioned architectures combine real-time control domains with general-purpose guest operating systems for industrial IoT gateways.
- Cloud-Based:Containerized embedded development environments and firmware update orchestration platforms serve distributed device fleets through SaaS delivery models.
On-Premises retains the largest installed base. Edge Computing is climbing the fastest as inference workloads migrate toward sensors.
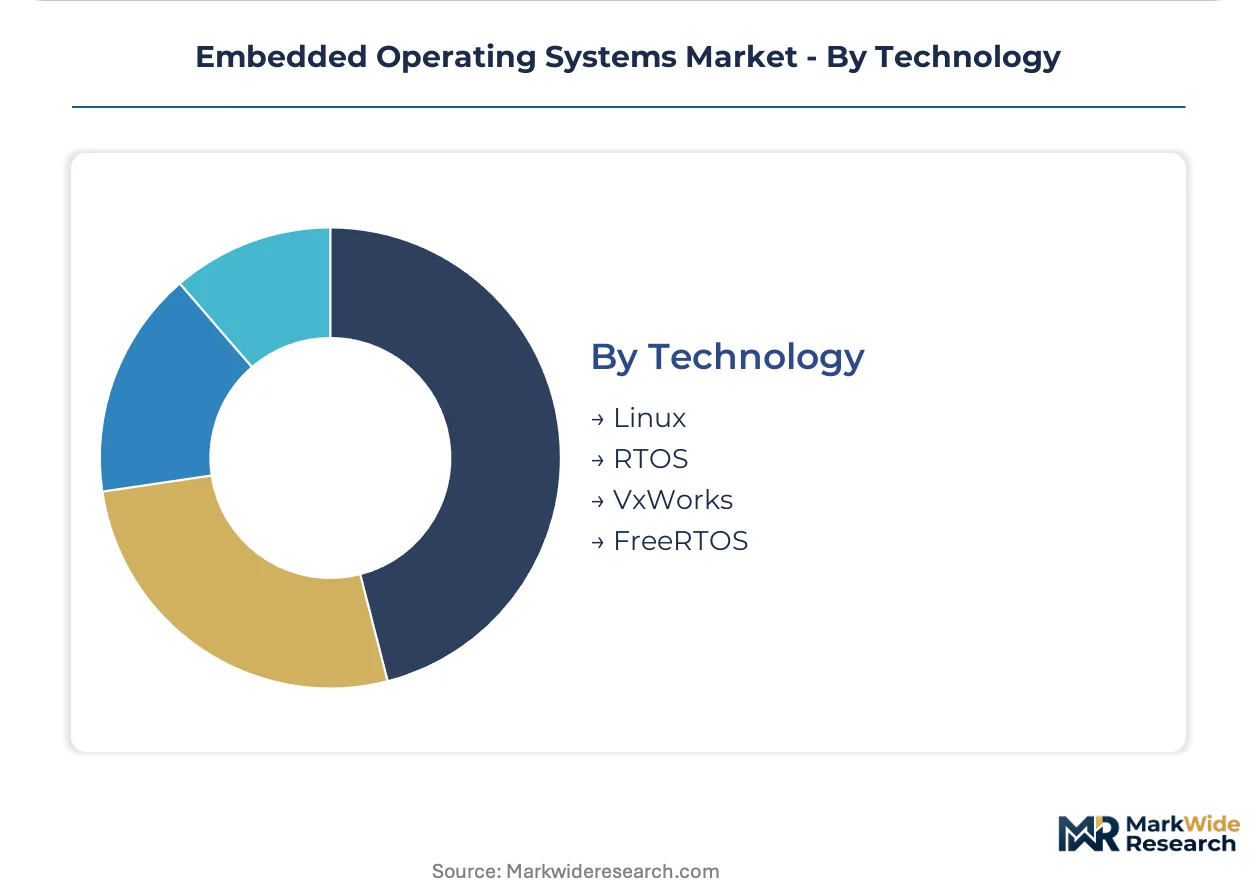
Technology:
Supply concentration around proprietary verification toolchains versus open-source ecosystem breadth shapes procurement risk profiles.
- RTOS:Vendor-specific schedulers with deterministic context switching and worst-case execution time analysis tools. Industrial automation OEMs favor these for IEC 61508 certifiability despite higher per-unit licensing costs.
- Linux:Yocto and commercial distributions dominate non-safety applications with broad driver ecosystem and zero licensing friction. Consumer electronics and enterprise edge deployments flow through semiconductor vendor BSP partnerships.
- VxWorks:DO-178C and ARINC 653 pedigree anchors aerospace and defense procurement through direct vendor engineering relationships.
- FreeRTOS:MIT-licensed kernel with AWS IoT integration serves cost-constrained IoT endpoints through semiconductor vendor pre-integration and cloud marketplace distribution.
Linux holds the broadest deployment footprint. RTOS is gaining share fastest as functional safety mandates harden across automotive and medical verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity for safety-certified kernels, while procurement teams in India and China remain acutely sensitive to per-unit licensing costs despite accelerating regulatory convergence.
Germany
Automotive OEMs in the Stuttgart-Munich corridor are consolidating supplier lists to two preferred partners per platform generation. The KBA enforces strict type-approval protocols for autonomous drive systems that mandate ASIL-D traceability. Tier-1 suppliers around Ingolstadt and Wolfsburg are standardizing on pre-certified platforms to compress qualification timelines.
United States
Aerospace and defense contractors sustain premium demand for DO-178C certifiable kernels through direct vendor engineering relationships. The FAA mandates rigorous software lifecycle documentation for avionics systems that eliminates commodity alternatives. Engineering clusters in Greater Seattle and Southern California anchor procurement for military unmanned platforms and commercial space applications.
China
Domestic EV manufacturers are accelerating adoption of functional safety platforms as MIIT tightens GB standards for intelligent connected vehicles. Foundry capacity constraints around Shanghai and Shenzhen are forcing kernel vendors to pre-integrate with local semiconductor tape-outs. BYD and NIO procurement teams are qualifying indigenous RTOS alternatives to reduce foreign dependency.
Japan
Factory automation OEMs in the Nagoya-Toyota corridor deploy RTOS kernels with deterministic scheduling for robotics and PLC systems. METI subsidies for Industry 4.0 adoption are compressing payback periods for certified platform investments. Denso and Renesas engineering centers in Kyoto and Osaka are driving integration requirements for heterogeneous SoC architectures.
India
Domestic automotive electronics manufacturing is expanding under the PLI scheme for advanced driver assistance systems. The CEA is harmonizing electromagnetic compatibility standards that intersect with kernel certification requirements. Engineering centers in Bengaluru and Pune are attracting kernel vendors to serve Maruti Suzuki and Mahindra procurement teams.
Embedded Operating Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with safety-certified incumbents commanding premium pricing while open-source distributors capture volume deployments. The market structure concentrates around three tiers: aerospace-defense specialists with decades-long certification pedigrees, automotive-focused vendors with ASIL-D toolchains, and semiconductor-integrated distributors of lightweight kernels. Dominant competitive moves include strategic partnerships with foundries for pre-integrated hardware-software certification packages and geographic expansion through local engineering centers in high-growth automotive markets.
Within the safety-critical tier, Wind River Systems and Green Hills Software exemplify the aerospace-defense archetype through direct vendor relationships with prime contractors. QNX Software Systems occupies a distinct position serving automotive digital cockpit consolidation requirements. Among open-source-integrated distributors, FreeRTOS represents the volume-driven model through semiconductor vendor pre-integration and cloud marketplace channels.
| Leading Market Players |
|---|
| Wind River Systems |
| Segger |
| Green Hills Software |
| FreeRTOS (Amazon) |
| Express Logic |
| Sysgo |
| Mentor Graphics |
| Zephyr Project |
| QNX Software Systems |
| Others |
Pricing and Supply Chain Analysis
ISO 26262 certification gates both supplier qualification and price differentiation simultaneously, forcing automotive OEMs to pay premiums for pre-certified platforms while freezing out uncertified vendors from procurement shortlists entirely. This regulatory filter concentrates pricing power among incumbents with amortized safety libraries and distorts competitive dynamics across the embedded stack.
Pricing Analysis
After-sales revenue from continuous validation subscriptions and maintenance contracts drives lifetime value for kernel vendors serving medical and automotive verticals. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified platforms with full traceability documentation from IEC 61508-compliant industrial variants and stripped-down open-source distributions. Cost compression in the general-purpose tier is intensifying because semiconductor vendors bundle lightweight kernels at zero marginal cost with MCU reference designs. Automotive OEMs in Germany demonstrate the lowest price sensitivity, while consumer electronics manufacturers in China remain acutely responsive to per-unit licensing fees.
Supply Chain Analysis
Inventory lead times for automotive-grade MCUs stretch to six months during node transitions, exposing kernel vendors to qualification delays that cascade through Tier-1 supplier schedules. Manufacturing concentrates in Taiwan, South Korea, and Germany, with foundry capacity for advanced automotive silicon anchored in TSMC's Hsinchu facilities and Samsung's Pyeongtaek complex. Kernel development draws from proprietary verification toolchains, certified compiler ecosystems, and safety monitor IP licensed from specialized vendors. Single-source vulnerability around Taiwan-based fabrication creates systemic exposure during geopolitical disruptions. Distribution runs through direct vendor engineering relationships for safety-critical platforms and semiconductor distributor channels for volume deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards vendors possessing ISO 26262 certified engineering teams and pre-validated hardware-software integration capabilities, assets that require multi-year investment horizons to replicate. Functional safety engineer scarcity creates durable competitive moats for incumbents while constraining expansion capacity across the vendor base.
For Market Incumbents: Consolidate vendor relationships with German and Japanese automotive OEMs by embedding engineering teams within customer platform development centers, while acquiring specialized safety monitor IP vendors to close gaps in heterogeneous SoC support. Open-source RTOS distributions with cloud marketplace distribution threaten margin compression in the non-safety tier. Vertical integration into compiler toolchain development reduces certification timeline risk. For New Entrants and Emerging Players: Lead with RISC-V architecture migration opportunities in India and China, where domestic OEMs seek alternatives to foreign-proprietary kernels for intelligent connected vehicle programs. Medical device software-as-a-service subscriptions for infusion pump manufacturers represent the most penetrable white-space target, given incumbent focus on automotive. Partner with local semiconductor vendors for pre-integrated hardware-software certification packages to bypass direct sales capability gaps. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across safety-critical kernel development as ASIL-D validation expenses exceed seven figures per platform variant and certification timelines extend. Target acquisition profiles center on mid-tier RTOS vendors possessing regional automotive relationships but lacking comprehensive safety libraries, whose engineering talent and customer contracts become accretive to incumbent platforms. Monitor MIIT enforcement of GB standards for intelligent connected vehicles as the signal indicating acceleration in Chinese domestic kernel qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Integrated Hardware-Software Certification Packages | RISC-V migration in India and China creates openings for bundled safety evidence offerings. |
| Continuous Validation Subscription Models | FDA 21 CFR Part 820 compliance bundles penetrate medical device markets previously served by perpetual licenses. |
| Regional Engineering Center Expansion | India PLI scheme for automotive electronics attracts kernel vendors to serve Maruti Suzuki and Mahindra procurement. |
| Separation Kernel Hypervisor Development | German OEM mandates for zonal E/E architectures compress standalone RTOS addressable market. |
| Safety-Critical Compiler Toolchain Acquisition | Worst-case execution time analysis capabilities reduce certification timeline risk for multi-core SoC deployments. |
Research Methodology
The analysis maps real-time operating systems, safety-critical platforms, general-purpose distributions, and network-optimized stacks, each validated through interviews with automotive platform engineers, medical device software architects, industrial automation procurement leads, and semiconductor vendor ecosystem managers. Primary fieldwork combined with secondary validation against SEC filings from embedded software vendors, IHS Markit vehicle production databases, FDA 510(k) submission records, and EU Cyber Resilience Act implementation guidance. Bottom-up socket deployment estimates triangulated against top-down vertical market sizing across automotive, medical, and industrial segments.
Consistency checks validated volume and value outputs against external benchmarks including hyperscaler IoT platform disclosures, semiconductor vendor BSP partnership announcements, and automotive Tier-1 supplier procurement database patterns. Segmentation modeling spanned product type, end-user vertical, deployment architecture, and technology pedigree across the projection horizon. CAGRs derived from regression analysis of historical certification timeline compression, foundry capacity expansion schedules, and regulatory mandate implementation trajectories. Forecast inputs incorporated RISC-V core licensing trends, edge inference workload migration patterns, and medical device SaaS subscription penetration curves.
Forecasts assume regulatory continuity in EU Cyber Resilience Act enforcement, FDA 21 CFR Part 820 quality system requirements, and MIIT GB standards for intelligent connected vehicles; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Photo Editor App Market
Software & Services
Embedded Software and Tools Market
Software & Services
Category Management Software Market
Software & Services
Global Cloud-Based Call Center Software Market
Software & Services
Global MSP Software Market
Software & Services
Salesforce Services Market
Software & Services
Global Apparel Management Software Market
Software & Services
Cloud-Based Payroll Software Market
Software & Services
Building Information Modeling (BIM) Extraction Software Market
Software & Services
Automation Test Software Market
Software & Services
Employee Advocacy Software Market
Software & Services
Global Intellectual Property Management Software Market
Software & Services
Online Project Management Software Market
Software & Services
Gym Motion Tracking Software Market
Software & Services
Library Management Software Market
Software & Services
Middleware Market