
 Zea Mays Starch Market | 2026-2036
Zea Mays Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Zea Mays Starch Market Analytics
A wide capital-intensity divergence between wet-milling specialists and dry-mill commodity producers is rotating competitive advantage toward integrated processors with captive corn supply. Cargill, Incorporated leverages its grain origination network across the North American Corn Belt to secure feedstock cost advantages. Ingredion Incorporated specializes in higher-margin modified starch derivatives for pharmaceutical and industrial binders. Tate & Lyle PLC anchors its position through refinery flexibility that switches between sweetener and starch output based on margin signals.
Zea mays starch denotes the carbohydrate polymer extracted from corn endosperm through wet milling or dry milling, typically containing 25-28% amylose and 72-75% amylopectin by weight, serving as a thickener, binder, and gelling agent across food manufacturing and industrial applications. Modified starch commands premium pricing due to cross-linked and stabilized variants that withstand extreme processing temperatures in convenience foods. Native starch retains volume leadership in paper and corrugated applications where cost minimization dominates procurement decisions. Pharmaceutical-grade pregelatinized starch is deepening its share in tablet disintegration and excipient formulations as drug makers pursue direct-compression efficiency.
The FDA governs starch purity and GRAS status for food and pharmaceutical applications, while the EPA regulates wastewater discharge from wet-milling facilities under Clean Water Act permits. The EU Green Deal and REACH compliance requirements are reshaping import specifications for corn starch entering European food processors and cosmetic manufacturers. Stakeholders must monitor how evolving biofuel blending mandates in Brazil and Indonesia redirect corn feedstock between starch extraction and ethanol fermentation channels.
Market Dynamics
Clean-label formulation mandates from Southeast Asian food processors are redirecting procurement toward native and minimally modified starch grades, compressing margins for conventional wet-milling operations while rewarding processors with integrated organic corn supply chains.
Growth Catalysts
- EU Green Deal traceability:Mandatory agricultural input documentation for European food and cosmetic manufacturers is accelerating demand for certified sustainable corn starch with verified chain-of-custody records.
- Pharmaceutical direct-compression:Tablet manufacturers are expanding pregelatinized starch purchases to eliminate granulation steps and reduce manufacturing cycle times.
- Indonesia processed food corridor:Concentrated investment in instant noodle and snack production around Jakarta and Surabaya is pulling modified starch volumes for texture stabilization.
Market Restraints
- Feedstock competition from ethanol:Brazil's biofuel blending mandates and Indonesia's B35 biodiesel program are diverting corn supply toward fermentation channels, tightening starch extraction feedstock availability.
- Wet-milling wastewater intensity:EPA Clean Water Act permit requirements for biological oxygen demand and suspended solids discharge impose fixed compliance costs that disadvantage smaller facilities.
- Cassava starch substitution:Paper and corrugated board manufacturers in Thailand and Vietnam are switching to tapioca-derived alternatives where price spreads exceed threshold levels.
Strategic Opportunities
- Clean-label native starch:Non-GMO and organic certification programs are opening premium positioning in European baby food and specialty bakery segments.
- Biodegradable packaging films:Thermoplastic starch formulations are penetrating flexible packaging applications as REACH-compliant alternatives to petroleum-based films.
- Pharmaceutical excipient consolidation:Multinational drug makers are reducing supplier bases, creating volume consolidation opportunities for processors with USP-NF and EP compliance.
Industry Challenges
- Wet-milling process engineering talent:Specialized expertise in steeping efficiency and gluten-starch separation is aging out without sufficient replacement pipeline in North American Corn Belt operations.
- Modified starch patent thickets:Cross-linking chemistry IP held by established players creates licensing friction for new entrants pursuing acetylated and hydroxypropyl variants.
- Legacy ERP integration:Traceability systems required for EU Green Deal compliance must interface with decades-old mill control architectures, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zea Mays Starch Market |
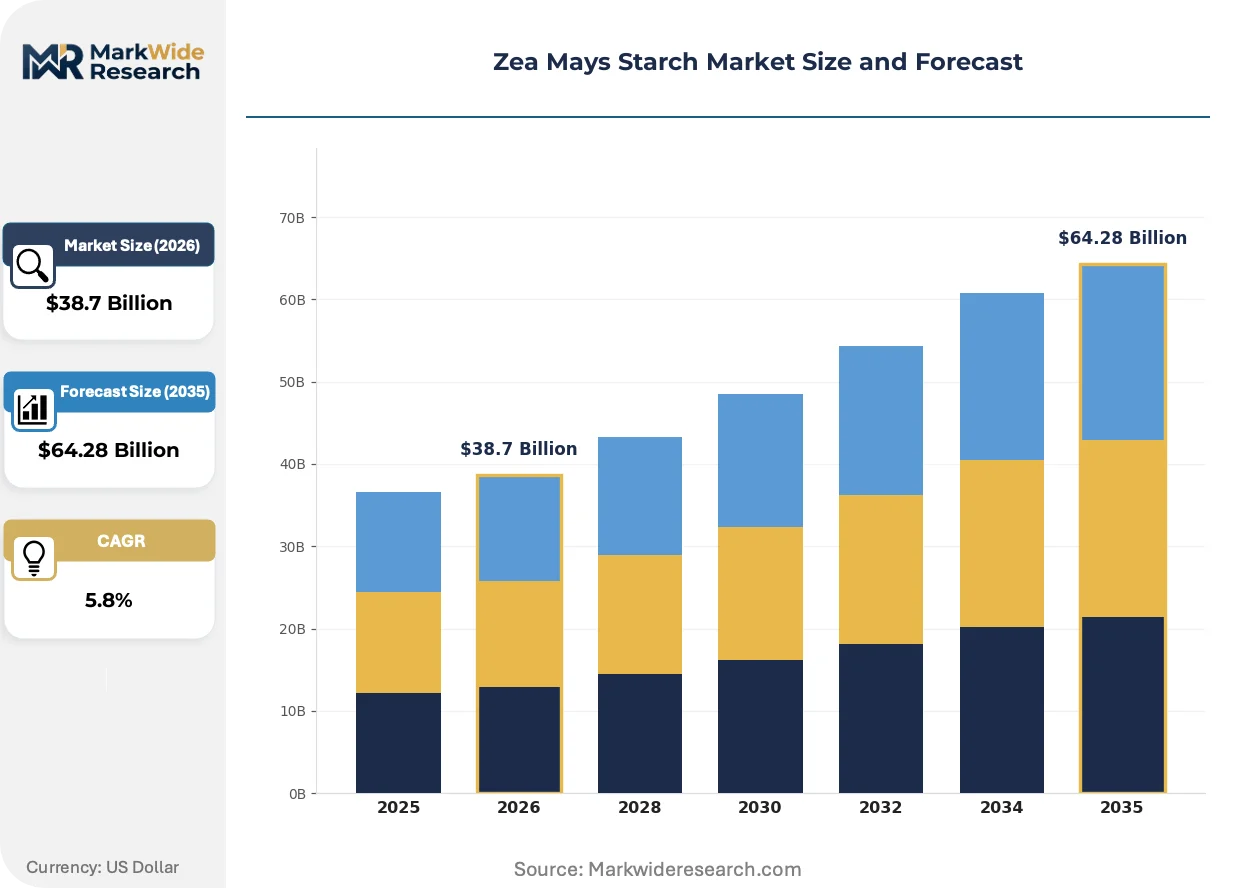
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starch, Modified Starch, Liquid Starch, Pregelatinized Starch Application: Food & Beverage, Pharmaceuticals, Textiles, Paper & Corrugated Form: Powder, Granule, Gel, Paste End User: Food Processors, Cosmetic Manufacturers, Adhesive Producers, Biofuel Companies |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Ingredion Incorporated, Tate & Lyle PLC, Roquette Frères, AGRANA Beteiligungs-AG, Tereos, Royal Avebe U.A., Emsland Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zea Mays Starch Market Evolving Landscape
Enzymatic processing breakthroughs and regulatory disclosure requirements are simultaneously transforming production economics and procurement criteria across food, pharmaceutical, and industrial starch applications.
Enzyme-assisted wet milling is fragmenting the traditional steeping process that has dominated corn starch extraction for decades. Pharmaceutical manufacturers and premium food brands are adopting enzyme-treated starches for cleaner label declarations and reduced processing chemical residues. This technology is fragmenting the supplier base by enabling smaller regional mills to achieve extraction efficiencies previously requiring massive capital-intensive facilities.
REACH compliance documentation and CSRD sustainability reporting obligations are tightening import specifications for corn starch entering European cosmetic and food manufacturing supply chains. Manufacturers must now provide full substance characterization and life-cycle assessment data to maintain market access. Pharmaceutical-grade and food-grade segments are responding by consolidating supplier qualification programs and demanding third-party verified chain-of-custody certification.
Direct-procurement relationships between Indonesian and Vietnamese food processors and starch refiners are compressing traditional distributor margins and accelerating price discovery. Large instant noodle and confectionery manufacturers are establishing volume contracts with wet-milling operations, bypassing regional trading houses. This disintermediation is most visible in Jakarta's processed food corridor where lead times have compressed from weeks to days.
Zea Mays Starch Market Segmentation
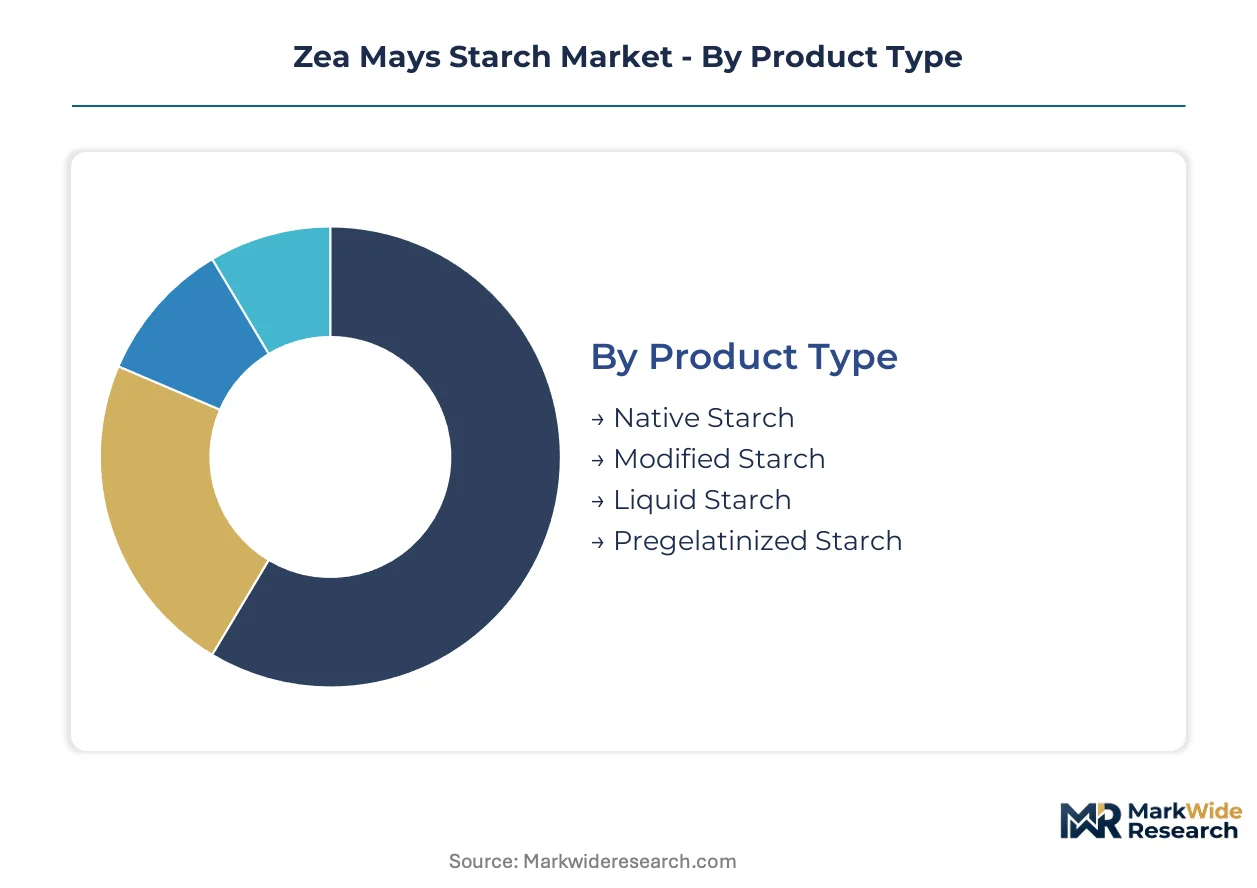
Segmentation in the Zea Mays Starch Market reveals how extraction methods, functional modifications, and end-use specifications create divergent margin profiles across supply chains. Processors configure production lines around specific segment requirements, from pharmaceutical-grade purity to corrugated board cost minimization.
Product Type:
Domestic consumption in North America and Europe concentrates in modified and pregelatinized grades, while Southeast Asian export corridors move substantial native starch volumes to paper and textile manufacturers.
- Native Starch:Unmodified carbohydrate polymer with 25-28% amylose content serves paper sizing and corrugated adhesive applications where cost minimization dominates procurement. Demand concentrates in Thailand and Vietnam's packaging sectors, though cassava substitution intensifies when price spreads exceed threshold levels.
- Modified Starch:Cross-linked and stabilized variants withstand extreme processing temperatures in convenience foods and industrial binders. Export-led demand from Indonesia's instant noodle manufacturers around Jakarta and Surabaya is pulling volumes for texture stabilization, with premium pricing sustained by functional performance requirements.
- Liquid Starch:Pre-dispersed aqueous suspensions eliminate hydration steps in continuous manufacturing processes.
- Pregelatinized Starch:Cold-water soluble grades manufactured through drum-drying or extrusion meet pharmaceutical direct-compression specifications.
Native starch holds the largest share; momentum sits with modified starch as Southeast Asian food processors expand clean-label formulations requiring functional performance.
Application:
Margin structures vary dramatically across applications, with pharmaceutical and food-grade segments commanding triple the pricing of industrial corrugated applications.
- Food & Beverage:Clean-label mandates from Southeast Asian processors are redirecting procurement toward native and minimally modified grades, compressing margins for conventional wet-milling operations while rewarding integrated organic corn supply chains.
- Pharmaceuticals:Tablet manufacturers are expanding pregelatinized starch purchases to eliminate granulation steps and reduce manufacturing cycle times, with USP-NF and EP compliance creating supplier consolidation pressures.
- Textiles:Warp sizing and finishing applications favor liquid starch formulations for continuous processing efficiency.
- Paper & Corrugated:Cost minimization dominates procurement decisions in this volume-driven segment where native starch retains leadership.
Food and beverage applications anchor volume; pharmaceutical-grade segments are expanding most quickly as drug makers pursue manufacturing efficiency.
Form:
Processing economics and handling requirements determine form selection, with powder dominating long-distance trade and gel/paste formulations serving regional just-in-time supply chains.
- Powder:Standard dehydrated form with extended shelf stability supports global trade flows and bulk pharmaceutical excipient shipments.
- Granule:Free-flowing agglomerated particles reduce dusting in high-speed food processing lines.
- Gel:Pre-hydrated matrices serve ready-to-use textile and adhesive applications requiring immediate viscosity development.
- Paste:High-solids preparations eliminate hydration energy costs in corrugated board manufacturing.
Powder form holds the largest share; gel formulations are gaining share fastest as regional processors seek to eliminate hydration infrastructure.
End User:
Direct-procurement relationships between large food processors and wet-milling operations are compressing traditional distributor margins and accelerating price discovery across end-user categories.
- Food Processors:Instant noodle and snack manufacturers in Indonesia's processed food corridor are establishing volume contracts with refiners, bypassing regional trading houses and compressing lead times from weeks to days.
- Cosmetic Manufacturers:REACH compliance documentation and CSRD sustainability reporting obligations are tightening import specifications for corn starch entering European cosmetic supply chains.
- Adhesive Producers:Corrugated board and packaging adhesive formulators prioritize native starch cost positions.
- Biofuel Companies:Ethanol fermentation demand competes directly with starch extraction for corn feedstock, with Brazil's biofuel blending mandates diverting supply toward fermentation channels.
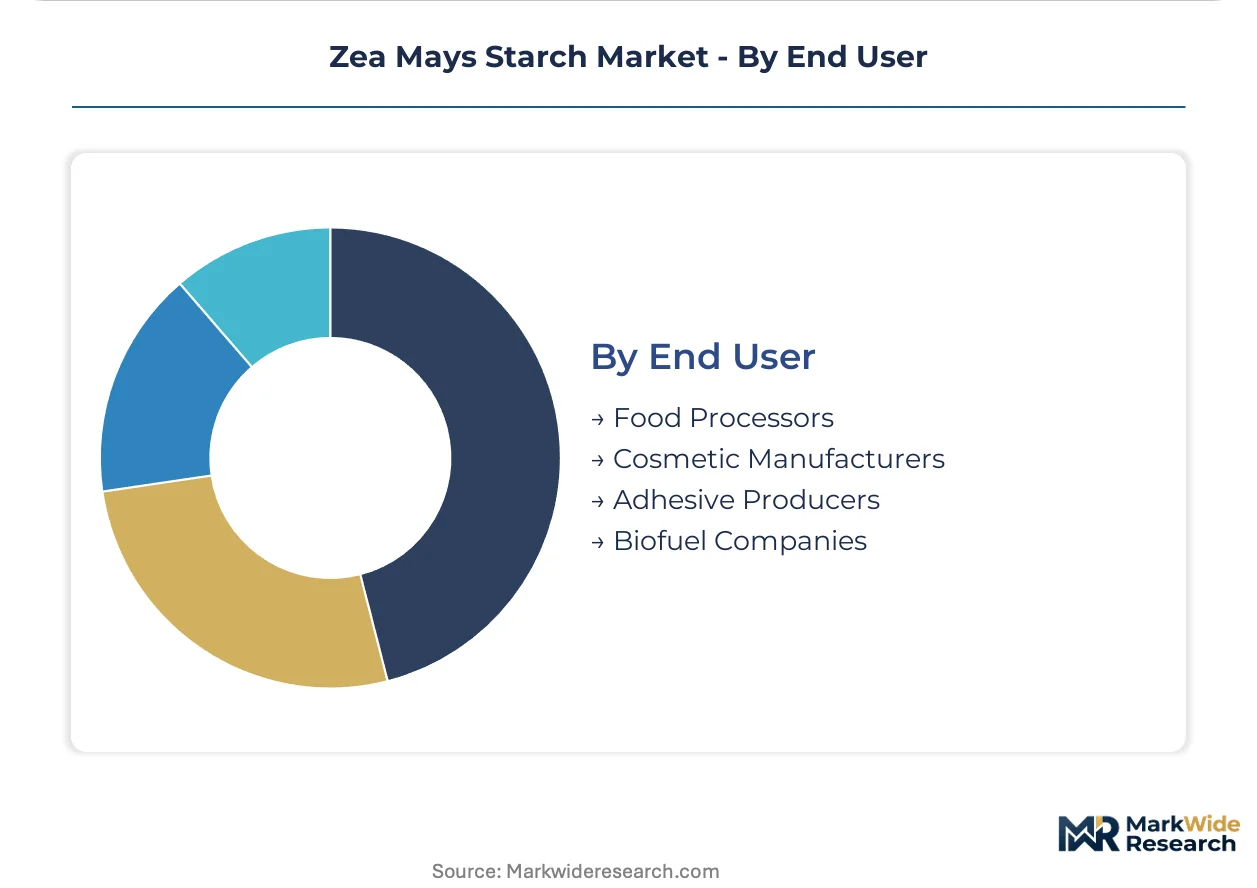
Food processors hold the largest share; cosmetic manufacturers are climbing the fastest as clean-label and sustainability certification requirements deepen penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances vary sharply across major starch-consuming economies, with surplus regions shipping native grades to deficit markets while modified and pharmaceutical grades flow in reverse. Trade corridors between North American Corn Belt origins and Southeast Asian food processing hubs command premium freight economics.
United States
Iowa and Illinois wet-milling complexes supply modified starch derivatives to Indonesian instant noodle manufacturers. EPA Clean Water Act permits constrain smaller facilities, consolidating processing capacity around Cargill's grain origination network. Chicago-area distribution terminals accelerate price discovery for pharmaceutical-grade exports.
Indonesia
Jakarta and Surabaya food processors drive modified starch demand for texture stabilization in convenience foods. The B35 biodiesel program diverts corn feedstock toward fermentation, tightening starch extraction availability. Direct-procurement contracts between noodle manufacturers and refiners compress traditional distributor margins.
Germany
REACH compliance documentation and EU Green Deal traceability requirements reshape import specifications for cosmetic and food-grade starch. Emsland Group facilities in Lower Saxony process pharmaceutical-grade pregelatinized derivatives for tablet manufacturers. Hamburg port logistics anchor continental distribution.
Brazil
Biofuel blending mandates redirect corn supply between starch extraction and ethanol fermentation channels. São Paulo-state processors face feedstock competition from sugarcane ethanol expansion. Paraná and Mato Grosso grain origination points supply both domestic wet-mills and export terminals.
Thailand
Paper and corrugated manufacturers switch between corn and cassava starch based on price spreads exceeding threshold levels. Bangkok-adjacent packaging clusters prioritize native starch cost minimization. Board manufacturers maintain dual-sourcing flexibility to arbitrage feedstock differentials.
Zea Mays Starch Market Competitive Landscape
Concentration sits with integrated agribusiness conglomerates possessing captive corn supply and multi-plant wet-milling networks. Three structural tiers define competitive positioning: global refiners with pharmaceutical-grade certification, regional processors serving food manufacturing clusters, and commodity native starch producers competing on feedstock proximity. Dominant competitive moves include backward integration into grain origination and portfolio diversification across sweetener-starch output switching.
Within the global refiner tier, Archer Daniels Midland Company and Cargill, Incorporated represent integrated agribusiness archetypes with North American Corn Belt presence. Ingredion Incorporated occupies a position emphasizing higher-margin modified derivatives. Tate & Lyle PLC exemplifies refinery flexibility between sweetener and starch production. Roquette Frères and AGRANA Beteiligungs-AG anchor European supply positions serving REACH-compliant markets.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Roquette Frères |
| AGRANA Beteiligungs-AG |
| Tereos |
| Royal Avebe U.A. |
| Emsland Group |
| Others |
Value Network & Pricing Analysis
Five-day lead times between Jakarta's instant noodle manufacturers and Surabaya refiners signal compressed inventory cycles that amplify buyer leverage and narrow margin capture for distributors caught between direct-procurement trends and wet-milling capacity concentration. This compression rewards processors with captive corn origination while penalizing merchant traders lacking upstream integration.
Pricing Analysis
The customization-premium spread between pharmaceutical-grade pregelatinized starch and standard native grades exceeds threefold, with contract-based long-term offtake dominating modified starch procurement for Indonesian food processors. Price differentiation hinges on USP-NF certification tier and verified non-GMO chain-of-custody documentation. Cost compression in native starch runs through cassava substitution threats in Thai packaging markets. Paper and corrugated manufacturers exhibit highest price sensitivity; pharmaceutical tablet makers show least sensitivity due to regulatory qualification barriers.
Supply Chain Analysis
Inventory cycles stretching 30-45 days for European REACH-compliant imports contrast with just-in-time flows in Southeast Asian food corridors. Supply concentrates in the United States, Indonesia, and Germany, with wet-milling capacity anchored in Iowa-Illinois Corn Belt operations and Emsland Group facilities. Corn feedstock, enzyme processing inputs, and drum-drying energy draw from agricultural and chemical supply bases. Single-source vulnerability sits with steeping expertise aging out in North American operations. Distribution runs through Chicago-area terminals for pharmaceutical exports and direct-procurement contracts bypassing regional trading houses in Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity deepens as clean-label mandates splinter demand across organic certification tiers, specialty modified grades, and pharmaceutical excipient qualifications that reward focused specialists over commodity generalists.
For Market Incumbents: Consolidate backward integration into Brazilian and Indonesian grain origination to secure feedstock priority against biofuel diversion threats. Lock pharmaceutical-grade capacity behind USP-NF and EP certification moats that disqualify regional competitors from multinational drug maker supplier reduction programs. For New Entrants and Emerging Players: Contract manufacturing services for enzyme-assisted wet milling address capability gaps where aging North American engineering talent constrains incumbent expansion. Penetrate European cosmetic manufacturers demanding REACH-compliant documentation with third-party verified sustainability reporting that established players integrate slowly against legacy ERP architectures. Lead with certified organic native starch for baby food specialists in Germany and France. For Investors and Strategic Acquirers: Carve-out targets emerge from agribusiness conglomerates divesting non-core starch assets amid sweetener-starch margin volatility. Five-to-ten year viability favors processors with pharmaceutical certification and Indonesian corridor access over commodity native starch exposure. Watch EU Green Deal chain-of-custody enforcement intensity as inflection signal for premium grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Origination | Cargill's grain network secures feedstock priority against Brazilian biofuel diversion mandates. |
| Pharmaceutical Certification Investment | USP-NF and EP compliance opens multinational drug maker supplier consolidation opportunities. |
| Enzyme-Assisted Wet Milling Adoption | Specialized processing reduces steeping chemical residues for clean-label European cosmetic demand. |
| Direct-Procurement Contracting | Indonesian instant noodle manufacturers bypass distributors, compressing lead times to under one week. |
| REACH Compliance Documentation Systems | Third-party verified chain-of-custody records maintain European market access under tightened import specifications. |
Research Methodology
Operator-level perspectives from wet-milling plant managers, pharmaceutical procurement directors, Indonesian food processor supply chain heads, and European cosmetic formulators anchored the qualitative base. Secondary validation drew from FDA GRAS determinations, EPA Clean Water Act permit databases, EU ECHA REACH substance registrations, and Indonesian B35 biodiesel program disclosures. Bottom-up volume modeling triangulated against top-down agricultural feedstock allocation estimates across the analysis window.
Sensitivity analysis tested extraction efficiency assumptions and biofuel policy trajectory variants throughout the forecast period. Segmentation dimensions spanned product type, application, form, and end-user concentration patterns with pharmaceutical-grade purity tiers modeled separately. CAGRs derived from historical capacity utilization trends and projected feedstock competition intensities between starch extraction and ethanol fermentation channels.
Underlying assumptions cover sustained EU Green Deal traceability enforcement and Southeast Asian processed food investment continuity, with deviation risk concentrated in Brazilian biofuel mandate escalation and cassava starch substitution threshold breaches. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Pulse Flours Market
Ingredients
North America Soybean Oil Market
Ingredients
Middle East and Africa Fermented Ingredients Market
Ingredients
Bakery Ingredients Market
Ingredients
Pea Protein Ingredients Industry Status and Prospects Professional Market
Ingredients
Textural Food Ingredients Market
Ingredients
Anti-Aging Ingredients Market
Ingredients
South America Feed Yeast Market
Ingredients
Cocoa Market
Ingredients
EPA and DHA Omega-3 Ingredient Market
Ingredients
Microencapsulated Oil Market
Ingredients
South America Insoluble Dietary Fibers Market
Ingredients
Global Fruits and Vegetables Ingredients Market
Ingredients
Europe Vanilla Beans and Extract Market
Ingredients
North America Gluten Free Flour Market
Ingredients
Canada Whey Protein Ingredients Market