
 Smoke Spill Motor Market | 2026-2036
Smoke Spill Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Smoke Spill Motor Market Insights
A shift from single-source to dual-source procurement is hardening among large facility operators seeking supply security for critical smoke control infrastructure. Siemens leverages its automation portfolio to bundle motor and control systems for integrated fire safety packages. ABB competes through direct-drive technology leadership that reduces maintenance intervals in high-rise installations. Wolong anchors cost-sensitive segments with scaled manufacturing of AC induction motors for industrial ventilation.
A smoke spill motor is an electrically driven fan motor engineered to operate at elevated temperatures for sustained periods, typically rated for 300°C to 400°C exposure per EN 12101-3, designed to maintain tenable conditions and facilitate safe evacuation during building fires. These motors employ Class H or Class F insulation systems with thermosetting resin coatings to prevent winding failure under thermal stress. AC Motors dominate current revenue as legacy installations favor proven induction technology, while Brushless motors capture the fastest expansion due to their superior thermal tolerance and reduced electromagnetic interference in sensitive building systems. Smoke Control Systems concentrate margin pools where certification requirements and specification-driven procurement limit price competition.
EN 12101-3 in Europe, NFPA 92 from the National Fire Protection Association in the United States, and China's GB 51251 standard collectively mandate temperature-rated performance and periodic testing that sustain replacement demand and bar uncertified suppliers. The EU F-Gas Regulation indirectly shapes motor specification by restricting refrigerants in combined HVAC-smoke control units, pushing manufacturers toward sealed brushless designs. Stakeholders must monitor divergence between regional certification regimes as specification engineers in multinational construction firms face mounting complexity in harmonizing equipment standards across project portfolios.
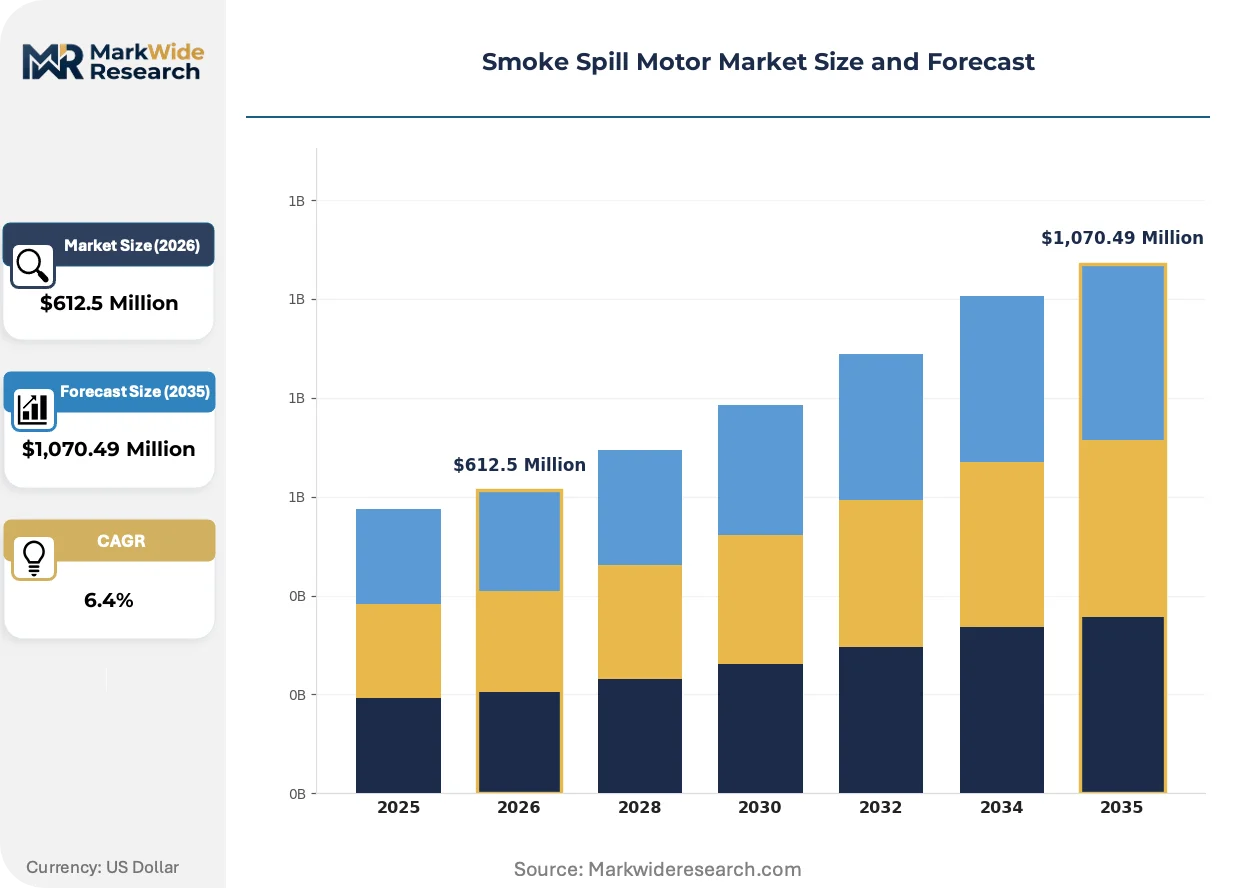
Market Dynamics
Brushless motor technology is consolidating specification authority across commercial building projects as thermal tolerance requirements harden under EN 12101-3 and GB 51251 enforcement, compressing the viable supplier base for legacy AC induction designs.
Growth Catalysts
- GB 51251 enforcement in China:Urban construction volume and mandatory fire safety testing accelerate replacement cycles for non-compliant legacy motors in high-rise residential towers.
- Commercial building code tightening:Shopping complexes and data centers in Germany, France, and the United Kingdom face upgraded smoke extraction mandates under the EU F-Gas Regulation.
- Brushless DC thermal performance:Superior heat dissipation and reduced electromagnetic interference enable specification in sensitive healthcare and telecommunications infrastructure.
Market Restraints
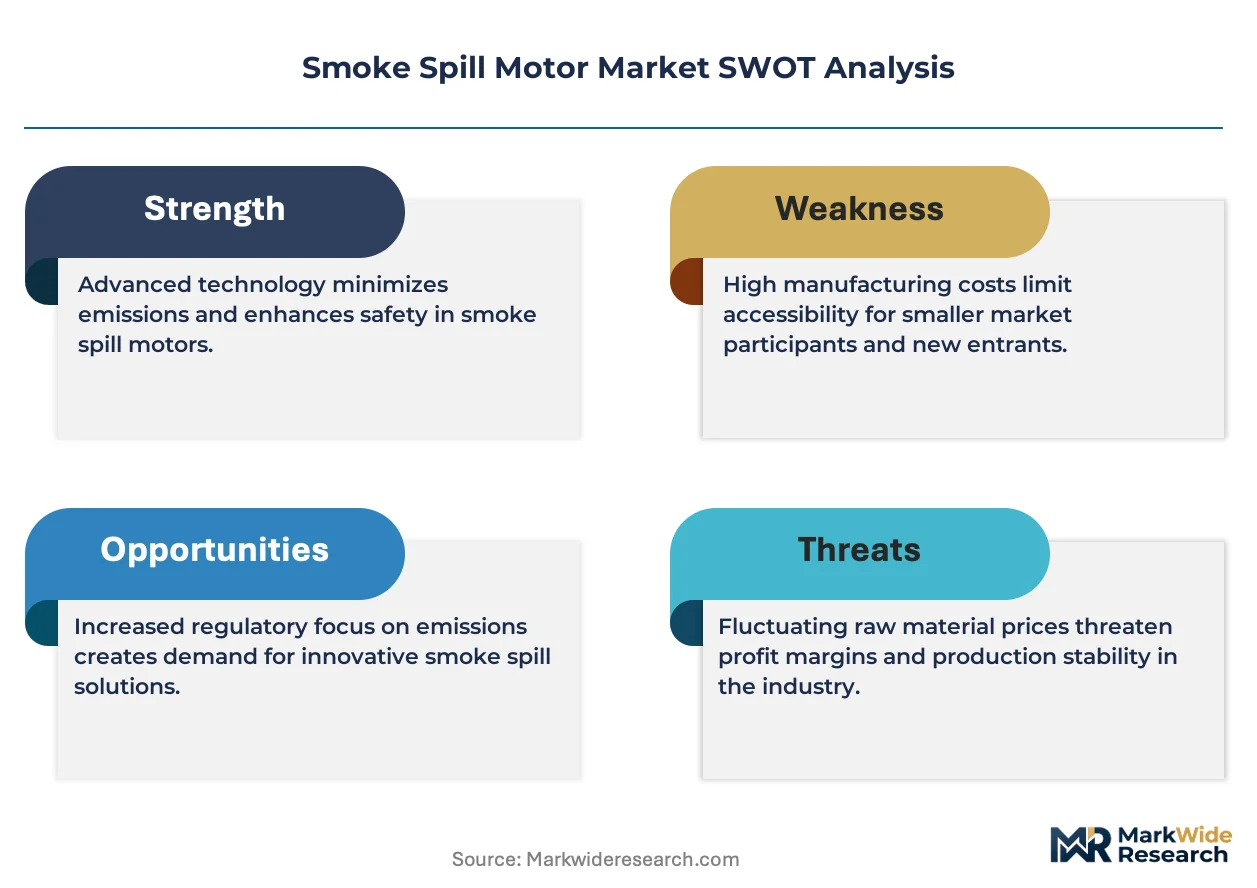
- Copper and rare earth magnet cost volatility:Neodymium price swings compress margins for brushless motor manufacturers dependent on Chinese processed magnet supply.
- EN 12101-3 certification timeline:Third-party testing and documentation requirements extend product launch cycles by 8-14 months for new market entrants.
- Legacy AC motor installed base:Decades of induction motor deployment in industrial ventilation creates substitution resistance among cost-sensitive facility operators.
Strategic Opportunities
- India commercial construction acceleration:Bureau of Indian Standards fire safety code harmonization with IEC standards opens specification pathways for temperature-rated motors in metro rail and airport terminals.
- Smart building integration:Convergence of smoke control motors with building automation systems enables predictive maintenance contracts and recurring revenue streams.
- EU Green Deal renovation wave:Deep energy retrofits of existing commercial stock mandate simultaneous HVAC and fire safety upgrades, bundling motor replacement with efficiency improvements.
Industry Challenges
- High-voltage insulation engineering shortage:Limited talent pool for Class H winding design and thermosetting resin application constrains R&D throughput at mid-tier manufacturers.
- Dual certification complexity:Multinational construction firms face mounting specification friction harmonizing EN 12101-3, NFPA 92, and GB standards across integrated project portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoke Spill Motor Market |
| Market Size in 2026 | $612.5 Million |
| Market Size in 2035 | $1,070.49 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Servo Motors, Stepper Motors Application: Industrial Ventilation, Smoke Control Systems, Fire Safety Solutions, HVAC Systems End User: Manufacturing Facilities, Commercial Buildings, Residential Complexes, Warehouses Technology: Direct Drive, Gear-Driven, Brushless, Synchronous |
| Companies Covered | HANZEL, VEM Group, ATB Motors, Havells, WEG, TECO, Siemens, ABB, Wolong, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoke Spill Motor Market Trends and Innovations
Permanent magnet synchronous motor architectures are actively compressing the performance gap between premium and standard product tiers. Specification engineers now prioritize thermal envelope over first-cost in critical infrastructure bids.
Permanent magnet synchronous motor technology is consolidating market position in high-rise smoke extraction applications. Building automation integrators specify these units for their superior torque density and reduced footprint in mechanical penthouses. The technology is consolidating supplier margins by enabling premium pricing for certified configurations that legacy induction designs cannot match.
The EU F-Gas Regulation restricts refrigerant choices in combined HVAC-smoke control units, indirectly mandating sealed motor architectures. Manufacturers respond with brushless designs that eliminate shaft seals and bearing contamination risks. German and French specification engineers now require F-Gas-compliant documentation alongside EN 12101-3 certification for bundled mechanical packages.
Dual-source procurement is hardening among large facility operators managing critical infrastructure portfolios. Hospital chains and airport authorities split motor orders between incumbent suppliers to mitigate single-point-of-failure exposure. This pattern is most visible in China and Germany, where state-owned enterprises and municipal operators face heightened accountability for fire safety system resilience.
Smoke Spill Motor Market Segmentation
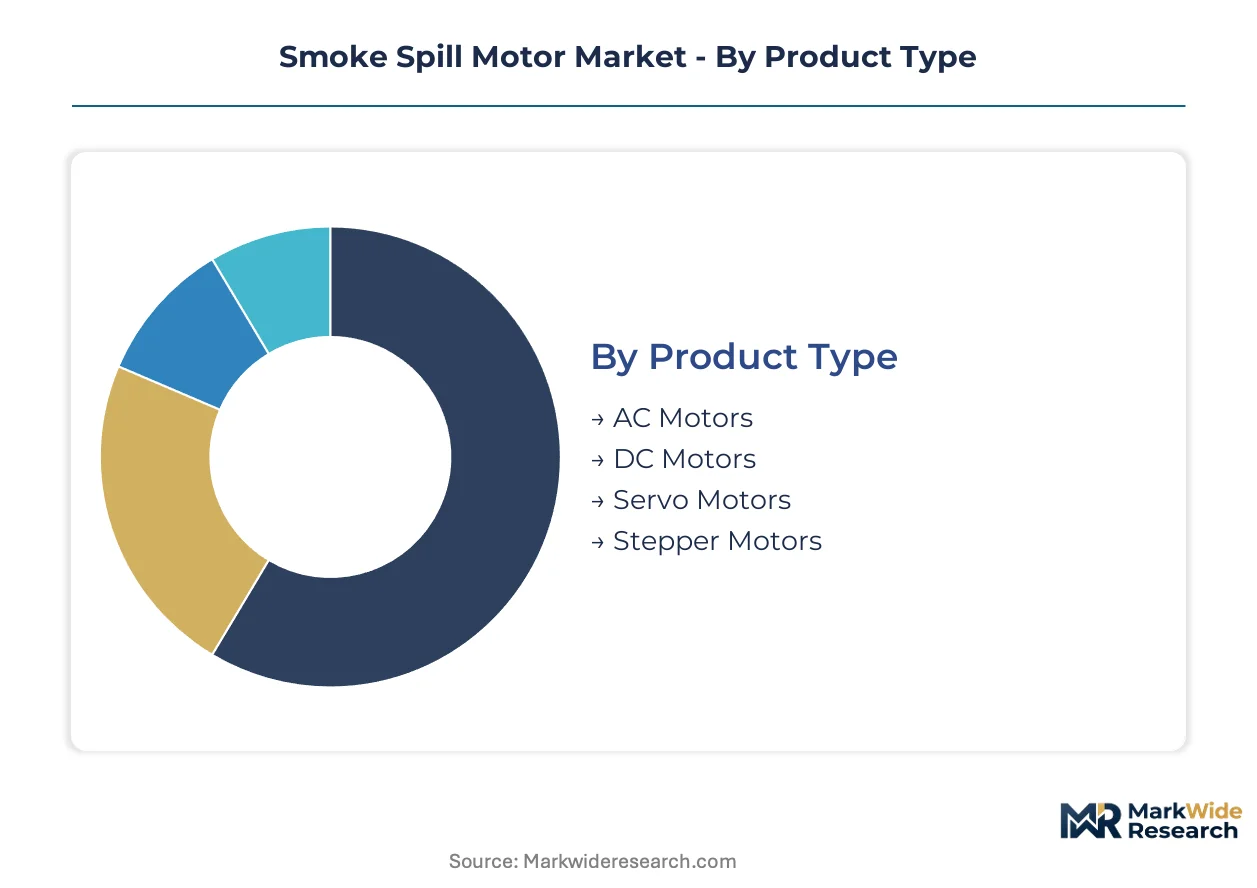
Smoke spill motor procurement hinges on thermal certification grade, building code jurisdiction, and integration complexity with automation infrastructure. Specification engineers weight motor architecture against EN 12101-3 temperature ratings and long-term maintenance access in high-rise mechanical penthouses.
Product Type:
Thermal tolerance and electromagnetic compatibility distinguish motor architectures for fire safety duty cycles.
- AC Motors:Induction designs with Class H insulation systems dominate legacy installations across industrial ventilation. Facility operators in Germany and France favor proven reliability for retrofit projects where certification continuity matters.
- DC Motors:Brushed configurations persist in cost-sensitive warehouse applications with simpler control requirements. Chinese manufacturing facilities specify these units for basic smoke extraction in single-story distribution centers.
- Servo Motors:Precision positioning capability enables variable-speed smoke control in atrium and atrium-adjacent spaces. Japanese commercial developers integrate these with building automation for dynamic airflow management.
- Stepper Motors:Discrete angular control suits damper-actuation subsystems within integrated fire safety packages. Korean data center operators specify stepper-driven louvers for zoned extraction protocols.
AC Motors lead on scale; Brushless DC architectures (within DC Motors) lead on momentum.
Application:
Certification intensity and system integration depth fragment demand across building safety domains.
- Smoke Control Systems:EN 12101-3 and NFPA 92 certification requirements sustain premium pricing for temperature-rated configurations. Hospital chains in the United Kingdom and airport authorities in the United Arab Emirates mandate redundant motor arrays for life safety criticality.
- Fire Safety Solutions:Integration with alarm and suppression networks demands sealed brushless architectures resistant to contamination. German municipal building codes now require F-Gas-compliant documentation for bundled mechanical packages.
- Industrial Ventilation:Continuous-duty AC induction motors serve process exhaust in manufacturing facilities. Indian steel plants and chemical processors specify these for ambient temperature fume extraction without fire-rated duty cycles.
- HVAC Systems:Combined heating, ventilation, and smoke control units face EU F-Gas refrigerant restrictions. French specification engineers prioritize sealed motor designs that eliminate shaft seal failure modes in rooftop installations.
Smoke Control Systems concentrate margin pools; Fire Safety Solutions gain share fastest through integrated procurement.
End User:
Accountability structures and code enforcement rigor shape specification authority across building types.
- Commercial Buildings:Shopping complexes, data centers, and telecom facilities face tightening extraction mandates under EU and Chinese regulations. State-owned enterprises in China accelerate replacement cycles for GB 51251 compliance in high-rise towers.
- Manufacturing Facilities:Process ventilation and emergency smoke extraction operate on separate motor fleets. German automotive plants maintain dual inventories for production exhaust versus fire-rated duty.
- Residential Complexes:High-rise residential towers in urban China drive volume for standardized AC motor configurations. Municipal fire safety testing mandates in Shanghai and Shenzhen compress replacement intervals.
- Warehouses:Single-story logistics facilities prioritize first-cost over thermal certification for basic smoke spill duty. E-commerce fulfillment centers in the United States specify commodity induction motors for ceiling-mounted extraction.
Commercial Buildings command specification authority; Residential Complexes in China climb the fastest.
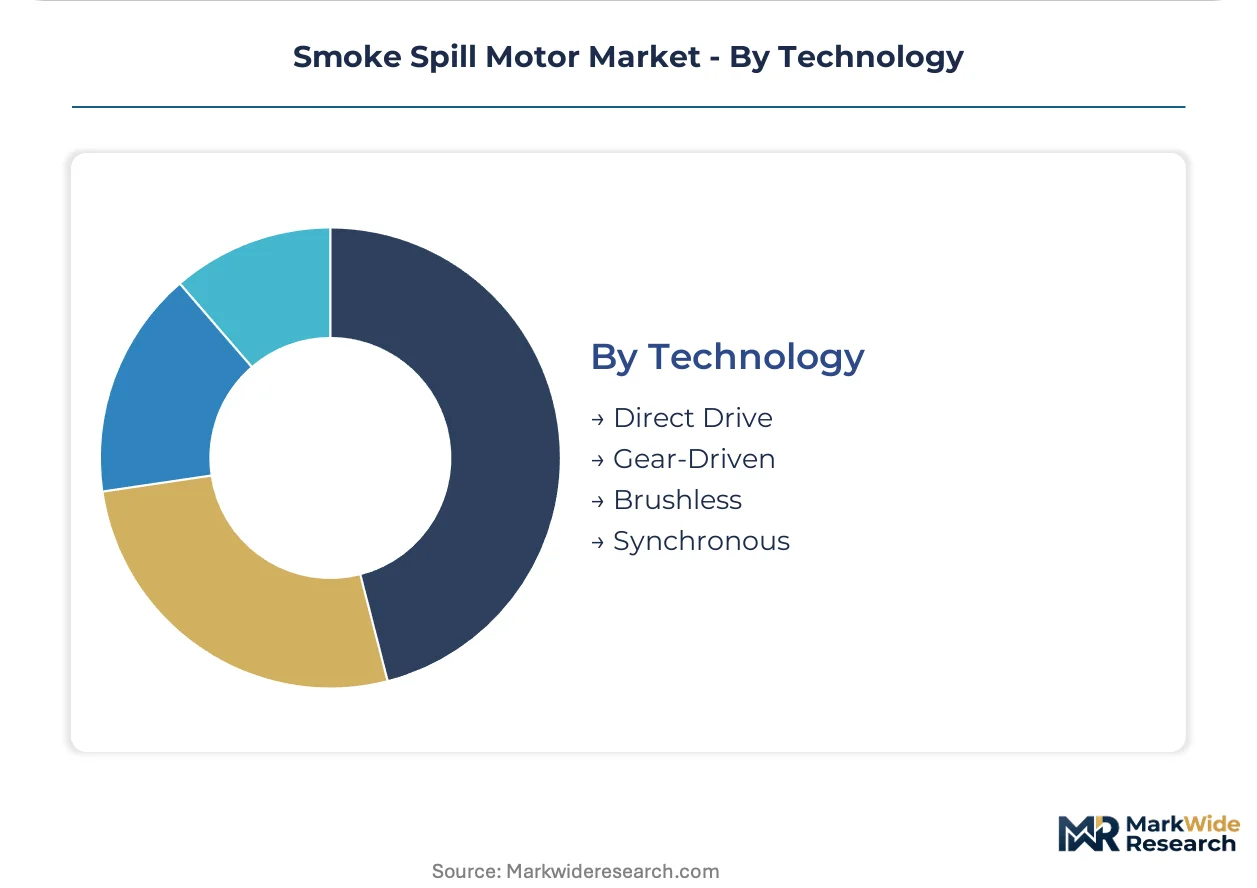
Technology:
Mechanical transmission architecture and rotor magnetization determine maintenance intervals and thermal envelopes.
- Brushless:Permanent magnet synchronous designs with thermosetting resin coatings achieve 300°C to 400°C thermal ratings. Healthcare and telecommunications infrastructure in Japan and Germany specify these for electromagnetic interference immunity.
- Direct Drive:Elimination of gearbox components reduces maintenance access requirements in high-rise mechanical penthouses. ABB's technology leadership anchors specification in premium commercial projects.
- Gear-Driven:Speed reduction through mechanical transmission persists in legacy industrial ventilation. Cost-sensitive operators in India retain these configurations for existing ductwork compatibility.
- Synchronous:Locked rotor speed enables precise coordination with variable frequency drives in smart building integration. Korean and Singaporean building automation integrators specify these for predictive maintenance enablement.
Brushless technology leads on specification momentum; Direct Drive leads on margin capture in premium installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta and Pearl River Delta industrial corridors concentrate smoke spill motor fabrication capacity alongside high-rise construction demand. Germany's Ruhr industrial basin and southern manufacturing belt anchor European specification engineering. The United Arab Emirates, India, and the United States complete the geographic spread through infrastructure investment cycles and code enforcement rigor.
China
Shanghai and Shenzhen municipal authorities enforce GB 51251 testing protocols that compress replacement intervals for legacy smoke control installations. The Ministry of Emergency Management coordinates with provincial fire safety bureaus to mandate temperature-rated motor certification in high-rise residential towers exceeding 100 meters. Yangtze River Delta manufacturing clusters supply both domestic demand and export markets across Southeast Asia.
Germany
North Rhine-Westphalia's industrial ventilation engineering base serves retrofit demand across aging commercial stock in the Ruhr region. The EU F-Gas Regulation drives specification of sealed brushless architectures in combined HVAC-smoke control packages. Bavarian building automation integrators specify premium motor configurations for data center and healthcare infrastructure in Munich and Stuttgart metropolitan zones.
United Arab Emirates
Dubai International Airport and Abu Dhabi hospital authority procurement mandates redundant motor arrays for life safety criticality. MOHAP certification requirements align with EN 12101-3 thermal rating standards for imported smoke control equipment. Dubai's commercial construction pipeline concentrates specification authority among state-owned developers managing mixed-use tower portfolios.
India
Maharashtra and Karnataka state metro rail projects generate specification pathways for temperature-rated motors in underground station ventilation. Bureau of Indian Standards fire safety code harmonization with IEC standards accelerates certification timelines for imported equipment. Mumbai and Bangalore commercial construction clusters drive demand for integrated fire safety packages in IT park developments.
United States
NFPA 92 compliance mandates sustain replacement demand across legacy high-rise stock in Chicago and New York metropolitan areas. OSHA workplace safety enforcement intersects with municipal fire codes to require periodic smoke control system testing. Pacific Northwest data center construction clusters specify electromagnetic interference-resistant motor configurations for telecommunications infrastructure.
Smoke Spill Motor Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart building integration and predictive maintenance service models. The supplier base stratifies across three archetypes: diversified industrial conglomerates bundling motor and control systems, specialized motor manufacturers with certification depth, and cost-focused fabricators serving commodity replacement cycles. Market consolidation proceeds through technology licensing agreements and strategic partnerships with building automation integrators rather than horizontal mergers.
Among diversified industrial conglomerates, Siemens and ABB exemplify specification authority through integrated fire safety portfolios. Wolong anchors the cost-optimized tier with scaled manufacturing capabilities for AC induction motor platforms. These three companies represent distinct competitive vectors: bundled system provision, premium direct-drive technology, and volume-driven standard product supply.
| Leading Market Players |
|---|
| HANZEL |
| VEM Group |
| ATB Motors |
| Havells |
| WEG |
| TECO |
| Siemens |
| ABB |
| Wolong |
| Others |
Pricing and Supply Chain Analysis
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by mandating sealed brushless architectures in combined HVAC-smoke control units. German and French specification engineers now require F-Gas-compliant documentation alongside EN 12101-3 certification, compressing the supplier base capable of commanding premium pricing while elevating compliance costs for uncertified competitors.
Pricing Analysis
Neodymium and copper cost pass-through dynamics shape margin compression across brushless motor manufacturers dependent on Chinese-processed rare earth magnet supply. Three-tier pricing structure across premium certified, standard compliant, and economy replacement levels stratifies by EN 12101-3 thermal rating and automation integration depth. Cost compression in the economy tier is intensifying because legacy AC induction motor substitution resistance persists among warehouse operators in the United States and India. Hospital chains and airport authorities exhibit least price sensitivity, while single-story logistics facilities in cost-sensitive markets drive commodity procurement.
Supply Chain Analysis
Reverse-logistics flows for refurbishment and remanufacturing of fire-rated motors remain underdeveloped, constraining circular economy participation. Manufacturing gravity centers on China, Germany, and India, with Yangtze River Delta clusters feeding domestic and Southeast Asian demand. Magnet supply draws from Chinese processed neodymium and Japanese insulation resin feedstocks. Single-source vulnerability in rare earth magnet processing creates structural risk. Distribution runs through building automation integrators and fire safety system OEMs rather than direct motor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smoke spill motor market reads as a late-cycle quality story as specification engineers prioritize thermal envelope performance over first-cost in critical infrastructure bids. This demand-shift toward premium-certified configurations rewards suppliers with EN 12101-3 and GB 51251 testing depth.
For Market Incumbents: Extend certification breadth across EN 12101-3, NFPA 92, and GB 51251 to capture multinational construction firm procurement. Deepen backward integration into Class H winding and thermosetting resin capabilities to defend margin position against magnet cost volatility. Anchor specification authority through bundled motor-control system packages that raise switching costs for facility operators. For New Entrants and Emerging Players: Enter via smart building integration partnerships with predictive maintenance service models that bypass capital-intensive manufacturing. Target Indian metro rail and airport terminal projects where Bureau of Indian Standards harmonization with IEC standards opens specification pathways before incumbent certification depth hardens. Pursue white-label supply to German building automation integrators seeking secondary motor sources for dual-source procurement mandates. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier AC induction motor fabricators with GB 51251 certification gaps but scalable manufacturing infrastructure. Long-term viability over a multi-year window hinges on brushless technology transition capability and automation integration depth. Acquisition target archetype: certified specialists with EN 12101-3 testing infrastructure and relationships with Chinese state-owned enterprise procurement channels. Monitor GB 51251 enforcement intensity in Shanghai and Shenzhen municipal jurisdictions as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EN 12101-3 Certification Expansion | Third-party testing investment opens specification pathways in German and UK hospital chains. |
| Brushless Motor Technology Transition | Permanent magnet synchronous designs capture premium positioning in high-rise mechanical penthouses. |
| Building Automation Integration Partnership | Siemens and ABB bundling strategies raise competitive barriers for standalone motor suppliers. |
| Indian Market Entry via BIS Harmonization | IEC-aligned fire safety codes enable certification pathway for metro rail and airport ventilation. |
| Predictive Maintenance Service Model | Recurring revenue streams from smart building integration offset commodity motor pricing pressure. |
Research Methodology
Multiple input streams — specification engineer interviews, fire safety contractor field assessments, and regulatory filing analysis — were reconciled to construct market estimates. Primary engagement with building automation integrators, OEM procurement teams, and municipal fire safety bureau officials in China, Germany, and India informed demand-side validation. Secondary sources included EN 12101-3 certification databases, GB standard enforcement notices, EU F-Gas Regulation implementation guidance, and customs trade records for motor and magnet flows. Bottom-up motor shipment estimates by thermal rating and top-down construction spend allocation were cross-referenced for convergence.
Historical shipment trajectories were cross-referenced against panel input from specification engineers and procurement directors to anchor projection assumptions. Segmentation modeling spanned motor architecture, thermal certification grade, building type, and regional regulatory cluster across the analysis window. CAGRs were derived from fitted growth curves applied to replacement cycle intervals and new construction penetration rates. Industry-specific forecast inputs included GB 51251 enforcement timelines and EU F-Gas Regulation compliance deadlines.
Inputs from Chinese provincial fire safety bureaus and German building automation integrators were available through the study window; gaps in Indian BIS certification timeline data introduce uncertainty bands around penetration assumptions. Forecasts reflect documented assumptions regarding code enforcement intensity and construction volume sustainability. Practitioners should monitor municipal testing mandate announcements in Shanghai and Shenzhen, alongside EU F-Gas Regulation amendment proposals, for early signals of replacement cycle acceleration or specification standard shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Intelligent All-Wheel Drive System Market
Automotive Parts
Global Bevel Gearbox Market
Automotive Parts
Brake Fluids Market
Automotive Parts
Automotive Fuel Accumulator Market
Automotive Parts
Automotive Trim Part Market
Automotive Parts
Automotive Viscosity Index Improvers Market
Automotive Parts
Die Cast Parts for Electric Vehicle Market
Automotive Parts
Automotive Seat Adjusters Market
Automotive Parts
Bulgaria Automotive Engine Oils Market
Automotive Parts
Global Automotive Engine Valves Market
Automotive Parts
Ceramic Matrix Composite Disc Brakes (CMC Brake Disc) Market
Automotive Parts
Global Automotive Muffler Tip Market
Automotive Parts
Automotive Key Blanks Market
Automotive Parts
Global Automotive Gasket and Seal Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
France Automotive Lubricants Market