
 Automatic Screw Feeding System Market | 2026-2036
Automatic Screw Feeding System Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Screw Feeding System Market Analysis
Multi-source procurement among tier-one automotive suppliers is recalibrating vendor qualification criteria for screw feeding equipment. Atlas Copco leverages its pneumatic systems heritage to anchor European OEM relationships. WEBER Schraubautomaten competes through precision engineering specialization in aerospace-grade applications. Shenzhen Haihou Industrial Co., Ltd. dominates cost-optimized bowl feeder production for Asian contract manufacturers.
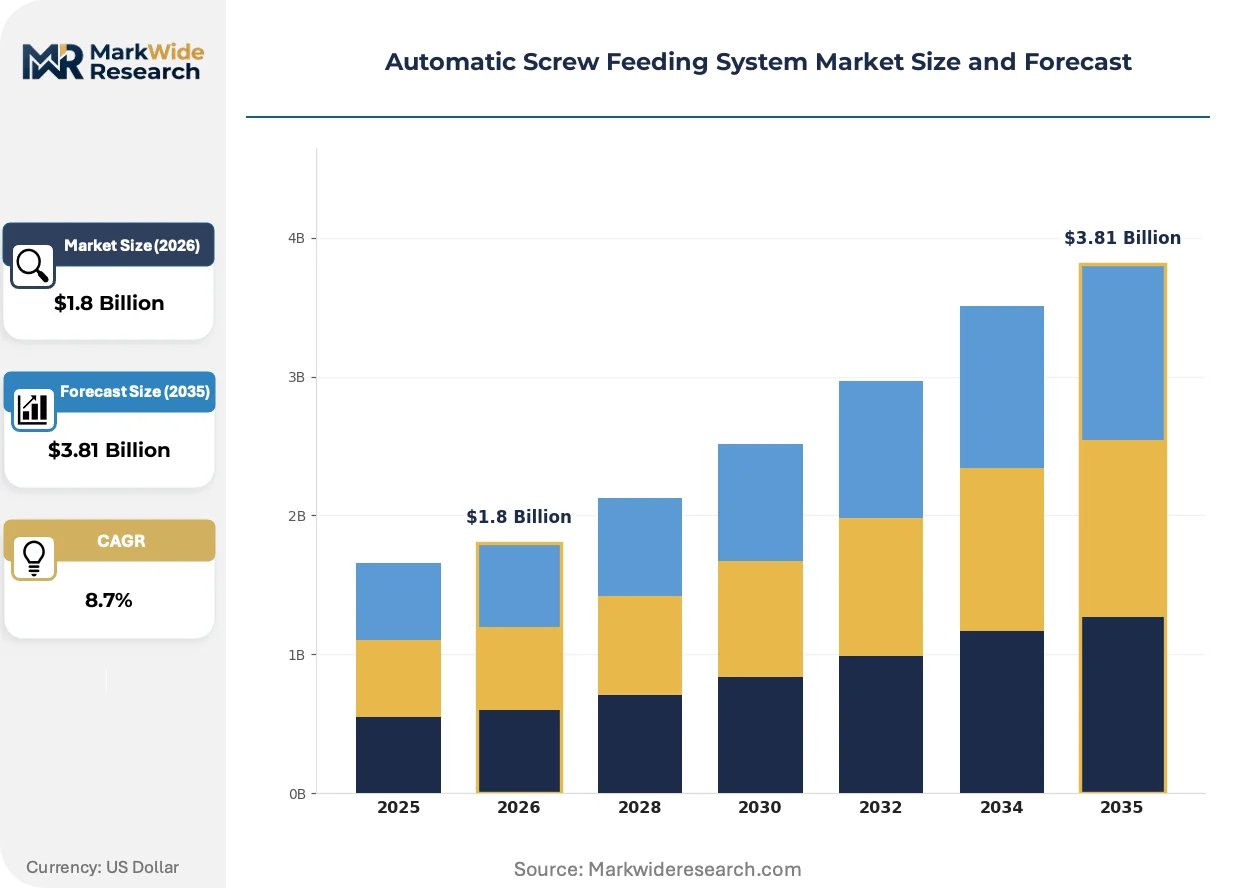
An automatic screw feeding system mechanically sorts, orients, and delivers fasteners to powered drivers at cycle rates exceeding 60 screws per minute, using vibratory bowl tracks or linear electromagnetic conveyors with photoelectric verification sensors. The equipment eliminates manual handling to reduce cross-threading defects and repetitive-strain injuries on high-volume assembly lines. Vibration feeders occupy the largest installed base across consumer electronics plants, though robotics-integrated systems represent the fastest-expanding margin pool as cobot deployments multiply. Electric drive systems sustain growing preference over pneumatic alternatives where energy efficiency and programmable torque control determine sourcing decisions.
The EU Machinery Directive and CE marking requirements shape product design obligations for equipment sold into European automotive and aerospace sectors. China's GB standards and MIIT equipment safety regulations govern domestic manufacturing and import compliance for automated assembly tools. ISO 10218 robot safety protocols increasingly influence system architecture where robotic arms perform screwdriving sequences. Stakeholders must monitor evolving cybersecurity annexes to machinery standards as networked production lines expose feeding controllers to remote access requirements.
Market Dynamics
Factory electrification programs across East Asian electronics hubs are systematically replacing pneumatic screw feeding infrastructure with programmable electric drive architectures, compressing equipment replacement cycles and recalibrating vendor qualification protocols for precision assembly tool procurement.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for automated assembly equipment are tightening verification protocols for machinery sold into European automotive and aerospace sectors, elevating demand for certified feeding system architectures.
- Electronics contract manufacturing clustering:Dense concentrations of smartphone and laptop assembly operations in China's Guangdong province are sustaining high-volume procurement of vibratory bowl and linear conveyor systems.
- ISO 10218 robot safety integration:Cobot deployment acceleration on precision assembly lines is driving specification of feeding controllers with embedded safety interlocks and collaborative motion verification.
Market Restraints
- Specialized component supply concentration:Precision electromagnetic drive coils and photoelectric verification sensors depend on concentrated sourcing from East Asian component foundries, exposing lead time volatility.
- Steel alloy input cost sensitivity:Vibratory bowl fabrication relies on cold-rolled spring steel grades whose price fluctuations directly impact equipment manufacturing economics.
- Pneumatic system installed base inertia:Legacy compressed-air infrastructure in mature automotive plants creates switching cost barriers against electric drive conversion despite efficiency advantages.
Strategic Opportunities
- India electronics manufacturing incentives:PLI scheme subsidies for smartphone and component production are attracting contract manufacturers to Gujarat and Tamil Nadu, opening greenfield automation procurement.
- Cybersecurity annex integration:Evolving machinery standards incorporating networked production line protection requirements create specification wedges for feeding controllers with encrypted remote access architectures.
- Medical device assembly precision demands:ISO 13485-certified manufacturers of implantable electronics are specifying aerospace-grade screw feeding tolerances, expanding addressable margin pools beyond consumer electronics.
Industry Challenges
- Mechatronics technician scarcity:Programming and maintenance of electric drive systems with programmable torque control requires cross-trained automation engineers whose availability lags deployment timelines.
- Multi-standard certification sequencing:Simultaneous pursuit of CE marking, China's GB compliance, and ISO 10218 robot safety protocols extends product launch timelines for equipment vendors serving multinational OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Screw Feeding System Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vibration Feeders, Bowl Feeders, Screw Counters, Automatic Assembly Systems Application: Electronics Assembly, Automotive Manufacturing, Aerospace Production, Furniture Assembly End User: OEMs, Contract Manufacturers, Tooling Suppliers, Industrial Assembly Lines Technology: Pneumatic Systems, Electric Drive Systems, Magnetic Feed Systems, Robotics |
| Companies Covered | Atlas Copco, Shenzhen Haihou Industrial Co., Ltd., WEBER Schraubautomaten, Shenzhen Jianfeng Electronic Co., Ltd., Sanmipa, Carlson Engineering, SHENZHEN CHISU AUTOMATION EQUIPMENT CO., LTD., Shenzhen Ruidexin Automation Co., Ltd., Danikor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Screw Feeding System Market Emerging Trajectories
Intelligent feeding architectures are converging with networked production ecosystems, embedding diagnostic and predictive capabilities that transform equipment from isolated mechanical subsystems into data-generating nodes within digital manufacturing infrastructure.
Linear electromagnetic conveyors with integrated force-feedback sensing are rewriting performance expectations for high-speed precision assembly. Medical device manufacturers in Switzerland and Germany are specifying these systems for implantable electronics production. The technology is compressing the viable performance gap between vibratory bowl economics and robotic pick-and-place flexibility.
China's MIIT equipment safety regulations are mandating enhanced documentation and traceability for automated assembly tools deployed in domestic manufacturing facilities. Domestic certification bodies are expanding testing capacity to accommodate accelerated equipment approval timelines. Exporters to China are restructuring quality management systems to satisfy GB standard documentation requirements.
Automotive tier-one suppliers are consolidating vendor relationships around full-line automation integrators capable of delivering screw feeding as a subsystem within comprehensive assembly cell contracts. Direct equipment procurement by plant engineering teams is yielding to capital expenditure decisions centralized at OEM headquarters. This concentration is most pronounced among German and Japanese automotive manufacturers with multi-continent production footprints.
Automatic Screw Feeding System Market Segmentation
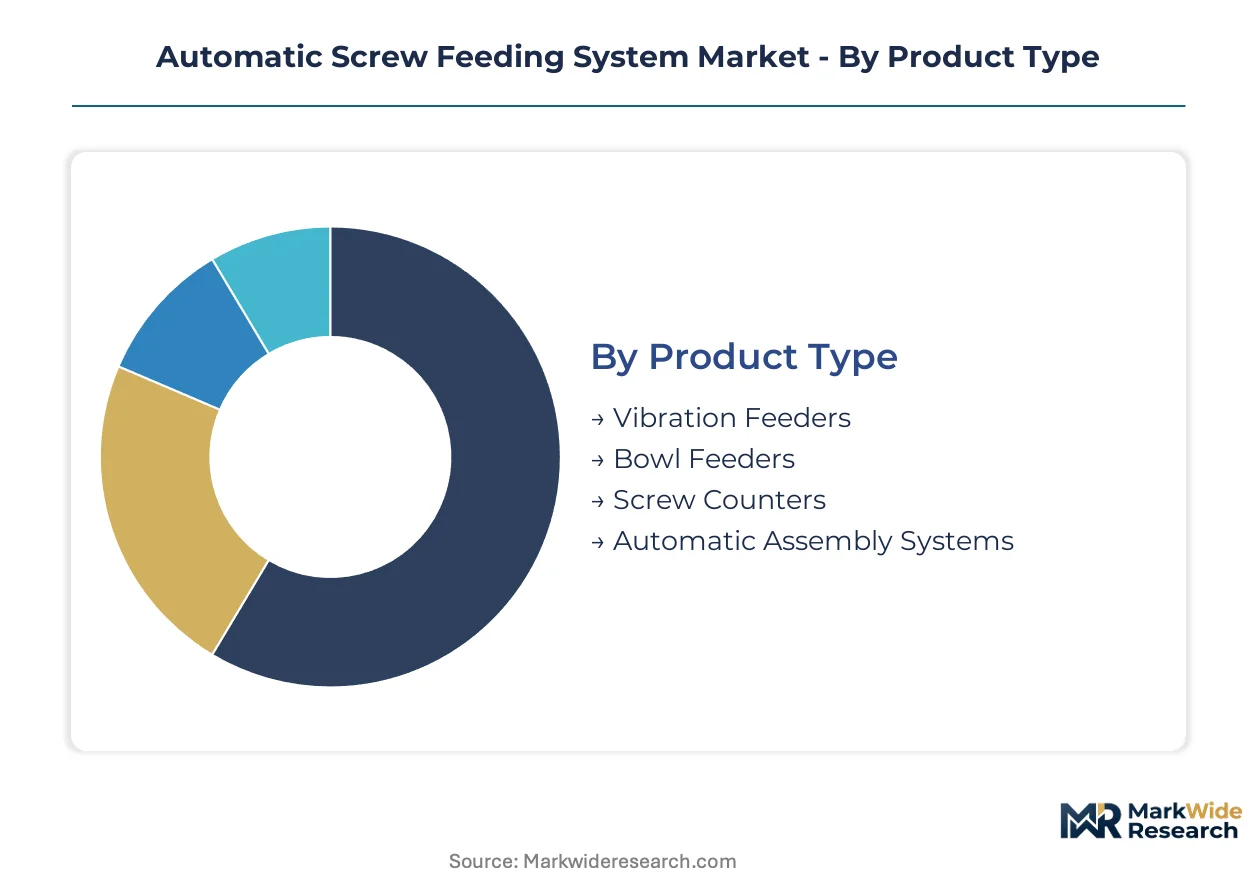
Segmentation in automatic screw feeding systems reveals how certification burdens, application precision requirements, and technology migration patterns reshape procurement decisions across discrete manufacturing verticals. Equipment specification diverges sharply between high-volume consumer electronics and aerospace-grade tolerance environments.
Product Type:
CE marking under the EU Machinery Directive and China's GB standards impose divergent documentation requirements on each product category, with vibration feeders facing the heaviest electromagnetic compatibility testing burdens.
- Vibration Feeders:Linear electromagnetic conveyors with integrated photoelectric verification sensors dominate high-speed electronics assembly. Guangdong contract manufacturers around Shenzhen specify these systems for smartphone production cycles exceeding 60 screws per minute. ISO 10218 safety integration is becoming mandatory for new installations.
- Bowl Feeders:Vibratory bowl tracks mechanically sort and orient fasteners using cold-rolled spring steel fabrication. These systems occupy the largest installed base across Asian consumer electronics plants. Steel alloy input cost sensitivity directly impacts equipment manufacturing economics for this segment.
- Screw Counters:Precision counting modules with programmable torque verification serve medical device assembly lines requiring ISO 13485-certified process documentation.
- Automatic Assembly Systems:Fully integrated feeding-to-driving architectures with cobot compatibility address automotive tier-one supplier consolidation around full-line automation integrators.
Vibration feeders sit at the top of the volume ranking, with automatic assembly systems climbing the fastest as robotics-integrated deployments multiply.
Application:
Cost tier stratification separates aerospace-grade precision requirements from furniture assembly commodity economics, with electronics and automotive occupying the mid-tier premium positioning.
- Electronics Assembly:Smartphone and laptop manufacturing in China's Guangdong province sustains high-volume procurement of linear conveyor systems. Factory electrification programs are systematically replacing pneumatic infrastructure with programmable electric drive architectures.
- Automotive Manufacturing:Tier-one suppliers are recalibrating vendor qualification criteria around multi-source procurement protocols. German and Japanese OEMs with multi-continent production footprints centralize capital expenditure decisions at headquarters.
- Aerospace Production:WEBER Schraubautomaten specializes in this segment through precision engineering for aerospace-grade tolerance requirements.
- Furniture Assembly:Cost-optimized bowl feeder production serves lower-precision woodworking and panel assembly operations.
Electronics assembly commands the highest unit volume, with aerospace production exhibiting the steepest expansion trajectory as implantable medical electronics converge on aerospace tolerance specifications.
End User:
Customer type determines whether procurement flows through plant engineering teams or centralizes at OEM headquarters, reshaping vendor relationship structures.
- OEMs:German and Japanese automotive manufacturers consolidate vendor relationships around full-line automation integrators capable of delivering screw feeding as a subsystem within comprehensive assembly cell contracts.
- Contract Manufacturers:Dense concentrations in China's Guangdong province drive specification of cost-optimized bowl feeders and vibration systems for high-volume consumer electronics.
- Tooling Suppliers:Specialized distributors serve mid-market manufacturers with standardized equipment configurations.
- Industrial Assembly Lines:Discrete manufacturing operations with legacy pneumatic infrastructure face switching cost barriers against electric drive conversion.
Contract manufacturers generate the highest shipment volumes, with OEMs gaining share fastest as direct plant procurement yields to centralized headquarters decisions.
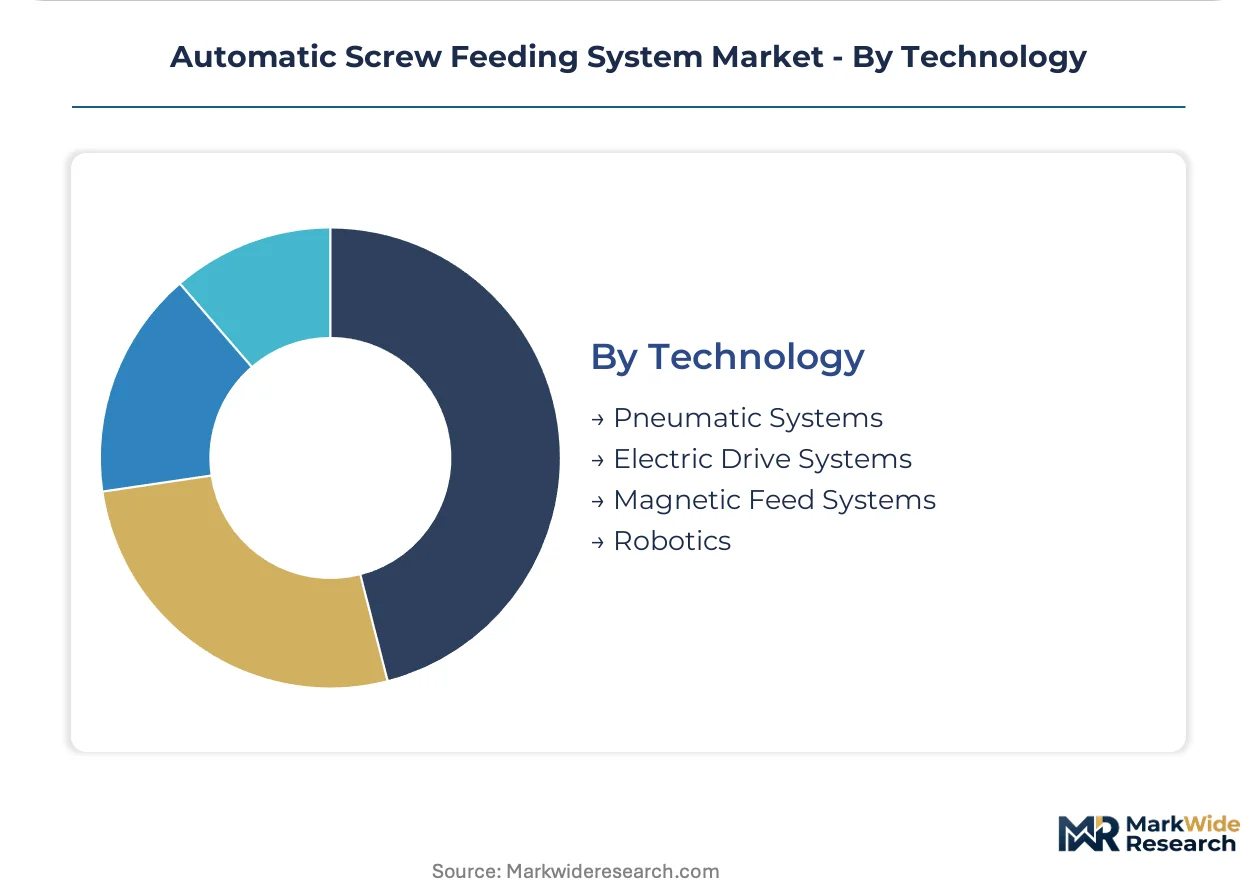
Technology:
Technology maturity curves separate established pneumatic infrastructure from emerging electric and magnetic architectures, with robotics representing the frontier integration layer.
- Pneumatic Systems:Compressed-air infrastructure dominates mature automotive plants. Atlas Copco leverages its pneumatic heritage to anchor European OEM relationships. Legacy installed base creates inertia against efficiency-driven conversion despite electric drive advantages.
- Electric Drive Systems:Programmable torque control and energy efficiency advantages determine sourcing decisions in precision assembly. East Asian electronics hubs are systematically replacing pneumatic infrastructure, compressing equipment replacement cycles.
- Magnetic Feed Systems:Electromagnetic coil-based conveyors with force-feedback sensing serve medical device manufacturers in Switzerland and Germany.
- Robotics:Cobot deployment acceleration drives specification of feeding controllers with embedded safety interlocks and collaborative motion verification per ISO 10218 protocols.
Pneumatic systems retain the largest installed base, with electric drive systems expanding most quickly as factory electrification programs advance across East Asian manufacturing hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province anchors procurement intensity for automatic screw feeding equipment, with factory electrification programs reshaping equipment replacement cycles across East Asian electronics corridors.
China
Guangdong's manufacturing corridor around Shenzhen and Dongguan sustains high-volume procurement of vibratory bowl and linear conveyor systems for smartphone assembly. MIIT equipment safety regulations and GB standards govern domestic certification requirements for automated assembly tools. Contract manufacturers cluster in the Pearl River Delta, where electric drive architectures are systematically displacing legacy pneumatic infrastructure.
Germany
Automotive tier-one suppliers headquartered in Stuttgart and Munich are consolidating vendor relationships around full-line automation integrators. CE marking under the EU Machinery Directive tightens verification protocols for screw feeding equipment sold into European aerospace and automotive sectors. Baden-Württemberg's precision engineering clusters specify aerospace-grade tolerance requirements for medical device and automotive applications.
United States
Medical device manufacturers in Minnesota and California are specifying ISO 13485-certified screw feeding systems for implantable electronics production. FDA quality system regulations intersect with OSHA workplace safety requirements for automated assembly equipment deployment. The Twin Cities corridor hosts concentrated demand for precision counting modules with programmable torque verification.
India
PLI scheme subsidies for smartphone production are attracting contract manufacturers to Gujarat and Tamil Nadu, opening greenfield automation procurement opportunities. BIS certification requirements and DGFT import regulations shape equipment compliance pathways for foreign suppliers. The Sriperumbudur-Oragadam industrial belt near Chennai is emerging as a secondary electronics assembly hub with fresh capital expenditure cycles.
Switzerland
Swissmedic-regulated manufacturers of implantable medical electronics in the Basel-Zurich corridor are specifying linear electromagnetic conveyors with force-feedback sensing. ISO standards for robot safety influence system architecture where collaborative robots perform screwdriving sequences. Precision assembly operations in the Swiss Mittelland demand aerospace-grade tolerances that compress the performance gap between bowl feeder economics and robotic flexibility.
Automatic Screw Feeding System Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue robotics-integrated architectures and cybersecurity-enhanced controller designs. The vendor base stratifies across pneumatic heritage specialists, precision engineering boutiques, and cost-optimized Asian fabricators. Three archetypes dominate: European OEM relationship anchors, Asian contract manufacturing suppliers, and aerospace-grade precision specialists. Competitive moves concentrate on geographic expansion into Indian PLI corridors and backward integration into electromagnetic drive coil production.
Among European heritage producers, Atlas Copco exemplifies the pneumatic-to-electric transition archetype, while WEBER Schraubautomaten occupies a position within precision-engineering specialization. Shenzhen Haihou Industrial Co., Ltd. represents the cost-optimized, high-volume fabrication tier serving Asian contract manufacturers. These three anchors illustrate the geographic and technological segmentation that structures vendor qualification protocols across automotive, electronics, and medical device verticals.
| Leading Market Players |
|---|
| Atlas Copco |
| Shenzhen Haihou Industrial Co., Ltd. |
| WEBER Schraubautomaten |
| Shenzhen Jianfeng Electronic Co., Ltd. |
| Sanmipa |
| Carlson Engineering |
| SHENZHEN CHISU AUTOMATION EQUIPMENT CO., LTD. |
| Shenzhen Ruidexin Automation Co., Ltd. |
| Danikor |
| Others |
Supply Flow & Price Mechanics
Factory electrification programs across East Asian electronics corridors are systematically displacing pneumatic infrastructure with programmable electric drive architectures, simultaneously compressing equipment replacement cycles and concentrating procurement leverage among contract manufacturers in China's Guangdong province. This technology transition reshapes cost economics by elevating precision electromagnetic drive coils and photoelectric verification sensors to critical cost components while consolidating vendor qualification protocols around energy efficiency and programmable torque control specifications.
Pricing Analysis
Input-cost pass-through from cold-rolled spring steel grades and precision electromagnetic components directly shapes equipment manufacturing economics across product tiers. Pricing stratifies across aerospace-grade precision, automotive-certified, and cost-optimized economy tiers, with CE marking and ISO 10218 certification levels commanding substantial premiums. Cost compression in the economy tier intensifies because Shenzhen Haihou Industrial Co., Ltd. and comparable Asian fabricators compete aggressively on bowl feeder production for consumer electronics. Contract manufacturers in Guangdong province exhibit the highest price sensitivity, while German automotive tier-one suppliers prioritize certification compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with East Asian component foundries supplying precision electromagnetic drive coils and photoelectric verification sensors. Equipment manufacturing draws from concentrated sourcing in China, Japan, and South Korea for critical electromechanical components, with cold-rolled spring steel fabrication feeding from German and Chinese metallurgical suppliers. Tariff exposure on precision sensor imports into the European Union and United States elevates landed cost volatility for non-regional vendors. Distribution runs through direct OEM procurement at headquarters level for automotive tier-one suppliers, while contract manufacturers in Asia purchase through regional equipment integrators and specialized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automatic screw feeding system market functions as a stable compounder anchored by irreversible factory automation penetration across electronics and automotive assembly operations. Capital expenditure centralization at OEM headquarters and contract manufacturing clustering in emerging electronics corridors sustain predictable demand visibility.
For Market Incumbents: Cement European OEM relationships by deepening backward integration into electromagnetic drive coil production, insulating Atlas Copco and comparable heritage producers from East Asian component supply volatility. Prioritize simultaneous CE marking, GB standard, and ISO 10218 certification sequencing to defend against emerging robotics-integrated entrants threatening full-line automation integrator consolidation.
For New Entrants and Emerging Players: Launch via equipment-as-a-service subscription models targeting India's PLI scheme corridors in Gujarat and Tamil Nadu, where greenfield automation procurement lacks legacy pneumatic infrastructure switching costs. Penetrate medical device assembly most aggressively, as ISO 13485-certified manufacturers of implantable electronics specify aerospace-grade tolerances with limited incumbent specialization.
For Investors and Strategic Acquirers: Valuations sit cheapest among precision engineering boutiques with aerospace-grade capabilities but limited scale, as tier-one automotive supplier consolidation favors full-line automation integrators. Long-term viability over a multi-year horizon rests on cybersecurity-enhanced controller architectures addressing evolving machinery standard annexes. Watch cobot deployment acceleration in Swiss and German medical device manufacturing as the inflection signal for robotics-integrated system demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electromagnetic Drive Coils | Captive supply of precision coils insulates vendors from East Asian foundry lead time volatility. |
| Cybersecurity-Enhanced Controller Development | Encrypted remote access architectures satisfy evolving EU Machinery Directive annex requirements. |
| India PLI Corridor Geographic Expansion | Gujarat and Tamil Nadu greenfield sites offer automation procurement without legacy infrastructure inertia. |
| ISO 13485 Certification Investment | Medical device assembly tolerances expand addressable margin pools beyond consumer electronics. |
| Cobot Safety Interlock Integration | Embedded ISO 10218 compliance enables specification for collaborative robot screwdriving sequences. |
Methodological Framework
Direct dialogue with plant engineers, OEM procurement directors, contract manufacturing operations managers, and aftermarket service specialists grounded qualitative assessment, validated against secondary sources including MIIT equipment safety filings, EU Machinery Directive certification databases, SEC equipment manufacturer disclosures, and Asian customs trade data. Bottom-up equipment shipment analysis triangulated with top-down capital expenditure modeling across automotive, electronics, and medical device verticals.
Segment-level projections across product type, application, end user, and technology dimensions informed value and volume outputs across the modeling period. CAGRs derived from equipment replacement cycle compression analysis, factory electrification program timelines, and cobot deployment trajectories. Forecast inputs incorporated pneumatic-to-electric technology migration curves and multi-standard certification sequencing delays.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged semiconductor component shortages or abrupt steel alloy price spikes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Machine Automation Controllers Market
Industrial Automation
Industrial Automation Services Market
Industrial Automation
Programmable Logic Controller Market
Industrial Automation
Smart Escalator Market
Industrial Automation
Intralogistics Market
Industrial Automation
Hardware in the Loop Market
Industrial Automation
Global Smart Warehousing Market
Industrial Automation
Parcel Sortation Systems Market
Industrial Automation
Pick and Place Machines Market
Industrial Automation
Europe Factory Automation and Industrial Controls Market
Industrial Automation
Rotary Vector (RV) Reducer Market
Industrial Automation
Global Programmable Logical Controllers Automation Market
Industrial Automation
Human Machine Interface (HMI) Market
Industrial Automation
Smart Elevator Automation System Market
Industrial Automation
Warehouse Automation Equipment Market
Industrial Automation
Smart and Connected Elevators and Elevators Control Systems Market