
 Smart Textile Market | 2026-2036
Smart Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Textile Market Intelligence
Buyer concentration in defense procurement is expanding as military organizations consolidate vendor lists for integrated soldier systems. DuPont de Nemours Inc. leverages its materials science heritage to supply aramid and conductive fiber substrates for ballistic-integrated smart uniforms. Gentherm Incorporated anchors the thermoregulation segment with phase-change and heating-cooling systems embedded in tactical and therapeutic garments. Bekaert competes through its dominance in fine metal fiber production, which enables washable conductive yarns without performance degradation.
Smart textiles are engineered fabrics that integrate electronic components, conductive polymers, or responsive materials directly into fiber structures to enable sensing, actuation, or energy management functions. These materials typically incorporate silver-coated nylon yarns, printed graphene circuits, or encapsulated phase-change microcapsules at thread counts between 150 and 300 denier, serving applications where physiological monitoring or environmental adaptation must occur without removing conventional equipment. Sensor-embedded textiles capture the largest margin pool because medical and defense buyers pay premiums for real-time biometric accuracy, while nanotechnology-based finishes represent the fastest-growing technology segment as antimicrobial and self-cleaning properties penetrate consumer sportswear. Shape memory polymers retain a specialized position in orthopedic and compression therapy markets where programmable fit recovery justifies higher unit costs.
FDA device classification rules govern smart textiles making diagnostic or therapeutic claims in the United States, while REACH and the EU Green Deal restrict hazardous substances in conductive coatings and battery-integrated garments sold across Europe. ISO 10993 biocompatibility standards and IEC 62368-1 safety requirements for wearable electronics create additional compliance layers that filter out undercapitalized entrants. Stakeholders must monitor how emerging battery-free energy harvesting standards reshape hardware architecture decisions before committing to multi-year platform designs.
Market Dynamics
The EU Green Deal and REACH chemical compliance frameworks are forcing material disclosure and hazardous substance elimination across conductive coating supply chains, compressing formulation options for wearable electronics integration.
Growth Catalysts
- Defense procurement consolidation:Military organizations are narrowing vendor lists for integrated soldier systems, creating pull-through demand for ballistic-integrated smart uniforms with embedded biometric monitoring.
- REACH material mandates:European chemical disclosure requirements are accelerating substitution of legacy conductive coatings with bio-based alternatives, opening procurement pathways for compliant suppliers.
- Sports performance embedding:Athletic programs are weaving biometric tracking into team apparel at scale, generating volume demand for washable sensor-integrated fabrics.
Market Restraints
- Silver price volatility:Conductive yarn production relies on silver-coated nylon, exposing margins to precious metal commodity swings.
- German supplier concentration:Technical textile clusters around Stuttgart and Munich control critical substrate supply for automotive and industrial wearable developers.
- Battery integration limits:Washable power storage remains technically constrained, capping functionality in consumer-grade garments.
Strategic Opportunities
- Battery-free energy harvesting:Emerging standards for kinetic and thermal energy capture are reshaping hardware architecture decisions, eliminating power cell dependencies.
- Orthopedic therapy expansion:Shape memory polymers in compression garments offer programmable fit recovery, commanding premium positioning in rehabilitation markets.
- India manufacturing incentives:PLI scheme benefits for technical textiles are attracting conductive fiber production investment away from European cost bases.
Industry Challenges
- ISO 10993 biocompatibility timelines:Medical-grade smart textiles face extended certification cycles for skin-contact sensors, delaying revenue recognition.
- Conductive yarn integration complexity:Fine metal fiber embedding requires specialized knitting equipment, creating capex barriers for traditional textile converters.
- Cross-standard harmonization gaps:Divergent IEC 62368-1 safety requirements and FDA device classification rules force dual-track development for transatlantic products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Textile Market |
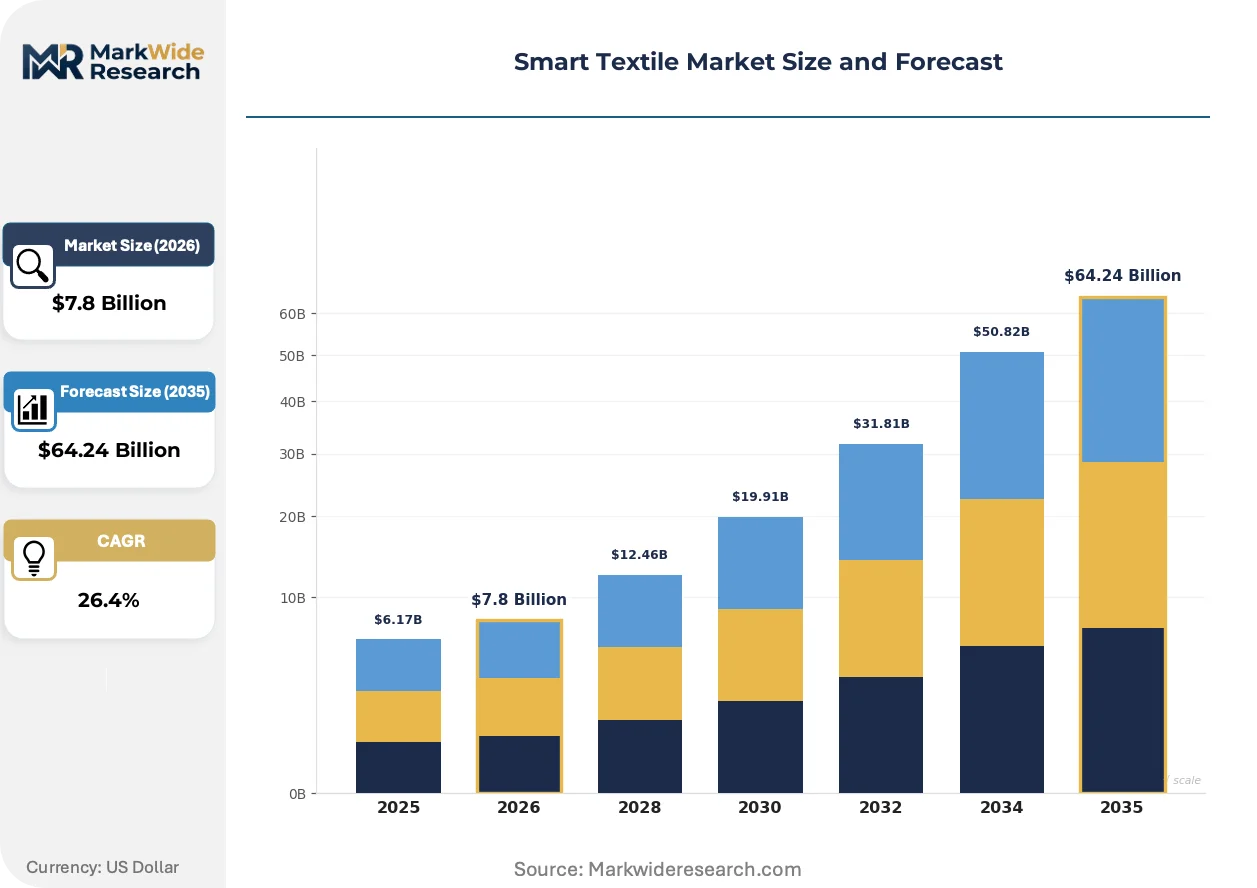
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $64.24 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Fabrics, Sensor-Embedded Textiles, Shape Memory Polymers, Phase Change Materials Technology: Wearable Electronics, Electrochromic Textiles, Thermoelectric Devices, Nanotechnology Application: Sports Performance Monitoring, Military Wear, Personal Protective Equipment, Fashion & Lifestyle End User: Sportswear Brands, Defense Manufacturers, Occupational Safety Firms, Luxury Apparel Companies |
| Companies Covered | AiQ Smart Clothing Inc., Gentherm Incorporated, DuPont de Nemours Inc., Sensoria Inc., Textronics Inc., Alphabet Inc., Interactive Wear AG, Bekaert, Adidas AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Textile Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory chemistry restrictions are converging to reshape how electronic functionality embeds into textile structures without compromising wearability or wash durability.
Printed graphene circuits are expanding into medical monitoring applications where real-time biometric accuracy commands premium pricing. Hospitals and remote care providers are adopting graphene-enabled garments for continuous patient surveillance. This expansion is compressing demand for rigid wearable devices that require removal for charging or cleaning.
REACH substance restrictions are eliminating perfluorinated compounds from water-repellent conductive coatings used in outdoor smart apparel. Formulators are pivoting to silicone-based alternatives that meet ECHA disclosure thresholds. German industrial laundries serving healthcare and hospitality sectors are now rejecting incoming textiles that lack compliant coating certifications.
Defense and medical buyers are consolidating vendor relationships around full-stack suppliers capable of delivering finished garments rather than component substrates. This pattern displaces pure-play conductive fiber merchants who lack garment assembly capabilities. The shift is most pronounced in US military procurement and German automotive supplier programs.
Smart Textile Market Segmentation
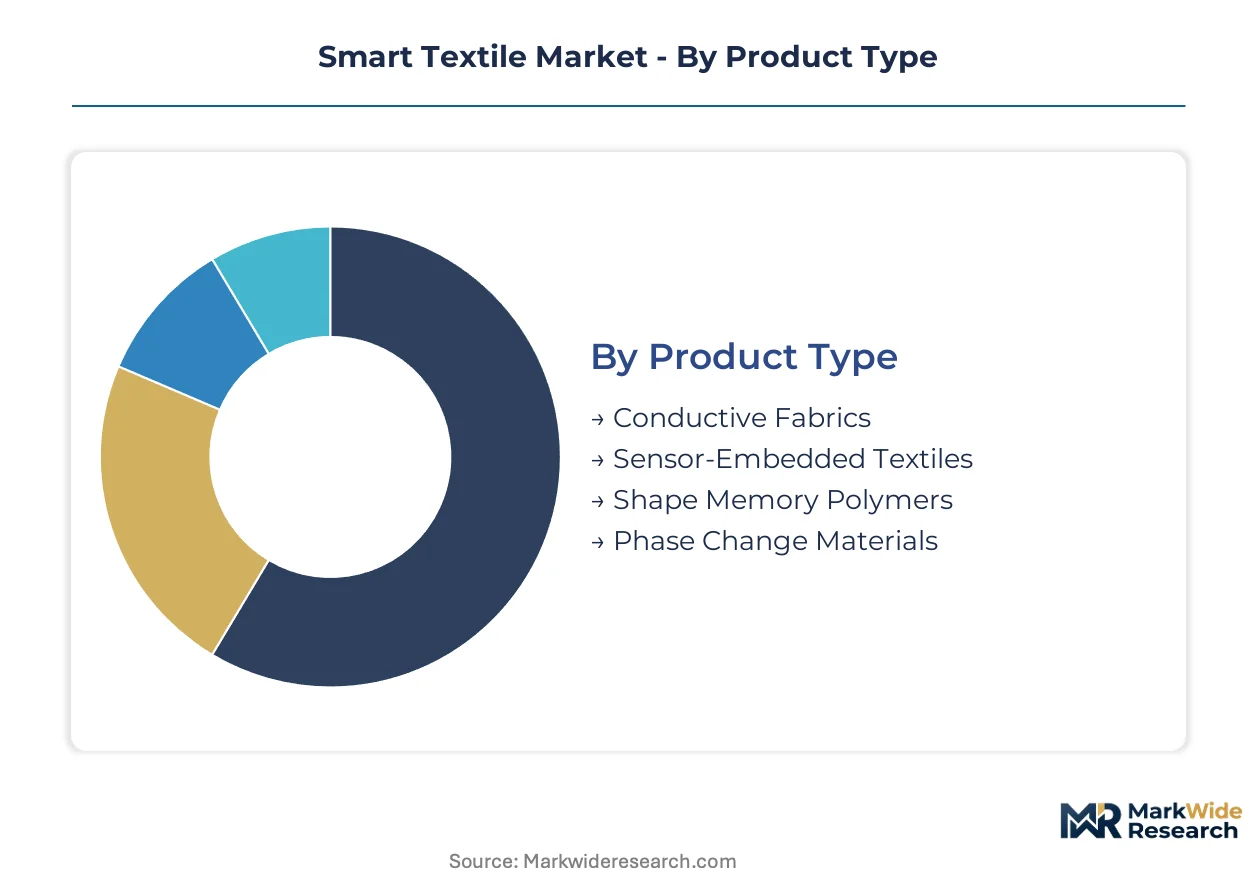
Smart textile segmentation reveals how functional requirements split procurement budgets between high-volume athletic wear and premium-priced medical and defense systems. Technical specifications around washability, conductivity, and biocompatibility create distinct supply chain configurations for each segment cluster.
Product Type:
Volume production concentrates in conductive fabrics for athletic and industrial applications, while premium positioning belongs to sensor-embedded systems for medical and military buyers.
- Sensor-Embedded Textiles:These fabrics integrate printed graphene circuits and silver-coated nylon yarns at 150-300 denier thread counts to capture real-time biometric data. Defense procurement programs in the United States and Germany are consolidating vendor lists around suppliers capable of delivering finished ballistic-integrated uniforms with embedded monitoring, not component substrates. FDA device classification rules and ISO 10993 biocompatibility standards govern medical applications, extending certification timelines but justifying premium unit economics.
- Conductive Fabrics:Silver-coated nylon and fine metal fiber substrates enable washable conductive yarns without performance degradation. Bekaert's dominance in fine metal fiber production shapes supply availability for automotive and industrial wearable developers clustered around Stuttgart and Munich, though silver price volatility compresses margins for downstream converters lacking backward integration into fiber production.
- Shape Memory Polymers:Programmable fit recovery in compression garments commands premium positioning in orthopedic rehabilitation markets.
- Phase Change Materials:Encapsulated microcapsules enable thermoregulation in tactical and therapeutic garments, with Gentherm Incorporated anchoring this segment.
Mature deployment sits with conductive fabrics. Newer deployment is concentrated in sensor-embedded textiles.
Technology:
Application requirements determine whether buyers prioritize energy autonomy through harvesting systems or responsive functionality through chromic and thermoelectric mechanisms.
- Wearable Electronics:Battery integration remains the primary technical constraint for consumer-grade garments, though emerging kinetic and thermal energy harvesting standards are reshaping hardware architecture decisions. Defense and medical buyers are consolidating procurement around full-stack suppliers capable of delivering finished garments rather than component substrates, displacing pure-play electronics merchants.
- Nanotechnology:Antimicrobial and self-cleaning finishes are gaining share fastest in consumer sportswear as REACH substance restrictions eliminate perfluorinated compounds from water-repellent conductive coatings. Formulators are pivoting to silicone-based alternatives that meet ECHA disclosure thresholds, with German industrial laundries now rejecting textiles lacking compliant coating certifications.
- Electrochromic Textiles:Color-changing functionality serves fashion and military camouflage applications where environmental adaptation must occur without equipment removal.
- Thermoelectric Devices:Heating-cooling systems embedded in tactical and therapeutic garments anchor thermoregulation functionality for extreme environment operations.
Established integration patterns dominate wearable electronics. Steepest expansion trajectory belongs to nanotechnology-based finishes.
Application:
Procurement concentration varies sharply between institutional buyers with consolidated vendor lists and fragmented consumer markets with dispersed decision-making.
- Sports Performance Monitoring:Athletic programs are weaving biometric tracking into team apparel at scale, generating volume demand for washable sensor-integrated fabrics. The EU Green Deal and REACH compliance frameworks are tightening material disclosure requirements for wearable electronics integration, accelerating substitution of legacy conductive coatings with bio-based alternatives.
- Military Wear:Integrated soldier systems with embedded biometric monitoring are pulling significant volume as defense organizations narrow vendor lists. DuPont de Nemours Inc. leverages its materials science heritage to supply aramid and conductive fiber substrates for ballistic-integrated smart uniforms.
- Personal Protective Equipment:Occupational safety firms require ISO 10993 biocompatibility and IEC 62368-1 safety compliance for skin-contact sensors in industrial environments.
- Fashion & Lifestyle:Luxury apparel companies prioritize aesthetic integration of responsive materials over functional performance metrics.
Volume concentration sits with sports performance monitoring. Premium margin capture is concentrated in military wear.
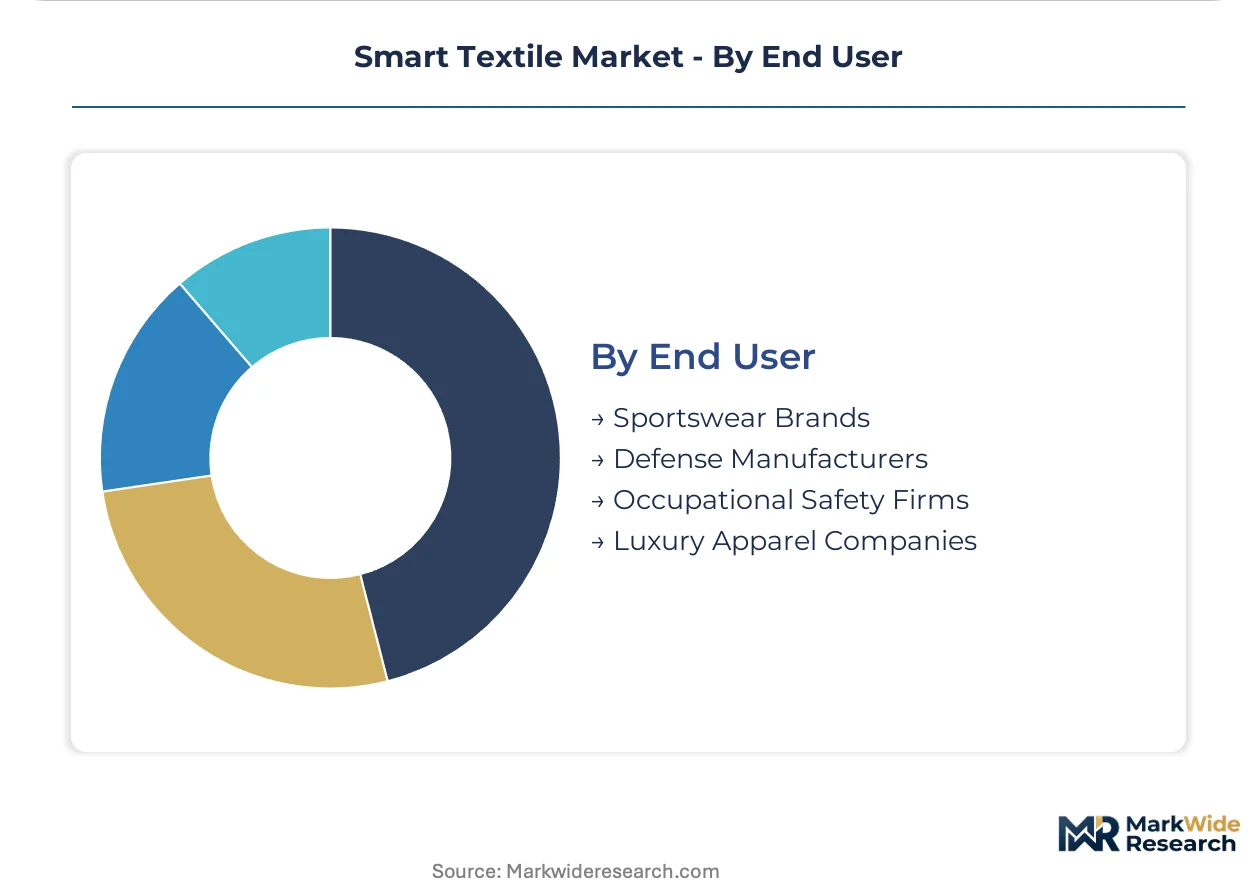
End User:
Supply chain relationships diverge between buyers seeking component substrates and those demanding finished garment delivery.
- Defense Manufacturers:These buyers are consolidating vendor relationships around full-stack suppliers capable of delivering finished garments rather than component substrates. This pattern is most pronounced in US military procurement programs, where integrated soldier systems require ballistic protection combined with biometric monitoring.
- Sportswear Brands:Athletic programs are embedding biometric tracking into team apparel at scale, generating volume demand for washable fabrics. India's PLI scheme benefits for technical textiles are attracting conductive fiber production investment away from European cost bases.
- Occupational Safety Firms:These buyers require compliance with ISO 10993 biocompatibility standards and IEC 62368-1 safety requirements for wearable electronics.
- Luxury Apparel Companies:Aesthetic integration of responsive materials drives procurement for fashion and lifestyle applications.
Established procurement patterns sit with defense manufacturers. Emerging volume concentration is shifting toward sportswear brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silver deposits in Peru and conductive fiber production clusters in Germany anchor raw material supply for the smart textile value chain. Regional demand patterns diverge sharply between defense procurement systems in North America and sports manufacturing ecosystems in Asia-Pacific.
United States
Defense procurement consolidation drives demand for ballistic-integrated smart uniforms with embedded biometric monitoring. FDA device classification rules govern diagnostic claims for medical-grade textiles, extending certification timelines. Boston and Austin host concentrated technical textile R&D operations serving military and healthcare developers.
Germany
Automotive and industrial wearable developers cluster around Stuttgart and Munich technical textile hubs. REACH chemical disclosure requirements and EU Green Deal mandates accelerate substitution of legacy conductive coatings with bio-based alternatives. ECHA compliance certification has become mandatory for suppliers serving German industrial laundries.
China
Dual carbon goals and MIIT industrial standards are reshaping energy harvesting textile development priorities. GB standards for wearable electronics safety create parallel compliance tracks for domestic and export markets. Yangtze River Delta manufacturing zones concentrate conductive yarn finishing capacity for global sportswear brands.
India
PLI scheme incentives for technical textiles attract conductive fiber production investment away from European cost bases. CDSCO medical device regulations govern diagnostic smart textile claims in domestic healthcare markets. Gujarat and Tamil Nadu textile belts are integrating sensor-embedding capabilities into existing apparel manufacturing infrastructure.
Japan
METI funding programs support next-generation fiber development for aging-population healthcare monitoring. PMDA oversight extends to therapeutic claims for smart textiles in rehabilitation applications. Kansai region textile engineering clusters collaborate with Osaka-based electronics manufacturers on wash-integrated sensor systems.
Smart Textile Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue nanotechnology-based finishes and battery-free energy harvesting architectures. The market exhibits moderate consolidation around full-stack garment suppliers capable of delivering finished systems rather than component substrates. Three archetypes dominate: materials science heritage players supplying aramid and conductive fiber substrates; thermoregulation specialists embedding phase-change systems; and fine metal fiber producers enabling washable conductive yarns. Competitive moves center on strategic partnerships for compliant coating formulations and geographic expansion toward India PLI scheme jurisdictions.
Within the materials science tier, DuPont de Nemours Inc. exemplifies heritage positioning through its aramid and conductive fiber substrate supply relationships. Gentherm Incorporated anchors thermoregulation specialization with phase-change and heating-cooling system integration. Bekaert occupies a distinctive position in fine metal fiber production, representing the washable conductive yarn segment where metal fiber embedding enables performance retention through industrial laundering cycles.
| Leading Market Players |
|---|
| AiQ Smart Clothing Inc. |
| Gentherm Incorporated |
| DuPont de Nemours Inc. |
| Sensoria Inc. |
| Textronics Inc. |
| Alphabet Inc. |
| Interactive Wear AG |
| Bekaert |
| Adidas AG |
| Others |
Cost & Logistics Intelligence
Defense procurement consolidation around integrated soldier systems concentrates buyer power among military organizations in the United States and Germany, forcing tiered pricing stratification across premium medical-grade textiles, standard industrial conductive fabrics, and economy athletic wear tiers.
Pricing Analysis
Volume production in sports performance monitoring generates thin margins at scale, while sensor-embedded medical and defense textiles capture premium positioning through ISO 10993 certification tiers and FDA device classification requirements. Price differentiation hinges on biocompatibility grade and wash-cycle durability guarantees, with silver-coated nylon yarn costs amplifying volatility. Cost compression in consumer-grade segments intensifies as India's PLI scheme attracts production investment away from European cost bases. Athletic programs show highest price sensitivity; military buyers prioritize performance metrics over unit economics.
Supply Chain Analysis
ISO 10993 and IEC 62368-1 qualification requirements gate supplier entry, filtering out undercapitalized converters lacking specialized knitting equipment for fine metal fiber embedding. Raw material supply draws from Peruvian silver deposits, German technical textile clusters around Stuttgart and Munich, and Chinese Yangtze River Delta finishing capacity. Critical dependencies include silver-coated nylon yarns, printed graphene circuits, and encapsulated phase-change microcapsules. Single-source vulnerability concentrates in Bekaert's fine metal fiber production. Distribution runs through full-stack garment suppliers capable of delivering finished systems rather than component substrates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as REACH chemical disclosure requirements and FDA device classification rules raise capital barriers, eliminating pure-play conductive fiber merchants lacking garment assembly capabilities or compliant coating formulations.
For Market Incumbents: Cement defensive positioning through backward integration into fine metal fiber production and captive aramid substrate supply, countering margin pressure from silver commodity volatility. Deepen certification investment in ISO 10993 biocompatibility and ECHA-compliant silicone-based coating alternatives to maintain procurement access to German industrial laundries and US military vendor lists.
For New Entrants and Emerging Players: Battery-free energy harvesting architectures offer the most penetrable technology wedge, targeting orthopedic rehabilitation markets where shape memory polymer compression garments command premium pricing with lower regulatory burden than diagnostic claims. Pursue geographic entry through India's PLI scheme jurisdictions, partnering with Gujarat and Tamil Nadu textile belts to embed sensor capabilities into existing apparel infrastructure.
For Investors and Strategic Acquirers: The window for entry favors full-stack garment suppliers with demonstrated ECHA compliance and military procurement relationships over pure-play substrate merchants. Acquisition targets should demonstrate integrated soldier system delivery capability and REACH-certified coating portfolios. Watch battery-free energy harvesting standard finalization as inflection indicator for hardware architecture obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Production | Captive silver-coated nylon supply insulates margins from precious metal commodity swings. |
| REACH-Compliant Coating Reformulation | Silicone-based alternatives unlock procurement pathways through German industrial laundries. |
| Full-Stack Garment Capability Buildout | Defense procurement consolidation favors finished system suppliers over component merchants. |
| Battery-Free Energy Harvesting R&D | Kinetic and thermal capture standards reshape hardware architecture decisions. |
| India PLI Scheme Manufacturing Footprint | Tamil Nadu and Gujarat textile belts attract conductive fiber investment from European cost bases. |
Research Approach
Multi-period observation of defense procurement consolidation patterns, REACH compliance certification timelines, and silver price volatility anchored the trend analysis, supplemented by interviews with technical textile R&D directors, military procurement officers, biomedical engineers at hospital systems, conductive fiber plant managers, and athletic program equipment directors. Secondary validation drew from ECHA substance restriction databases, FDA device classification filings, SEC 10-K disclosures from materials science heritage players, German industrial laundry certification records, and India PLI scheme beneficiary lists. Bottom-up segment sizing triangulated against top-down market boundary analysis.
Segment-weighting across product type, technology, application, and end-user dimensions shaped the analytical framework, with sensor-embedded textiles, nanotechnology finishes, and battery-free energy harvesting systems receiving distinct trajectory modeling. CAGRs derived from regression against historical volume patterns and projected procurement cycle timing. Industry-specific forecast inputs included defense budget authorization trends for integrated soldier systems and ECHA substance restriction implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under silver price spike scenarios, REACH restriction acceleration timelines, or breakthrough battery-free energy harvesting standard adoption. Forecasts reflect documented assumptions regarding procurement consolidation velocity and coating formulation substitution rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Innovations
Waterproof Socks Market
Textile Innovations
Global Textile Market
Textile Innovations
Textile Felt Market
Textile Innovations
Textile Acoustic Panel Market
Textile Innovations
Handloom Products Market
Textile Innovations
Europe Digital Clothing Market
Textile Innovations
Smart and Interactive Textiles Market
Textile Innovations
US Digital Printed Textile Market
Textile Innovations
Fiber Patch System Market
Textile Innovations
GCC Textile Market
Textile Innovations
Quilt Market
Textile Innovations
Canvas Bags Market
Textile Innovations
Smart Fabrics in Fashion and Entertainment Market
Textile Innovations
Asia-Pacific Textile Market
Textile Innovations
Global Smart Fabrics Market
Textile Innovations
Clothes Fastener Market