
 Handloom Products Market | 2026-2036
Handloom Products Market Size, Share, and Industry Trends Forecast 2026-2036
Handloom Products Market Analytics
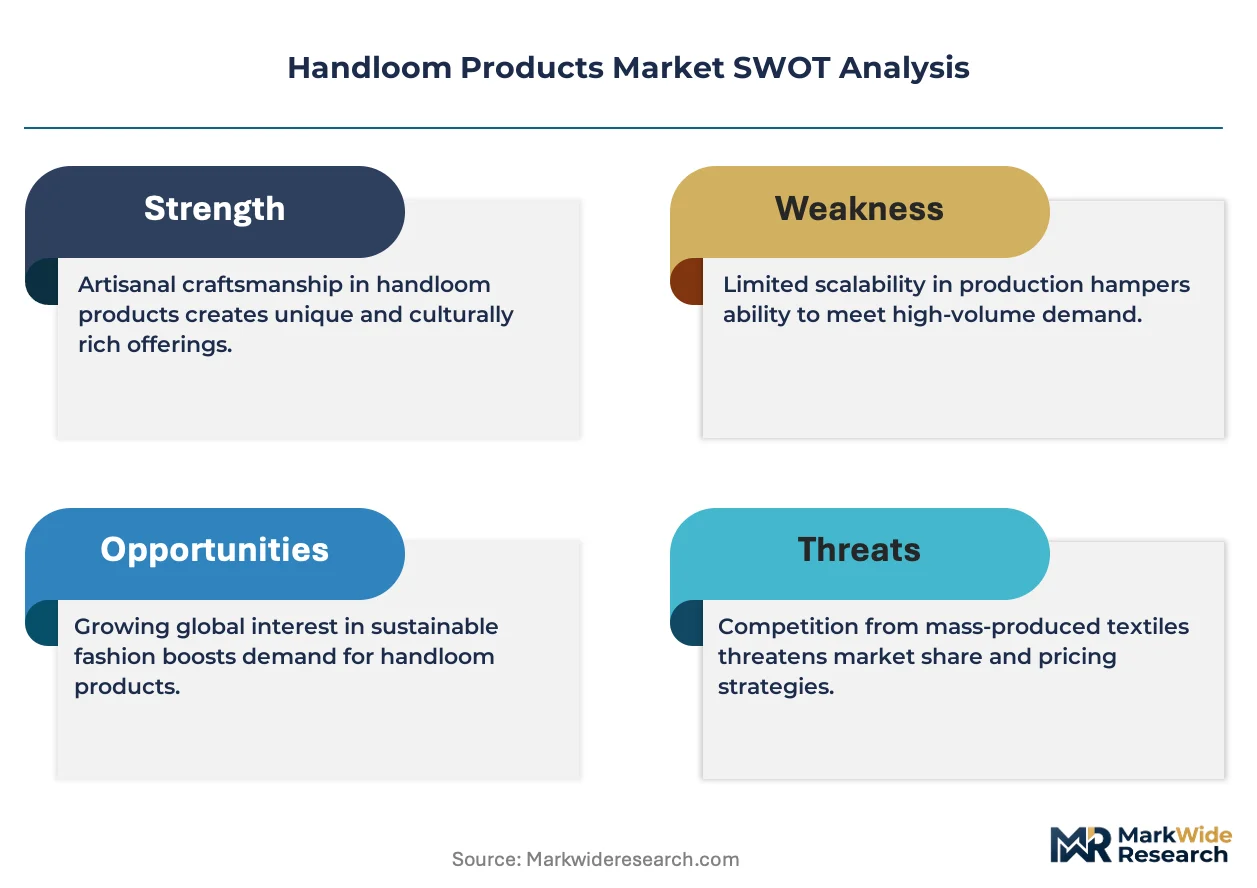
Boutique hospitality procurement is realigning toward artisan-certified handloom textiles as hotels replace mass-produced décor with region-specific woven narratives. Fabindia leverages its decades-old weaver network to sustain exclusive supply agreements across Rajasthan and Gujarat clusters. GoCoop anchors its platform on direct artisan-to-buyer logistics, competing with aggregator models through transparent origin tracing. Jaypore differentiates via curated design collaborations that position handloom apparel as contemporary wardrobe staples rather than ceremonial artifacts.
Handloom products denote textiles and allied goods manufactured on manually operated looms without automated mechanization, typically employing natural fibers such as cotton, silk, or wool through warp-and-weft interlacing techniques that yield distinctive irregularities valued as authenticity markers. These products serve both functional and ceremonial purposes across residential furnishing, personal apparel, and cultural artifact segments. Cotton textiles dominate volume throughput across local markets and export channels, while silk apparel commands concentrated margin pools in boutique and online retail segments. Home décor applications in jute and wool are maturing within commercial hospitality procurement, though residential usage retains the broadest geographic spread.
India's BIS certification framework for handloom labeling, combined with the GeM portal procurement mandate and Khadi Gramodyog Board quality standards, shapes market access by creating tiered credibility signals that institutional buyers require before contract award. The EU's REACH chemical compliance and the US FTC textile labeling rules further constrain export-oriented weaver cooperatives that lack testing infrastructure. Stakeholders must monitor how digital traceability mandates from multiple regulators reshape the cost structure of small-batch artisan verification.
Market Dynamics
Digital traceability infrastructure is compressing verification timelines for artisan cooperatives, forcing weaver networks to adopt blockchain-based origin documentation that institutional buyers now mandate before contract execution.
Growth Catalysts
- GeM Portal Mandate:India's government e-marketplace procurement directive channels institutional demand toward certified weaver cooperatives, creating guaranteed offtake volumes for registered artisans.
- REACH Compliance:EU chemical safety standards for textile imports are elevating certified natural fiber products above synthetic alternatives in European boutique retail channels.
- Boutique Hospitality:Design-forward hotel chains are replacing mass-produced décor with region-specific woven narratives that command premium positioning in guest experience marketing.
Market Restraints
- Input Cost Volatility:Natural silk and organic cotton prices fluctuate with monsoon-dependent harvests across Maharashtra and Karnataka growing belts.
- Supply Concentration:Master weaver networks in Varanasi and Kanchipuram control dyeing expertise that smaller cooperatives cannot replicate without multi-year apprenticeship investments.
- Substitution Threat:Power-loom textiles with artificial aging treatments capture price-sensitive segments that cannot distinguish authentic irregularity from manufactured distress.
Strategic Opportunities
- Underpenetrated Geographies:Northeast Indian states including Assam and Manipur harbor undercommercialized silk traditions that lack organized market linkages.
- Technology Convergence:Integration of near-field communication chips into textile labels enables smartphone-based provenance verification for direct-to-consumer channels.
- PLI Scheme Tailwinds:India's production-linked incentive framework for textile manufacturing offers capital subsidies for handloom modernization that reduces lead times.
Industry Challenges
- Skill Transmission Gap:Master weavers in their sixties report declining apprentice enrollment as younger workers migrate to urban garment assembly jobs.
- Certification Timeline Compression:BIS handloom labeling requires six-to-nine-month documentation cycles that miss seasonal procurement windows for export buyers.
- Supply Chain Reconfiguration:Direct artisan-to-brand logistics bypass traditional aggregator margins but impose inventory risk on weavers unaccustomed to demand forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handloom Products Market |
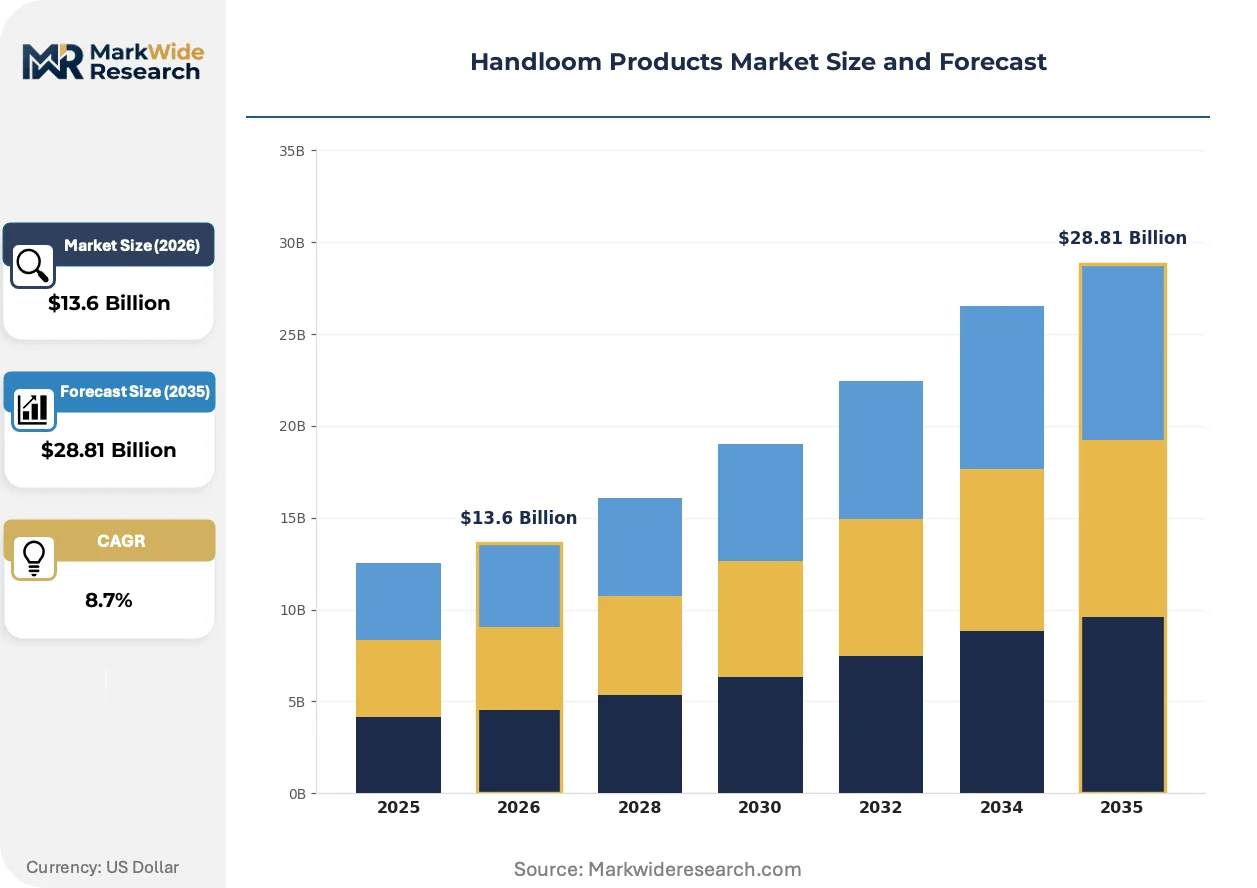
| Market Size in 2026 | $13.6 Billion |
| Market Size in 2035 | $28.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textiles, Home Decor, Apparel, Accessories Material: Cotton, Silk, Wool, Jute Usage: Residential, Commercial, Traditional Events, Crafts Distribution Channel: Online Retail, Local Markets, Exports, Boutiques |
| Companies Covered | Fabindia, Khadi Gramodyog, Dastkar, GoCoop, Maheshwari Handloom Works, Bharat Handloom, Anokhi, Jaypore, Dastkari Haat Samiti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handloom Products Market Evolving Landscape
Three intersecting forces are restructuring how handloom products reach end buyers: embedded verification technology, tightening chemical compliance, and procurement model evolution that disintermediates traditional trading layers.
Blockchain-based origin documentation is modularizing supply chain transparency into discrete verification modules that cooperatives can adopt incrementally. Boutique hospitality procurement teams are piloting these systems to satisfy ESG audit requirements without overhauling entire sourcing operations. The technology is modularizing what was previously an all-or-nothing certification burden into stackable compliance components.
India's BIS handloom labeling framework is expanding mandatory testing for azo dyes and heavy metal residues, mirroring EU REACH standards that already block non-compliant shipments at European ports. Weaver cooperatives in Tamil Nadu and Andhra Pradesh are consolidating testing costs through regional laboratory partnerships. Export-oriented clusters face the steepest compliance investments as dual-jurisdiction requirements multiply.
Direct artisan relationships are displacing aggregator-dependent procurement for mid-size apparel brands seeking margin recovery and story authenticity. Digital platforms enable video documentation of specific weavers at work, which marketing teams deploy as consumer-facing content. This shift concentrates most visibly in online-first apparel retailers targeting metropolitan Indian consumers with disposable income and heritage-conscious purchasing preferences.
Handloom Products Market Segmentation
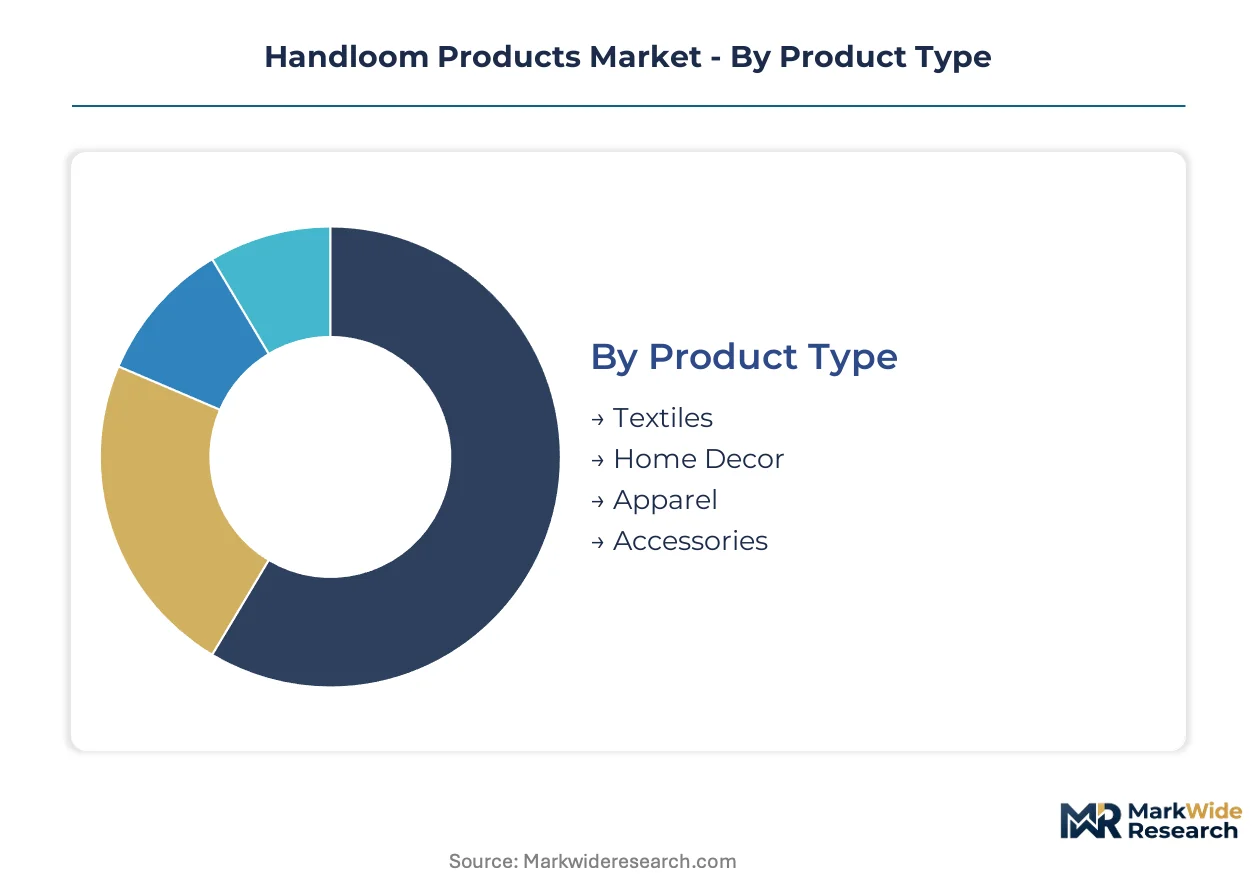
Handloom market segmentation reveals how artisan production maps onto distinct value chains. Material type determines certification requirements and export eligibility. Distribution channel selection shapes margin capture and brand positioning for weaver cooperatives.
Product Type:
Standalone ceremonial pieces command premium positioning, while embedded furnishing textiles integrate into broader interior design specifications.
- Textiles:Yardage and fabric rolls woven for downstream conversion into finished goods. Varanasi silk brocades supply bridalwear manufacturers in Delhi and Mumbai with certified heritage-grade material.
- Apparel:Finished garments including sarees, shawls, and contemporary separates. Direct-to-consumer platforms in Bangalore and Hyderabad are driving demand for design-forward handloom wardrobe staples with embedded NFC verification tags.
- Home Decor:Cushion covers, table runners, and wall hangings. Boutique hospitality procurement in Rajasthan and Kerala sources region-specific woven narratives for guest experience differentiation.
- Accessories:Scarves, stoles, and bags requiring minimal loom width. Compact production suits home-based weavers in Assam and Manipur with limited workspace.
Textiles lead volumes today; apparel is gaining share fastest.
Material:
Cost tiers stratify sharply between commodity natural fibers and certified heritage grades requiring multi-year cultivation cycles.
- Cotton:Short-staple and long-staple varieties spun into khadi and muslin traditions. Maharashtra and Gujarat growing belts supply organic-certified fiber to GeM-registered cooperatives meeting government procurement mandates.
- Silk:Mulberry and tasar varieties with distinctive sheen and drape characteristics. Kanchipuram master weavers control dyeing expertise that smaller cooperatives cannot replicate without apprenticeship investments spanning multiple years.
- Wool:Himalayan and Deccan plateau varieties with coarse-to-fine gradations. Kullu and Kinnaul shawl traditions anchor winter apparel demand in northern hill stations.
- Jute:Bast fiber woven into durable furnishing textiles and ceremonial floor coverings. West Bengal processing clusters face REACH compliance barriers for European export channels.
Cotton dominates volume throughput; silk commands concentrated margin pools.
Usage:
Application context determines specification rigor, with commercial procurement imposing stricter documentation than residential or ceremonial use.
- Residential:Daily-use furnishings and personal apparel without institutional certification requirements. Broadest geographic spread across tier-2 and tier-3 Indian cities.
- Commercial:Hospitality, corporate gifting, and office furnishing with ESG audit documentation. Boutique hotel chains in Jaipur and Udaipur replace mass-produced décor with artisan-certified textiles.
- Traditional Events:Bridal trousseaus, temple offerings, and festival-specific garments. Varanasi and Maheshwar weaving belts concentrate ceremonial demand with rigid seasonal procurement windows.
- Crafts:Raw material supply for downstream artisan processing into embroidered or embellished finished goods. Northeast Indian states including Manipur harbor undercommercialized traditions lacking organized market linkages.
Residential usage retains broadest spread; commercial procurement is expanding most quickly.
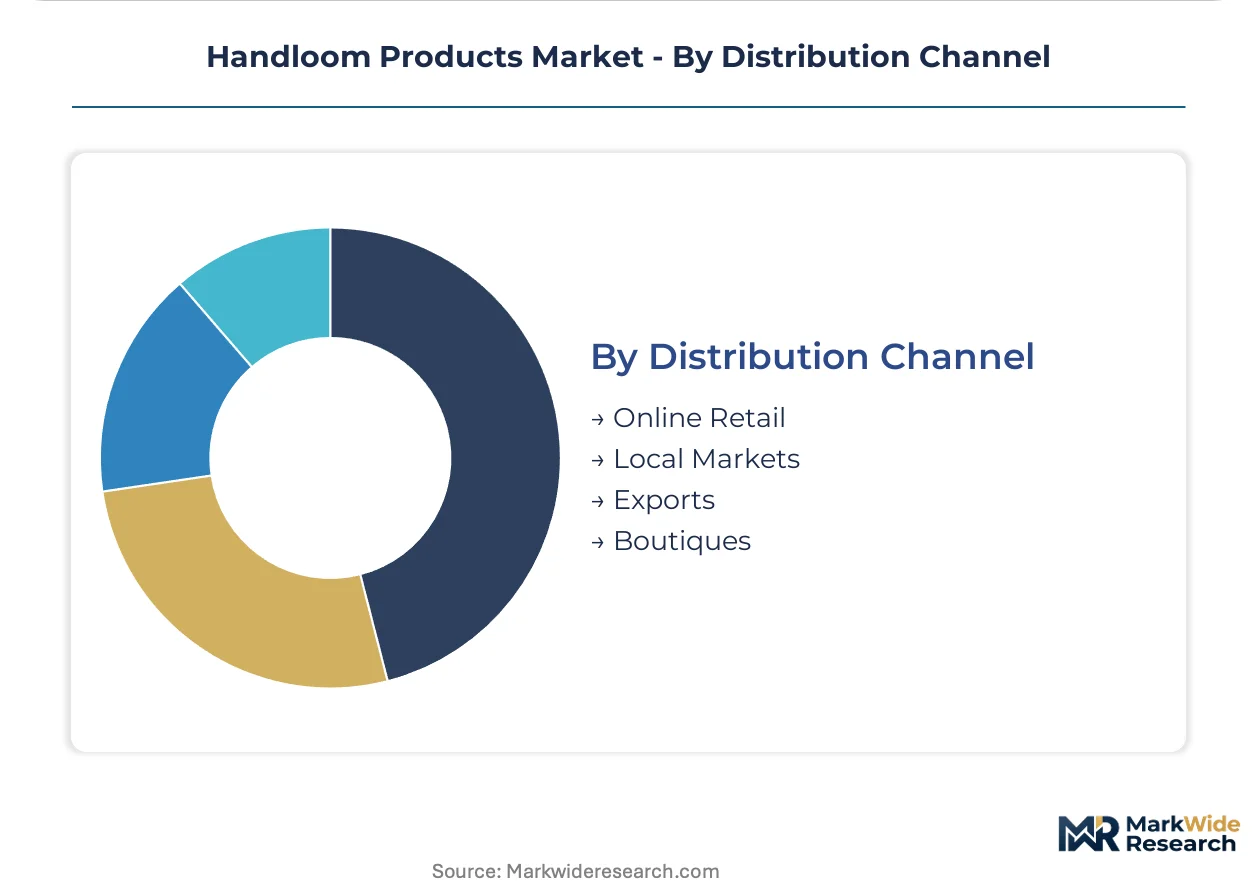
Distribution Channel:
Channel selection determines margin capture and inventory risk allocation between weavers and intermediaries.
- Online Retail:Platform-mediated sales with video documentation and smartphone-based provenance verification. Metropolitan Indian consumers with disposable income drive demand for heritage-conscious purchasing.
- Local Markets:Physical bazaars and haats with immediate cash settlement and minimal documentation. Price-sensitive segments in smaller towns cannot distinguish authentic irregularity from power-loom substitutes with artificial aging.
- Exports:EU and North American channels requiring REACH and FTC compliance. Tamil Nadu and Andhra Pradesh cooperatives consolidate testing costs through regional laboratory partnerships.
- Boutiques:Curated retail with design collaboration and story-based merchandising. Margin recovery for mid-size apparel brands seeking authenticity positioning.
Local markets lead volumes today; online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as weaver cooperatives migrate toward jurisdictions with streamlined certification timelines and consolidated testing infrastructure. Cost-of-compliance gaps between REACH-aligned European markets and domestic Indian channels are diverting investment toward BIS-registered clusters with dual-export capability.
India
GeM portal procurement mandates channel institutional demand toward certified weaver cooperatives in Varanasi, Maheshwar, and Kanchipuram. BIS handloom labeling requirements and Khadi Gramodyog Board quality standards create tiered credibility signals that registered artisans leverage for guaranteed offtake volumes. Master weaver networks in Tamil Nadu and Andhra Pradesh control dyeing expertise through consolidated regional laboratory partnerships.
Bangladesh
Dhaka-based trading houses are capturing spillover demand from Indian export quotas through simplified origin documentation for European boutique retail channels. The country's national textile regulator maintains streamlined chemical compliance pathways that reduce REACH alignment costs for natural fiber cooperatives. Jamdani weaving traditions in Narayanganj supply certified heritage-grade yardage to bridalwear manufacturers in Delhi and Mumbai.
Vietnam
Silk-reeling cooperatives in Lam Dong province are expanding mulberry cultivation to capture premium positioning in Japanese and South Korean apparel markets. The Ministry of Industry and Trade's craft village certification program channels state subsidies toward loom modernization that reduces lead times for export buyers. Hoi An's heritage textile quarter anchors tourism-integrated retail with direct-artisan merchandising models.
Thailand
Mudmee ikat traditions in Isaan provinces supply boutique hospitality procurement across Southeast Asian resort corridors with region-specific woven narratives. The Department of Industrial Promotion's One Tambon One Product framework standardizes quality grading for institutional buyers seeking ESG-audited supply chains. Chiang Mai's Bo Sang-San Kamphaeng cluster concentrates dyeing expertise for silk and cotton furnishing textiles.
Indonesia
Ikat weaving cooperatives in Sumba and Flores are leveraging digital traceability platforms to bypass traditional aggregator margins for direct-to-brand relationships with European ethical fashion labels. The Ministry of Cooperatives and Small and Medium Enterprises provides capital access for loom modernization that meets dual-jurisdiction chemical compliance requirements. Toraja highland clusters in Sulawesi supply ceremonial textile demand with rigid seasonal procurement windows.
Handloom Products Market Competitive Landscape
Direct artisan-to-brand relationship-building dominates the current landscape as procurement teams disintermediate traditional trading layers. The vendor base stratifies across three tiers: heritage-anchored cooperatives with multi-decade weaver networks, platform-mediated aggregators with transparent origin tracing, and curated retail specialists with design-forward positioning. Weaver-owned entities, technology-enabled marketplaces, and boutique merchandisers represent the primary strategic archetypes. Competitive moves concentrate on digital traceability infrastructure deployment and exclusive supply agreement negotiation.
Within the heritage-anchored cooperative tier, Fabindia and Khadi Gramodyog occupy positions that exemplify divergent scale approaches. Fabindia leverages decades-old weaver networks across Rajasthan and Gujarat clusters to sustain exclusive supply agreements. Khadi Gramodyog represents the institutional procurement vector through government-mandated sourcing channels. GoCoop anchors the platform-mediated segment with direct artisan-to-buyer logistics competing against aggregator models through transparent origin tracing.
| Leading Market Players |
|---|
| Fabindia |
| Khadi Gramodyog |
| Dastkar |
| GoCoop |
| Maheshwari Handloom Works |
| Bharat Handloom |
| Anokhi |
| Jaypore |
| Dastkari Haat Samiti |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between BIS-labeled heritage tiers and unmarked commodity yardage manifests in both pricing power and supply chain configuration across Indian weaving clusters. Premium silk brocades from Kanchipuram master weavers command sustained margin pools through dyeing expertise that smaller cooperatives cannot replicate, while GeM-registered cotton khadi suppliers compete on volume throughput with compressed margins.
Pricing Analysis
Retailer markup layers dominate handloom pricing structures, with boutique channels capturing 40-60 percent margins above weaver gate prices while direct-to-consumer platforms compress this spread. Price differentiation rests on BIS certification tier and volume scale, with institutional procurement mandating labeled grades that command 25-35 percent premiums over unmarked alternatives. Pricing pressure stems from power-loom substitutes with artificial distress treatments capturing price-sensitive segments in local bazaars. Metropolitan online buyers exhibit lowest price sensitivity, prioritizing provenance verification over cost minimization.
Supply Chain Analysis
Certification gating through BIS handloom labeling and EU REACH compliance is concentrating supply among Tamil Nadu and Andhra Pradesh cooperatives with consolidated regional laboratory partnerships. Raw material dependencies center on Maharashtra organic cotton, Karnataka mulberry silk, and Himalayan wool varieties. Single-source vulnerability runs through Varanasi and Kanchipuram master weaver networks controlling multi-year apprenticeship-dependent dyeing expertise. Distribution runs through platform-mediated direct artisan relationships that displace traditional aggregator margins for mid-size apparel brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where boutique hospitality procurement shifts toward artisan-certified textiles with embedded verification technology, displacing mass-produced décor regardless of cost premium.
For Market Incumbents: Deploy exclusive weaver network lock-ins as the primary defensive lever. Fabindia-style decades-old supply agreements across Rajasthan and Gujarat clusters create switching costs that platform competitors cannot replicate overnight. Counter power-loom substitution threats by accelerating NFC-enabled provenance verification deployment that price-sensitive segments cannot easily counterfeit. Channel control investments in direct artisan relationships recover margins lost to traditional trading layers. For New Entrants and Emerging Players: Capture undercommercialized silk traditions in Assam and Manipur before organized market linkages mature. Northeast Indian states harbor ceremonial textile demand with rigid seasonal procurement windows that established players have overlooked. Target commercial hospitality procurement in Rajasthan and Kerala boutique hotel corridors where ESG audit documentation requirements favor new entrants with clean compliance infrastructure. Go-to-market angle: video-documented weaver narratives deployed as consumer-facing content. For Investors and Strategic Acquirers: Consolidation pressure builds where certification timeline compression meets fragmented weaver cooperative structures. Long-term viability favors platform-mediated aggregators with transparent origin tracing capabilities over pure retail plays. Acquisition target archetype: technology-enabled marketplaces with direct artisan logistics infrastructure and existing BIS registration. Signal to watch: GeM portal procurement volume shifts indicating institutional buyer preference consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Based Origin Documentation | Modular verification modules satisfy ESG audit requirements without overhauling entire sourcing operations for boutique hospitality procurement. |
| Regional Laboratory Partnership Consolidation | Tamil Nadu and Andhra Pradesh cooperatives share REACH compliance testing costs that individual weavers cannot bear alone. |
| Direct Artisan-to-Brand Logistics | Video documentation of specific weavers enables margin recovery and story authenticity for mid-size apparel brands. |
| NFC-Enabled Provenance Verification | Smartphone-based origin confirmation meets metropolitan Indian consumer demand for heritage-conscious purchasing with disposable income. |
| PLI Scheme Capital Subsidy Utilization | Production-linked incentive framework reduces lead times for handloom modernization that export buyers require. |
Research Methodology
Direct dialogue with master weavers, cooperative federation secretaries, boutique hospitality procurement officers, and GeM portal administrators grounded qualitative findings in operational reality. Secondary validation drew from BIS certification records, Khadi Gramodyog Board quality standard filings, EU REACH compliance databases, and customs export documentation for natural fiber textiles. Bottom-up weaver output estimates triangulated against top-down institutional procurement volume data.
Bottom-up modeling of individual cooperative capacity and top-down institutional demand aggregation generated volume and value outputs across the analysis window. Segmentation dimensions included material type, product category, distribution channel, and geographic production cluster. CAGRs derived from historical procurement trajectory analysis and projected certification expansion rates. Forecast inputs incorporated PLI scheme subsidy uptake velocity and digital traceability infrastructure deployment timelines.
Underlying measurement precision varies by segment; GeM-registered cooperatives with mandatory reporting carry tighter precision than unorganized home-based weavers in Northeast states. Forecasts reflect assumptions regarding monsoon-dependent fiber harvest stability and apprentice enrollment recovery. Deviation in REACH enforcement intensity or BIS labeling timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Innovations
Smart Fabrics in Fashion and Entertainment Market
Textile Innovations
Textile Acoustic Panel Market
Textile Innovations
Clothes Fastener Market
Textile Innovations
Digital Textile Printing Market
Textile Innovations
GCC Textile Market
Textile Innovations
Europe Digital Clothing Market
Textile Innovations
Smart Textile Market
Textile Innovations
Asia-Pacific Textile Market
Textile Innovations
Waterproof Socks Market
Textile Innovations
Smart and Interactive Textiles Market
Textile Innovations
Quilt Market
Textile Innovations
Fiber Patch System Market
Textile Innovations
Global Textile Market
Textile Innovations
Textile Felt Market
Textile Innovations
US Digital Printed Textile Market
Textile Innovations
Canvas Bags Market