
 Fiber Patch System Market | 2026-2036
Fiber Patch System Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Patch System Market Analysis
Single-mode OS2-grade performance is redrawing procurement benchmarks across enterprise and hyperscale networks. Corning Incorporated leverages its captive optical fiber manufacturing to sustain margin control from raw glass through finished patch assemblies. Amphenol Corporation anchors its position through connector miniaturization programs that dominate high-density rack environments. Sumitomo Electric Industries competes on fusion-spliced pigtail integration, a specialization that reduces field termination labor for carrier customers.
A fiber patch system comprises factory-terminated optical fiber cables with precision-polished connectors designed to achieve insertion loss below 0.3 dB and return loss exceeding 50 dB for single-mode variants, serving as removable interconnects between active equipment, distribution frames, and optical cross-connects in structured cabling infrastructure. Single mode products occupy the dominant revenue position due to 100G/400G wavelength-division multiplexing requirements across telecommunications backbones, while MPO connector formats represent the fastest-expanding segment as parallel optics displace duplex configurations inside cloud data centers. Indoor installation types maintain volume leadership, though outdoor armored assemblies carry premium positioning for 5G fronthaul and utility fiber deployments.
FCC broadband infrastructure programs and TIA-568 structured cabling standards shape North American product certification requirements, while REACH and RoHS compliance in Europe restricts halogenated jacketing materials and mandates substance disclosure across supply chains. OSHA laser safety classifications govern installation practices in enterprise and healthcare environments where patch system technicians encounter active optical power. Stakeholders must monitor connector density roadmaps and polymer jacket material substitutions as regulatory thresholds tighten and rack-space economics intensify.
Market Dynamics
Parallel optics architectures are decomposing traditional duplex fiber configurations inside hyperscale data centers, forcing connector suppliers to retool manufacturing lines for MPO density requirements while compressing insertion loss tolerances below 0.3 dB.
Growth Catalysts
- AI-driven rack density:Machine learning clusters in Northern Virginia and Dallas-Fort Worth are consuming single-mode OS2 patch assemblies at volumes that justify dedicated fiber manufacturing lines.
- FCC broadband infrastructure programs:Federal capital injections into last-mile fiber deployments are expanding addressable demand for factory-terminated outdoor armored assemblies in rural utility networks.
- TIA-604-5 standardization:MPO connector interoperability mandates are eliminating vendor-lock friction and accelerating procurement cycles across multi-tenant colocation facilities.
Market Restraints
- Raw glass supply concentration:Optical fiber preform manufacturing concentrates among three dominant suppliers, exposing patch system margins to silica rod price volatility and allocation rationing during demand spikes.
- Fusion splicer skill scarcity:Field termination labor for pigtail integration requires certified technicians, creating installation bottlenecks in markets with limited fiber optic training infrastructure.
- Halogenated jacketing restrictions:REACH and RoHS substance thresholds in Europe are forcing polymer formulation changes that extend qualification timelines by 8-14 months for international suppliers.
Strategic Opportunities
- 5G fronthaul densification:Outdoor armored patch systems are penetrating mobile network edge builds where macro tower fiber counts must triple to support C-band and mmWave radio heads.
- Data center liquid cooling convergence:Immersion-cooled server racks are driving demand for sealed MPO connector variants that maintain optical performance across thermal cycling from 15°C to 65°C.
- OSHA laser safety compliance services:Enterprise IT departments are unbundling installation safety protocols from hardware procurement, creating attach-rate opportunities for certified field service programs.
Industry Challenges
- MPO polarity management complexity:Method A/B/C fiber routing configurations are generating 12-18% order error rates in high-volume distribution channels, forcing distributors to maintain specialized technical support desks.
- Legacy SC/LC infrastructure integration:Hybrid patching between parallel MPO trunks and duplex breakout cables is multiplying connection points and attenuation budget risk in brownfield enterprise upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Patch System Market |
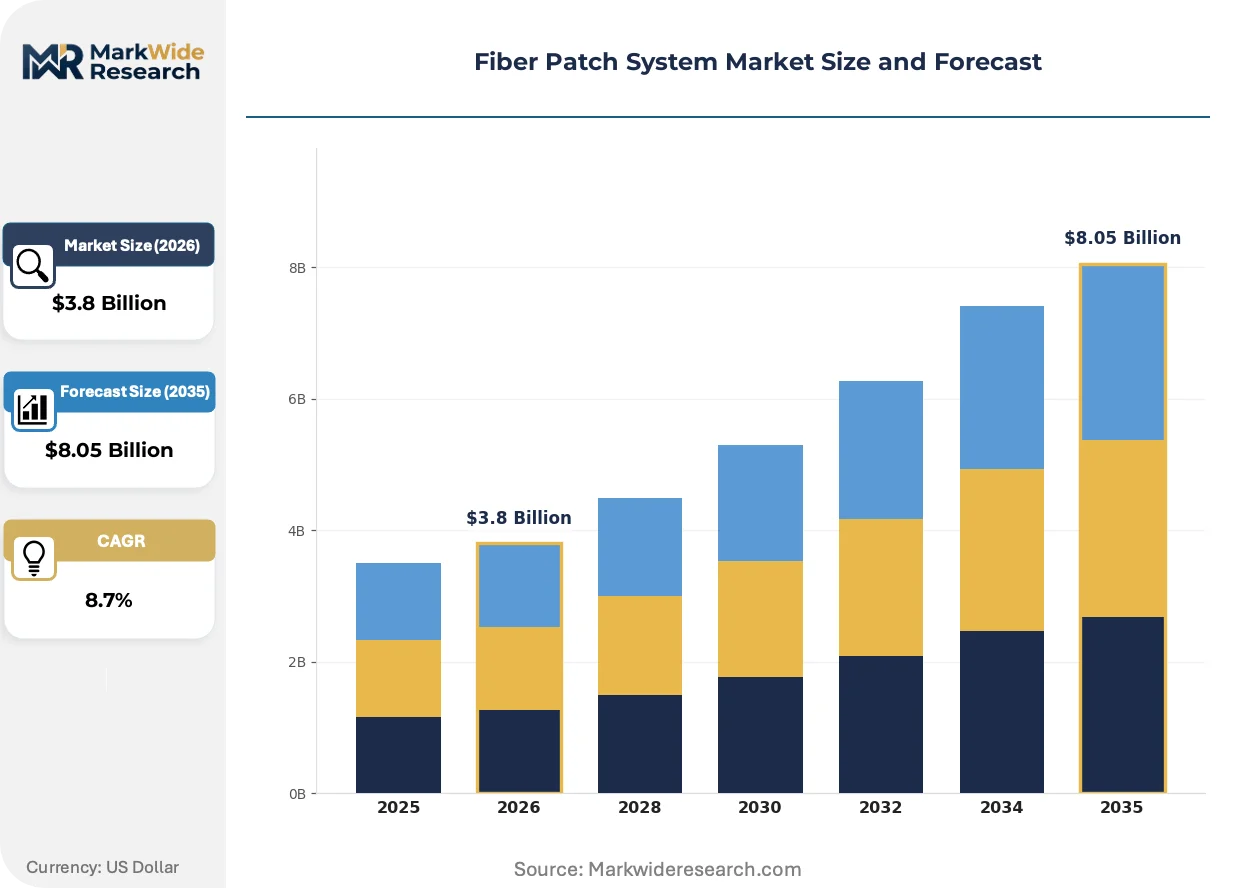
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Mode, Multimode, Armored Patch Cables, Unarmored Patch Cables Installation Type: Indoor, Outdoor, Enterprise, Data Center Connector Type: LC, SC, ST, MPO End User: Telecommunications, Infrastructure, Healthcare, Government |
| Companies Covered | Corning Incorporated, CommScope, Amphenol Corporation, 3M Company, Sumitomo Electric Industries, Panduit, HUBER+SUHNER, Black Box, Shenzhen Lightwit Photonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Patch System Market Emerging Trajectories
Connector miniaturization and automated polishing are compressing form factors while tightening optical performance windows. Three forces are actively restructuring how fiber patch systems are specified, procured, and deployed.
Multi-fiber push-on (MPO) 16-fiber and 32-fiber variants are decomposing traditional 12-fiber trunk cable dominance in AI training clusters. Hyperscale operators in the United States are specifying these higher-count assemblies to reduce cable bulk under raised floors. This density escalation is decomposing legacy cable management architectures and forcing rack manufacturers to redesign vertical cable organizers.
REACH substance disclosure mandates in Europe are accelerating jacket material substitutions from PVC to low-smoke zero-halogen (LSZH) compounds. Compound suppliers must now certify full supply chain substance inventories back to raw petrochemical feedstocks. Medical and enterprise verticals in Germany and France are responding by pre-qualifying LSZH-only suppliers, compressing vendor pools for international manufacturers.
Direct procurement from connector manufacturers is fragmenting traditional distribution channels as hyperscale operators establish volume tiering agreements that bypass value-added resellers. Cloud operators in Northern Virginia are negotiating 24-month blanket purchase orders with price lock provisions. This channel compression is most visible in the United States, where three data center operators now account for a disproportionate share of single-mode patch cord volume.
Fiber Patch System Market Segmentation
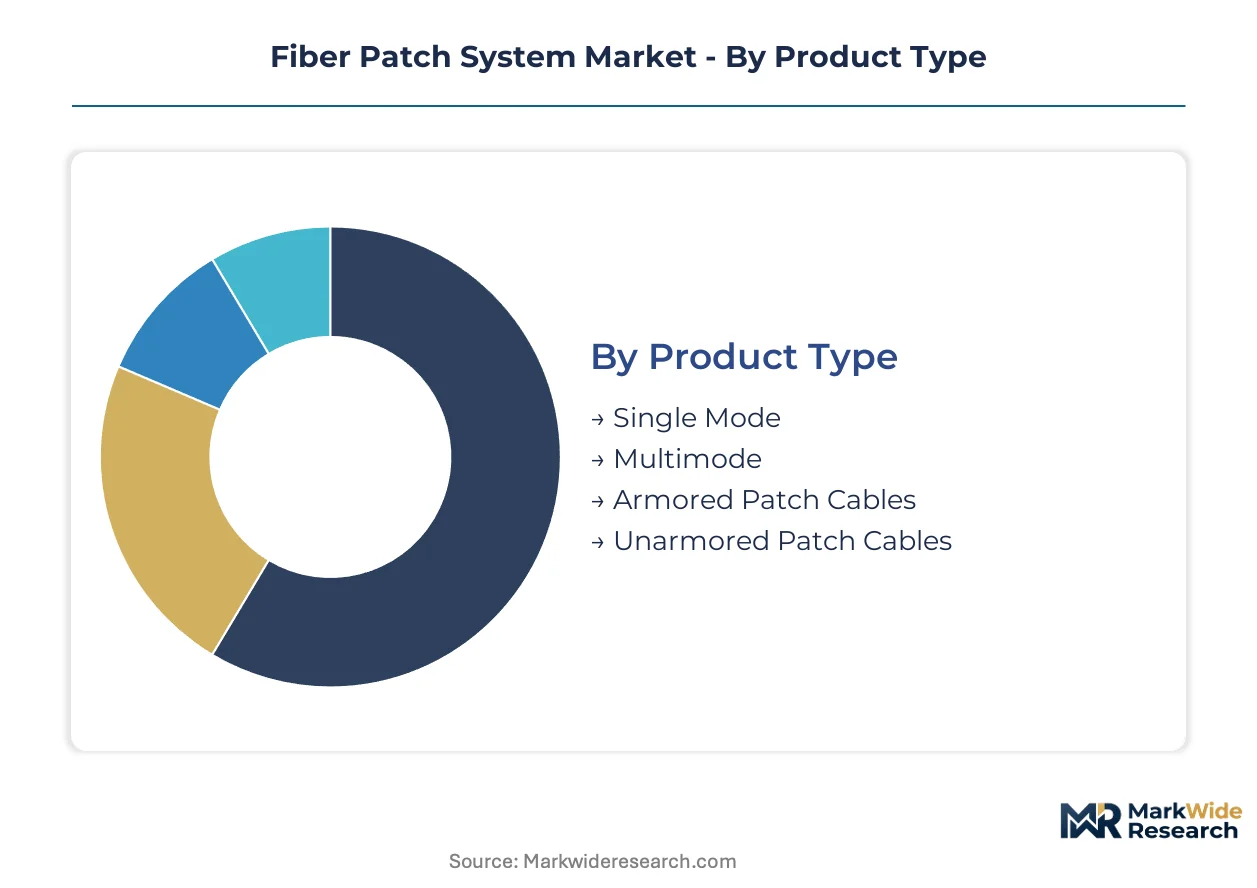
Fiber patch system procurement channels diverge sharply by performance tier and installation environment. Hyperscale operators negotiate direct with connector manufacturers for MPO trunk assemblies, while enterprise IT departments route duplex single-mode orders through value-added resellers with field termination support.
Product Type:
Channel mix splits between carrier-direct procurement for high-performance grades and distribution for standard enterprise SKUs.
- Single Mode:OS2-grade assemblies achieve insertion loss below 0.3 dB and return loss exceeding 50 dB through precision-polished ferrules. Demand concentrates in Northern Virginia and Dallas-Fort Worth AI training clusters where 100G/400G wavelength-division multiplexing mandates low-attenuation interconnects.
- MPO:Multi-fiber push-on connectors dominate hyperscale data center channels with 16-fiber and 32-fiber variants displacing legacy 12-fiber trunk configurations. Cloud operators specify these for reduced cable bulk under raised floors in liquid-cooled rack environments.
- Multimode:OM3 and OM4 grades persist in enterprise LAN upgrades with shorter reach requirements.
- Armored Patch Cables:Steel-tape or interlocking aluminum sheathing protects against rodent damage and crush loads in 5G fronthaul and utility fiber deployments.
- Unarmored Patch Cables:PVC or LSZH jacketed assemblies serve standard indoor structured cabling with lower material cost.
By volume, Single Mode leads. By growth pace, MPO is climbing the fastest.
Installation Type:
Cost tiering separates premium outdoor armored assemblies from standard indoor configurations.
- Data Center:Factory-terminated MPO trunks with method A/B/C polarity management support spine-leaf architectures. Hyperscale facilities in the United States consume these through 24-month blanket purchase orders with price lock provisions.
- Outdoor:Armored assemblies with UV-resistant jackets and moisture barriers penetrate 5G macro tower builds where fiber counts triple for C-band and mmWave radio heads.
- Indoor:Standard LSZH-jacketed patch cords serve commercial building structured cabling under TIA-568 standards.
- Enterprise:Hybrid configurations bridge legacy SC/LC infrastructure with parallel optics upgrades in brownfield environments.
By volume, Indoor maintains leadership. By margin expansion, Outdoor armored variants are gaining share fastest.
Connector Type:
Application requirements dictate connector selection across telecommunications backbones and enterprise edge networks.
- LC:Small form factor duplex connectors dominate high-density rack environments with latch-style retention. Data center operators specify these for 10G/25G server-facing ports.
- MPO:Parallel optics interfaces consolidate multiple fibers into single push-pull connectors. AI clusters in the United States drive 16-fiber and 32-fiber variant adoption for reduced connection point count.
- SC:Push-pull duplex connectors persist in carrier central offices and legacy infrastructure.
- ST:Bayonet-mount connectors retain niche presence in industrial and military applications requiring vibration resistance.
By installed base, LC leads. By deployment momentum, MPO shows the steepest expansion trajectory.
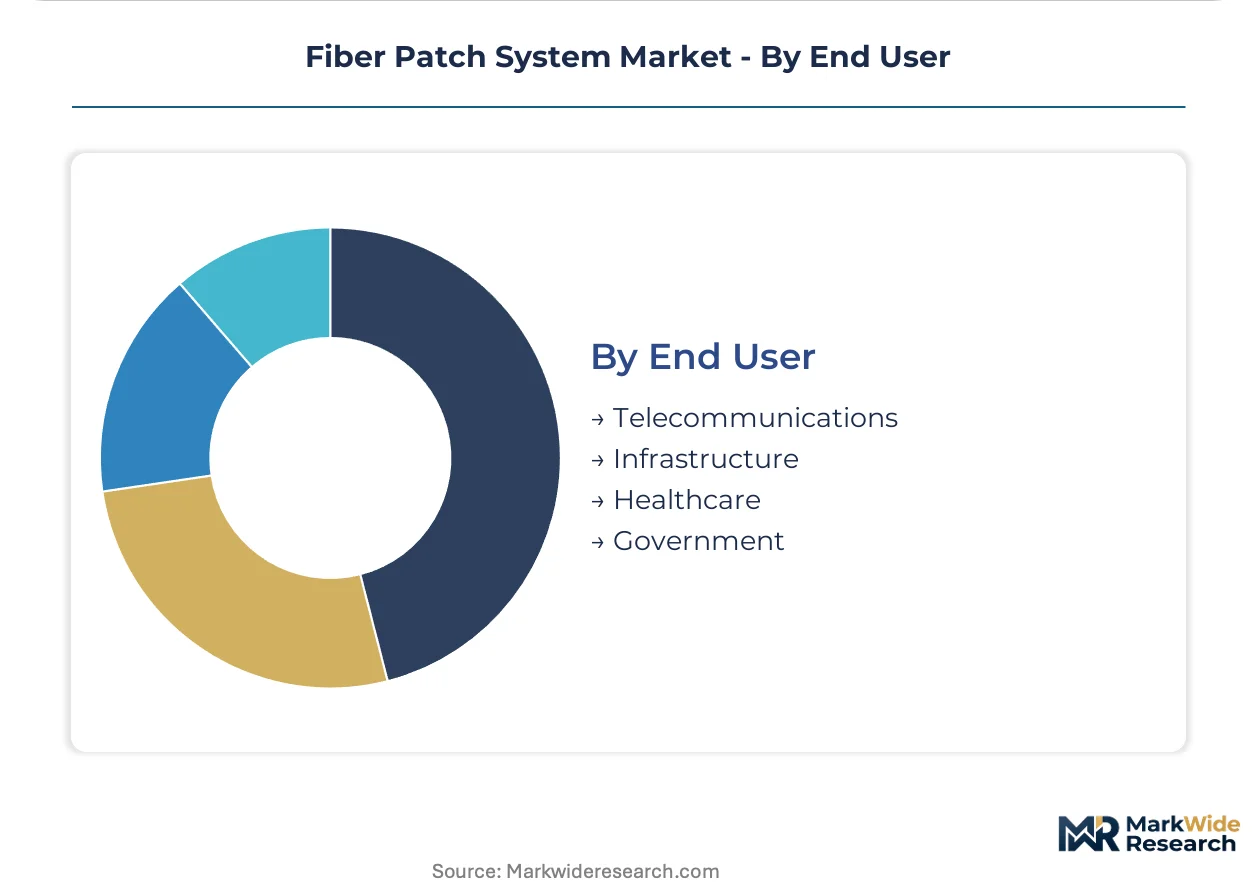
End User:
Customer type determines certification requirements and procurement cycle length.
- Telecommunications:Carrier networks demand fusion-spliced pigtail integration to reduce field termination labor. TIA-604-5 standardization accelerates MPO interoperability across multi-tenant colocation facilities.
- Infrastructure:FCC broadband programs expand addressable demand for factory-terminated outdoor assemblies in rural utility networks.
- Healthcare:OSHA laser safety classifications govern installation practices where technicians encounter active optical power in hospital IT environments.
- Government:Federal procurement mandates domestic manufacturing content and supply chain substance disclosure under Buy American provisions.
By contract value, Telecommunications leads. By program-driven expansion, Infrastructure is accelerating most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for optical fiber preforms shapes trade balances across major consuming economies, with domestic manufacturing capacity expansion programs altering procurement patterns in key markets. Export-oriented fiber patch system production concentrates in East Asian manufacturing hubs serving hyperscale data center buildouts in North America and Europe.
United States
Hyperscale operators in Northern Virginia and Dallas-Fort Worth drive single-mode OS2 consumption for AI training clusters. FCC broadband infrastructure programs expand factory-terminated outdoor armored assembly demand across rural utility networks. OSHA laser safety classifications govern installation practices in enterprise and healthcare environments where technicians encounter active optical power.
Germany
REACH substance disclosure mandates accelerate jacket material substitutions from PVC to low-smoke zero-halogen compounds across industrial verticals. ECHA compliance requirements force polymer formulation changes that extend qualification timelines for international suppliers. Medical and enterprise IT departments in Frankfurt and Munich pre-qualify LSZH-only suppliers, compressing vendor pools.
China
Domestic optical fiber preform manufacturing expansion reduces import dependence for silica rod feedstocks. MIIT standards for data center infrastructure accelerate MPO connector adoption in cloud computing facilities. Manufacturing clusters in Jiangsu and Zhejiang provinces supply high-density patch assemblies for both domestic hyperscale builds and export markets.
Japan
Fusion-spliced pigtail integration specialization serves carrier customers seeking reduced field termination labor. METI industrial standards govern optical performance certification for telecommunications backbone deployments. Manufacturing concentration in Osaka and Nagoya metropolitan areas supports precision polishing and connector miniaturization programs.
India
TRAI fiber-to-the-home deployment mandates expand addressable demand for factory-terminated indoor patch cords across urban broadband networks. BIS certification requirements for structured cabling products create compliance barriers for unqualified imports. Data center construction in Mumbai and Bengaluru drives MPO trunk assembly consumption for spine-leaf architectures.
Fiber Patch System Market Vendor Landscape
Listed leaders compete with private specialists across manufacturing scale and connector technology depth, producing a tiered structure where public companies control raw fiber supply and private operators dominate high-density assembly niches. The vendor base separates into three archetypes: captive fiber manufacturers, connector miniaturization specialists, and fusion-splicing integrators. Capacity expansion and strategic partnerships represent the dominant competitive moves, with direct procurement agreements bypassing traditional distribution channels.
Within the captive manufacturing tier, Corning Incorporated exemplifies backward integration from optical fiber preforms through finished patch assemblies. Amphenol Corporation and Sumitomo Electric Industries occupy positions on the connector technology and systems integration vectors respectively, with the former representing miniaturization capabilities and the latter anchoring fusion-spliced pigtail specialization for carrier markets.
| Leading Market Players |
|---|
| Corning Incorporated |
| CommScope |
| Amphenol Corporation |
| 3M Company |
| Sumitomo Electric Industries |
| Panduit |
| HUBER+SUHNER |
| Black Box |
| Shenzhen Lightwit Photonics |
| Others |
Supply Flow & Price Mechanics
REACH substance disclosure mandates in Europe gate both supplier qualification and price differentiation simultaneously, as ECHA compliance requirements force polymer formulation changes that compress vendor pools while extending premium positioning for certified LSZH compound suppliers serving medical and enterprise verticals in Germany and France.
Pricing Analysis
Hyperscale operators anchor pricing structures through 24-month blanket purchase orders with price lock provisions, while enterprise IT departments route smaller duplex orders through value-added resellers with field termination support. Price differentiation stems from insertion loss certification tier and volume scale commitments, with OS2-grade assemblies commanding premium positioning over standard single-mode variants. Cost compression in unarmored indoor patch cords is intensifying due to raw glass supply concentration among three dominant preform manufacturers. Carrier procurement teams exhibit lowest price sensitivity given fusion-spliced pigtail integration requirements, while rural utility networks under FCC broadband programs show highest sensitivity to factory-terminated outdoor assembly costs.
Supply Chain Analysis
Port congestion on Asia-North America trade lanes elevates inbound logistics costs for connector ferrules and precision polishing equipment sourced from East Asian manufacturing hubs. Optical fiber preform manufacturing concentrates in the United States, Japan, and China, while MPO connector assembly clusters in Jiangsu and Zhejiang provinces. Raw material dependencies span silica rod feedstocks, zirconia ceramic ferrules, and LSZH polymer compounds. Single-source vulnerability in optical fiber preform supply exposes patch system margins to allocation rationing during demand spikes. Distribution runs through direct procurement agreements for hyperscale volumes and specialized distributors for enterprise channels requiring polarity management technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fusion splicer certification scarcity constrains field service expansion velocity, creating a capability gap that separates qualified installation providers from hardware-only suppliers across telecommunications and data center deployment channels.
For Market Incumbents: Compound backward integration into optical fiber preform manufacturing to defend margin control from raw glass through finished patch assemblies against silica rod price volatility. Expand captive polishing capacity in Osaka and Nagoya metropolitan areas to maintain connector miniaturization leadership as MPO density requirements escalate toward 32-fiber variants. For New Entrants and Emerging Players: Differentiate on sealed MPO connector variants engineered for liquid-cooled rack thermal cycling from 15°C to 65°C, targeting data center operators in Northern Virginia and Dallas-Fort Worth cloud corridors. Pursue OSHA laser safety compliance service bundling as a go-to-market angle, attaching certified field protocols to hardware procurement for enterprise IT departments and healthcare environments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across MPO trunk assembly manufacturing as 16-fiber and 32-fiber variants displace legacy 12-fiber configurations, requiring retooling investments for automated polishing lines. Target fusion-splicing integration specialists with established carrier relationships and certified technician networks as acquisition archetypes. Monitor silica rod allocation announcements from dominant preform suppliers as the critical inflection signal for margin compression timing across the patch system value chain.| Strategic Initiative | Industry Significance |
|---|---|
| Connector Miniaturization Program | Amphenol Corporation dominates high-density rack environments through latch-style LC and push-pull MPO form factor compression. |
| Backward Integration into Preform Manufacturing | Corning Incorporated sustains margin control from raw glass through finished patch assemblies across single-mode OS2 grades. |
| Fusion-Spliced Pigtail Specialization | Sumitomo Electric Industries reduces field termination labor for carrier customers through integrated assembly capabilities. |
| Direct Procurement Agreement | Hyperscale operators in Northern Virginia bypass value-added resellers through 24-month blanket purchase orders with price lock provisions. |
| LSZH Compound Certification | REACH-compliant suppliers capture medical and enterprise verticals in Germany and France through ECHA substance disclosure compliance. |
Methodological Framework
A spread of perspectives from data center infrastructure directors, carrier network engineers, fiber optic technicians, and polymer compound suppliers converged on the working assumptions underlying demand projections. Primary interviews with hyperscale procurement teams and enterprise IT managers combined with secondary validation from TIA-604-5 standard documentation, FCC broadband infrastructure program disclosures, OSHA laser safety classifications, and ECHA REACH substance databases. Bottom-up volume estimates from connector shipment data and top-down market sizing from hyperscaler capex disclosures were triangulated to anchor the analytical framework.
Segmentation dimensions modeled span product type (single-mode OS2, MPO, multimode OM3/OM4, armored versus unarmored), installation environment (data center, outdoor, indoor, enterprise), connector format (LC, MPO, SC, ST), and end-user vertical (telecommunications, infrastructure, healthcare, government). CAGRs were derived from elasticity-adjusted demand curves across the projection horizon, incorporating AI training cluster buildout schedules in Northern Virginia and Dallas-Fort Worth, FCC rural broadband deployment timelines, and 5G fronthaul densification trajectories for C-band and mmWave radio heads.
Material uncertainties — silica rod supply allocation disruptions, REACH polymer formulation qualification delays, and fusion splicer technician training pipeline constraints — sit outside the modeled envelope. Forecasts reflect assumptions about TIA-604-5 standardization adoption velocity and hyperscale direct procurement channel expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Innovations
Textile Felt Market
Textile Innovations
Textile Acoustic Panel Market
Textile Innovations
GCC Textile Market
Textile Innovations
Clothes Fastener Market
Textile Innovations
Global Smart Fabrics Market
Textile Innovations
Smart Textile Market
Textile Innovations
US Digital Printed Textile Market
Textile Innovations
Global Textile Market
Textile Innovations
Quilt Market
Textile Innovations
Asia-Pacific Textile Market
Textile Innovations
Canvas Bags Market
Textile Innovations
Handloom Products Market
Textile Innovations
Europe Digital Clothing Market
Textile Innovations
Digital Textile Printing Market
Textile Innovations
Waterproof Socks Market
Textile Innovations
Smart and Interactive Textiles Market