
 Europe Digital Clothing Market | 2026-2036
Europe Digital Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Clothing Market Analytics
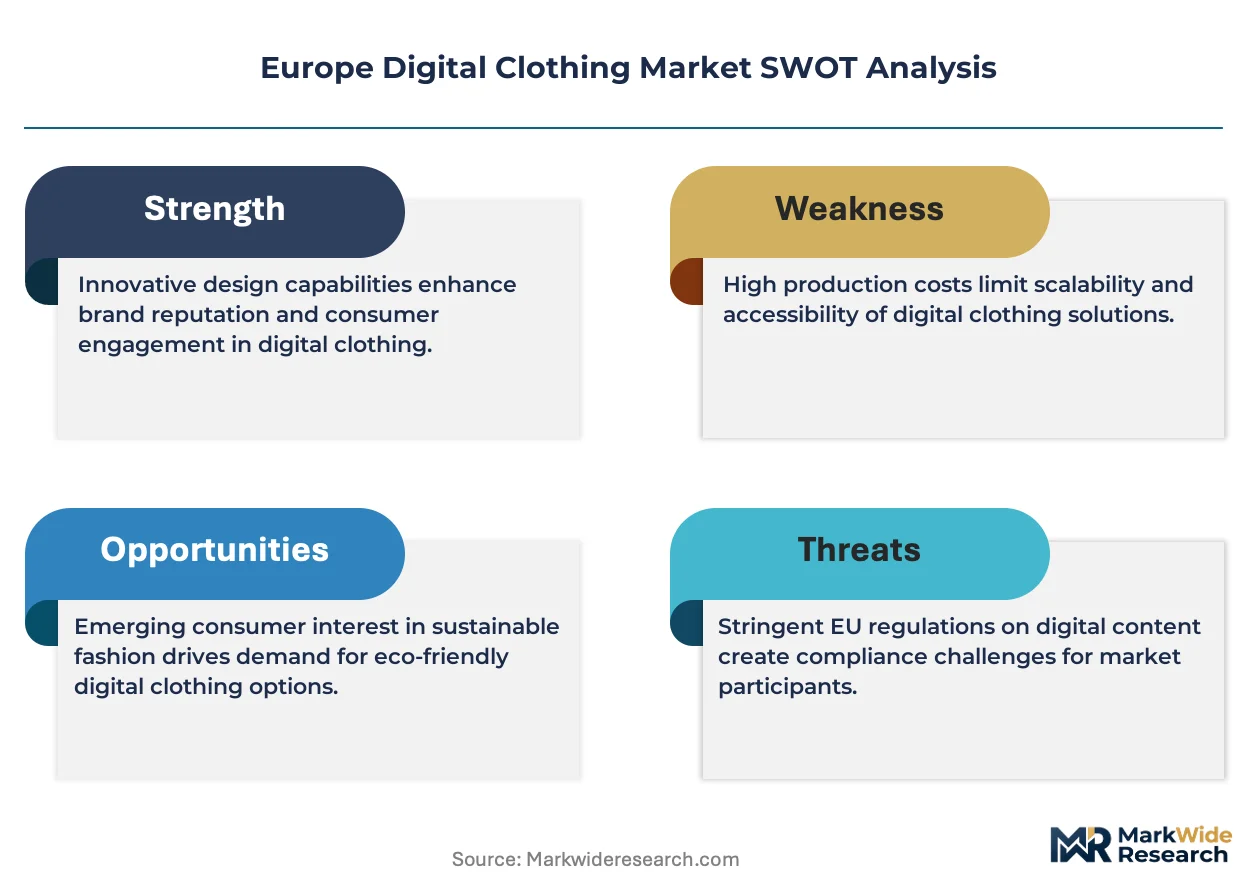
Fashion designer adoption is recalibrating the end-use mix for Europe digital clothing. Puma SE leverages its sportswear heritage to anchor digital sneaker and athleisure collections in virtual environments. Burberry Group plc sustains British luxury positioning through exclusive digital runway pieces and NFT-linked garments. Zalando competes by operating a platform model that extends discovery tools for emerging European digital fashion labels.
Europe digital clothing encompasses computer-generated garments rendered through 3D modeling software, blockchain authentication protocols, and augmented reality try-on interfaces, primarily serving virtual identity expression and metaverse commerce. Smart fabrics and augmented reality wearables lead current product type traction, while virtual fashion captures the fastest expansion as gaming platforms and social environments integrate avatar customization. Blockchain technology dominates technology segment margins through provenance verification, though artificial intelligence is displacing manual design workflows for pattern generation and fit simulation.
GDPR and the EU AI Act constrain how platforms collect biometric data for AR try-on features, while CE marking requirements under the EU Green Deal pressure lifecycle transparency for digital-to-physical hybrid garments. ECHA chemical safety frameworks indirectly shape material standards when digital designs translate into sample production. Stakeholders must monitor evolving CSRD disclosure obligations that will soon mandate reporting on virtual product environmental footprints.
Market Dynamics
Blockchain authentication protocols and the EU AI Act are compressing design cycles while fragmenting platform compliance costs across European digital clothing ecosystems.
Growth Catalysts
- GDPR-compliant biometric frameworks:AR try-on interfaces in France and Germany now operate under standardized consent architectures, accelerating consumer trust in virtual fitting rooms.
- Metaverse commerce integration:Gaming platforms across the Netherlands and Belgium are embedding native digital garment marketplaces, creating embedded demand channels.
- CSRD disclosure mandates:The EU's Corporate Sustainability Reporting Directive is pressuring fashion houses to document virtual product footprints, legitimizing digital-only collections as measurable sustainability assets.
Market Restraints
- Specialized 3D modeling talent scarcity:Pattern simulation expertise concentrates in Paris and Milan, creating wage inflation and recruitment bottlenecks for platforms outside these clusters.
- Blockchain infrastructure concentration:Ethereum and Layer-2 validation nodes cluster in Northern European data centers, exposing margin compression during energy price volatility.
- ECHA chemical safety translation:Digital-to-physical sample production must reconcile virtual designs with REACH substance restrictions, adding compliance layers to hybrid garment workflows.
Strategic Opportunities
- Eastern European creator economies:Poland and Romania host underpenetrated independent designer communities with lower studio overhead and emerging NFT marketplace participation.
- AI-generative pattern tools:Machine learning workflows are converging with manual atelier craft in Lisbon and Barcelona, enabling small-batch digital couture at scale economics previously reserved for algorithmic sportswear.
- CE marking for hybrid garments:The EU Green Deal's lifecycle transparency requirements create first-mover advantage for platforms that pre-integrate digital provenance with physical garment passports.
Industry Challenges
- Cross-border IP enforcement:Blockchain-verified ownership claims face jurisdictional friction when French designers dispute unauthorized derivatives circulating on Spanish-language platforms.
- Legacy ERP integration:Established luxury houses in Italy and Germany struggle to reconcile digital garment inventory systems with century-old physical supply chain software architectures.
- Biometric data retention limits:GDPR's storage minimization rules complicate AR try-on feature development, forcing platforms to purge body-scan data that could otherwise train fit algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Clothing Market |
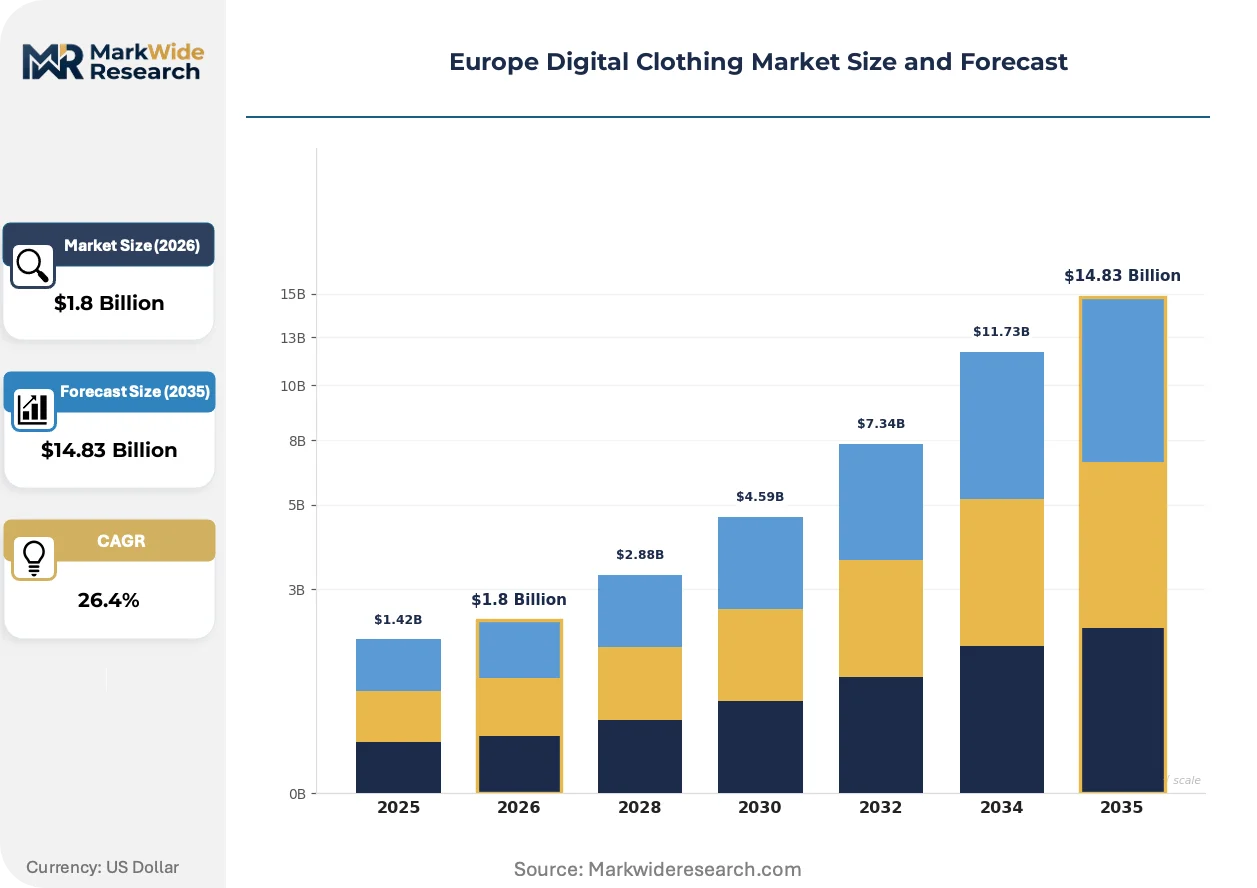
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $14.83 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Fabrics, Augmented Reality Wearables, Digital Apparel, Virtual Fashion End User: Fitness Enthusiasts, Gamers, Fashion Designers, Tech-Savvy Consumers Technology: Blockchain, Artificial Intelligence, IoT, 3D Printing Distribution Channel: Online Retail, E-commerce Platforms, Mobile Apps, Virtual Marketplaces |
| Companies Covered | Puma SE, Zalando, Burberry Group plc, Na-kd, Inditex, Hennes & Mauritz AB, Kering S.A., Otrium, Adidas AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Clothing Market Evolving Landscape
Generative workflows and regulatory disclosure mandates are reconfiguring how European digital clothing platforms authenticate provenance and compress design-to-market timelines.
Procedural texture generation is electrifying material library expansion for independent creators. Berlin and Amsterdam-based studios now deploy neural networks to synthesize fabric draping physics from limited reference samples. This capability is collapsing the traditional weeks-long manual iteration cycles into hours, enabling small ateliers to compete with heritage houses on visual fidelity.
The EU AI Act's risk classification framework is mandating algorithmic transparency for automated design tools. Platforms deploying AI-generated patterns must now document training data provenance and bias mitigation protocols. French luxury houses are responding by establishing in-house ethics review boards, while Dutch sportswear labels are outsourcing compliance to specialized legal-technical consultancies.
Direct-to-avatar distribution is displacing traditional e-commerce discovery for Gen Z consumers. Virtual try-on interfaces on social platforms in Sweden and Denmark now serve as primary purchase funnels, bypassing conventional retail websites. This behavioral shift concentrates marketing spend on influencer partnerships within gaming environments rather than conventional fashion editorial channels.
Europe Digital Clothing Market Segmentation
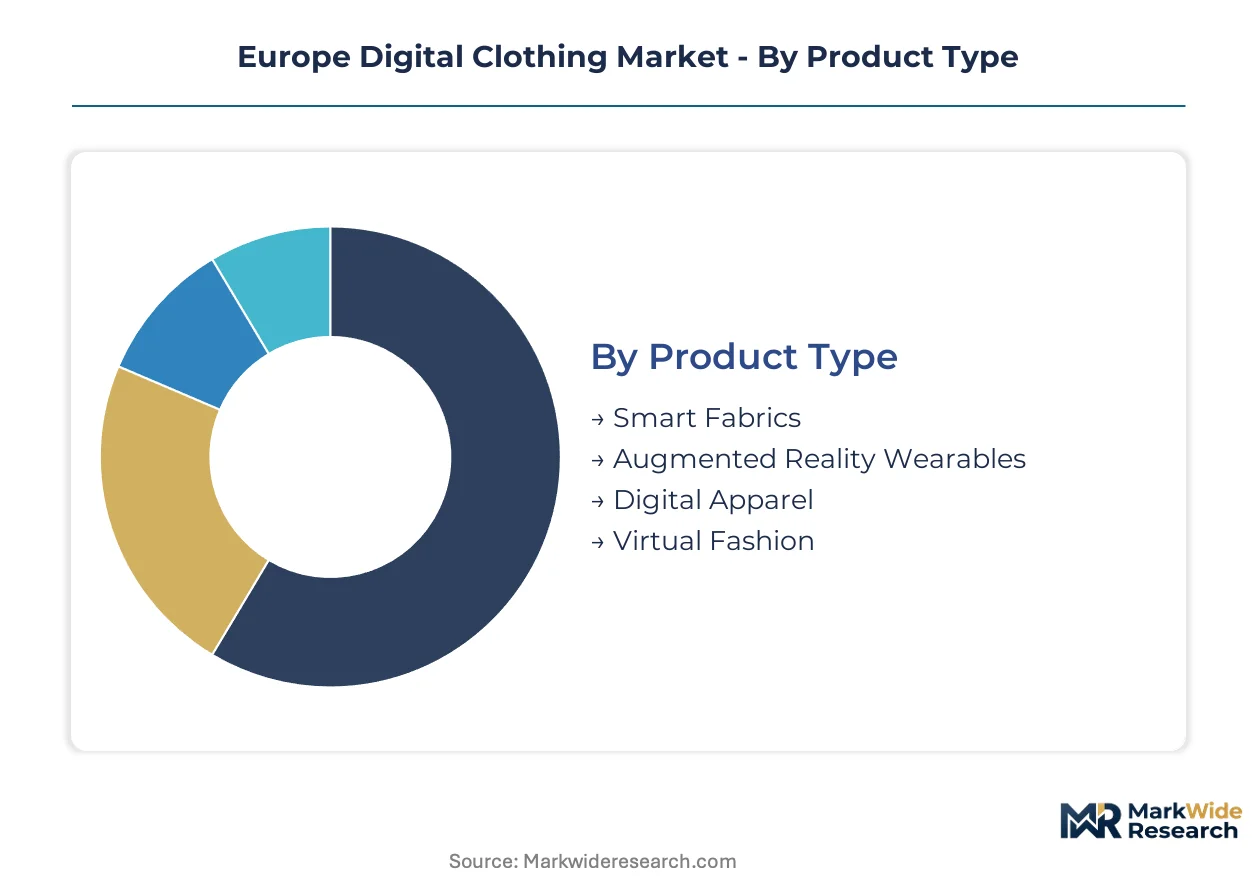
Segmentation in Europe digital clothing reveals how technology integration depth varies across consumer touchpoints. Standalone virtual garments operate independently of physical production, while embedded systems link digital designs to biometric data capture and blockchain authentication protocols.
Product Type:
Standalone digital garments function without hardware dependencies, whereas embedded categories require sensor integration or AR interface compatibility to deliver value.
- Smart Fabrics:Textiles interwoven with conductive threads and micro-sensors enable biometric monitoring through physical-digital hybrid garments. French sportswear houses in Lyon and Paris drive demand for temperature-responsive prototypes that bridge sample production with virtual visualization.
- Augmented Reality Wearables:AR-enabled garments overlay digital effects onto physical clothing through smartphone cameras or smart glasses. Dutch retailers in Amsterdam deploy these for in-store try-on experiences constrained by GDPR biometric consent frameworks.
- Digital Apparel:Computer-generated garments exist purely as 3D assets for social media and virtual environments.
- Virtual Fashion:Avatar-specific clothing for gaming platforms and metaverse environments dominates creator economy revenue streams.
Volume placements concentrate in Digital Apparel; the faster expansion belongs to Virtual Fashion.
End User:
Customer archetypes span from hardware-dependent fitness segments to purely virtual identity consumers, creating divergent margin profiles across the value chain.
- Fitness Enthusiasts:Athletes and gym users demand biometric-integrated garments tracking performance metrics through embedded sensors. German connected-fitness platforms in Munich and Berlin anchor procurement for sweat-responsive fabric interfaces.
- Gamers:Video game players purchase avatar skins and in-game cosmetic items across PC, console, and mobile environments. Polish and Romanian gaming communities generate disproportionate per-capita spend on rare digital item drops.
- Fashion Designers:Creators use digital tools for pattern visualization and virtual runway presentation before physical sampling.
- Tech-Savvy Consumers:Early adopters experiment with AR try-on features and NFT-linked garment ownership.
Designer adoption is climbing the fastest; fitness integration delivers the steadiest volume base.
Technology:
Technology selection determines compliance burden and infrastructure investment, with decentralized protocols carrying distinct regulatory overhead versus centralized AI systems.
- Blockchain:Distributed ledger technology authenticates garment provenance and enables secondary market royalties through smart contracts. Ethereum and Layer-2 validation nodes concentrated in Northern European data centers expose margin compression during regional energy price spikes.
- Artificial Intelligence:Machine learning algorithms generate patterns, simulate fabric draping physics, and optimize fit predictions from body-scan data. The EU AI Act's risk classification framework mandates algorithmic transparency documentation for automated design tools deployed by French luxury houses.
- IoT:Internet-connected sensors embedded in physical garments transmit usage and environmental data to cloud platforms.
- 3D Printing:Additive manufacturing translates digital designs into physical prototypes and small-batch production samples.
AI deployment is gaining share fastest; blockchain retains the highest margin contribution per transaction.
Distribution Channel:
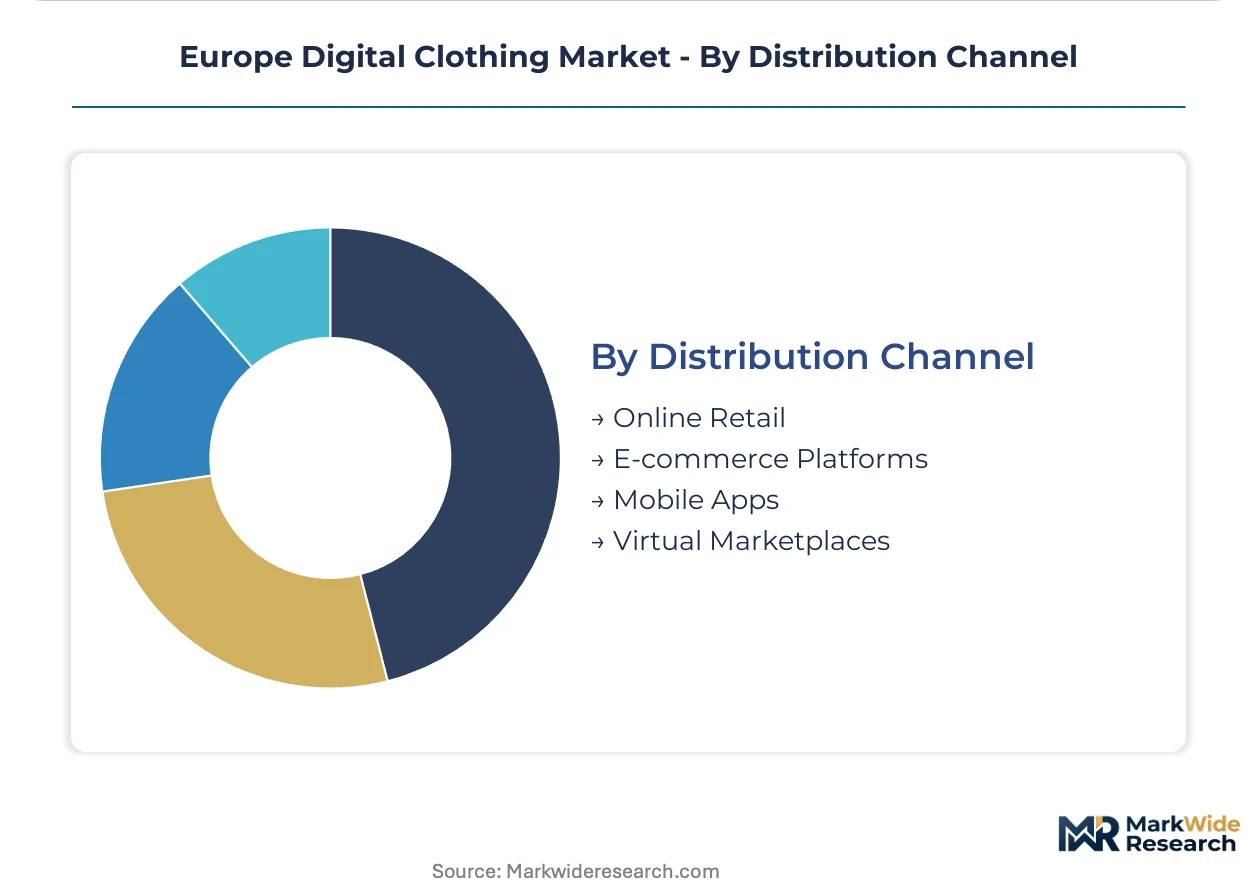
Channel selection reflects consumer journey fragmentation, with native virtual environments displacing traditional e-commerce discovery for younger demographics.
- Online Retail:Direct-to-consumer websites and brand-owned digital storefronts control pricing and customer data capture. Zalando's Berlin-based platform extends discovery tools for emerging European digital fashion labels seeking audience access.
- E-commerce Platforms:Multi-brand marketplaces aggregate inventory and handle payment processing for independent creators. Cross-border VAT compliance complexity across EU member states fragments platform operational costs.
- Mobile Apps:Smartphone-native applications deliver AR try-on features and push notification-driven purchase prompts.
- Virtual Marketplaces:In-game stores and metaverse-native trading platforms enable direct-to-avatar transactions without physical shipping logistics.
Mobile Apps capture the steepest expansion trajectory; E-commerce Platforms maintain the broadest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's Jeux Vidéo et Image de Synthèse tax credit zone concentrates digital fashion R&D investment, while Germany's Medienstandort initiative and the Netherlands' Creative Industries Fund accelerate studio formation across Northern Europe.
France
LVMH and Kering luxury houses drive avatar-ready couture demand through Paris-based digital ateliers. The EU AI Act mandates algorithmic transparency documentation for AI-generated pattern tools deployed by French creators. Lyon hosts smart fabric prototyping clusters where temperature-responsive textiles bridge physical sampling with virtual visualization pipelines.
Germany
Munich connected-fitness platforms anchor procurement for biometric-integrated sportswear, while Berlin studios specialize in procedural texture generation workflows. GDPR-compliant biometric consent architectures from the Federal Data Protection Authority standardize AR try-on deployments. The Medienstandort NRW program concentrates 3D modeling talent in Cologne-Düsseldorf corridors facing acute wage inflation.
Netherlands
Amsterdam retailers deploy AR-enabled in-store experiences constrained by the Autoriteit Persoonsgegevens biometric data rulings. Gaming platforms in Utrecht embed native digital garment marketplaces creating embedded demand channels. The Creative Industries Fund subsidizes neural network research for fabric physics simulation at Delft technical institutes.
United Kingdom
Burberry Group plc sustains British luxury positioning through London-based digital runway collections. The UK Information Commissioner's Office enforces GDPR-aligned biometric data retention limits on AR try-on features. Manchester and Birmingham host emerging independent creator communities with lower studio overhead than Southeast England clusters.
Poland
Warsaw and Krakow gaming communities generate disproportionate per-capita spend on rare digital item drops. The Polish Financial Supervision Authority monitors NFT marketplace compliance under EU MiCA transitional provisions. Lodz textile engineering institutes supply technical pattern simulation expertise to Western European luxury houses at competitive rates.
Europe Digital Clothing Market Competitive Landscape
Top-tier vendors anchor heritage luxury positioning, while mid-tier platform operators and independent creator tools occupy fragmented specialization layers. The vendor base stratifies across three tiers: integrated fashion houses with captive digital studios, multi-brand marketplace operators, and standalone software-as-a-service tool providers. Two strategic archetypes dominate—heritage luxury houses leveraging brand equity for NFT-linked scarcity plays, and platform-native operators optimizing discovery algorithms for emerging labels. Competitive moves concentrate on strategic partnerships between gaming engines and fashion houses, plus backward integration into proprietary 3D rendering pipelines.
Among German sportswear and platform operators, Puma SE, Zalando, and Adidas AG exemplify divergent archetypes. Puma SE represents heritage athletic brands translating physical sneaker DNA into virtual environments. Zalando occupies the marketplace-aggregator position extending discovery infrastructure for independent European digital labels. Adidas AG anchors the performance-lifestyle hybrid tier where physical product heritage informs virtual collection credibility. These three entities collectively illustrate how geographic origin—Herzogenaurach-based versus Berlin-based—correlates with strategic emphasis on manufacturing heritage versus platform scalability.
| Leading Market Players |
|---|
| Puma SE |
| Zalando |
| Burberry Group plc |
| Na-kd |
| Inditex |
| Hennes & Mauritz AB |
| Kering S.A. |
| Otrium |
| Adidas AG |
| Others |
Value Network & Pricing Analysis
3D modeling talent concentration in Paris and Milan amplifies labor-cost differentials between heritage ateliers and emerging Eastern European studios, widening pricing-tier spreads across premium couture visualization and mass-market avatar assets.
Pricing Analysis
Short lead-time premiums command substantial markups in digital garment production, while spot inventory of pre-rendered 3D assets trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-authenticated limited editions from templated avatar wearables and bulk-licensed game skins. Cost compression in the economy tier is intensifying because Polish and Romanian studios undercut Western European rates for comparable polygon fidelity. Indie game developers exhibit the highest price sensitivity; LVMH and Kering digital ateliers demonstrate minimal elasticity for exclusive couture drops.
Supply Chain Analysis
Workforce availability in France, Germany, and the Netherlands anchors European digital clothing production, though talent scarcity in Northern Italy and Spain constrains atelier expansion. Raw material dependencies center on GPU compute cycles from Northern European data centers, proprietary fabric physics engines from Delft and Berlin research institutes, and blockchain validation infrastructure concentrated in Frankfurt and Amsterdam server farms. Single-source vulnerability in Ethereum Layer-2 node clustering exposes margin compression during regional energy price spikes. Distribution runs through direct-to-avatar virtual marketplaces embedded in gaming platforms, bypassing traditional e-commerce logistics entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe digital clothing market functions as a vertical-integration race where proprietary 3D rendering pipelines and captive blockchain authentication protocols determine margin capture. Players are pursuing backward integration into neural network training datasets for fabric simulation.
For Market Incumbents: Deepen control over 3D modeling talent pipelines through apprenticeship partnerships with Lodz and Krakow textile engineering institutes. Incumbents should anchor blockchain node infrastructure in diversified Northern European data centers to mitigate energy price volatility exposure from Ethereum validation concentration. For New Entrants and Emerging Players: The EU AI Act in France opens a window for compliance-as-a-service offerings targeting independent creators lacking in-house ethics review boards. New entrants should prioritize Eastern European gaming communities in Poland and Romania with underpenetrated NFT marketplace participation, leveraging direct-to-avatar distribution partnerships with Utrecht-based gaming platforms. For Investors and Strategic Acquirers: The window for entry favors specialized legal-technical consultancies bridging EU AI Act compliance gaps for Dutch sportswear labels. Long-term viability hinges on acquisition of procedural texture generation startups with neural network IP from Berlin and Amsterdam studios. The signal to watch is CSRD disclosure mandate adoption rates among Italian luxury houses struggling with legacy ERP integration.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary 3D Rendering Pipeline Development | Captive fabric physics simulation reduces dependency on Delft technical institute licensing. |
| EU AI Act Compliance Infrastructure Investment | Automated algorithmic transparency documentation accelerates French luxury house deployment timelines. |
| Blockchain Node Geographic Diversification | Frankfurt and Amsterdam server concentration mitigation hedges against regional energy price spikes. |
| Eastern European Creator Economy Partnership | Lodz and Krakow studio alliances access technical pattern simulation at competitive wage rates. |
| Direct-to-Avatar Distribution Channel Integration | Native marketplace embedding in Utrecht gaming platforms bypasses conventional e-commerce discovery friction. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with digital fashion studio founders, blockchain platform engineers, luxury house creative directors, and gaming marketplace operators. Secondary sources included ECHA chemical safety frameworks, EU AI Act implementation guidance, CSRD disclosure templates, and GPU compute pricing indices from Northern European data center operators. Bottom-up segment sizing triangulated against top-down market value estimates.
Granularity-level modeling operated at product type, end user archetype, technology protocol, and distribution channel dimensions, with additional layering by national regulatory cluster and city-specific talent concentration. CAGRs were derived from segment-level growth trajectory analysis across the analysis window, incorporating AI adoption curves for pattern generation tools and blockchain transaction volume projections for provenance verification.
The model assumes a particular technology adoption path; alternative pathways for generative AI design workflows would alter the outlook if EU AI Act risk classifications tighten unexpectedly. Forecasts reflect assumptions about GDPR biometric consent framework stability and gaming platform marketplace integration velocity. Material deviation in Ethereum energy consumption regulation or CSRD enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Innovations
GCC Textile Market
Textile Innovations
Textile Acoustic Panel Market
Textile Innovations
Asia-Pacific Textile Market
Textile Innovations
Canvas Bags Market
Textile Innovations
Digital Textile Printing Market
Textile Innovations
Smart Textile Market
Textile Innovations
Smart and Interactive Textiles Market
Textile Innovations
US Digital Printed Textile Market
Textile Innovations
Clothes Fastener Market
Textile Innovations
Quilt Market
Textile Innovations
Fiber Patch System Market
Textile Innovations
Handloom Products Market
Textile Innovations
Global Smart Fabrics Market
Textile Innovations
Textile Felt Market
Textile Innovations
Waterproof Socks Market
Textile Innovations
Smart Fabrics in Fashion and Entertainment Market