
 Textile Felt Market | 2026-2036
Textile Felt Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Felt Market Analytics
The gap between premium technical felts and commodity craft grades is shifting from a price spread to a capability divide. Freudenberg Performance Materials leverages its vertically integrated polymer operations to control specification consistency across automotive supply chains. Wool Felt Company anchors its position through heritage manufacturing techniques that sustain margin pools in heritage craft and luxury accessories segments. 3M Company differentiates via proprietary resin bonding technologies that extend performance thresholds in acoustic and thermal insulation applications.
Textile felt consists of matted, non-woven fiber sheets produced through mechanical entanglement or chemical bonding, with densities typically ranging from 0.15 to 0.40 g/cm³ and thickness tolerances critical for industrial sealing applications. The material functions primarily as a conformable barrier, absorbing vibration, filtering particulates, or providing thermal insulation across engineered systems. Industrial felt occupies the deepest margin pool due to certification requirements and long-term supply agreements with transportation OEMs, while needle-punched polyester felt competes aggressively on scale in construction and geotextile applications. Wool felt retains pricing power in heritage craft and luxury interiors where natural fiber content commands specification premiums.
REACH substance restrictions and the EU Green Deal framework are elevating compliance costs for synthetic fiber producers serving European automotive and furnishing markets. EPA toxicity thresholds under TSCA Section 6 and evolving California Proposition 65 labeling requirements are reshaping formulation strategies for US-bound product lines. Stakeholders must monitor divergence between European chemical hazard classifications and US risk-based approaches, as misalignment threatens to fragment product platforms and inflate inventory carrying costs for multinational suppliers.
Market Dynamics
OEM specification tightening for acoustic and thermal management is compressing supplier margins while elevating technical entry barriers across automotive interior supply chains. REACH substance restrictions and EPA toxicity thresholds are forcing simultaneous reformulation of resin bonding systems and synthetic fiber inputs.
Growth Catalysts
- Automotive NVH mandates:NHTSA safety standards and OEM interior comfort specifications are pulling higher-density technical felts into door panels, headliners, and trunk assemblies.
- EU Green Deal circularity requirements:The framework incentivizes recycled polyester and bio-based fiber content in furnishing and automotive applications, redirecting R&D spend toward closed-loop production systems.
- German technical textile clustering:Concentrated expertise in Baden-Württemberg and North Rhine-Westphalia sustains premium industrial felt capabilities that command specification premiums in aerospace and precision engineering.
Market Restraints
- Crude oil derivative volatility:Polyester staple fiber and synthetic binder costs fluctuate with naphtha and PTA pricing, compressing margin stability for commodity-grade producers.
- Sheep wool supply concentration:Australian and New Zealand wool auctions dominate fine micron fiber availability, exposing heritage craft and luxury felt producers to climate-driven fleece yield variability.
- REACH authorization delays:ECHA substance evaluation timelines for legacy flame retardants and plasticizers extend 18-36 months, freezing formulation choices for EU-bound product lines.
Strategic Opportunities
- India automotive localization:PLI scheme incentives for advanced automotive components are drawing technical felt investments toward Chennai and Pune manufacturing corridors.
- Building energy retrofit mandates:Germany's Building Energy Act and similar national renovation frameworks are expanding specification-grade felt demand in HVAC duct insulation and facade systems.
- Needle-punching and thermal bonding convergence:Hybrid manufacturing lines capable of switching between mechanical and chemical bonding are enabling contract manufacturers to serve multiple specification tiers from shared assets.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists capable of balancing acoustic performance, flame resistance, and REACH compliance command wage premiums that inflate fixed costs for mid-cap producers.
- Multi-jurisdiction certification stacking:Simultaneous pursuit of FMVSS 302 automotive burn ratings, UL 94 flammability classifications, and OEM-specific material data sheet approvals extends qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Felt Market |
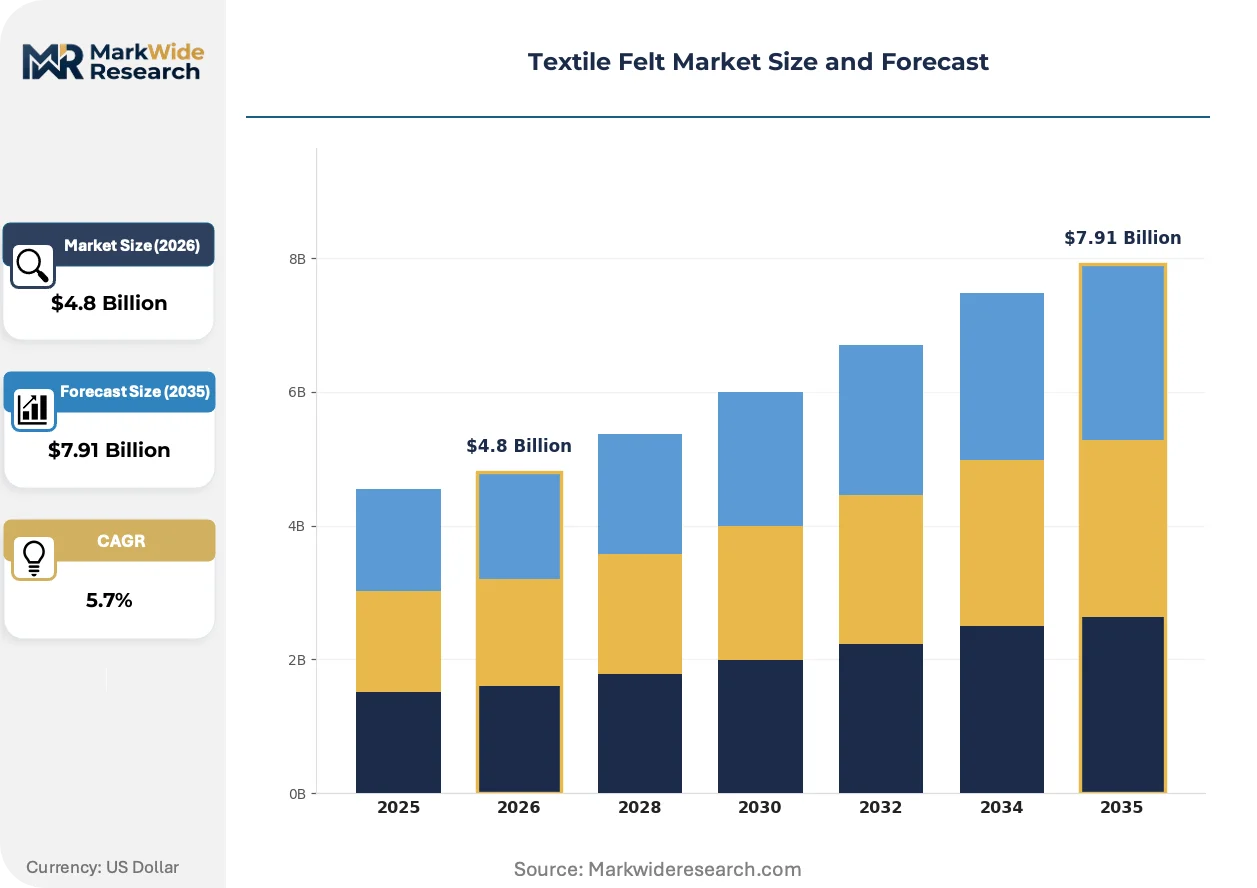
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Craft Felt, Industrial Felt, Wool Felt, Polyester Felt End Use: Fashion Accessories, Home Furnishings, Automotive Interiors, Acoustic Insulation Thickness: Thin, Medium, Thick, Extra Thick Manufacturing Process: Wet Felting, Needle Punching, Stamping, Lamination |
| Companies Covered | Felt Products Corp, 3M Company, Wool Felt Company, Aetna Felt, BWF Group, FilzFelt, Freudenberg Performance Materials, Pugalia Woolen Mills Private Limited, Swicofil AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Felt Market Evolving Landscape
Material science advances and regulatory chemistry constraints are converging to redefine specification thresholds across industrial, automotive, and furnishing applications. Three developments are compressing legacy production models while opening capability gaps for prepared suppliers.
Bio-based binder chemistries derived from lignin and plant-derived polyols are rewriting performance benchmarks for interior-grade felts. Tier 1 automotive seating suppliers in Germany and the Czech Republic are piloting these systems at commercial scale. The shift is compressing petroleum-based resin market share while elevating acoustic damping consistency in premium vehicle segments.
REACH Annex XVII substance restrictions on per- and polyfluoroalkyl substances are forcing reformulation of oil- and water-repellent industrial felts. ECHA hazard classifications for specific fluorinated chemistries are triggering substitution mandates in filtration and protective equipment applications. German and Italian felt producers are accelerating silicone and paraffin-based alternative development to maintain specification compliance in EU industrial markets.
Consolidated procurement desks at major automotive OEMs are compressing supplier panels and demanding integrated acoustic-thermal solutions rather than discrete material inputs. Tier 1 seating and interior systems integrators are absorbing felt specification authority previously held by raw material distributors. This concentration is most visible in Stuttgart and Wolfsburg supply corridors, where direct mill-to-OEM relationships are displacing traditional wholesale channels.
Textile Felt Market Segmentation
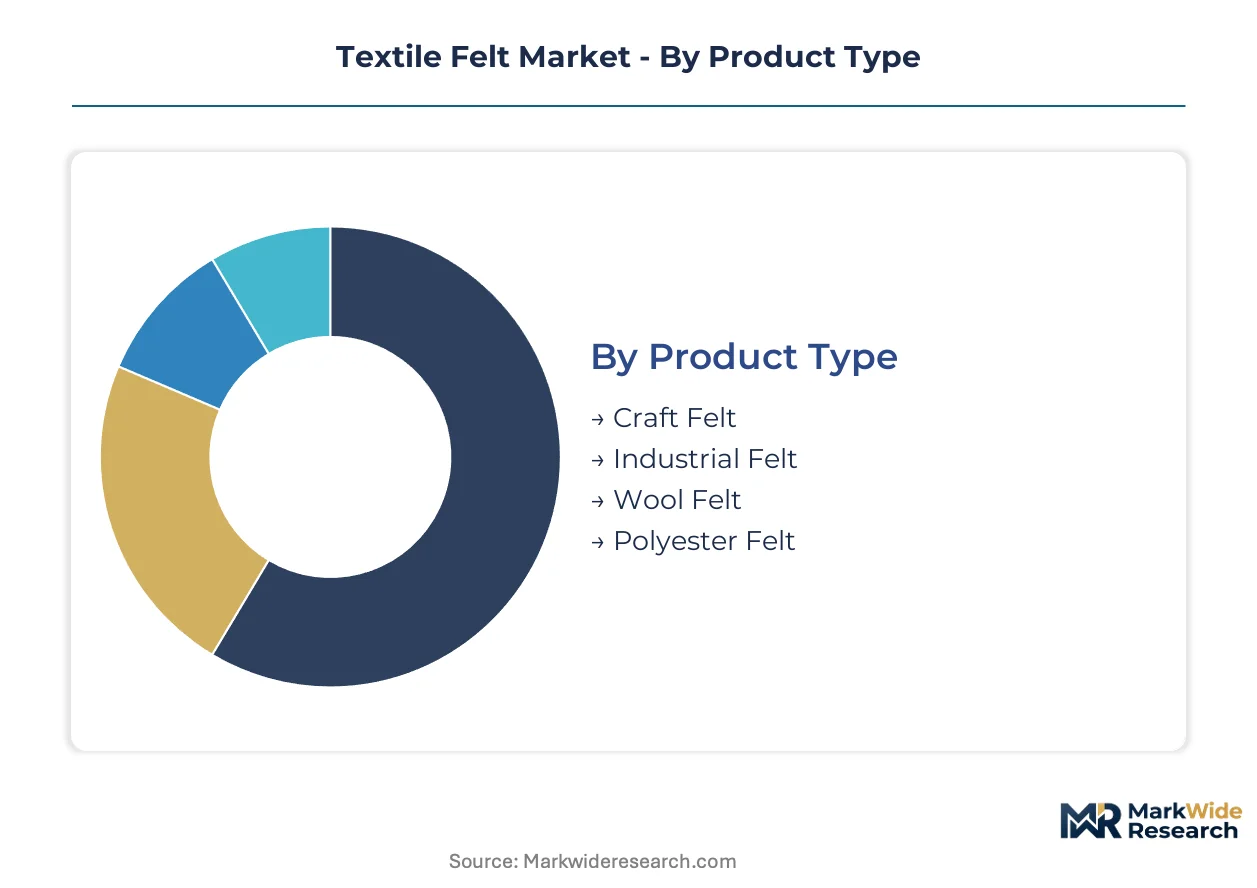
Specification divergence across textile felt categories reflects fundamentally different margin architectures and customer qualification requirements. Each segment category demands distinct production assets, certification pathways, and supply chain configurations that shape competitive positioning.
Product Type:
Customization intensity spans from standardized commodity grades to engineered performance specifications with locked-in customer relationships.
- Craft Felt:Acrylic and rayon staple fiber constructions dominate hobby, education, and decorative applications with minimal certification overhead. Demand concentrates in North American and European retail channels where seasonal purchasing patterns and private-label sourcing agreements compress margin stability for contract manufacturers.
- Industrial Felt:Wool and synthetic fiber blends engineered to precise density, resilience, and fluid absorption specifications serve sealing, filtration, and vibration damping in precision machinery. German technical textile clusters in Baden-Württemberg anchor global supply for aerospace and automotive OEMs requiring REACH-compliant formulations with documented batch traceability.
- Wool Felt:Natural fiber content commands specification premiums in heritage craft and luxury accessories segments where Australian and New Zealand fine micron wool supply concentration creates raw material cost volatility.
- Polyester Felt:Recycled PET staple fiber constructions compete aggressively on scale in construction geotextiles and disposable filtration where EU Green Deal circularity requirements are redirecting R&D toward closed-loop production systems.
Leading the category by volume: Polyester Felt. Growing fastest: Industrial Felt.
End Use:
Application-driven specification tiers separate discrete material sales from integrated system supply with deeper customer captivity.
- Fashion Accessories:Wool and blended felts for handbags, hats, and jewelry components where heritage manufacturing techniques sustain margin pools in Italian and French luxury supply chains.
- Home Furnishings:Medium-density polyester and wool felts for upholstery backing, rug underlay, and decorative wall panels where German Building Energy Act retrofit mandates are expanding specification-grade demand in HVAC and facade applications.
- Automotive Interiors:High-density technical felts engineered to NHTSA FMVSS 302 burn ratings and OEM-specific acoustic performance thresholds dominate door panels, headliners, and trunk assemblies where consolidated procurement desks are compressing supplier panels.
- Acoustic Insulation:Multi-layer laminated constructions combining felt substrates with mass-loaded barriers and decoupling foams where 3M proprietary resin bonding technologies extend performance thresholds in premium vehicle segments.
Volume leadership: Automotive Interiors. Steepest expansion trajectory: Acoustic Insulation.
Thickness:
Process yield and cutting efficiency create distinct cost structures across dimensional specifications.
- Thin:Sub-2mm calipers for filtration media, precision gaskets, and apparel interfacing where needle-punching density controls permeability and tensile consistency.
- Medium:2-5mm range serving automotive NVH pads, furniture padding, and industrial wipers where Freudenberg vertically integrated polymer operations control specification consistency.
- Thick:5-10mm constructions for heavy-duty sealing, sound barriers, and protective packaging where density uniformity across the Z-axis determines functional performance.
- Extra Thick:Above 10mm specialty grades for vibration isolation mounts, industrial polishing wheels, and architectural acoustic panels requiring custom lamination and controlled compression set properties.
Most produced: Medium. Gaining share fastest: Thin.
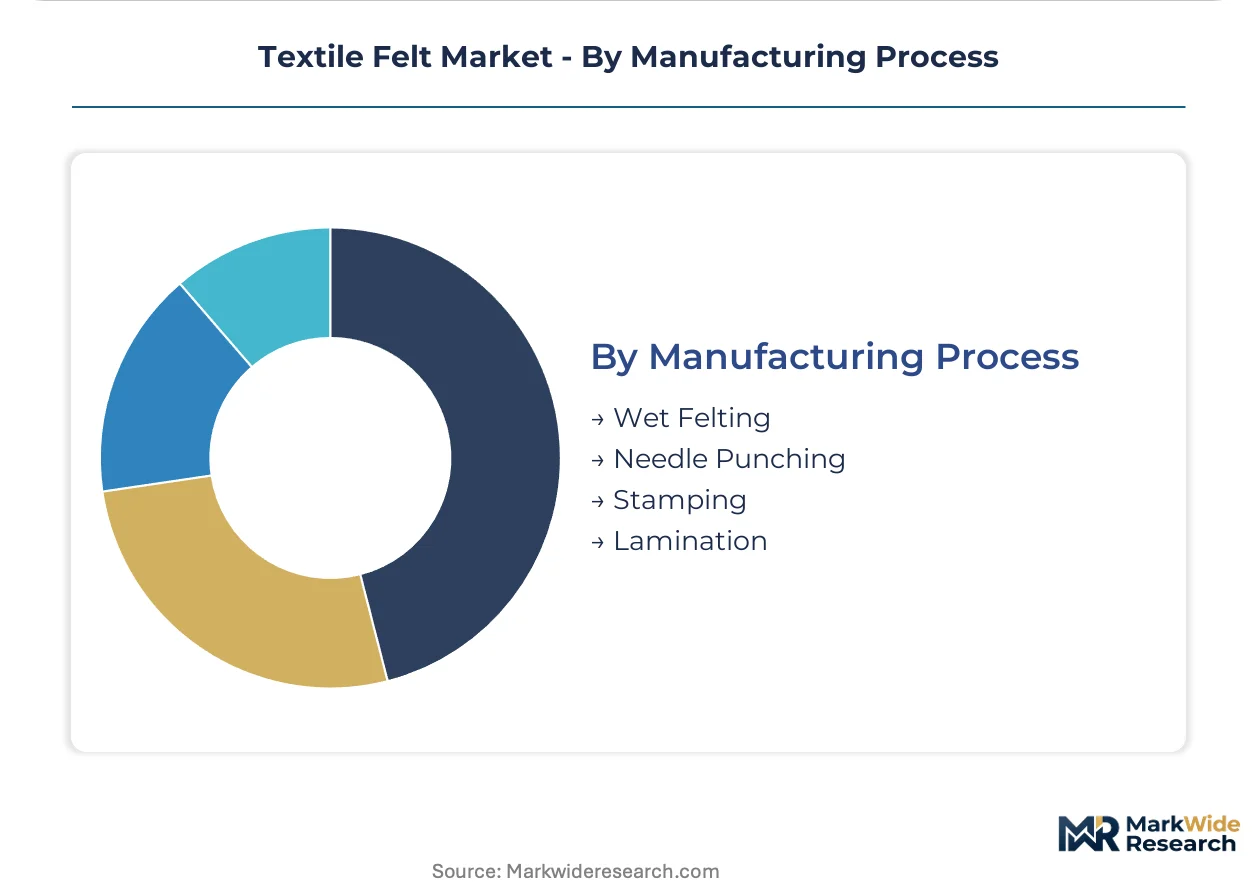
Manufacturing Process:
Capital intensity and flexibility trade-offs separate heritage craft methods from scalable industrial systems.
- Wet Felting:Traditional wool fiber matting using water, heat, and mechanical agitation sustains artisan production in heritage craft segments where Wool Felt Company anchors position through generational manufacturing expertise.
- Needle Punching:Mechanical entanglement of synthetic staple fibers dominates industrial scale production with hybrid lines capable of switching between bonding methods to serve multiple specification tiers from shared assets.
- Stamping:Die-cutting and compression molding of pre-felted sheets into complex geometries for automotive and appliance gaskets where tooling amortization favors high-volume, long-life programs.
- Lamination:Bonding felt substrates to films, foams, or pressure-sensitive adhesives for integrated acoustic-thermal solutions where Tier 1 seating suppliers are absorbing specification authority from raw material distributors.
Volume concentration: Needle Punching. Expanding most quickly: Lamination.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg and North Rhine-Westphalia anchor European technical felt production, with Stuttgart's automotive supply corridor driving specification-grade demand for acoustic and thermal management materials.
United States
NHTSA safety standards and OEM interior comfort specifications pull higher-density technical felts into door panels and headliners. EPA toxicity thresholds under TSCA Section 6 reshape formulation strategies for domestic automotive supply chains. Detroit's manufacturing corridor concentrates Tier 1 seating suppliers absorbing felt specification authority from distributors.
Germany
EU Green Deal circularity requirements incentivize recycled polyester and bio-based fiber content in furnishing applications. REACH Annex XVII substance restrictions force reformulation of oil- and water-repellent industrial felts. Technical textile clusters in Baden-Württemberg sustain premium industrial felt capabilities commanding specification premiums in aerospace and precision engineering.
India
PLI scheme incentives for advanced automotive components draw technical felt investments toward Chennai and Pune manufacturing corridors. BIS certification requirements elevate compliance thresholds for construction geotextile applications. Maharashtra's industrial belt hosts emerging needle-punching operations serving domestic automotive localization mandates.
China
Dual carbon goals redirect R&D spend toward closed-loop production systems for synthetic fiber inputs. MIIT standards for automotive interior materials tighten chemical content thresholds parallel to European REACH frameworks. Yangtze River Delta manufacturing zones concentrate scale-driven polyester felt production for construction and filtration export markets.
Japan
METI energy efficiency mandates expand specification-grade felt demand in HVAC duct insulation and building retrofit applications. JIS standards for industrial sealing materials maintain rigorous density and thickness tolerance requirements. Kanto region technical textile producers supply precision felts for robotics and semiconductor equipment vibration damping.
Textile Felt Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity and customer qualification depth. The market structures into three tiers: heritage craft specialists commanding specification premiums through generational expertise, vertically integrated polymer producers controlling raw material consistency, and scale-driven commodity fabricators competing on needle-punching throughput. Strategic moves concentrate on hybrid manufacturing line investments enabling multi-bonding flexibility, and direct mill-to-OEM relationship cultivation displacing wholesale distribution channels.
Within the heritage craft tier, Wool Felt Company exemplifies margin sustainability through artisan production techniques. Among diversified materials conglomerates, 3M Company and Freudenberg Performance Materials occupy positions defined by proprietary bonding technologies and captive polymer supply control. These three anchors represent distinct competitive archetypes: generational expertise, technology differentiation, and vertical integration.
| Leading Market Players |
|---|
| Felt Products Corp |
| 3M Company |
| Wool Felt Company |
| Aetna Felt |
| BWF Group |
| FilzFelt |
| Freudenberg Performance Materials |
| Pugalia Woolen Mills Private Limited |
| Swicofil AG |
| Others |
Value Network & Pricing Analysis
Polyester staple fiber feedstock costs cascade through three distinct pricing tiers, with naphtha and PTA volatility compressing margins at the commodity end while REACH-compliant industrial grades sustain specification premiums through German technical textile clusters.
Pricing Analysis
Outcome-based pricing anchors specification-grade industrial felts to acoustic performance guarantees and batch traceability documentation. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified automotive grades from construction geotextiles and craft felts. Price differentiation rests on certification intensity and OEM qualification depth, with commodity polyester needle-punching operations absorbing the steepest cost compression from crude oil derivative swings. Tier 1 automotive seating suppliers exhibit lowest price sensitivity due to consolidated procurement mandates, while hobby craft distributors face acute margin pressure from private-label sourcing.
Supply Chain Analysis
Single-source vulnerability sits with Australian and New Zealand wool auctions dominating fine micron fiber availability for heritage craft segments. Geographic supply concentration centers on Germany, China, and India, with Baden-Württemberg technical textile clusters feeding European automotive OEMs and Yangtze River Delta operations serving scale-driven construction markets. Raw material dependencies draw from petroleum-based synthetic binders, recycled PET flake streams, and bio-based lignin alternatives under EU Green Deal circularity mandates. Climate-driven fleece yield variability poses structural risk to wool-dominant producers. Distribution runs through direct mill-to-OEM relationships displacing traditional wholesale channels in Stuttgart and Wolfsburg supply corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around specification authority, with REACH authorization delays and multi-jurisdiction certification stacking forcing sub-scale competitors toward exit.
For Market Incumbents: Anchor position through backward integration into polymer operations or captive resin bonding capabilities that control specification consistency across automotive supply chains. Invest in hybrid manufacturing lines enabling mechanical-to-chemical bonding switches to serve multiple tiers from shared assets. Defend against Tier 1 seating suppliers absorbing specification authority by deepening direct OEM relationships and locking in long-term material data sheet approvals. For New Entrants and Emerging Players: Regional automotive component suppliers in India's Chennai and Pune corridors represent the most penetrable buyer archetype, with PLI scheme incentives reducing qualification friction for localized technical felt production. Target building energy retrofit contractors in Germany responding to Building Energy Act mandates for HVAC duct insulation and facade systems. Pursue contract manufacturing arrangements with established European brands seeking REACH-compliant offshore capacity rather than building proprietary distribution. For Investors and Strategic Acquirers: ECHA substance evaluation timeline acceleration for legacy flame retardants is the leading indicator that formulation-capable mid-caps will command scarcity premiums over commodity fabricators. Long-term viability favors vertically integrated polymer producers or German technical textile specialists with documented aerospace and automotive OEM relationships. Watch for REACH Annex XVII expansion announcements as the signal triggering consolidation waves among reformulation-constrained suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Manufacturing Line Investment | Enables switching between needle-punching and thermal bonding to serve multiple specification tiers from shared assets. |
| Bio-Based Binder Chemistry Development | Rewrites performance benchmarks for interior-grade felts as lignin-derived systems displace petroleum-based resins under EU Green Deal requirements. |
| Direct Mill-to-OEM Relationship Cultivation | Displaces traditional wholesale channels in Stuttgart and Wolfsburg supply corridors where Tier 1 suppliers concentrate procurement authority. |
| REACH Compliance Infrastructure Buildout | Creates defensible moats as ECHA substance evaluation timelines freeze formulation choices for sub-scale competitors. |
| India Manufacturing Localization | Captures PLI scheme incentives for advanced automotive components in Chennai and Pune corridors serving domestic OEM mandates. |
Research Methodology
Independent corroboration across primary interviews with Tier 1 automotive procurement officers, technical textile plant managers, and REACH compliance consultants underwrites the qualitative findings. Secondary validation draws from ECHA substance restriction databases, BIS certification registries, SEC filings of diversified materials conglomerates, and EU customs trade data. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across the analysis window.
Comparable-period anchoring to historical automotive production cycles and building retrofit installation rates shaped the projection horizon. The analytical framework models segmentation across product type, end-use application, thickness specification, and manufacturing process. CAGRs derive from elasticity-adjusted demand curves incorporating OEM specification tightening velocity and circularity mandate implementation pace. Forecast inputs include naphtha-PTA spread trajectories and wool auction volume variability.
Revisions become necessary when ECHA accelerates substance evaluation timelines, when PLI scheme incentive structures shift, or when automotive OEM consolidation triggers supplier panel compression. Forecasts reflect documented assumptions about regulatory harmonization persistence and raw material cost pass-through elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Innovations
Waterproof Socks Market
Textile Innovations
Canvas Bags Market
Textile Innovations
US Digital Printed Textile Market
Textile Innovations
Clothes Fastener Market
Textile Innovations
Textile Acoustic Panel Market
Textile Innovations
Fiber Patch System Market
Textile Innovations
Smart Fabrics in Fashion and Entertainment Market
Textile Innovations
Global Smart Fabrics Market
Textile Innovations
Quilt Market
Textile Innovations
Smart Textile Market
Textile Innovations
Asia-Pacific Textile Market
Textile Innovations
Europe Digital Clothing Market
Textile Innovations
Smart and Interactive Textiles Market
Textile Innovations
Handloom Products Market
Textile Innovations
Digital Textile Printing Market
Textile Innovations
GCC Textile Market